
 5G in Aviation Market | 2026-2036
5G in Aviation Market Size, Share, and Industry Trends Forecast 2026-2036
5G in Aviation Market Intelligence
Market Context
European telecom infrastructure vendors is consolidating around aviation-specific 5G portfolios as airlines accelerate connectivity upgrades. Ericsson leverages its Open RAN partnerships to secure ground station contracts across Nordic and Central European airports. Nokia anchors its position through private wireless deployments for airport operations and air traffic management systems. Gogo LLC specializes in onboard 5G hardware, sustaining dominance in North American in-flight connectivity through direct airline relationships.
Technical Definition and Segment Structure
5G in Aviation denotes the deployment of fifth-generation cellular networks across airport infrastructure, aircraft systems, and airspace management platforms, utilizing millimeter-wave spectrum, network slicing, and massive MIMO arrays to deliver sub-10-millisecond latency for real-time communication between pilots, controllers, and ground systems. Its primary purpose is to replace legacy satellite and LTE-based links with higher-bandwidth, lower-latency connectivity for safety-critical and passenger-facing applications. In-flight connectivity and air traffic management represent the largest application segments, with predictive maintenance emerging as the fastest-growing margin pool due to sensor-data throughput requirements. Massive MIMO and edge computing dominate technology deployment, while ground stations and onboard equipment capture the majority of infrastructure spending as carriers phase out older Ku-band satellite terminals.
Regulatory Frame and Outlook
The FAA mandates equipage timelines for NextGen airspace modernization, while EASA coordinates 5G spectrum allocation near European airports to prevent altimeter interference. China's MIIT and NMPA jointly govern aviation 5G certification through GB standards and equipment type approval processes. Stakeholders must monitor spectrum reallocation decisions and cross-border harmonization protocols to anticipate certification delays and infrastructure rollout sequencing.
Market Dynamics
Airlines now treat connectivity as a revenue-generating product rather than a cost center, forcing infrastructure vendors to restructure pricing around passenger throughput metrics and service-level guarantees rather than hardware procurement cycles.
Growth Catalysts
- NextGen airspace mandates:The FAA's equipage timelines for ADS-B and data communications compel carriers to replace legacy satellite links with 5G-enabled ground-to-air systems.
- Millimeter-wave spectrum allocation:Regulators in the United States, Germany, and China have released mid-band and mmWave frequencies specifically for aviation use cases, reducing interference risks.
- Predictive maintenance data throughput:Engine and airframe sensor arrays now generate terabytes per flight, requiring 5G's bandwidth to transmit real-time analytics to ground operations centers.
Market Restraints
- Altimeter interference constraints:The FCC's C-band reallocation near airport approaches forces 5G power reductions that limit coverage radius and increase base station density requirements.
- Ground station hardware concentration:Specialized massive MIMO arrays and edge computing nodes for aviation applications rely on a concentrated supplier base in Nordic manufacturing clusters.
- Ku-band satellite legacy lock-in:Existing in-flight connectivity contracts with satellite operators create contractual friction and switching costs for airlines evaluating 5G migration.
Strategic Opportunities
- Private wireless airport deployments:Untapped demand exists for 5G campus networks serving baggage handling, tarmac vehicle tracking, and perimeter security at secondary hubs in India and Southeast Asia.
- Network slicing for cargo operations:Dedicated virtual networks with guaranteed latency for drone delivery coordination and cold-chain monitoring represent an emerging application segment.
- EU Green Deal aviation incentives:The F-Gas Regulation and associated emissions reduction frameworks subsidize equipment refresh cycles that bundle 5G connectivity with more efficient aircraft systems.
Industry Challenges
- Cross-border spectrum harmonization:Divergent national allocations for aviation 5G frequencies complicate certification and roaming agreements for international carriers.
- Integration with legacy avionics:ARINC 429 and MIL-STD-1553 bus architectures in existing fleets require costly gateway hardware to interface with IP-native 5G modems.
- Airworthiness certification timelines:EASA and FAA type approval processes for new connectivity hardware extend 18-36 months, compressing deployment windows for technology refresh programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 5G in Aviation Market |
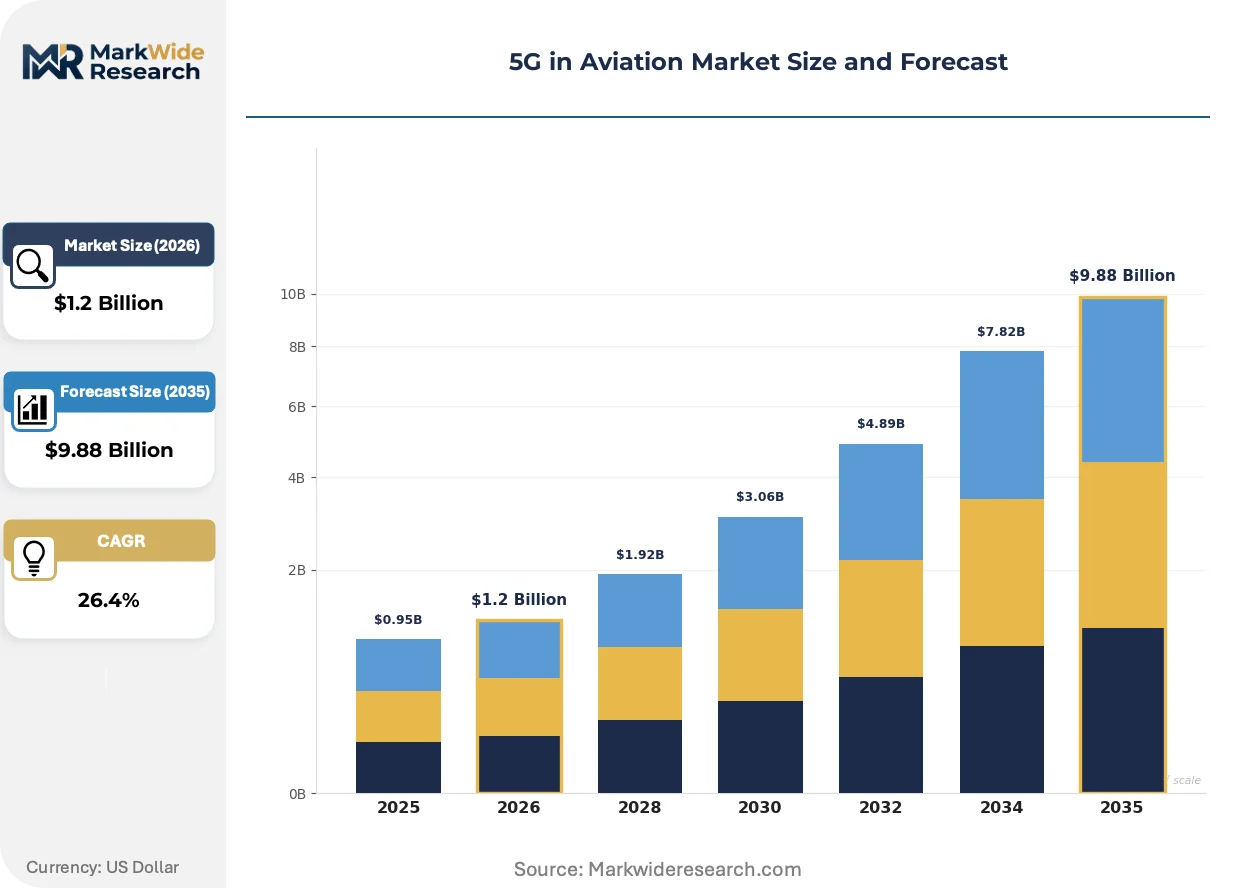
| Market Size in 2026 | $1.2 Billion |
| Market Size in 2035 | $9.88 Billion |
| CAGR (2026 – 2036) | 26.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Massive MIMO, Beamforming, Network Slicing, Edge Computing, mmWave, Small Cells Application: In-Flight Connectivity, Air Traffic Management, Predictive Maintenance, Passenger Experience Enhancement, Cargo Tracking, Security Monitoring Deployment Type: Ground Stations, Onboard Equipment, Airport Infrastructure, Control Towers, Maintenance Facilities, Training Simulators End User: Airlines, Aircraft Manufacturers, Ground Handling Agencies, Air Navigation Service Providers, Cargo Operators, Maintenance Providers |
| Companies Covered | Ericsson, Nokia, Huawei, Gogo LLC, Qualcomm, Cisco Systems, AT&T, Verizon, Panasonic Avionics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
5G in Aviation Market Strategic Shifts & Innovations
Aviation connectivity infrastructure is pivoting from passenger entertainment toward operational data pipelines, with vendors restructuring product roadmaps around deterministic latency guarantees rather than peak bandwidth claims.
Open RAN architectures are automating baseband processing distribution across airport edge nodes, enabling carriers to deploy software-defined ground stations without proprietary hardware lock-in. Tier-one airports in Germany and the United States are piloting these disaggregated systems for apron coverage. This architecture is automating the shift from centralized network management to localized, AI-driven radio resource allocation that adapts to flight schedule density.
The EU's F-Gas Regulation is accelerating equipment replacement cycles by phasing out refrigerants used in legacy ground station cooling systems, indirectly mandating 5G infrastructure upgrades that employ liquid-cooled or ambient-tolerant designs. Equipment vendors must now certify thermal performance alongside radio specifications. European airport operators are responding by bundling connectivity modernization with broader energy efficiency retrofits.
Airline procurement teams now evaluate connectivity vendors through total cost of ownership models that weight data offload economics against passenger satisfaction scores, displacing earlier capex-focused selection criteria. This behavioral shift favors suppliers offering throughput-based pricing with guaranteed service levels. The transformation is most visible among low-cost carriers in the United States and hybrid operators in Asia-Pacific seeking to monetize connectivity as ancillary revenue.
5G in Aviation Market Segmentation
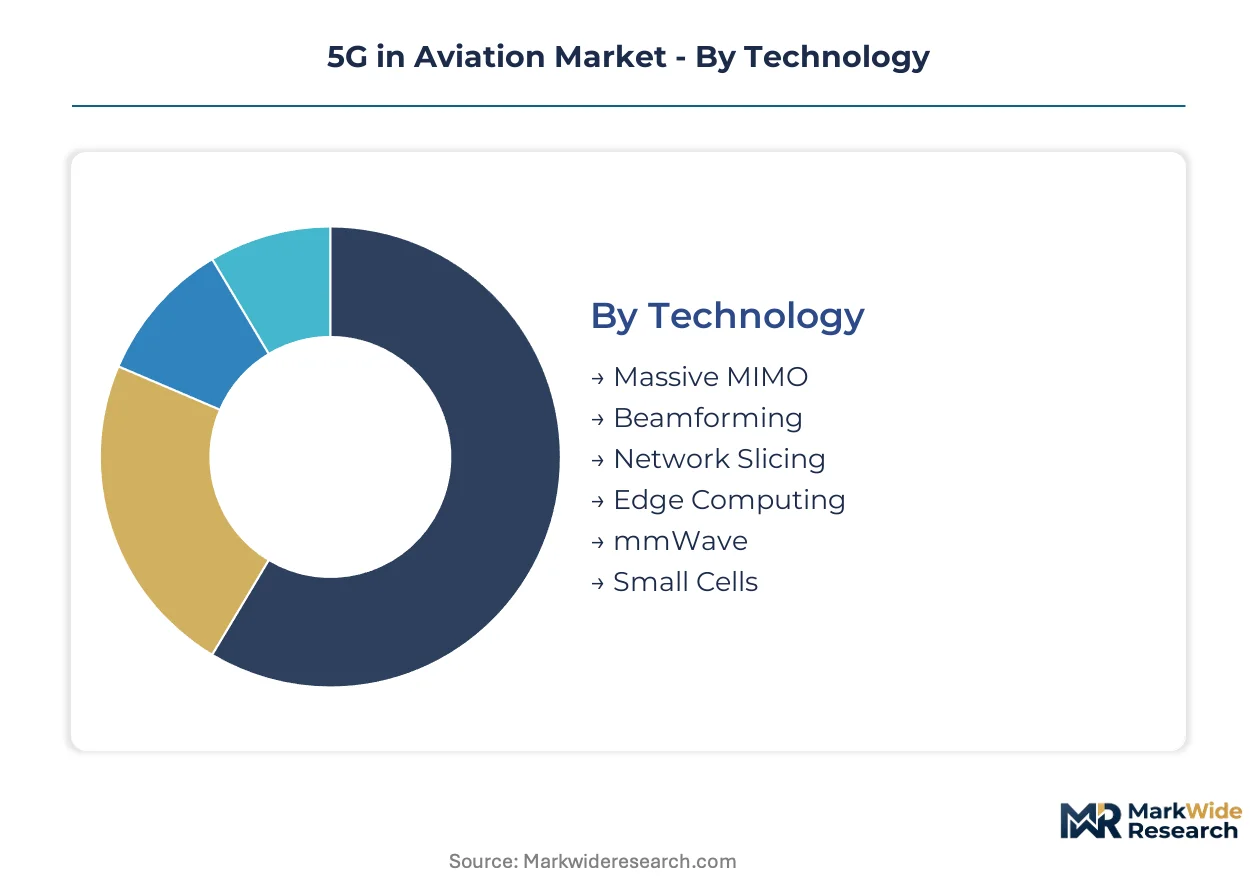
Segmentation in aviation 5G reveals how capital flows diverge between passenger-facing connectivity and operational infrastructure. Equipment specifications, deployment timelines, and regulatory certification requirements vary sharply across these boundaries, forcing vendors to maintain distinct product portfolios and pricing architectures.
Technology:
Supply concentration in radio access network components shapes competitive positioning across the technology stack. Nordic manufacturing clusters dominate massive MIMO array production, while semiconductor foundries in Taiwan and South Korea control mmWave chipset supply.
- Massive MIMO:Arrays with 64+ antenna elements enable spatial multiplexing across airport apron zones. Demand concentrates at Frankfurt Airport and Dallas-Fort Worth International, where FAA and EASA mandates for ground station density drive procurement volume.
- Edge Computing:Micro data centers deployed at runway thresholds process sensor data with sub-5-millisecond latency. Germany's major hub operators are installing these nodes to support predictive maintenance pipelines for Lufthansa Technik and MTU Aero Engines.
- Beamforming:Dynamic signal steering optimizes coverage for aircraft on approach paths.
- Network Slicing:Virtualized network partitions isolate safety-critical air traffic communications from passenger Wi-Fi traffic.
- mmWave:24-47 GHz spectrum bands deliver gigabit throughput for high-density terminal areas.
- Small Cells:Distributed low-power base stations fill coverage gaps in baggage handling zones and remote stands.
Massive MIMO absorbs the bulk of installed capacity; edge computing is expanding most quickly.
Application:
Cost tier differentiation separates commoditized passenger entertainment from premium operational data services. Airlines monetize connectivity through tiered pricing models, while air traffic management contracts carry stringent service-level guarantees.
- In-Flight Connectivity:Ku-band satellite replacement programs using 5G ground-to-air links now dominate North American carrier capex. United Airlines and Delta Air Lines are retrofitting narrowbody fleets with Gogo 5G hardware to capture ancillary revenue.
- Predictive Maintenance:Real-time engine telemetry transmission requires guaranteed bandwidth for vibration analysis and oil debris monitoring. Rolls-Royce and GE Aviation are mandating 5G data pipelines for their TotalCare and OnPoint service contracts.
- Air Traffic Management:Ground-to-air data links replace voice communications for clearance delivery.
- Passenger Experience Enhancement:Immersive entertainment and retail platforms drive Wi-Fi satisfaction scores.
- Cargo Tracking:Cold-chain monitoring for pharmaceutical shipments uses dedicated network slices.
- Security Monitoring:Perimeter surveillance and baggage screening video backhaul consume substantial uplink capacity.
In-flight connectivity captures the largest revenue pool; predictive maintenance is climbing the fastest.
Deployment Type:
Volume concentration in ground infrastructure reflects the FAA's NextGen equipage timelines and EASA's parallel mandates. Onboard equipment cycles lag due to airworthiness certification bottlenecks.
- Ground Stations:Massive MIMO arrays with aviation-specific beam patterns cover approach corridors and apron areas. Installation concentrates at Hartsfield-Jackson Atlanta and Denver International, where the FAA coordinates multi-carrier spectrum sharing agreements.
- Onboard Equipment:5G modems and antenna radomes require DO-160G environmental qualification and FAA TSO-C159 certification. Boeing and Airbus are qualifying factory-installed options for next-generation narrowbody programs.
- Airport Infrastructure:Campus-wide 5G networks integrate baggage handling, fueling, and catering operations.
- Control Towers:Dedicated low-latency links support remote tower operations and contingency communications.
- Maintenance Facilities:Hangar coverage enables high-definition video collaboration with OEM engineering centers.
- Training Simulators:Full-flight simulators use 5G for cloud-based scenario streaming and instructor station connectivity.
Ground stations absorb the bulk of installed capacity; onboard equipment is gaining share fastest as certification backlogs clear.
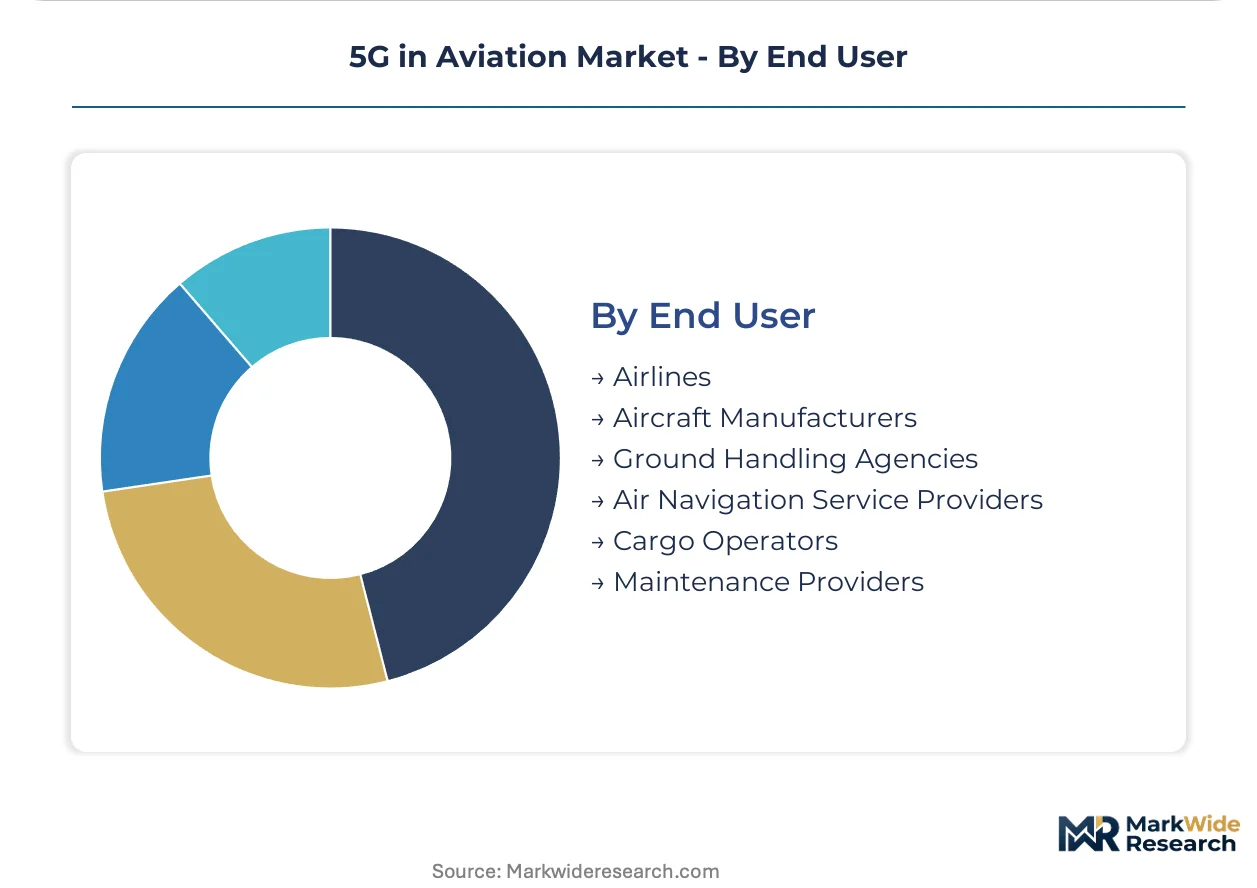
End User:
Customer type determines procurement authority and contract structure. Airlines control passenger-facing connectivity decisions, while air navigation service providers govern safety-critical infrastructure.
- Airlines:Network equipment procurement centers on total cost of ownership models weighting passenger satisfaction against data offload economics. American Airlines and Southwest Airlines are restructuring vendor relationships around throughput-based pricing with guaranteed service levels.
- Aircraft Manufacturers:Line-fit and retrofit program decisions at Boeing and Airbus determine hardware form factors and antenna placement. Both manufacturers are certifying 5G as standard equipment on single-aisle platforms.
- Ground Handling Agencies:Swissport and dnata deploy private wireless networks for tarmac vehicle tracking.
- Air Navigation Service Providers:FAA, DFS Germany, and NATS manage ground station deployment for surveillance and communications infrastructure.
- Cargo Operators:FedEx Express and UPS Airlines prioritize dedicated network slices for package tracking.
- Maintenance Providers:Lufthansa Technik and ST Engineering use 5G for augmented reality troubleshooting and parts logistics.
Airlines absorb the bulk of installed capacity; aircraft manufacturers are expanding most quickly through line-fit programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon foundries in Taiwan and South Korea supply the mmWave chipsets anchoring aviation 5G hardware manufacturing. Ground station deployments cluster near major hub airports where FAA and EASA mandates drive equipment refresh cycles. Equipment vendors coordinate certification timelines across three regulatory jurisdictions.
United States
FAA NextGen equipage deadlines compel carriers to replace legacy satellite links with 5G ground-to-air systems. The FCC's C-band reallocation near airport approaches forces power reductions that expand base station density requirements. Dallas-Fort Worth International and Hartsfield-Jackson Atlanta anchor multi-carrier spectrum sharing agreements coordinated by federal regulators.
Germany
DFS Germany manages ground station deployment for surveillance and communications infrastructure across major hubs. The EU's F-Gas Regulation phases out refrigerants in legacy ground station cooling systems, mandating thermal-efficient 5G upgrades. Frankfurt Airport and Munich Airport drive procurement volume for massive MIMO arrays with aviation-specific beam patterns.
China
MIIT and NMPA jointly govern aviation 5G certification through GB standards and equipment type approval processes. Beijing Capital International and Shanghai Pudong anchor factory-installed 5G modem programs for next-generation narrowbody platforms. Domestic carriers commit to infrastructure upgrades under central government airspace modernization directives.
United Kingdom
NATS coordinates ground station deployment for surveillance infrastructure serving transatlantic corridor traffic. The UK Civil Aviation Authority aligns certification timelines with EASA harmonization protocols for cross-border operations. London Heathrow anchors private wireless deployments for tarmac vehicle tracking and baggage handling integration.
Japan
METI governs spectrum allocation for aviation use cases through coordinated ministry-industry working groups. Tokyo Haneda and Osaka Kansai pilot edge computing nodes for predictive maintenance pipelines serving regional MRO providers. Domestic airlines retrofit narrowbody fleets with connectivity hardware to capture ancillary revenue streams.
5G in Aviation Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue private wireless campus networks and cargo-specific network slicing applications. The vendor base spans Nordic telecom infrastructure specialists, North American in-flight connectivity incumbents, and Asian semiconductor suppliers. Three archetypes dominate: ground station system integrators, onboard hardware specialists, and chipset suppliers. Capacity expansion and strategic partnerships represent the dominant competitive moves as carriers restructure procurement around throughput-based pricing.
Within the infrastructure tier, Ericsson and Nokia exemplify ground station system integrators leveraging Open RAN architectures for aviation-specific deployments. Gogo LLC anchors the onboard hardware specialist position. These three occupy positions across the value chain without proprietary claims to specific market segments or technologies.
| Leading Market Players |
|---|
| Ericsson |
| Nokia |
| Huawei |
| Gogo LLC |
| Qualcomm |
| Cisco Systems |
| AT&T |
| Verizon |
| Panasonic Avionics |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up telecom infrastructure specialists have consolidated massive MIMO array production across Nordic manufacturing clusters, tightening supply discipline while forcing airlines into throughput-based pricing contracts that bundle hardware procurement with guaranteed service-level agreements.
Pricing Analysis
Warranty and service-bundling separates premium aviation 5G contracts from commodity hardware sales. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and after-sales support intensity. Cost compression in standard-tier ground station hardware is intensifying because airlines now evaluate total cost of ownership against passenger satisfaction metrics. Low-cost carriers exhibit highest price sensitivity; air navigation service providers demonstrate lowest sensitivity due to FAA and EASA mandate-driven procurement timelines.
Supply Chain Analysis
Domestic-content mandates in China's GB standards certification process and India's phased manufacturing program are reshaping sourcing patterns for aviation 5G equipment. mmWave chipset fabrication draws from Taiwan and South Korea; massive MIMO array assembly rests on Sweden and Finland. Single-source vulnerability concentrates in Taiwan semiconductor foundries serving aviation-qualified component demand. Distribution runs through direct OEM relationships with Ericsson, Nokia, and Gogo LLC rather than channel intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The FAA's NextGen airspace modernization mandates and EASA's parallel equipage timelines create a cost-of-compliance barrier that protects certified incumbents while raising entry costs for unqualified competitors.
For Market Incumbents: Hedge against Open RAN disruption by accelerating software-defined baseband development while locking in multi-year spectrum sharing agreements at Hartsfield-Jackson Atlanta and Dallas-Fort Worth International. Certification investment represents the critical lever for defending against emerging private wireless specialists targeting secondary hub airports.
For New Entrants and Emerging Players: Enter via cargo-specific network slicing applications for cold-chain pharmaceutical tracking, where dedicated latency guarantees command premium pricing. Secondary hubs in India and Southeast Asia offer the most penetrable geography; ground handling agency partnerships provide the lowest-friction go-to-market pathway.
For Investors and Strategic Acquirers: Distressed-cycle entries favor semiconductor component suppliers with aviation-qualified mmWave chipsets in South Korea and Taiwan, where foundry capacity expansions temporarily compress margins. Long-term viability hinges on 5G-Advanced standard adoption for autonomous aircraft coordination; monitor FAA spectrum reallocation proceedings as the inflection signal for infrastructure refresh timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Open RAN Architecture Deployment | Disaggregated baseband processing at Frankfurt Airport reduces proprietary hardware lock-in for DFS Germany. |
| Edge Computing Node Installation | Runway-threshold micro data centers enable Lufthansa Technik predictive maintenance with sub-5-millisecond latency. |
| Network Slicing for Cargo Operations | Dedicated virtual networks support FedEx Express cold-chain monitoring with guaranteed bandwidth isolation. |
| Aviation-Specific Certification Investment | DO-160G environmental qualification opens Boeing and Airbus factory-installed modem programs. |
| Private Wireless Campus Deployment | Secondary hub 5G networks integrate Swissport baggage handling with tarmac vehicle tracking systems. |
Research Approach
Independent corroboration across FAA NextGen program documentation, EASA certification registries, and MIIT equipment type approval filings underwrites the qualitative findings. Primary interviews with airline connectivity procurement directors, ground station system integrators, air navigation service provider engineering leads, and semiconductor component suppliers combined with secondary validation from customs trade data, SEC infrastructure vendor filings, and spectrum allocation databases. Bottom-up equipment shipment tallies and top-down carrier capex surveys were triangulated to anchor market sizing.
Comparable-period anchoring tied projection assumptions to historical NextGen equipage trajectories and satellite-to-5G migration patterns observed across North American carrier fleets. The analytical framework modeled technology deployment, application segment, infrastructure type, and end-user category dimensions throughout the forecast period. CAGRs were derived from equipment refresh cycle analysis and mandate-driven procurement schedules, with inputs from mmWave spectrum availability timelines and airworthiness certification backlog durations.
Forecast precision tightens around the base case; tail outcomes carry wider variance under cross-border spectrum harmonization failures or altimeter interference regulatory reversals. Forecasts reflect documented assumptions regarding FAA and EASA mandate adherence, foundry capacity expansion schedules, and airline ancillary revenue monetization progress. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Navigation and Communication
Global Drone Navigation System Market
Aircraft Navigation and Communication
Global Flight Navigation System Market
Aircraft Navigation and Communication
5G Adoption Analysis in Aviation Market
Aircraft Navigation and Communication
Aviation Weather Radar Market
Aircraft Navigation and Communication
Aircraft Communication System Market
Aircraft Navigation and Communication
Air Traffic Management Software Market
Aircraft Navigation and Communication
Global Aircraft Antenna Market
Aircraft Navigation and Communication
Asia-Pacific VHF Air-Ground Communication Stations Market
Aircraft Navigation and Communication
Air Traffic Control Market
Aircraft Navigation and Communication
Airborne Situational Awareness Systems Market
Aircraft Navigation and Communication
America Air Traffic Management Market
Aircraft Navigation and Communication
Air Traffic Management Market
Aircraft Navigation and Communication
Airspace and Procedure Design Market
Aircraft Navigation and Communication
Automatic Dependent Surveillance-Broadcast (ADS-B) Market
Aircraft Navigation and Communication
Digital Radiosonde Market
Aircraft Navigation and Communication
Airborne Telemetry Market