
 Air Traffic Management Software Market | 2026-2036
Air Traffic Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Air Traffic Management Software Market Analysis
Defense organizations are collapsing procurement timelines for next-generation air traffic management platforms. Thales Group leverages its vertical integration across surveillance and communications subsystems to sustain program wins across NATO member states. L3Harris Technologies anchors its position through R&D intensity in flight data processing architectures. RTX Corporation dominates the North American defense segment with channel control over FAA and Department of Defense procurement pathways.
Air traffic management software comprises integrated digital platforms that process radar feeds, flight plans, and meteorological data to coordinate aircraft separation and flow management, typically operating with sub-second latency requirements and 99.999% uptime thresholds. Flight data processing systems lead the product type category as aging mainframe replacements accelerate across ANSPs worldwide. Cloud-based deployment models represent the fastest-expanding segment as sovereign cloud frameworks mature and security certifications for aviation-critical workloads harden. Decision support tools concentrate margin pools where AI-based systems and machine learning tools command premium pricing against legacy rule-based algorithms.
The FAA's NextGen program and Europe's Single European Sky ATM Research framework reshape product standards by mandating trajectory-based operations and system-wide information management compatibility. Eurocontrol's interoperability requirements and the ICAO Global Air Navigation Plan create compliance barriers that favor suppliers with multi-jurisdiction certification depth. Stakeholders must monitor how China's GB standards for civil aviation software and its dual carbon goals for airport infrastructure reshape procurement criteria for vendors seeking access to the country's expanding airport construction pipeline.
Market Dynamics
The FAA's NextGen modernization mandate and Europe's Single European Sky initiative are forcing air navigation service providers into accelerated software replacement cycles, compressing procurement timelines from decade-long refresh periods to continuous upgrade schedules.
Growth Catalysts
- Trajectory-based operations mandate:The FAA's NextGen program requires flight data processing systems capable of four-dimensional trajectory management, pulling ANSPs toward modern platforms.
- China's airport construction pipeline:Dual carbon goals for airport infrastructure under GB standards are creating procurement demand for energy-optimized traffic management software in new hub developments.
- AI-based decision support:Machine learning tools for conflict detection and flow optimization are commanding premium positioning as defense organizations expand procurement of intelligent automation layers.
Market Restraints
- Certification timeline friction:ICAO Global Air Navigation Plan compliance requirements and multi-jurisdiction safety certifications extend vendor onboarding to 18-36 months.
- Legacy system entrenchment:Aging mainframe architectures in established ANSPs create technical debt that resists modular replacement without full-stack overhaul.
- Specialized talent scarcity:Deep expertise in both aviation operations and real-time software engineering concentrates among a narrow contractor pool, inflating implementation costs.
Strategic Opportunities
- Sovereign cloud maturation:Security certifications for aviation-critical workloads are hardening in Germany and France, enabling cloud-based deployment models previously blocked by data sovereignty concerns.
- Urban air mobility integration:Unmanned aircraft system traffic management requirements are opening new application layers for low-altitude coordination software in advanced city deployments.
- Carbon-neutral airport incentives:EU Green Deal funding mechanisms favor software vendors offering fuel-burn optimization and continuous descent approach tooling.
Industry Challenges
- Interoperability complexity:Eurocontrol's system-wide information management standards demand seamless data exchange between heterogeneous national systems with incompatible legacy protocols.
- Cyber-physical security integration:Real-time systems with 99.999% uptime thresholds require simultaneous hardening against network intrusions without latency degradation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Traffic Management Software Market |
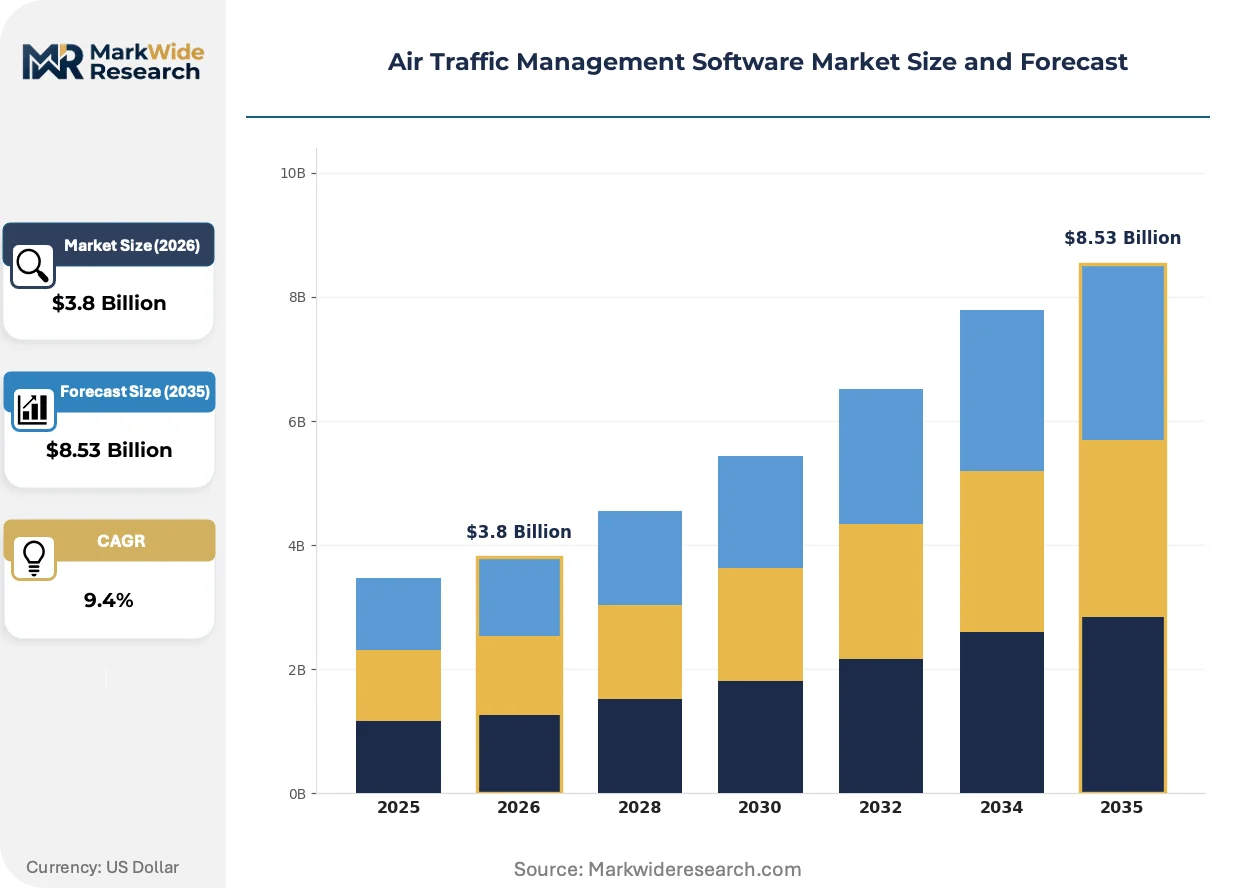
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air Traffic Control Systems, Flight Data Processing Systems, Surveillance Systems, Decision Support Tools Deployment Model: On-Premises, Cloud-Based, Hybrid, Managed Services End User: Airports, Airlines, Government Agencies, Defense Organizations Technology: AI-Based Systems, Machine Learning Tools, IoT Devices, Data Analytics Solutions |
| Companies Covered | Thales Group, RTX Corporation, L3Harris Technologies, Inc., Honeywell International Inc., Indra Sistemas, S.A., Leonardo S.p.A., Lockheed Martin Corporation, BAE Systems, Frequentis AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Traffic Management Software Market Emerging Trajectories
Software architectures are pivoting from centralized mainframe processing toward distributed edge computing nodes, enabling faster conflict resolution while complicating system-wide synchronization.
Machine learning-based predictive analytics is supplanting rule-based decision algorithms in flight data processing systems. ANSPs in the United States and Germany are deploying neural network models for traffic flow prediction within 24-month procurement windows. This shift is compressing competitive positioning toward vendors with captive AI training infrastructure and aviation-specific data repositories.
Europe's F-Gas Regulation and CSRD reporting requirements are reshaping procurement criteria for airport infrastructure software. Vendors must now document embedded carbon in hardware lifecycles and refrigerant leakage from associated cooling systems. The flight data processing segment faces the steepest compliance burden as these systems operate continuously in climate-controlled facilities.
Service unbundling is fragmenting traditional long-term maintenance contracts. ANSP procurement teams in China and the United States are separating software licenses from implementation support and ongoing algorithm tuning. This pattern concentrates margin pressure on vendors while creating openings for specialized system integrators with regional regulatory expertise.
Air Traffic Management Software Market Segmentation
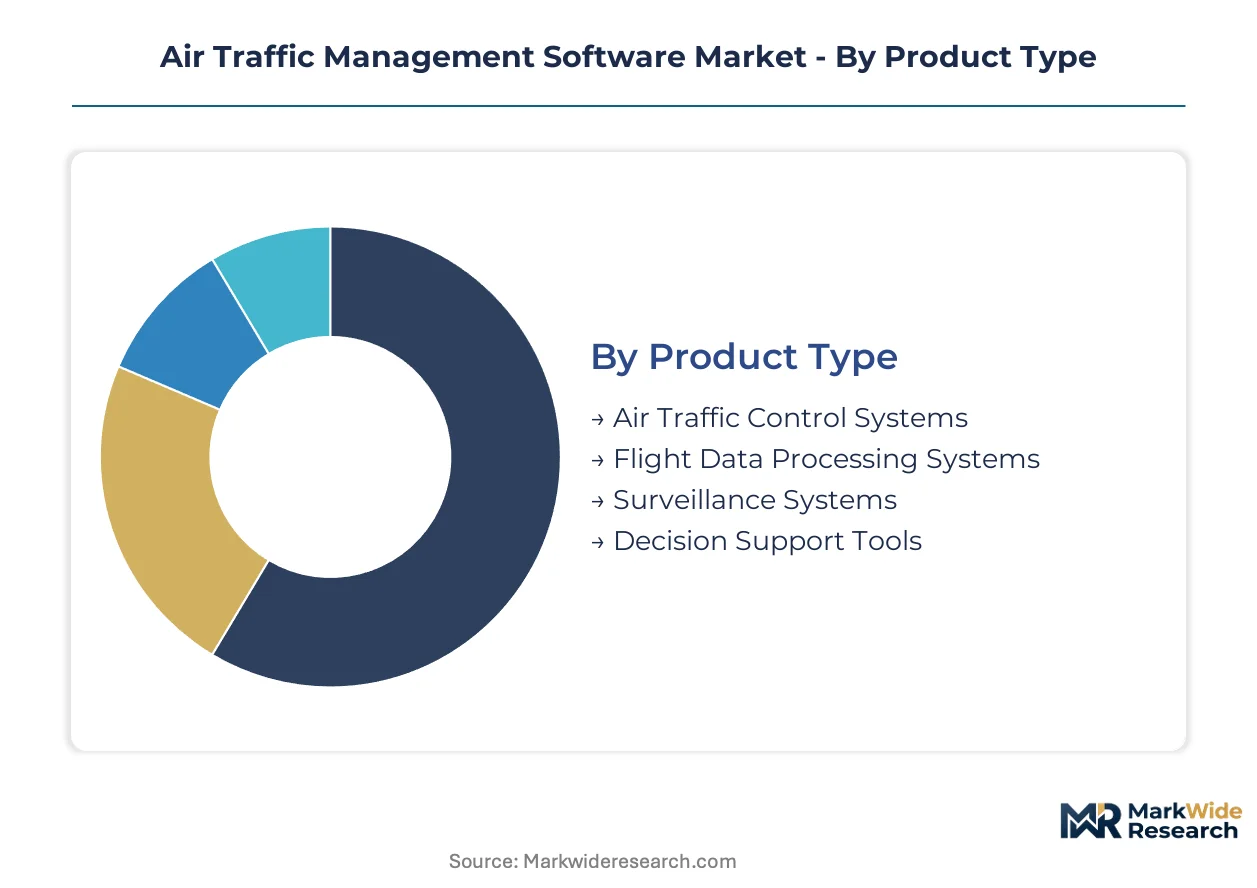
Air traffic management software segments reflect divergent procurement channels, from sovereign defense contracts to commercial airline SaaS subscriptions. ANSPs and airport authorities route purchasing through distinct vendor qualification pathways, shaping how each segment reaches end-users.
Product Type:
Flight data processing systems and decision support tools flow through direct vendor-ANSP relationships, while surveillance hardware often routes via systems integrators with airfield construction contracts.
- Flight Data Processing Systems:These platforms ingest radar feeds, flight plans, and meteorological data to calculate aircraft separation minima with sub-second latency. Demand concentrates in Germany and the United States as ANSPs replace aging mainframe architectures under NextGen and SESAR mandates. The FAA's trajectory-based operations requirements are accelerating procurement timelines for four-dimensional capable platforms.
- Decision Support Tools:AI-based conflict detection and flow optimization modules command premium positioning in defense procurement channels. China's GB standards for civil aviation software are reshaping qualification criteria for vendors seeking access to hub airport developments.
- Air Traffic Control Systems:Integrated tower and en-route control platforms with 99.999% uptime thresholds.
- Surveillance Systems:Radar and multilateration processing software bundled with sensor hardware deployments.
By volume, flight data processing systems lead procurement activity across NATO member states. By growth pace, decision support tools are climbing the fastest as machine learning capabilities displace rule-based algorithms.
Deployment Model:
Cost tier stratification separates sovereign cloud deployments in France and Germany from budget-constrained on-premises installations in emerging aviation markets.
- Cloud-Based:Sovereign cloud frameworks in Germany and France now carry aviation-critical security certifications previously blocking data residency requirements. ANSP procurement teams are unbundling licenses from infrastructure, creating openings for specialized integrators with regional regulatory expertise.
- On-Premises:Legacy air-gapped installations persist where data sovereignty concerns or latency requirements preclude external hosting. Aging mainframe architectures in established ANSPs create technical debt that resists modular replacement without full-stack overhaul.
- Hybrid:Split architectures processing sensitive flight data locally while pushing analytics to cloud tiers.
- Managed Services:Outsourced operational support models gaining traction where specialized talent scarcity inflates internal implementation costs.
By installed base, on-premises retains the largest footprint. By expansion trajectory, cloud-based deployment is gaining share fastest as security certifications harden.
End User:
Application focus varies sharply: defense organizations prioritize AI-based decision layers, while commercial airports emphasize passenger throughput optimization.
- Government Agencies:Civil aviation authorities and ANSPs dominate procurement volume for system-wide replacements. Eurocontrol's interoperability requirements create compliance barriers favoring vendors with multi-jurisdiction certification depth.
- Defense Organizations:Military air traffic management demands hardened cyber-physical security integration without latency degradation. Procurement timelines are compressing from decade-long refresh periods to continuous upgrade schedules.
- Airports:Hub operators seeking fuel-burn optimization and continuous descent approach tooling under EU Green Deal mechanisms.
- Airlines:Carriers investing in fleet-wide flight data analytics for operational performance management.
By contract value, government agencies lead. By procurement velocity, defense organizations are expanding most quickly as NATO members modernize joint theater airspace management.
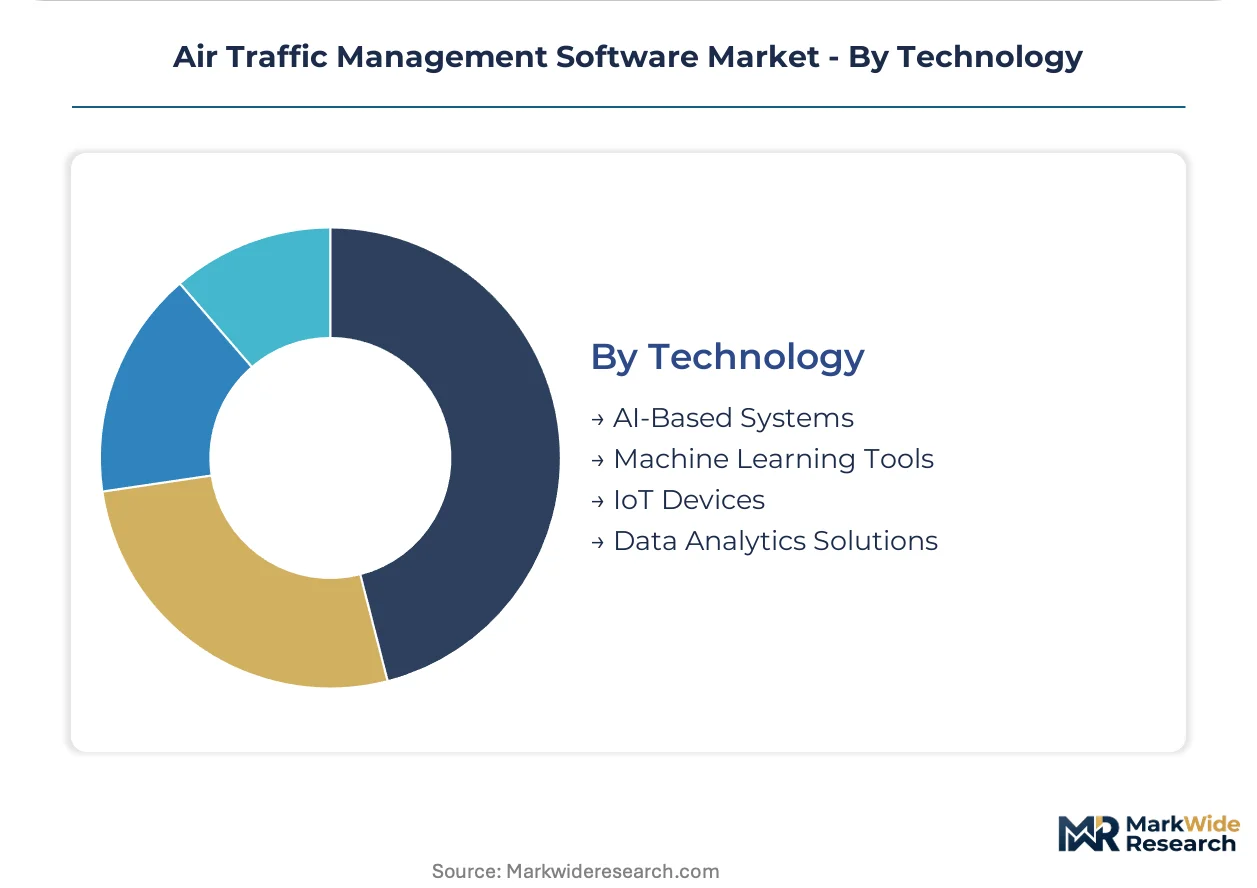
Technology:
Customer type segmentation separates established ANSPs with captive data repositories from new entrants purchasing training-ready platforms.
- AI-Based Systems:Neural network models for traffic flow prediction and conflict detection are supplanting rule-based algorithms. ANSPs in the United States and Germany are deploying these within compressed procurement windows.
- Machine Learning Tools:Predictive analytics for runway capacity optimization and weather impact modeling. Demand concentrates where vendors possess aviation-specific training datasets.
- IoT Devices:Sensor networks for surface movement guidance and environmental monitoring integration.
- Data Analytics Solutions:Business intelligence layers for ANSP operational performance and regulatory reporting.
By current deployment, data analytics solutions hold the widest installed base. By capability investment, AI-based systems are advancing fastest as defense procurement prioritizes intelligent automation layers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German ATM software vendors export trajectory-based operations platforms to ANSPs across Central and Eastern Europe, while US suppliers channel NextGen-certified systems through FAA procurement pathways to allied defense ministries.
United States
The FAA's NextGen modernization mandate compresses procurement timelines for flight data processing replacements. Military air traffic management demands from the Department of Defense prioritize hardened cyber-physical security integration. Greater Washington DC hosts the densest concentration of defense-aviation contractors serving joint theater airspace management programs.
Germany
Deutsche Flugsicherung drives demand for sovereign cloud-certified ATM platforms under national data residency requirements. The EU Green Deal and F-Gas Regulation reshape procurement criteria toward carbon-neutral airport infrastructure software. Frankfurt and Munich hub developments anchor software deployment for energy-optimized traffic management systems.
China
Dual carbon goals for airport infrastructure under GB standards create procurement demand for energy-optimized traffic management software. The country's expanding airport construction pipeline requires civil aviation software meeting domestic certification frameworks. Beijing and Shanghai metropolitan clusters concentrate new hub developments deploying advanced flow optimization platforms.
France
DGAC and DSAC interoperability requirements favor vendors with multi-jurisdiction certification depth across Eurocontrol frameworks. ANSP procurement teams unbundle software licenses from implementation support under evolving service models. Toulouse and Paris aviation clusters sustain development of trajectory-based operations tooling for European SESAR deployment.
United Kingdom
NATS procurement prioritizes AI-based decision support layers for conflict detection and flow optimization capabilities. Post-Brexit regulatory divergence creates parallel certification pathways for vendors seeking UK ANSP access. London terminal airspace modernization drives demand for continuous descent approach and fuel-burn optimization software.
Air Traffic Management Software Market Vendor Landscape
Player mix skews toward integrated defense-aerospace conglomerates with captive surveillance and communications subsystem capabilities. Market structure concentrates around three tiers: full-stack platform vendors, specialized decision support module suppliers, and systems integrators with regional regulatory expertise. Dominant competitive moves include backward integration into sensor hardware production and strategic partnerships with sovereign cloud infrastructure providers.
Among French integrated defense groups, Thales Group exemplifies the full-stack archetype spanning surveillance subsystems through software platforms. RTX Corporation and L3Harris Technologies, Inc. anchor the North American defense segment, with the former representing channel control over FAA procurement pathways and the latter occupying a position in R&D-intensive flight data processing architectures. These three entities collectively illustrate how vertical control over communications and radar subsystems sustains program wins across NATO modernization cycles.
| Leading Market Players |
|---|
| Thales Group |
| RTX Corporation |
| L3Harris Technologies, Inc. |
| Honeywell International Inc. |
| Indra Sistemas, S.A. |
| Leonardo S.p.A. |
| Lockheed Martin Corporation |
| BAE Systems |
| Frequentis AG |
| Others |
Supply Flow & Price Mechanics
Long-term service contracts with embedded algorithm-tuning clauses lock in multi-year revenue visibility for ATM software vendors while binding ANSPs to specific upgrade cadences under FAA NextGen and Eurocontrol SESAR mandates. These arrangements concentrate pricing power with full-stack platform providers who bundle flight data processing licenses with sovereign cloud infrastructure commitments in Germany and France.
Pricing Analysis
Next-generation AI-based decision support tools command substantial premiums over legacy rule-based flight data processing systems, while prior-generation mainframe architectures face accelerated price erosion as ANSPs accelerate replacement timelines. Three-tier pricing structure across premium AI-enabled platforms, standard trajectory-based operations suites, and economy-grade surveillance-software bundles reflects certification-grade differentiation under ICAO Global Air Navigation Plan standards. Pricing pressure stems from service unbundling trends in China and the United States, where procurement teams separate software licenses from implementation support. Defense organizations exhibit lowest price sensitivity given mission-critical uptime requirements, while emerging aviation markets in Southeast Asia drive hardest bargain on standard-tier deployments.
Supply Chain Analysis
Strategic stockpiling of aviation-grade compute hardware dominates procurement strategy among ANSPs preparing for sovereign cloud migrations, contrasting with just-in-time software delivery models for routine module updates. Supply concentrates in the United States for flight data processing architectures, Germany for radar subsystem integration, and France for tower automation platforms. Component dependencies span aviation-certified servers, real-time operating system licenses, and specialized meteorological data feeds. Single-source vulnerability runs through concentrated radar sensor manufacturing in NATO-aligned supply bases. Distribution runs through direct vendor-ANSP relationships for core platforms, with systems integrators handling peripheral surveillance hardware deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ATM software markets fragment across procurement channel specialization, as unbundling of licenses from implementation support creates openings for regional system integrators with regulatory expertise. Sovereign cloud maturation and urban air mobility integration are spawning niche demand pockets outside incumbent full-stack dominance.
For Market Incumbents: Secure channel control over FAA and Eurocontrol certification pathways to defend against modular entrants unbundling decision support tools from integrated platforms. Deepen backward integration into sensor hardware production to sustain margin pools as software-only vendors capture unbundled maintenance contracts. Lock in long-term data residency agreements with German and French sovereign cloud providers before regional integrators consolidate regulatory relationships.
For New Entrants and Emerging Players: Lead with AI training infrastructure and aviation-specific data repositories to penetrate compressed procurement windows in United States and German ANSPs. Target urban air mobility traffic management modules where legacy vendors lack low-altitude coordination expertise. Pursue partnership-first go-to-market models with established systems integrators possessing Eurocontrol interoperability certification depth.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap specialists with captive AI development capabilities and multi-jurisdiction certification portfolios across NATO and Asia-Pacific markets. Five-to-ten year viability hinges on trajectory-based operations mandate compliance rather than legacy mainframe replacement cycles. Watch for inflection when China's GB standards for civil aviation software achieve reciprocal recognition with ICAO frameworks, opening procurement access to foreign vendors.
| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Certification | Enables data residency compliance for German and French ANSP procurement under national security frameworks. |
| AI Module Unbundling | Creates standalone revenue streams for decision support tools outside traditional full-stack platform sales. |
| Urban Air Mobility Integration | Opens low-altitude coordination software demand as cities deploy advanced unmanned traffic management. |
| Carbon-Neutral Airport Tooling | Aligns vendor offerings with EU Green Deal funding mechanisms for fuel-burn optimization platforms. |
| Defense Channel Deepening | Accelerates procurement velocity as NATO members modernize joint theater airspace management systems. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FAA NextGen program documentation, Eurocontrol SESAR implementation reports, ICAO Global Air Navigation Plan filings, and ANSP procurement disclosures. Interviews with air traffic control operations directors, aviation software procurement leads, sovereign cloud infrastructure architects, and defense aviation program officers informed demand-side validation. Bottom-up triangulation across flight data processing system deployments and top-down reconciliation against ANSP budget allocations anchored market sizing.
Segmentation dimensions modeled span product type, deployment architecture, end-user category, and technology generation across the projection horizon. CAGRs derive from trajectory-based operations mandate compliance timelines and AI-based decision support procurement velocity. Forecast inputs incorporate airport construction pipeline data from China's GB standards framework and NATO defense modernization program disclosures.
The analysis sits within stated boundaries; outcomes outside sustained FAA NextGen funding continuity or Eurocontrol interoperability agreement stability would require recalibration. Forecasts reflect assumptions regarding certification timeline standardization and sovereign cloud security hardening progression. Revision becomes warranted when China's civil aviation software certification reciprocity thresholds cross into formal mutual recognition agreements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Navigation and Communication
Aircraft Navigation System Market
Aircraft Navigation and Communication
America Air Traffic Management Market
Aircraft Navigation and Communication
Global Flight Navigation System Market
Aircraft Navigation and Communication
Air Traffic Management Market
Aircraft Navigation and Communication
Airborne Situational Awareness Systems Market
Aircraft Navigation and Communication
Defense Advanced GPS Receiver (DAGR) Market
Aircraft Navigation and Communication
Air-Based Tactical Data Link Market
Aircraft Navigation and Communication
Ultra Short Base Line Positioning System Market
Aircraft Navigation and Communication
Automatic Dependent Surveillance-Broadcast (ADS-B) Market
Aircraft Navigation and Communication
Digital Radiosonde Market
Aircraft Navigation and Communication
Airborne High Frequency Radio Market
Aircraft Navigation and Communication
Airborne Radars Market
Aircraft Navigation and Communication
Ground to Air on-Board Connectivity Market
Aircraft Navigation and Communication
Connected Aircraft Market
Aircraft Navigation and Communication
Airspace and Procedure Design Market
Aircraft Navigation and Communication
Europe Inertial Systems Market