
 Aircraft Communication System Market | 2026-2036
Aircraft Communication System Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Communication System Market Analysis
Aircraft systems engineering talent scarcity is redrawing competitive boundaries across the avionics supply chain. Thales Group leverages its Galileo ground segment expertise to dominate European satcom integration programs. Honeywell International Inc. sustains aftermarket revenue through proprietary data link protocols that lock in fleet operators. L3Harris Technologies specializes in military waveform cryptography, anchoring its position in defense communication architectures.
An aircraft communication system comprises transmitters, receivers, antennas, and control interfaces operating across VHF, HF, and satellite frequency bands to enable voice and data exchange between flight crews, air traffic controllers, and ground networks. These systems typically process signals through software-defined radio architectures with 25 kHz channel spacing in VHF aeronautical bands to ensure interference-resistant connectivity during all flight phases. Satcom and data link segments are capturing the fastest expansion as airlines replace analog voice-centric equipment with broadband-connected flight decks for real-time weather and operational data. VHF communication remains the mature revenue base due to mandatory carriage requirements for terminal area operations, though margin pools are migrating toward cloud-based ground infrastructure.
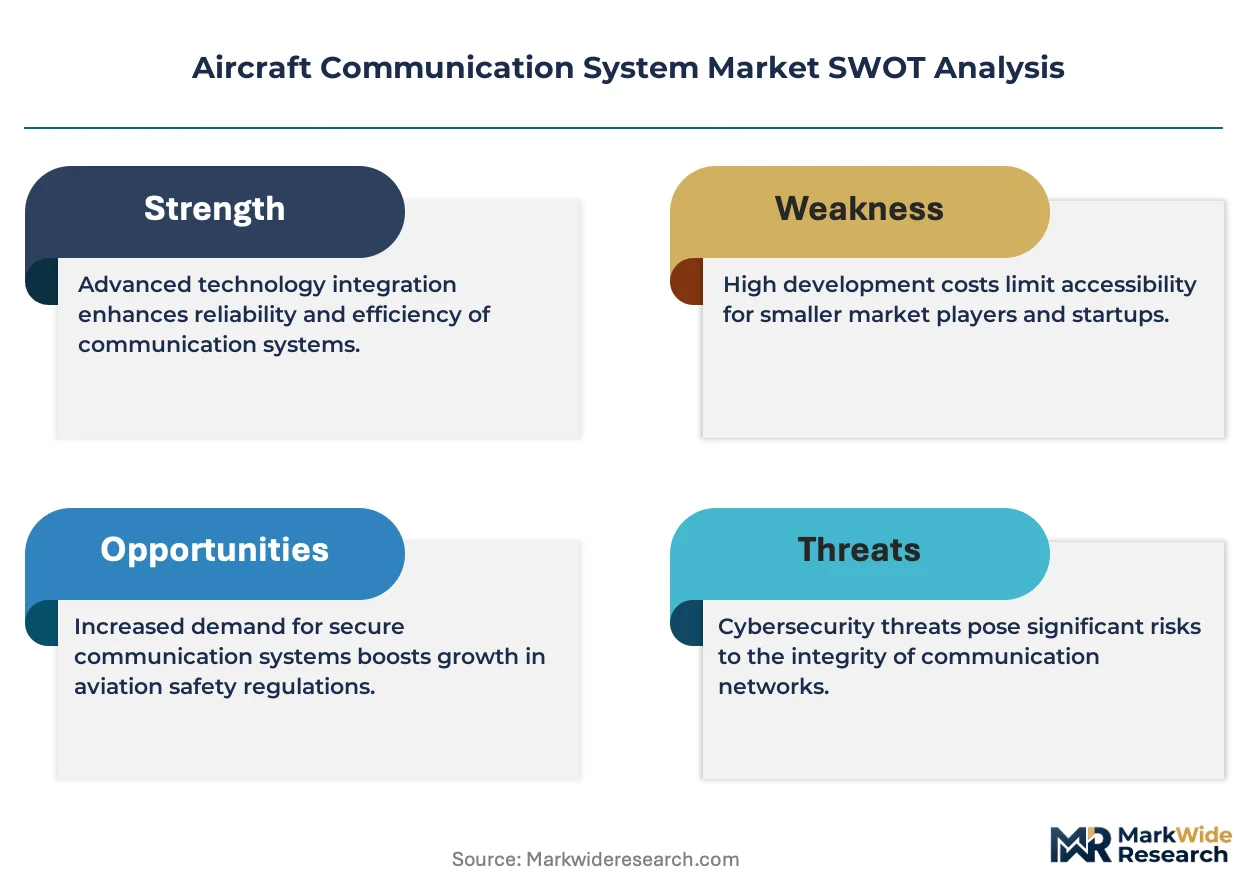
The FAA mandates DO-178C software certification and DO-254 hardware assurance for all new communication equipment deployed in US-registered aircraft, creating compliance barriers for non-domestic suppliers. EASA's CS-25 airworthiness codes and the EU's Cyber Resilience Act are converging to demand encrypted, tamper-resistant avionics interfaces across European fleets. Stakeholders must weigh certification pathway costs against the operational advantages of multi-frequency, multi-orbit connectivity architectures as spectrum allocation debates intensify between civil and military users.
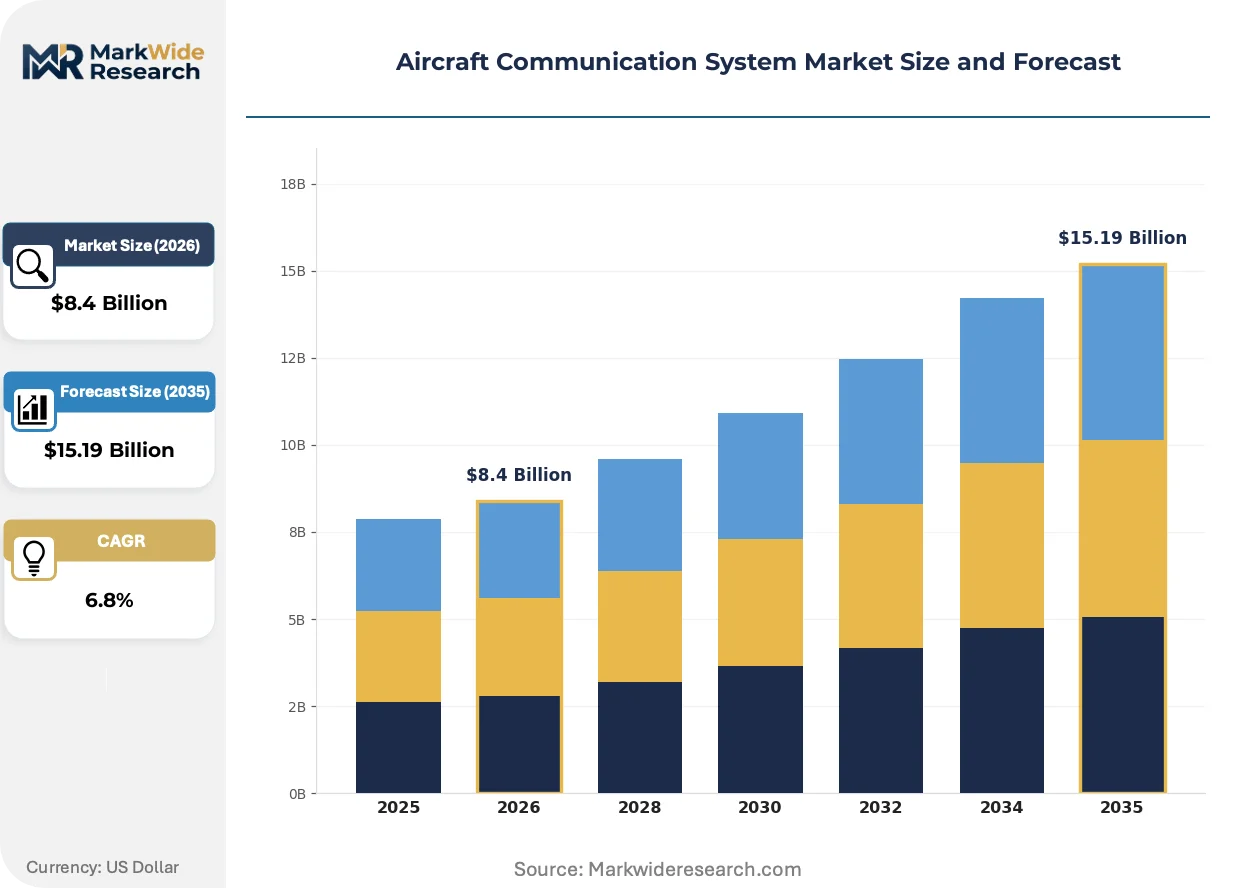
Market Dynamics
The FAA's NextGen modernization mandate is compressing replacement cycles for legacy voice-centric avionics across US-registered fleets. Military procurement across NATO members is simultaneously accelerating demand for encrypted, multi-orbit satellite communication suites.
Growth Catalysts
- NextGen Mandate:The FAA's airspace modernization program requires all commercial aircraft operating in US controlled airspace to deploy data link-equipped flight decks by specified operational dates, forcing systematic hardware refreshes.
- German Defense Modernization:The Bundeswehr's multi-year aircraft upgrade cycle is converging with Lufthansa Technik's commercial fleet renewal programs, creating concentrated demand for software-defined radio platforms in Central Europe.
- Software-Defined Radio Architecture:SDR platforms enable single hardware units to host multiple waveforms, reducing part count and certification burden while supporting seamless transitions between VHF, HF, and satellite frequency bands.
Market Restraints
- DO-178C Certification Burden:The FAA's software assurance standard requires extensive documentation and testing for airborne software, creating compliance barriers that extend development timelines and exclude smaller suppliers.
- Gallium Nitride Supply Concentration:High-frequency power amplifiers for next-generation satcom terminals depend on GaN substrates sourced from a limited set of foundries, exposing the supply chain to geopolitical disruption.
- Spectrum Allocation Tension:Civil aeronautical bands face encroachment from terrestrial 5G deployments and military requirements, creating regulatory friction that delays equipment certification.
Strategic Opportunities
- EU Cyber Resilience Act Alignment:EASA's CS-25 airworthiness codes are converging with EU-wide cybersecurity mandates, creating regulatory tailwinds for suppliers offering encrypted, tamper-resistant avionics interfaces.
- Multi-Orbit Connectivity Integration:Convergence of geostationary, medium-earth, and low-earth orbit networks enables seamless handoff architectures that guarantee connectivity redundancy across oceanic and polar routes.
- Cloud-Based Ground Infrastructure:Airlines are unbundling traditional maintenance contracts in favor of subscription-based ground network services, opening recurring revenue streams for communication service providers.
Industry Challenges
- DO-254 Hardware Assurance Timeline:Complex programmable logic devices require extensive verification against the FAA's hardware design assurance standard, stretching certification cycles and compressing product margins.
- Legacy Analog Integration Complexity:New digital communication suites must maintain backward compatibility with aging VHF ground station infrastructure, adding software overhead and testing burden.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Communication System Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: VHF Communication, HF Communication, Satcom, Data Link End User: Commercial Aviation, Military Aviation, Business Jets, General Aviation Technology: Analog, Digital, 3D Voice, Cloud-based Systems Application: Pilot Communication, Flight Data Exchange, Air Traffic Control, Cabin Communication |
| Companies Covered | Thales Group, General Dynamics Corporation, Honeywell International Inc., Iridium Communications Inc., Northrop Grumman Corporation, L3Harris Technologies, Viasat Inc., Cobham Plc, RTX Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Communication System Market Emerging Trajectories
Aviation communication architectures are pivoting from analog voice-centric systems toward broadband-connected flight decks capable of real-time operational data exchange. This transformation is reshaping supplier value capture and fleet operator technology roadmaps.
Software-defined radio platforms are bifurcating the installed base between legacy hardware-defined units and programmable multi-waveform systems. Major carriers operating long-haul fleets are prioritizing SDR adoption to reduce spare parts inventory and enable remote configuration updates. The technology is bifurcating competitive positioning between integrated platform vendors and specialized waveform developers.
EASA's Cyber Resilience Act is mandating encrypted, tamper-resistant interfaces across European-registered aircraft, with compliance deadlines cascading through type certificate amendment schedules. The regulation is compelling avionics suppliers to redesign control interfaces and establish secure software update pipelines. European fleet operators are responding by consolidating procurement around vendors with demonstrated cybersecurity certification track records.
Airlines are compressing communication equipment refresh cycles from historical ten-year intervals toward five-to-seven-year horizons driven by cybersecurity patch requirements and feature velocity. Traditional equipment lessors and aftermarket service providers are losing share to manufacturer-direct subscription models. This behavioral shift is most pronounced among US-based low-cost carriers with younger, more homogeneous fleets.
Aircraft Communication System Market Segmentation
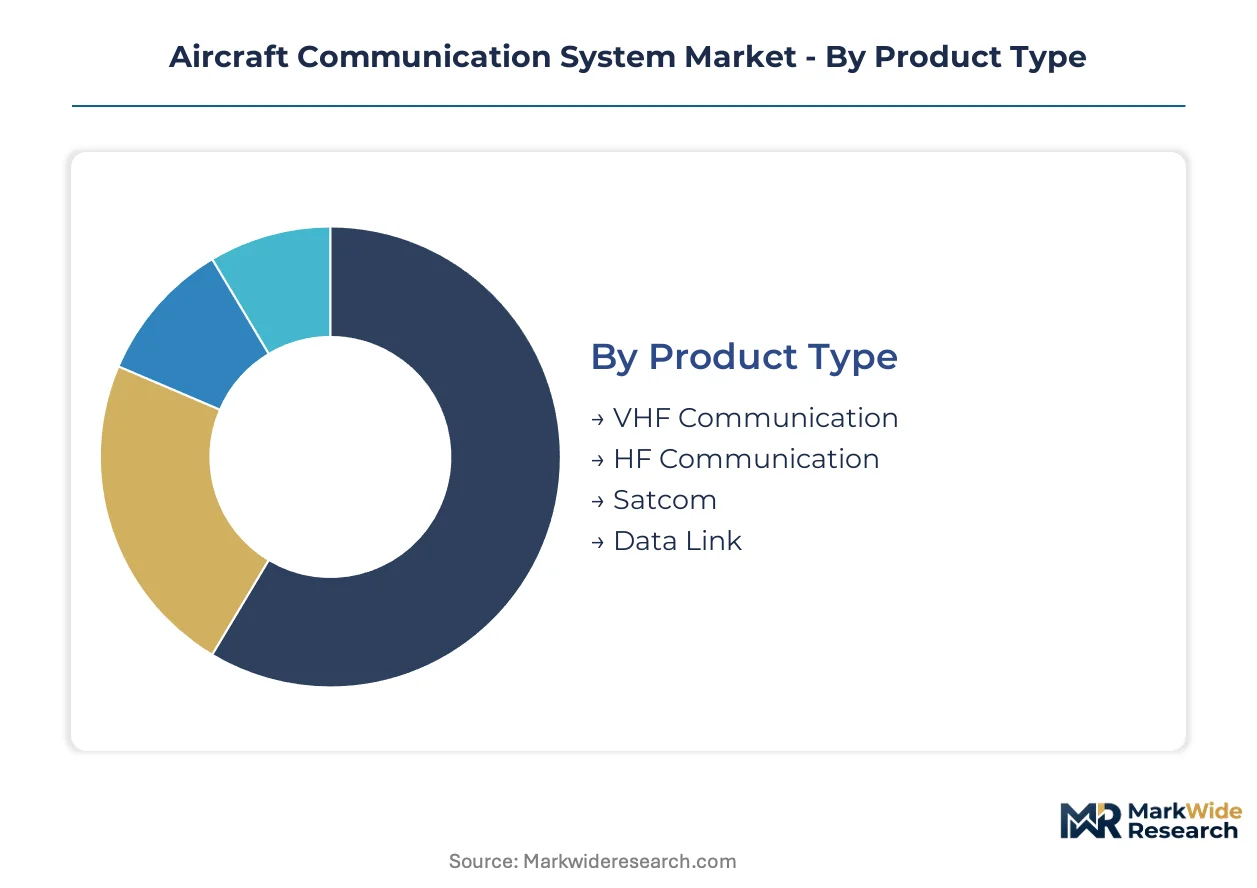
Aircraft communication system procurement patterns diverge sharply across product architectures, operator types, and deployment environments. Understanding these fault lines reveals where certification investments concentrate and which technology transitions offer the steepest return trajectories for suppliers.
Product Type:
Domestic demand in Germany and France anchors VHF and HF equipment procurement, while Satcom and Data Link adoption tracks export-led airline fleet modernization across Middle Eastern and Asia-Pacific carriers.
- VHF Communication:Operating in the 118-137 MHz aeronautical band with 25 kHz channel spacing, these systems remain mandatory for terminal area operations under FAA and EASA carriage rules. European short-haul operators in Germany and France sustain replacement demand as legacy analog units face cybersecurity retrofit mandates.
- Satcom:Ku-band and Ka-band satellite terminals enable broadband connectivity across oceanic and polar routes where ground-based infrastructure is absent. Middle Eastern long-haul carriers operating Boeing 777 and Airbus A350 fleets are driving adoption of multi-orbit terminals that hand off between geostationary and low-earth orbit constellations.
- HF Communication:High-frequency systems provide beyond-line-of-sight voice coverage over remote terrain and oceanic regions where VHF ground stations cannot reach. Polar route operators maintain these as regulatory backup systems despite declining primary usage.
- Data Link:ACARS and ATN-B1 protocols enable digital messaging between flight decks and ground networks for flight plan updates and weather dissemination. FAA NextGen compliance deadlines are compressing installation timelines across US-registered narrowbody fleets.
VHF Communication commands the established base. The steepest expansion runs through Satcom.
End User:
Cost tier segmentation separates military-grade encrypted platforms from commercial aviation's price-sensitive procurement, with business jets occupying a mid-tier bandwidth where customization premiums apply.
- Commercial Aviation:Full-service and low-cost carriers operate the largest installed base, with fleet-wide standardization reducing spare parts complexity. US major airlines are consolidating suppliers around vendors offering integrated VHF, Satcom, and data link platforms to simplify line maintenance.
- Military Aviation:NATO member air forces demand NSA-certified encryption, anti-jam waveforms, and compatibility with sovereign satellite constellations. The Bundeswehr's multi-year helicopter and transport fleet upgrade is concentrating procurement authority in Germany's defense acquisition office.
- Business Jets:Fractional ownership fleets and ultra-high-net-worth operators prioritize cabin connectivity and concierge dispatch services over cockpit functionality. Installations emphasize compact antenna footprints and rapid reconfiguration between aircraft types.
- General Aviation:Part 91 operators in the US and private pilots in Europe select portable or panel-mounted units based on minimum equipment list requirements and cost thresholds. Garmin and Collins Aerospace dominate this price-sensitive segment with certified but non-integrated offerings.
Commercial Aviation absorbs the highest absolute volume. Military Aviation is gaining share fastest as defense budgets accelerate encrypted platform procurement.
Technology:
Application maturity separates legacy analog architectures still serving general aviation from digital and cloud-based systems now standard in transport category aircraft.
- Digital:Software-defined radio architectures host multiple waveforms on reprogrammable hardware, enabling remote configuration updates and reducing part number proliferation. EASA's Cyber Resilience Act is mandating encrypted digital interfaces across European-registered fleets.
- Cloud-based Systems:Ground network functions migrate to hosted infrastructure, enabling subscription-based service models and continuous feature deployment. Airlines are unbundling traditional equipment purchases in favor of connectivity-as-a-service contracts with satellite operators.
- Analog:Legacy amplitude modulation voice systems persist in general aviation and as regulatory backup in older transport aircraft. Manufacturing volume concentrates in Southeast Asian contract facilities serving the aftermarket.
- 3D Voice:Spatial audio processing separates multiple simultaneous radio transmissions into distinct perceptual channels, reducing pilot workload during high-density terminal operations. Adoption tracks next-generation cockpit human factors requirements in Airbus and Boeing development programs.
Analog retains residual presence in the long tail of the installed base. Cloud-based Systems are climbing the fastest as fleet operators abandon capital-intensive ownership models.
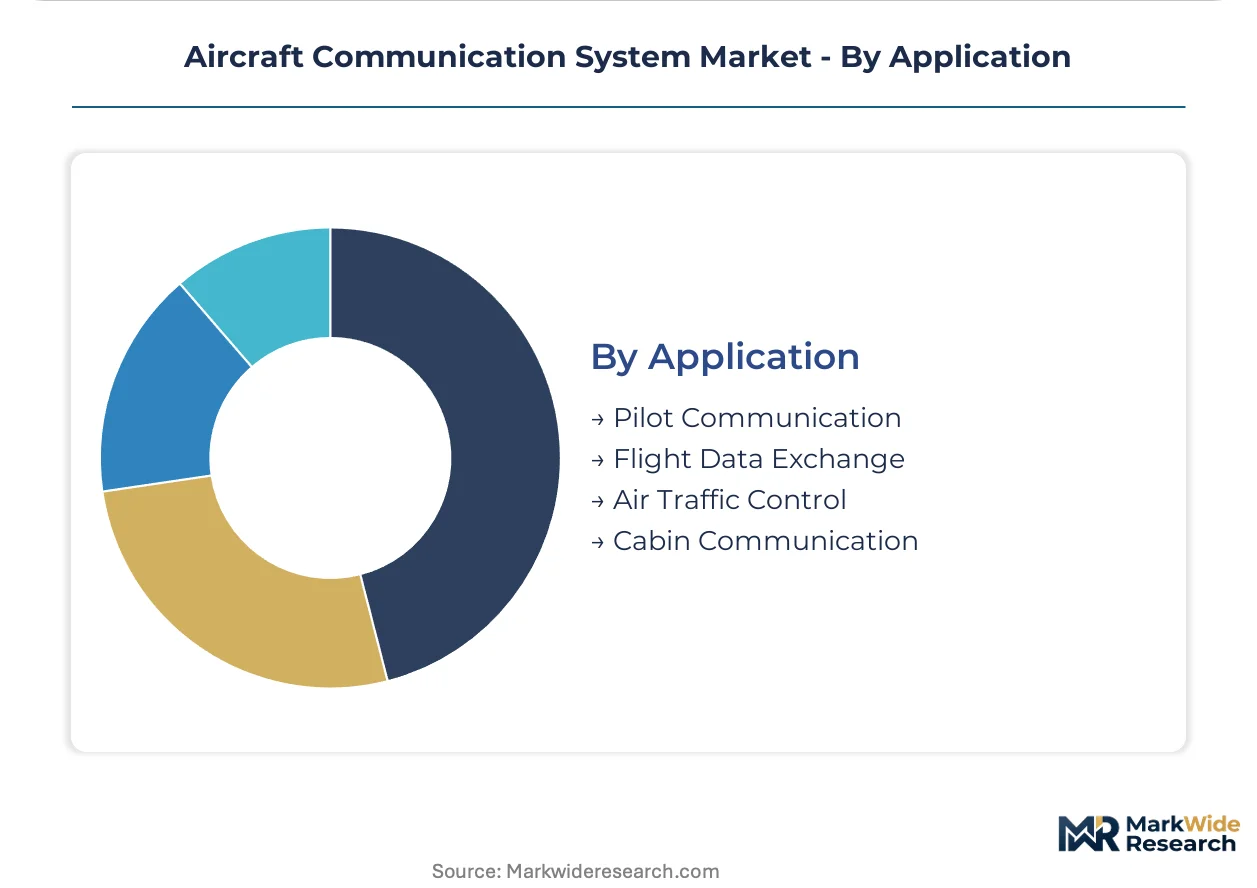
Application:
Customer type segmentation separates safety-critical pilot communication from operational efficiency applications where procurement authority rests with airline IT departments rather than flight operations.
- Pilot Communication:Voice and data exchange between flight deck and air traffic control remains the regulatory foundation of all certified systems. FAA and EASA mandate dual independent communication paths for extended overwater operations.
- Flight Data Exchange:Real-time transmission of engine parameters, position reports, and operational metrics enables predictive maintenance and fuel optimization. Low-cost carriers with homogeneous fleets are prioritizing this capability for network-wide efficiency gains.
- Air Traffic Control:Ground infrastructure integration demands standardized message formats and interoperability testing against national air navigation service providers. Eurocontrol's Maastricht Upper Area Control Center sets interoperability benchmarks for European implementations.
- Cabin Communication:Passenger connectivity, crew coordination, and in-flight entertainment systems operate on separate frequency allocations and certification pathways. This application tracks consumer broadband demand patterns rather than aviation regulatory cycles.
Pilot Communication anchors regulatory compliance spending. Flight Data Exchange is expanding most quickly as airlines operationalize real-time analytics for fuel and maintenance optimization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German defense procurement while US commercial aviation operates on compressed margins driven by FAA mandate compliance. European suppliers extract premiums from encrypted platform requirements, whereas Asia-Pacific carriers prioritize cost-optimized data link retrofits.
United States
FAA NextGen deadlines force narrowbody fleet retrofits across American, Delta, and United operations. The agency's DO-178C certification requirements exclude non-domestic suppliers from critical data link contracts. Seattle-Tacoma aerospace clusters host integration facilities where Collins Aerospace and Honeywell pre-certify combined VHF-satcom platforms.
Germany
Bundeswehr helicopter modernization converges with Lufthansa Technik commercial renewal cycles on software-defined radio procurement. EASA CS-25 amendments align with EU Cyber Resilience Act deadlines, mandating encrypted avionics interfaces. Hamburg's Lufthansa Technik campus anchors dual-use platform development serving military and civilian operators simultaneously.
France
Dassault Aviation and Airbus Defence & Space sustain demand for sovereign satellite communication suites with NSA-resistant encryption. ANSM cybersecurity guidelines for connected aircraft systems tighten procurement specifications. Toulouse aerospace corridors concentrate Thales Group integration facilities serving NATO interoperability requirements.
United Kingdom
RAF Typhoon and F-35 upgrade programs drive classified waveform development alongside civilian data link mandates. Civil Aviation Authority adoption of FAA-equivalent software assurance standards raises barriers for non-certified suppliers. Farnborough-Aldershot defense clusters house Cobham Plc and Northrop Grumman facilities focused on multi-orbit terminal integration.
Japan
JAL and ANA widebody fleet renewals prioritize Ka-band satcom for transpacific routes where VHF infrastructure gaps persist. METI funding for domestic aerospace supply chain resilience supports local integration partnerships. Nagoya aerospace manufacturing corridors concentrate Mitsubishi Heavy Industries avionics subcontracting for Boeing platforms.
Aircraft Communication System Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated platform vendors commanding premium pricing while specialized waveform developers compete on certification velocity. The market structure consolidates around three tiers: full-stack avionics houses, military-grade encryption specialists, and satellite network operators. Dominant competitive moves include strategic partnerships between hardware integrators and constellation operators, plus geographic expansion into German and Japanese defense procurement offices.
Within the integrated platform tier, Thales Group and Honeywell International Inc. occupy positions spanning civil and military certification pathways. L3Harris Technologies exemplifies the military-specialist archetype, anchoring encrypted waveform development for NATO member requirements. These three entities represent distinct strategic postures: European regulatory alignment, aftermarket protocol lock-in, and defense cryptographic certification respectively.
| Leading Market Players |
|---|
| Thales Group |
| General Dynamics Corporation |
| Honeywell International Inc. |
| Iridium Communications Inc. |
| Northrop Grumman Corporation |
| L3Harris Technologies |
| Viasat Inc. |
| Cobham Plc |
| RTX Corporation |
| Others |
Supply Flow & Price Mechanics
Software-defined radio architectures displacing legacy hardware-defined units are simultaneously redrawing supply geography toward semiconductor fabrication centers and compressing pricing premiums for configurable platforms. This substitution dynamic concentrates value capture in programmable logic device suppliers while eroding margins for analog component manufacturers locked into declining replacement cycles.
Pricing Analysis
The customization-premium spread separates military-grade encrypted platforms commanding configured-to-order pricing from commercial aviation's standard-catalog procurement. Three-tier pricing structure across NSA-certified, DO-178C-compliant, and baseline configurations tracks certification burden and encryption complexity. Cost compression in the commercial tier intensifies as airlines consolidate procurement around integrated platform vendors. Low-cost carriers exhibit highest price sensitivity, while NATO defense acquisition offices accept substantial premiums for sovereign waveform compatibility.
Supply Chain Analysis
The United States and Germany anchor high-assurance hardware design and certification testing, while Taiwan and South Korea feed semiconductor substrates for software-defined radio chipsets. Gallium nitride wafers for satcom power amplifiers draw from a concentrated foundry base, creating single-source vulnerability for next-generation terminal production. Distribution runs through avionics integrators maintaining FAA and EASA certification credentials, with final assembly clustering near Seattle-Tacoma, Toulouse, and Hamburg aerospace corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-moat arena where DO-178C and DO-254 certification entrenchment creates switching costs that lock fleet operators into incumbent supplier relationships. The network effect of ground infrastructure compatibility reinforces this defensive structure.
For Market Incumbents: Shield installed base relationships through captive supply of GaN power amplifier modules and accelerated cybersecurity certification pipelines. Deepen backward integration into semiconductor packaging to offset foundry concentration risk. Prioritize EASA Cyber Resilience Act pre-certification to capture European fleet renewal cycles before compliance deadlines cascade. For New Entrants and Emerging Players: Differentiate on rapid DO-254 hardware assurance velocity for commercial aviation's compressed refresh timelines. Target general aviation and business jet segments where certification burden remains lower and price elasticity permits margin extraction. Pursue constellation-operator partnerships for multi-orbit terminal integration rather than competing head-to-head with integrated platform vendors. For Investors and Strategic Acquirers: The market sits at a mandate-driven replacement phase that favors regulatory-entrenched specialists with demonstrated certification track records. Long-term viability rests on cybersecurity patch velocity and cloud-based service model transitions. Acquisition focus should center on waveform cryptography developers and secure software update pipeline operators. The signal to monitor is Bundeswehr procurement authority consolidation and its spillover into dual-use commercial platform demand.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Radio Platform Launch | Enables single hardware units to host multiple waveforms, reducing part count for Lufthansa Technik and Bundeswehr procurement. |
| Multi-Orbit Terminal Integration | Secures connectivity redundancy across oceanic routes for Middle Eastern long-haul carriers operating Boeing 777 fleets. |
| DO-178C Pre-Certification Investment | Creates compliance barriers excluding non-domestic suppliers from FAA NextGen data link contracts. |
| GaN Substrate Supply Agreement | Addresses single-source vulnerability for high-frequency power amplifiers in next-generation satcom terminals. |
| Cloud-Based Ground Network Partnership | Captures recurring subscription revenue as airlines abandon capital-intensive equipment ownership models. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across flight operations executives, avionics procurement managers, certification engineers, and ground network service directors. Primary interview insights combined with secondary validation against FAA type certificate databases, EASA CS-25 amendment records, Eurocontrol interoperability specifications, and defense acquisition office procurement disclosures. Bottom-up equipment installation projections and top-down fleet modernization spend estimates underwent cross-triangulation to anchor segmentation outputs.
Across the analysis window, the forecasting framework modeled product type evolution, end-user procurement authority shifts, technology architecture transitions, and application prioritization by operator segment. CAGRs derived from equipment replacement cycle compression, regulatory mandate phasing, and satellite constellation deployment timelines. Industry-specific inputs incorporated DO-178C certification queue lengths, GaN substrate foundry capacity allocation, and cloud-based service contract penetration rates.
The analysis sits within stated boundaries; outcomes outside sustained FAA NextGen enforcement, EASA-EU Cyber Resilience Act alignment, or stable gallium nitride supply flows would require recalibration. Forecasts reflect documented assumptions regarding mandate compliance velocity and defense budget trajectory. Recalibration cycles align with material shifts in spectrum allocation rulings, cybersecurity regulation amendments, or sovereign satellite constellation deployment schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Navigation and Communication
Europe Inertial Systems Market
Aircraft Navigation and Communication
Asia-Pacific Air Traffic Management Market
Aircraft Navigation and Communication
America Air Traffic Management Market
Aircraft Navigation and Communication
Airborne Telemetry Market
Aircraft Navigation and Communication
Military Navigation Systems Market
Aircraft Navigation and Communication
Global Drone Navigation System Market
Aircraft Navigation and Communication
Air-Based Tactical Data Link Market
Aircraft Navigation and Communication
Automatic Dependent Surveillance-Broadcast (ADS-B) Market
Aircraft Navigation and Communication
Global Air Traffic Control Equipment Market
Aircraft Navigation and Communication
Defense Advanced GPS Receiver (DAGR) Market
Aircraft Navigation and Communication
Aircraft Turn Coordinator Market
Aircraft Navigation and Communication
Asia-Pacific VHF Air-Ground Communication Stations Market
Aircraft Navigation and Communication
Helicopter Meteorological Software Market
Aircraft Navigation and Communication
Airspace and Procedure Design Market
Aircraft Navigation and Communication
Global Aircraft Antenna Market
Aircraft Navigation and Communication
Digital Radiosonde Market