
 Air-Based Tactical Data Link Market | 2026-2036
Air-Based Tactical Data Link Market Size, Share, and Industry Trends Forecast 2026-2036
Air-Based Tactical Data Link Market Analysis
STANAG 5602 certification is reorganizing supplier eligibility across NATO procurement channels. L3Harris Technologies leverages its legacy JTIDS manufacturing footprint to sustain long-term service contracts with allied defense ministries. BAE Systems anchors European supply through its secure communications division in Great Britain. RTX Corporation competes on software-defined radio integration, differentiating its offerings across multiple airborne platforms.
Air-based tactical data links are secure, jam-resistant digital communication systems operating in L-band frequencies to exchange tactical information between aircraft, ground stations, and naval vessels in real time. These systems employ time-division multiple access protocols and embedded encryption to ensure message integrity during contested electromagnetic environments. Link 16 terminals dominate installed base volumes across fighter and command-and-control aircraft, while VHF Data Link segments show concentrated growth in rotary-wing and unmanned platform applications. Network management services capture expanding margin pools as militaries outsource system maintenance and spectrum coordination rather than building organic capabilities.
The US DoD's open systems architecture mandates and NATO STANAG standards shape product roadmaps, forcing hardware vendors toward modular designs that ease third-party integration. The FAA and national spectrum regulators in Germany, France, and Italy constrain frequency allocations, directly limiting transmission power and range specifications available to manufacturers. Stakeholders must monitor shifting electromagnetic spectrum policy across defense and civilian aviation authorities to anticipate platform certification timelines and competitive positioning requirements.
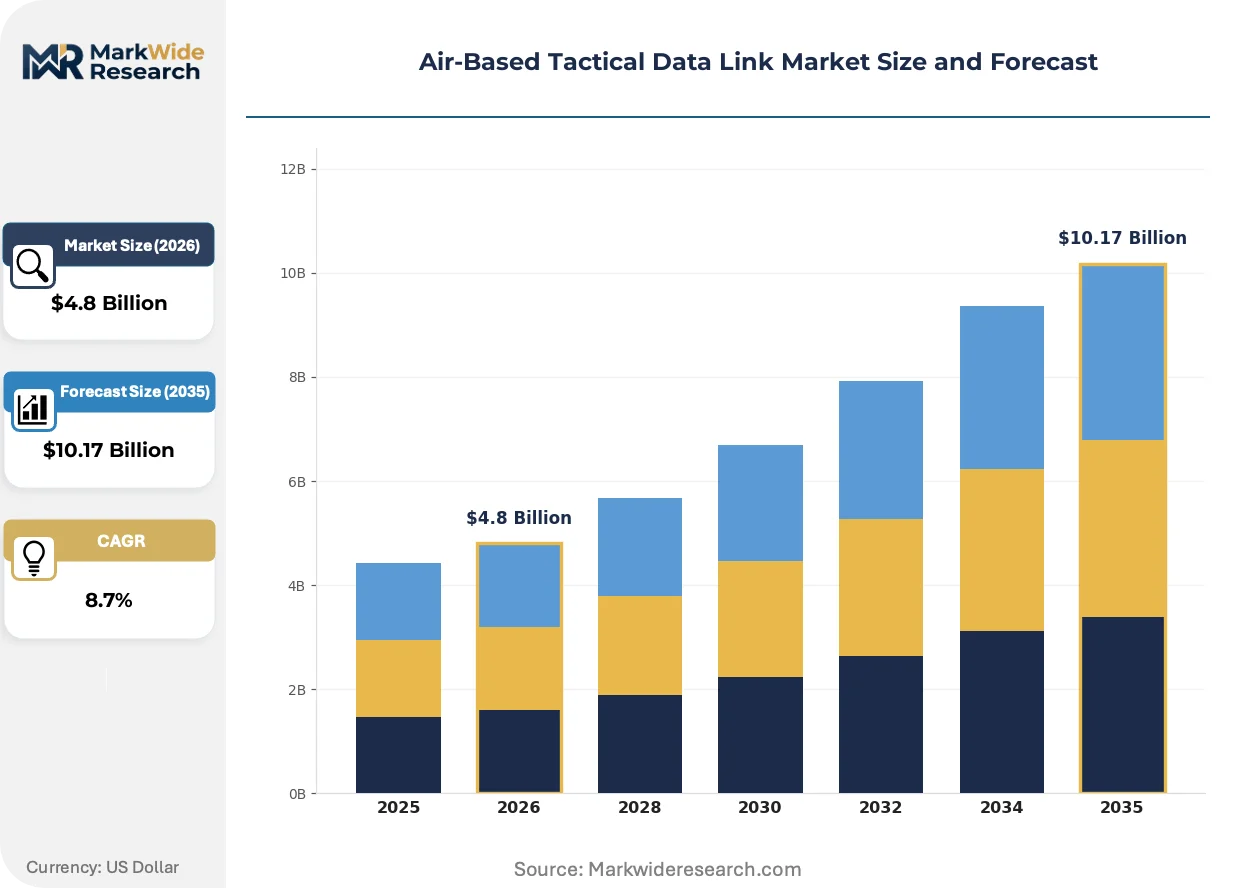
Market Dynamics
The US DoD's open systems architecture mandates are forcing hardware vendors toward modular, software-defined radio designs that enable third-party integration across NATO fighter modernization programs.
Growth Catalysts
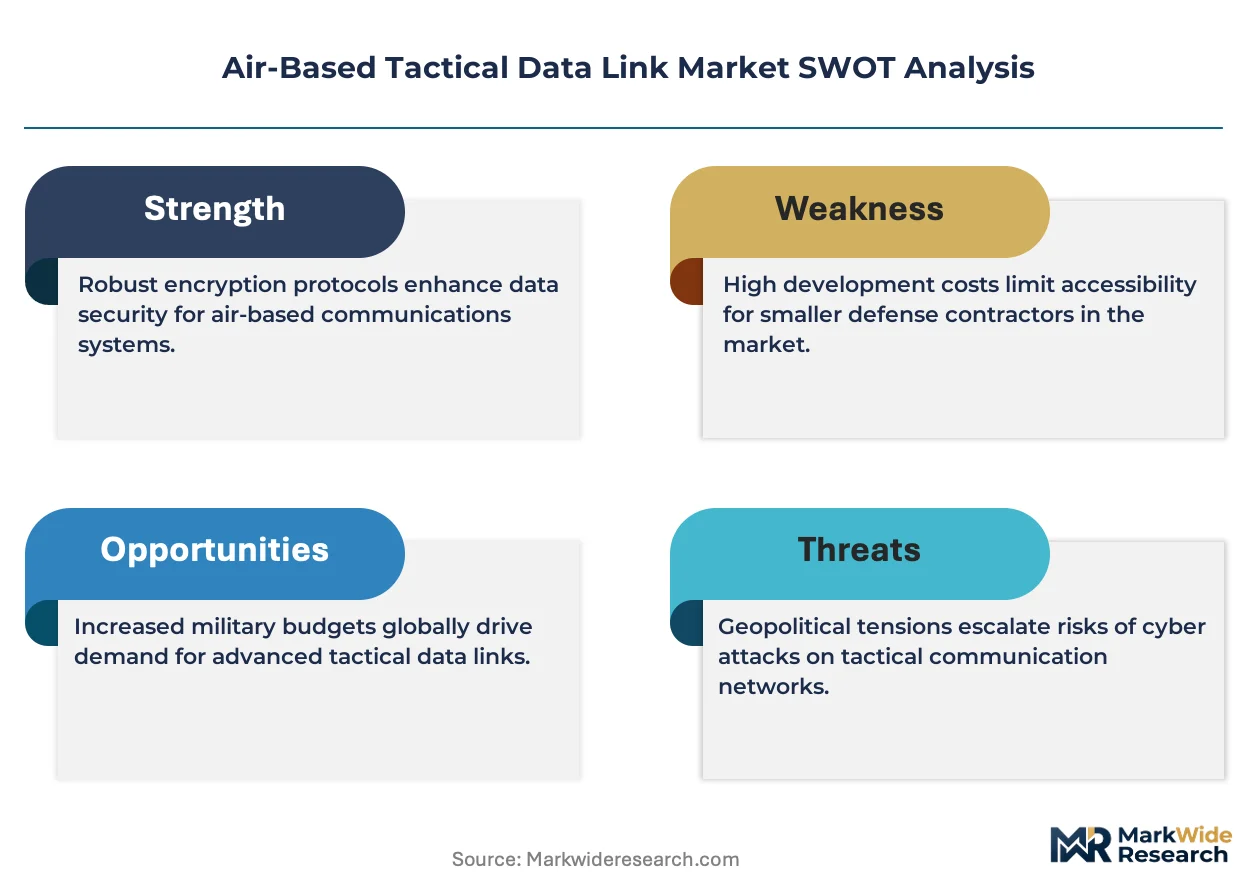
- STANAG 5602 Certification:NATO's interoperability standard is expanding supplier eligibility across allied procurement channels, accelerating terminal replacement cycles in European air forces.
- Multi-Domain Operations Doctrine:US, British, and Australian military strategies prioritize networked command-and-control architectures, driving Link 16 terminal upgrades on fourth- and fifth-generation fighter platforms.
- Unmanned Aerial Vehicle Proliferation:Rotary-wing and drone applications are expanding demand for compact VHF Data Link segments beyond traditional manned fighter installations.
Market Restraints
- Spectrum Allocation Constraints:The FAA and German, French, and Italian national regulators limit L-band transmission power and range specifications, compressing operational envelopes for airborne terminals.
- Input Cost Volatility:Specialized gallium nitride semiconductors and radiation-hardened components face concentrated sourcing from limited foundry capacity, creating supply vulnerability.
- Certification Timeline Friction:Platform-specific military airworthiness approvals from defense ministries add 18-36 months to deployment schedules, delaying revenue recognition for hardware vendors.
Strategic Opportunities
- Network Management Services Outsourcing:Militaries in the United States and United Kingdom are shifting spectrum coordination and system maintenance to contractor-led models, capturing recurring revenue streams.
- Software-Defined Radio Convergence:Integration of cognitive radio algorithms with existing Link 16 infrastructure enables waveform adaptability without hardware replacement.
- Australian Defense Modernization:The Royal Australian Air Force's AIR 6500 integrated air and missile defense program creates demand for interoperable tactical data link terminals across F-35 and E-7A platforms.
Industry Challenges
- Legacy Platform Integration Complexity:Retrofitting JTIDS-compatible terminals onto aging F-15, F-16, and Tornado airframes requires custom mechanical and electrical engineering, inflating non-recurring engineering costs.
- Cybersecurity Certification Burden:NSA Type 1 encryption approval and NATO SECAN requirements demand specialized secure manufacturing facilities with limited auditor capacity, constraining production scale-up.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air-Based Tactical Data Link Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Link 16, Link 11, JTIDS, VHF Data Link Service Type: Communication Services, Network Management, Data Processing, Training Services End User: Military, Defense Contractors, Government Agencies, Aerospace Manufacturers Deployment: On-premises, Cloud-based, Hybrid, Mobile |
| Companies Covered | General Dynamics Corporation, L3Harris Technologies, Inc., Thales Group, Elbit Systems Ltd., Leonardo S.p.A., BAE Systems plc, RTX Corporation, Curtiss-Wright Corporation, Northrop Grumman Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air-Based Tactical Data Link Market Emerging Trajectories
Software-defined architectures are displacing fixed-function hardware across airborne communications, enabling waveform portability and reducing platform-specific development cycles for tactical data link terminals.
Waveform virtualization technology is bifurcating the installed base between legacy fixed-format Link 16 terminals and adaptive software-defined implementations. Fifth-generation fighter programs in the United States and United Kingdom are adopting virtualized stacks, while older platforms remain hardware-constrained. This split is compressing margins on legacy terminal production while expanding service revenue from software licensing and firmware updates.
REACH and RoHS compliance requirements in Europe are restricting hazardous substance use in printed circuit board manufacturing and solder compositions. Terminal vendors serving NATO procurement channels must reformulate component supply chains to maintain CE marking eligibility. German and French defense ministries are prioritizing green procurement criteria in tender evaluations, affecting supplier selection for airborne radio programs.
Buyer concentration among prime defense contractors is consolidating subsystem sourcing decisions. Lockheed Martin, Boeing, and BAE Systems are exerting greater control over data link terminal specifications on platform contracts, compressing tier-two vendor negotiation leverage. This pattern is most visible in F-35 Lightning II production, where airframe-integrated communications subsystems limit aftermarket terminal opportunities for independent suppliers.
Air-Based Tactical Data Link Market Segmentation
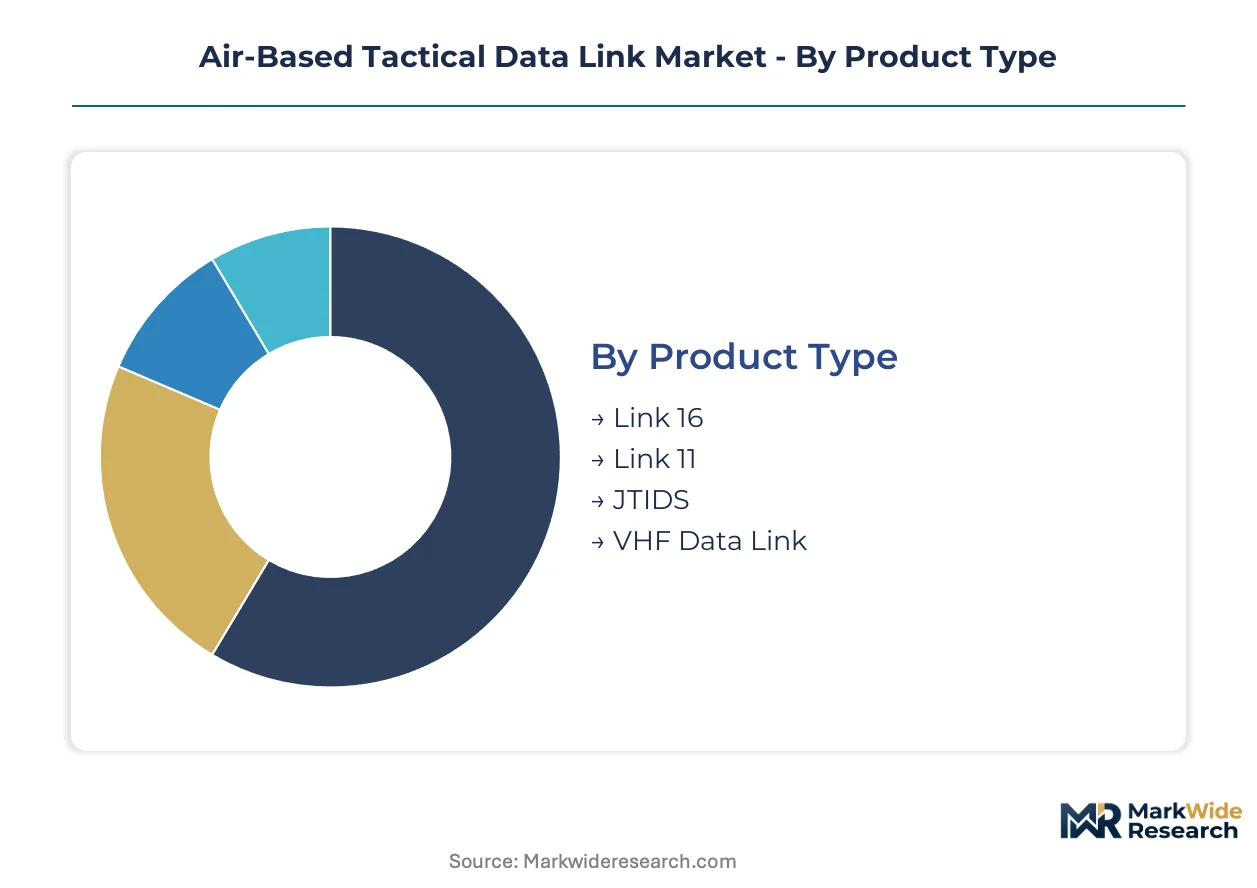
Segmentation in air-based tactical data links reveals distinct procurement patterns across NATO air forces and allied defense ministries. Product architecture, service delivery models, and deployment constraints each shape vendor positioning and contract structures differently.
Product Type:
Channel flows diverge sharply between hardware terminals and software-defined implementations, with prime contractors controlling platform-integrated sales while aftermarket opportunities concentrate on modular upgrades.
- Link 16:Time-division multiple access terminals operating in L-band frequencies provide jam-resistant tactical messaging between fighter aircraft and command nodes. NATO air forces in the United States, United Kingdom, and Australia drive procurement through F-35 and E-7A platform modernization, constrained by STANAG 5602 certification timelines.
- JTIDS:Joint Tactical Information Distribution System terminals represent the legacy installed base across fourth-generation fighter fleets. Retrofit demand concentrates on F-15 and F-16 sustainment programs where hardware obsolescence forces replacement cycles.
- Link 11:HF and UHF data link standard persists in naval-air coordination scenarios requiring beyond-line-of-sight propagation.
- VHF Data Link:Compact form factors suit rotary-wing and unmanned platforms with severe size-weight-power constraints.
By volume, Link 16 leads. By growth pace, VHF Data Link is expanding most quickly.
Service Type:
Cost tier stratification separates commodity communication services from high-margin network management, with defense ministries outsourcing spectrum coordination to capture operational flexibility.
- Network Management:Contractor-led spectrum allocation, crypto key distribution, and link quality monitoring generate recurring revenue streams. The US DoD and British Ministry of Defence have shifted toward service-based contracts, avoiding organic capability buildup.
- Communication Services:Real-time message routing and relay operations form the operational backbone of multi-domain command architectures. Australian Defense Force requirements under AIR 6500 are accelerating procurement of managed link services for integrated air and missile defense.
- Data Processing:Sensor fusion and track correlation algorithms transform raw link data into actionable intelligence.
- Training Services:Simulator-based operator certification and maintenance instruction support field readiness.
By contract value, Network Management commands premium pricing. By expansion trajectory, Communication Services are gaining share fastest.
End User:
Customer type determines specification authority, with military operators defining requirements while aerospace manufacturers control integration architecture.
- Military:Air force procurement offices in NATO member states specify terminal performance, encryption standards, and interoperability mandates. The US Air Force, Royal Air Force, and Royal Australian Air Force dominate volume through fighter and command-and-control platform programs.
- Aerospace Manufacturers:Lockheed Martin, Boeing, and BAE Systems integrate data link subsystems during airframe production, limiting aftermarket access for independent terminal vendors. F-35 production lines exemplify this concentration.
- Defense Contractors:Tier-two suppliers bid for subsystem contracts on platform modernization programs.
- Government Agencies:National spectrum regulators and defense research organizations influence standard adoption.
By procurement volume, Military leads. By margin capture, Aerospace Manufacturers are pulling ahead.
Deployment:
Maturity gradients separate field-proven on-premises installations from emerging cloud architectures, with hybrid models bridging classified and unclassified operational domains.
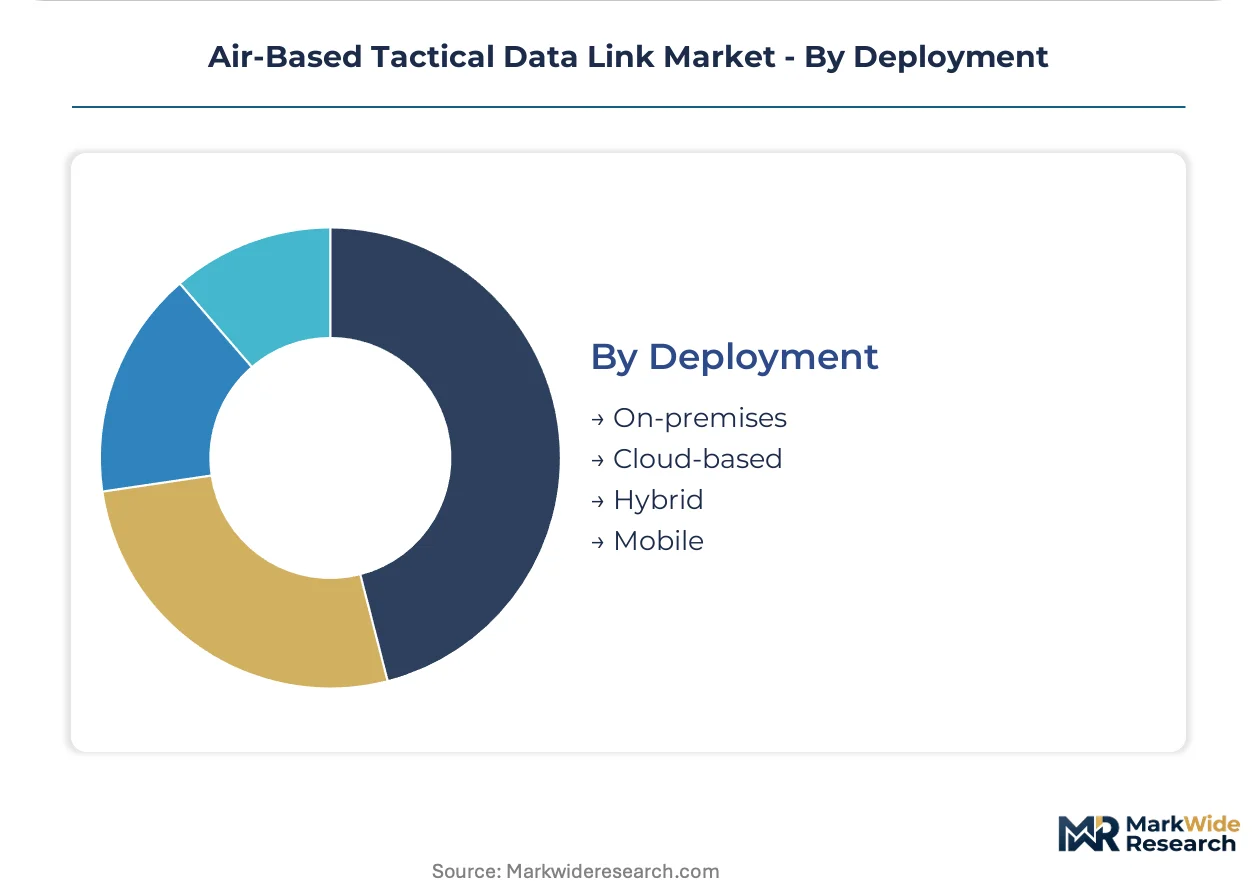
- On-premises:Air-gapped terminals with embedded NSA Type 1 encryption dominate operational deployments where electromagnetic isolation is mandatory. German, French, and Italian air forces maintain strict on-premises requirements for national command networks.
- Hybrid:Classified tactical data remains on local hardware while logistics and training migrate to secured cloud infrastructure. The US DoD's Commercial Cloud Enterprise and British Defence Digital programs are piloting this architecture.
- Cloud-based:Unclassified network management and spectrum planning tools are shifting to contractor-hosted environments.
- Mobile:Deployable ground stations and airborne relay platforms enable expeditionary operations.
By installed base, On-premises dominates. By transition momentum, Hybrid is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US DoD's open systems architecture mandates are accelerating procurement cycles across NATO air forces, with national spectrum regulators in Germany, France, and Italy constraining transmission specifications. Fighter modernization programs and unmanned platform proliferation are reshaping demand geography.
United States
The US Air Force's F-35 and E-7A platform programs drive Link 16 terminal volume through STANAG 5602 certification requirements. The FAA limits L-band transmission power for airborne terminals, compressing operational range specifications. Defense contractors in the Baltimore-Washington corridor and Dallas-Fort Worth aerospace cluster are integrating software-defined radio architectures into production lines.
United Kingdom
Royal Air Force networked command-and-control priorities under the Multi-Domain Operations doctrine sustain JTIDS replacement demand. The British Ministry of Defence's Commercial Cloud Enterprise program is piloting hybrid deployment architectures for network management services. BAE Systems' secure communications division in Great Britain anchors European supply for NATO interoperability programs.
Germany
The German Air Force's Tornado and Eurofighter sustainment programs create retrofit demand for JTIDS-compatible terminals. REACH and RoHS compliance requirements restrict hazardous substance use in printed circuit board manufacturing, forcing supply chain reformulation. Defense electronics suppliers in Bavaria and Baden-Württemberg are adapting component sourcing to maintain CE marking eligibility.
Australia
The Royal Australian Air Force's AIR 6500 integrated air and missile defense program generates demand for interoperable tactical data link terminals across F-35 and E-7A platforms. The country's national spectrum regulator coordinates frequency allocations with defense requirements. Aerospace integration facilities in South Australia and Victoria are expanding platform modification capacity for Link 16 upgrades.
France
French Air and Space Force Rafale modernization programs prioritize Link 16 terminal integration for NATO interoperability. ANSM and national defense procurement authorities enforce cybersecurity certification timelines for encryption modules. Thales Group's communications systems division in the Île-de-France region sustains domestic manufacturing for export and allied programs.
Air-Based Tactical Data Link Market Vendor Landscape
Listed leaders compete with private specialists across platform integration and aftermarket service delivery. The vendor base organizes around prime defense contractors controlling airframe-integrated subsystem specifications, with tier-two suppliers bidding for modular upgrade contracts. Two strategic archetypes dominate: full-spectrum platform integrators and waveform-agnostic software-defined radio specialists. Competitive moves concentrate on strategic partnerships for open architecture compliance and geographic expansion into Australian and British modernization programs.
Within the platform integrator tier, General Dynamics Corporation and Northrop Grumman Corporation exemplify listed defense conglomerates anchoring long-term service contracts with allied ministries. L3Harris Technologies, Inc. occupies a position representing legacy JTIDS manufacturing specialists transitioning toward software-defined implementations. These three entities collectively illustrate the competitive tension between hardware-anchored installed bases and modular, third-party-integrable architectures demanded by US DoD mandates.
| Leading Market Players |
|---|
| General Dynamics Corporation |
| L3Harris Technologies, Inc. |
| Thales Group |
| Elbit Systems Ltd. |
| Leonardo S.p.A. |
| BAE Systems plc |
| RTX Corporation |
| Curtiss-Wright Corporation |
| Northrop Grumman Corporation |
| Others |
Supply Flow & Price Mechanics
Foundry utilization rates for gallium nitride and radiation-hardened semiconductor capacity establish price floors across NATO procurement channels, concentrating supply leverage with specialized defense electronics manufacturers in the United States and United Kingdom. Scale advantages in NSA Type 1 secure manufacturing facilities translate directly into bidding power for Link 16 terminal contracts, while smaller European suppliers absorb certification cost burdens that compress margins on retrofit programs.
Pricing Analysis
Certification level — NSA Type 1 encryption versus NATO SECAN baseline — creates the primary spread between premium and standard terminal offerings. Three-tier pricing structure across mission-certified, interoperable-standard, and commercial-derivative levels dominates contract structures, with the US Air Force and Royal Air Force showing lowest price sensitivity for platform-integrated systems. Cost compression in aftermarket modular upgrades is intensifying because prime contractors are internalizing subsystem specifications on F-35 and E-7A production lines. Rotary-wing and unmanned platform operators exhibit highest price sensitivity, driving demand for compact VHF Data Link alternatives.
Supply Chain Analysis
Strategic stockpiling of specialized semiconductors prevails over just-in-time approaches given single-source vulnerabilities in radiation-hardened component foundries. Manufacturing concentrates in the United States, United Kingdom, and Germany, with German suppliers adapting to REACH and RoHS compliance requirements that reformulate printed circuit board solder compositions. The supply chain draws from concentrated gallium nitride substrate production and limited-auditor secure manufacturing facilities, exposing procurement timelines to cybersecurity certification queue risks. Distribution runs through prime defense contractor integration channels rather than independent aftermarket terminals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Secure manufacturing facility scarcity — only a handful of auditor-approved sites can produce NSA Type 1 encryption modules — concentrates competitive advantage with incumbents who have already cleared certification barriers. This capability gap shapes strategic positioning across all stakeholder archetypes.
For Market Incumbents: Shield installed base revenue by accelerating software-defined radio transition before open architecture mandates commoditize hardware terminals. Deepen upstream control over gallium nitride semiconductor sourcing to offset foundry concentration risks. Counter prime contractor integration threats by securing long-term service contracts for network management and spectrum coordination with British and Australian defense ministries. For New Entrants and Emerging Players: Anchor in Australian AIR 6500 modernization demand where interoperability requirements favor modular suppliers over platform-integrated incumbents. Target VHF Data Link segments for rotary-wing and unmanned platforms where size-weight-power constraints limit prime contractor dominance. Pursue STANAG 5602 certification early to unlock NATO procurement channel eligibility before European retrofit cycles peak. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors software-defined radio specialists with waveform-agnostic architectures over legacy JTIDS hardware manufacturers. Long-term viability rests on recurring service revenue streams rather than terminal replacement cycles. Acquisition targets should demonstrate established NSA Type 1 or NATO SECAN certification infrastructure. The signal to monitor is US DoD open systems architecture mandate enforcement speed — accelerated compliance timelines would compress hardware margins faster than modeled.| Strategic Initiative | Industry Significance |
|---|---|
| STANAG 5602 Certification Investment | Unlocks NATO procurement channel access for European air force modernization programs. |
| Software-Defined Radio Platform Development | Enables waveform adaptability on F-35 and E-7A platforms without hardware replacement cycles. |
| Network Management Services Outsourcing | Captures recurring revenue from US DoD and British Ministry of Defence spectrum coordination shifts. |
| Gallium Nitride Supply Agreement | Secures semiconductor substrate access against foundry concentration risks in defense electronics. |
| Australian Defense Market Expansion | Positions for AIR 6500 integrated air and missile defense terminal demand across RAAF platforms. |
Methodological Framework
A standing panel of platform integration engineers, defense procurement officers, secure manufacturing facility managers, and spectrum coordination specialists provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation from US DoD budget documentation, NATO standardization agreements, FAA spectrum allocation records, and national defense procurement databases. Bottom-up terminal shipment estimates and top-down defense electronics market sizing were triangulated to constrain forecast variance.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation by product architecture (Link 16, JTIDS, VHF Data Link), service delivery model (network management, communication services), end-user type (military operator, aerospace manufacturer), and deployment architecture (on-premises, hybrid, cloud-based). CAGRs were derived from fitted growth curves incorporating platform modernization cycle timing and unmanned system proliferation trajectories. Forecast inputs included STANAG 5602 certification timeline assumptions and open systems architecture mandate compliance schedules.
Material uncertainties — electromagnetic spectrum policy shifts, cybersecurity certification queue delays, gallium nitride foundry capacity constraints — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding NATO interoperability standard adoption rates and defense ministry outsourcing preferences. Revision becomes warranted when US DoD open architecture enforcement intensity or European green procurement criteria stringency crosses thresholds that would accelerate hardware margin compression or disqualify existing component formulations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Navigation and Communication
America Air Traffic Management Market
Aircraft Navigation and Communication
Aircraft Interface Device Market
Aircraft Navigation and Communication
5G in Aviation Market
Aircraft Navigation and Communication
Global Air Traffic Control Equipment Market
Aircraft Navigation and Communication
Aircraft Communication System Market
Aircraft Navigation and Communication
Connected Aircraft Market
Aircraft Navigation and Communication
Aircraft Navigation System Market
Aircraft Navigation and Communication
Military Navigation Systems Market
Aircraft Navigation and Communication
Asia-Pacific VHF Air-Ground Communication Stations Market
Aircraft Navigation and Communication
Middle-East and Africa Air Traffic Management Market
Aircraft Navigation and Communication
Aviation Weather Radar Market
Aircraft Navigation and Communication
Digital Radiosonde Market
Aircraft Navigation and Communication
Air Traffic Control Market
Aircraft Navigation and Communication
Defense Advanced GPS Receiver (DAGR) Market
Aircraft Navigation and Communication
Helicopter Meteorological Software Market
Aircraft Navigation and Communication
Airborne High Frequency Radio Market