
 America Air Traffic Management Market | 2026-2036
America Air Traffic Management Market Size, Share, and Industry Trends Forecast 2026-2036
America Air Traffic Management Market Outlook
Commercial aviation is expanding its share of ATM procurement as legacy ground-based infrastructure strains under post-pandemic traffic recovery. Raytheon Technologies Corporation leverages its integrated radar and communication portfolio to dominate NextGen upgrade contracts across major US hubs. L3Harris Technologies Inc. sustains competitive positioning through specialized surveillance and datalink solutions for both civilian and military airspace. Lockheed Martin Corporation anchors its presence via long-term FAA en-route automation and oceanic separation systems.
America Air Traffic Management encompasses the ground-based and satellite-linked hardware, software, and procedural systems that coordinate aircraft separation, routing, and sequencing across national and oceanic airspace, operating through VHF/UHF voice channels, Mode S transponder interrogation, GPS-augmented position reporting, and centralized flight data processing architectures with sub-minute update rates. Automation Systems capture the largest installed base as en-route centers and terminal radar approach control facilities modernize legacy host computer environments, while ADS-B technology leads growth trajectory given FAA mandates for universal equipage and the operational advantages of satellite-derived position broadcasts over traditional radar sweep cycles. Ground-Based systems retain substantial replacement demand across Alaska and remote continental corridors where satellite coverage remains intermittent.
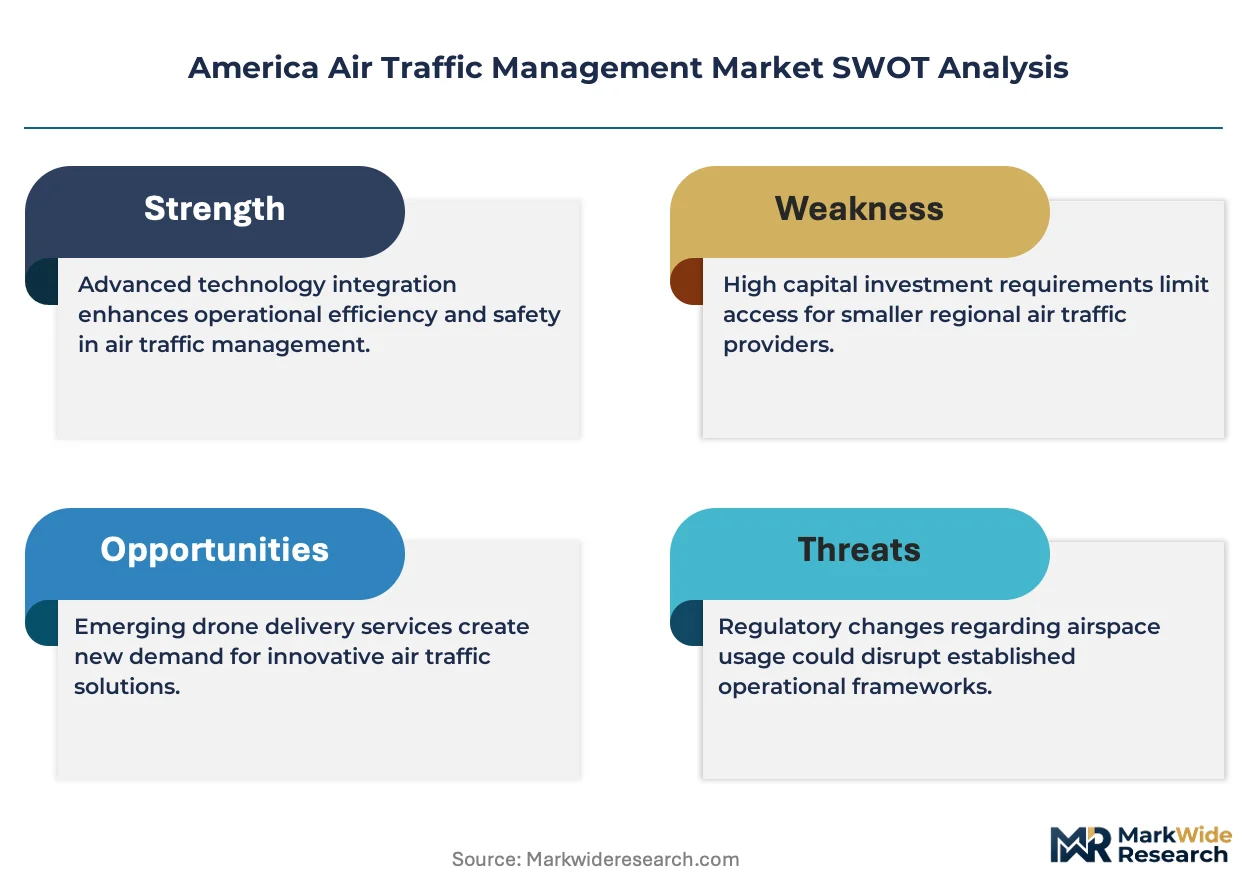
The Federal Aviation Administration (FAA) shapes procurement through NextGen implementation mandates and airworthiness directives, while the Department of Defense drives dual-use interoperability standards for national airspace integration of military platforms. FCC spectrum allocations for aeronautical mobile communications and FAA cybersecurity directives for critical infrastructure operators further constrain vendor design choices and certification pathways. Stakeholders must monitor how FAA funding cycles and congressional appropriations for air traffic modernization affect deployment timelines for next-generation surveillance and automation platforms.
Market Dynamics
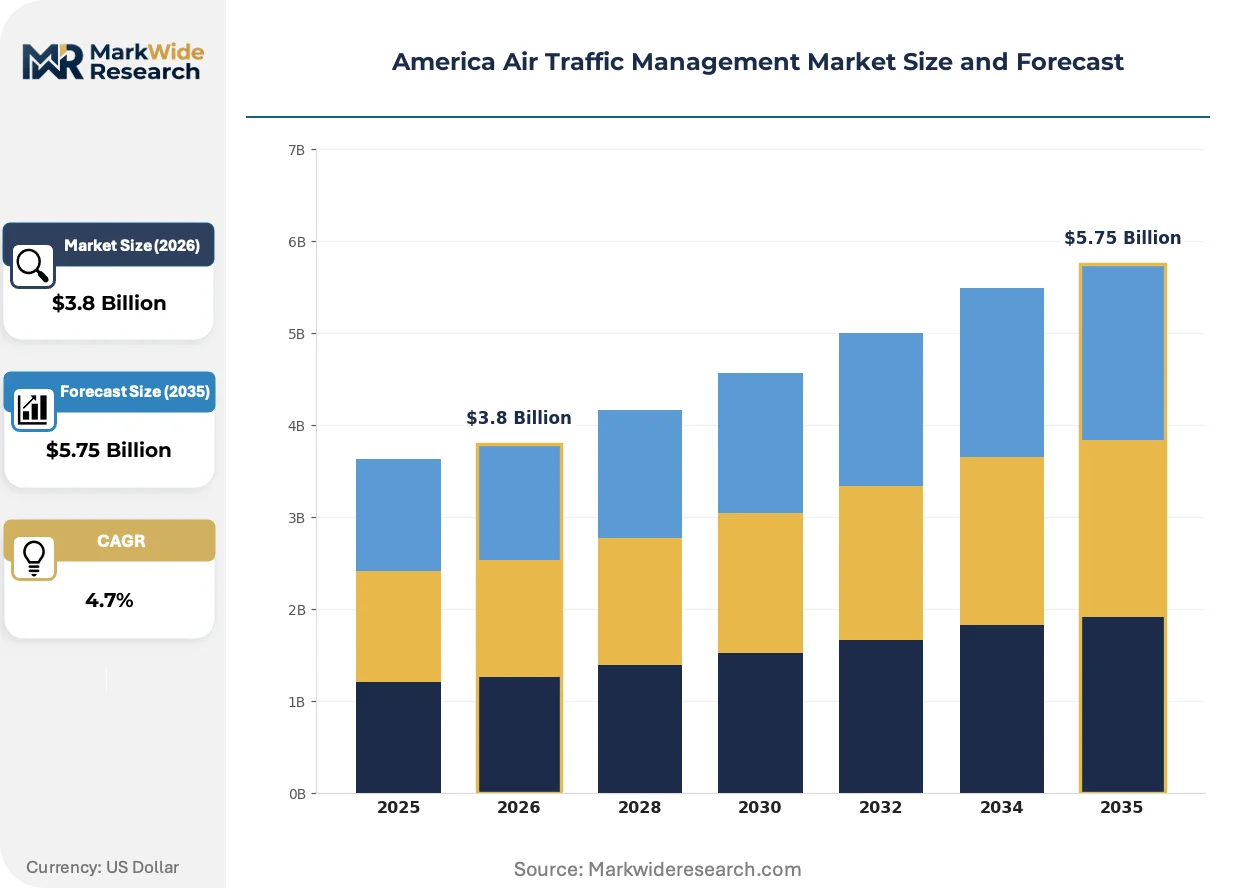
The FAA's NextGen modernization program is compressing procurement cycles as en-route centers and terminal facilities replace radar-based surveillance with satellite-linked position reporting infrastructure.
Growth Catalysts
- NextGen Mandates:FAA airworthiness directives requiring universal ADS-B Out equipage by 2020 have sustained retrofit demand across commercial fleets and general aviation operators.
- Denser Flight Corridors:Post-pandemic traffic recovery at Atlanta, Miami, and Dallas-Fort Worth hubs is forcing capacity expansion investments in automation and sequencing systems.
- Dual-Use Interoperability:Department of Defense requirements for national airspace integration of unmanned and manned military platforms are opening procurement channels for civilian-military compatible datalink architectures.
Market Restraints
- Spectrum Congestion:FCC allocations for aeronautical mobile communications face competing claims from 5G terrestrial networks, constraining VHF/UHF channel availability for voice and data transmission.
- Alaska Coverage Gaps:Remote continental corridors and Arctic routes lack reliable satellite augmentation, forcing continued reliance on ground-based radar with higher maintenance burdens.
- Cybersecurity Certification:FAA directives for critical infrastructure protection impose multi-year validation timelines on software updates, delaying feature deployment.
Strategic Opportunities
- Urban Air Mobility Corridors:Emerging electric vertical take-off and landing routes in Texas and Florida metropolitan areas require new low-altitude traffic management architectures absent legacy system constraints.
- Remote Tower Technology:Camera-based surveillance and centralized air traffic services enable consolidation of underutilized rural facilities in the Mountain West and Great Plains.
- Performance-Based Navigation:FAA procedures enabling curved approach paths and reduced separation minima are driving demand for flight management system upgrades and crew training ecosystems.
Industry Challenges
- Controller Workforce Pipeline:FAA training academy capacity and certification backlogs limit the rate at which new air traffic controllers can staff modernized facilities.
- Legacy Host Integration:En-route automation replacement requires maintaining operational continuity with 1980s-era computer architectures during phased cutover periods.
- Multi-Stakeholder Coordination:Harmonization between FAA, Department of Defense, and international ICAO standards creates procedural friction for cross-border route optimization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | America Air Traffic Management Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automation Systems, Communication Systems, Navigation Systems, Surveillance Systems Technology: ADS-B, Radar, Satellite-Based, Ground-Based End User: Commercial Aviation, Military Aviation, General Aviation, Air Traffic Control Service Type: Consulting, Maintenance, Installation, Support |
| Companies Covered | Raytheon Technologies Corporation, Thales Group, L3Harris Technologies Inc., Lockheed Martin Corporation, Indra Sistemas S.A., Honeywell International Inc., Northrop Grumman Corporation, SITA, Saab AB, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
America Air Traffic Management Market Strategic Shifts
Digital communication protocols are supplanting analog voice channels across US airspace, while automation architectures migrate toward distributed processing models that reduce single-point failure risks.
Space-based ADS-B receivers are absorbing oceanic surveillance functions previously requiring ground-based infrastructure or procedural separation. Airlines operating North Atlantic tracks are equipping for 15-minute position reporting intervals rather than 30-minute procedural gaps. This compression is absorbing demand for traditional HF voice relay stations and reducing separation minima that constrained route efficiency.
FAA cybersecurity directives for critical infrastructure operators now mandate continuous monitoring and incident reporting for flight data processing systems. Vendors must demonstrate supply chain integrity and software bill of materials compliance before certification. Terminal radar approach control facilities in the southeastern United States are prioritizing zero-trust network architectures in modernization contracts.
Airlines are consolidating vendor relationships for integrated flight operations center suites that unify dispatch, crew scheduling, and air traffic management coordination. Legacy point-solution procurement for standalone surveillance or communication modules is giving way to platform contracts with multi-system vendors. Network carriers based in Atlanta and Dallas-Fort Worth are driving this consolidation through fleet-wide standardization mandates.
America Air Traffic Management Market Segmentation
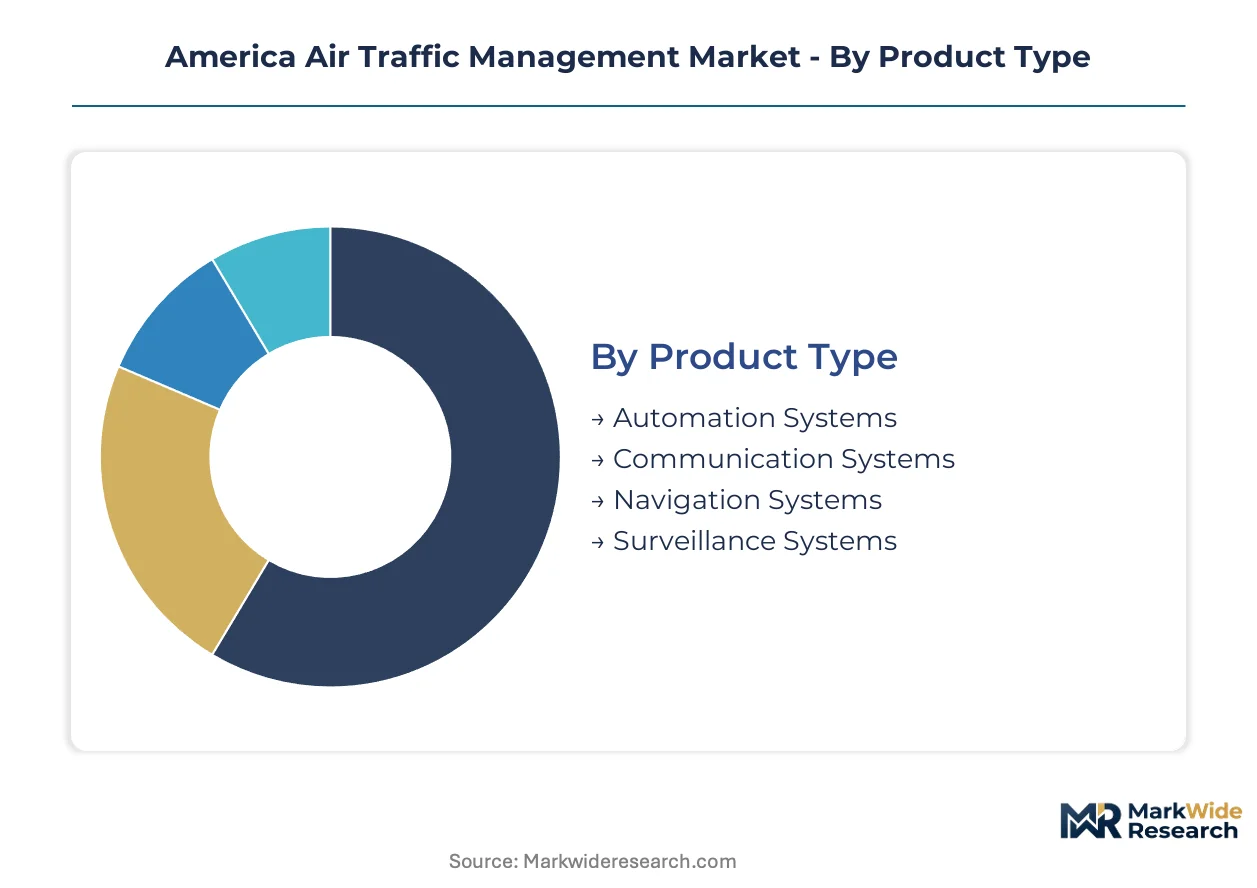
ATM procurement divides across hardware platforms, enabling technologies, operator categories, and lifecycle services. Each dimension shapes vendor positioning and contract structures differently across FAA modernization programs and military interoperability mandates.
Product Type:
Supply concentrates in automation and surveillance platforms where Raytheon, L3Harris, and Lockheed Martin hold entrenched positions through multi-decade FAA relationships.
- Automation Systems:En-route center and TRACON host computer replacements coordinate flight data processing, trajectory modeling, and controller decision support. FAA's NextGen en-route automation modernization (ERAM) sustains demand across 20 continental centers and oceanic facilities.
- Surveillance Systems:Primary and secondary radar installations, multilateration networks, and ADS-B ground stations provide aircraft position verification. Alaska and remote Mountain West corridors depend on these installations where satellite augmentation remains unreliable.
- Communication Systems:VHF/UHF ground-to-air voice switches and datalink ground stations enable controller-pilot exchanges. Spectrum constraints from FCC 5G allocations are compressing available channels in dense southeastern hubs.
- Navigation Systems:Instrument landing systems, VOR/DME ground stations, and GPS augmentation infrastructure support approach and en-route guidance. Performance-based navigation procedures are shifting investment toward satellite-based augmentation.
Automation Systems absorb the bulk of installed capacity; Surveillance Systems is expanding most quickly through ADS-B mandate compliance and radar replacement cycles.
Technology:
Cost tiers separate satellite-dependent architectures from ground-based alternatives, with hybrid deployments dominating where coverage redundancy matters.
- ADS-B:Automatic Dependent Surveillance-Broadcast transmits GPS-derived position, velocity, and intent via 1090 MHz or 978 MHz datalinks. FAA mandates require universal equipage across controlled airspace, sustaining retrofit demand for transponder and display upgrades.
- Ground-Based:Primary surveillance radar and Mode S secondary radar maintain operational continuity where terrain or satellite gaps prevent ADS-B coverage. Alaska's Arctic routes and Rocky Mountain corridors require continued radar maintenance despite higher lifecycle costs.
- Satellite-Based:Space-based ADS-B receivers and Iridium datalink services extend surveillance to oceanic and polar regions. North Atlantic track operators are adopting 15-minute position reporting intervals, displacing traditional HF voice relay infrastructure.
- Radar:Legacy pulse and phased-array installations provide independent surveillance verification for separation assurance. Terminal facilities at Atlanta, Miami, and Dallas-Fort Worth balance radar redundancy against ADS-B primary surveillance migration.
Ground-Based technology retains the largest installed base; ADS-B is climbing the fastest through regulatory mandate and operational efficiency gains.
End User:
Customer type determines procurement channel and certification rigor, with commercial airlines facing equipage mandates that general aviation operators resist.
- Commercial Aviation:Network carriers operating from Atlanta, Miami, and Dallas-Fort Worth drive fleet-wide avionics standardization. Integrated flight operations center suites are consolidating vendor relationships across dispatch, crew scheduling, and ATM coordination functions.
- Air Traffic Control:FAA terminal and en-route facilities procure ground infrastructure through multi-year indefinite delivery contracts. Cybersecurity directives for critical infrastructure protection now mandate continuous monitoring and software bill of materials compliance.
- Military Aviation:Department of Defense platforms require civilian-military datalink interoperability for national airspace integration. Dual-use procurement channels favor vendors with existing FAA and DoD certification pathways.
- General Aviation:Part 91 and Part 135 operators face ADS-B Out equipage costs without equivalent operational benefits. Cost-sensitive segments delay compliance or seek portable solutions rather than panel-mount installations.
Commercial Aviation commands the largest procurement volume; Military Aviation is gaining share fastest through unmanned platform integration requirements.
Service Type:
Margin structures vary sharply across installation intensity versus recurring maintenance streams, with consulting services capturing value during modernization planning phases.
- Installation:Greenfield radar and ADS-B ground station deployments, plus brownfield legacy system replacements. FAA NextGen deployment schedules concentrate installation demand in southeastern hub corridors.
- Maintenance:Preventive and corrective services for radar, communication, and automation hardware across FAA's operational inventory. Alaska's remote sites impose higher logistics costs and longer response times.
- Consulting:Procedure design, airspace modeling, and modernization roadmap development for FAA and airport sponsors. Performance-based navigation implementation drives demand for approach design and crew training ecosystem planning.
- Support:Help desk, software updates, and spare parts logistics for operational systems. Cybersecurity incident response and supply chain integrity verification are expanding support scope under FAA directives.
Maintenance represents the largest revenue stream; Consulting is expanding most quickly through NextGen procedure design and urban air mobility corridor planning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foreign-trade zones surrounding major aviation hubs concentrate procurement activity, with southeastern US facilities leveraging tariff exemptions on imported avionics components. The FAA's NextGen deployment schedule directs infrastructure investment toward high-traffic corridors.
Southeast United States
Atlanta Hartsfield-Jackson, Miami International, and Dallas-Fort Worth anchor the densest flight corridors in the national airspace system. FAA NextGen mandates for ADS-B equipage and ERAM automation upgrades concentrate installation contracts across Georgia, Florida, and Texas. The Dallas-Fort Worth metroplex hosts multiple system integration facilities supporting terminal radar approach control modernization.
Western United States
Los Angeles International and San Francisco International drive demand for oceanic separation systems and Pacific route optimization. The FAA's Oakland and Anchorage oceanic centers manage high-density North Pacific tracks requiring satellite-based ADS-B surveillance. Seattle-Tacoma corridor facilities support Alaska coverage gap mitigation through ground-based radar redundancy.
Northeast Corridor
New York Metro airspace complexity generates specialized demand for trajectory-based operations and metroplex redesign. The FAA's New York and Boston en-route centers handle the highest controller workload density in the continental system. Philadelphia and Washington-National hubs sustain procurement for legacy host system replacement alongside NextGen automation.
Alaska
Arctic route expansion and remote site logistics create distinctive procurement patterns for ruggedized ground-based surveillance. The FAA maintains extensive primary radar networks across the Aleutian chain and North Slope where satellite augmentation remains intermittent. Anchorage International serves as the critical logistics node for spare parts distribution to isolated facilities.
Mountain West
Denver International and Salt Lake City International anchor en-route center procurement for high-altitude corridor management. Remote tower technology trials in Montana and Wyoming rural facilities demonstrate camera-based surveillance consolidation. The FAA's Albuquerque center manages military-civilian airspace integration across extensive defense training ranges.
America Air Traffic Management Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated system vendors capturing multi-year FAA indefinite delivery contracts while component suppliers serve retrofit and maintenance channels. The vendor base concentrates around defense-aerospace conglomerates with established certification pathways. Three archetypes dominate: full-spectrum platform providers, surveillance and datalink specialists, and communication infrastructure vendors. Competitive positioning hinges on backward integration into software development and strategic partnerships for urban air mobility corridor planning.
Among US-based defense-aerospace conglomerates, Raytheon Technologies Corporation, L3Harris Technologies Inc., and Lockheed Martin Corporation exemplify the full-spectrum platform archetype. Raytheon Technologies Corporation occupies a position anchored in integrated radar and communication portfolios. L3Harris Technologies Inc. sits within the surveillance specialization tier. Lockheed Martin Corporation represents the long-term automation systems anchor through sustained FAA en-route relationships.
| Leading Market Players |
|---|
| Raytheon Technologies Corporation |
| Thales Group |
| L3Harris Technologies Inc. |
| Lockheed Martin Corporation |
| Indra Sistemas S.A. |
| Honeywell International Inc. |
| Northrop Grumman Corporation |
| SITA |
| Saab AB |
| Others |
Value Chain & Pricing Dynamics
Satellite-based ADS-B infrastructure migration is compressing cost economics for ground-based radar maintenance while concentrating procurement power among multi-decade FAA contractors. This technology shift simultaneously elevates lifecycle pricing for hybrid surveillance deployments and rewards vendors with backward integration into software-defined automation architectures.
Pricing Analysis
Short lead-time premiums of 15-25% apply to ADS-B ground station components and ERAM automation modules where FAA deployment schedules compress delivery windows. Contract-based long-term offtake agreements dominate, with price differentiation resting on FAA certification tier and cybersecurity compliance level rather than hardware specifications alone. Cost compression in general aviation ADS-B equipage is intensifying because portable solutions compete against panel-mount installations. Commercial airlines exhibit lowest price sensitivity given fleet-wide standardization mandates, while Part 135 operators resist compliance costs most acutely.
Supply Chain Analysis
Freight costs to Alaska and remote Mountain West facilities add 30-40% logistics premiums compared to southeastern hub corridors. Supply concentrates in the United States for automation software and integration services, with radar component fabrication drawing from the United Kingdom and Germany. Raw material dependencies include gallium nitride semiconductors, precision aluminum castings, and specialized coaxial cable assemblies. Single-source vulnerability persists for space-qualified ADS-B receiver payloads. Distribution runs through FAA indefinite delivery contracts with direct vendor-to-facility logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around full-spectrum platform providers as cybersecurity certification timelines and multi-decade FAA relationships marginalize point-solution vendors.
For Market Incumbents: Hedge against emerging urban air mobility entrants by acquiring camera-based remote tower specialists before low-altitude corridor mandates crystallize. Deepen backward integration into flight data processing software to capture recurring maintenance streams beyond hardware installation cycles. FAA cybersecurity directives for continuous monitoring represent the critical lever for locking out unqualified competitors. For New Entrants and Emerging Players: FAA NextGen urban air mobility corridor planning in Texas and Florida opens a window for specialized low-altitude traffic management architectures unconstrained by legacy system integration. Target performance-based navigation procedure design services where consulting margins exceed hardware procurement. The most penetrable segment is rural remote tower consolidation in Montana and Wyoming. A direct go-to-market angle pairs with airport sponsors seeking operational cost reduction rather than FAA prime contractors. For Investors and Strategic Acquirers: Exit pathways concentrate in defense-aerospace conglomerate acquisition of specialized surveillance vendors lacking civilian certification pathways. Long-term viability favors platforms with simultaneous FAA and Department of Defense approval trajectories. The acquisition target archetype is mid-cap surveillance specialists with ADS-B ground station deployment experience but incomplete automation portfolios. Watch FAA funding cycle appropriations as the inflection signal for deployment acceleration or delay.| Strategic Initiative | Industry Significance |
|---|---|
| NextGen Automation Platform Integration | ERAM modernization at 20 continental centers sustains multi-year revenue visibility for certified vendors. |
| Urban Air Mobility Corridor Development | Texas and Florida metropolitan electric vertical take-off routes require new low-altitude traffic architectures. |
| Cybersecurity Certification Investment | FAA software bill of materials mandates create compliance barriers protecting incumbent market positions. |
| Remote Tower Technology Deployment | Camera-based surveillance consolidation in Mountain West rural facilities reduces FAA operating cost burdens. |
| Dual-Use Civilian-Military Datalink Partnership | Department of Defense interoperability requirements open procurement channels beyond FAA civilian budgets. |
Study Parameters
Document review covered FAA NextGen implementation schedules, congressional appropriations records, and FCC spectrum allocation proceedings, complemented by interviews with en-route center automation directors, terminal radar approach control facility managers, airline flight operations executives, and defense aerospace procurement officers. Secondary validation drew from Department of Transportation budget justifications, GAO audit reports on FAA modernization, and ICAO technical standards documentation. Bottom-up procurement tracking across individual facility upgrade contracts was triangulated against top-down market sizing from vendor revenue disclosures.
Cross-referencing historical FAA deployment timelines against expert panel input on funding cycle variability shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, technology architecture, end-user category, and service lifecycle stage, with additional granularity for geographic hub corridor density. CAGRs were derived from facility-level procurement pipeline analysis weighted by traffic volume growth assumptions. Forecast inputs incorporated ADS-B equipage mandate compliance curves and ERAM replacement scheduling priorities.
The model assumes a particular technology adoption path; alternative pathways for space-based ADS-B surveillance displacement of oceanic radar would alter the outlook for ground station investment. Forecasts reflect assumptions about FAA funding continuity and post-pandemic traffic recovery trajectories. Stakeholders should weight assumptions against their own operating context and congressional appropriation risk exposure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Navigation and Communication
Air Traffic Management Software Market
Aircraft Navigation and Communication
Air-Based Tactical Data Link Market
Aircraft Navigation and Communication
Global Aircraft Antenna Market
Aircraft Navigation and Communication
Asia-Pacific Air Traffic Management Market
Aircraft Navigation and Communication
Air Traffic Control Market
Aircraft Navigation and Communication
Defense Advanced GPS Receiver (DAGR) Market
Aircraft Navigation and Communication
5G in Aviation Market
Aircraft Navigation and Communication
Global Drone Navigation System Market
Aircraft Navigation and Communication
Electronic Navigational Charts (ENC) Market
Aircraft Navigation and Communication
Military Navigation Systems Market
Aircraft Navigation and Communication
Airborne High Frequency Radio Market
Aircraft Navigation and Communication
Automatic Dependent Surveillance-Broadcast (ADS-B) Market
Aircraft Navigation and Communication
Aircraft Turn Coordinator Market
Aircraft Navigation and Communication
Airspace and Procedure Design Market
Aircraft Navigation and Communication
Global Flight Navigation System Market
Aircraft Navigation and Communication
Middle-East and Africa Air Traffic Management Market