
 Low-Cost Satellite Market | 2026-2036
Low-Cost Satellite Market Size, Share, and Industry Trends Forecast 2026-2036
Low-Cost Satellite Market Intelligence
Project finance through milestone-based launch contracts is reconfiguring capital requirements for new entrants. Rocket Lab leverages vertical integration across launch and satellite manufacturing to sustain margin control. Planet Labs dominates optical Earth observation constellations through rapid revisit capabilities. Thales Alenia Space anchors European institutional demand through dual-use telecommunications platforms.
Low-cost satellites are compact spacecraft with standardized form factors, typically under 50 kg, utilizing commercial off-the-shelf electronics and modular bus architectures for rapid assembly. These platforms deliver remote sensing, communications relay, and scientific data collection at unit costs one to two orders of magnitude below traditional geostationary spacecraft. NanoSatellite and MicroSatellite segments lead current production volume, with CubeSat architectures maturing into predictable margin pools for university and technology demonstration missions. Earth Observation and Telecommunications applications capture the deepest demand, while Agricultural Monitoring represents the fastest-expanding use case as precision farming platforms integrate satellite-derived analytics.
FCC streamlined small satellite licensing in the United States, compressing authorization timelines and lowering barriers for commercial constellation operators. ESA and national regulators across France, Germany, and Italy coordinate spectrum allocation and debris mitigation standards under EU Space Surveillance and Tracking frameworks. Stakeholders must monitor evolving orbital congestion rules and spectrum auction designs that will determine which constellation architectures achieve sustained operational scale.
Market Dynamics
Constellation operators now compress satellite replacement cycles from decade-long geostationary timelines to 3-5 year refresh rates, forcing component suppliers to abandon radiation-hardened heritage parts for commercial automotive-grade electronics.
Growth Catalysts
- India's PLI scheme for space manufacturing:ISRO's commercial arm offers subsidized launch slots and ground infrastructure to foreign payload operators, drawing European and Asian constellation developers to Indian facilities.
- Agricultural Monitoring demand surge:Smallholder cooperatives in Vietnam and Indonesia deploy satellite-derived analytics for irrigation scheduling and pest prediction, creating recurring data subscription revenue pools.
- FCC streamlined licensing:The Commission's small satellite authorization framework compresses approval timelines from 18 months to 6 months, enabling rapid constellation deployment for US-based operators.
Market Restraints
- Launch capacity concentration:Three providers control 70% of dedicated small satellite launch slots, creating queue bottlenecks and price volatility for operators without multi-year block bookings.
- Solar cell supply fragility:German and Japanese suppliers dominate triple-junction photovoltaic substrates, exposing constellation builders to 14-month lead times and currency fluctuation risk.
- Orbital debris liability frameworks:ESA's Space Surveillance and Tracking coordination lacks binding enforcement mechanisms, leaving operators exposed to collision risk and insurance premium spikes.
Strategic Opportunities
- Brazil's underpenetrated agribusiness sector:Soybean and cattle operators in Mato Grosso lack precision farming infrastructure, creating first-mover advantage for satellite analytics providers with Portuguese-language platforms.
- Synthetic aperture radar convergence:Integration of SAR payloads with optical sensors enables all-weather imaging, opening maritime surveillance contracts with Southeast Asian coast guards.
- Japan's METI space data subsidies:The ministry funds disaster response and maritime domain awareness pilots, creating procurement channels for foreign constellation operators meeting JIS reliability standards.
Industry Challenges
- Radiation effects engineering talent scarcity:Universities produce insufficient specialists in single-event upset mitigation, forcing operators to poach from legacy aerospace primes at 40% salary premiums.
- ITAR compliance timeline compression:US State Department classification reviews for camera payloads now exceed satellite fabrication cycles, forcing non-US operators to source European imaging components.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low-Cost Satellite Market |
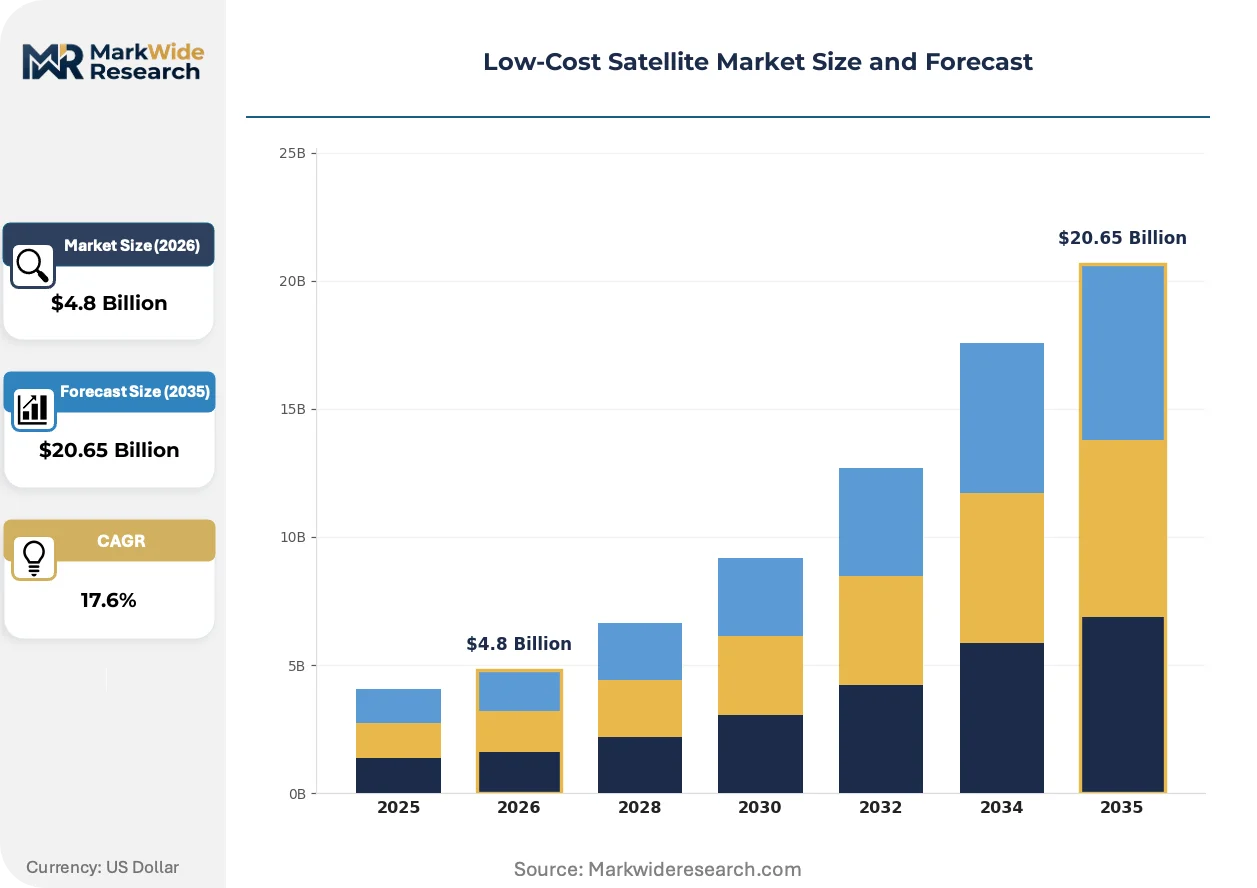
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $20.65 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CubeSat, NanoSatellite, MicroSatellite, PicoSatellite Application: Agricultural Monitoring, Earth Observation, Telecommunications, Disaster Management Deployment: Launch Vehicle, Rideshare, Dedicated Launcher, Secondary Payload End User: Government Agencies, Private Companies, Research Institutions, NGOs |
| Companies Covered | Rocket Lab, OneWeb, SpaceX, Axelspace Corporation, L3Harris Technologies Inc., Planet Labs Inc., Blue Origin, Thales Alenia Space, Spire Global Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low-Cost Satellite Market Strategic Shifts & Innovations
Software-defined payload architectures now dominate new satellite designs, replacing fixed-function hardware with reprogrammable processors that adapt to shifting customer requirements mid-mission.
Electric propulsion systems utilizing iodine-based thrusters are rendering obsolete hydrazine-fueled attitude control units. University technology demonstration missions and early-stage constellation operators adopt these systems for orbit-raising and deorbit compliance. The shift eliminates ground handling hazards and reduces launch mass margins by 15-20%.
REACH chemical restrictions in Europe now classify traditional satellite coatings and propellants as substances of very high concern. Manufacturers reformulate thermal control surfaces and pursue ECSS qualification for alternative materials. Small satellite builders in France and Germany face 8-12 month recertification cycles for revised material sets.
Consolidated procurement through launch brokerage platforms now displaces direct operator-to-manufacturer contracting. Aggregators like Spaceflight and ISILaunch bundle payloads across multiple customers, standardizing interface requirements and compressing integration timelines. This channel shift concentrates pricing power with brokers and reduces visibility for component suppliers into end-use applications.
Low-Cost Satellite Market Segmentation
Low-cost satellite architectures fragment across mass classes, orbital insertion methods, and customer procurement patterns. Each segmentation axis carries distinct margin profiles and regulatory exposure, requiring constellation operators to optimize across multiple dimensions simultaneously.
Product Type:
Mature standardized platforms now dominate production volume, while emerging form factors capture technology demonstration missions and specialized payloads.
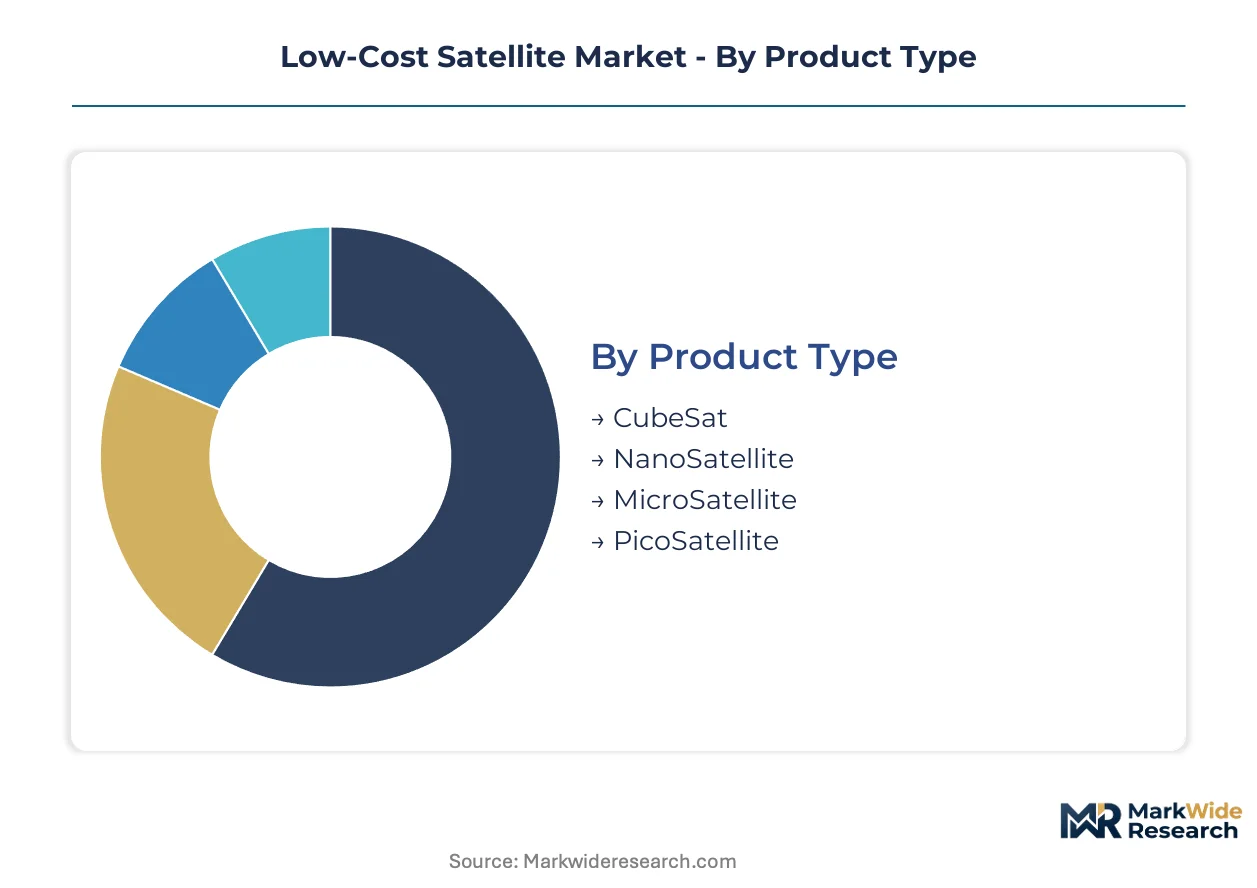
- CubeSat:Modular 10x10x10 cm units leverage commercial off-the-shelf electronics for rapid assembly. University programs in Germany and Japan drive procurement, constrained by limited payload capacity and radiation tolerance.
- NanoSatellite:1-10 kg spacecraft balance mission capability with launch economics. Earth observation startups in India and the United States concentrate demand here, drawn by rideshare affordability and standardized dispenser interfaces.
- MicroSatellite:10-100 kg platforms accommodate multi-sensor payloads and electric propulsion. ISRO's commercial arm actively courts foreign operators in this mass class through subsidized launch slots.
- PicoSatellite:Sub-1 kg units serve brief technology validation missions. Academic consortia and amateur radio groups constitute the primary demand pool.
CubeSat retains volume leadership; Agricultural Monitoring applications are driving NanoSatellite's steepest expansion curve.
Application:
Cost tier differentiation separates subscription-based data services from capital-intensive infrastructure deployments.
- Agricultural Monitoring:Multispectral and hyperspectral imaging enables precision farming analytics. Smallholder cooperatives in Vietnam and Indonesia generate recurring subscription revenue, though cloud cover limits optical sensor reliability during monsoon seasons.
- Earth Observation:Rapid revisit optical constellations deliver geospatial intelligence. Defense and intelligence agencies in France, Germany, and the United States anchor procurement through multi-year service contracts.
- Telecommunications:Narrowband IoT relay and store-forward messaging serve remote asset tracking. Maritime and aviation sectors drive uptake, constrained by spectrum coordination complexity under ITU frameworks.
- Disaster Management:On-demand imaging and communications restoration supports emergency response. Japan's METI funds pilot programs for foreign operators meeting JIS reliability standards.
Earth Observation commands premium pricing; Agricultural Monitoring is expanding most quickly across Southeast Asian markets.
Deployment:
Supply concentration among launch providers creates divergent queue access and price volatility across insertion methods.
- Launch Vehicle:Primary payload status offers schedule certainty and orbital precision. Government and defense missions dominate this channel, absorbing higher per-kilogram costs for dedicated access.
- Rideshare:Aggregated small satellite launches through brokers like Spaceflight standardize integration timelines. Commercial constellation operators without block bookings face 12-18 month queue uncertainty.
- Dedicated Launcher:Small-lift vehicles from Rocket Lab and emerging Indian providers serve time-sensitive deployments. Premium pricing applies for rapid-response replenishment missions.
- Secondary Payload:Opportunistic rides on large geostationary launches minimize cost but constrain orbital parameters. University and demonstration missions tolerate destination uncertainty.
Rideshare captures plurality volume; Dedicated Launcher services are climbing the fastest as constellation refresh cycles compress.
End User:
Customer type determines procurement rigor, contract duration, and technical specification tolerance.
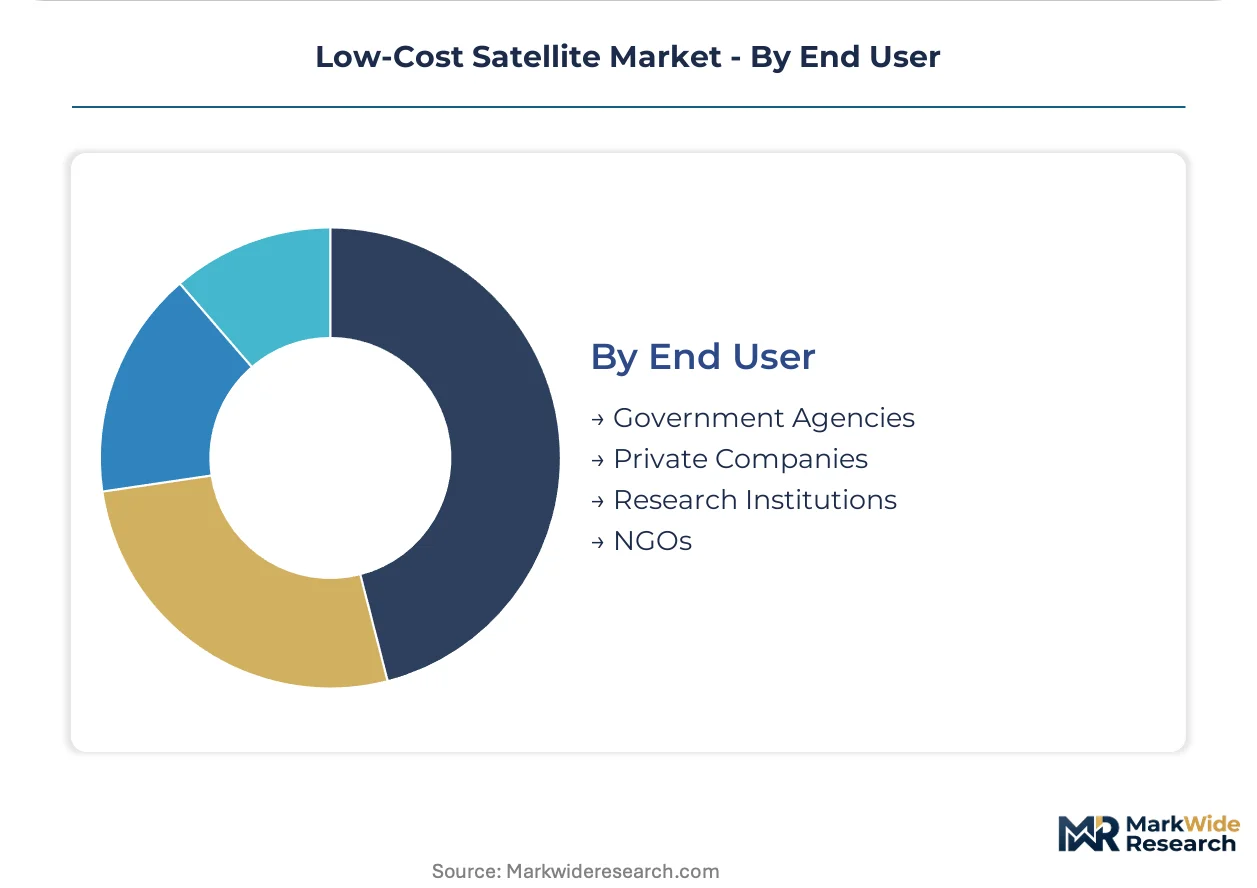
- Government Agencies:National space programs and defense departments require ECSS or MIL-STD qualification. ESA member states and the United States anchor institutional demand through multi-satellite framework agreements.
- Private Companies:Venture-backed constellation operators prioritize speed-to-orbit over heritage qualification. Vertical integration across manufacturing and data analytics distinguishes surviving operators from capital-constrained competitors.
- Research Institutions:Universities and national laboratories pursue technology demonstration and training missions. European and Japanese academic programs drive CubeSat and PicoSatellite procurement.
- NGOs:Environmental monitoring and connectivity initiatives access philanthropic and development finance. Maritime domain awareness projects in Southeast Asian waters attract blended funding structures.
Government Agencies sustain contract value leadership; Private Companies are gaining share fastest through venture-scale constellation deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ISRO's commercial arm subsidizes launch slots and ground infrastructure for foreign payload operators, drawing constellation developers toward Indian facilities. The FCC compressed small satellite licensing timelines from 18 months to 6 months, accelerating US-based operator deployments. ESA member states coordinate spectrum allocation under EU Space Surveillance and Tracking frameworks.
United States
Defense and intelligence agencies anchor demand through multi-year Earth observation service contracts. The FCC streamlined small satellite authorization frameworks, compressing approval timelines for commercial constellation operators. California hosts the densest cluster of venture-backed satellite manufacturers and launch providers.
India
ISRO's commercial arm courts foreign payload operators with subsidized launch slots and ground infrastructure access. The country's PLI scheme for space manufacturing draws European and Asian constellation developers to Indian facilities. Bengaluru concentrates satellite bus assembly operations serving domestic and export markets.
Japan
METI funds disaster response and maritime domain awareness pilots, creating procurement channels for foreign operators meeting JIS reliability standards. The ministry's space data subsidies target emergency response applications. Tokyo-Yokohama hosts precision component suppliers serving regional constellation builders.
Germany
REACH chemical restrictions now classify traditional satellite coatings as substances of very high concern, forcing 8-12 month recertification cycles. ESA coordinates spectrum allocation and debris mitigation standards across member states. Munich-Stuttgart anchors European institutional demand through dual-use telecommunications platforms.
Brazil
Soybean and cattle operators in Mato Grosso lack precision farming infrastructure, creating first-mover opportunity for satellite analytics providers. The country's national space regulator oversees orbital licensing for commercial constellation deployments. São Paulo concentrates emerging agribusiness technology adoption among large-scale agricultural operators.
Low-Cost Satellite Market Key Industry Players
Channel-controlling players compete with product-specialist players across launch services, satellite manufacturing, and data analytics. Three providers control 70% of dedicated small satellite launch slots, creating queue bottlenecks for operators without multi-year block bookings. The vendor base separates into launch-integrated operators, pure-play satellite manufacturers, and constellation data service providers. Consolidated procurement through launch brokerage platforms displaces direct operator-to-manufacturer contracting, concentrating pricing power with aggregators.
Among vertically integrated operators, Rocket Lab exemplifies the launch-plus-satellite manufacturing archetype. Planet Labs occupies a position within rapid-revisit optical Earth observation constellations. Thales Alenia Space anchors European institutional demand through dual-use telecommunications platforms, representing the heritage aerospace prime adaptation to low-cost satellite architectures.
| Leading Market Players |
|---|
| Rocket Lab |
| OneWeb |
| SpaceX |
| Axelspace Corporation |
| L3Harris Technologies Inc. |
| Planet Labs Inc. |
| Blue Origin |
| Thales Alenia Space |
| Spire Global Inc. |
| Others |
Cost & Logistics Intelligence
Launch vehicle undercapacity in the United States is compressing rideshare slot availability and forcing constellation operators toward premium dedicated services or extended queue positions. This utilization squeeze simultaneously elevates broker pricing power and accelerates supplier migration toward Indian and Japanese launch alternatives.
Pricing Analysis
Certification level (ECSS/MIL-STD heritage versus COTS automotive-grade) creates the primary spread between government agency contracts and venture-backed constellation deployments. Three-tier pricing structure across premium, standard, and economy levels reflects payload qualification rigor, launch schedule certainty, and ground segment bundling. Cost compression in the standard tier is intensifying because rideshare aggregators are consolidating procurement volume and extracting supplier rebates. Research institutions and university programs exhibit highest price sensitivity, while defense and intelligence agencies absorb premium positioning for schedule priority.
Supply Chain Analysis
Contract manufacturing for satellite bus assembly concentrates in Bengaluru, Toulouse, and Tokyo-Yokohama clusters where ISRO-aligned facilities and ESA heritage suppliers anchor regional capacity. Triple-junction photovoltaic substrates draw from German and Japanese suppliers, while commercial automotive-grade processors feed from Taiwanese foundries and South Korean memory fabricators. Single-source vulnerability in solar cell supply exposes constellation builders to currency fluctuation and export control disruption. Distribution runs through launch brokerage platforms that standardize interface requirements and compress integration timelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Constellation data marketplaces are crystallizing as platform-economics inflection points, with interoperability standards enabling multi-operator analytics fusion and subscription bundling across previously siloed Earth observation providers.
For Market Incumbents: Harden orbital slot registration strategies through accelerated replenishment cycles and deorbit compliance bonds that preempt regulatory congestion penalties. ISRO's subsidized launch infrastructure and FCC's compressed licensing timelines represent dual threats to heritage pricing power; backward integration into iodine-based propulsion and software-defined payload architectures preserves margin control against commercial automotive-grade component commoditization.
For New Entrants and Emerging Players: Mid-market agricultural cooperatives in Mato Grosso and precision farming operators across Vietnam's Mekong Delta represent the most penetrable entry points for satellite analytics providers with localized language interfaces and cloud-based subscription models. Synthetic aperture radar convergence with optical sensors opens maritime surveillance contracts with Southeast Asian coast guards lacking all-weather independent monitoring capacity. Direct-to-cooperative sales bypassing legacy distribution channels accelerates customer acquisition.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across rideshare-dependent NanoSatellite deployments as reusable launch economics and standardized dispenser interfaces reduce per-unit insertion costs. Acquisition targets should demonstrate software-defined payload adaptability and JIS or ECSS qualification pathways for Japanese and European institutional procurement channels. The signal to watch is consolidation velocity among launch brokerage platforms as pricing power concentration determines downstream constellation operator viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Payload Migration | Reprogrammable processors enable mid-mission capability reconfiguration for shifting customer requirements. |
| Iodine Propulsion Adoption | Electric thrusters eliminate hydrazine ground handling hazards and reduce launch mass margins. |
| Launch Brokerage Platform Consolidation | Aggregators like Spaceflight and ISILaunch standardize interfaces and concentrate pricing power. |
| REACH Compliance Reformulation | European manufacturers face recertification cycles for thermal control surfaces and alternative coatings. |
| PLI Scheme Manufacturing Migration | ISRO's subsidized infrastructure draws foreign constellation developers to Indian assembly facilities. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with constellation program managers, launch procurement leads, satellite bus engineers, ground segment operators, and agricultural analytics subscription sales executives. Secondary validation drew from FCC licensing databases, ESA Space Surveillance and Tracking coordination filings, ISRO commercial launch manifests, and ITU spectrum registration records. Bottom-up unit economics modeling triangulated against top-down addressable market sizing across the projection horizon.
Calibration against disclosed launch manifests and constellation deployment announcements anchored volume assumptions throughout the forecast period. Segmentation dimensions modeled include mass class architecture, application vertical, deployment channel, and end-user procurement rigor. CAGRs were derived from fitted growth curves adjusted for regulatory licensing velocity and launch capacity expansion schedules. Iodine propulsion adoption curves and software-defined payload penetration rates served as technology-specific forecast inputs.
Practitioners should monitor FCC orbital debris rulemaking, ESA binding enforcement mechanism development, and ISRO foreign payload queue allocation for early signals of competitive positioning shifts. Quarterly review of launch broker pricing transparency, solar cell supplier export control notifications, and agricultural cooperative subscription renewal rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Small Satellite Launch Market
Satellite
Europe Satellite Manufacturing and Launch Systems Market
Satellite
North America Mobile Satellite Services Market
Satellite
China Satellite Communication Market
Satellite
India Satellite-Based Earth Observation Market
Satellite
Russia Satellite Communications Market
Satellite
Remote Sensing Satellite Market
Satellite
US Satellite Connectivity Market
Satellite
Asia-Pacific Satellite Bus Market
Satellite
Aviation Satellite Antenna Systems Market
Satellite
Satellite Amplifier Market
Satellite
Europe Small Satellite Market
Satellite
France Satellite Connectivity Market
Satellite
Spain Satellite-Based Earth Observation Market
Satellite
UAE Satellite Communication Market
Satellite
Global Satellite Propulsion System Market