
 Laser Telemetry Binoculars Market | 2026-2036
Laser Telemetry Binoculars Market Size, Share, and Industry Trends Forecast 2026-2036
Laser Telemetry Binoculars Market Insights
Aluminum alloy housings are replacing heavier magnesium chassis in mid-tier units and is restructuring unit economics across the supply base. Zeiss leverages captive glass foundries in Germany to sustain premium optical performance. Leica anchors its positioning through precision engineering heritage and dominates European defense procurement channels. Nikon competes aggressively on cost-engineered digital rangefinder variants for Asian outdoor markets.
Laser telemetry binoculars integrate laser rangefinding modules with precision optics to measure distance, elevation, and azimuth for targeting or navigation applications, typically operating at 905 nanometer wavelength with pulse repetition rates under 10 hertz for eye-safe civilian use. Their primary purpose spans military fire control, maritime collision avoidance, and long-range wildlife monitoring where GPS denial or signal weakness renders satellite positioning unreliable. Rangefinder binoculars command the largest revenue pool due to established defense procurement volumes, while thermal imaging binoculars represent the fastest-expanding category as sensor fusion architectures merge laser telemetry with uncooled microbolometer arrays. Digital binoculars occupy a maturing mid-market segment where margin compression from smartphone-connected alternatives forces vendors toward software-defined feature differentiation.
FDA laser product regulations in the United States classify emitter outputs and mandate accessible safety interlocks, directly shaping product design for civilian-exportable models. EAR dual-use export controls administered by the US Commerce Department restrict rangefinding accuracy thresholds, fragmenting product architectures between unrestricted commercial variants and ITAR-governed military configurations. CE marking under the EU Radio Equipment Directive and RoHS substance restrictions compel European vendors to redesign power management circuits and eliminate legacy lead solder joints. Stakeholders must monitor evolving semiconductor laser export classifications and decide whether to maintain dual product lines or consolidate around commercially compliant platforms with software-locked performance tiers.
Market Dynamics
Defense procurement cycles in Germany, the United States, and Japan are compressing supplier lead times while EU Green Deal ecodesign mandates force simultaneous retooling of laser component supply chains. This dual pressure is restructuring competitive positioning around energy-efficient architectures and dual-use compliance capabilities.
Growth Catalysts
- ITAR-governed military configurations:US Commerce Department EAR dual-use export controls create captive demand for domestically certified rangefinding systems among NATO-aligned defense forces.
- Sensor fusion architectures:Maritime collision avoidance systems are integrating 905 nanometer laser modules with uncooled microbolometer arrays for all-weather navigation reliability.
- Germany:Bundeswehr artillery spotting modernization programs are expanding volume commitments for rangefinder binoculars with integrated ballistic calculators.
Market Restraints
- Semiconductor laser export classifications:BIS and DGFT restrictions on high-pulse-rate emitters fragment product architectures between commercial and defense-grade platforms.
- Magnesium chassis cost volatility:Mid-tier manufacturers face margin compression as aluminum alloy substitution requires retooling of precision machining workflows.
- Smartphone-connected alternatives:Consumer outdoor segments face substitution pressure from GPS-enabled mobile applications with sufficient accuracy for casual rangefinding needs.
Strategic Opportunities
- India:PLI scheme incentives for defense electronics manufacturing create localized assembly opportunities for ITAR-compliant rangefinder subsystems.
- Software-defined feature differentiation:Digital binocular vendors are unbundling hardware from subscription-based ballistic calculation and environmental compensation algorithms.
- EU AI Act:Automated target recognition compliance requirements favor vendors with embedded edge-computing architectures for European defense procurement channels.
Industry Challenges
- Optical engineering talent scarcity:Precision glass grinding and laser collimation expertise concentrates in legacy German and Japanese manufacturing clusters.
- CE marking timeline compression:EU Radio Equipment Directive recertification cycles for redesigned power management circuits extend product launch windows by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laser Telemetry Binoculars Market |
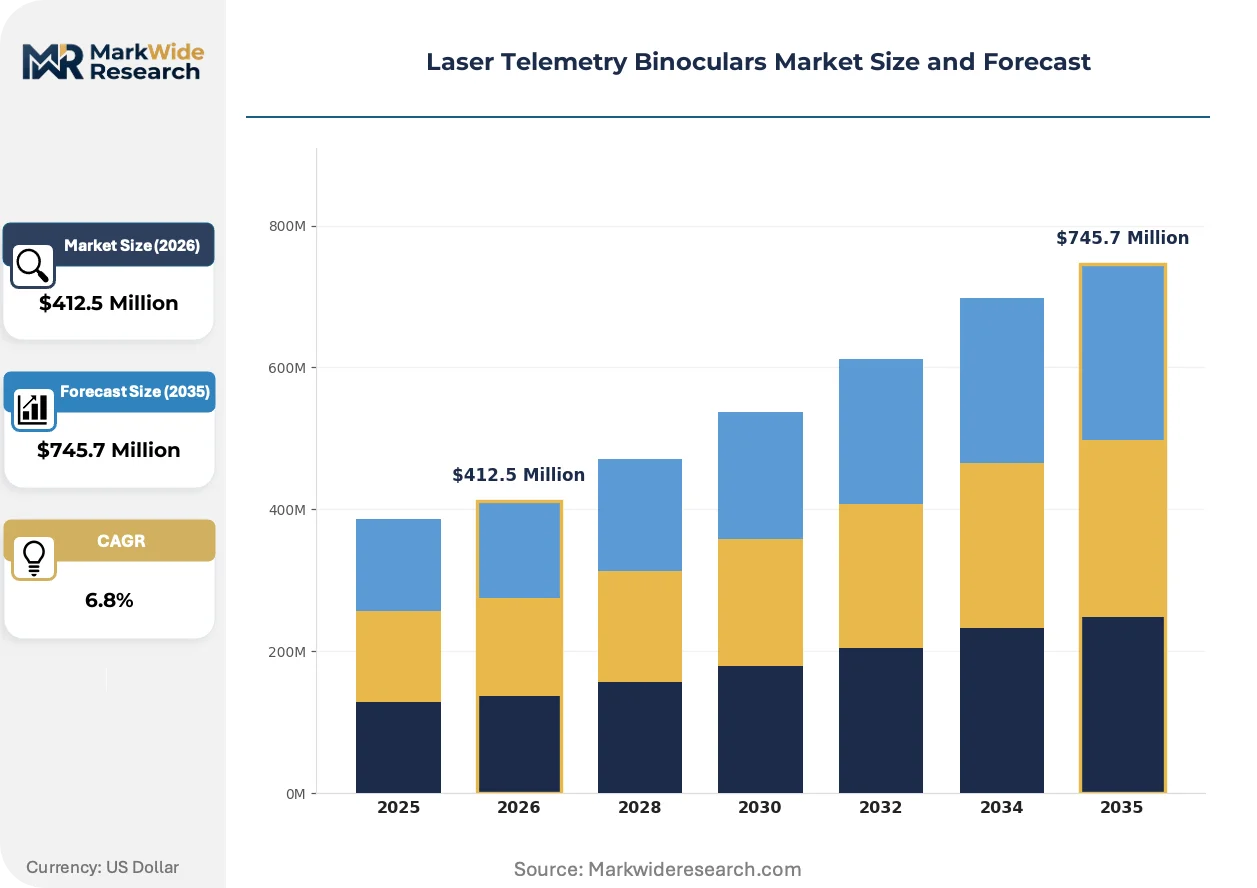
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $745.7 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rangefinder Binoculars, Digital Binoculars, Night Vision Binoculars, Thermal Imaging Binoculars Technology: Laser Rangefinding, Infrared Detection, Digital Zoom, Optical Stabilization, Reflective Targeting Application: Hunting, Maritime Navigation, Military Surveillance, Wildlife Observation, Search & Rescue End User: Defense Forces, Maritime Operators, Outdoor Enthusiasts, Security Agencies, Wildlife Researchers |
| Companies Covered | Zeiss, Leica, Swarovski Optik, Bushnell, Nikon, Leupold, Steiner Defense, Pulsar, Carl Zeiss AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laser Telemetry Binoculars Market Trends and Innovations
Active matrix organic LED microdisplays are replacing conventional eyepiece optics in next-generation units, while regulatory pressure on rare earth supply chains accelerates alternative dopant research in solid-state laser materials.
Gallium nitride laser diodes are rewriting power efficiency benchmarks for 905 nanometer emitters. Japanese maritime defense contractors are adopting these emitters for extended-range collision avoidance systems. This technology is rewriting the thermal management requirements that previously constrained pulse repetition rates in compact binocular form factors.
EU Green Deal ecodesign requirements are mandating standby power consumption below 0.5 watts for battery-operated optical equipment. European vendors are redesigning laser driver circuits and eliminating always-on Bluetooth beaconing. Civilian-exportable models destined for German and Austrian hunting markets face the most aggressive compliance deadlines.
Defense procurement officers are consolidating vendor relationships around platforms offering unified logistics support across rangefinder, night vision, and thermal imaging categories. System integrators are displacing standalone binocular specialists in NATO tender processes. This concentration is most visible in United States Army and Marine Corps modernization programs where multi-sensor contracts favor full-spectrum suppliers.
Laser Telemetry Binoculars Market Segmentation
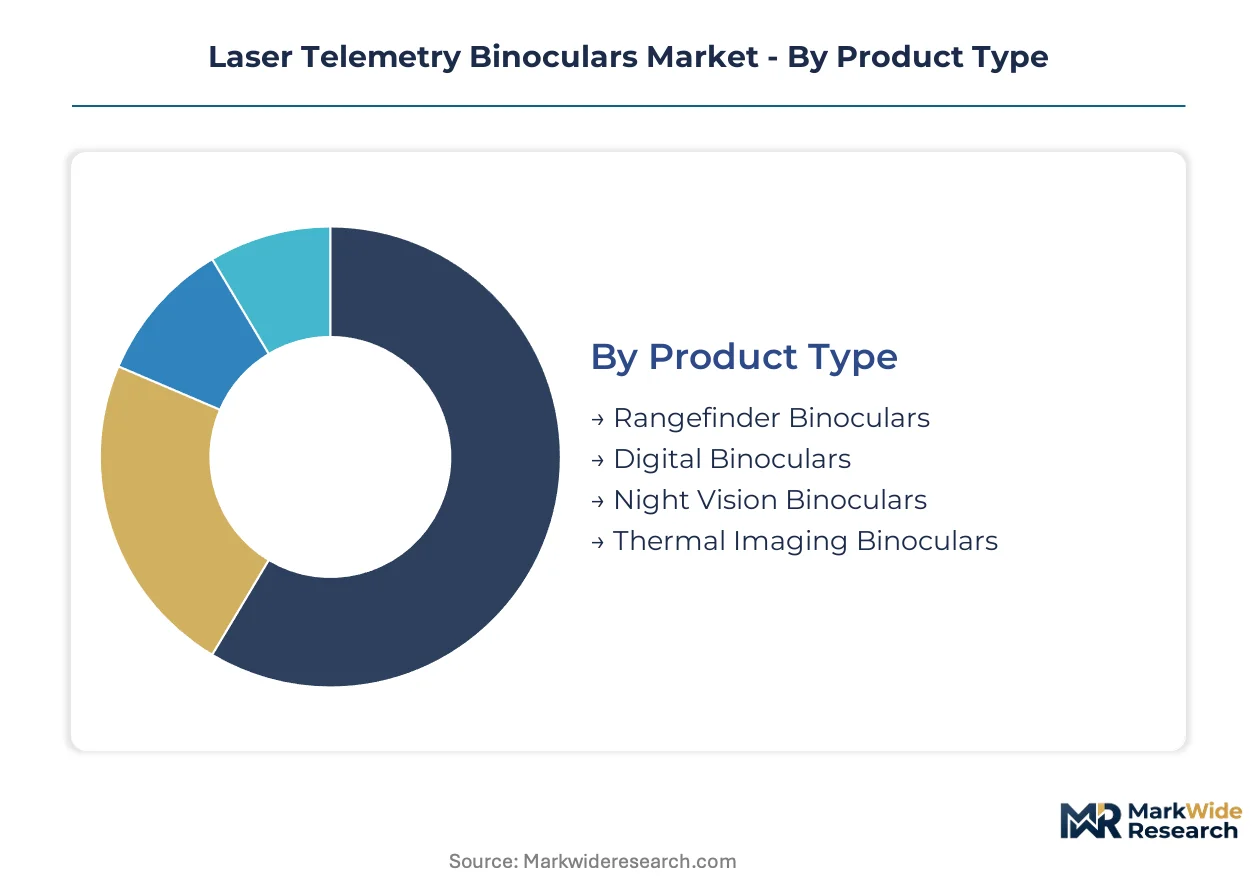
Laser telemetry binoculars fragment across four distinct axes that determine procurement priorities and margin structures. Product type governs defense contract eligibility, while technology selection locks vendors into specific regulatory compliance pathways. Application and end-user dimensions further stratify pricing power and replacement cycle velocity.
Product Type:
Optical architecture defines unit economics and defense certification requirements across the category.
- Rangefinder Binoculars:These units integrate 905 nanometer laser modules with precision glass optics for distance, elevation, and azimuth measurement. Bundeswehr artillery spotting programs in Germany are expanding volume commitments for variants with embedded ballistic calculators.
- Thermal Imaging Binoculars:Uncooled microbolometer arrays merge with laser telemetry in sensor fusion architectures for all-weather navigation reliability. Japanese maritime defense contractors are adopting gallium nitride emitters to extend detection ranges while compressing thermal management footprints.
- Digital Binoculars:Software-defined feature sets and smartphone connectivity define this maturing mid-market segment where vendors unbundle hardware from subscription-based ballistic calculation algorithms.
- Night Vision Binoculars:Image intensifier tubes paired with laser rangefinding serve military surveillance and security agency applications requiring low-light target acquisition.
Rangefinder binoculars lead on scale; thermal imaging binoculars lead on momentum.
Technology:
Emitter specification and signal processing architecture determine export control classification and power efficiency benchmarks.
- Laser Rangefinding:905 nanometer wavelength operation with pulse repetition rates under 10 hertz maintains eye-safe civilian certification under FDA regulations. Gallium nitride diodes are rewriting power efficiency benchmarks and extending operational endurance in compact form factors.
- Infrared Detection:Passive thermal signature capture enables target identification without active emission, critical for covert military surveillance applications where emission detection risks compromise.
- Digital Zoom:Electronic magnification supplements optical systems in cost-engineered variants for Asian outdoor markets where Nikon competes aggressively on price-performance ratios.
- Optical Stabilization:Gyroscopic or electronic compensation systems maintain image clarity on maritime platforms subject to vessel motion and vibration.
- Reflective Targeting:Retroreflector-dependent measurement modes enhance accuracy for fixed-position artillery spotting and survey applications.
Laser rangefinding anchors volume; infrared detection is climbing the fastest.
Application:
Use case determines environmental sealing requirements, accuracy thresholds, and regulatory jurisdiction.
- Military Surveillance:ITAR-governed configurations with restricted rangefinding accuracy serve NATO-aligned defense forces under US Commerce Department EAR dual-use export controls.
- Maritime Navigation:Collision avoidance systems integrate laser modules with uncooled microbolometer arrays for all-weather reliability on commercial and naval vessels.
- Hunting:Civilian-exportable models for German and Austrian markets face aggressive EU Green Deal ecodesign compliance deadlines for standby power consumption below 0.5 watts.
- Wildlife Observation:GPS-denied environments drive demand for autonomous distance measurement where satellite positioning proves unreliable.
- Search & Rescue:Rapid deployment requirements favor ruggedized housings with extended battery endurance for alpine and maritime emergency response.
Military surveillance commands premium pricing; maritime navigation shows steepest expansion trajectory.
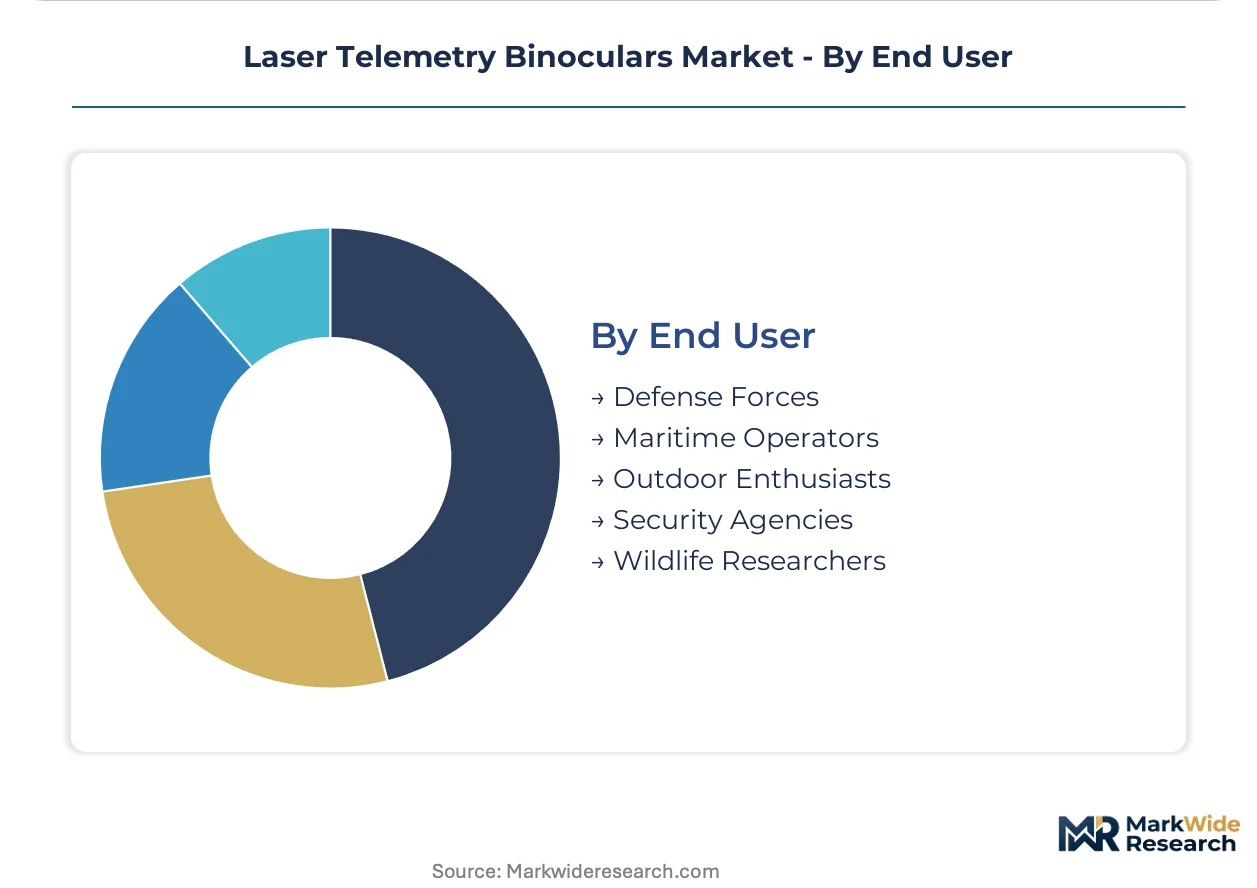
End User:
Procurement authority and budget cycle timing create distinct sales motion requirements.
- Defense Forces:Multi-sensor consolidation in United States Army and Marine Corps modernization programs favors full-spectrum suppliers over standalone binocular specialists.
- Maritime Operators:Commercial shipping lines and naval commands prioritize unified logistics support across rangefinder, night vision, and thermal imaging categories.
- Outdoor Enthusiasts:Substitution pressure from GPS-enabled smartphone applications constrains pricing power in casual rangefinding segments.
- Security Agencies:Border patrol and critical infrastructure protection drive demand for night vision variants with laser augmentation.
- Wildlife Researchers:Non-invasive observation requirements favor infrared detection modes that eliminate visible spectrum disturbance.
Defense forces concentrate procurement volume; maritime operators are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wetzlar-Oberhessen in Germany anchors precision optics manufacturing for laser telemetry binoculars, with Zeiss and Leica maintaining captive glass foundries and engineering clusters. Defense procurement cycles in NATO-aligned nations compress supplier lead times while dual-use export controls fragment product architectures between commercial and ITAR-governed configurations.
United States
Army and Marine Corps modernization programs consolidate multi-sensor contracts around full-spectrum suppliers. FDA laser product regulations classify emitter outputs and mandate accessible safety interlocks for civilian-exportable models. Defense procurement channels in Huntsville, Alabama and Orlando, Florida concentrate artillery spotting and night vision integration contracts.
Germany
Bundeswehr artillery spotting programs expand volume commitments for rangefinder variants with embedded ballistic calculators. EU Green Deal ecodesign mandates force retooling toward standby power consumption below 0.5 watts. Wetzlar and Oberkochen industrial clusters sustain precision glass grinding expertise that concentrates laser collimation capabilities.
Japan
Maritime defense contractors adopt gallium nitride laser diodes for extended-range collision avoidance systems. METI procurement guidelines favor domestic vendors for naval modernization programs. Nagoya and Yokohama manufacturing bases integrate uncooled microbolometer arrays with 905 nanometer emitters for all-weather navigation reliability.
India
PLI scheme incentives for defense electronics manufacturing create localized assembly opportunities for ITAR-compliant rangefinder subsystems. DGFT restrictions on high-pulse-rate emitters shape import substitution strategies. Bengaluru and Hyderabad defense corridors attract system integrators seeking to bypass semiconductor laser export classification barriers.
United Kingdom
Border patrol and critical infrastructure protection drive demand for night vision variants with laser augmentation. CE marking under the EU Radio Equipment Directive compels recertification of redesigned power management circuits. Glasgow and Southampton maritime clusters prioritize unified logistics support across rangefinder and thermal imaging categories.
Laser Telemetry Binoculars Market Competitive Landscape
Global majors compete with regional champions across defense certification and dual-use compliance capabilities. The vendor base stratifies into three tiers: premium European heritage brands with captive optical supply chains, mid-tier Asian cost-engineered specialists, and emerging system integrators displacing standalone binocular specialists in NATO tender processes. Dominant competitive moves include sensor fusion portfolio diversification and geographic expansion through localized assembly partnerships.
Within the premium heritage tier, Zeiss and Leica exemplify positioning through precision engineering legacy and defense procurement channel dominance. Nikon occupies a position among cost-engineered digital rangefinder specialists competing aggressively for Asian outdoor market share. These three anchors illustrate how optical engineering talent scarcity concentrates competitive advantage in legacy German and Japanese manufacturing clusters.
| Leading Market Players |
|---|
| Zeiss |
| Leica |
| Swarovski Optik |
| Bushnell |
| Nikon |
| Leupold |
| Steiner Defense |
| Pulsar |
| Carl Zeiss AG |
| Others |
Pricing and Supply Chain Analysis
Gallium nitride laser diode adoption is simultaneously compressing thermal management costs and concentrating emitter sourcing among Japanese and German semiconductor foundries. This technology transition redraws cost curves across mid-tier and premium product lines while locking vendors into specific regulatory compliance tiers.
Pricing Analysis
Input-cost pass-through from rare earth dopants and precision glass substrates drives three-tier pricing structure across premium, standard, and economy levels. ITAR certification tier and captive optical supply chain integration separate Zeiss and Leica positioning from Nikon cost-engineered variants. Pricing pressure stems from aluminum alloy substitution retooling costs in mid-tier magnesium chassis displacement. Outdoor enthusiasts exhibit highest price sensitivity, while defense procurement channels absorb premium tiers through multi-year contract structures.
Supply Chain Analysis
Optical engineering talent scarcity in Wetzlar-Oberhessen and Nagoya manufacturing clusters constrains production scaling for precision glass grinding and laser collimation. Germany, Japan, and the United States anchor geographic supply concentration for rangefinder module assembly. Raw material dependencies center on germanium substrates, rare earth laser dopants, and aerospace-grade aluminum alloys. Single-source vulnerability in gallium nitride wafer supply creates structural risk exposure. Distribution runs through defense procurement channels in Huntsville and Orlando, Austrian and German hunting retailers, and maritime system integrators in Yokohama.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Laser telemetry binoculars represent a late-cycle quality story as defense procurement shifts toward sensor fusion platforms demanding unified logistics support across rangefinder, night vision, and thermal imaging categories.
For Market Incumbents: Hedge against system integrator displacement in NATO tender processes by deepening backward integration into captive glass foundries and gallium nitride emitter supply chains. Prioritize EU AI Act compliance investment for automated target recognition architectures to defend European defense channel access against full-spectrum competitors. For New Entrants and Emerging Players: Direct-to-consumer digital channels targeting Indian defense electronics manufacturing corridors under PLI scheme incentives offer the most penetrable white-space entry. Pursue localized assembly partnerships in Bengaluru and Hyderabad to bypass DGFT semiconductor laser export classification barriers while building ITAR compliance capabilities. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier aluminum alloy housing specialists facing margin compression from magnesium substitution retooling costs. Five-to-ten year viability hinges on successful sensor fusion portfolio diversification. Monitor gallium nitride laser diode adoption rates in Japanese maritime defense contracts as the primary inflection signal for technology transition completion.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Platform Integration | Maritime collision avoidance systems in Japan merge laser telemetry with uncooled microbolometer arrays for all-weather reliability. |
| Backward Integration into Captive Glass Foundries | Zeiss and Leica sustain premium optical performance through in-house precision grinding expertise in Wetzlar-Oberhessen clusters. |
| EU Green Deal Ecodesign Compliance Investment | Standby power consumption below 0.5 watts mandates redesign of laser driver circuits for German and Austrian hunting markets. |
| Localized Assembly Partnership in India | PLI scheme incentives attract system integrators seeking to bypass DGFT high-pulse-rate emitter export restrictions. |
| Software-Defined Feature Unbundling | Digital binocular vendors separate hardware from subscription-based ballistic calculation algorithms to escape smartphone substitution pressure. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with defense procurement officers, optical engineering directors, maritime system integrators, and hunting retail channel managers with secondary validation. Defense contract databases, FDA laser product registration filings, EU Radio Equipment Directive certification records, and customs trade data for precision optical equipment informed bottom-up and top-down triangulation.
Historical reference periods anchored volume and value projections across the modeling period, with CAGR derivation reflecting segment-specific adoption curves. Product type, technology architecture, application use case, and end-user procurement authority structured the analytical framework. Gallium nitride laser diode efficiency benchmarks and EU Green Deal ecodesign compliance timelines served as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for solid-state laser materials or active matrix organic LED microdisplays would alter the outlook. Forecasts reflect assumptions around defense procurement cycle continuity, semiconductor laser export classification stability, and rare earth supply chain resilience. Material deviation in Bundeswehr artillery spotting program commitments or BIS emitter restriction amendments warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Surveillance
Europe Intelligence Surveillance and Reconnaissance Market
Military Surveillance
Drone Surveillance Platform Market
Military Surveillance
Maritime Surveillance and Intervention Market
Military Surveillance
EO/IR Gimbal Market
Military Surveillance
Maritime Situational Awareness Systems Market
Military Surveillance
Early Warning Radar Market
Military Surveillance
Target Acquisition Systems Market
Military Surveillance
Tactical Optics Market
Military Surveillance
Anti-Sniper Detection System Market
Military Surveillance
Military Electro-Optics/Infrared (EO/IR) Systems Market
Military Surveillance
Global Military Electro-Optical and Infrared Systems Market
Military Surveillance
Air-Based Military Electro-Optical and Infrared Systems Market
Military Surveillance
Defense Geospatial Market
Military Surveillance
Airborne Target Acquisition Systems Market
Military Surveillance
North America Hydrographic Survey Equipment Market
Military Surveillance
Global Airborne Warning and Control System Market