
 Ultra Short Base Line Positioning System Market | 2026-2036
Ultra Short Base Line Positioning System Market Size, Share, and Industry Trends Forecast 2026-2036
Ultra Short Base Line Positioning System Market Analytics
ISO 13628-8 subsea production system qualification is collapsing the vendor pool for certified Ultra Short Base Line transponder hardware. Kongsberg Maritime leverages its integrated seabed-to-surface portfolio to dominate Norwegian deepwater contracts. Teledyne Marine sustains transducer manufacturing scale across multiple acoustic frequency bands. Sonardyne International anchors its position through captive supply of calibration-grade transponders for defense survey programs.
An Ultra Short Base Line Positioning System employs phased-array acoustic transducers operating at 20-40 kHz to calculate subsea asset coordinates through time-of-flight triangulation from a surface vessel. Fixed Systems command the highest installed base in permanent offshore installations where long-term seabed stability justifies capital deployment, while Portable Systems represent the fastest-expanding category as environmental monitoring contractors seek rapid-deployment alternatives for short-duration survey campaigns. Hybrid Systems integrating inertial navigation with acoustic fixes are capturing margin pools in ROV operations where GPS denial requires continuous dead-reckoning backup.
FAA underwater vehicle guidelines, the EU Marine Strategy Framework Directive, and BIS acoustic equipment standards collectively dictate transponder frequency allocation, environmental noise thresholds, and import certification pathways. These frameworks compel manufacturers to maintain parallel product variants for jurisdiction-specific compliance, elevating R&D overhead but creating regulatory moats against uncertified competitors. Stakeholders must monitor evolving seabed sovereignty claims and associated national content requirements that threaten to fragment procurement standards across coastal state exclusive economic zones.
Market Dynamics
ISO 13628-8 subsea production system qualification is compressing the certified vendor pool for Ultra Short Base Line transponder hardware, forcing procurement officers to consolidate supplier relationships around integrated seabed-to-surface portfolios.
Growth Catalysts
- IMO maritime safety codes:Tightening equipment certification requirements are mandating redundant acoustic positioning on offshore construction vessels, expanding hardware replacement cycles.
- Deepwater energy projects:Norway's North Sea cluster demands centimeter-level underwater positioning accuracy for subsea asset installation, pulling advanced transponder systems into frontline deployment.
- Environmental monitoring contractors:Rapid-deployment survey campaigns are accelerating portable system adoption as a flexible alternative to fixed seabed installations.
Market Restraints
- Transducer material cost volatility:Piezoelectric ceramic supply concentrates in East Asian specialty manufacturers, exposing production schedules to rare earth price swings.
- Calibration-grade transponder scarcity:Defense survey programs capture limited production capacity, constraining commercial availability for civilian offshore operators.
- Phased-array acoustic frequency allocation:National regulators enforce non-overlapping 20-40 kHz band plans, fragmenting product variants and elevating R&D overhead.
Strategic Opportunities
- Brazil pre-salt basin expansion:ANVISA seabed licensing frameworks are opening new procurement channels for certified positioning systems in deepwater hydrocarbon development.
- Inertial-acoustic hybrid convergence:ROV operations requiring GPS denial backup create margin pools for integrated dead-reckoning solutions.
- EU Marine Strategy Framework Directive:Environmental noise thresholds are incentivizing quieter transducer designs that command premium positioning in European waters.
Industry Challenges
- Parallel product variant maintenance:Jurisdiction-specific compliance requirements force manufacturers to sustain multiple hardware configurations, complicating inventory management.
- Seabed sovereignty claim fragmentation:Coastal state exclusive economic zone regulations threaten to splinter procurement standards, increasing contract negotiation complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ultra Short Base Line Positioning System Market |
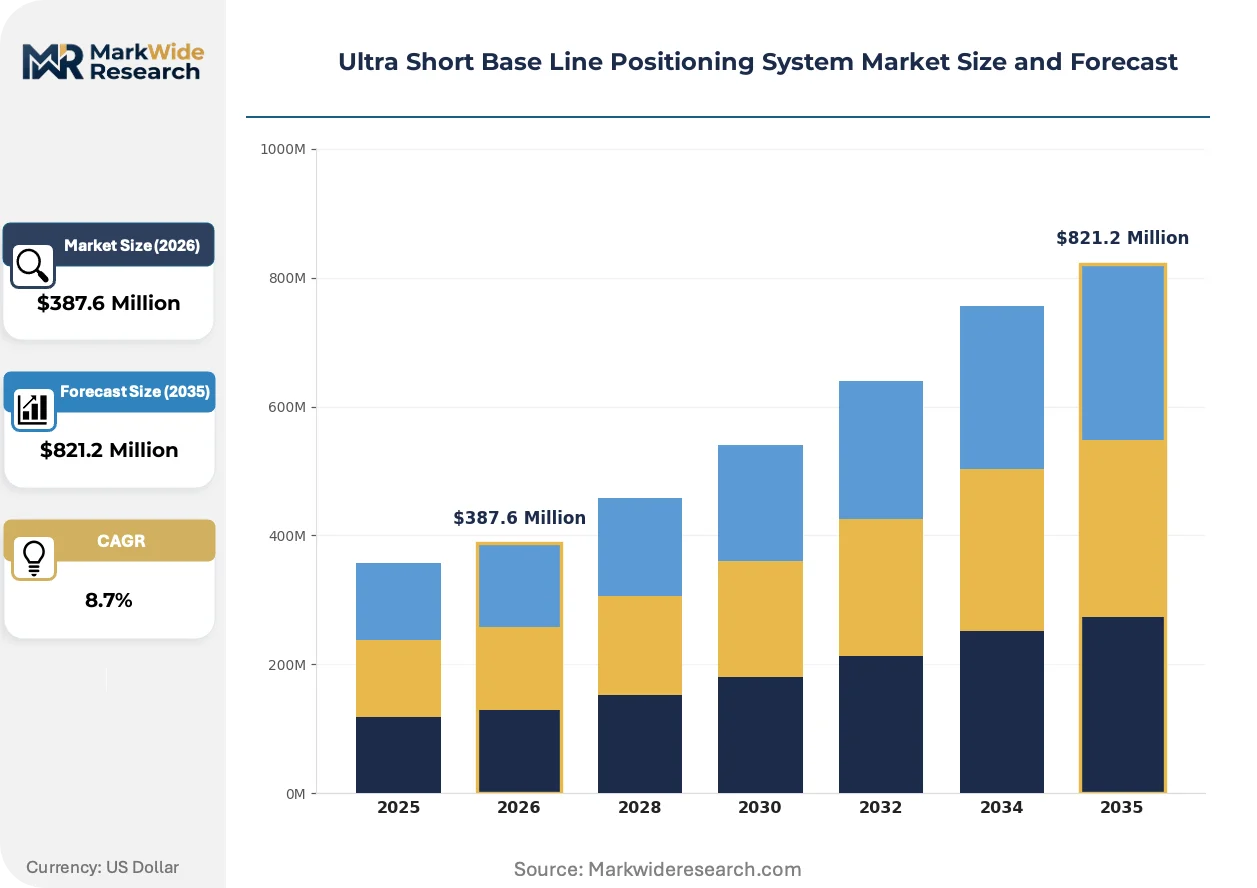
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gimbaled Systems, Fixed Systems, Semi-Fixed Systems, Portable Systems End User: Marine Surveyors, Offshore Construction, Defense Applications, Oil & Gas Industry Technology: Acoustic Positioning, GPS, Inertial Navigation, Hybrid Systems Application: Subsea Exploration, Hydrographic Surveying, ROV Operations, Environmental Monitoring |
| Companies Covered | Kongsberg Marine, Teledyne Marine, iXblue, Sonardyne Holdings, Tritech International, Sonardyne International, Exail Technologies, Kongsberg Maritime, Teledyne Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ultra Short Base Line Positioning System Market Evolving Landscape
Acoustic positioning technology is splitting between permanent seabed infrastructure and rapidly deployable survey platforms, with regulatory pressure and operational flexibility demands pulling development in divergent directions.
Phased-array acoustic transducers operating at 20-40 kHz calculate subsea asset coordinates through time-of-flight triangulation from surface vessels. Offshore construction firms in Norway's North Sea cluster are adopting these systems at accelerated pace for subsea asset installation. The technology is bifurcating the vendor landscape between integrated seabed-to-surface providers and specialized transducer manufacturers.
EU Marine Strategy Framework Directive environmental noise thresholds are compelling manufacturers to engineer quieter acoustic signatures into new transponder designs. Industrial consequence includes elevated R&D cycles and premium pricing for compliant hardware. Norwegian deepwater contractors are responding by specifying certified low-noise systems in tender documents, creating procurement preference shifts.
Environmental monitoring contractors are unbundling after-sales calibration services from hardware procurement, compressing traditional integrated supply relationships. Survey service providers are replacing captive maintenance contracts with third-party metrology laboratory arrangements. This pattern is most visible in the North Sea cluster where rapid-deployment campaign economics favor operational flexibility over long-term vendor lock-in.
Ultra Short Base Line Positioning System Market Segmentation
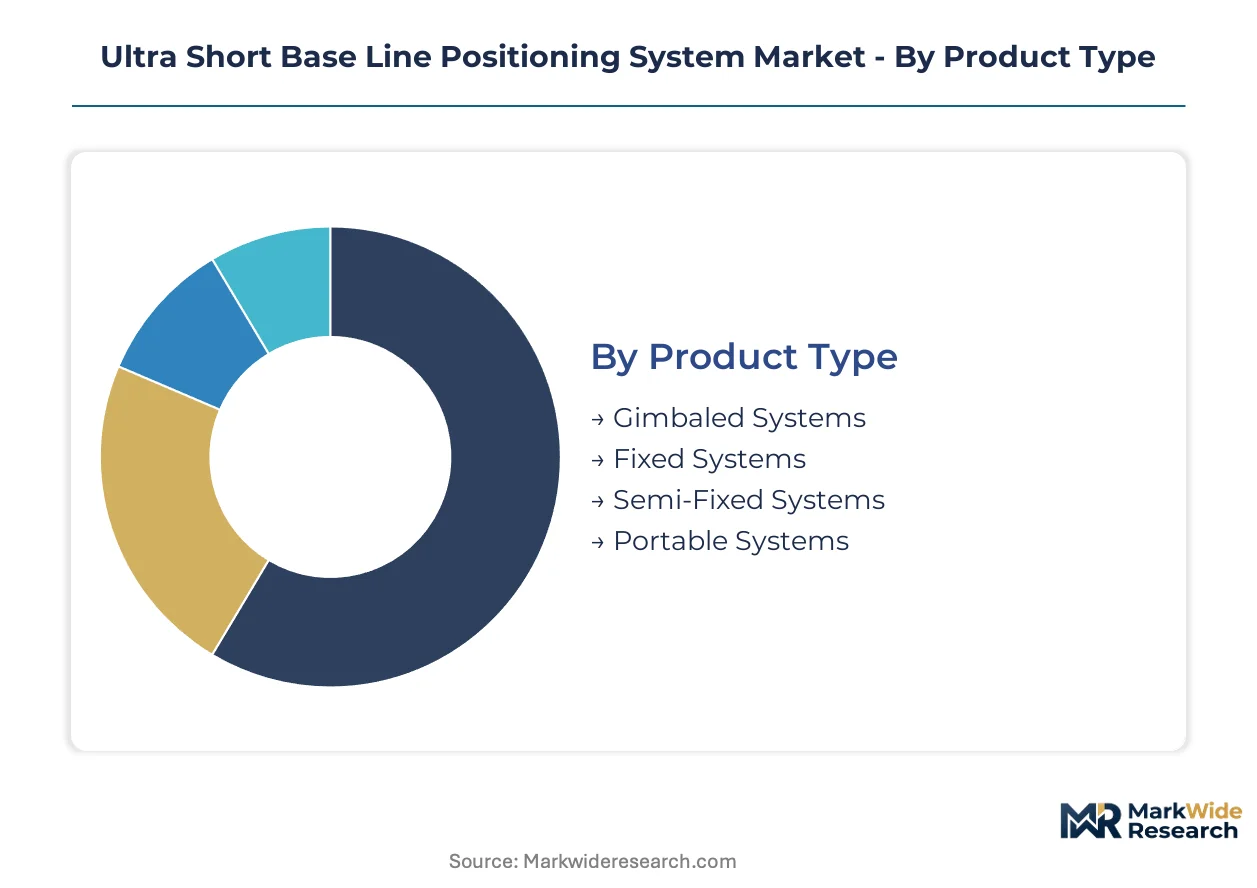
Ultra Short Base Line positioning systems fragment across four distinct category axes. Product configuration determines capital deployment patterns, while end-use concentration shapes regional demand clusters and technology integration requirements.
Product Type:
Fixed systems flow through long-cycle offshore engineering procurement channels, while portable configurations reach environmental contractors through rapid-rental networks and survey service providers.
- Fixed Systems:Permanent seabed installations with hardened transponder arrays rated for decade-long subsea exposure. Norway's North Sea cluster anchors procurement volume as deepwater energy projects demand centimeter-level stability for subsea asset installation.
- Portable Systems:Rapid-deployment configurations with modular transducer pods and vessel-agnostic mounting. Environmental monitoring contractors in European waters are compressing hardware replacement cycles through short-duration rental arrangements rather than capital purchase.
- Gimbaled Systems:Stabilized phased-array platforms compensating for vessel motion in high-sea states.
- Semi-Fixed Systems:Hybrid deployments combining seabed anchors with recoverable surface electronics.
Fixed systems dominate installed base. Portable systems are where expansion concentrates.
End User:
Defense survey programs concentrate demand for calibration-grade hardware, while commercial offshore operators prioritize integrated seabed-to-surface portfolios that compress procurement complexity.
- Offshore Construction:Subsea installation contractors deploying redundant acoustic positioning for IMO-mandated maritime safety compliance. Norwegian deepwater projects specify certified transponder systems in tender documents, creating procurement preference shifts toward qualified vendors.
- Oil & Gas Industry:Hydrocarbon operators integrating USBL with subsea production systems under ISO 13628-8 qualification protocols. Brazil's ANVISA seabed licensing frameworks are opening new procurement channels for certified positioning hardware in pre-salt basin development.
- Marine Surveyors:Hydrographic service providers unbundling after-sales calibration from hardware procurement.
- Defense Applications:Military survey programs capturing limited production capacity of calibration-grade transponders.
Offshore construction commands premium pricing tiers. Oil and gas procurement is climbing the fastest as deepwater frontier projects multiply.
Technology:
Acoustic positioning retains core revenue share, though hybrid architectures are gaining margin traction where GPS denial creates operational risk.
- Acoustic Positioning:Phased-array transducers operating at 20-40 kHz calculating coordinates through time-of-flight triangulation. National regulators enforce non-overlapping frequency band plans, fragmenting product variants across jurisdiction-specific compliance requirements.
- Hybrid Systems:Inertial navigation fused with acoustic fixes for continuous dead-reckoning backup. ROV operations in GPS-denied environments are pulling integrated solutions into frontline deployment.
- GPS:Surface vessel positioning providing reference coordinates for acoustic triangulation baselines.
- Inertial Navigation:Self-contained motion sensing for short-duration positioning continuity during acoustic signal interruption.
Acoustic positioning dominates installed base. Hybrid systems are where technology investment concentrates.
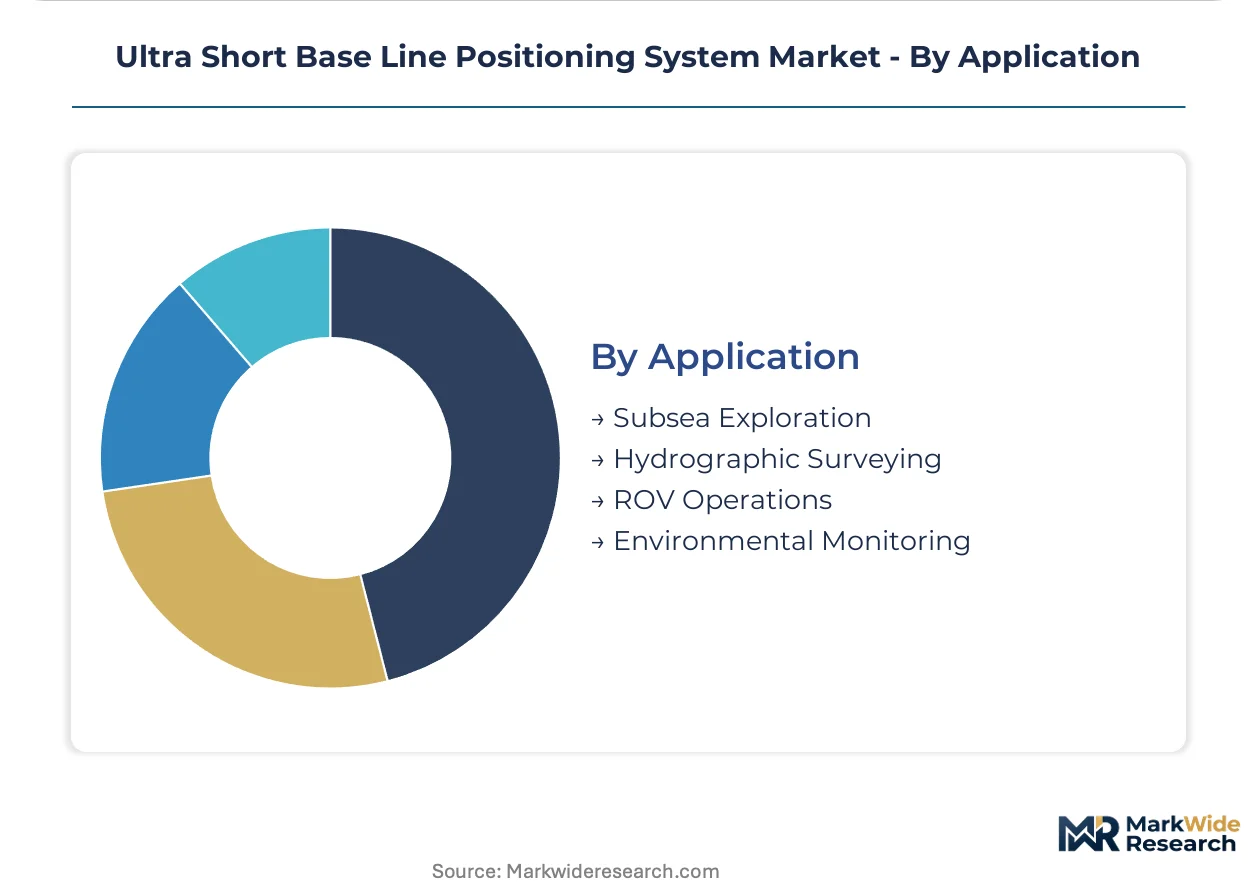
Application:
Subsea exploration and ROV operations split procurement channels between permanent infrastructure deployment and campaign-based rental economics.
- ROV Operations:Remotely operated vehicle positioning requiring continuous coordinate updates for manipulator precision. North Sea contractors are specifying inertial-acoustic hybrid architectures to mitigate GPS denial risk during subsea intervention.
- Environmental Monitoring:Rapid-deployment survey campaigns for EU Marine Strategy Framework Directive compliance. Contractors favor portable system rentals over fixed installations, compressing traditional integrated supply relationships.
- Subsea Exploration:Frontier hydrocarbon prospecting requiring seabed-to-surface positioning integration.
- Hydrographic Surveying:Charting and mapping operations with IMO-mandated equipment certification requirements.
ROV operations anchor technology premium capture. Environmental monitoring is where volume expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Deepwater energy contractors and defense survey programs concentrate procurement power across five national markets. Each geography presents distinct regulatory hurdles and industrial cluster dynamics that shape vendor selection criteria.
Norway
North Sea offshore construction firms drive demand for centimeter-level positioning accuracy in subsea asset installation. The Norwegian Petroleum Safety Authority enforces redundant acoustic positioning mandates on offshore vessels. Stavanger and Bergen harbor Europe's densest concentration of subsea engineering contractors specifying certified USBL systems in tender documents.
United States
Gulf of Mexico deepwater operators and Navy survey programs split procurement between commercial offshore and defense applications. FAA underwater vehicle guidelines dictate transponder frequency allocation and equipment certification pathways. Houston anchors the Western Hemisphere's largest subsea technology procurement cluster, with engineering offices clustering in the Energy Corridor.
Brazil
Pre-salt basin hydrocarbon development is opening new procurement channels for certified positioning hardware. ANVISA seabed licensing frameworks impose equipment qualification requirements that mirror ISO standards. Rio de Janeiro hosts the primary engineering decision centers for Petrobras-led deepwater projects.
United Kingdom
North Sea decommissioning campaigns and offshore wind installation are pulling portable USBL systems into rapid-deployment service. The Maritime and Coastguard Agency implements IMO safety code compliance inspections on construction vessels. Aberdeen maintains its position as the UK's subsea technology procurement hub despite production decline.
China
South China Sea seabed sovereignty claims and offshore energy expansion are driving indigenous positioning system development. MIIT acoustic equipment standards govern import certification and domestic frequency allocation. Shenzhen and Shanghai harbor the primary manufacturing and engineering clusters for marine electronics development.
Ultra Short Base Line Positioning System Market Competitive Landscape
Player mix skews toward integrated seabed-to-surface providers with captive transponder manufacturing. Three structural tiers have crystallized: full-stack system integrators commanding Norwegian deepwater contracts, specialized transducer manufacturers sustaining multi-frequency production scale, and calibration-grade specialists serving defense survey programs. Competitive maneuvering centers on ISO 13628-8 qualification acquisition and parallel product variant maintenance for jurisdiction-specific compliance.
Within the integrated-system tier, Kongsberg Maritime and Teledyne Marine occupy positions exemplifying full-stack seabed-to-surface portfolios. Sonardyne International sits within the calibration-grade specialist archetype, representing defense survey program concentration. These three entities anchor the vendor landscape as procurement officers consolidate supplier relationships around qualified hardware sources.
| Leading Market Players |
|---|
| Kongsberg Marine |
| Teledyne Marine |
| iXblue |
| Sonardyne Holdings |
| Tritech International |
| Sonardyne International |
| Exail Technologies |
| Kongsberg Maritime |
| Teledyne Technologies |
| Others |
Value Network & Pricing Analysis
ISO 13628-8 subsea production system qualification gates both supplier entry and price differentiation simultaneously, compressing the certified vendor pool while enabling qualified manufacturers to command structural premiums over uncertified competitors. Procurement officers face constrained choice sets that elevate pricing power for integrated seabed-to-surface providers with captive transponder manufacturing.
Pricing Analysis
Cost-plus contracts with piezoelectric ceramic indexation dominate long-cycle offshore engineering procurement. Pricing stratifies across calibration-grade, commercial-certified, and uncertified economy tiers, with defense survey programs absorbing the highest tier and environmental monitoring contractors driving volume at the commercial mid-tier. Cost compression in the economy tier is intensifying because unbundled after-sales calibration services are displacing traditional integrated supply relationships. Environmental monitoring contractors exhibit the highest price sensitivity due to rapid-deployment campaign economics, while Norwegian deepwater energy projects show the lowest sensitivity given centimeter-level accuracy requirements.
Supply Chain Analysis
Japan and China anchor piezoelectric ceramic production for acoustic transducer cores, with Norway and the United States hosting final system integration and calibration. Production draws from rare earth mineral feedstocks concentrated in East Asian specialty manufacturers, alongside precision-machined titanium housings and underwater-rated electronic assemblies. Single-source vulnerability in piezoelectric ceramic supply exposes production schedules to commodity price swings and geopolitical disruption. Distribution runs through direct long-term contracts with offshore construction firms and defense survey programs, supplemented by rapid-rental networks serving environmental monitoring contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a defensive-moat story anchored in regulatory entrenchment. ISO 13628-8 qualification requirements create switching costs that lock procurement officers into validated supplier relationships across decade-long offshore project cycles.
For Market Incumbents: Secure ISO 13628-8 qualification moats through sustained calibration-grade transponder capacity investment, insulating against emerging specialized transducer manufacturers seeking entry via portable system niches. Deepen backward integration into piezoelectric ceramic supply to mitigate raw material cost volatility and defend margin position against price-sensitive environmental monitoring contractors. For New Entrants and Emerging Players: Lead with rapid-deployment portable system architectures targeting European environmental monitoring contractors, where unbundled calibration service preferences have already eroded incumbent integrated supply relationships. Penetrate via third-party metrology laboratory partnerships that compress traditional vendor lock-in, then ladder into fixed system qualification through accumulated deployment track records. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across hybrid inertial-acoustic system development, as ROV operations in GPS-denied environments demand continuous dead-reckoning backup integration. Favor acquisition targets with dual-use defense-commercial certification portfolios and established Norwegian deepwater contract relationships. Monitor ANVISA seabed licensing framework implementation velocity in Brazil as the primary inflection indicator for frontier deepwater procurement expansion.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13628-8 Qualification Acquisition | Certification gates Norwegian deepwater contracts and defense survey program supply. |
| Hybrid Inertial-Acoustic System Development | Integration captures margin pools in ROV operations requiring GPS denial backup. |
| Piezoelectric Ceramic Backward Integration | Upstream control insulates production schedules from rare earth price volatility. |
| Third-Party Calibration Service Partnerships | Unbundled metrology arrangements penetrate environmental monitoring contractor procurement. |
| Brazil Pre-Salt Basin Market Entry | ANVISA framework alignment opens certified positioning hardware procurement channels. |
Research Methodology
Initial hypotheses were tested against primary input from offshore construction procurement officers, subsea engineering contractors, defense survey program managers, environmental monitoring service providers, and acoustic transducer manufacturing engineers, then refined through secondary validation. Primary fieldwork combined structured interviews with secondary analysis of IMO maritime safety code filings, national seabed licensing framework documentation, ISO 13628-8 certification registries, and offshore project tender databases. Bottom-up segment sizing triangulated against top-down market aggregation across product configuration, end-use concentration, technology integration, and application deployment dimensions.
Variance decomposition structured the analytical framework across the projection horizon, with modeled segmentation spanning fixed-portable-gimbaled-semi-fixed product types, offshore construction-oil and gas-marine survey-defense end users, acoustic-hybrid-GPS-inertial technology architectures, and ROV operations-environmental monitoring-subsea exploration-hydrographic surveying applications. CAGRs derived from installed base evolution and replacement cycle analysis, incorporating deepwater energy project pipeline visibility, defense procurement budget trajectories, and environmental regulatory compliance mandate timing as industry-specific forecast inputs.
Forecasts assume regulatory continuity in IMO maritime safety codes, EU Marine Strategy Framework Directive environmental noise thresholds, and BIS acoustic equipment standards; material policy shifts in frequency allocation or seabed sovereignty claims would require re-modeling. Recalibration cycles align with material shifts in national licensing framework implementations, rare earth supply disruptions, or hybrid navigation technology adoption inflections.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Navigation and Communication
Aviation Weather Radar Market
Aircraft Navigation and Communication
GPS and GNSS Receivers in Aviation Market
Aircraft Navigation and Communication
Airborne Situational Awareness Systems Market
Aircraft Navigation and Communication
Global Air Traffic Control Equipment Market
Aircraft Navigation and Communication
Aircraft Interface Device Market
Aircraft Navigation and Communication
Global Drone Navigation System Market
Aircraft Navigation and Communication
Automatic Dependent Surveillance-Broadcast (ADS-B) Market
Aircraft Navigation and Communication
Air Traffic Management Software Market
Aircraft Navigation and Communication
Europe Air Traffic Management Market
Aircraft Navigation and Communication
Defense Advanced GPS Receiver (DAGR) Market
Aircraft Navigation and Communication
Global Aviation Mapping Software Market
Aircraft Navigation and Communication
Air-Based Tactical Data Link Market
Aircraft Navigation and Communication
Aircraft Communication System Market
Aircraft Navigation and Communication
Connected Aircraft Market
Aircraft Navigation and Communication
Airborne Telemetry Market
Aircraft Navigation and Communication
Ground to Air on-Board Connectivity Market