
 Aircraft Navigation Software Market | 2026-2036
Aircraft Navigation Software Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Navigation Software Market Analysis
Aftermarket service revenue is tilting toward subscription-based flight data updates and terrain database refreshes. NAVBLUE leverages its Airbus heritage to dominate airline flight planning services across Europe and Asia. Honeywell International Inc. sustains R&D intensity in integrated avionics through its Phoenix engineering centers. Thales Group anchors military navigation contracts with NATO members while competing in civil flight management systems.
Aircraft navigation software encompasses digital systems that compute position, trajectory, and guidance commands using GPS signals, inertial reference units, and terrain databases with sub-meter accuracy requirements. These systems enable pilots and autonomous platforms to execute precision approaches, avoid terrain conflicts, and optimize fuel-efficient routing across controlled airspace. Flight Management Systems command the largest installed base but face margin compression from commoditized hardware; Cloud-Based deployment grows fastest as airlines seek reduced IT infrastructure burdens and real-time fleet synchronization. Embedded Systems retain dominance in military applications where electromagnetic hardening and jam-resistant GPS receivers justify premium pricing against commercial alternatives.
The FAA's NextGen mandate and EASA's CS-25 airworthiness standards shape certification timelines and interoperability requirements for new navigation software entrants. The EU AI Act introduces algorithmic transparency obligations for machine-learning-based flight path optimization tools deployed in European airspace. Stakeholders must monitor whether China's GB standards for BeiDou integration fragment avionics certification into competing regional ecosystems or converge toward ICAO-led harmonization.
Market Dynamics
The FAA's NextGen airspace modernization mandate is compressing retrofit timelines for commercial fleets, forcing carriers to accelerate digital cockpit upgrades while navigating fragmented certification pathways across FAA, EASA, and emerging BeiDou integration standards in China.
Growth Catalysts
- NextGen Mandate:The FAA's trajectory-based operations require airlines to deploy Performance-Based Navigation software across controlled airspace, mandating equipage for access to optimal routing and reduced separation minima.
- Flight Data Monetization:Carriers are extracting incremental value from proprietary trajectory analytics, selling anonymized performance datasets to fuel optimization service providers and airport capacity planners.
- Urban Air Mobility:eVTOL developers in Germany, the United States, and China are procuring certifiable navigation stacks for autonomous passenger operations in dense metropolitan corridors.
Market Restraints
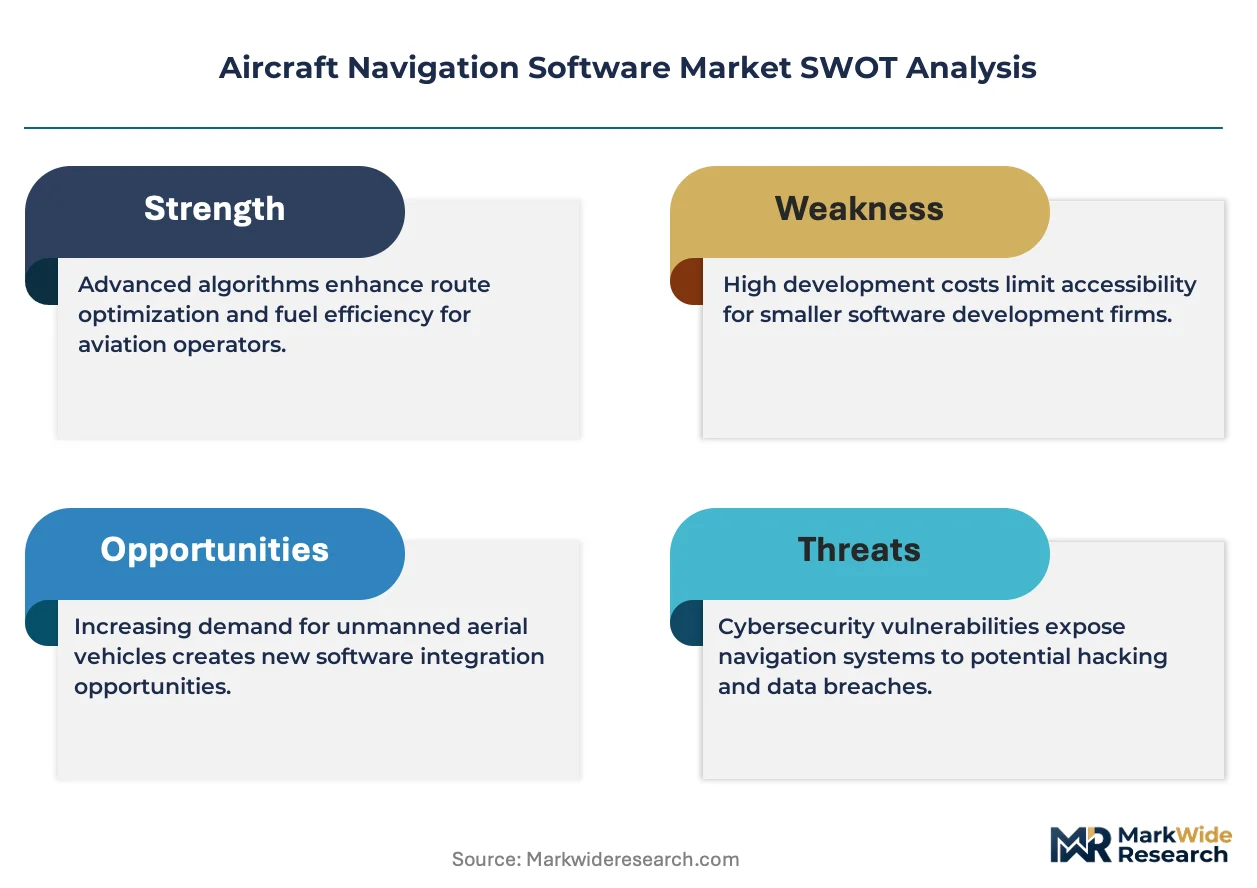
- Semiconductor Supply Concentration:Radiation-hardened GPS receiver ASICs depend on a single foundry in Taiwan, creating vulnerability for military-grade navigation hardware procurement cycles.
- DO-178C Certification Burden:Software assurance Level A requirements demand 50-70% of total development budget for new flight management system entrants, elevating breakeven volumes.
- Jam-Resistant Hardware Cost:Military M-code GPS receivers with anti-spoofing capabilities command 8-12x premium over commercial equivalents, limiting dual-use technology crossover.
Strategic Opportunities
- India Fleet Expansion:IndiGo and Air India combined orders for 970 narrow-body aircraft create concentrated demand for integrated avionics suites with indigenous GAGAN augmentation compatibility.
- Cloud-Native Flight Planning:Subscription-based 4D trajectory optimization is displacing on-premise server installations, reducing airline IT infrastructure capital intensity by 40-60%.
- EU AI Act Alignment:Machine-learning path optimization tools that demonstrate algorithmic transparency under European artificial intelligence governance frameworks gain preferential positioning with EU-registered carriers.
Industry Challenges
- DO-178C Talent Scarcity:Software verification engineers with Level A certification experience command 35-50% salary premiums, constraining development velocity for new entrants.
- Legacy ARINC 429 Integration:Hybrid architectures bridging 1970s databus protocols with modern Ethernet avionics networks multiply testing matrices and extend type certification timelines by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Navigation Software Market |
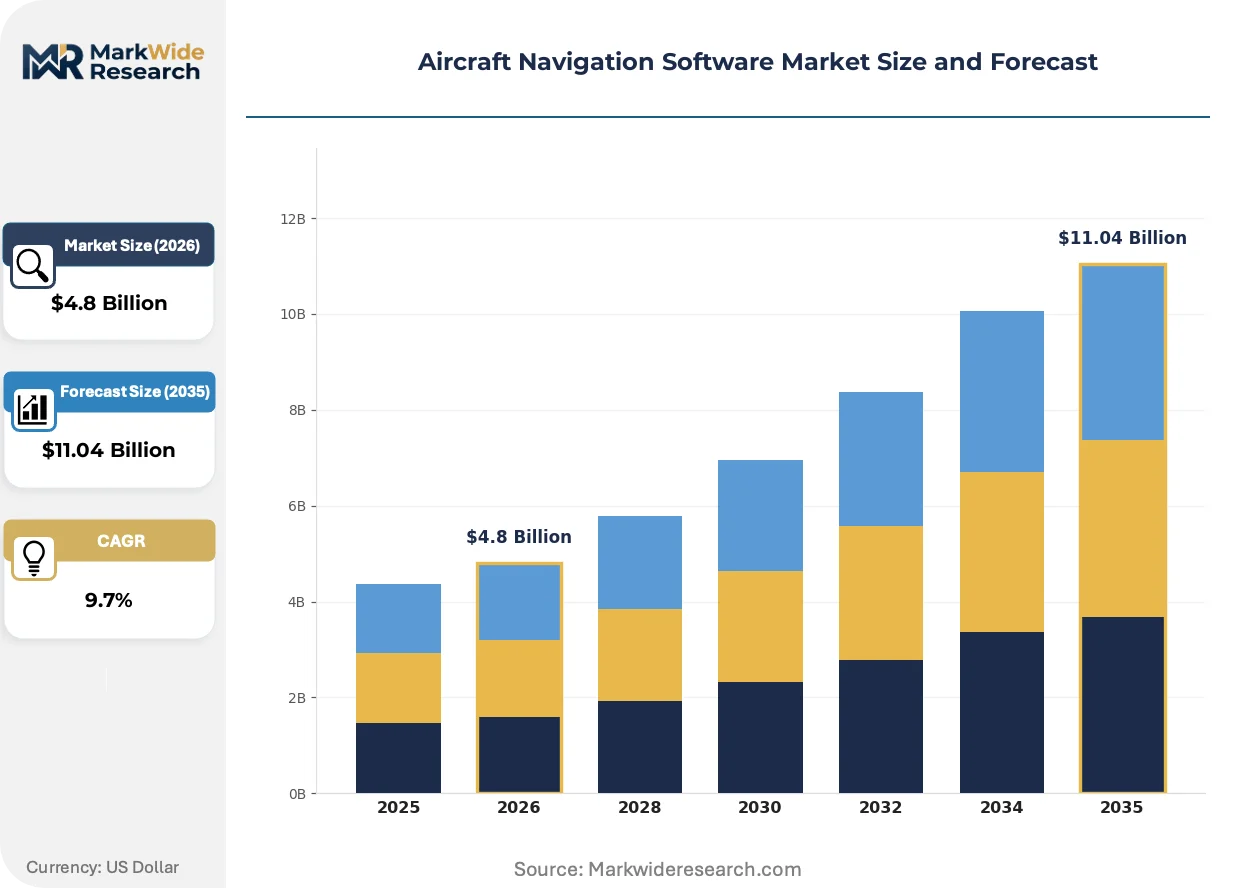
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flight Management Systems, Ground Control Software, Terrain Awareness Software, Avionics Solutions End User: Commercial Aircraft, Military Aircraft, Drones, Civil Aviation Deployment: On-Premise, Cloud-Based, Hybrid Solutions, Embedded Systems Technology: GPS, Inertial Navigation Systems, Radio Navigation, Integrated Avionics |
| Companies Covered | NAVBLUE, Garmin Ltd., Honeywell International Inc., Lufthansa Systems, Northrop Grumman Corporation, Thales Group, Jeppesen, Collins Aerospace, RTX Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Navigation Software Market Emerging Trajectories
Navigation software architectures are pivoting from federated black-box systems toward modular, software-defined platforms that decouple hardware refresh cycles from functional capability upgrades.
Synthetic vision systems fused with real-time terrain database streaming are rendering obsolete traditional blue-background primary flight displays in business jet and helicopter segments. Gulfstream and Dassault are mandating SVS equipage on new production aircraft. The technology is rendering obsolete pilot reliance on instrument interpretation during low-visibility approach phases.
REACH restrictions on per- and polyfluoroalkyl substances are compelling avionics manufacturers to reformulate conformal coatings and lubricants used in inertial reference units. ECHA's 2023 PFAS restriction proposal forces suppliers to qualify alternative chemistries before 2027 sunset dates. European component suppliers are accelerating fluorine-free material validation to maintain airworthiness certification continuity.
Airlines are unbundling navigation database subscriptions from integrated avionics hardware purchases, treating terrain and obstacle updates as separately negotiable service lines. Lufthansa and Delta have established direct relationships with NAVBLUE and Jeppesen for flight planning data, bypassing OEM markup structures. This procurement fragmentation is most pronounced among top-twenty global carriers with sufficient fleet scale to justify direct licensing.
Aircraft Navigation Software Market Segmentation
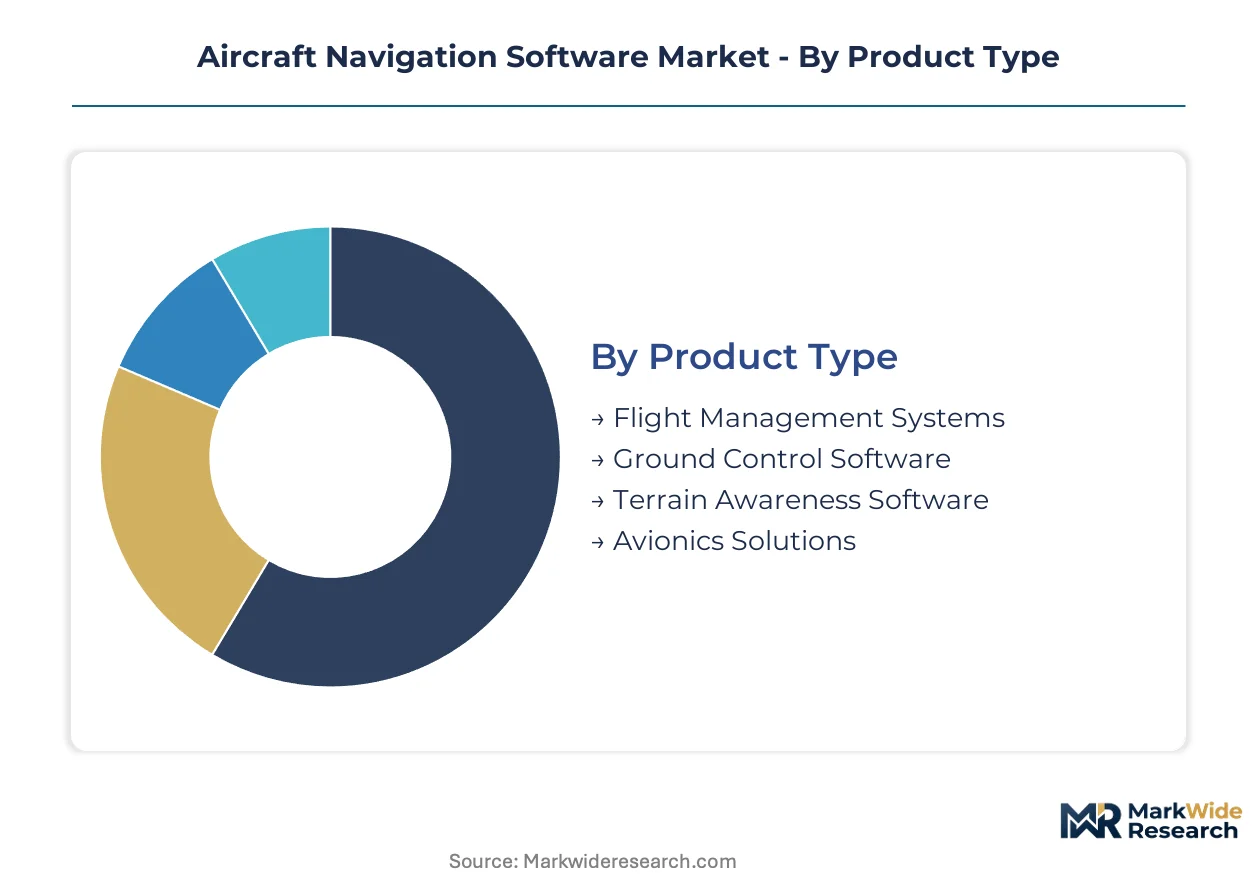
Navigation software procurement cycles vary dramatically across aircraft platforms, with commercial retrofits turning over every 7-10 years while military systems endure 20-year service lives. Understanding these differential replacement rhythms helps vendors align R&D pipelines with revenue concentration points.
Product Type:
Flight Management Systems command the longest replacement cycles due to DO-178C recertification burdens, while Terrain Awareness Software refreshes annually as obstacle databases require continuous updates.
- Flight Management Systems:Core avionics computers executing lateral and vertical flight path optimization through ARINC 429 and AFDX databus architectures. Demand concentrates in narrow-body retrofit programs at Delta, United, and American Airlines as FAA NextGen mandates compress equipage timelines for trajectory-based operations access.
- Ground Control Software:Mission planning and fleet dispatch systems managing pre-flight performance calculations and 4D trajectory optimization. European carriers including Lufthansa and Air France-KLM are migrating these workloads to cloud-native architectures, reducing on-premise server capital intensity.
- Terrain Awareness Software:Real-time terrain database correlation with GPS position for predictive ground proximity warning.
- Avionics Solutions:Integrated cockpit display suites combining navigation, communication, and surveillance functions.
Flight Management Systems anchors the volume base while Ground Control Software gains share at the steepest rate.
End User:
Procurement authority structures diverge sharply across customer types, with commercial airlines centralizing fleet-wide avionics decisions while military services fragment procurement across platform-specific program offices.
- Commercial Aircraft:Scheduled passenger and cargo operators operating under FAA Part 121 and EASA Part-CAT regulations. Narrow-body fleet renewal at IndiGo, Air India, and Southwest Airlines is concentrating demand for integrated avionics with GAGAN and WAAS augmentation compatibility.
- Military Aircraft:Combat and transport platforms requiring M-code GPS receivers with anti-spoofing and electromagnetic hardening. NATO member states including Germany, France, and Poland are modernizing fighter navigation suites through the European Defence Fund procurement mechanisms.
- Drones:Uncrewed aerial systems spanning tactical military platforms and commercial beyond-visual-line-of-sight operations.
- Civil Aviation:General aviation and business jet operators under Part 91 and Part 135 regulations.
Commercial Aircraft anchors the volume base while Drones climbs the fastest as urban air mobility certification pathways mature.
Deployment:
Capital intensity thresholds separate deployment modes, with Embedded Systems requiring upfront hardware qualification while Cloud-Based alternatives shift costs to recurring operational expenditure.
- On-Premise:Airline-hosted server installations for flight planning and performance optimization. Legacy carriers with substantial IT infrastructure investments including British Airways and Qantas maintain these deployments for data sovereignty and latency-sensitive operations.
- Cloud-Based:SaaS-delivered navigation database subscriptions and 4D trajectory optimization. Low-cost carriers such as Ryanair and Spirit Airlines are adopting these models to eliminate data center capital expenditure and enable real-time fleet synchronization.
- Hybrid Solutions:Architectures combining edge avionics processing with cloud-based analytics.
- Embedded Systems:Certifiable software loaded directly onto line-replaceable units with DO-178C Level A assurance.
Embedded Systems anchors the volume base while Cloud-Based deployment expands most quickly among new-entrant airlines.
Technology:
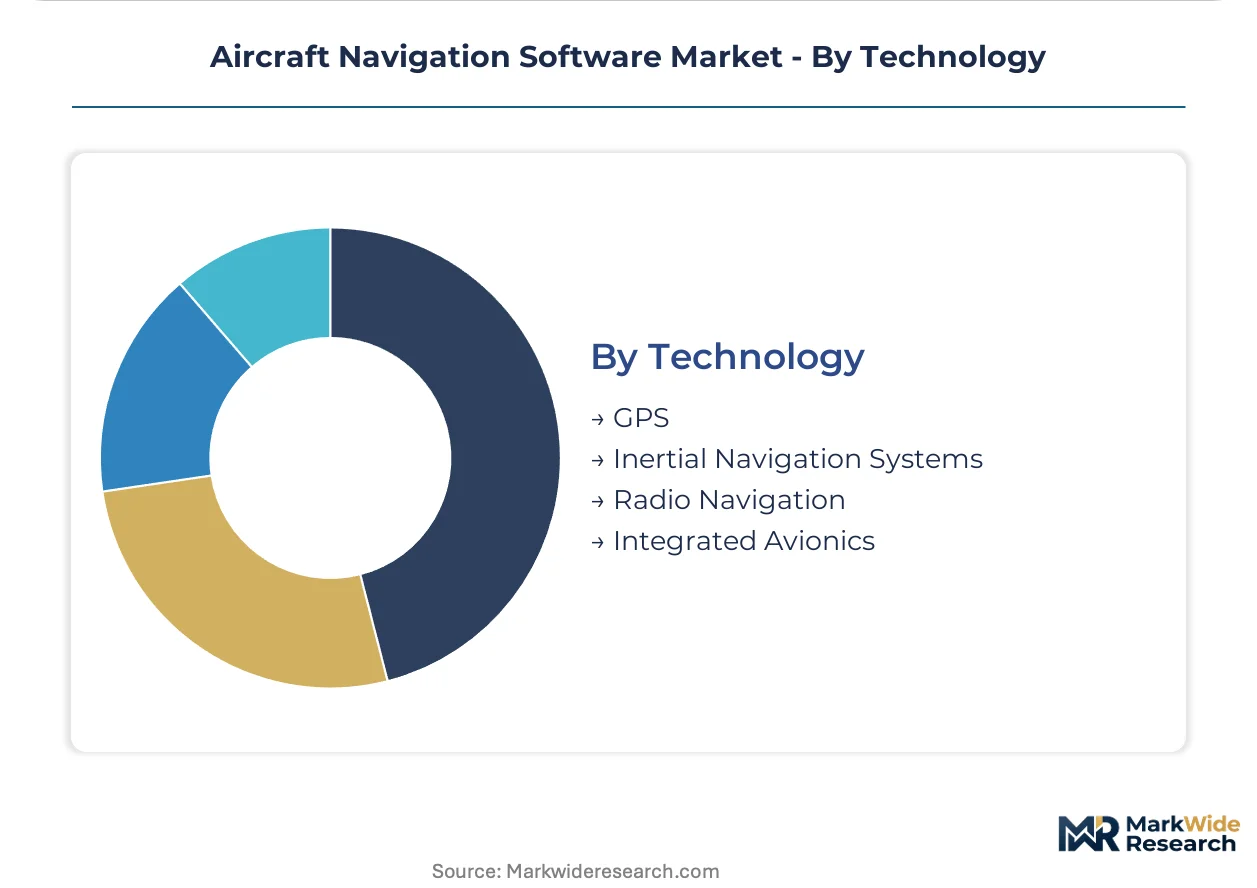
Sensor fusion architectures are displacing single-source navigation dependencies, with Integrated Avionics commanding premium pricing for redundancy management while standalone GPS commoditizes.
- GPS:Satellite-based positioning using L1/L2/L5 frequencies with WAAS, EGNOS, and GAGAN augmentation. Commercial aviation dependency on these signals has intensified as VOR ground infrastructure decommissioning accelerates under FAA NextGen and ESES programs.
- Inertial Navigation Systems:Self-contained position computation using ring laser gyroscopes and accelerometers without external signal dependency. Military platforms operating in GPS-denied environments including submarine-launched aircraft and electronic warfare variants require these systems for mission continuity.
- Radio Navigation:VOR, DME, and ILS ground-based signal reception for approach guidance.
- Integrated Avionics:Multi-sensor fusion architectures combining GPS, inertial, and radio navigation with synthetic vision.
GPS anchors the volume base while Integrated Avionics shows the steepest expansion trajectory as synthetic vision mandates proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. European carriers resist hardware refresh cycles due to fragmented certification costs, while Indian airlines absorb premium pricing for integrated avionics to secure GAGAN compatibility. Military procurement in NATO states shows the least elasticity, prioritizing jam-resistant capabilities over unit economics.
United States
Delta, United, and American Airlines are accelerating narrow-body retrofits to meet FAA NextGen trajectory-based operations deadlines. The FAA mandates Performance-Based Navigation equipage for optimal routing access. Honeywell's Phoenix engineering centers anchor R&D intensity for integrated avionics suites serving these carrier programs.
Germany
Lufthansa and Air France-KLM are migrating flight planning workloads to cloud-native architectures, eliminating on-premise server capital expenditure. EASA CS-25 airworthiness standards shape certification timelines for new navigation software entrants. NAVBLUE leverages its Airbus heritage to dominate airline flight planning services across German and broader European operations.
China
Commercial airlines face pressure to integrate BeiDou augmentation alongside GPS for domestic airspace operations. GB standards for BeiDou integration may fragment avionics certification into competing regional ecosystems. eVTOL developers in dense metropolitan corridors are procuring certifiable navigation stacks for autonomous passenger operations.
India
IndiGo and Air India combined orders for narrow-body aircraft create concentrated demand for integrated avionics with indigenous GAGAN augmentation compatibility. The country's national aviation regulator enforces equipage standards aligned with ICAO frameworks. Bengaluru and Hyderabad host emerging avionics integration facilities serving these fleet expansion programs.
France
Thales Group anchors military navigation contracts with NATO members while competing in civil flight management systems. The EU AI Act introduces algorithmic transparency obligations for machine-learning-based flight path optimization tools. Toulouse's aerospace cluster concentrates avionics engineering talent serving both defense and commercial navigation programs.
Aircraft Navigation Software Market Vendor Landscape
Capability concentration sits with defense-heritage specialists possessing DO-178C certification expertise; scale advantage sits with diversified industrial conglomerates leveraging cross-divisional R&D budgets. The market structures around three archetypes: avionics-integrated conglomerates, flight planning service specialists, and defense-focused navigation hardware providers. Competitive moves center on cloud-native platform migration and direct airline data licensing relationships that bypass OEM intermediaries.
Among aerospace-integrated conglomerates, Honeywell International Inc. and Thales Group occupy positions spanning civil and military navigation domains. NAVBLUE exemplifies the flight planning service specialist archetype with airline heritage advantages. Garmin Ltd. represents the diversified electronics fabricator segment with civil aviation positioning. These three anchors illustrate the competitive tension between embedded systems expertise and subscription-based service expansion.
| Leading Market Players |
|---|
| NAVBLUE |
| Garmin Ltd. |
| Honeywell International Inc. |
| Lufthansa Systems |
| Northrop Grumman Corporation |
| Thales Group |
| Jeppesen |
| Collins Aerospace |
| RTX Corporation |
| Others |
Supply Flow & Price Mechanics
Trans-Pacific air freight corridors connecting Taiwan's semiconductor foundries to Phoenix and Toulouse engineering centers concentrate cost dynamics for radiation-hardened GPS receiver ASICs. This logistics concentration amplifies price differentiation between military-grade M-code units and commercial alternatives while forcing avionics OEMs to absorb premium inventory carrying costs.
Pricing Analysis
Aftermarket subscription revenue for terrain database refreshes and flight data updates now drives lifetime value in aircraft navigation software. Three-tier pricing structure across DO-178C Level A certified, Level B qualified, and uncertified commercial tiers separates military programs from airline retrofits and general aviation installations. Pricing pressure stems from cloud-native flight planning displacing perpetual license models, compressing upfront recognition. Low-cost carriers exhibit highest price sensitivity, while NATO defense procurement shows minimal elasticity for anti-spoofing capabilities.
Supply Chain Analysis
Single-source vulnerability for radiation-hardened GPS receiver production in Taiwan dominates supply risk exposure for military navigation hardware programs. Component sourcing draws from Taiwan for ASIC fabrication, the United States for inertial reference unit assembly, and France for integrated avionics integration. Semiconductor supply concentration creates procurement bottlenecks for DO-178C Level A certification timelines. Distribution runs through OEM avionics suites, direct airline licensing relationships, and defense contractor prime systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of software verification engineers with DO-178C Level A certification experience constrains development velocity and elevates compensation premiums across the competitive landscape. This talent gap shapes strategic positioning for every participant category.
For Market Incumbents: Build certification moats by expanding captive training pipelines for DO-178C Level A engineers and securing exclusive relationships with FAA-designated engineering representatives. Acquire cloud-native flight planning specialists before subscription revenue models commoditize traditional hardware margins. Prioritize backward integration into terrain database compilation to capture recurring service revenue bypassed by NAVBLUE and Jeppesen direct licensing. For New Entrants and Emerging Players: Uncrewed aerial system navigation stacks for German and Chinese urban air mobility corridors represent the most penetrable entry point before eVTOL certification pathways mature. Target Indian fleet expansion programs requiring GAGAN-compatible integrated avionics where indigenous integration capabilities remain underdeveloped. Lead with SaaS-delivered 4D trajectory optimization to circumvent DO-178C hardware certification burdens entirely. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors defense-heritage specialists with embedded DO-178C certification infrastructure over pure-play software vendors facing compliance barriers. Long-term viability rests on dual-use technology crossover potential between military jam-resistant capabilities and commercial synthetic vision mandates. Watch for FAA NextGen deadline acceleration as the inflection signal compressing retrofit timelines and concentrating demand.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Migration | SaaS delivery eliminates airline data center capex while enabling real-time fleet synchronization across Delta and United networks. |
| Direct Data Licensing Relationships | Bypassing OEM markup structures allows Lufthansa and Delta to negotiate terrain database subscriptions independently. |
| DO-178C Certification Investment | Level A assurance capabilities command 35-50% salary premiums and extend competitive moats against new entrants. |
| Backward Integration into ASIC Design | Captive supply of radiation-hardened GPS receivers mitigates Taiwan foundry concentration risk for military programs. |
| Urban Air Mobility Navigation Stack Development | eVTOL certification pathways in Germany and China create first-mover positioning before regulatory standards solidify. |
Methodological Framework
A standing panel of flight management system engineering directors, airline fleet procurement managers, FAA certification specialists, and defense program office leads provided ongoing calibration across primary fieldwork. Secondary validation drew from FAA NextGen implementation reports, EASA CS-25 airworthiness directives, EU AI Act regulatory filings, and ICAO harmonization documentation. Bottom-up triangulation against airline retrofit announcements and top-down reconciliation with avionics OEM revenue disclosures anchored volume estimates.
Scenario-bracketing around FAA mandate acceleration, EASA algorithmic transparency enforcement, and BeiDou integration fragmentation in China bounded uncertainty ranges across the projection horizon. Segmentation dimensions modeled include product type, end-user platform, deployment architecture, and sensor technology fusion level. CAGRs derived from fitted growth curves against historical equipage patterns, with specific inputs for narrow-body fleet renewal schedules and military modernization program phasing.
Macroeconomic conditions sit as an overlay; deviation in semiconductor capital expenditure cycles, defense budget authorization trajectories, or airline fleet financing availability would shift the trajectory. Forecasts reflect documented assumptions regarding certification timeline compression and cloud adoption elasticity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Navigation and Communication
Middle-East and Africa Air Traffic Management Market
Aircraft Navigation and Communication
Global Air Traffic Control Equipment Market
Aircraft Navigation and Communication
Europe Air Traffic Management Market
Aircraft Navigation and Communication
Aviation Weather Radar Market
Aircraft Navigation and Communication
Helicopter Meteorological Software Market
Aircraft Navigation and Communication
Aircraft Interface Device Market
Aircraft Navigation and Communication
Defense Advanced GPS Receiver (DAGR) Market
Aircraft Navigation and Communication
Global Drone Navigation System Market
Aircraft Navigation and Communication
Ultra Short Base Line Positioning System Market
Aircraft Navigation and Communication
Ground to Air on-Board Connectivity Market
Aircraft Navigation and Communication
Europe Inertial Systems Market
Aircraft Navigation and Communication
Connected Aircraft Market
Aircraft Navigation and Communication
Aircraft Turn Coordinator Market
Aircraft Navigation and Communication
Airborne High Frequency Radio Market
Aircraft Navigation and Communication
Digital Radiosonde Market
Aircraft Navigation and Communication
5G in Aviation Market