
 South Korea Satellite-Based Earth Observation Market | 2026-2036
South Korea Satellite-Based Earth Observation Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Satellite-Based Earth Observation Market Insights
The gap between premium military-grade observation services and commodity commercial imagery is expanding as defense budgets prioritize sovereign sensor capabilities over foreign data subscriptions. Korea Aerospace Industries Ltd. leverages its government-backed position to anchor domestic launch and satellite integration workflows. Hanwha Systems competes through vertical control over ground segment electronics and command infrastructure. Satrec Initiative Co., Ltd. specializes in compact optical payloads that occupy the export-oriented mid-tier segment for emerging space nations.
South Korea satellite-based earth observation encompasses the acquisition, processing, and distribution of geospatial intelligence from orbiting platforms carrying electro-optical, synthetic aperture radar, or multi-spectral instruments operating at resolutions from sub-meter to tens of meters. These systems serve defense reconnaissance, agricultural yield prediction, urban land-use planning, and disaster response coordination through standardized data delivery protocols. Optical satellites lead current revenue contribution due to mature domestic manufacturing chains and established defense procurement pathways, while radar satellites represent the fastest-expanding category as all-weather, day-night imaging becomes mandatory for maritime domain awareness and peninsula monitoring. Multi-spectral satellites concentrate margin pools in precision agriculture analytics where SI Imaging Services and Geofocus Co., Ltd. bundle imagery with crop health algorithms.
The Ministry of Science and ICT and the Korea Forest Service shape market access through domestic launch quotas and national mapping standards that preference locally registered data processors. MFDS guidelines on geospatial data security classification restrict foreign cloud-based analytics from handling sensitive infrastructure imagery, redirecting procurement toward on-premise solutions. The national space development plan and KARI licensing requirements for commercial remote sensing operations further tighten operational parameters for non-Korean operators. Stakeholders must weigh sovereign data custody obligations against the cost penalties of bypassing established international satellite constellations.
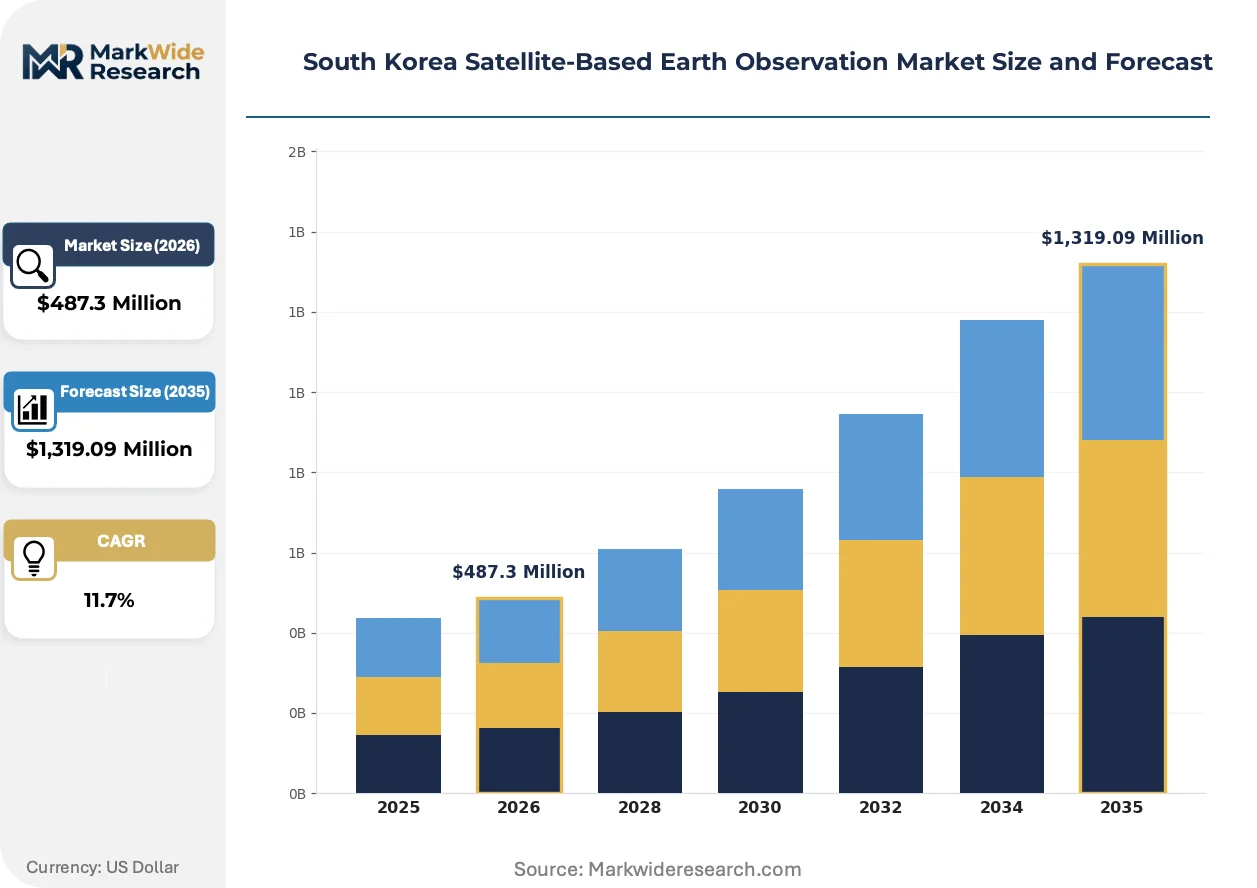
Market Dynamics
Sovereign sensor mandates from the Ministry of Science and ICT are compressing procurement timelines for domestic satellite operators while tightening operational constraints on foreign imagery providers seeking Korean market access.
Growth Catalysts
- MFDS Data Localization Directives:The Ministry of Food and Drug Safety's geospatial security classification rules redirect sensitive infrastructure imagery processing toward on-premise domestic solutions, creating captive demand for locally registered operators.
- Synthetic Aperture Radar Uptake:Defense reconnaissance requirements for all-weather, day-night peninsula monitoring are accelerating procurement of SAR payloads for maritime domain awareness and border surveillance applications.
- Gwangju-Jeonnam Cluster Concentration:Deepening payload integration capabilities in Korea's aerospace manufacturing belt are shortening supply chains for electro-optical instrument assembly and test operations.
Market Restraints
- Launch Capacity Bottlenecks:Limited domestic heavy-lift vehicle availability forces reliance on foreign launch providers, creating schedule risk and foreign exchange exposure for constellation deployment programs.
- Optical Weather Dependency:Persistent cloud cover over the Korean peninsula degrades electro-optical satellite utility for agricultural monitoring and disaster response, necessitating costly radar backup systems.
- KARI Licensing Friction:The Korea Aerospace Research Institute's commercial remote sensing operation permits impose payload resolution caps and orbital slot coordination requirements that extend market entry timelines for non-Korean operators.
Strategic Opportunities
- Precision Agriculture Analytics Bundling:Crop health algorithm integration with multi-spectral imagery creates sticky subscription revenue streams among Jeolla Province rice and greenhouse operators.
- Urban Digital Twin Convergence:Municipal land-use planning departments in Seoul and Busan are fusing satellite-derived elevation data with IoT sensor networks for infrastructure stress monitoring.
- Export-Oriented Compact Payloads:Emerging space nations in Southeast Asia and the Middle East present demand for proven small-satellite optical instruments with established flight heritage.
Industry Challenges
- RF Spectrum Coordination Complexity:Downlink frequency allocation negotiations with the Korea Communications Commission and international ITU filings create deployment delays for commercial operators.
- Ground Segment Integration Talent Scarcity:Shortage of antenna control software engineers and geospatial data pipeline architects constrains operational scaling for domestic satellite service providers.
- Legacy Defense Procurement Cycles:Multi-year budget authorization timelines for reconnaissance satellite programs mismatch commercial satellite technology refresh rates, creating capability obsolescence risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Satellite-Based Earth Observation Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,319.09 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Optical Satellites, Radar Satellites, Multi-Spectral Satellites, Hyperspectral Satellites End User: Agriculture, Urban Planning, Forestry, Disaster Management Application: Climate Monitoring, Environmental Assessment, Mapping, Infrastructure Monitoring Technology: Remote Sensing, Image Processing, GIS, Data Analytics |
| Companies Covered | Korea Aerospace Industries Ltd., Hanwha Systems, Satrec Initiative Co., Ltd., SI Imaging Services, Electro-Metric Technology, Dabeeo Inc., Airbus, Space Si, Geofocus Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Satellite-Based Earth Observation Market Trends and Innovations
Payload miniaturization and on-board processing architectures are compressing the traditional ground-segment value chain, while regulatory data custody requirements reshape competitive positioning between sovereign and commercial operators.
Synthetic aperture radar technology is consolidating its position as the mandatory imaging modality for defense and maritime applications where electro-optical systems fail. The Korea Forest Service and Coast Guard are accelerating SAR procurement for wildfire damage assessment and illegal fishing detection. This technology shift is compressing margins for pure-play optical satellite operators while rewarding vertically integrated radar payload manufacturers.
KARI licensing requirements for commercial remote sensing operations now mandate encrypted downlink protocols and domestic ground station custody for sub-meter resolution imagery. These rules force foreign constellation operators to establish Korean-registered data processing entities or forfeit defense-adjacent contracts. Domestic satellite service providers capture margin pools previously flowing to international analytics platforms.
Subscription-based imagery access is displacing per-scene procurement across agricultural and insurance verticals. SI Imaging Services and domestic competitors now offer annual crop monitoring packages to cooperatives in Jeolla and Gyeongsang provinces, replacing spot purchases. This model shift concentrates buyer power among large agricultural associations while squeezing smaller regional data resellers.
South Korea Satellite-Based Earth Observation Market Segmentation
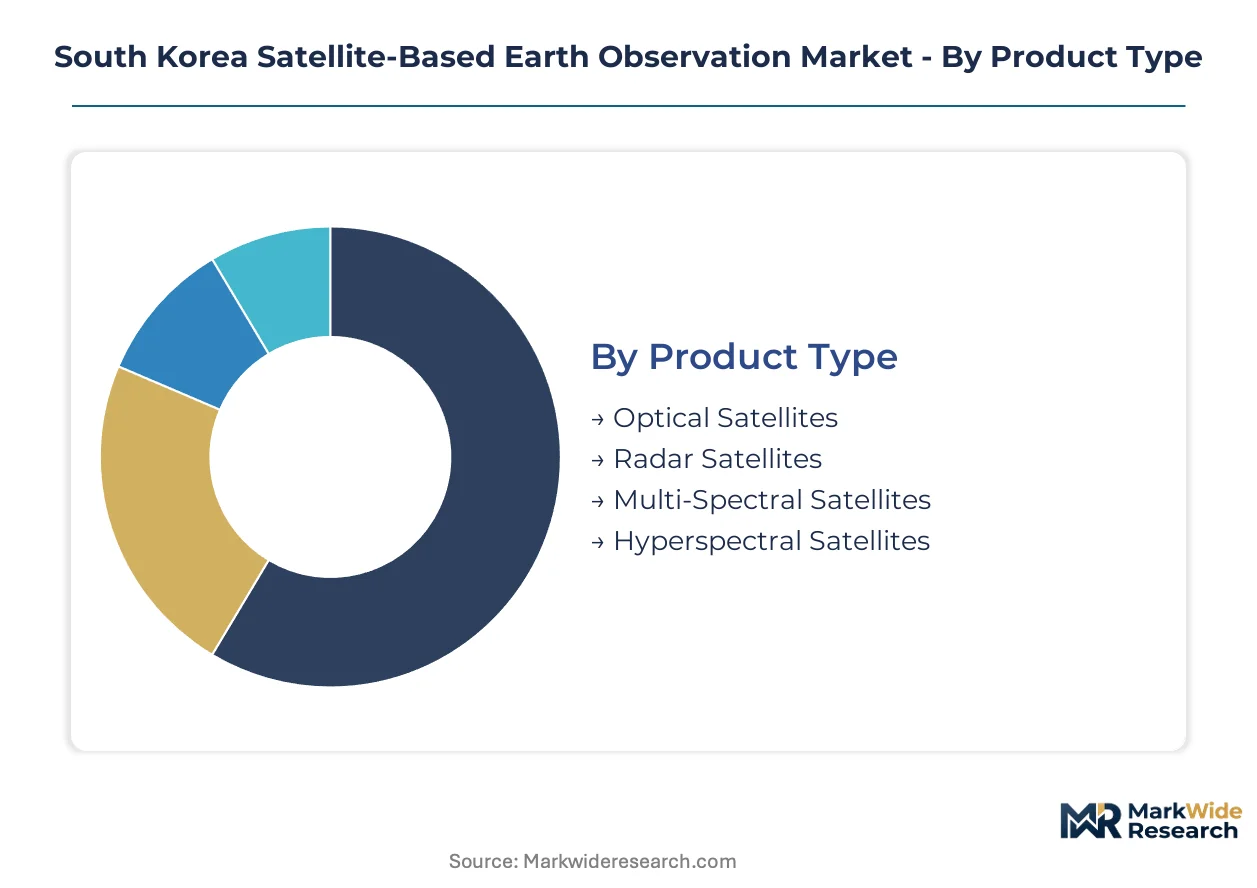
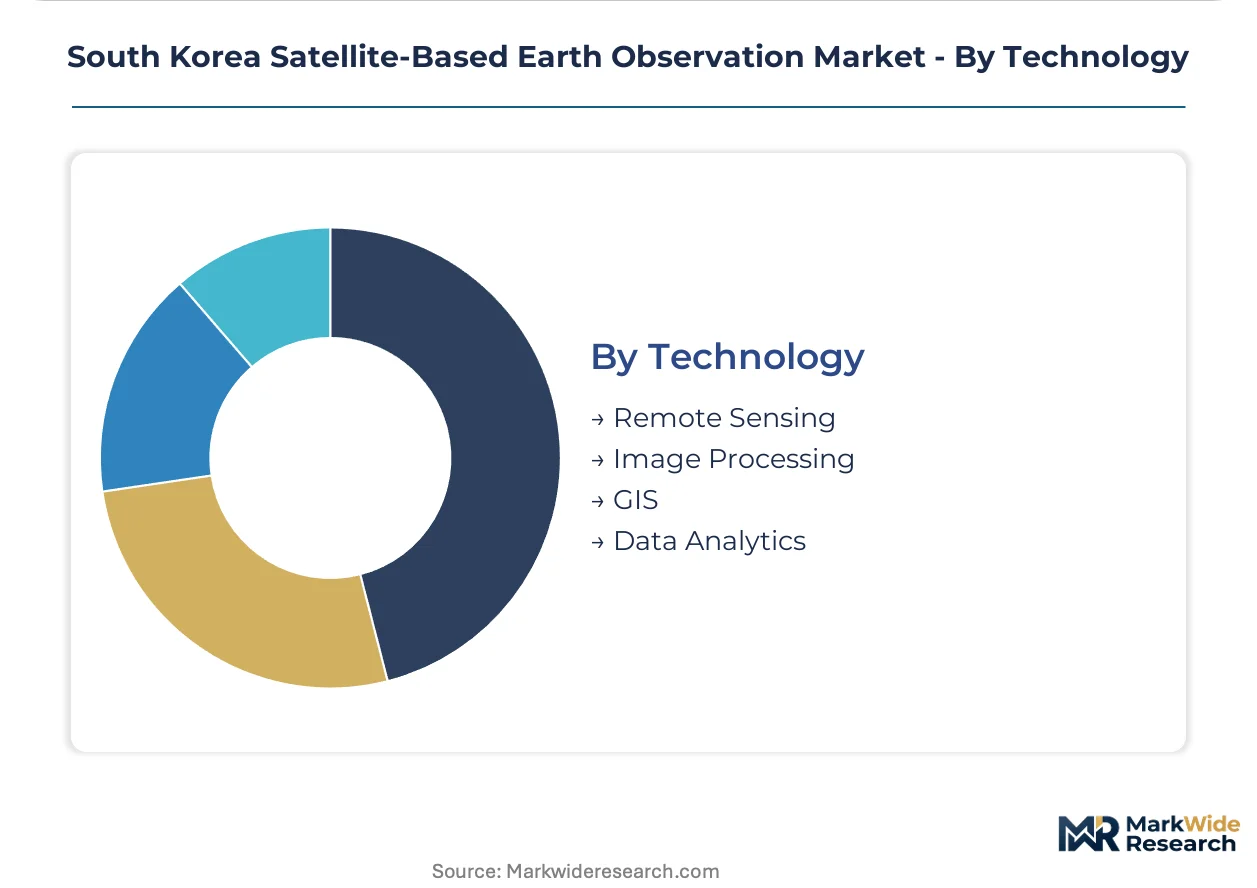
Segmentation reveals how procurement priorities diverge across South Korea's satellite earth observation landscape. Defense reconnaissance demands sovereign radar capabilities while agricultural users prioritize cost-efficient multi-spectral subscriptions. Understanding these divides clarifies where technology investments concentrate versus where commoditization pressures mount.
Product Type:
Upgrade cycles differentiate procurement patterns across sensor modalities, with defense agencies replacing electro-optical systems faster than commercial operators refresh agricultural platforms.
- Optical Satellites:Electro-optical payloads capture visible and near-infrared spectrum imagery at resolutions from sub-meter to tens of meters. Demand concentrates in Gwangju-Jeonnam aerospace clusters where Korea Aerospace Industries Ltd. anchors domestic manufacturing chains for defense reconnaissance programs. Persistent cloud cover over the peninsula degrades operational utility, forcing costly radar backup procurement.
- Radar Satellites:Synthetic aperture radar instruments penetrate cloud cover and darkness using microwave illumination. Defense reconnaissance requirements for all-weather peninsula monitoring drive procurement acceleration through the Ministry of Science and ICT sovereign sensor mandates. Maritime domain awareness and border surveillance applications mandate day-night imaging unavailable from electro-optical alternatives.
- Multi-Spectral Satellites:Instruments capturing discrete wavelength bands enable vegetation health and moisture detection. SI Imaging Services bundles crop monitoring subscriptions for Jeolla Province rice cooperatives.
- Hyperspectral Satellites:Continuous spectrum sensors detect subtle material compositions for mineral exploration and environmental contamination tracking. Korea Forest Service pilots wildfire damage assessment programs.
Volume placements concentrate in Optical Satellites; the faster expansion belongs to Radar Satellites.
End User:
Cost tier stratification separates premium defense budgets from subscription-constrained agricultural associations.
- Agriculture:Precision farming operations in Jeolla and Gyeongsang provinces subscribe to annual crop health monitoring packages. Multi-spectral imagery combined with yield prediction algorithms displaces per-scene procurement among greenhouse operators and rice cooperatives.
- Urban Planning:Seoul and Busan municipal departments fuse satellite-derived elevation data with IoT sensor networks for infrastructure stress monitoring. Digital twin convergence creates recurring demand for updated surface models.
- Forestry:Korea Forest Service procurement concentrates on wildfire damage assessment and illegal logging detection. SAR uptake accelerates for smoke-penetrating fire perimeter mapping.
- Disaster Management:Coast Guard and emergency response agencies require all-weather imagery for flood and earthquake damage rapid assessment. MFDS data localization rules redirect processing toward on-premise domestic solutions.
Revenue concentration sits with Agriculture; steepest expansion trajectory belongs to Urban Planning.
Application:
Customer type segmentation separates sovereign security applications from commercial analytics services.
- Climate Monitoring:Long-term atmospheric and oceanic pattern tracking supports national adaptation planning. KARI licensing requirements mandate encrypted downlink protocols for sub-meter resolution climate data.
- Environmental Assessment:Industrial contamination and ecosystem health evaluation drives hyperspectral instrument demand. MFDS geospatial security classification restricts foreign cloud-based analytics from sensitive infrastructure imagery.
- Mapping:National cadastral updates and topographic revision programs sustain optical satellite procurement cycles. Korea Forest Service standards preference locally registered data processors.
- Infrastructure Monitoring:Transportation corridor and utility network surveillance requires frequent revisit capabilities. Defense-adjacent contracts flow exclusively to Korean-registered data processing entities under KARI commercial remote sensing rules.
Procurement volume clusters in Mapping; Infrastructure Monitoring climbs the fastest.
Technology:
Supply concentration shapes competitive positioning across the value chain from raw data capture to derived intelligence.
- Remote Sensing:Orbital platform and sensor hardware manufacturing anchors in Gwangju-Jeonnam aerospace clusters. Hanwha Systems controls ground segment electronics and command infrastructure.
- Image Processing:On-board processing architectures compress traditional ground-segment value chains. Payload miniaturization enables compact satellite platforms for export markets.
- GIS:Geospatial information system integration fuses satellite-derived layers with cadastral and demographic databases. Urban digital twin convergence accelerates municipal demand.
- Data Analytics:Algorithm-driven crop health and infrastructure stress prediction creates sticky subscription revenue. Talent scarcity for geospatial data pipeline architects constrains operational scaling.
Capability investment concentrates in Remote Sensing; Data Analytics gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gwangju-Jeonnam anchors South Korea's satellite earth observation manufacturing density, with payload integration facilities clustering along the Honam Expressway corridor. Defense procurement timelines and MFDS data localization mandates are redistributing operational activity across five sub-national regions.
Seoul Capital Area
Defense reconnaissance procurement and KARI licensing administration concentrate demand in Seoul and Sejong. The Ministry of Science and ICT directs sovereign sensor mandates from government complexes in Gwacheon. Pangyo Techno Valley hosts ground segment software developers serving encrypted downlink protocol requirements.
Busan-Ulsan
Maritime domain awareness applications drive Coast Guard SAR procurement along the southeastern coast. The Korea Coast Guard headquarters in Busan coordinates illegal fishing detection programs. Ulsan's shipbuilding heritage feeds antenna manufacturing for vessel-mounted satellite terminals.
Daegu-Gyeongbuk
Precision agriculture analytics subscriptions concentrate among greenhouse operators in Gyeongsang provinces. The Korea Forest Service operates wildfire monitoring stations from Daegu. Pohang's steel industry corridor supplies radar payload component fabrication.
Daejeon-Sejong
KARI headquarters and satellite control infrastructure dominate the central region's institutional demand. The Korea Aerospace Research Institute manages commercial remote sensing permits from its Daejeon campus. Sejong's administrative city status attracts geospatial data processing registrations.
Gwangju-Honam
Electro-optical instrument assembly and test operations deepen in Korea's southwestern aerospace belt. Korea Aerospace Industries Ltd. maintains satellite integration facilities in Sacheon. The Gwangju Institute of Science and Technology supplies photonics engineers for compact payload development.
South Korea Satellite-Based Earth Observation Market Competitive Landscape
Premium-margin players sit above commodity-margin players across sovereign sensor capability depth. Defense-adjacent contracts flow exclusively to domestic-registered entities with KARI licensing and encrypted downlink infrastructure. Three archetypes dominate: government-backed prime contractors controlling launch and integration workflows, vertically integrated electronics suppliers commanding ground segment infrastructure, and compact payload specialists targeting export markets. Competitive moves concentrate on backward integration into sensor manufacturing and strategic partnerships with municipal digital twin programs.
Within the government-backed prime tier, Korea Aerospace Industries Ltd. and Hanwha Systems exemplify divergent strategic positions. Satrec Initiative Co., Ltd. occupies the export-oriented compact payload segment. These three entities represent distinct capability concentrations: KARI-licensed integration authority, ground segment electronics control, and small-satellite optical heritage for emerging space nations.
| Leading Market Players |
|---|
| Korea Aerospace Industries Ltd. |
| Hanwha Systems |
| Satrec Initiative Co., Ltd. |
| SI Imaging Services |
| Electro-Metric Technology |
| Dabeeo Inc. |
| Airbus |
| Space Si |
| Geofocus Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Defense reconnaissance procurement programs anchor South Korea's satellite earth observation pricing structure, with sovereign sensor mandates from the Ministry of Science and ICT compressing procurement timelines while elevating value-based contract premiums for KARI-licensed domestic operators.
Pricing Analysis
Outcome-linked pricing for maritime domain awareness and border surveillance contracts sets the value anchor, with defense agencies paying premiums for guaranteed all-weather SAR availability. Subscription-based crop health monitoring packages for Jeolla Province agricultural cooperatives operate on throughput-scaled tiers. Cost compression in commercial optical imagery stems from foreign constellation oversupply. Agricultural associations exhibit highest price sensitivity; defense reconnaissance buyers prioritize sovereign custody over unit cost.
Supply Chain Analysis
KARI licensing and MFDS data security classification act as qualification gates for ground segment participation, restricting foreign cloud-based analytics from sensitive infrastructure contracts. Payload integration draws from South Korea's Gwangju-Jeonnam aerospace belt, with component sourcing tethered to Japan and the United States for precision optics and radar electronics. Single-source vulnerability concentrates in domestic heavy-lift launch capacity. Distribution runs through Korea Aerospace Industries Ltd. integration facilities and Hanwha Systems ground infrastructure deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Korea's satellite earth observation market is becoming a vertical-integration race, with players pursuing backward control over sensor manufacturing to capture defense procurement premiums and satisfy data localization mandates.
For Market Incumbents: Deploy sovereign sensor certification investments to lock out foreign constellation operators from defense-adjacent contracts. Anchor payload integration workflows in Gwangju-Jeonnam facilities to shorten supply chains for electro-optical instrument assembly. The threat of foreign SAR constellation price erosion demands accelerated domestic radar payload manufacturing scale-up. For New Entrants and Emerging Players: The premium-to-economy pricing gap in precision agriculture analytics offers entry leverage for algorithm-driven crop health subscription providers. White-space concentrates among greenhouse operators in Gyeongsang provinces underserved by bundled monitoring packages. A channel partnership with agricultural cooperatives bypasses direct competition with SI Imaging Services' established rice paddy coverage. For Investors and Strategic Acquirers: The window for entry favors compact payload specialists with established flight heritage in Southeast Asian export markets. Long-term viability hinges on sovereign data custody tailwinds persisting through successive national space development plan revisions. Acquisition targets should demonstrate KARI licensing progress and encrypted downlink infrastructure deployment. The signal to watch is MFDS geospatial security classification expansion beyond current infrastructure imagery categories.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into SAR Payload Manufacturing | Captures defense reconnaissance premiums while satisfying Ministry of Science and ICT sovereign sensor mandates. |
| Strategic Partnership with Municipal Digital Twin Programs | Locks recurring elevation data demand from Seoul and Busan infrastructure stress monitoring deployments. |
| Acquisition of Compact Optical Payload Specialist | Accelerates export market penetration among emerging space nations in Southeast Asia and Middle East. |
| Domestic Ground Station Infrastructure Expansion | Secures KARI licensing compliance for sub-meter resolution imagery processing under encrypted downlink protocols. |
| Precision Agriculture Analytics Platform Integration | Creates sticky subscription revenue among Jeolla Province rice cooperatives displacing per-scene procurement. |
Research Methodology
KARI licensing documentation, MFDS geospatial security classification guidelines, and national space development plan white papers formed the secondary backbone. Primary interviews with satellite integration engineers at Korea Aerospace Industries Ltd., ground segment software architects at Hanwha Systems, and procurement officers at the Korea Forest Service validated demand assumptions. Customs records for electro-optical instrument imports and defense budget authorization disclosures provided import parity checks. Bottom-up capacity assessments across Gwangju-Jeonnam aerospace facilities were triangulated against top-down market sizing from subscription revenue disclosures.
Historical trendline analysis of defense reconnaissance satellite procurement cycles and commercial agricultural imagery subscription growth established baseline momentum parameters. The analytical framework segmented by sensor modality, end-use vertical, and application type across the projection horizon. CAGRs were derived from elasticity modeling against sovereign sensor mandate implementation intensity and foreign constellation market access restrictions. Forecast inputs included KARI licensing queue depth and Gwangju-Jeonnam payload integration capacity expansion timelines.
Inputs from KARI commercial remote sensing permit databases and Korea Forest Service procurement records were available through the study window; gaps in classified defense reconnaissance budget line-item detail introduce uncertainty bands around military-grade SAR demand projections. Forecasts reflect assumptions about MFDS data localization enforcement consistency and domestic heavy-lift launch vehicle development progress. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Satellite Communication Subsystem Market
Satellite
Asia-Pacific Remote Sensing Satellites Market
Satellite
Asia-Pacific Satellite Attitude and Orbit Control System Market
Satellite
Global Satellite Based Earth Observation Market
Satellite
Japan Satellite Connectivity Market
Satellite
Satellite Market
Satellite
Healthcare Satellite Connectivity Market
Satellite
Advanced Satellite Market
Satellite
Germany Satellite Imagery Services Market
Satellite
Satellite Services Market
Satellite
UK Satellite Connectivity Market
Satellite
Satellite Operation Service Market
Satellite
United Arab Emirates Satellite-Based Earth Observation Market
Satellite
Germany Satellite-Based Earth Observation Market
Satellite
Satellite Imaging Market
Satellite
United States Satellite Communications Market