
 Global Drone Navigation System Market | 2026-2036
Global Drone Navigation System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Drone Navigation System Market Analysis
Silicon carbide is broadening power efficiency in drone navigation inverters against legacy silicon substrates. DJI leverages captive semiconductor sourcing to sustain cost leadership across consumer and enterprise tiers. Skydio specializes in AI-native flight autonomy, while AeroVironment anchors military-grade navigation resilience through hardened GPS-denied architectures.
Drone navigation systems integrate inertial measurement units, multi-constellation GNSS receivers, and real-time kinematic correction to achieve centimeter-level positional accuracy during autonomous flight. Agricultural Monitoring applications command the deepest software customization cycles as variable-rate spraying demands sub-meter repeatability. VTOL form factors attract the fastest hardware refresh rates because hybrid lift configurations stress sensor fusion algorithms beyond conventional multirotor baselines.
The FAA enforces Remote ID broadcast standards that compel retrofit investments across existing US fleets, while EASA's drone regulation framework mandates equivalent electronic conspicuity across European airspace. China's MIIT coordinates GB standard certification for navigation modules, creating divergent compliance burdens for manufacturers serving multiple jurisdictions. Stakeholders must monitor whether emerging beyond-visual-line-of-sight corridors in Australia and Canada force convergence or further fragmentation in certification requirements.
Market Dynamics
The FAA's Remote ID mandate and EASA's equivalent protocols are forcing immediate hardware replacement cycles across commercial fleets, compressing supplier lead times and fragmenting certification pathways.
Growth Catalysts
- Silicon carbide substrates:Power inverters in navigation systems achieve higher thermal efficiency and reduced weight versus legacy silicon, extending flight endurance for agricultural and surveillance missions.
- Precision agriculture in Brazil and Australia:Variable-rate spraying operations require centimeter-level positional accuracy, driving replacement of manual flight controllers with autonomous RTK-GNSS units.
- China's MIIT GB standards:Domestic certification acceleration for navigation modules enables faster product release cycles in Shenzhen and Dongguan manufacturing clusters.
Market Restraints
- GNSS receiver supply concentration:Multi-constellation chipsets depend on a limited supplier base in Taiwan and South Korea, creating vulnerability to geopolitical disruption.
- Dual-use export controls:Military-grade navigation resilience technologies face ITAR and EU dual-use regulation restrictions, limiting cross-border technology transfer.
- IMU sensor cost volatility:MEMS fabrication capacity constraints and rare earth magnetometer dependencies inflate bill-of-materials for mid-tier flight controllers.
Strategic Opportunities
- Beyond-visual-line-of-sight corridors in Australia and Canada:Emerging airspace frameworks for long-range autonomous routes create first-mover positioning for navigation stack providers.
- AI-native sensor fusion:Machine learning-based obstacle avoidance converges with traditional inertial navigation, opening new product tiers for complex urban environments.
- India's PLI scheme for drones:Domestic manufacturing incentives attract navigation system assembly, reducing import dependency for sub-components.
Industry Challenges
- RTK-GNSS certification timelines:Country-specific radio frequency approvals for correction signal receivers delay product launches by six to eighteen months.
- Sensor fusion algorithm talent scarcity:Shortage of embedded systems engineers with simultaneous expertise in Kalman filtering and computer vision constrains R&D velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Drone Navigation System Market |
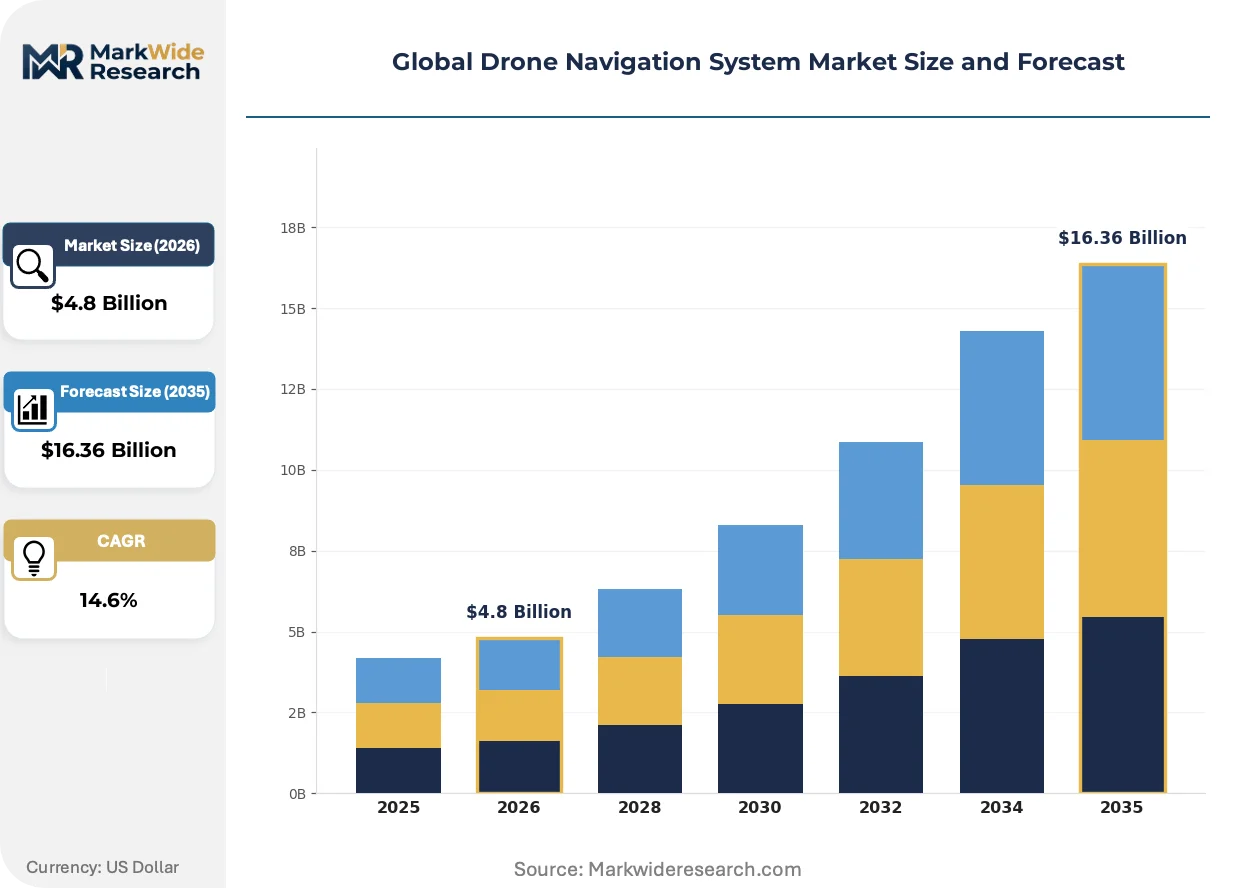
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $16.36 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: GPS, LiDAR, Infrared, Ultrasonic Application: Aerial Surveillance, Agricultural Monitoring, Infrastructure Inspection, Delivery Services End User: Military, Agriculture, Logistics, Construction Form Factor: Fixed-Wing, Quadrotor, Hexacopter, VTOL |
| Companies Covered | Autel Robotics, Draganfly, DJI, JOUAV, Ascent Aerosystems, Skydio, Parrot, Quantum-Systems, AeroVironment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Drone Navigation System Market Emerging Trajectories
Navigation architectures are bifurcating between cost-optimized consumer stacks and hardened enterprise-grade systems, with regulatory mandates accelerating the technical divergence between these tiers.
Silicon carbide power electronics are consolidating their position in high-end navigation inverters. Agricultural drone operators in Australia and Brazil are adopting SiC-based motor controllers to extend flight time per battery cycle. This substrate transition is consolidating supplier relationships around semiconductor foundries with proven wide-bandgap fabrication expertise.
EASA's drone regulation framework mandates electronic conspicuity standards equivalent to FAA Remote ID requirements. European operators must retrofit existing fleets with broadcast-capable navigation modules or face operational restrictions. VTOL manufacturers serving German and French logistics markets are absorbing the steepest compliance costs due to hybrid lift sensor complexity.
After-sales service unbundling is altering procurement patterns for navigation hardware. Large agricultural cooperatives in Brazil are negotiating direct technical support agreements with component suppliers, bypassing traditional distributor maintenance contracts. This disintermediation concentrates most visibly among soybean and sugarcane operators with fleet sizes exceeding fifty units.
Global Drone Navigation System Market Segmentation
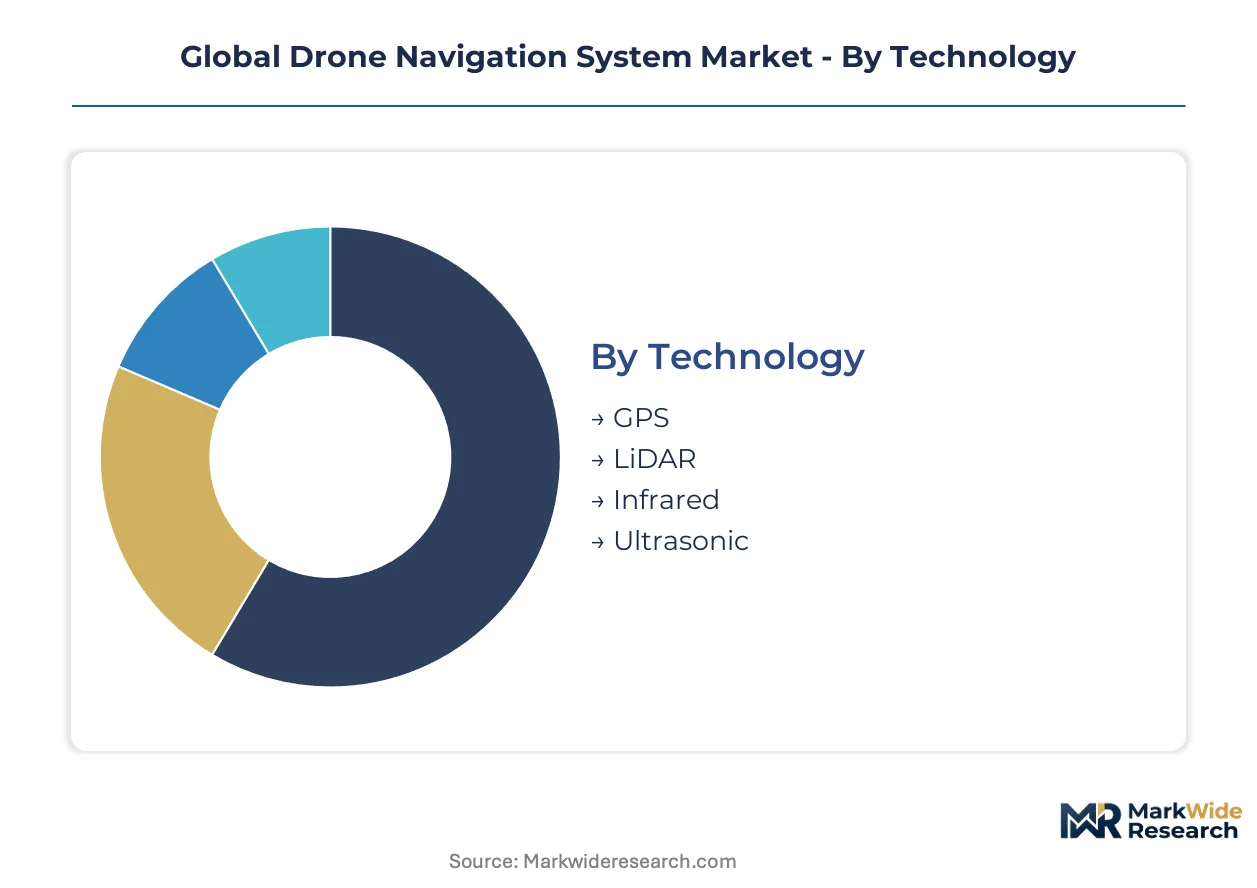
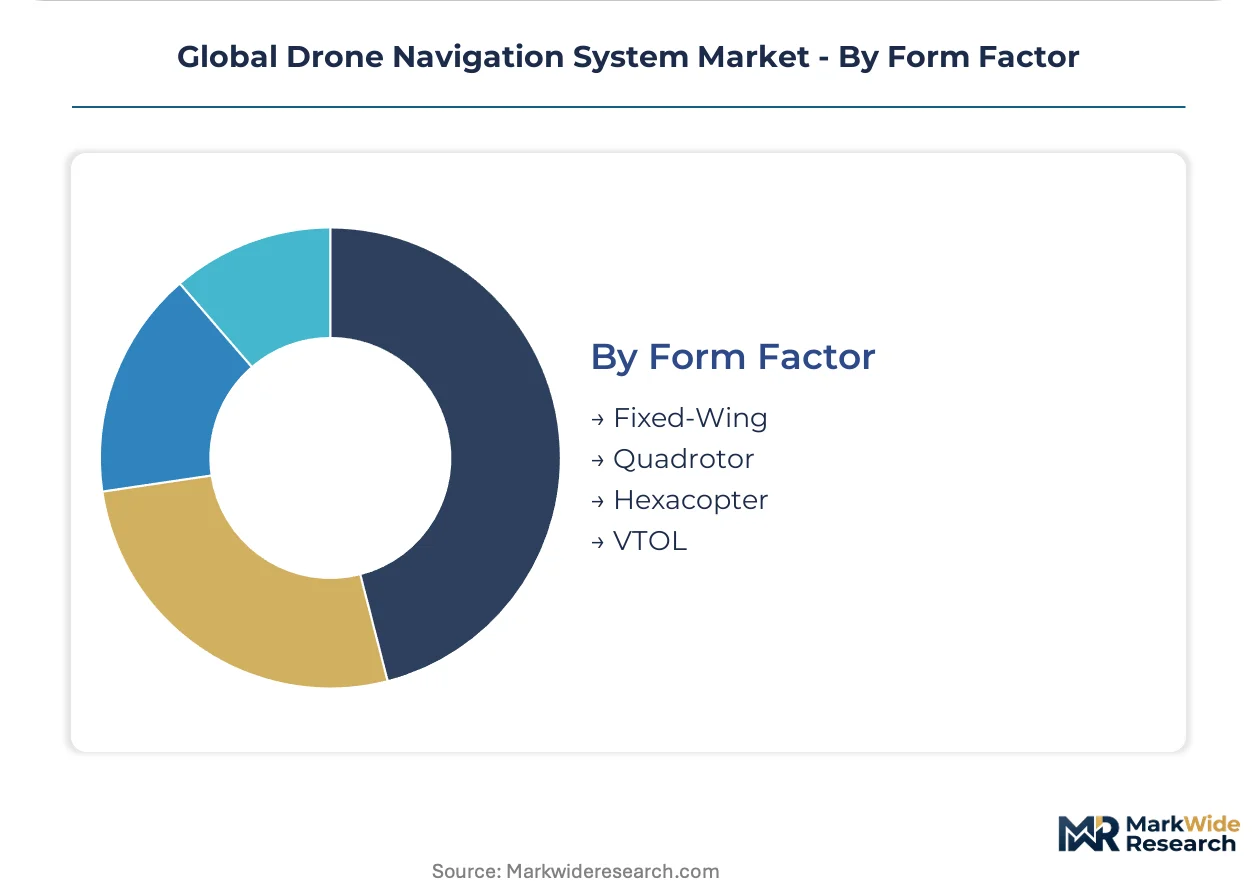
Drone navigation architectures diverge sharply across use cases, with precision agriculture demanding centimeter-level RTK-GNSS integration while military applications prioritize GPS-denied resilience. Form factor selection directly constrains sensor fusion complexity, battery endurance, and regulatory compliance pathways.
Technology:
The customization-vs-standardization spectrum spans from commoditized GPS modules to bespoke LiDAR fusion stacks requiring extensive calibration protocols.
- GPS:Multi-constellation GNSS receivers with real-time kinematic correction dominate commercial agriculture in Brazil and Australia. Variable-rate spraying operations in Mato Grosso soybean belts drive replacement of manual flight controllers with autonomous RTK units.
- LiDAR:3D point-cloud generation enables obstacle avoidance in complex urban corridors where satellite visibility degrades. Logistics operators in Shenzhen's dense manufacturing districts deploy solid-state LiDAR for last-meter delivery precision.
- Infrared:Thermal imaging navigation supports pipeline inspection across Saudi Arabia's desert infrastructure corridors.
- Ultrasonic:Proximity sensing for indoor warehouse automation in German automotive parts distribution centers.
Leading the category by volume: GPS. Growing fastest: LiDAR.
Application:
Cost tier stratification separates capital-intensive infrastructure inspection from high-volume agricultural monitoring deployments.
- Agricultural Monitoring:Sub-meter repeatability requirements for variable-rate chemical application command the deepest software customization cycles. Australian cotton cooperatives negotiate direct technical support agreements with component suppliers, bypassing traditional distributor maintenance contracts.
- Delivery Services:Urban air mobility corridors in Canada and Australia stress-test navigation redundancy for beyond-visual-line-of-sight certification. Hybrid lift configurations demand sensor fusion algorithms beyond conventional multirotor baselines.
- Aerial Surveillance:Border patrol operations along US-Mexico corridors require hardened GPS-denied architectures.
- Infrastructure Inspection:Wind turbine blade assessment in North Sea offshore arrays leverages RTK-GNSS for repeatable flight paths.
Volume concentration: Agricultural Monitoring. Steepest expansion trajectory: Delivery Services.
End User:
Customer type determines procurement authority, with military buyers mandating ITAR-compliant supply chains versus commercial agriculture's price-sensitive fleet purchasing.
- Military:GPS-denied navigation resilience through inertial measurement unit redundancy and celestial backup positioning. US Department of Defense contracts enforce hardened architectures resistant to electronic warfare.
- Agriculture:Fleet operators exceeding fifty units in Brazil's sugarcane belts drive after-sales service unbundling, negotiating direct component supplier relationships.
- Logistics:German and French VTOL manufacturers absorb steepest EASA electronic conspicuity compliance costs.
- Construction:Site surveying accuracy requirements in UAE megaproject developments.
Dominant procurement volume: Agriculture. Fastest certification urgency: Military.
Form Factor:
Supply concentration for MEMS inertial sensors and multi-constellation chipsets disproportionately impacts hybrid lift configurations versus fixed-wing simplicity.
- VTOL:Hybrid lift architectures stress sensor fusion algorithms through transition phases between hover and forward flight. EASA-mandated electronic conspicuity retrofits concentrate cost burdens on German and French logistics fleet operators.
- Quadrotor:Standardized flight controller form factors enable rapid hardware refresh cycles for consumer and prosumer tiers. DJI's captive semiconductor sourcing sustains cost leadership across Shenzhen manufacturing clusters.
- Fixed-Wing:Extended endurance missions for Australian pastoral property monitoring.
- Hexacopter:Redundant motor configurations for critical infrastructure inspection in South Korean smart city deployments.
Highest shipment volume: Quadrotor. Most rapid hardware refresh: VTOL.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen's Qianhai Free Trade Zone concentrates navigation module assembly through preferential tax treatment and bonded logistics infrastructure. Brazil's Mato Grosso agricultural belt and Australia's Queensland cotton regions drive parallel demand for RTK-GNSS precision. Regulatory fragmentation across FAA, EASA, and MIIT jurisdictions forces manufacturers to maintain multiple certification tracks.
United States
Precision agriculture operators in California's Central Valley retrofit fleets with Remote ID-compliant navigation stacks ahead of FAA enforcement deadlines. The FAA mandates broadcast-capable modules for all commercial operations above 250 grams. DJI and Skydio maintain development centers in Silicon Valley and Austin respectively, adapting sensor fusion algorithms for BVLOS corridor trials in North Dakota and Oklahoma.
China
Shenzhen and Dongguan manufacturing clusters produce over sixty percent of global consumer drone flight controllers under MIIT GB standard certification. The MIIT accelerates type approval timelines for domestic navigation module suppliers. XAG and DJI integrate captive semiconductor sourcing through Yangtze River Delta foundry partnerships, compressing bill-of-materials for agricultural autopilot units.
Germany
VTOL logistics operators absorb steepest EASA electronic conspicuity compliance costs due to hybrid lift sensor complexity. EASA mandates equivalent Remote ID broadcast standards across European airspace by 2024. Quantum-Systems anchors development in Gilching near Munich, serving German postal and medical delivery networks with certified navigation stacks.
Brazil
Soybean and sugarcane cooperatives in Mato Grosso and São Paulo states negotiate direct technical support agreements with component suppliers, bypassing distributor maintenance contracts. ANVISA coordinates with the national civil aviation regulator on agricultural spray drone type certification. Embraer X maintains a navigation systems integration lab in São José dos Campos for regional VTOL adaptation.
Australia
Cotton and pastoral property monitoring drives replacement of manual flight controllers with autonomous RTK-GNSS units in Queensland and New South Wales. CASA's emerging BVLOS corridor framework creates first-mover positioning for navigation stack providers serving long-range autonomous routes. Brisbane hosts a cluster of precision agriculture software firms customizing variable-rate spraying algorithms for local topography.
Global Drone Navigation System Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated platform vendors dominating consumer tiers and component suppliers capturing enterprise retrofit cycles. The vendor base organizes around three archetypes: captive semiconductor integrators, AI-native autonomy specialists, and military-hardened resilience architects. Consolidation pressure concentrates in mid-tier flight controller suppliers lacking either cost leadership or differentiated sensor fusion capabilities. Competitive moves center on strategic partnerships for foundry access and geographic expansion through local certification partnerships.
Among China-based platform vendors, DJI exemplifies captive supply chain integration across consumer and enterprise navigation tiers. Skydio occupies a position within the AI-native autonomy specialist archetype, while AeroVironment anchors military-grade resilience positioning through GPS-denied architecture development. These three represent divergent strategic postures rather than direct segment overlap.
| Leading Market Players |
|---|
| Autel Robotics |
| Draganfly |
| DJI |
| JOUAV |
| Ascent Aerosystems |
| Skydio |
| Parrot |
| Quantum-Systems |
| AeroVironment |
| Others |
Supply Flow & Price Mechanics
Silicon carbide wafer costs cascade through navigation inverter pricing tiers, with wide-bandgap foundry capacity in Taiwan and South Korea commanding premiums for agricultural drone operators in Brazil and Australia seeking extended flight endurance.
Pricing Analysis
Short lead-time premiums concentrate around RTK-GNSS module procurement for FAA Remote ID retrofit cycles, while spot inventory discounts appear in commoditized GPS chipsets. Three-tier pricing structure across premium, standard, and economy levels separates ITAR-compliant military stacks from enterprise agricultural units and consumer-grade controllers. Cost compression in mid-tier flight controllers intensifies because MEMS foundry capacity constraints inflate IMU sensor bills-of-materials. Agricultural fleet operators in Mato Grosso exhibit highest price sensitivity, while military buyers absorbing GPS-denied resilience architectures show least.
Supply Chain Analysis
Regional distribution centers in Shenzhen's Qianhai Free Trade Zone and Dongguan bonded logistics parks feed hub-and-spoke patterns into Brazilian soybean cooperatives and Australian cotton regions. Multi-constellation GNSS chipsets draw from Taiwan and South Korea fabrication, MEMS IMU sensors rest on rare earth magnetometer supply from China, and silicon carbide substrates source from Japanese and European foundries. Single-source vulnerability concentrates in Taiwan semiconductor packaging for navigation-grade receivers. Distribution runs through direct technical support agreements with large agricultural cooperatives bypassing traditional distributor maintenance contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market sits in a substrate-transition phase as silicon carbide power electronics displace legacy silicon in navigation inverters, forcing hardware refresh decisions across precision agriculture fleets.
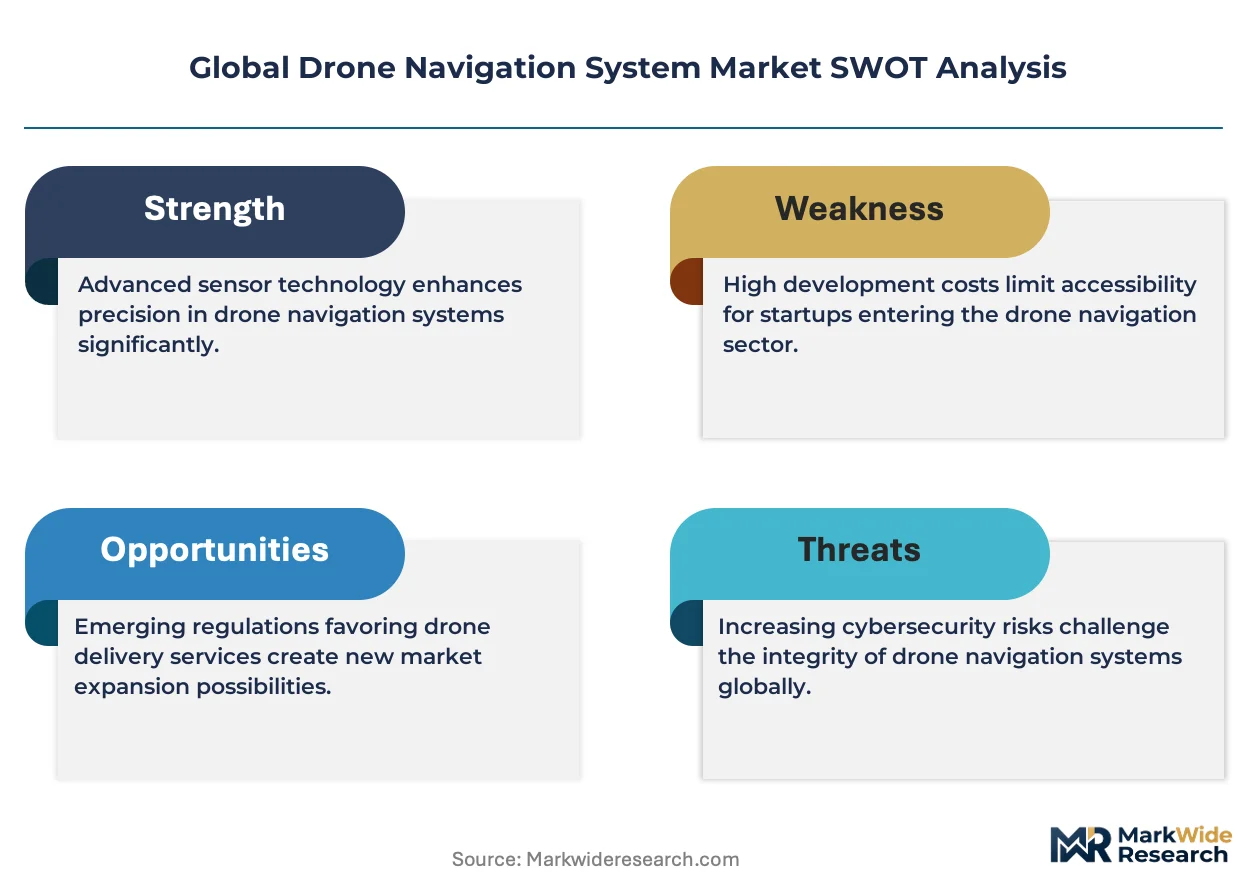
For Market Incumbents: Extend captive semiconductor sourcing relationships through Yangtze River Delta foundry partnerships to defend cost leadership against emerging AI-native autonomy specialists. Lock in multi-year RTK-GNSS correction service agreements with Brazilian and Australian agricultural cooperatives before after-sales service unbundling accelerates channel disintermediation. For New Entrants and Emerging Players: Capture first-mover positioning in CASA's emerging beyond-visual-line-of-sight corridors across Queensland and New South Wales, where long-range autonomous route certification creates navigation stack procurement windows unclaimed by incumbents. Target India's PLI scheme for drone manufacturing to establish domestic assembly capacity reducing import dependency for navigation sub-components. For Investors and Strategic Acquirers: FAA enforcement acceleration on Remote ID retrofit deadlines is the leading indicator that hardware replacement cycles will concentrate procurement authority among navigation module suppliers with pre-certified broadcast architectures. Acquisition targets should emphasize mid-tier flight controller specialists lacking backward integration into MEMS fabrication but holding EASA electronic conspicuity certification pathways. Watch for MIIT GB standard harmonization signals with FAA protocols as convergence catalyst.| Strategic Initiative | Industry Significance |
|---|---|
| Wide-Bandgap Semiconductor Partnership | SiC foundry access in Taiwan extends flight endurance for Australian agricultural operators. |
| RTK-GNSS Correction Network Expansion | Ground station density in Mato Grosso enables centimeter-level spraying repeatability. |
| EASA Electronic Conspicuity Certification | Broadcast module approval unlocks German and French VTOL logistics corridors. |
| AI-Native Sensor Fusion Acquisition | Machine learning obstacle avoidance addresses urban delivery complexity in Shenzhen. |
| India PLI Scheme Manufacturing Entry | Domestic navigation assembly reduces import dependency for sub-continental drone OEMs. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews across flight controller engineering leads at Shenzhen manufacturing clusters, agricultural fleet procurement managers in Brazil's sugarcane cooperatives, and CASA certification officers in Australia. FAA Remote ID implementation timelines, EASA drone regulation framework updates, and MIIT GB standard certification databases provided regulatory trajectory inputs. Bottom-up bill-of-materials analysis for navigation inverters triangulated against top-down market sizing from shipment data.
Data-stream reconciliation across technology segmentation, application use cases, end-user procurement tiers, and regional regulatory clusters shaped the analytical framework over the projection horizon. CAGRs derived from weighted average of historical trajectory and technology adoption curve acceleration, with silicon carbide penetration rates and BVLOS corridor rollout timelines as drone-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to geopolitical disruption in Taiwan semiconductor supply, EASA-FAA certification convergence or divergence, and rare earth magnetometer export restrictions from China. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Navigation and Communication
Global Air Traffic Control Equipment Market
Aircraft Navigation and Communication
Airborne Situational Awareness Systems Market
Aircraft Navigation and Communication
Aircraft Communication System Market
Aircraft Navigation and Communication
Airborne Radars Market
Aircraft Navigation and Communication
Connected Aircraft Market
Aircraft Navigation and Communication
Asia-Pacific Air Traffic Management Market
Aircraft Navigation and Communication
In Flight Connectivity Market
Aircraft Navigation and Communication
Airborne Telemetry Market
Aircraft Navigation and Communication
Air Traffic Control Market
Aircraft Navigation and Communication
Aircraft Turn Coordinator Market
Aircraft Navigation and Communication
Airspace and Procedure Design Market
Aircraft Navigation and Communication
Air-Based Tactical Data Link Market
Aircraft Navigation and Communication
Ultra Short Base Line Positioning System Market
Aircraft Navigation and Communication
Military Navigation Systems Market
Aircraft Navigation and Communication
5G Adoption Analysis in Aviation Market
Aircraft Navigation and Communication
Global Aviation Mapping Software Market