
 Aircraft Interface Device Market | 2026-2036
Aircraft Interface Device Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Interface Device Market Analysis
DO-178C software certification is unwinding the competitive landscape for aircraft interface device suppliers, forcing smaller vendors to absorb multi-year validation costs. Collins Aerospace leverages its integrated avionics portfolio to sustain platform-level contracts across commercial and military programs. Thales Group anchors European demand through cockpit modernization programs on Airbus platforms. Honeywell International Inc. competes aggressively in the retrofit segment where its Primus Epic architecture dominates upgrade cycles.
An aircraft interface device is a certified hardware unit that bridges avionics databuses with portable or wireless consumer electronics, typically supporting ARINC 429 and Ethernet protocols at bandwidths up to 100 Mbps to enable electronic flight bag synchronization and real-time performance telemetry. Its primary purpose is to stream flight-critical data to crew tablets and ground systems without compromising airworthiness. Embedded product types command the deepest margin pools because they require airframe-specific integration and long-term OEM support commitments. Wireless technology segments are expanding fastest as airlines phase out wired electronic flight bag mounts in favor of Bluetooth and Wi-Fi cockpit connectivity. Maintenance tracking applications now absorb disproportionate R&D investment as predictive analytics vendors demand higher-fidelity data streams.
FAA Technical Standard Order C153 and EASA Certification Memorandum SW 2011-01 govern hardware qualification and electromagnetic compatibility, while RTCA DO-160G environmental testing requirements shape supplier design priorities and filter out uncertified entrants. The EU AI Act and emerging machine-learning guidance from EASA will soon extend compliance burdens to interface devices running adaptive diagnostic algorithms. Stakeholders must monitor how pending cybersecurity mandates from the FAA's Aircraft Systems Information Security Protection framework reshape development roadmaps and certification timelines.
Market Dynamics
DO-178C software certification mandates are compressing supplier margins and filtering out uncertified vendors, while wireless cockpit connectivity standards accelerate hardware refresh cycles across commercial aviation fleets.
Growth Catalysts
- FAA Aircraft Systems Information Security Protection framework:Pending cybersecurity mandates force carriers to upgrade legacy interface hardware, creating replacement demand across installed bases.
- Predictive maintenance analytics:Airlines now require higher-fidelity telemetry streams to feed ground-based diagnostic platforms, expanding bandwidth specifications for new device installations.
- Bluetooth and Wi-Fi cockpit protocols:Phased elimination of wired electronic flight bag mounts drives retrofit programs at major carriers seeking crew mobility improvements.
Market Restraints
- DO-178C validation costs:Multi-year software certification timelines absorb capital that smaller suppliers cannot recover without platform-level OEM contracts.
- ARINC 429 legacy protocol persistence:Backward compatibility requirements constrain design freedom and extend development cycles for next-generation architectures.
- Electromagnetic compatibility testing:RTCA DO-160G environmental qualification expenses filter out uncertified entrants and raise per-unit fixed costs.
Strategic Opportunities
- Adaptive diagnostic algorithms:EU AI Act compliance positions early movers to capture premium pricing for machine-learning-enabled interface devices before standards harden.
- Defense contractor retrofit pipelines:Military platform modernization programs outside commercial certification paths offer alternative volume channels with different margin structures.
- Embedded product integration:Airframe-specific OEM support commitments create captive revenue streams through long-term service contracts tied to new aircraft deliveries.
Industry Challenges
- DO-178C software engineering talent scarcity:Qualified verification specialists command premium compensation, stretching R&D budgets at mid-tier suppliers.
- Legacy avionics databus integration:Heterogeneous fleet configurations force device manufacturers to maintain multiple hardware variants, complicating inventory and support logistics.
- EASA Certification Memorandum SW 2011-01 harmonization:Divergent interpretation timelines between FAA and European regulators delay dual-certification programs and compress launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Interface Device Market |
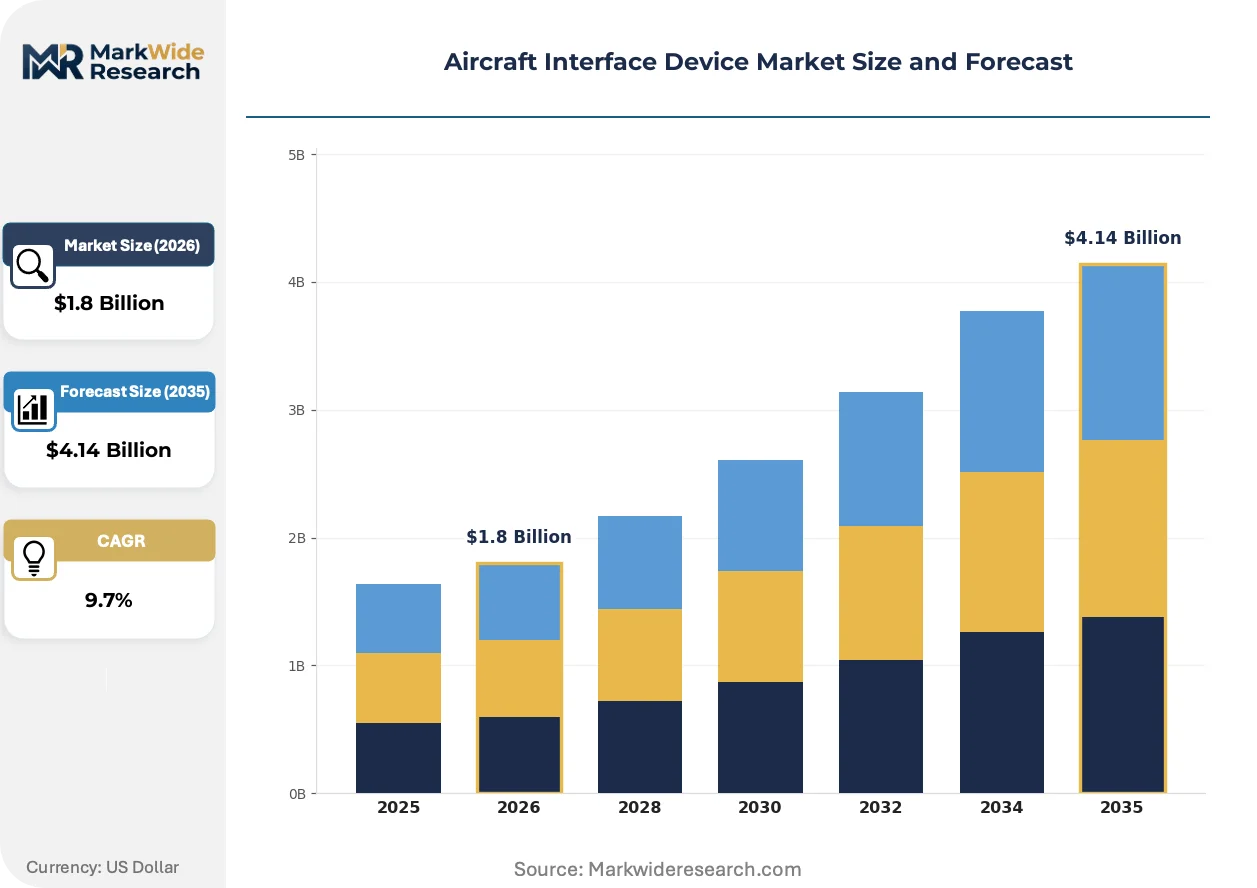
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.14 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Embedded, Wireless, Standalone Technology: Bluetooth, Wi-Fi, USB, Ethernet End User: Airlines, Aircraft Manufacturers, Maintenance Providers, Regulatory Bodies Application: Flight Data Monitoring, Maintenance Tracking, Performance Analysis, Pilot Communication |
| Companies Covered | Collins Aerospace, Astronics Corporation, Thales Group, Honeywell International Inc., Teledyne Technologies Incorporated, Elbit Systems Ltd, The Boeing Company, L3Harris Technologies, Inc., Garmin Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Interface Device Market Emerging Trajectories
Wireless cockpit connectivity protocols are fragmenting established supplier relationships while regulatory cybersecurity mandates compress hardware replacement timelines across fleet operators.
Software-defined radio architectures for aircraft interface devices are fragmenting the traditional hardware-centric competitive landscape. Regional carriers and low-cost operators now adopt modular platforms that separate physical layer hardware from protocol processing firmware. This decoupling enables faster certification cycles for protocol updates without hardware redesign, compressing supplier differentiation around integration services rather than proprietary silicon.
EASA's emerging machine-learning guidance extends compliance burdens to adaptive diagnostic algorithms running on interface devices. Hardware suppliers must now document training data provenance and algorithmic transparency alongside traditional airworthiness evidence. European cockpit modernization programs on Airbus platforms face compressed development schedules as these requirements crystallize before technical standards stabilize.
Airline technical procurement departments now unbundle electronic flight bag hardware from software licensing and integration services. Major carriers issue separate RFPs for device supply, airworthiness certification support, and ongoing maintenance analytics, fragmenting vendor relationships that previously consolidated under single-source contracts. This pattern concentrates most visibly at United States legacy carriers managing heterogeneous fleet ages and connectivity standards.
Aircraft Interface Device Market Segmentation
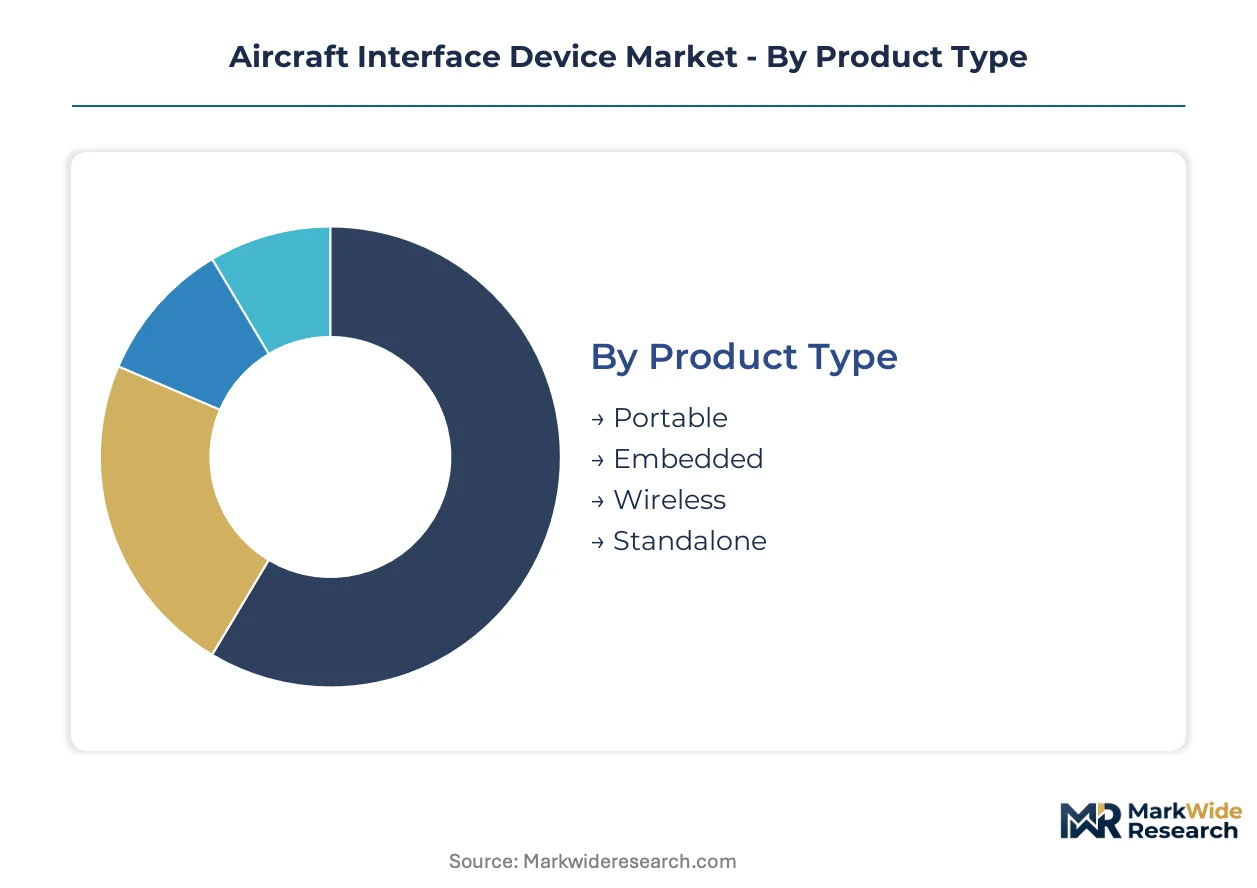
Regulatory differentiation across FAA and EASA jurisdictions shapes how aircraft interface device segments capture value. Certification requirements fragment procurement patterns by product complexity, connectivity protocol, and end-use operational criticality.
Product Type:
FAA Technical Standard Order C153 and EASA Certification Memorandum SW 2011-01 impose distinct validation burdens on fixed versus portable installations, reshaping supplier economics across hardware categories.
- Embedded:These airframe-integrated units require airworthiness certification at the platform level and lock OEMs into decade-long support commitments. United States defense contractors and major carriers like Delta and United drive procurement volumes for new aircraft deliveries where embedded architectures dominate factory installations.
- Wireless:Elimination of wired electronic flight bag mounts accelerates retrofit demand at legacy carriers seeking crew mobility improvements. Bluetooth and Wi-Fi cockpit protocols expand fastest as airlines phase out legacy tethered configurations, though electromagnetic compatibility testing under RTCA DO-160G extends qualification timelines.
- Portable:Clip-on units for temporary installations serve regional operators and charter fleets with lower certification overhead.
- Standalone:Self-contained devices address aftermarket maintenance scenarios without permanent airframe modification.
Embedded handles the majority of throughput; wireless is the fastest mover on share.
Technology:
Bandwidth specifications diverge sharply between legacy ARINC 429 bridging and next-generation Ethernet architectures, concentrating R&D investment where predictive analytics vendors demand higher-fidelity data streams.
- Ethernet:Supporting bandwidths up to 100 Mbps, these interfaces enable real-time performance telemetry streaming to ground-based diagnostic platforms. Airlines in the United States now specify Ethernet-native devices for new fleet deliveries to feed predictive maintenance analytics pipelines.
- Bluetooth:Low-energy protocols eliminate cable clutter for electronic flight bag synchronization, accelerating adoption at low-cost carriers and regional operators prioritizing rapid crew device pairing over data throughput.
- Wi-Fi:Cockpit wireless LANs support multiple concurrent device connections but face stricter electromagnetic compatibility scrutiny under evolving FAA cybersecurity mandates.
- USB:Wired connectivity persists in retrofit scenarios where airlines seek deterministic data transfer without wireless certification complexity.
Ethernet captures the dominant installed base; Bluetooth is expanding most quickly among retrofit programs.
End User:
Procurement authority concentrates differently across factory-install versus aftermarket channels, with certification risk allocation determining contract structures.
- Aircraft Manufacturers:Boeing and Airbus factory installations embed devices at the platform specification stage, locking suppliers into multi-year OEM service contracts with captive revenue streams.
- Airlines:Fleet operators now unbundle hardware supply from software licensing and integration services, fragmenting vendor relationships that previously consolidated under single-source agreements.
- Maintenance Providers:Third-party MROs drive aftermarket retrofit demand where standalone and portable configurations address heterogeneous fleet ages without permanent modification.
- Regulatory Bodies:FAA and EASA certification authorities indirectly shape demand through evolving cybersecurity and machine-learning compliance requirements rather than direct procurement.
Airlines command the largest procurement volumes; maintenance providers are gaining share fastest in the aftermarket channel.
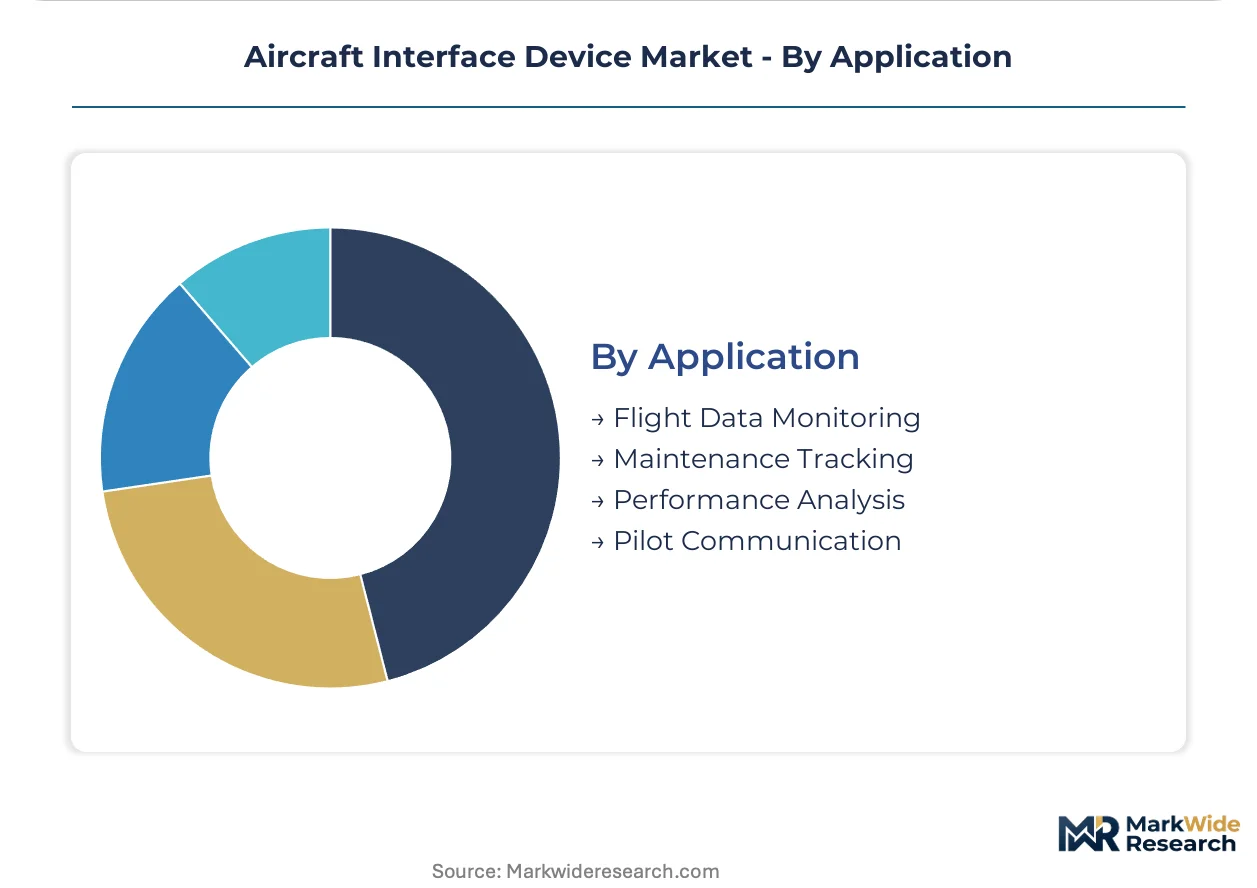
Application:
Data fidelity requirements escalate from pilot communication through predictive maintenance, with bandwidth and latency specifications determining hardware selection.
- Maintenance Tracking:Predictive analytics vendors now demand continuous high-fidelity telemetry streams, absorbing disproportionate R&D investment as airlines prioritize ground-based diagnostic platforms over manual inspection cycles.
- Flight Data Monitoring:Real-time streaming to crew tablets and operations centers requires certified interfaces bridging ARINC 429 avionics databuses with consumer electronics without airworthiness compromise.
- Performance Analysis:Post-flight data extraction for fuel optimization and route planning utilizes lower-bandwidth protocols where intermittent connectivity suffices.
- Pilot Communication:Electronic flight bag synchronization for charts and manuals represents the most mature application with established certification pathways.
Maintenance tracking leads R&D investment intensity; flight data monitoring retains the largest installed base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FAA Technical Standard Order C153 and the Aircraft Systems Information Security Protection framework drive procurement urgency at United States carriers, while EASA Certification Memorandum SW 2011-01 shapes European cockpit modernization timelines. Regulatory divergence between Washington and Brussels fragments certification strategies for suppliers seeking dual-market access.
United States
Major carriers including Delta and United drive embedded device procurement for new aircraft deliveries, while defense contractors sustain aftermarket volumes through military platform upgrades. FAA cybersecurity mandates under the Aircraft Systems Information Security Protection framework compress replacement timelines for legacy hardware across installed commercial fleets. Seattle and Wichita clusters concentrate avionics engineering talent and OEM integration facilities serving Boeing production lines.
France
Airbus cockpit modernization programs anchor European demand for certified interface hardware, with Thales Group securing platform-level contracts through integrated avionics portfolios. EASA's emerging machine-learning guidance extends compliance burdens to adaptive diagnostic algorithms, compressing development schedules for suppliers targeting A320 and A350 installations. Toulouse and Paris-Saclay clusters house Airbus engineering centers and Thales avionics divisions shaping regional specification standards.
Germany
Lufthansa Group and regional operators drive retrofit demand for wireless cockpit connectivity as airlines eliminate wired electronic flight bag mounts. EU AI Act requirements position early movers to capture premium pricing for machine-learning-enabled devices before technical standards stabilize. Hamburg and Munich clusters concentrate Lufthansa Technik maintenance capabilities and supplier engineering facilities serving Central European fleet operators.
United Kingdom
British Airways and low-cost carriers accelerate Bluetooth and Wi-Fi protocol adoption for crew mobility improvements across narrowbody fleets. Civil Aviation Authority alignment with EASA harmonization timelines delays dual-certification programs, compressing launch windows for suppliers targeting transatlantic operators. Bristol and Farnborough clusters sustain BAE Systems and smaller avionics specialists serving military and commercial retrofit channels.
Japan
ANA and JAL specifications for predictive maintenance analytics expand bandwidth requirements for new fleet deliveries, favoring Ethernet-native architectures over legacy ARINC 429 bridging. METI industrial policy supports domestic avionics component sourcing, creating procurement preferences for locally integrated solutions. Nagoya and Tokyo clusters concentrate Mitsubishi Aircraft engineering and tier-one supplier facilities serving regional jet programs.
Aircraft Interface Device Market Vendor Landscape
Player mix skews toward integrated avionics conglomerates with platform-level OEM relationships and specialized certification houses serving retrofit aftermarket channels. Market structure concentrates around three strategic archetypes: full-stack avionics suppliers capturing factory-install contracts, wireless connectivity specialists exploiting retrofit refresh cycles, and defense-focused integrators operating outside commercial certification paths. Dominant competitive moves include strategic partnerships for dual-certification acceleration and portfolio diversification into predictive maintenance software layers.
Among United States-based conglomerates, Collins Aerospace and Honeywell International Inc. occupy positions anchoring the integrated avionics tier through long-term OEM service commitments, while L3Harris Technologies, Inc. represents the defense-contractor archetype with alternative volume channels. Thales Group exemplifies European platform-level positioning through cockpit modernization programs. Elbit Systems Ltd. and Teledyne Technologies Incorporated sit within the specialized certification tier serving military retrofit pipelines with distinct margin structures.
| Leading Market Players |
|---|
| Collins Aerospace |
| Astronics Corporation |
| Thales Group |
| Honeywell International Inc. |
| Teledyne Technologies Incorporated |
| Elbit Systems Ltd |
| The Boeing Company |
| L3Harris Technologies, Inc. |
| Garmin Ltd. |
| Others |
Supply Flow & Price Mechanics
DO-178C software certification gates both supplier qualification and price differentiation simultaneously, forcing smaller vendors to absorb multi-year validation costs that tier-one OEMs recover through platform-level contracts. Certification burden concentrates pricing power among integrated avionics conglomerates while filtering uncertified entrants from premium contract tiers.
Pricing Analysis
Certification level creates the primary spread between embedded and portable configurations, with airframe-specific DO-178C validation commanding premium positioning against clip-on aftermarket alternatives. Three-tier pricing structure across platform-integrated, retrofit wireless, and temporary portable levels reflects R&D amortization schedules and support commitment duration. Cost compression in the portable tier is intensifying because regional carriers unbundle hardware from software licensing. Airlines with heterogeneous fleet configurations exhibit highest price sensitivity; defense contractors with single-platform standardization show least.
Supply Chain Analysis
Inventory lead times for RTCA DO-160G-qualified components extend qualification pipelines, tethering device manufacturers to pre-certified semiconductor and connector suppliers. Manufacturing concentrates in the United States, France, and Germany where FAA and EASA oversight proximity accelerates certification cycles. Supply chain risk centers on single-source vulnerability for ARINC 429 protocol chips and radiation-hardened microcontrollers. Distribution runs through OEM direct channels for factory-install contracts and specialized avionics distributors for aftermarket retrofit programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory entrenchment story where DO-178C validation timelines create switching costs that cement incumbent positions. Certification moats deepen as FAA cybersecurity mandates compress replacement windows.
For Market Incumbents: Shield platform-level OEM relationships through accelerated dual-certification programs spanning FAA Technical Standard Order C153 and EASA Certification Memorandum SW 2011-01. Absorb DO-178C software engineering talent scarcity by anchoring verification teams in Seattle and Toulouse clusters. Consolidate aftermarket share via captive service contracts tied to predictive maintenance analytics pipelines. For New Entrants and Emerging Players: Lead with software-defined radio architectures that decouple physical hardware from protocol firmware, targeting regional carriers and low-cost operators with modular retrofit platforms. Wireless cockpit connectivity protocols offer the most penetrable white-space as major carriers phase out wired electronic flight bag mounts. Pursue military platform modernization programs outside commercial certification paths where margin structures differ. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across embedded product integration as airframe-specific OEM support commitments lengthen. Long-term viability favors suppliers with demonstrated dual-certification velocity and established relationships with Boeing or Airbus platform engineering. Acquisition target archetype: specialized certification houses with DO-178C verification track records and defense contractor retrofit pipelines. Watch EASA machine-learning guidance crystallization as inflection indicator for adaptive diagnostic algorithm premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Certification Acceleration | Simultaneous FAA and EASA validation compresses launch windows for transatlantic operators. |
| Software-Defined Radio Investment | Protocol-hardware decoupling enables faster certification cycles without silicon redesign. |
| Predictive Maintenance Partnership | Ground-based diagnostic platform integration locks in long-term data service revenue. |
| Defense Retrofit Channel Expansion | Military modernization programs outside commercial paths offer alternative volume channels. |
| Cybersecurity Compliance Prepositioning | FAA Aircraft Systems Information Security Protection framework readiness captures replacement demand. |
Methodological Framework
Operator-level perspectives from avionics engineering directors, airline technical procurement managers, MRO aftermarket specialists, and regulatory certification consultants anchored the qualitative base. Primary interview insights combined with secondary validation from FAA Technical Standard Order filings, EASA Certification Memorandum interpretations, RTCA DO-178C and DO-160G documentation, and OEM platform specification databases. Bottom-up segmentation modeling triangulated against top-down market sizing across embedded, wireless, portable, and standalone hardware categories.
Sensitivity analysis framed volume and value outputs across the projection horizon, with segmentation dimensions spanning product type, connectivity protocol, end-user procurement authority, and application bandwidth requirements. CAGRs derived from installed base replacement cycles, new aircraft delivery schedules, and retrofit program acceleration patterns. Forecast inputs incorporated DO-178C validation timeline assumptions and electromagnetic compatibility testing completion rates.
The analysis sits within stated boundaries; outcomes outside sustained FAA and EASA regulatory harmonization progress would require recalibration. Forecasts reflect documented assumptions regarding certification backlog clearance and wireless protocol standardization velocity. Revision becomes warranted when cybersecurity mandate implementation timelines cross threshold acceleration or delay scenarios.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Navigation and Communication
5G Adoption Analysis in Aviation Market
Aircraft Navigation and Communication
Global Drone Navigation System Market
Aircraft Navigation and Communication
GPS and GNSS Receivers in Aviation Market
Aircraft Navigation and Communication
Airborne Radars Market
Aircraft Navigation and Communication
Europe Inertial Systems Market
Aircraft Navigation and Communication
Automatic Dependent Surveillance-Broadcast (ADS-B) Market
Aircraft Navigation and Communication
Asia-Pacific VHF Air-Ground Communication Stations Market
Aircraft Navigation and Communication
America Air Traffic Management Market
Aircraft Navigation and Communication
Asia-Pacific Air Traffic Management Market
Aircraft Navigation and Communication
Airborne Telemetry Market
Aircraft Navigation and Communication
5G in Aviation Market
Aircraft Navigation and Communication
Aircraft Turn Coordinator Market
Aircraft Navigation and Communication
Aviation Weather Radar Market
Aircraft Navigation and Communication
In Flight Connectivity Market
Aircraft Navigation and Communication
Airspace and Procedure Design Market
Aircraft Navigation and Communication
Ground to Air on-Board Connectivity Market