
 Airborne Radars Market | 2026-2036
Airborne Radars Market Size, Share, and Industry Trends Forecast 2026-2036
Airborne Radars Market Insights
The capability gap between full-spectrum radar developers and component-dependent suppliers is unwinding competitive tiers. Lockheed Martin leverages captive semiconductor foundry partnerships to sustain AESA production margins. RTX Corporation anchors its position through classified program relationships spanning three U.S. military branches. Northrop Grumman differentiates via integrated sensor-to-shooter architectures that reduce platform integration risk.
Airborne radars are pulsed or continuous-wave radio detection systems operating in X-band, Ku-band, or L-band frequencies, generating range, velocity, and angular data for platforms moving through three-dimensional airspace. Synthetic Aperture Radar configurations now dominate long-range surveillance contracts due to all-weather imaging fidelity. Phased Array Radar technology, particularly Active Electronically Scanned Array implementations, captures the fastest-growing investment flow as militaries retire mechanically scanned legacy systems. Pulse-Doppler Radar maintains volume leadership in fighter aircraft fire control applications where proven track-while-scan reliability outweighs upgrade cost.
FAA certification requirements for transport-category weather radar and EASA CS-25 airworthiness standards shape commercial product development timelines. The U.S. Department of Defense's Cybersecurity Maturity Model Certification and EU export control frameworks under the Wassenaar Arrangement constrain cross-border technology transfer. Stakeholders must monitor gallium nitride supply chain concentration and sovereign foundry investments as determinants of future radar performance trajectories and contract eligibility.
Market Dynamics
AESA migration is compressing upgrade cycles across NATO military fleets and forcing foundry-dependent suppliers into captive semiconductor partnerships or exit.
Growth Catalysts
- FAA Transport-Category Certification:Weather radar mandates for commercial airliners sustain replacement demand for X-band and Ku-band systems in the United States.
- Synthetic Aperture Radar:All-weather imaging fidelity positions SAR configurations for long-range surveillance contracts across maritime patrol platforms.
- Gallium Nitride Foundry Investment:Sovereign semiconductor subsidies in Japan and Germany are expanding domestic AESA production capacity.
Market Restraints
- GaN Substrate Concentration:Epitaxial wafer supply clusters in East Asian foundries expose Western radar OEMs to export control friction.
- EASA CS-25 Airworthiness Timelines:Multi-year certification pathways for new radar architectures delay platform integration revenue recognition.
- Mechanical Array Obsolescence:Pulse-Doppler fire control systems face accelerated retirement, straining military sustainment budgets.
Strategic Opportunities
- Sensor-to-Shooter Integration:Converging radar, electronic warfare, and communications payloads into unified apertures reduces platform weight and power draw.
- Unmanned Aerial System Payloads:Shrinking SWaP-C requirements for Group 4-5 drones open volume opportunities for compact AESA modules.
- India Defense Modernization:Indigenous radar development under the PLI scheme creates partnership pathways for subsystem suppliers.
Industry Challenges
- Phased Array Engineering Talent:RF semiconductor and antenna design expertise concentrates at a handful of defense-focused universities and national laboratories.
- Cybersecurity Maturity Model Certification:CMMC compliance timelines for U.S. defense contractors compress bid preparation windows.
- Legacy Platform Integration:Mechanical-to-electronic scan retrofits require airframe structural modifications that exceed original equipment lifespan projections.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Airborne Radars Market |
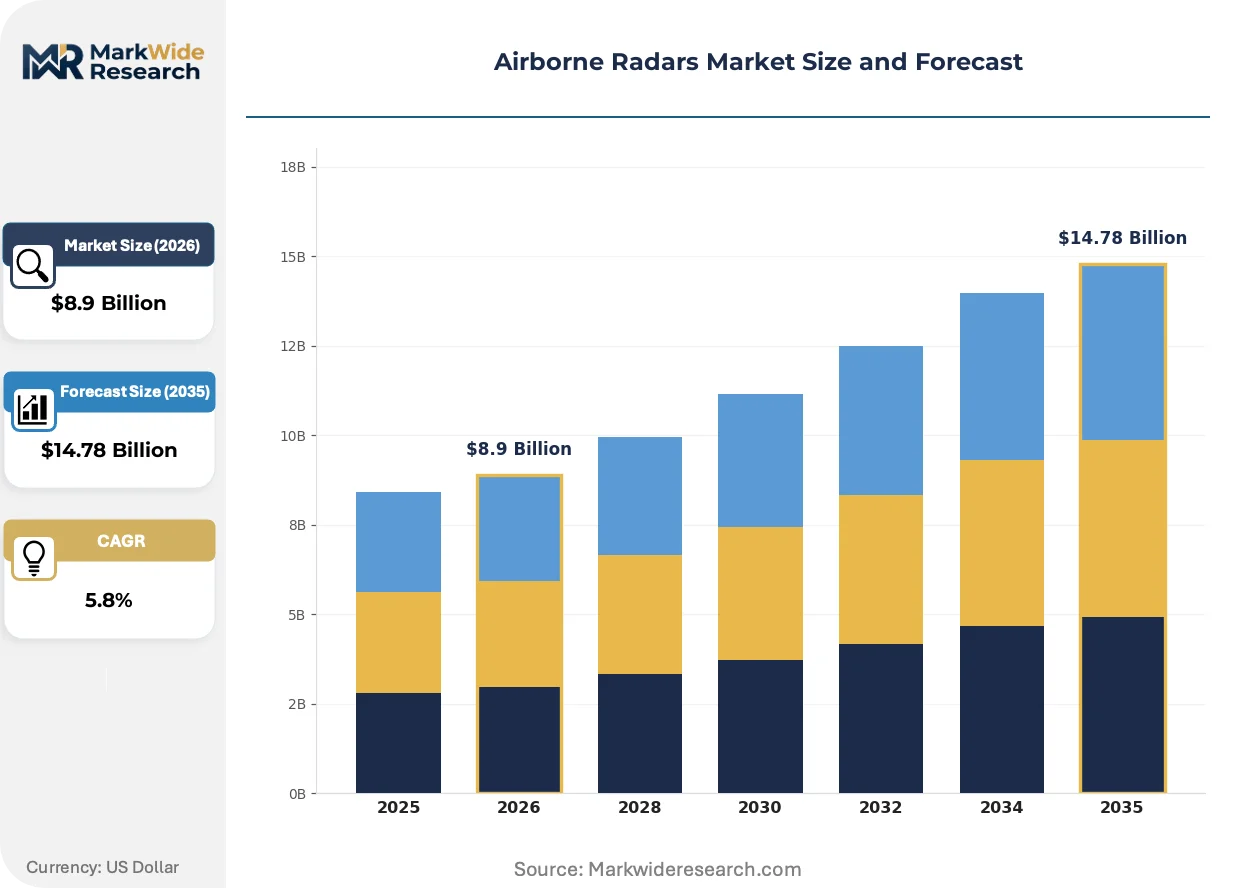
| Market Size in 2026 | $8.9 Billion |
| Market Size in 2035 | $14.78 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
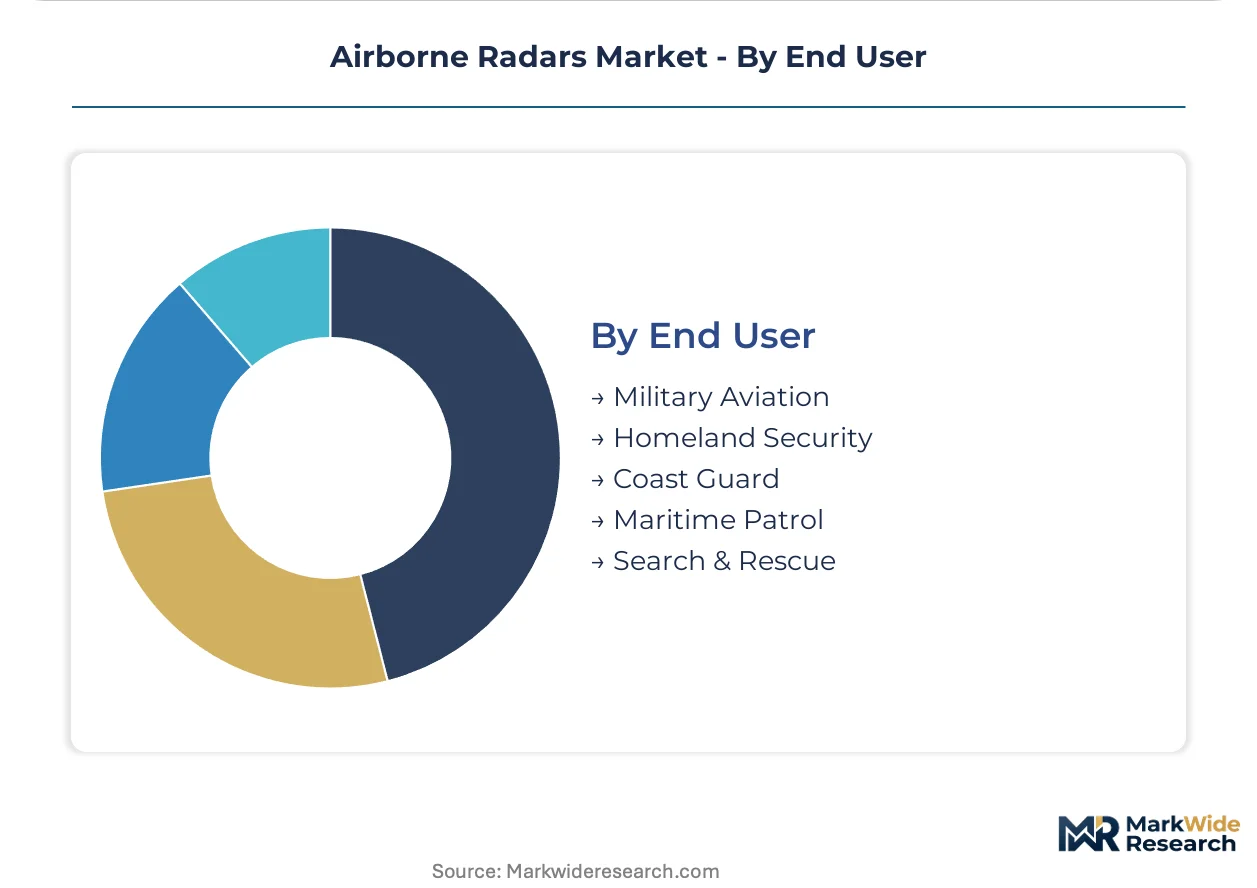
| Segmentation | Product Type: Pulse-Doppler Radar, Synthetic Aperture Radar, Weather Radar, Phased Array Radar, Continuous Wave Radar Technology: Active Electronically Scanned Array, Mechanically Scanned Array, Passive Electronically Scanned Array, Solid State, Quantum Radar Application: Surveillance, Target Tracking, Collision Avoidance, Weather Monitoring, Terrain Mapping End User: Military Aviation, Homeland Security, Coast Guard, Maritime Patrol, Search & Rescue |
| Companies Covered | Lockheed Martin Corporation, RTX Corporation, Northrop Grumman Corporation, BAE Systems, Thales Group, L3Harris Technologies, Leonardo S.p.A., Saab AB, Israel Aerospace Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Airborne Radars Market Trends and Innovations
Radar architecture is fragmenting between high-performance military AESA stacks and cost-optimized commercial weather systems, with semiconductor process geometry determining competitive boundaries.
Gallium nitride power amplifiers are bifurcating radar transmitter design. GaN-on-SiC substrates enable higher power density and thermal tolerance than legacy gallium arsenide. U.S. and European fighter programs are adopting GaN for fire control radars, while commercial weather radar suppliers remain anchored to GaAs cost structures. This divergence is compressing margins for component suppliers without captive GaN access.
EU export control frameworks under the Wassenaar Arrangement are tightening technology transfer licensing for dual-use radar components. Dual-use classification ambiguity is delaying contract execution for multinational programs. European prime contractors are responding by localizing final assembly in recipient nations to circumvent re-export restrictions.
Defense procurement offices are unbundling hardware acquisition from sustainment services. Traditional long-term integrated logistics support contracts are fragmenting into competitive spares and depot maintenance competitions. This shift is most visible in U.S. Navy and Royal Air Force fleet modernization programs, where platform primes now compete with third-party MRO providers for overhaul revenue.
Airborne Radars Market Segmentation
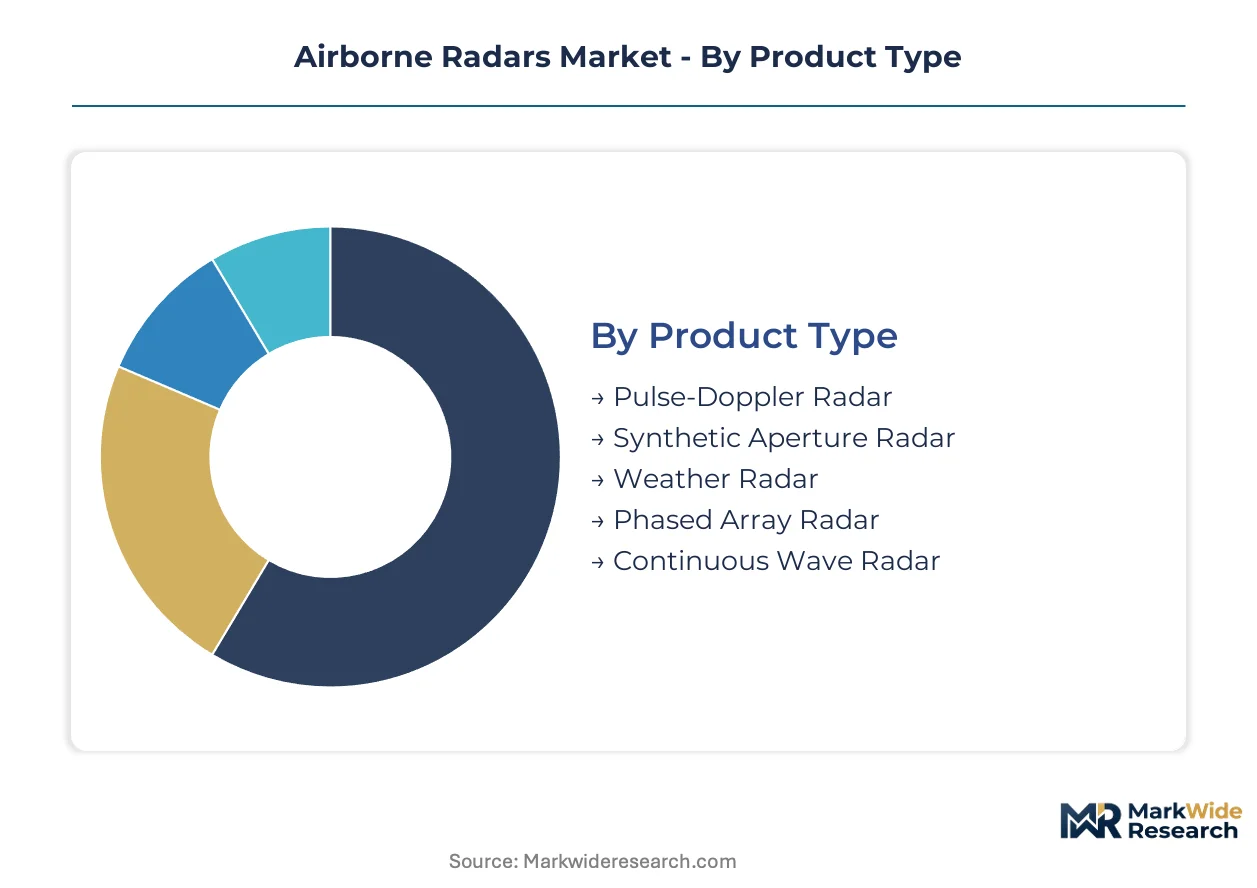
Airborne radar procurement splits across divergent certification pathways and operational envelopes. Military platforms prioritize fire-control precision and electronic survivability, while commercial aviation segments optimize for weather penetration and airspace compliance. Understanding these fault lines clarifies where technology premiums concentrate versus where cost engineering dominates.
Product Type:
FAA transport-category certification and EASA CS-25 airworthiness standards create divergent product roadmaps, with commercial weather systems facing stricter electromagnetic interference testing than military fire-control units.
- Synthetic Aperture Radar:SAR configurations generate high-resolution imagery through signal processing of platform motion rather than physical antenna movement. Maritime patrol platforms across NATO members are consolidating procurement around SAR for all-weather surface surveillance, driven by North Atlantic anti-submarine mission requirements.
- Phased Array Radar:Electronically steered beam arrays eliminate mechanical gimbal latency and enable simultaneous multi-target tracking. Fighter modernization programs in the United States, Germany, and Japan are retiring mechanically scanned legacy units in favor of AESA-equipped Phased Array systems, constrained by gallium nitride foundry capacity.
- Pulse-Doppler Radar:Doppler shift processing enables moving target indication against ground clutter. Legacy fighter fire-control applications sustain volume demand despite AESA displacement pressure.
- Weather Radar:X-band and Ku-band precipitation detection systems for commercial transport aircraft. FAA mandates sustain replacement cycles for U.S. carrier fleets.
- Continuous Wave Radar:Unmodulated carrier wave systems for short-range altimetry and proximity sensing. Helicopter and unmanned platform applications dominate uptake.
Established volume favors Pulse-Doppler legacy installations; emerging adoption favors Phased Array AESA configurations.
Technology:
Semiconductor process geometry and thermal tolerance specifications segment supplier capabilities, with GaN-on-SiC foundry access determining who can bid on next-generation military programs.
- Active Electronically Scanned Array:Solid-state transmit-receive modules enable rapid beam steering without mechanical inertia. U.S. Department of Defense Cybersecurity Maturity Model Certification requirements are filtering supplier pools for AESA integration contracts, favoring contractors with cleared semiconductor supply chains.
- Solid State:Transistor-based transmitters replace vacuum tube magnetrons for reliability and SWaP-C reduction. Commercial weather radar and unmanned aerial system payloads drive volume scaling.
- Mechanically Scanned Array:Servo-driven antenna pedestals with established logistics footprints. Sustainment budgets strain as prime contractors exit legacy production lines.
- Passive Electronically Scanned Array:Centralized transmitter with phase-shifting feed networks. Interim upgrade path for platforms lacking AESA power and cooling margins.
- Quantum Radar:Entangled photon illumination for low-observable target detection. National laboratory research programs in Japan and Germany anchor current investment.
Production maturity concentrates in Mechanically Scanned Array sustainment; steepest expansion trajectory attaches to AESA module fabrication.
Application:
Mission profile determines waveform complexity and processing latency requirements, with surveillance applications demanding synthetic aperture coherence and collision avoidance prioritizing update rate over resolution.
- Surveillance:Wide-area search and track across air, surface, and subsurface domains. Coast Guard and Maritime Patrol end-users in the United States and Japan are expanding long-range AESA surveillance fits for exclusive economic zone enforcement.
- Target Tracking:Fire-control quality track-while-scan for weapons engagement. Fighter aircraft integration specifications from the U.S. Department of Defense and Japan's Ministry of Defense constrain supplier eligibility.
- Weather Monitoring:Precipitation intensity and wind shear detection for flight path optimization. FAA-certified transport-category installations require dedicated reliability testing protocols.
- Collision Avoidance:Traffic alert and terrain proximity warning for commercial and general aviation. TCAS integration mandates shape radar packaging constraints.
- Terrain Mapping:Digital elevation model generation for navigation and mission planning. Synthetic aperture coherence requirements favor dedicated ISR platform installations.
Defense procurement volume anchors Surveillance and Target Tracking; commercial fleet modernization propels Weather Monitoring retrofits.
End User:
Budget authority and operational tempo create distinct acquisition rhythms, with military aviation programs running multi-year development cycles and homeland security agencies prioritizing rapid fielding of commercially derived systems.
- Military Aviation:Fighter, bomber, and support aircraft platforms with classified performance specifications. U.S. Air Force, Navy, and Marine Corps programs fragment procurement across platform primes with established security clearances.
- Maritime Patrol:Long-endurance surface and subsurface surveillance platforms. Japan and Germany are expanding P-8 and indigenous platform fleets with AESA radar suites.
- Homeland Security:Border surveillance and critical infrastructure protection missions. FAA certification shortcuts for non-transport applications accelerate deployment timelines.
- Coast Guard:Search and rescue plus law enforcement patrol requirements. U.S. Coast Guard HC-130 and HC-144 fleets balance mission flexibility against sensor modernization budgets.
- Search & Rescue:Helicopter-mounted weather penetration and beacon detection. Mountainous terrain operations in Japan and alpine European regions drive multi-sensor integration demands.
Program scale favors Military Aviation platform integration; procurement velocity favors Homeland Security commercial derivative acquisitions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States and Germany where defense procurement budgets sustain AESA premium tiers, while Japanese suppliers compete on sovereign foundry subsidies rather than export scale.
United States
U.S. Air Force and Navy modernization programs drive fire-control radar replacement cycles. FAA transport-category certification requirements for commercial weather systems sustain dual-use supplier revenue streams. The aerospace cluster in Greater Seattle and Southern California concentrates platform integration activity for fighter and maritime patrol programs.
Germany
Bundeswehr fleet upgrades and NATO shared procurement obligations expand AESA surveillance fits for maritime patrol platforms. EASA CS-25 airworthiness standards govern commercial derivative systems for homeland security applications. The Bavaria and Baden-Württemberg engineering corridors host subsystem suppliers aligned with Airbus Defence and Space integration hubs.
Japan
Ministry of Defense fighter modernization and exclusive economic zone enforcement missions prioritize domestic radar production. METI semiconductor subsidies under sovereign foundry programs expand gallium nitride epitaxial wafer capacity. The Kanto region around Tokyo anchors national laboratory research into quantum radar and advanced phased array architectures.
United Kingdom
Royal Air Force fleet modernization and third-party MRO competition reshape sustainment revenue recognition timelines. UK export control frameworks under the Wassenaar Arrangement constrain cross-border technology transfer for dual-use components. The Southwest England cluster around Bristol maintains legacy mechanical array sustainment capabilities alongside AESA integration facilities.
India
Indigenous radar development under the PLI scheme creates partnership pathways for foreign subsystem suppliers. DGFT licensing requirements and offset obligations structure defense procurement contract terms. The Bangalore and Hyderabad corridors concentrate public-sector radar development with DRDO laboratory and HAL manufacturing integration.
Airborne Radars Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with full-spectrum developers capturing AESA premiums and component-dependent suppliers facing margin compression. The vendor base stratifies across three tiers: vertically integrated primes with captive semiconductor access, subsystem specialists with classified program clearances, and regional integrators dependent on licensed technology. Dominant competitive moves include sovereign foundry partnerships for GaN supply security and sensor-to-shooter architecture convergence to reduce platform integration risk.
Among U.S.-based defense primes, Lockheed Martin Corporation, RTX Corporation, and Northrop Grumman Corporation exemplify the vertically integrated tier. These entities occupy positions defined by established security clearances and classified program relationships spanning multiple military branches. Their competitive positioning rests on sustained access to domestic semiconductor supply chains rather than cost engineering alone.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| RTX Corporation |
| Northrop Grumman Corporation |
| BAE Systems |
| Thales Group |
| L3Harris Technologies |
| Leonardo S.p.A. |
| Saab AB |
| Israel Aerospace Industries |
| Others |
Pricing and Supply Chain Analysis
GaN-on-SiC foundry scale economies in Japan and the United States compress unit costs for AESA transmit-receive modules while elevating price floors for component-dependent suppliers lacking captive semiconductor access. This concentration dynamic bifurcates procurement economics between vertically integrated primes and foundry-dependent subsystem vendors.
Pricing Analysis
Configured-to-order AESA radar systems for fighter fire-control applications command substantial premiums over standard-catalog weather radar units for commercial transport aircraft. Three-tier pricing structure across certified-military, dual-use, and commercial-aviation levels reflects FAA and EASA certification investment recovery timelines. Pricing pressure stems from gallium nitride substrate scarcity and sovereign foundry competition in Japan and Germany. Military aviation primes exhibit lowest price sensitivity due to classified program security requirements; commercial airline procurement teams demonstrate highest sensitivity to unit cost and total cost of ownership.
Supply Chain Analysis
Strategic stockpiling of GaN epitaxial wafers dominates inventory strategy among Western radar OEMs confronting export control friction from East Asian foundry concentration. Critical input dependencies center on gallium nitride substrates, silicon carbide wafers, and specialized RF semiconductor packaging from Japan, Germany, and Taiwan. Supply chain risk manifests in single-source vulnerability for GaN-on-SiC epitaxy capacity. Distribution runs through prime contractor platform integration contracts with military procurement offices and commercial avionics OEM tier-one supply agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The airborne radars market is entering a cyclical recovery phase driven by NATO military fleet modernization cycles and FAA-mandated commercial weather radar replacement waves. Procurement momentum concentrates in AESA technology migration and sovereign foundry capacity expansion.
For Market Incumbents: Consolidate gallium nitride foundry partnerships in Japan and Germany to secure substrate supply against export control tightening. Deepen backward integration into transmit-receive module fabrication to defend margins against component-dependent competitors. Lockheed Martin and RTX Corporation demonstrate this model through captive semiconductor relationships. CMMC compliance investment filters supplier pools; accelerate security clearance infrastructure to maintain bid eligibility.
For New Entrants and Emerging Players: Differentiate on compact AESA modules for Group 4-5 unmanned aerial systems where SWaP-C requirements outpace incumbent product roadmaps. White-space targets include India defense modernization partnerships under PLI scheme incentives and homeland security commercial-derivative acquisitions with accelerated FAA certification pathways. Go-to-market angle should emphasize rapid fielding timelines versus military platform integration cycles.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among subsystem specialists with classified program clearances and multi-year sustainment contracts. Long-term viability across the projection horizon hinges on GaN foundry access and sensor-to-shooter architecture integration capabilities. Acquisition target archetype: mid-cap RF semiconductor firms with cleared supply chains and AESA module production expertise. Signal to watch: Japan METI subsidy allocation shifts indicating sovereign foundry capacity expansion timing.
| Strategic Initiative | Industry Significance |
|---|---|
| GaN Foundry Partnership | Secures substrate supply against Wassenaar Arrangement export control tightening. |
| Sensor-to-Shooter Integration | Converges radar, EW, and communications payloads to reduce platform weight and power draw. |
| CMMC Compliance Investment | Maintains bid eligibility for U.S. Department of Defense AESA integration contracts. |
| India PLI Scheme Partnership | Creates localized assembly pathways circumventing EU dual-use re-export restrictions. |
| Compact AESA Module Development | Captures Group 4-5 UAS payload opportunities with shrinking SWaP-C requirements. |
Research Methodology
A standing panel of fighter program procurement officers, radar subsystem engineering directors, FAA certification specialists, and GaN foundry operations managers provided ongoing calibration across primary interview cycles. Secondary validation drew from U.S. Department of Defense budget justification documents, EASA CS-25 airworthiness certification databases, Japan METI semiconductor subsidy disclosures, and NATO shared procurement announcements. Bottom-up segment sizing triangulated against top-down defense budget allocation analysis.
Consistency checks validated volume and value outputs against external benchmarks including military platform production schedules and commercial aircraft delivery backlogs. The analytical framework modeled segmentation across product type, technology node, application mission profile, and end-user budget authority. CAGRs were derived from platform retirement timelines and upgrade cycle compression rates. Industry-specific forecast inputs included AESA adoption curves and gallium nitride foundry capacity expansion announcements.
The analysis sits within stated boundaries; outcomes outside sustained defense modernization budget trajectories or stable export control frameworks would require recalibration. Forecasts reflect assumptions regarding NATO fleet expansion, FAA certification timeline stability, and sovereign foundry subsidy continuity. Revision becomes warranted when GaN substrate supply concentration or CMMC implementation delays cross threshold levels affecting contract execution velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Navigation and Communication
America Air Traffic Management Market
Aircraft Navigation and Communication
Ground to Air on-Board Connectivity Market
Aircraft Navigation and Communication
Asia-Pacific Air Traffic Management Market
Aircraft Navigation and Communication
Asia-Pacific VHF Air-Ground Communication Stations Market
Aircraft Navigation and Communication
Airborne High Frequency Radio Market
Aircraft Navigation and Communication
Aviation Weather Radar Market
Aircraft Navigation and Communication
Air Traffic Management Software Market
Aircraft Navigation and Communication
Air Traffic Management Market
Aircraft Navigation and Communication
Air-Based Tactical Data Link Market
Aircraft Navigation and Communication
Connected Aircraft Market
Aircraft Navigation and Communication
In Flight Connectivity Market
Aircraft Navigation and Communication
Digital Radiosonde Market
Aircraft Navigation and Communication
Airspace and Procedure Design Market
Aircraft Navigation and Communication
5G Adoption Analysis in Aviation Market
Aircraft Navigation and Communication
Global Aviation Mapping Software Market
Aircraft Navigation and Communication
Middle-East and Africa Air Traffic Management Market