
 Ground to Air on-Board Connectivity Market | 2026-2036
Ground to Air on-Board Connectivity Market Size, Share, and Industry Trends Forecast 2026-2036
Ground to Air on-Board Connectivity Market Foresight
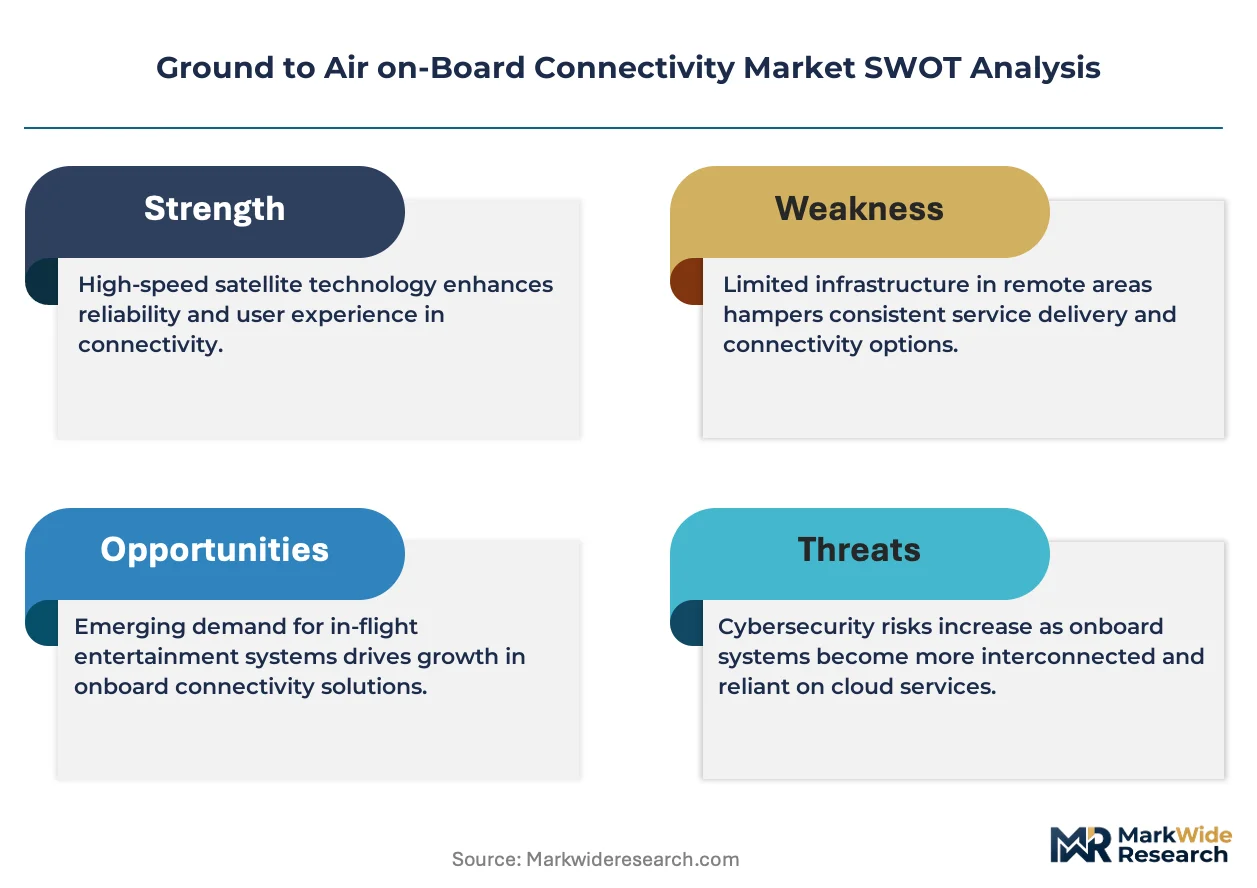
Aftermarket service revenue is reshaping margin capture across the Ground to Air on-Board Connectivity landscape as hardware commoditization pressures OEM pricing. Gogo Inc. leverages its established air-to-ground network infrastructure to dominate North American regional jet connectivity. Viasat Inc. anchors its position through vertically integrated satellite capacity, from orbital assets to terminal manufacturing. Panasonic Avionics Corporation specializes in integrated in-flight entertainment and connectivity bundles that sustain premium pricing on wide-body platforms.
Ground to Air on-Board Connectivity encompasses the integrated systems enabling real-time data, voice, and video transmission between aircraft and terrestrial networks via satellite relay, air-to-ground cellular towers, or direct beamforming links operating across L-band through Ka-band frequencies. Its primary commercial purpose is to deliver passenger broadband internet, cockpit operational data, and crew communications while maintaining uninterrupted connectivity throughout all flight phases. Satellite technology leads installed base value due to coverage ubiquity over oceans and remote terrain where terrestrial infrastructure cannot reach. Wi-Fi distribution within the cabin represents the fastest-growing service layer as airlines monetize tiered access models. Retrofit installations command substantial margin pools as aging fleets require antenna and modem upgrades to match passenger expectations set by terrestrial broadband.
The FAA governs airworthiness certification under Title 14 CFR, creating compliance barriers that filter equipment suppliers and extend product qualification cycles. The FCC manages spectrum allocation for air-to-ground services and satellite earth stations, directly constraining bandwidth economics and competitive entry. The EU AI Act and CE marking requirements under the Radio Equipment Directive shape product standards for European airline procurement. Stakeholders must monitor spectrum reallocation proceedings and emerging cybersecurity mandates as regulatory complexity becomes a structural determinant of vendor viability.
Market Dynamics
Airline fleet retrofit cycles are compressing hardware refresh timelines as narrow-body aircraft now require Ka-band antenna upgrades to match passenger connectivity expectations set by terrestrial broadband.
Growth Catalysts
- Passenger Connectivity Mandates:FAA airworthiness certification under Title 14 CFR is accelerating equipment standardization across US commercial fleets. Airlines treat broadband as competitive differentiation on transcontinental routes.
- LEO Satellite Constellation Deployment:Low-earth orbit satellite networks are expanding coverage density over oceanic corridors previously served only by geostationary assets.
- India:TRAI spectrum allocation frameworks for in-flight connectivity are opening airspace over the subcontinent to foreign carrier roaming agreements.
Market Restraints
- Antenna Weight Penalties:Radome and phased-array assemblies add fuel-burn costs that erode airline margin on short-haul sectors.
- Semiconductor Supply Concentration:Gallium nitride power amplifier fabrication concentrates in East Asian foundries, creating single-source vulnerability for terminal manufacturers.
- Ka-band Rain Fade:Atmospheric attenuation at higher frequencies degrades signal integrity during tropical precipitation events, limiting reliable throughput.
Strategic Opportunities
- Brazil:ANVISA harmonization with FAA certification pathways is reducing duplicate testing burdens for equipment entering Latin American fleets.
- Cockpit Operational Data Streaming:Real-time engine health monitoring via satellite backhaul is displacing post-flight manual downloads.
- EU AI Act:Automated spectrum management algorithms gain procurement preference as European carriers prioritize CE-marked predictive maintenance systems.
Industry Challenges
- RF Engineer Scarcity:Phased-array antenna calibration and beamforming optimization require specialized expertise that outpaces university program output.
- Line-Fit Integration Complexity:Airbus and Boeing production slots for factory-installed connectivity hardware face 18-month backlogs that delay fleet-wide standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ground to Air on-Board Connectivity Market |
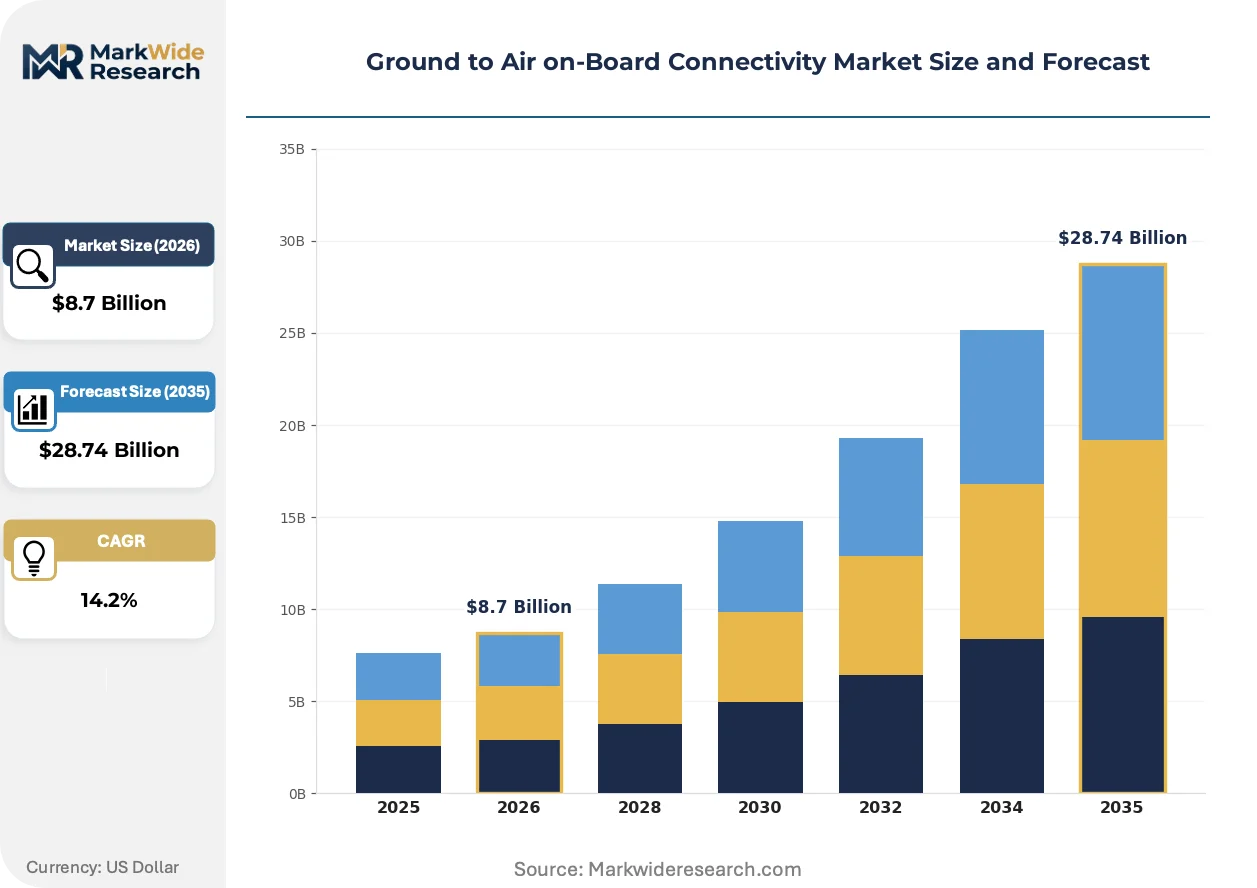
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
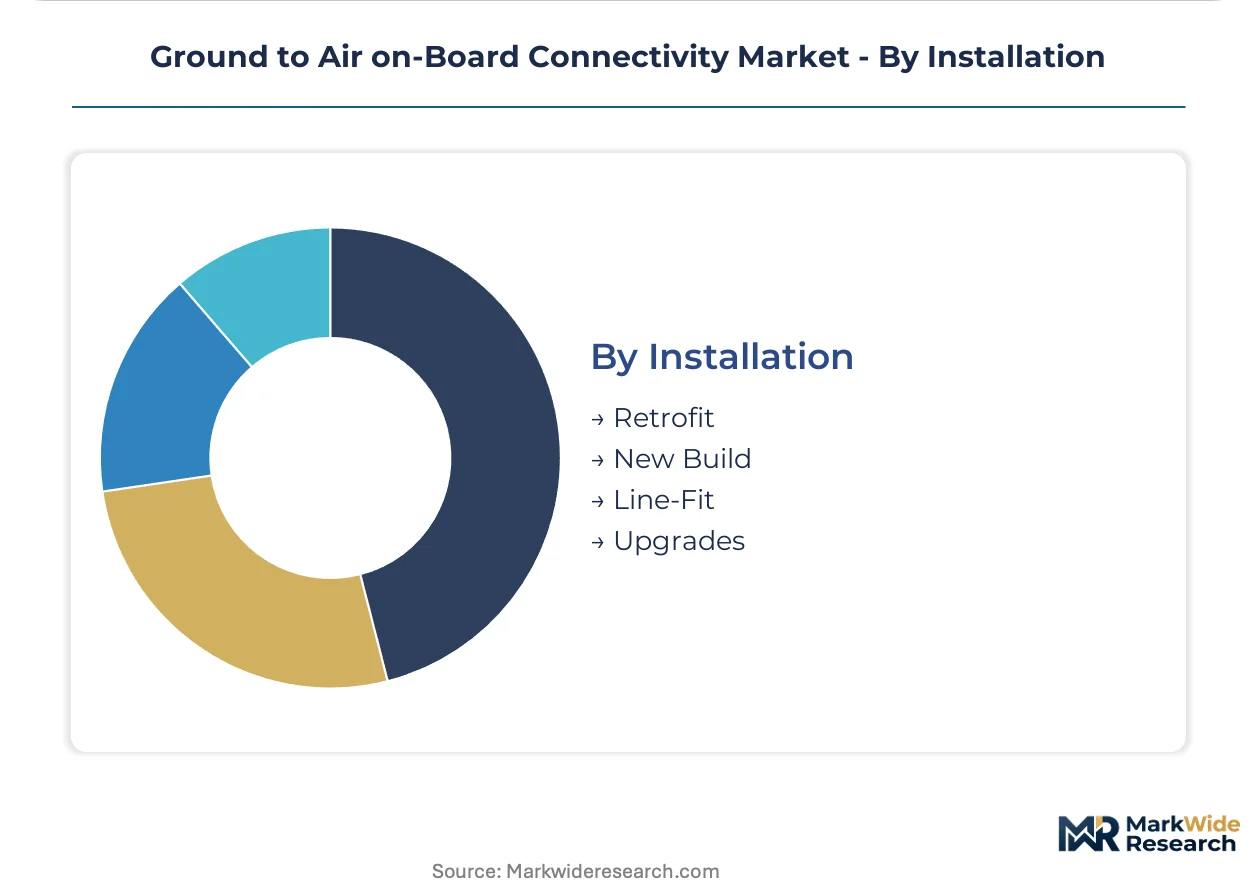
| Segmentation | Technology: Wi-Fi, Satellite, LTE, 5G Service Type: In-Flight Entertainment, Internet Access, Communication Services, Data Services End User: Aerospace OEMs, Airlines, Private Jets, Maintenance Providers Installation: Retrofit, New Build, Line-Fit, Upgrades |
| Companies Covered | Gogo Inc., Viasat Inc., Honeywell International, Collins Aerospace, Panasonic Avionics Corporation, AT&T, Qualcomm, Thales Group, Nokia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ground to Air on-Board Connectivity Market Shifts & Advancements
Terminal architecture is flattening as software-defined modems displace hardware-centric designs, compressing equipment refresh cycles and opening supplier entry points.
Electronically steered antennas are migrating from mechanical gimbal systems to solid-state phased arrays. Regional jet operators at Delta and United are adopting these terminals to reduce drag and maintenance intervals. The shift is compressing aftermarket service revenue pools as solid-state reliability extends mean-time-between-failures.
The EU Radio Equipment Directive's 2024 cybersecurity amendments are mandating encrypted firmware update channels for all cabin connectivity hardware. Terminal manufacturers must now embed hardware security modules to achieve CE marking. Wide-body retrofit programs at European flag carriers are absorbing these compliance costs through extended supplier financing terms.
Airline technical procurement teams are consolidating vendor relationships around full-stack providers capable of satellite capacity, terminal hardware, and passenger portal management. This consolidation is displacing best-of-breed component sourcing that dominated early connectivity deployments. The pattern is most visible in US major carrier RFPs, where single-source accountability clauses now outweigh unit cost minimization.
Ground to Air on-Board Connectivity Market Segmentation
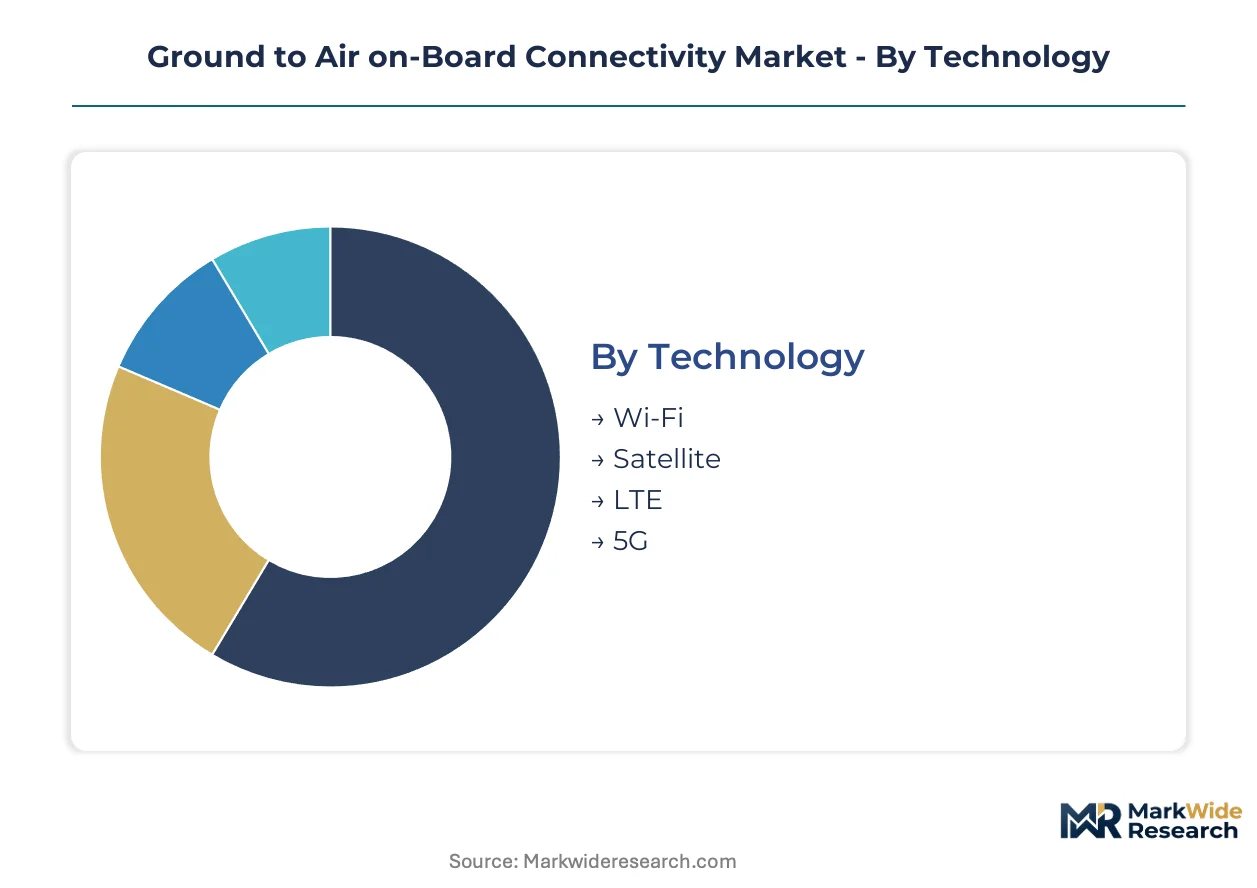
Technology heterogeneity across the Ground to Air on-Board Connectivity Market creates divergent equipment upgrade cycles and margin structures. Satellite and air-to-ground systems compete for bandwidth economics while installation modality determines fleet deployment velocity and regulatory pathway complexity.
Technology:
Mature satellite infrastructure dominates transoceanic routes; emerging 5G terrestrial networks are compressing latency benchmarks for continental corridors.
- Wi-Fi:Cabin distribution networks operate on 802.11ac/ax standards with dual-band access points managing passenger device density. Demand concentrates in narrow-body retrofits where airlines monetize tiered access models across domestic US routes. Antenna weight penalties limit deployment on regional jets with tight fuel margins.
- Satellite:Geostationary and LEO constellations deliver Ka-band and Ku-band capacity over oceanic corridors beyond terrestrial reach. Maritime and polar routes drive procurement as carriers compete on uninterrupted connectivity for transpacific flights. Phased-array terminals are displacing mechanically steered antennas to reduce drag.
- LTE:Air-to-ground cellular networks leverage ground station infrastructure for continental coverage at lower latency than orbital assets. Gogo's terrestrial footprint anchors North American regional jet deployments where satellite economics fail.
- 5G:Millimeter-wave and sub-6GHz protocols promise sub-100ms latency for real-time cockpit data streaming. Trials are accelerating in Chinese and South Korean airspace where terrestrial 5G density supports aerial handoffs.
Satellite retains volume leadership; 5G holds the steepest expansion curve.
Service Type:
Revenue concentration shifts from hardware sales toward recurring service layers as airlines bundle connectivity into loyalty programs.
- In-Flight Entertainment:Integrated seatback screens and streaming portals deliver licensed content and live television. Wide-body fleets at European and Middle Eastern flag carriers sustain premium pricing for bundled entertainment-connectivity packages. Content licensing costs erode margins unless offset by advertising revenue.
- Internet Access:Passenger broadband generates the highest service revenue per available seat mile across long-haul configurations. US major carriers are standardizing free ad-supported tiers to match terrestrial consumer expectations. Ka-band throughput limitations during precipitation events constrain reliability guarantees.
- Communication Services:Crew voice and messaging systems prioritize safety-critical channels over passenger traffic. Cockpit operational data is displacing legacy ACARS messaging on satellite backhaul.
- Data Services:Real-time engine telemetry and predictive maintenance feeds reduce unscheduled downtime. Airbus and Boeing are mandating connectivity readiness for new production slots.
Internet Access commands the largest revenue pool; Data Services are climbing fastest as operational technology converges.
End User:
Procurement authority fragments across fleet operators, airframers, and third-party maintainers with divergent technical specifications.
- Aerospace OEMs:Airbus and Boeing factory-install connectivity hardware during final assembly, capturing line-fit premiums and multi-year service contracts. Production slot backlogs extend 18 months for integrated antenna configurations.
- Airlines:Network carriers and low-cost operators drive retrofit demand as passenger connectivity becomes a competitive differentiator on domestic US and European trunk routes. Fleet heterogeneity complicates vendor standardization.
- Private Jets:Business aviation operators prioritize bandwidth reliability and cybersecurity over unit cost, accepting premium pricing for dedicated satellite beams. Fractional ownership fleets at NetJets and Flexjet consolidate procurement.
- Maintenance Providers:Third-party MROs capture aftermarket antenna upgrades and STC certification services as aging fleets require modem replacements. Lufthansa Technik and ST Engineering are expanding connectivity-specific hangar capacity.
Airlines dominate unit volume; Private Jets sustain the highest margin per installation.
Installation:
Supply lead times and regulatory burden vary sharply between factory integration and aftermarket retrofit.
- Retrofit:Aging narrow-body fleets require antenna and radome upgrades to match passenger expectations, driving substantial aftermarket revenue. Delta and United are accelerating A320 and 737NG connectivity programs.
- New Build:Factory-installed systems avoid supplemental type certificate delays and integrate cleanly with avionics architectures. Boeing 787 and Airbus A350 production lines now standardize connectivity readiness.
- Line-Fit:Airframer-managed installation during final assembly compresses certification cycles and locks in long-term service agreements. Single-source accountability clauses are displacing best-of-breed component sourcing.
- Upgrades:Modem and antenna swaps extend equipment life as spectrum allocations shift and throughput standards rise. Ka-band migration from Ku-band is accelerating across US carrier fleets.
Retrofit commands current volume; Line-Fit is gaining share fastest as production rates recover.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Connectivity consumption patterns diverge sharply across geographies: North American carriers prioritize passenger broadband monetization, while European and Asian operators emphasize operational data streaming and regulatory compliance integration.
United States
Major carriers including Delta and United are accelerating narrow-body retrofit programs for Ka-band antenna upgrades. The FAA's Title 14 CFR airworthiness certification shapes equipment approval timelines and vendor selection criteria. Seattle-Tacoma and Dallas-Fort Worth aerospace clusters concentrate terminal manufacturing and MRO capacity for domestic fleet deployments.
Germany
Lufthansa Technik drives aftermarket connectivity upgrades across aging European narrow-body fleets. The EU Radio Equipment Directive's 2024 cybersecurity amendments mandate encrypted firmware channels for CE marking compliance. Hamburg and Munich maintenance hubs specialize in STC certification services for satellite terminal retrofits.
China
Domestic carriers are trialing millimeter-wave 5G aerial handoffs leveraging dense terrestrial infrastructure. MIIT spectrum allocation frameworks govern sub-6GHz and mmWave bands for in-flight services. The Yangtze River Delta aerospace corridor concentrates avionics integration facilities near Shanghai and Nanjing production centers.
United Arab Emirates
Emirates and Etihad compete on premium connectivity bundles for long-haul transpacific routes. The General Civil Aviation Authority harmonizes certification pathways with EASA and FAA standards. Dubai's Al Maktoum aerospace cluster hosts specialized hangar capacity for wide-body line-fit installations.
Brazil
ANVISA harmonization with FAA certification pathways is reducing duplicate testing burdens for equipment entering Latin American fleets. Gol and Azul are evaluating satellite connectivity for domestic trunk routes. São Paulo's Embraer supply chain ecosystem supports regional jet terminal integration programs.
Ground to Air on-Board Connectivity Market Competitive Landscape
Capability concentration sits with vertically integrated satellite operators; scale advantage sits with established air-to-ground network providers. The vendor base organizes around three archetypes: full-stack integrators controlling orbital capacity through terminal manufacturing, terrestrial infrastructure specialists leveraging ground station density, and avionics OEMs embedding connectivity into factory-installed avionics suites. Dominant competitive moves include strategic partnerships between satellite operators and airline technical procurement teams, plus portfolio diversification into predictive maintenance data services.
Within the full-stack integrator tier, Viasat Inc. and Panasonic Avionics Corporation exemplify vertically integrated positioning spanning orbital assets to passenger portal management. Gogo Inc. anchors the terrestrial specialist archetype through its established North American air-to-ground infrastructure. These three entities collectively represent the competitive vectors shaping procurement consolidation around single-source accountability clauses.
| Leading Market Players |
|---|
| Gogo Inc. |
| Viasat Inc. |
| Honeywell International |
| Collins Aerospace |
| Panasonic Avionics Corporation |
| AT&T |
| Qualcomm |
| Thales Group |
| Nokia |
| Others |
Supply & Pricing Matrix
Undercapacity in Ka-band phased-array antenna fabrication is compressing supplier margins while extending lead times for airline retrofit programs. Equipment vendors are responding with tiered contract structures that lock in long-term service revenue to offset hardware commoditization.
Pricing Analysis
Long-term offtake agreements dominate equipment procurement as airlines seek cost predictability across fleet-wide connectivity deployments. Pricing stratifies across premium, standard, and economy tiers based on bandwidth guarantees and antenna form-factor sophistication. Cost compression in terminal hardware is intensifying because semiconductor foundry capacity constraints limit gallium nitride power amplifier supply. Regional jet operators exhibit the highest price sensitivity due to thin fuel margins, while business aviation buyers prioritize reliability over unit cost.
Supply Chain Analysis
Extended payment terms from European flag carriers are cascading upstream to terminal manufacturers and satellite operators. Component fabrication concentrates in the United States, Germany, and Japan for precision antenna assemblies and avionics-grade semiconductors. The supply chain draws from gallium nitride substrates, composite radome materials, and specialized RF connectors. Single-source vulnerability in East Asian foundry capacity for power amplifiers threatens equipment delivery schedules. Distribution runs through airframer line-fit channels and third-party MRO retrofit networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory certification entrenchment creates durable barriers against new supplier entry. FAA airworthiness approval cycles and STC validation requirements embed switching costs that protect established vendor positions.
For Market Incumbents: Insulate market position by deepening backward integration into satellite capacity ownership and securing exclusive line-fit partnerships with Airbus and Boeing production lines. Emerging LEO constellation operators threaten legacy geostationary bandwidth economics, making captive orbital assets the priority defensive lever. Accelerate predictive maintenance data service bundling to capture recurring revenue streams that hardware commoditization erodes. For New Entrants and Emerging Players: Build out white-space presence in Brazilian and Indian retrofit markets where regulatory harmonization is reducing certification barriers for foreign equipment suppliers. Regional jet connectivity at North American carriers remains underpenetrated relative to narrow-body fleets, offering the most accessible entry vector. Pursue partnerships with third-party MROs for STC-certified installation capacity rather than competing for direct airline procurement contracts. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among full-stack integrators controlling satellite capacity, terminal manufacturing, and passenger portal management within unified ownership structures. Five-to-ten year viability favors vendors with FAA and EASA certification breadth plus established airline technical procurement relationships. Monitor LEO constellation deployment velocity as the critical inflection signal for geostationary bandwidth pricing power erosion.| Strategic Initiative | Industry Significance |
|---|---|
| Satellite Capacity Backward Integration | Viasat's orbital asset ownership secures bandwidth economics independent of third-party leases. |
| Phased-Array Terminal Platform Launch | Solid-state antenna migration reduces drag penalties and extends mean-time-between-failures for regional jets. |
| Airframer Line-Fit Partnership | Factory-installed connectivity at Boeing and Airbus compresses certification cycles and locks service contracts. |
| Predictive Maintenance Data Service | Real-time engine telemetry bundling captures operational technology budgets beyond passenger connectivity. |
| Regulatory Harmonization Joint Venture | ANVISA-FAA alignment reduces duplicate testing burdens for Latin American fleet equipment entry. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with airline technical procurement directors, satellite network operations executives, avionics integration engineers, and MRO facility managers. Secondary validation drew from FAA airworthiness certification databases, EASA type certificate filings, FCC spectrum allocation proceedings, and airline fleet planning disclosures. Bottom-up equipment shipment tallies and top-down satellite capacity utilization estimates were triangulated to anchor market sizing.
Calibration against historical retrofit installation rates and production line delivery schedules informed trajectory modeling across the projection horizon. Segmentation dimensions include technology type, service layer, end-user category, and installation modality, with regional regulatory cluster as an additional cross-cutting variable. CAGRs were derived from fitted growth curves applied to equipment and service revenue streams, incorporating airline passenger traffic recovery patterns and satellite constellation deployment timelines as industry-specific demand drivers.
Sensitivities concentrate around FAA certification timeline extensions, LEO constellation commercial service delays, and airline fleet retirement decisions that accelerate or defer retrofit demand. Forecasts reflect documented assumptions regarding spectrum allocation stability and semiconductor supply normalization. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Navigation and Communication
Air Traffic Management Software Market
Aircraft Navigation and Communication
Europe Air Traffic Management Market
Aircraft Navigation and Communication
Global Drone Navigation System Market
Aircraft Navigation and Communication
Helicopter Meteorological Software Market
Aircraft Navigation and Communication
GPS and GNSS Receivers in Aviation Market
Aircraft Navigation and Communication
Aircraft Turn Coordinator Market
Aircraft Navigation and Communication
Airborne Situational Awareness Systems Market
Aircraft Navigation and Communication
Military Navigation Systems Market
Aircraft Navigation and Communication
Asia-Pacific Air Traffic Management Market
Aircraft Navigation and Communication
Defense Advanced GPS Receiver (DAGR) Market
Aircraft Navigation and Communication
Air Traffic Control Market
Aircraft Navigation and Communication
Aviation Weather Radar Market
Aircraft Navigation and Communication
5G in Aviation Market
Aircraft Navigation and Communication
In Flight Connectivity Market
Aircraft Navigation and Communication
Global Flight Navigation System Market
Aircraft Navigation and Communication
Europe Inertial Systems Market