
 Airborne Collision Avoidance System Market | 2026-2036
Airborne Collision Avoidance System Market Size, Share, and Industry Trends Forecast 2026-2036
Airborne Collision Avoidance System Market Analysis
Unmanned aerial vehicle operators are redrawing procurement priorities across the airborne collision avoidance system value chain. Thales Group leverages its radar portfolio to anchor European defense and civil aviation programs. Honeywell International Inc sustains broad certification coverage across Boeing and Airbus platforms. L3Harris Technologies, Inc specializes in military-grade integrative systems for contested airspace environments.
An airborne collision avoidance system is an avionics subsystem that processes sensor inputs from radar, ADS-B transponders, and visual sensors to compute resolution advisories and traffic alerts for flight crews, with typical response latencies below one second for critical alerts. Its primary purpose is to prevent mid-air collisions and enable safe separation in dense or uncontrolled airspace. Active systems dominate commercial aviation installations due to regulatory mandates for autonomous threat detection, while ADS-B technology is expanding fastest as the backbone of next-generation surveillance infrastructure. Military aviation applications favor hybrid architectures that fuse multiple sensor modalities for jam-resistant performance.
The FAA mandates TCAS II and ADS-B Out equipage under 14 CFR 91.225, while EASA enforces equivalent standards through its Air Traffic Management master plan and CS-ACNS certification specifications. These frameworks create durable replacement demand as legacy Mode C transponder fleets age out of compliance. Stakeholders must monitor evolving detect-and-avoid standards for UAV integration into national airspace systems, as regulatory divergence between jurisdictions threatens to fragment certification pathways and inflate development costs for multi-market platforms.
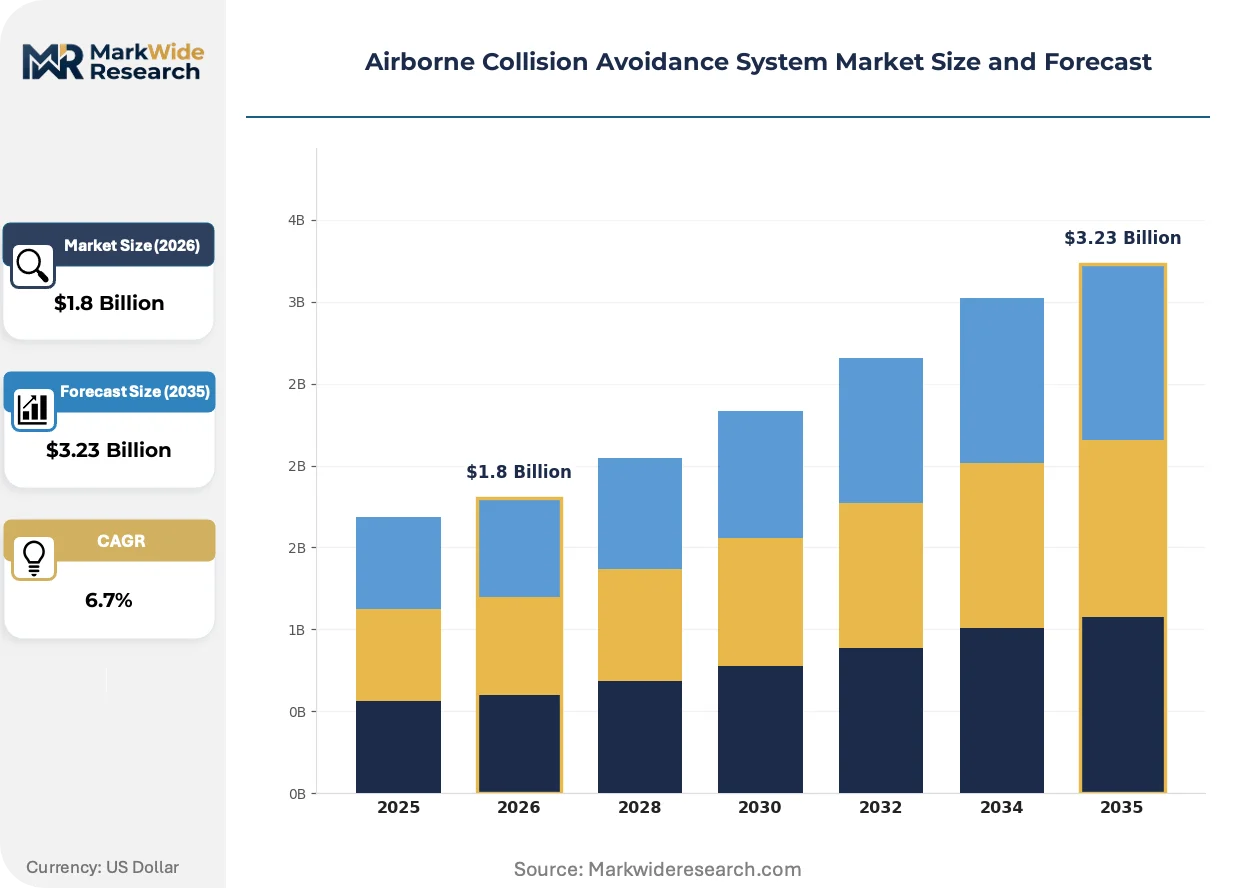
Market Dynamics
Retrofit mandates from the FAA and EASA are forcing accelerated hardware replacement across aging commercial fleets, compressing procurement cycles and reshaping supplier relationships throughout the value chain.
Growth Catalysts
- ADS-B Out Mandates:The FAA's 14 CFR 91.225 requirement compels operators to replace legacy Mode C transponders, generating sustained equipment demand across the United States.
- Trajectory-Based Operations:EUROCONTROL's framework in Europe drives next-generation surveillance infrastructure investment among legacy carriers retrofitting wide-body fleets.
- UAV Integration:Unmanned platform proliferation creates parallel demand streams for detect-and-avoid systems in both defense and commercial drone operations.
Market Restraints
- Semiconductor Supply Concentration:Specialized RF component fabrication concentrates in East Asian foundries, exposing lead times to geopolitical disruption.
- Certification Cost Burden:DO-178C software assurance requirements for TCAS II impose substantial validation costs that deter new market entrants.
- Technical Obsolescence Risk:Rapid ADS-B protocol evolution threatens premature depreciation of hardware certified under earlier standards.
Strategic Opportunities
- Urban Air Mobility:eVTOL manufacturers in Germany and the United States seek purpose-built collision avoidance architectures for low-altitude corridor operations.
- Multi-Sensor Fusion:Convergence of radar, electro-optical, and ADS-B inputs enables jam-resistant systems for contested military environments.
- Service Contract Expansion:Airlines in China increasingly favor performance-based maintenance agreements over capital equipment purchases.
Industry Challenges
- Systems Integration Complexity:Retrofitting TCAS II onto 1990s-era avionics buses requires extensive airframe-specific engineering validation.
- Regulatory Divergence:Inconsistent detect-and-avoid standards between the FAA and EASA force redundant certification efforts for multi-market UAV platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Airborne Collision Avoidance System Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Systems, Passive Systems, Hybrid Systems, Integrative Systems Technology: Radar, Lidar, ADS-B, Visual Sensors End User: Commercial Aviation, Military Aviation, General Aviation, UAVs Application: Air Traffic Control, Flight Safety, Training, Research |
| Companies Covered | Thales Group, Lockheed Martin Corporation, BAE Systems Plc, Rockwell Collins Inc, Saab Group, Honeywell International Inc, L3Harris Technologies, Inc, FLARM Technology Ltd, Garmin Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Airborne Collision Avoidance System Market Emerging Trajectories
Sensor fusion architectures and machine-learning threat classification are redefining system performance benchmarks, while procurement models shift toward integrated lifecycle service arrangements.
Multi-static passive radar is displacing traditional monostatic configurations in next-generation military programs. Defense integrators in the United States and Europe are adopting these distributed arrays for covert surveillance. The technology is displacing legacy active radar in contested electromagnetic environments where emissions reveal platform position.
EUROCONTROL's CS-ACNS certification specifications now mandate interoperability testing across mixed-vendor environments. European operators face compressed implementation timelines as the 2030 trajectory-based operations deadline approaches. Narrow-body fleets based in Germany and France are prioritizing integrated surveillance packages that satisfy both EASA and FAA requirements simultaneously.
Airlines are consolidating avionics procurement under fleet-wide service agreements rather than transactional equipment purchases. Maintenance, repair, and overhaul providers are capturing expanded scope as original equipment manufacturers reposition toward recurring revenue streams. This consolidation is most pronounced among low-cost carriers operating standardized narrow-body fleets in the United States and China.
Airborne Collision Avoidance System Market Segmentation
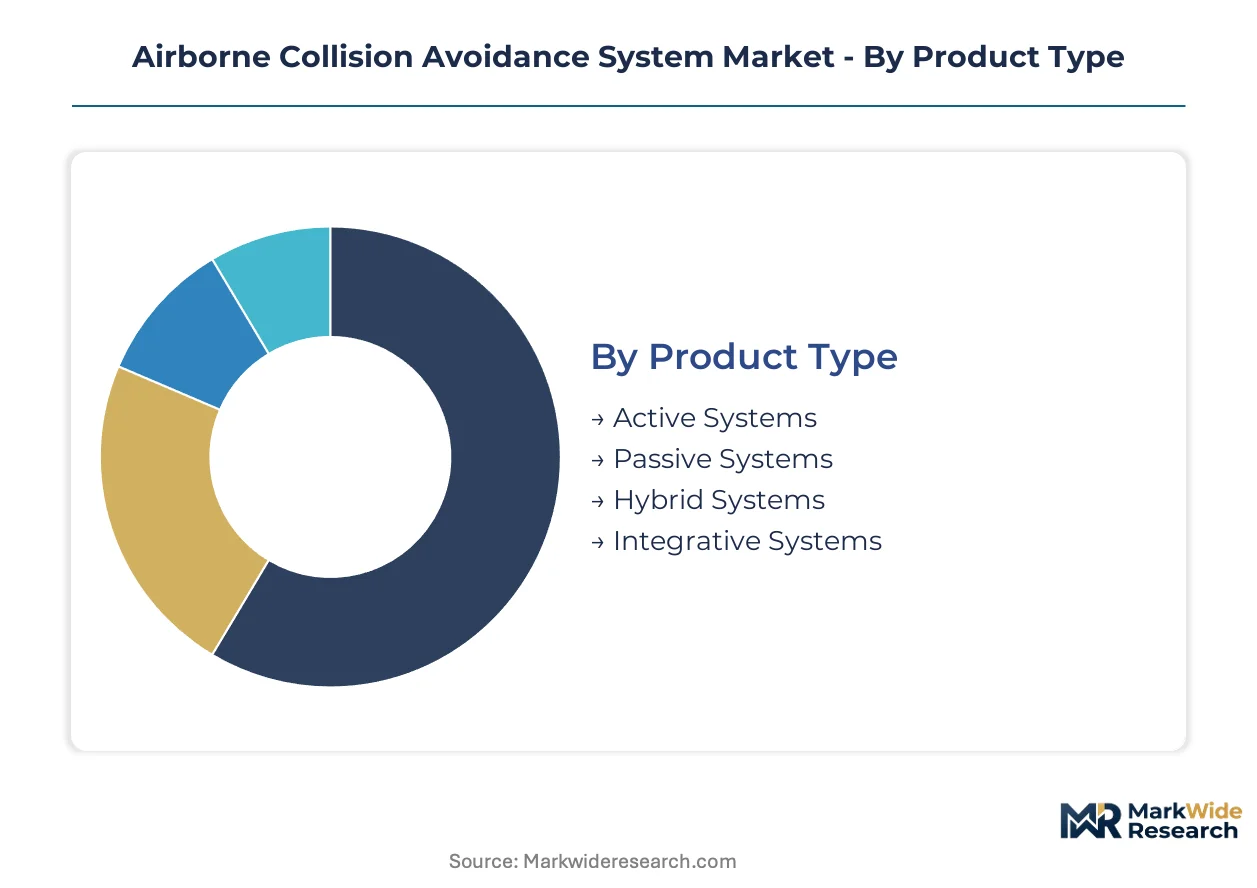
Segmentation reveals distinct procurement pathways across defense, commercial, and emerging unmanned platforms. Each category channels hardware through different certification regimes and supplier relationships.
Product Type:
Active systems flow through OEM line-fit channels and airline retrofit programs, while hybrid architectures reach military integrators via defense procurement offices.
- Active Systems:Autonomous threat detection architectures process radar and transponder inputs to generate resolution advisories without pilot intervention. Commercial airlines in the United States and Germany concentrate procurement here to satisfy FAA TCAS II and EASA CS-ACNS mandates for autonomous collision avoidance.
- Hybrid Systems:Multi-sensor fusion platforms combine radar, electro-optical, and ADS-B modalities for jam-resistant performance in contested electromagnetic environments. Military aviation programs in the United States favor these architectures where emissions control and threat diversity matter.
- Passive Systems:Non-emitting detection architectures rely on external surveillance infrastructure or cooperative transponder signals.
- Integrative Systems:Unified avionics packages embed collision avoidance within broader flight management architectures.
Active systems dominate installed base. Hybrid systems are where expansion concentrates.
Technology:
Technology selection tracks the cost-to-performance hierarchy of surveillance infrastructure, with premium tiers commanding dedicated hardware budgets and commodity tiers bundled into fleet packages.
- Radar:Primary surveillance technology for independent target acquisition in all weather conditions. Commercial wide-body retrofits in Germany and France prioritize solid-state radar upgrades as trajectory-based operations deadlines approach.
- ADS-B:Automatic dependent surveillance-broadcast enables cooperative position reporting without ground radar interrogation. UAV operators in the United States channel procurement here as the FAA's detect-and-avoid framework matures for national airspace integration.
- Lidar:Optical ranging systems provide precision separation data for low-altitude urban operations.
- Visual Sensors:Electro-optical and infrared detection for non-cooperative traffic in visual flight conditions.
Radar retains the largest installed footprint. ADS-B is climbing the fastest as surveillance backbone replacement accelerates.
End User:
End-user segmentation separates capital-intensive fleet operators from fragmented owner-flier markets and emerging unmanned categories with distinct certification pathways.
- Commercial Aviation:Scheduled airlines and cargo operators operating transport-category aircraft under Part 121 or equivalent regulations. Narrow-body fleet standardization in China drives volume procurement through maintenance, repair, and overhaul service agreements rather than direct equipment purchases.
- UAVs:Unmanned platforms spanning defense reconnaissance, commercial delivery, and industrial inspection missions. Regulatory divergence between FAA and EASA detect-and-avoid standards fragments procurement for multi-market platforms, forcing redundant certification investments.
- Military Aviation:Defense platforms requiring contested-airspace survivability and multi-domain interoperability.
- General Aviation:Private and business aircraft operating under less stringent equipage requirements.
Commercial aviation anchors equipment revenue. UAVs represent the steepest expansion trajectory as regulatory frameworks mature.
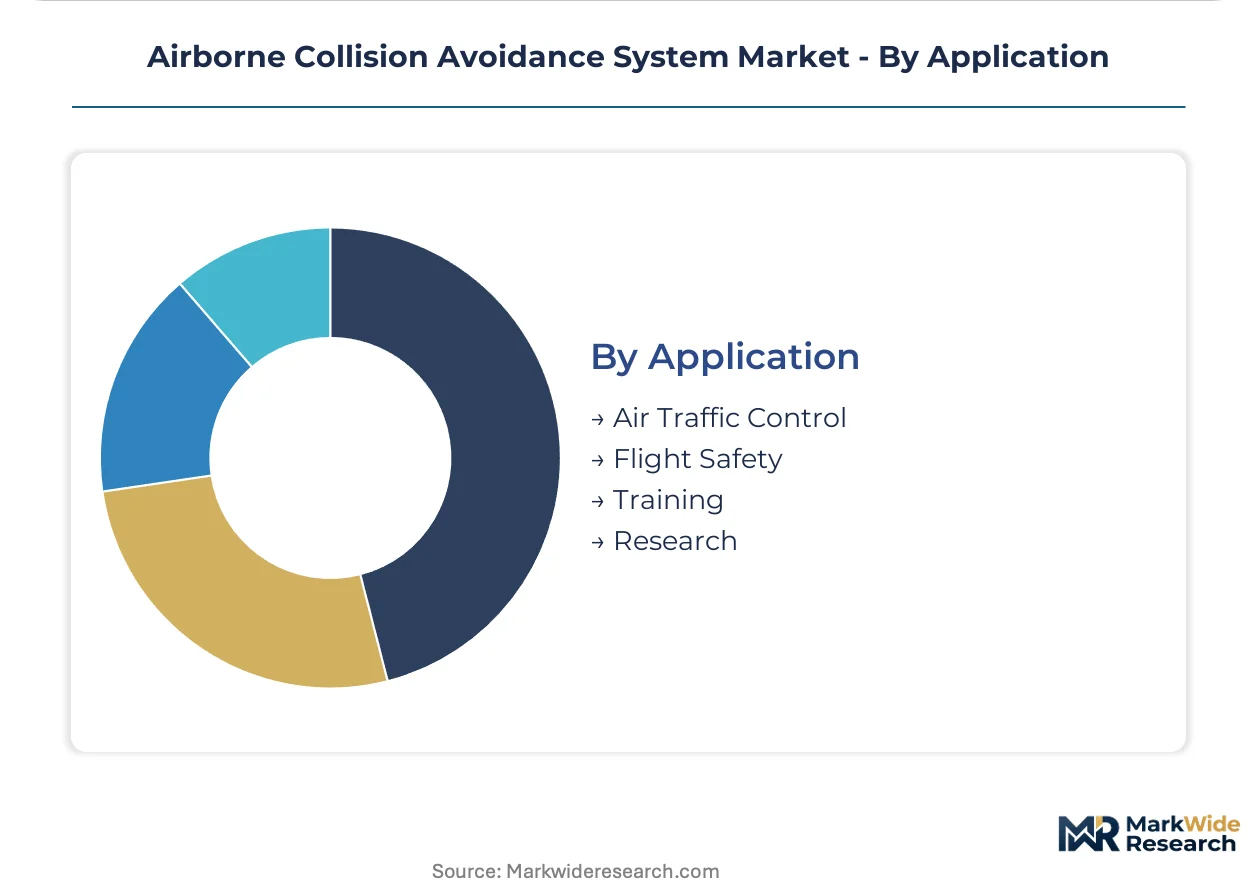
Application:
Application scope distinguishes operational safety systems from infrastructure-dependent traffic management and non-recurring research procurement.
- Flight Safety:Onboard collision avoidance providing direct pilot alerting and resolution guidance. eVTOL manufacturers in Germany and the United States concentrate demand here for purpose-built low-altitude corridor architectures.
- Air Traffic Control:Ground-based surveillance and separation assurance infrastructure. EUROCONTROL's trajectory-based operations framework in Europe drives next-generation surveillance investment among legacy carriers retrofitting wide-body fleets.
- Training:Simulation and instructional platforms for crew proficiency and certification.
- Research:Experimental systems for algorithm validation and next-generation concept development.
Flight safety commands the deepest equipment integration. Air traffic control is gaining share fastest as surveillance infrastructure modernization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial airlines and defense integrators concentrate procurement in four countries with the largest installed bases of transport-category aircraft and unmanned platforms. Regulatory mandates in each jurisdiction compress replacement cycles and reshape supplier relationships.
United States
The FAA's ADS-B Out requirement under 14 CFR 91.225 compels operators to replace legacy Mode C transponders, generating sustained equipment demand across commercial and general aviation fleets. Military aviation programs favor hybrid architectures that fuse multiple sensor modalities for contested airspace performance. Dallas-Fort Worth anchors a cluster of avionics integrators serving both Boeing platform line-fit programs and airline retrofit contracts.
Germany
EUROCONTROL's trajectory-based operations framework drives next-generation surveillance infrastructure investment among legacy carriers retrofitting wide-body fleets. The country's central bank and federal aviation authority coordinate financing mechanisms for fleet modernization programs. Hamburg concentrates maritime-aerospace crossover engineering talent supporting multi-sensor fusion development for jam-resistant military applications.
China
Airlines increasingly favor performance-based maintenance agreements over capital equipment purchases, consolidating procurement under fleet-wide service arrangements. The country's civil aviation regulator accelerates detect-and-avoid framework maturation for unmanned platform integration into national airspace. Tianjin hosts a manufacturing cluster where narrow-body fleet standardization drives volume procurement through maintenance, repair, and overhaul providers.
France
EASA enforces CS-ACNS certification specifications mandating interoperability testing across mixed-vendor environments, compressing implementation timelines as the 2030 deadline approaches. The country's defense procurement agency channels multi-static passive radar adoption for covert surveillance in contested electromagnetic environments. Toulouse anchors Airbus platform engineering integration where integrated surveillance packages satisfy both EASA and FAA requirements simultaneously.
United Kingdom
Defense integrators adopt distributed radar arrays for emissions-controlled operations where platform concealment matters. The country's military aviation authority prioritizes contested-airspace survivability specifications in procurement tenders. Farnborough concentrates systems engineering expertise supporting hybrid architecture validation for multi-domain interoperability programs.
Airborne Collision Avoidance System Market Vendor Landscape
Player mix skews toward diversified aerospace conglomerates with established certification coverage across Boeing and Airbus platforms. The vendor base stratifies across three tiers: prime contractors with full-spectrum avionics portfolios, defense specialists with military-grade integrative capabilities, and component suppliers focused on specific sensor modalities. Strategic moves concentrate on portfolio diversification into unmanned platform detect-and-avoid systems and geographic expansion through maintenance service contract capture.
Within the prime contractor tier, Thales Group and Honeywell International Inc exemplify archetypes with broad regulatory certification spanning multiple jurisdictions. L3Harris Technologies, Inc occupies a position among defense specialists with contested-environment system integration expertise. These three anchors represent the competitive structure: European conglomerates leveraging radar heritage, US-based diversified avionics manufacturers, and military-focused integrators addressing hybrid architecture demand.
| Leading Market Players |
|---|
| Thales Group |
| Lockheed Martin Corporation |
| BAE Systems Plc |
| Rockwell Collins Inc |
| Saab Group |
| Honeywell International Inc |
| L3Harris Technologies, Inc |
| FLARM Technology Ltd |
| Garmin Ltd |
| Others |
Supply Flow & Price Mechanics
Long-term fleet service agreements lock in multi-year hardware procurement commitments for airlines in China and the United States, anchoring both supplier capacity allocation and predictable unit economics across the analysis window. These contract structures bundle equipment, installation, and maintenance into performance-based arrangements that compress price volatility for buyers while securing revenue visibility for avionics integrators.
Pricing Analysis
Cost-plus contracts with semiconductor indexation dominate component sourcing for RF modules and processor boards, tying hardware pricing to foundry capacity costs in Taiwan and South Korea. Three-tier pricing structure across TCAS II line-fit, retrofit upgrade, and aftermarket replacement levels reflects certification grade differentiation and volume scale. Pricing pressure stems from airline procurement consolidation under MRO service agreements in China. Low-cost carriers operating standardized narrow-body fleets exhibit highest price sensitivity, while defense integrators in the United States accept premium tiers for contested-environment performance specifications.
Supply Chain Analysis
Inventory lead times for specialized RF components stretch 40-52 weeks, exposing procurement cycles to disruption from foundry concentration in Taiwan, South Korea, and Japan. Gallium nitride semiconductors, precision aluminum radar housings, and DO-178C certified software modules constitute critical input dependencies. Single-source vulnerability concentrates in advanced node fabrication for military-grade processors. Distribution runs through OEM line-fit channels for Boeing and Airbus platforms, with aftermarket retrofit procurement consolidating under airline-MRO service partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through fleet-wide service agreement consolidation among low-cost carriers in China and the United States, fragmenting direct equipment procurement and shifting margin capture toward maintenance providers.
For Market Incumbents: Fortify certification coverage across both FAA TCAS II and EASA CS-ACNS specifications to prevent displacement by multi-market competitors. Deepen backward integration into RF component supply through captive sourcing agreements with Taiwanese foundries, mitigating semiconductor lead-time volatility. Prioritize detect-and-avoid system development for UAV integration as regulatory frameworks mature in the United States. For New Entrants and Emerging Players: Differentiate on purpose-built architectures for urban air mobility corridors serving eVTOL manufacturers in Germany and the United States, where incumbent radar portfolios lack low-altitude optimization. Target unmanned platform detect-and-avoid procurement as the most penetrable segment, given regulatory divergence fragments incumbent certification advantages. Pursue partnership-based go-to-market models with MRO providers in China to bypass direct airline procurement consolidation. For Investors and Strategic Acquirers: Defense-focused integrators with contested-environment multi-sensor fusion capabilities represent the most defensible acquisition archetype, given military procurement prioritizes jam-resistant performance over cost optimization. Long-term viability hinges on positioning against UAV integration timelines and trajectory-based operations mandates. Monitor FAA detect-and-avoid framework finalization as the critical inflection signal for unmanned platform market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Sensor Fusion Development | Enables jam-resistant performance for contested airspace operations demanded by US military programs. |
| Detect-and-Avoid Certification | Unlocks UAV integration into national airspace as FAA and EASA frameworks mature. |
| Fleet Service Agreement Capture | Secures recurring revenue streams from airline procurement consolidation in China and the United States. |
| Dual-Jurisdiction Certification | Reduces redundant engineering validation for platforms serving both FAA and EASA mandates simultaneously. |
| Passive Radar Architecture Adoption | Supports emissions-controlled surveillance requirements in European defense procurement tenders. |
Methodological Framework
The analysis maps active collision avoidance, hybrid military architectures, ADS-B surveillance infrastructure, and UAV detect-and-avoid sub-sectors, each validated through avionics procurement directors, airline fleet managers, defense program officers, and MRO contract specialists. Primary fieldwork combined structured interviews with secondary validation against FAA ADS-B implementation databases, EASA certification filings, EUROCONTROL trajectory-based operations documentation, and customs trade records for avionics components. Bottom-up equipment shipment tracking and top-down fleet retrofit requirement modeling were triangulated against regulatory mandate timelines.
Consistency checks validated volume and value outputs against external benchmarks including fleet age profiles from aviation authorities and defense procurement budget disclosures. The analytical framework modeled segmentation across system architecture type, surveillance technology modality, end-user category, and application scope throughout the projection horizon. CAGRs were derived from equipment replacement cycle analysis tied to regulatory compliance deadlines and fleet expansion programs. Forecast inputs incorporated semiconductor supply lead-time trajectories and detect-and-avoid regulatory development status.
Decision-makers should treat outputs as directional under assumptions of stable FAA and EASA mandate enforcement timelines and continued airline fleet standardization trends; material deviation in regulatory implementation or supply chain disruption would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Safety Systems
Aviation Life Rafts Market
Aircraft Safety Systems
Aircraft Arresting System Market
Aircraft Safety Systems
Aerospace & Aircraft Collision Avoidance System Market
Aircraft Safety Systems
Aerospace Lightning Strike Protection Market
Aircraft Safety Systems
Aircraft Smoke Detection and Fire Extinguishing System Market
Aircraft Safety Systems
Military Airborne Collision Avoidance Systems (ACAS) Market
Aircraft Safety Systems
Commercial Parachute Market
Aircraft Safety Systems
Aircraft Lightning Protection Market
Aircraft Safety Systems
HUD Helmet Market
Aircraft Safety Systems
Commercial Aircraft Collision Avoidance System Market
Aircraft Safety Systems
Identification Friend or Foe Systems Market
Aircraft Safety Systems
Global Aircraft Brakes Market
Aircraft Safety Systems
Aircraft Braking System Market
Aircraft Safety Systems
Aircraft Door Dampers Market
Aircraft Safety Systems
Commercial Aircraft Evacuation System Market
Aircraft Safety Systems
South Korea Aircraft Windshield Wiper and Washer System Market