
 Aircraft Evacuation Systems Market | 2026-2036
Aircraft Evacuation Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Evacuation Systems Market Analysis
North American aerospace manufacturing capacity is reconfiguring around next-generation narrowbody programs. Collins Aerospace leverages its integrated propulsion and interiors portfolio to dominate evacuation slide production for Boeing platforms. Safran sustains competitive positioning through European regulatory relationships and Airbus supply chain proximity. Martin-Baker anchors military ejection and evacuation capabilities, extending its specialization into rotary-wing emergency systems for defense operators.
Aircraft evacuation systems comprise inflatable slides, life rafts, emergency exits, and deployment mechanisms engineered to evacuate occupants within regulatory time limits, typically utilizing coated fabric assemblies rated for thermal resistance and puncture tolerance under load. These systems serve the fundamental commercial purpose of passenger and crew survival during unplanned ground or water emergencies. Slide systems occupy the largest value share given their mandatory fitment on all transport-category aircraft, while raft systems command premium positioning in overwater-configured fleets. Aftermarket and maintenance installations represent a structurally expanding segment as aging global fleets require periodic recertification and component replacement.
FAA certification under 14 CFR Part 25 and EASA CS-25 standards govern evacuation system performance, mandating full-scale demonstration tests that shape product development cycles and supplier qualification timelines. The EU AI Act and CSRD disclosure requirements are beginning to influence supply chain documentation and materials traceability for European-registered equipment. Stakeholders must monitor how emerging sustainable aviation mandates from regulators including EPA and MEE will reshape fabric chemistry and end-of-life disposal protocols for inflatable evacuation assets.
Market Dynamics
Fleet modernization mandates and tightening evacuation certification timelines are compressing supplier qualification windows while concentrating procurement authority at major OEMs.
Growth Catalysts
- FAA Part 25 Amendment:Updated full-scale evacuation demonstration requirements are forcing carriers to replace aging slide systems with certified next-generation equipment, expanding aftermarket demand.
- Coated fabric thermal resistance:Advanced polymer formulations meeting puncture tolerance under load specifications are extending system service intervals and reducing lifecycle costs for operators.
- United States narrowbody production:Boeing's next-generation single-aisle programs are driving OEM procurement volumes for integrated evacuation systems at final assembly.
Market Restraints
- Specialized coated fabric supply:Raw material concentration among limited qualified suppliers creates input cost volatility and delivery uncertainty for inflatable assembly manufacturers.
- EASA CS-25 certification timeline:Extended full-scale demonstration test cycles and documentation requirements stretch product development schedules, delaying revenue recognition.
- Fixed-base simulator training:Virtual evacuation training systems are reducing physical slide deployment frequency in crew certification, compressing replacement cycle visibility.
Strategic Opportunities
- India commercial aviation expansion:IndiGo and Air India's fleet growth programs are creating first-tier supplier qualification opportunities for evacuation system specialists.
- EU AI Act documentation:Automated inspection and predictive maintenance algorithms for inflatable assets are opening software-enabled service revenue streams.
- Rotary-wing emergency systems:Military and offshore helicopter operators are adopting adapted slide-raft configurations for water ditching scenarios.
Industry Challenges
- Certified technician scarcity:FAA-authorized evacuation system inspectors and repair specialists are concentrated at legacy maintenance hubs, constraining field service expansion.
- Legacy fleet integration:New lightweight slide designs must interface with decades-old door frame geometries and deployment mechanisms without structural modification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Evacuation Systems Market |
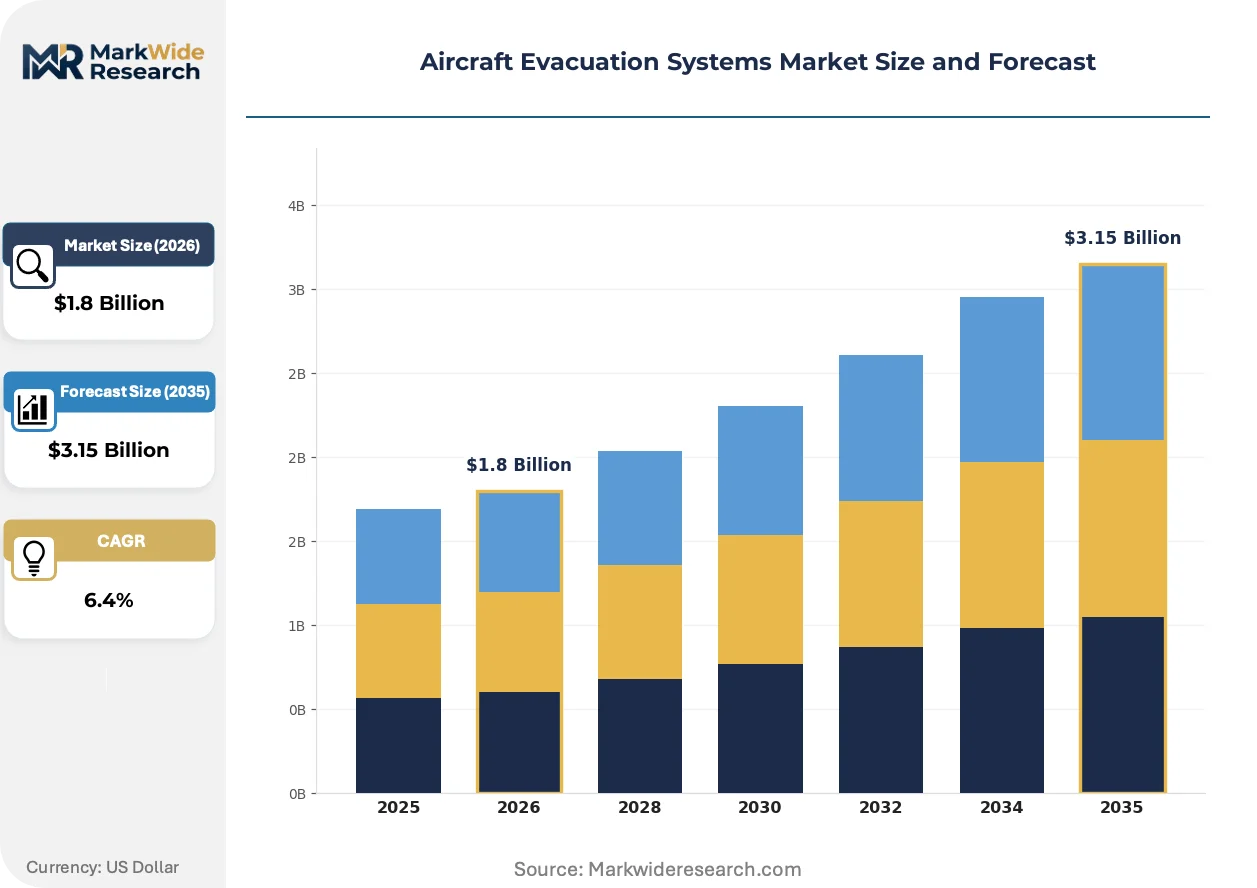
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Slide Systems, Raft Systems, Emergency Exits, Evacuation Chutes End User: Airlines, Military, Charter Operators, Private Aviation Installation Type: OEM, Aftermarket, Maintenance, Retrofits Deployment Model: Commercial Aviation, General Aviation, Cargo Aircraft, Business Jets |
| Companies Covered | Collins Aerospace, EAM Worldwide, Survitec Group, Safran, Zodiac Aerospace, Trelleborg, Martin-Baker, Dart Aerospace, Honeywell International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Evacuation Systems Market Emerging Trajectories
Smart materials and automated inspection protocols are transforming how evacuation systems are manufactured, certified, and maintained across the aviation value chain.
Embedded fiber-optic sensing networks within inflatable slide assemblies are digitizing structural health monitoring. Major carriers are piloting real-time pressure and fabric integrity telemetry during routine maintenance checks. This capability is digitizing condition-based replacement schedules, compressing the traditional time-based overhaul model.
REACH chemical substance restrictions and the EU Green Deal sustainable aviation mandates are reshaping coated fabric chemistry specifications. European-registered equipment must now demonstrate full materials traceability and end-of-life recyclability. Suppliers serving Airbus and European operators are reformulating polymer coatings to eliminate restricted substances while maintaining thermal and puncture performance.
Airline procurement departments are consolidating evacuation system purchasing under fleet-wide lifecycle contracts. Single-source agreements spanning initial fitment through 15-year maintenance are displacing transactional component orders. This concentration is most visible among United States legacy carriers managing mixed Boeing and Airbus fleets under unified supplier frameworks.
Aircraft Evacuation Systems Market Segmentation
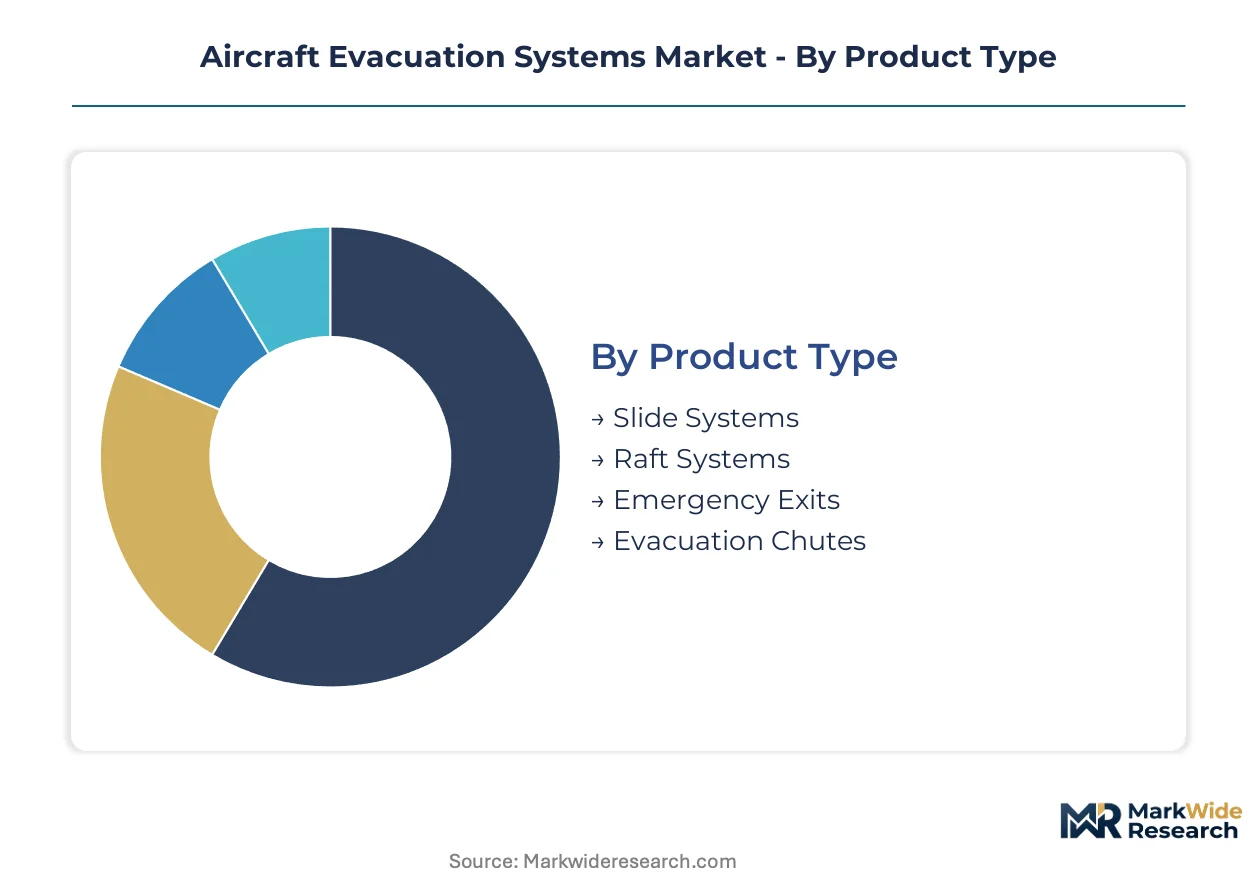
Evacuation system procurement patterns diverge sharply across product architectures and operator types, with certification requirements and fleet age creating distinct demand profiles for each segment. Understanding these fault lines reveals where supplier qualification investments concentrate and which installation channels offer structural expansion potential.
Product Type:
Mature slide architectures dominate current fleet fitments while raft configurations emerge as the premium growth vector for overwater route expansion.
- Slide Systems:Inflatable coated-fiber assemblies deploy from door and overwing exits to create egress pathways meeting FAA Part 25 90-second evacuation mandates. Narrowbody production lines at Boeing's Renton facility and Airbus's Toulouse complex drive OEM procurement concentration for single-aisle platforms.
- Raft Systems:Dual-purpose slide-raft combinations support water ditching scenarios through integrated flotation chambers and canopy shelters. Demand concentrates among transpacific and transatlantic carriers configuring widebody fleets for extended overwater operations under EASA CS-25 ditching provisions.
- Emergency Exits:Plug-type and hinged door mechanisms with integrated lighting and assist handles.
- Evacuation Chutes:Compact deployment systems for cargo decks and upper deck configurations on multi-level aircraft.
Slide systems handle the majority of throughput; raft systems are gaining share fastest on long-haul fleet renewal cycles.
End User:
Volume concentration tilts toward scheduled carriers while military specifications create insulated procurement channels with divergent technical requirements.
- Airlines:Full-service and low-cost carriers operating transport-category aircraft under Part 121 certificates constitute the core demand base. United States legacy carriers consolidate procurement through fleet-wide lifecycle contracts spanning initial fitment through 15-year maintenance intervals.
- Military:Defense operators require ejection seats, troop egress systems, and rotary-wing emergency equipment meeting MIL-STD-810 environmental specifications. Specialized suppliers anchor this segment through sole-source relationships with airframe primes.
- Charter Operators:Fractional ownership and on-demand services with mixed fleet age profiles.
- Private Aviation:Owner-operated turbine aircraft with customized cabin configurations.
Airlines absorb the dominant procurement volume; military specifications are expanding most quickly on rotorcraft modernization programs.
Installation Type:
Channel economics favor long-cycle aftermarket relationships over transactional OEM placements as fleet age demographics shift.
- OEM:Factory-fit systems installed during final assembly at airframe manufacturer facilities. Boeing's next-generation narrowbody programs and Airbus A320 family production lines concentrate procurement authority with tier-one integrators.
- Aftermarket:Replacement and upgrade installations during heavy maintenance checks. Aging global fleets require periodic recertification and component replacement, extending revenue visibility for qualified maintenance providers.
- Maintenance:Scheduled overhaul and inspection services under continuing airworthiness programs.
- Retrofits:Door modification and slide system upgrades to meet amended certification standards.
Aftermarket channels now match OEM volume on mature fleet demographics; retrofits show the steepest expansion trajectory on regulatory amendment cycles.
Deployment Model:
Operational intensity and passenger density create divergent specification requirements across aviation subsectors.
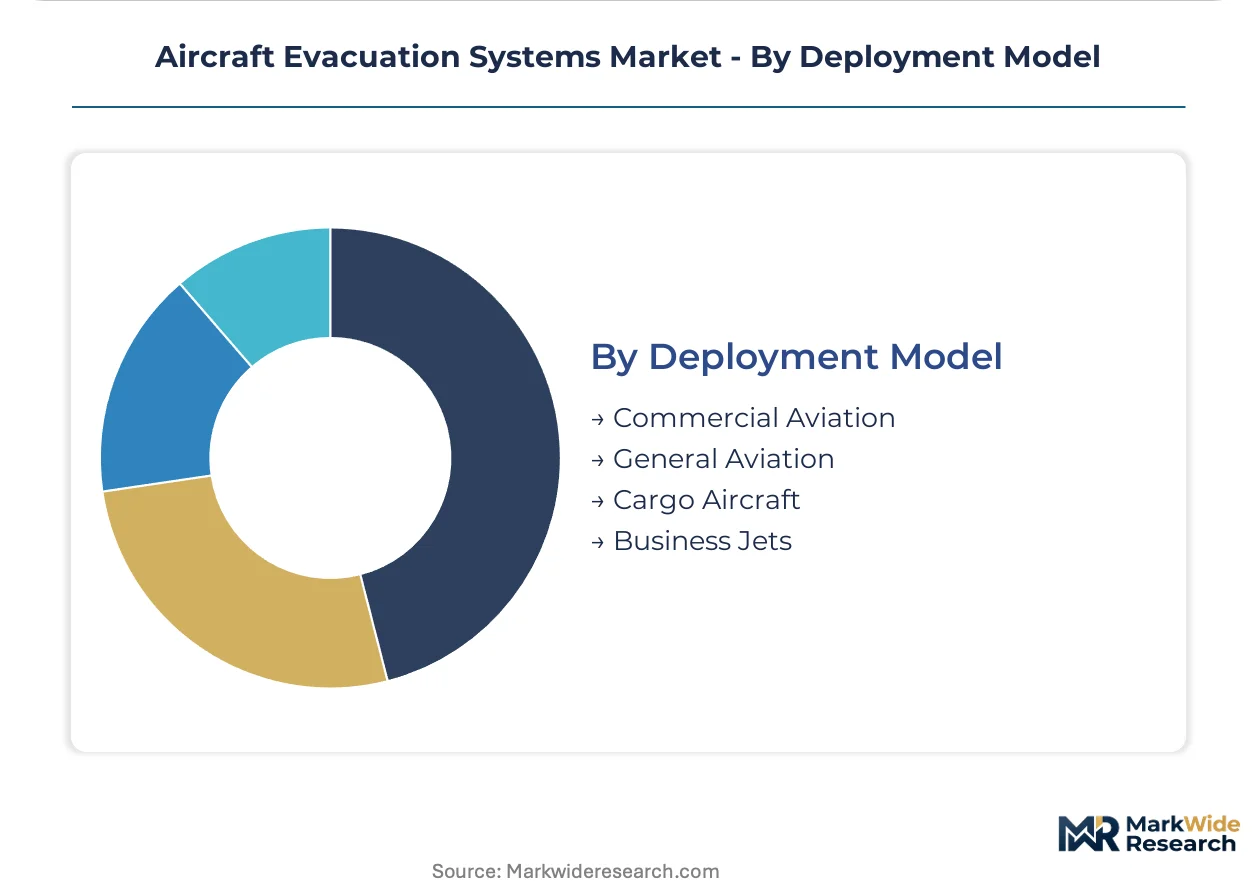
- Commercial Aviation:High-cycle operations with maximum certified passenger loads drive redundant slide configurations and accelerated replacement schedules. FAA-mandated full-scale evacuation demonstrations shape product development cycles for this segment.
- General Aviation:Lower-density operations with simplified egress requirements and reduced regulatory demonstration burdens.
- Cargo Aircraft:Freighter conversions and dedicated cargo platforms with crew-only evacuation scenarios.
- Business Jets:Custom cabin layouts with overwing exit and airstair configurations.
Commercial aviation commands the dominant specification intensity; cargo conversions are climbing fastest on e-commerce-driven freighter demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Evacuation system procurement patterns diverge sharply by geography, with mature aviation markets emphasizing aftermarket recertification while emerging economies concentrate on first-fit OEM installations for expanding fleets.
United States
Boeing's Renton and Everett production lines drive concentrated OEM demand for narrowbody and widebody evacuation systems. FAA Part 25 certification mandates shape supplier qualification timelines, with full-scale evacuation demonstrations required for all new installations. The Pacific Northwest aerospace cluster anchors domestic manufacturing capacity for coated-fiber assemblies.
Germany
Lufthansa Technik's heavy maintenance operations generate substantial aftermarket volume for slide system overhaul and recertification. EASA CS-25 standards govern all equipment approvals, with REACH chemical compliance increasingly influencing fabric chemistry specifications. The Hamburg aviation cluster houses specialized evacuation system service facilities serving European-registered fleets.
France
Airbus Toulouse final assembly lines concentrate OEM procurement for A320 and A350 family evacuation equipment. The EU AI Act documentation requirements are reshaping supply chain traceability protocols for inflatable assets. The Occitanie region hosts tier-one integrators supplying integrated door and slide systems.
China
COMAC C919 production ramp-up is creating qualification opportunities for domestic and foreign evacuation system suppliers. MIIT certification processes and GB standards compliance govern equipment approvals for Chinese-registered aircraft. The Yangtze River Delta aerospace cluster is developing indigenous coated-fiber manufacturing capacity.
India
IndiGo and Air India fleet expansion programs are driving first-fit procurement for both narrowbody and widebody platforms. DGFT import regulations and BIS quality standards shape supplier entry pathways. The Delhi-NCR aviation maintenance corridor is attracting evacuation system specialists establishing regional service capabilities.
Aircraft Evacuation Systems Market Vendor Landscape
Capability concentration sits with integrated aerospace primes; scale advantage sits with specialized evacuation equipment suppliers. The vendor base organizes into two functional tiers: full-service aerospace conglomerates controlling OEM channels, and dedicated safety equipment specialists dominating aftermarket and military segments. Three archetypes define competitive positioning: integrated propulsion-interiors portfolios, European regulatory-aligned specialists, and military-anchored egress system providers. Consolidation through strategic acquisitions and long-term fleet lifecycle contracts represent the dominant competitive moves reshaping supplier relationships.
Within the integrated aerospace tier, Collins Aerospace and Safran exemplify full-service positioning through proximity to Boeing and Airbus final assembly lines respectively. Martin-Baker occupies a distinct specialization anchor in military ejection and rotary-wing emergency systems. These three companies represent the structural segmentation between commercial OEM integration, European regulatory alignment, and defense-specialized capabilities that defines competitive boundaries in evacuation system supply.
| Leading Market Players |
|---|
| Collins Aerospace |
| EAM Worldwide |
| Survitec Group |
| Safran |
| Zodiac Aerospace |
| Trelleborg |
| Martin-Baker |
| Dart Aerospace |
| Honeywell International |
| Others |
Supply Flow & Price Mechanics
Undercapacity in European coated-fiber manufacturing is compressing supplier margins while concentrating pricing power among qualified raw material providers serving FAA and EASA-certified assembly lines. This utilization imbalance forces evacuation system integrators to accept longer-term offtake commitments with less price flexibility than transactional spot markets would allow.
Pricing Analysis
Long-term fleet lifecycle contracts dominate procurement, with United States legacy carriers consolidating purchasing under 15-year agreements spanning initial fitment through recertification intervals. Price differentiation hinges on certification tier—FAA Part 25 versus EASA CS-25—and volume scale across mixed Boeing and Airbus fleets. Cost compression in aftermarket slide replacements is intensifying because qualified technician scarcity limits service provider competition. Low-cost carriers exhibit highest price sensitivity due to unbundled maintenance strategies, while flag carriers accept premium positioning for integrated door-slide systems with predictive maintenance telemetry.
Supply Chain Analysis
Specialized polymer feedstock production draws from Germany, France, and the United States, where REACH-compliant coated-fiber manufacturing clusters anchor qualified supplier networks. Critical inputs include aramid reinforcement fabrics, polyurethane coating formulations, and fiber-optic sensing elements for structural health monitoring. Single-source vulnerability concentrates in thermal-resistant polymer chemistry, where patent-protected formulations limit qualified alternatives. Distribution runs through tier-one aerospace integrators at Boeing Renton and Airbus Toulouse final assembly lines, with aftermarket channels feeding Lufthansa Technik and Delta TechOps heavy maintenance hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from predictive maintenance algorithms and automated inspection protocols is expanding faster than hardware replacement cycles, making software-enabled lifecycle contracts the priority investment layer for all market participants.
For Market Incumbents: Build certification moats around EU AI Act documentation requirements and CSRD materials traceability protocols. Deepen backward integration into coated-fiber manufacturing in the Pacific Northwest aerospace cluster to capture margin from raw material volatility. Anchor long-term fleet lifecycle contracts with United States narrowbody operators before next-generation production ramps accelerate. For New Entrants and Emerging Players: IndiGo and Air India fleet expansion programs in India represent the most penetrable entry point for first-tier supplier qualification outside established Boeing and Airbus supply chains. Rotary-wing emergency systems for offshore helicopter operators offer insulated demand with less OEM concentration. Pursue DGFT import compliance partnerships with Delhi-NCR maintenance corridor specialists to establish regional service credibility. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across software-enabled inspection services, where algorithm development displaces physical inventory requirements. Target mid-cap evacuation system specialists with established EASA regulatory relationships and Airbus supply chain proximity. Monitor FAA Part 25 amendment implementation timelines as inflection signals for aftermarket replacement demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coated-Fiber Manufacturing | Captures margin from REACH-compliant polymer supply concentration in European clusters. |
| Fleet Lifecycle Contract Consolidation | Locks 15-year revenue visibility with United States legacy carriers managing mixed fleets. |
| Predictive Maintenance Algorithm Development | Opens software-enabled service revenue under EU AI Act documentation requirements. |
| Rotary-Wing Emergency System Adaptation | Accesses military and offshore helicopter modernization programs with adapted slide-raft configurations. |
| India Regional Service Capability Establishment | Positions for IndiGo and Air India procurement as DGFT regulations shape supplier entry pathways. |
Methodological Framework
Cross-validation between primary interviews with evacuation system procurement directors and secondary FAA certification databases anchors the qualitative findings. This study combines discussions with OEM integration engineers, MRO facility managers, regulatory compliance officers, and coated-fiber manufacturing specialists with validation against EASA CS-25 demonstration test records, SEC filings from aerospace primes, customs trade data for polymer feedstock flows, and fleet age demographics from aviation authority registries. Bottom-up segment sizing and top-down market triangulation ensure methodological consistency.
Calibration against historical replacement cycle data and production rate announcements from Boeing and Airbus shapes the projection framework. The analytical model segments by product architecture, end-user type, installation channel, and deployment model across the analysis window. CAGRs derive from regression analysis of fleet expansion trajectories, regulatory amendment implementation schedules, and aftermarket recertification interval compression. Industry-specific inputs include narrowbody production line rates and heavy maintenance visit frequency by fleet age cohort.
Practitioners should monitor FAA Part 25 amendment implementation delays, EASA REACH chemical restriction expansions, and COMAC C919 production ramp signals for early revision triggers. Forecasts reflect assumptions about certification timeline continuity and raw material supplier qualification stability. Cross-checking against IATA fleet forecasts and OEM delivery guidance is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Safety Systems
Free Fall Sensor Market
Aircraft Safety Systems
Instrument Landing System (ILS) Market
Aircraft Safety Systems
Aircraft Braking System Market
Aircraft Safety Systems
Commercial Parachute Market
Aircraft Safety Systems
HUD Helmet Market
Aircraft Safety Systems
Airborne Collision Avoidance System Market
Aircraft Safety Systems
Global Aircraft Brakes Market
Aircraft Safety Systems
Commercial Aircraft Evacuation System Market
Aircraft Safety Systems
Commercial Aircraft Carbon Brakes Market
Aircraft Safety Systems
Aircraft Arresting System Market
Aircraft Safety Systems
Aviation Life Rafts Market
Aircraft Safety Systems
Aircraft Smoke Detection and Fire Extinguishing System Market
Aircraft Safety Systems
Helicopter Ice Protection Systems Market
Aircraft Safety Systems
Aerospace Lightning Strike Protection Market
Aircraft Safety Systems
Cloud-Connected Aircraft Safety Data Management Platforms Market
Aircraft Safety Systems
Military Aircraft Collision Avoidance Systems Market