
 Aviation Life Rafts Market | 2026-2036
Aviation Life Rafts Market Size, Share, and Industry Trends Forecast 2026-2036
Aviation Life Rafts Market Analysis
Aftermarket service revenue is reconfiguring how manufacturers capture lifetime value from aviation life raft fleets. Survitec Group Limited leverages its global service station network to anchor recurring inspection and repack contracts. Safran competes through integrated survival systems that bundle rafts with emergency beacons and evacuation slides. Winslow LifeRaft Company specializes in handcrafted marine-grade construction for private jet and helicopter operators seeking custom capacity ratings.
Aviation life rafts are self-contained flotation devices engineered from coated nylon or neoprene fabrics with carbon dioxide inflation systems, designed to sustain occupants during aircraft ditching or over-water emergencies. Self-inflating variants dominate commercial airline procurement due to sub-30-second deployment requirements under FAA TSO-C70a standards. Military aircraft end users represent the fastest-growing demand pool as defense procurement shifts toward multi-place rafts with integrated survival kits. Manual deployment systems retain share in training and recreational segments where cost sensitivity outweighs speed requirements.
FAA certification under TSO-C70a governs United States market access, while EASA CS-25 Appendix J shapes European product specifications and testing protocols. ISO 9650 standards influence procurement criteria for private aviation and helicopter operators seeking cross-border operational acceptance. Stakeholders must monitor evolving ditching survivability requirements from ICAO and national regulators as composite fuselage designs alter evacuation dynamics and raft capacity calculations.
Market Dynamics
EASA's stricter ditching survivability mandates are compressing product refresh cycles as airlines retrofit fleets ahead of compliance deadlines. This regulatory pressure cascades through procurement budgets, forcing trade-offs between capacity upgrades and maintenance deferrals.
Growth Catalysts
- TSO-C70a Certification Thresholds:FAA's deployment speed requirements below 30 seconds are eliminating manual systems from commercial airline tenders. Carriers face non-negotiable replacement schedules.
- Composite Fuselage Penetration:Boeing 787 and Airbus A350 programs require recalibrated raft capacity ratings. OEMs specify multi-place configurations that integrate with altered evacuation dynamics.
- Military Multi-Place Procurement:Defense end users in the United States are consolidating purchases around integrated survival kits. This specification shift favors vendors with captive beacon and slide manufacturing.
Market Restraints
- Neoprene Feedstock Volatility:Petroleum-derived coated fabrics represent 35-45% of bill-of-materials costs. Asian chemical suppliers concentrate production, exposing manufacturers to input price swings.
- Inspection Station Geography:FAA-certified repack facilities cluster in Texas, Florida, and California. Operators in Mountain and Pacific Northwest states face logistics premiums or extended AOG risk.
- ISO 9650 Fragmentation:Private aviation buyers demand cross-border operational acceptance. Dual-certification requirements inflate development timelines without expanding addressable demand.
Strategic Opportunities
- Helicopter Offshore Expansion:Gulf of Mexico and North Sea energy transport operators specify compact 4-6 person rafts. Winslow LifeRaft Company's marine-grade construction commands premium positioning.
- CSRD Reporting Alignment:European carriers must document safety equipment lifecycle emissions. Vendors offering carbon footprinted supply chains capture ESG-mandated procurement.
- Beacon-Raft Convergence:Integration of 406 MHz ELTs with inflation systems reduces installation complexity. Safran's bundled survival systems demonstrate this architecture's procurement efficiency.
Industry Challenges
- FAA-EASA Harmonization Gaps:Divergent testing protocols for wave impact and thermal exposure force parallel certification tracks. Development teams duplicate validation spend.
- Legacy Fleet Documentation:Pre-2000 installations lack digital configuration records. Retrofit quoting requires physical inspection, compressing margin on small-batch orders.
- Survival Kit Integration:Desalination, signaling, and medical components sourced from disparate vendors create BOM synchronization risk. Final assembly bears liability for subsystem failures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aviation Life Rafts Market |
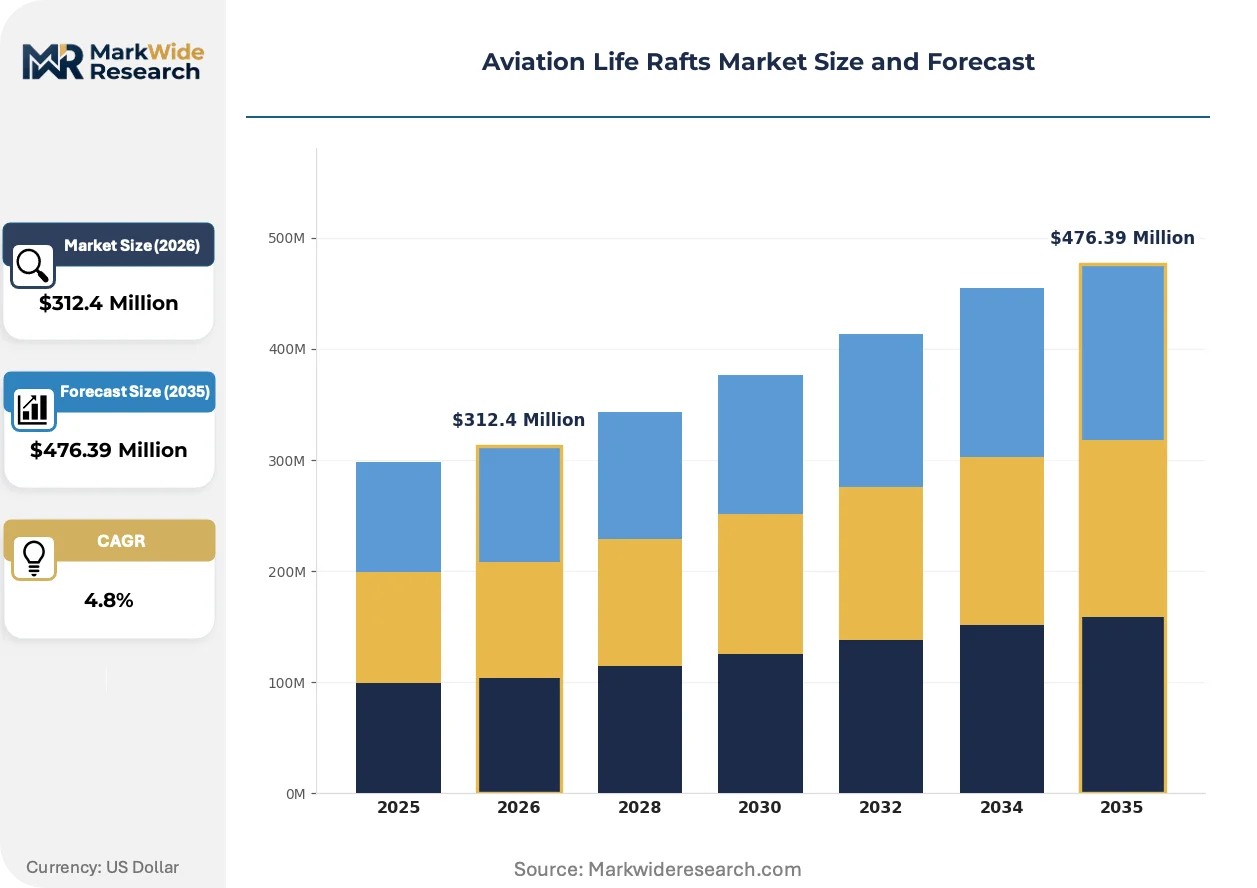
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $476.39 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Inflating, Manual, Buoyancy Tubes, Survival Rafts End User: Commercial Airlines, Private Jets, Military Aircraft, Helicopters Deployment Type: Emergency, Survival, Training, Recreational Regulatory Compliance: FAA Certified, ISO Standards, DOT Regulations, Others |
| Companies Covered | Survitec Group Limited, EAM Worldwide, Safran, Life Support International, Inc., Revere Survival Inc., Winslow LifeRaft Company, Plastimo, Switlik Parachute Company, VIKING LifeSaving Equipment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aviation Life Rafts Market Emerging Trajectories
Aviation life raft engineering is pivoting from standalone flotation devices toward integrated survival ecosystems. Material science advances and regulatory precision are compressing the gap between certification minimums and operational reliability expectations.
Carbon dioxide inflation systems are migrating from single-chamber architectures to redundant dual-chamber designs. Commercial airlines operating transoceanic routes specify this configuration to satisfy ETOPS extended-range requirements. The technology is migrating from premium long-haul configurations into narrowbody retrofit programs as FAA field experience validates reliability claims.
EASA CS-25 Appendix J amendments now mandate dynamic wave tank testing for all new type certifications. Manufacturers must demonstrate 24-hour occupant survivability in Sea State 4 conditions. European carriers with mixed fleet profiles are consolidating procurement around vendors with in-house hydrodynamic testing capabilities.
Aftermarket service unbundling is fragmenting traditional OEM-captive relationships. Airlines with internal technical operations now solicit third-party inspection and repack contracts through competitive tender. This pattern concentrates in the United States where Survitec's station network competes with independent FAA Part 145 repair stations on turnaround time and documentation quality.
Aviation Life Rafts Market Segmentation
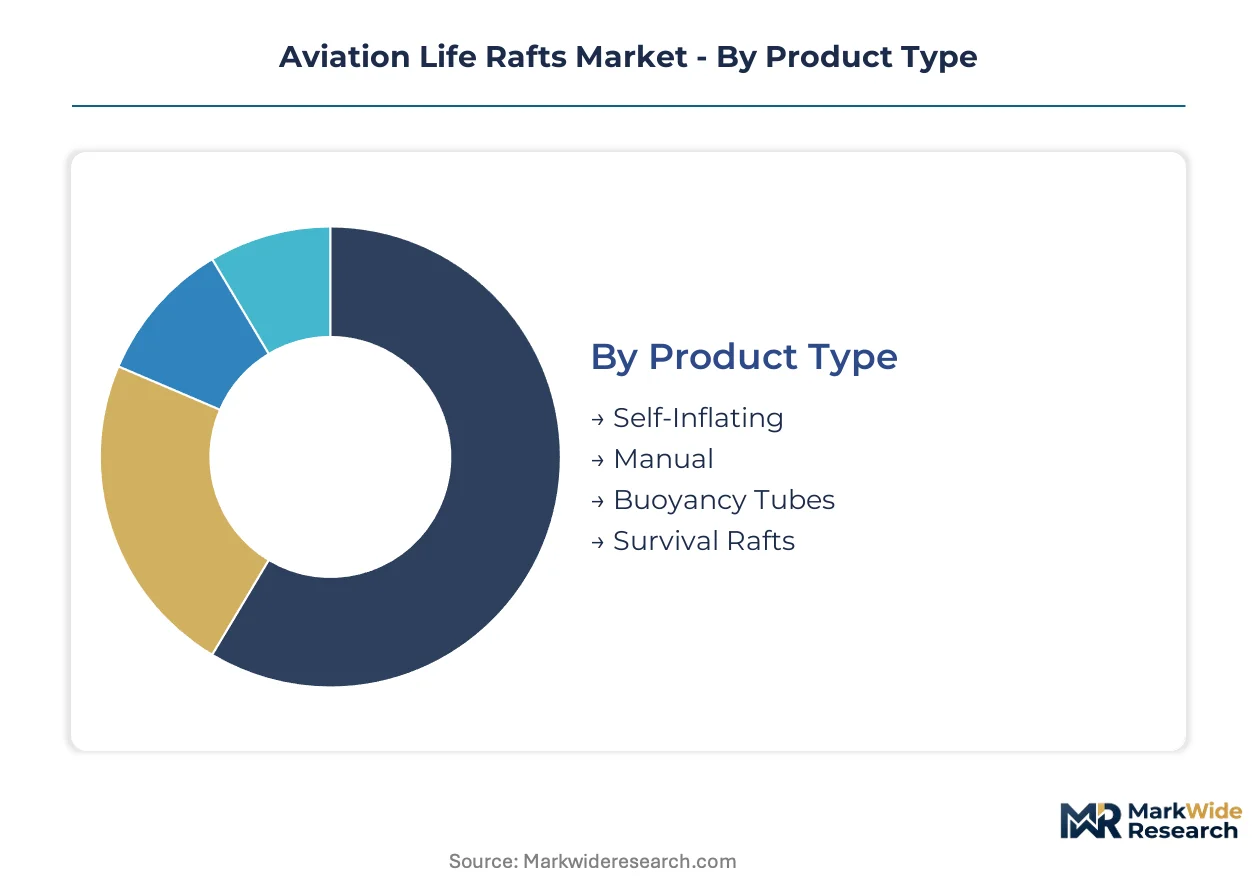
Aviation life raft procurement patterns diverge sharply across operational contexts. Regulatory mandates, deployment speed requirements, and fleet composition dictate specification choices that segment manufacturers into distinct competitive arenas.
Product Type:
Use-case spectrum spans sub-30-second emergency deployment to cost-driven training applications where speed is secondary.
- Self-Inflating:Carbon dioxide inflation systems activate automatically upon water contact, meeting FAA TSO-C70a sub-30-second deployment thresholds. Commercial airlines operating transoceanic routes specify these for ETOPS compliance, with demand concentrating in United States retrofit programs.
- Manual:Hand-pulled inflation mechanisms trade deployment speed for cost efficiency and maintenance simplicity. Flight schools and recreational operators in cost-sensitive segments favor these systems where regulatory minimums permit.
- Buoyancy Tubes:Modular flotation chambers enable capacity scaling without full raft replacement.
- Survival Rafts:Integrated configurations bundle signaling, shelter, and medical provisions for extended isolation scenarios.
The dominant share belongs to Self-Inflating, while Survival Rafts are closing the gap fastest.
End User:
Customer type determines specification intensity, from mass-fleet standardization to bespoke capacity engineering.
- Commercial Airlines:Fleet-wide standardization drives volume procurement with non-negotiable FAA TSO-C70a certification. United States carriers dominate retrofit spending as EASA-aligned European operators accelerate fleet refresh cycles.
- Military Aircraft:Multi-place configurations with integrated survival kits command premium positioning. Defense procurement consolidation in the United States favors vendors with captive beacon and slide manufacturing capabilities.
- Private Jets:Custom capacity ratings and marine-grade construction specifications predominate.
- Helicopters:Compact 4-6 person designs serve offshore energy transport in Gulf of Mexico and North Sea corridors.
Commercial Airlines anchor procurement volume, though Military Aircraft exhibits the steepest expansion trajectory.
Deployment Type:
Application context separates life-critical emergency systems from replaceable training inventory.
- Emergency:Ditching-optimized designs prioritize single-action deployment and 24-hour occupant survivability. EASA CS-25 Appendix J wave tank testing mandates now govern European certification for these configurations.
- Survival:Extended-duration specifications integrate desalination, signaling, and thermal protection for isolation scenarios.
- Training:Repackable designs withstand repeated deployment cycles without full refurbishment.
- Recreational:Basic flotation for general aviation and private use where regulatory minima apply.
Emergency deployment claims the largest installed base, while Survival specifications gain share through integrated kit bundling.
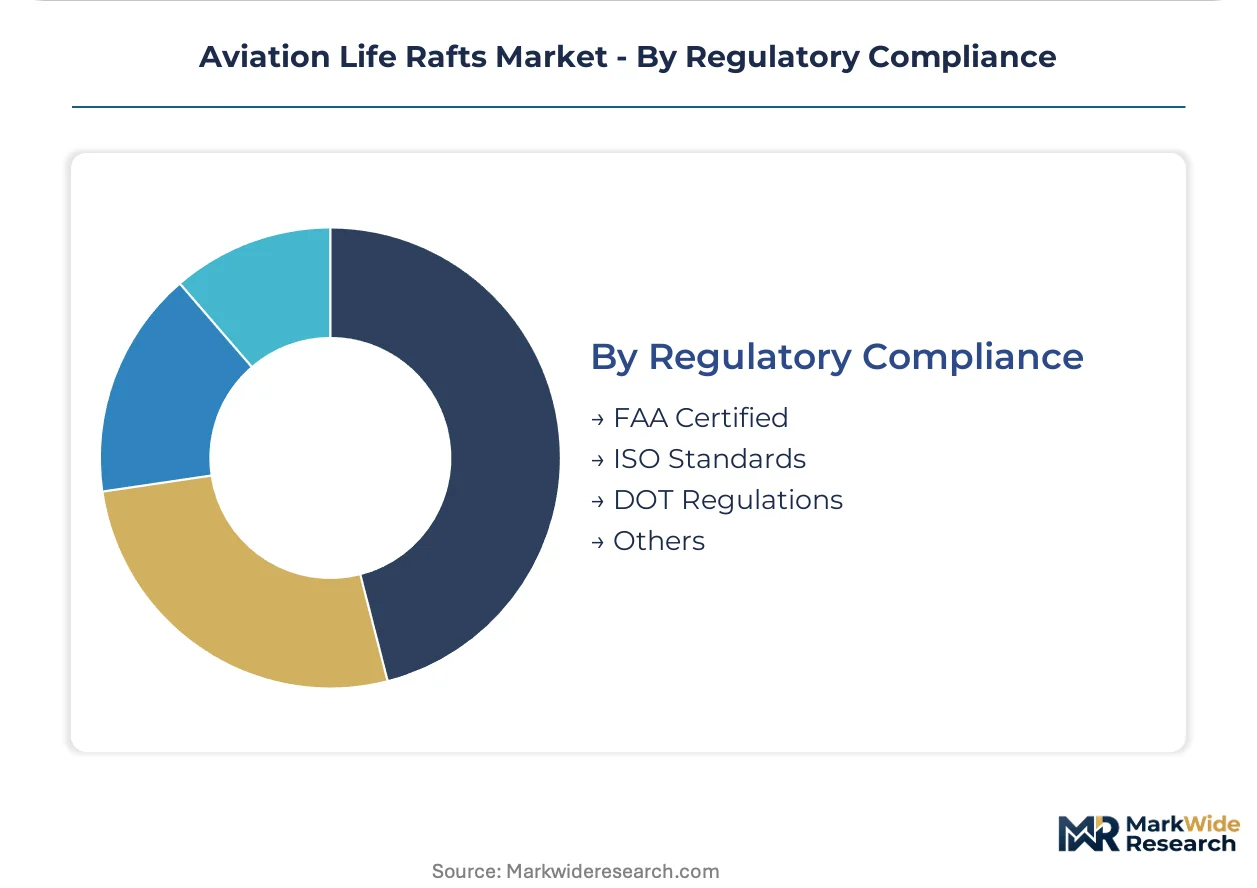
Regulatory Compliance:
Certification tier determines market access and pricing architecture across operational domains.
- FAA Certified:TSO-C70a governs United States commercial aviation access with strict deployment speed and material standards. FAA-certified repack facility networks concentrate in Texas, Florida, and California, shaping aftermarket service geography.
- ISO Standards:ISO 9650 enables cross-border operational acceptance for private aviation and helicopter operators. Dual-certification requirements inflate development timelines without proportional demand expansion.
- DOT Regulations:Transport-specific provisions govern cargo and non-passenger aircraft configurations.
- Others:National and regional standards fill gaps in non-harmonized jurisdictions.
FAA Certified systems hold entrenched position in commercial fleets, while ISO Standards adoption accelerates among private operators seeking operational flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aviation life raft consumption patterns diverge sharply by geography: commercial airlines in the United States prioritize FAA-certified rapid-deployment systems, while European carriers respond to EASA ditching mandates with integrated survival configurations, and offshore helicopter operators in the North Sea and Gulf of Mexico specify compact marine-grade designs.
United States
FAA TSO-C70a certification requirements drive retrofit spending across legacy fleets as carriers face non-negotiable replacement schedules. The FAA mandates sub-30-second deployment thresholds that eliminate manual systems from commercial tenders. Texas, Florida, and California host concentrated networks of FAA-certified repack facilities serving domestic airline technical operations.
Germany
EASA CS-25 Appendix J compliance deadlines compress product refresh cycles for Lufthansa Group and other major carriers. The regulator now requires dynamic wave tank testing demonstrating 24-hour occupant survivability in Sea State 4 conditions. Hamburg and Munich anchor aerospace manufacturing clusters where survival system vendors maintain hydrodynamic testing capabilities.
United Kingdom
North Sea offshore helicopter transport specifications favor compact 4-6 person rafts with marine-grade construction. The Civil Aviation Authority enforces ditching equipment standards aligned with EASA frameworks. Aberdeen and the Scottish east coast concentrate energy sector procurement for helicopter emergency flotation systems.
France
Airbus manufacturing presence shapes integrated survival system specifications for A350 and A320neo programs. EASA mandates cascade through Air France-KLM procurement budgets, prioritizing multi-place configurations. Toulouse and the Occitanie region host OEM engineering centers that influence raft capacity rating calculations.
United Arab Emirates
Emirates and Etihad fleet expansion drives premium long-haul equipment procurement for transoceanic ETOPS routes. The General Civil Aviation Authority adopts FAA and EASA standards for commercial certification. Dubai International Airport and Abu Dhabi anchor MRO hubs serving Middle East and African carrier retrofit programs.
Aviation Life Rafts Market Vendor Landscape
Capability concentration sits with integrated survival system specialists; scale advantage sits with global service network operators. The market structures around three tiers: OEM-aligned integrated system vendors, aftermarket service specialists with certified station networks, and marine-grade craftsmen serving private aviation niches. Dominant competitive moves include strategic partnerships with aircraft manufacturers for line-fit programs and geographic expansion of FAA-certified repack facilities to reduce airline AOG risk.
Within the integrated survival systems tier, Safran exemplifies the OEM-aligned archetype through its bundled beacon and evacuation slide manufacturing. Survitec Group Limited anchors the aftermarket service vector with its global station network for inspection and repack contracts. Winslow LifeRaft Company occupies the marine-grade specialist position, representing handcrafted construction for private jet and helicopter operators seeking custom capacity ratings.
| Leading Market Players |
|---|
| Survitec Group Limited |
| EAM Worldwide |
| Safran |
| Life Support International, Inc. |
| Revere Survival Inc. |
| Winslow LifeRaft Company |
| Plastimo |
| Switlik Parachute Company |
| VIKING LifeSaving Equipment |
| Others |
Supply Flow & Price Mechanics
Houston's petrochemical corridor feeds coated fabric production for aviation life raft manufacturers, concentrating neoprene and coated nylon supply within a 200-mile radius of Gulf Coast refineries. This geographic clustering grants incumbent suppliers pricing leverage over smaller raft builders lacking volume offtake agreements with Dow Chemical or DuPont elastomer divisions.
Pricing Analysis
Long-term offtake contracts dominate procurement between major airlines and integrated survival system vendors, locking in multi-year pricing for FAA-certified self-inflating configurations. Price differentiation hinges on certification tier—TSO-C70a compliance commands substantial premiums over ISO 9650-aligned private aviation units—and aftermarket service bundling that anchors lifetime value capture. Pricing pressure stems from EASA-mandated fleet retrofit deadlines compressing carrier capital allocation decisions. Commercial airlines exhibit lowest price sensitivity given regulatory non-negotiability, while flight schools and recreational operators in manual-system segments negotiate aggressively on unit economics.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculus for carbon dioxide inflation system components, with solenoid valves and precision regulators concentrated in Shenzhen and Dongguan manufacturing clusters. Raw material dependencies center on petroleum-derived neoprene from Texas and Louisiana refineries, carbon dioxide canisters from Alabama and Pennsylvania metal forming facilities, and marine-grade coated nylon from South Korean textile exporters. Distribution runs through FAA-certified repack facilities clustered in Texas, Florida, and California, with independent Part 145 repair stations competing on turnaround velocity for inspection contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among commercial airline technical operations consolidating procurement around integrated survival system vendors with captive service networks. Lufthansa Group, Air France-KLM, and United Airlines have each reduced qualified supplier pools from six to three vendors over the past retrofit cycle.
For Market Incumbents: Entrench position through backward integration into carbon dioxide inflation system manufacturing, capturing margin currently flowing to precision valve suppliers in China. Expand FAA-certified repack station footprint into Mountain and Pacific Northwest states to eliminate competitor turnaround advantages. EASA-EASA harmonization gaps represent the critical threat; invest in parallel validation capabilities to prevent development timeline duplication. For New Entrants and Emerging Players: Mid-cap helicopter operators in the Gulf of Mexico and North Sea corridors represent the most penetrable entry point, as these buyers prioritize marine-grade construction over integrated system bundling. Private jet fractional ownership fleets seeking custom capacity ratings offer secondary white-space with lower certification barriers than commercial airline tenders. A go-to-market angle anchored to rapid turnaround inspection services—competing on documentation quality rather than OEM pedigree—circumvents entrenched Safran and Survitec relationships. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because FAA and EASA certification timelines create structural barriers that protect incumbent revenue streams across product refresh cycles. Acquisition targets should exhibit captive testing capabilities—hydrodynamic wave tanks, thermal exposure chambers—and established airline technical operations relationships. The signal to watch is EASA CS-25 Appendix J amendment velocity; accelerated testing mandate expansion would compress valuations for certification-lagged vendors.| Strategic Initiative | Industry Significance |
|---|---|
| Beacon-Raft System Integration | Safran's bundled architecture reduces installation complexity for Airbus A350 line-fit programs. |
| Third-Party Repack Network Expansion | Independent FAA Part 145 stations in Seattle and Denver challenge Survitec's geographic concentration. |
| Dual-Chamber Inflation R&D Investment | Redundant CO2 architectures migrate from widebody ETOPS configurations into narrowbody retrofits. |
| CSRD-Aligned Supply Chain Certification | Carbon footprint documentation captures European carrier ESG-mandated procurement preferences. |
| Helicopter Offshore Specification Focus | Winslow LifeRaft Company's marine-grade construction commands premium positioning in energy transport. |
Methodological Framework
A spread of perspectives from airline technical operations directors, survival system procurement managers, FAA certification engineers, and aftermarket service station operators converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation against TSO-C70a certification databases, EASA CS-25 Appendix J amendment filings, and customs records tracking neoprene fabric imports through Gulf Coast ports. Bottom-up fleet installation counts triangulated against top-down manufacturer revenue segmentation across self-inflating, manual, and survival-integrated product categories.
Demand-supply balance framing anchored the forecast architecture, with installed base refresh cycles modeled against EASA compliance deadlines and ETOPS route expansion patterns across the projection horizon. Segmentation dimensions included deployment mechanism, end-user operational context, certification tier, and regional regulatory cluster. CAGRs derived from regression analysis of historical fleet growth correlated with aircraft delivery backlogs and survival equipment content-per-aircraft assumptions. Hydrodynamic testing capacity expansion and carbon dioxide inflation system reliability field data served as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in petroleum feedstock pricing, trans-Pacific shipping rates, or commercial aviation passenger recovery trajectories would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory amendment velocity and OEM fleet introduction schedules. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Safety Systems
Aircraft Door Dampers Market
Aircraft Safety Systems
Free Fall Sensor Market
Aircraft Safety Systems
Military Aircraft Collision Avoidance Systems Market
Aircraft Safety Systems
Global Aircraft Brake System Market
Aircraft Safety Systems
Aircraft Fire Protection Systems Market
Aircraft Safety Systems
Global Aircraft Brakes Market
Aircraft Safety Systems
South Korea Aircraft Windshield Wiper and Washer System Market
Aircraft Safety Systems
Aircraft Survivability Equipment Market
Aircraft Safety Systems
Aircraft Survival Equipment Market
Aircraft Safety Systems
Cloud-Connected Aircraft Safety Data Management Platforms Market
Aircraft Safety Systems
Aircraft Ejection Seats Market
Aircraft Safety Systems
Aircraft Evacuation Systems Market
Aircraft Safety Systems
Commercial Aircraft Collision Avoidance System Market
Aircraft Safety Systems
Instrument Landing System (ILS) Market
Aircraft Safety Systems
Aircraft Evacuation Slide Market
Aircraft Safety Systems
Aircraft Lightning Protection Market