
 Unmanned Surface Vessel (USV) Market | 2026-2036
Unmanned Surface Vessel (USV) Market Size, Share, and Industry Trends Forecast 2026-2036
Unmanned Surface Vessel (USV) Market Insights
Multi-source component procurement is consolidating around a handful of defense primes with captive maritime autonomy stacks. Kongsberg Maritime leverages its Nordic naval heritage to dominate mine countermeasure system integration. L3Harris Technologies sustains broad-spectrum capabilities spanning command-and-control interfaces to full vessel platforms. Elbit Systems competes through specialized naval portfolios concentrated on Mediterranean and Asia-Pacific navies.
An unmanned surface vessel is a self-propelled craft operating on water without embarked personnel, typically measuring 3 to 15 meters in length and integrating sensor payloads, communications arrays, and propulsion systems rated for 20 to 50 hours of endurance for persistent maritime domain awareness. Surveillance vessels anchor current procurement volumes as coast guards and navies prioritize persistent patrol over contested chokepoints. Mine countermeasure vessels represent the fastest-growing product category as legacy fleet retirements accelerate demand for standoff clearance capabilities. Defense agencies command the dominant end-user share, though scientific research institutes are expanding environmental monitoring fleets with hybrid-propulsion architectures.
The U.S. Navy's Unmanned Campaign Framework, the UK Maritime Autonomous Systems Regulatory Working Group, and the International Maritime Organization's ongoing MASS code development collectively shape certification pathways and operational authorization for commercial and military USV deployment. Classification societies including Lloyd's Register and DNV are establishing prescriptive standards for autonomous navigation system redundancy that directly influence vendor qualification and fleet insurance economics. Stakeholders must monitor which regulatory jurisdiction achieves operational code maturity first, as that geography will attract platform development investment and establish de facto interoperability benchmarks for allied fleet procurement.
Market Dynamics
Naval procurement offices across NATO member states are redirecting capital from crewed vessel programs toward uncrewed platforms, compressing traditional shipbuilding timelines and forcing defense primes to restructure engineering teams around autonomy-first architectures.
Growth Catalysts
- Mine Countermeasure Platform Replacements:Legacy fleet retirements across European navies are accelerating demand for standoff clearance capabilities that remove human operators from explosive ordnance proximity.
- The U.S. Navy's Unmanned Campaign Framework:This strategic directive channels procurement budgets toward persistent maritime domain awareness vessels with standardized command-and-control interfaces.
- Coast Guard Persistent Patrol Mandates:Contested chokepoint surveillance requirements in the Mediterranean and South China Sea are expanding procurement volumes for medium-endurance USVs.
Market Restraints
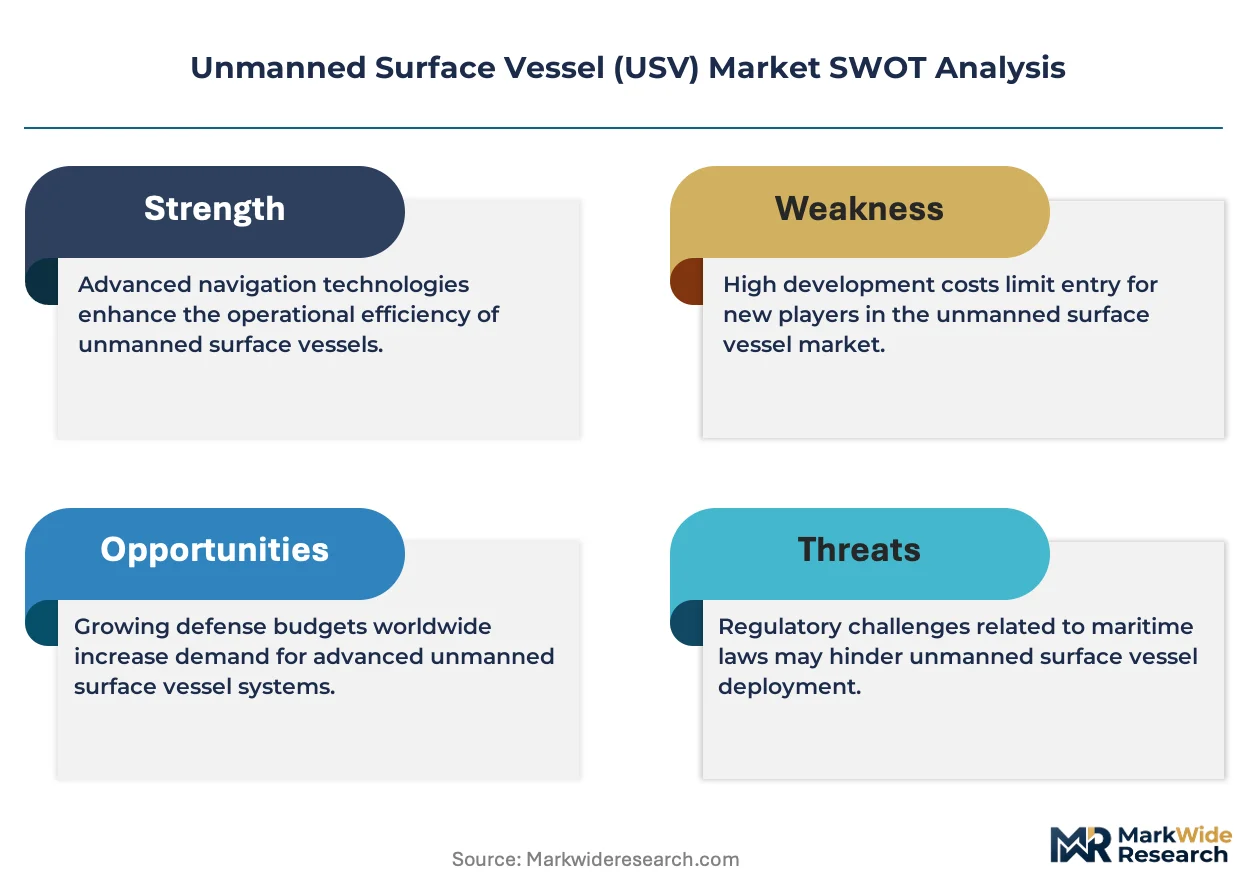
- Maritime Lithium-Ion Supply Concentration:Battery cell production for extended endurance configurations remains concentrated in East Asian manufacturing clusters, creating input cost volatility and qualification delays.
- Autonomy Software Certification Gaps:The International Maritime Organization's incomplete MASS code leaves classification societies without harmonized testing protocols, extending vendor qualification timelines.
- Crewed Vessel Maintenance Inertia:Existing naval maintenance infrastructures and union agreements create institutional resistance to platform substitution in several NATO member fleets.
Strategic Opportunities
- Hybrid-Propulsion Scientific Fleets:Research institutes in Norway and Australia are expanding environmental monitoring contracts that combine diesel-electric endurance with zero-emission harbor operations.
- UK Maritime Autonomous Systems Regulatory Working Group:Early operational code maturity in British waters is attracting platform development investment and establishing de facto interoperability benchmarks for allied procurement.
- Artificial Intelligence Sensor Fusion:Convergence of computer vision and synthetic aperture radar processing is enabling single-platform missions previously requiring multiple asset types.
Industry Challenges
- Maritime Robotics Engineering Talent Scarcity:The specialized intersection of naval architecture, autonomy software, and ocean engineering commands premium compensation that mid-tier suppliers struggle to match.
- Classification Society Certification Timelines:Lloyd's Register and DNV prescriptive standards for navigation system redundancy require multi-year validation cycles that delay fleet insurance economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Unmanned Surface Vessel (USV) Market |
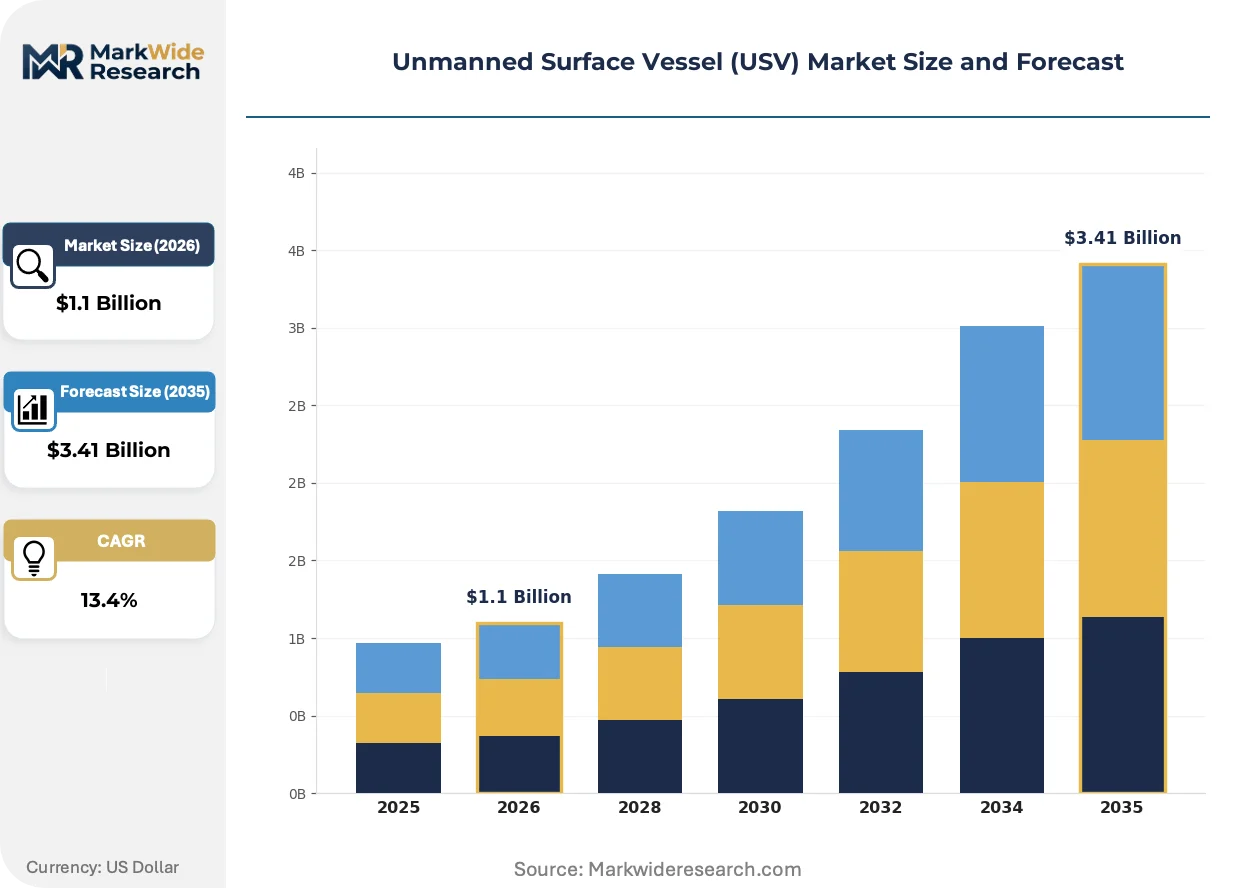
| Market Size in 2026 | $1.1 Billion |
| Market Size in 2035 | $3.41 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surveillance Vessels, Patrol Vessels, Research Vessels, Logistics Vessels, Mine Countermeasure Vessels Technology: Autonomous Navigation, Remote Control, Hybrid Propulsion, Acoustic Sensors, Optical Imaging Application: Maritime Security, Oceanography, Environmental Monitoring, Offshore Exploration, Border Protection End User: Defense Agencies, Scientific Research Institutes, Oil & Gas Companies, Coast Guard, Port Authorities |
| Companies Covered | L3Harris Technologies, Northrop Grumman, Textron Systems, Elbit Systems, Exail Technologies, Kongsberg Maritime, Teledyne Technologies, Saronic Technologies, Thales Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Unmanned Surface Vessel (USV) Market Trends and Innovations
Autonomous navigation architectures are absorbing capital and engineering talent previously allocated to crewed vessel electronics, compressing development cycles for perception systems and collision-avoidance algorithms.
Synthetic aperture radar and electro-optical sensor fusion is absorbing integration complexity previously handled by separate platform types. Naval procurement offices in Australia and the United Kingdom are specifying these combined payloads for single-vessel mine hunting and surveillance missions. The technology is absorbing demand that previously required dedicated mine countermeasure ships alongside separate patrol craft.
The International Maritime Organization's ongoing MASS code development is forcing classification societies to publish interim guidelines ahead of final ratification. Lloyd's Register and DNV have issued prescriptive standards for autonomous navigation system redundancy that directly influence vendor qualification requirements. Mine countermeasure vessel configurations face the most stringent certification demands due to operational proximity to explosive ordnance.
Buyer procurement patterns are consolidating vendor relationships around defense primes offering captive maritime autonomy stacks. Coast guard and naval procurement offices are reducing supplier counts from component-level sourcing to platform-level contracting. This concentration is most visible in NATO member states where interoperability requirements favor standardized command-and-control interfaces across national fleets.
Unmanned Surface Vessel (USV) Market Segmentation
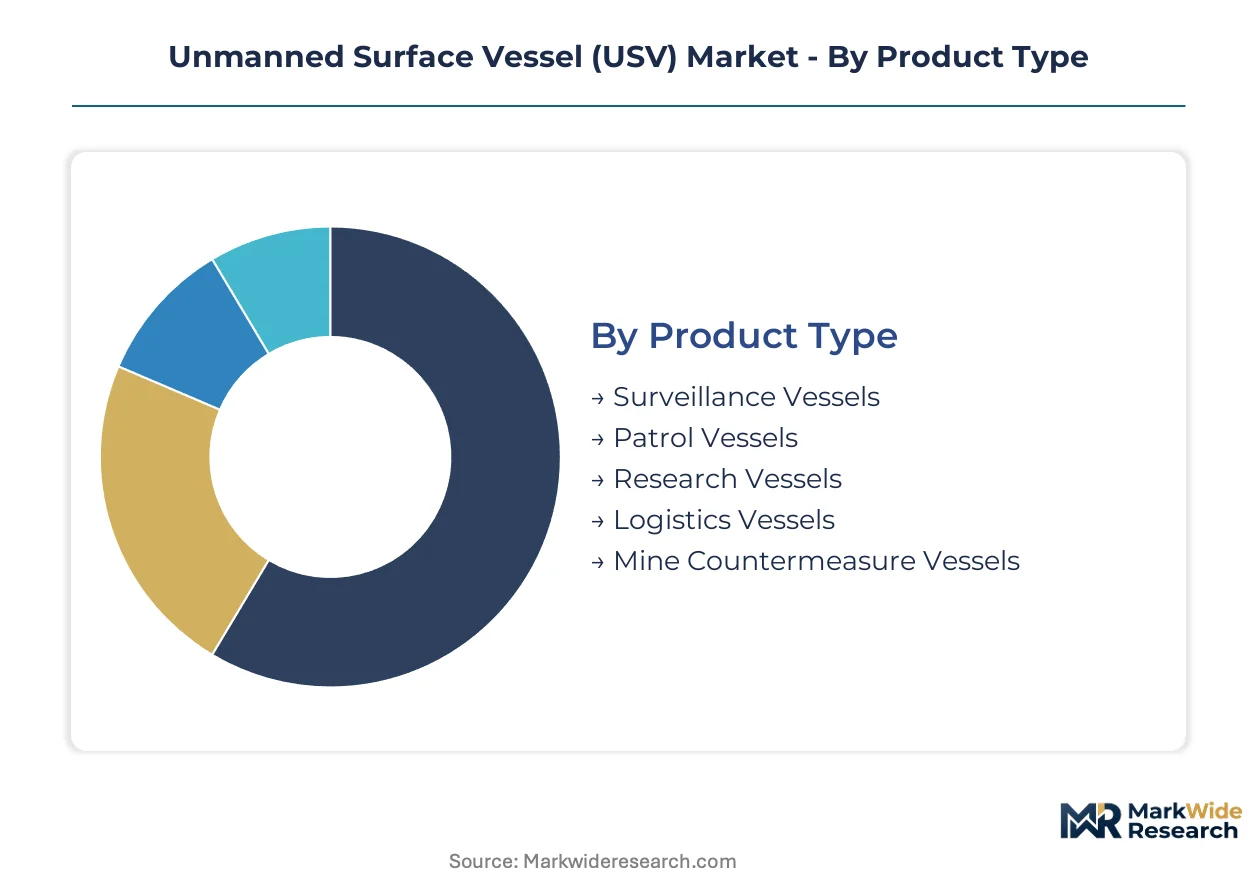
USV procurement patterns diverge sharply across mission profiles, with defense agencies prioritizing mine countermeasure and surveillance platforms while research institutes drive hybrid-propulsion adoption. Technology selection and end-user requirements create distinct supply chain configurations that favor specialized vendors over generalist platform builders.
Product Type:
Supply concentration in mine countermeasure system integration has consolidated around Nordic and Anglo-American defense primes with captive maritime autonomy stacks.
- Surveillance Vessels:Medium-endurance platforms measuring 7 to 12 meters integrate electro-optical and radar payloads for persistent chokepoint monitoring. Coast guard procurement offices in Australia and the United Kingdom specify standardized command-and-control interfaces that compress vendor qualification timelines.
- Mine Countermeasure Vessels:Standoff clearance configurations remove human operators from explosive ordnance proximity through acoustic and magnetic signature detection. European naval procurement offices redirect capital from crewed minehunters toward these platforms as legacy fleets retire.
- Patrol Vessels:Shorter-endurance craft optimized for harbor and coastal enforcement missions with modular payload bays.
- Research Vessels:Scientific platforms emphasizing precision positioning and low acoustic signature for oceanographic sampling.
- Logistics Vessels:Cargo-carrying configurations for ship-to-shore resupply in contested environments.
Surveillance vessels absorb the bulk of installed capacity; mine countermeasure vessels are expanding most quickly.
Technology:
Cost tier differentiation separates defense-grade autonomous navigation systems from commercial remote-control configurations with limited operational authorization.
- Autonomous Navigation:Perception systems fusing synthetic aperture radar with computer vision enable collision avoidance without human intervention. Lloyd's Register and DNV prescriptive standards for navigation redundancy extend vendor qualification cycles but establish fleet insurance economics.
- Hybrid Propulsion:Diesel-electric architectures with battery buffer systems support zero-emission harbor operations alongside extended offshore endurance. Norwegian and Australian research institutes expand environmental monitoring contracts specifying these configurations.
- Remote Control:Line-of-sight and satellite-communicated manual operation for missions requiring human-in-the-loop authorization.
- Acoustic Sensors:Sonar payloads for seabed mapping and mine detection with multi-frequency processing.
- Optical Imaging:Electro-optical and infrared cameras for surface target identification and tracking.
Autonomous navigation commands premium pricing; hybrid propulsion is climbing the fastest as environmental regulations tighten.
Application:
Volume concentration in maritime security applications absorbs procurement budgets from coast guards and naval forces prioritizing contested chokepoint presence.
- Maritime Security:Anti-piracy and threat detection missions require persistent patrol capabilities across exclusive economic zones. The U.S. Navy's Unmanned Campaign Framework channels demand toward standardized interfaces across allied fleets.
- Environmental Monitoring:Long-duration water quality and marine life observation missions leverage hybrid propulsion for reduced acoustic disturbance. Australian research institutes and Norwegian oceanographic centers expand fleet procurement.
- Oceanography:Deep-water bathymetry and current measurement with precision navigation requirements.
- Offshore Exploration:Seismic survey support and pipeline inspection for oil and gas operators.
- Border Protection:Coastal surveillance and interdiction support for national sovereignty enforcement.
Maritime security absorbs the bulk of installed capacity; environmental monitoring is gaining share fastest.
End User:
Customer type determines certification pathway complexity, with defense agencies requiring military-grade qualification and port authorities facing commercial maritime regulatory frameworks.
- Defense Agencies:Naval procurement offices specify mine countermeasure and surveillance platforms with encrypted command links and weapon-avoidance protocols. NATO interoperability requirements favor vendors offering captive autonomy stacks.
- Scientific Research Institutes:Environmental monitoring and oceanographic missions prioritize sensor precision over speed or payload capacity. Norwegian and Australian institutes lead hybrid-propulsion fleet expansion.
- Oil & Gas Companies:Offshore inspection and logistics support with commercial classification society certification.
- Coast Guard:Persistent patrol mandates across Mediterranean and Indo-Pacific chokepoints with dual-use surveillance capabilities.
- Port Authorities:Harbor security and traffic management with limited operational range requirements.
Defense agencies absorb the bulk of installed capacity; scientific research institutes are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement offices in the United States channel the dominant share of naval autonomy investment, with NATO allies following at scaled-down commitments. Fleet modernization directives across allied navies are compressing development timelines for mine countermeasure and surveillance configurations.
United States
The U.S. Navy's Unmanned Campaign Framework directs capital toward persistent maritime domain awareness vessels with standardized command-and-control interfaces. The Department of Defense acquisition pathways prioritize encrypted datalinks and weapon-avoidance protocols for contested environment operations. Engineering teams in Rhode Island and Virginia concentrate on autonomy-first architectures that displace traditional crewed vessel electronics spending.
United Kingdom
Royal Navy fleet modernization accelerates standoff mine clearance procurement as legacy minehunter retirements remove human operators from explosive ordnance proximity. The Maritime Autonomous Systems Regulatory Working Group publishes interim operational codes that attract platform development investment to British waters. Autonomy engineering clusters in Portsmouth and Plymouth establish de facto interoperability benchmarks for allied NATO procurement.
Australia
Australian Defence Force investments in Indo-Pacific chokepoint surveillance expand medium-endurance USV procurement volumes for exclusive economic zone patrol. The Department of Defence integrates unmanned platforms into joint maritime task forces under the 2023 Defence Strategic Review recommendations. Perth and Sydney harbor engineering facilities specialize in diesel-electric hybrid architectures for reduced acoustic signature missions.
Norway
Kongsberg Maritime leverages Nordic naval heritage to dominate mine countermeasure system integration for European and Asia-Pacific navies. Norwegian research institutes expand environmental monitoring fleets specifying precision positioning and low acoustic signature configurations. Ocean engineering clusters in Kongsberg and Horten advance hybrid-propulsion architectures that combine offshore endurance with zero-emission harbor operations.
Israel
Israeli naval procurement prioritizes surveillance platforms for Mediterranean maritime security and exclusive economic zone enforcement. The Ministry of Defense specifies compact autonomous vessels for littoral operations with synthetic aperture radar and electro-optical sensor fusion. Haifa-based defense contractors concentrate on specialized naval portfolios serving Mediterranean and Asia-Pacific export markets.
Unmanned Surface Vessel (USV) Market Competitive Landscape
Platform-level contracting dominates the current landscape as coast guard and naval procurement offices reduce supplier counts from component-level sourcing. Defense primes with captive maritime autonomy stacks capture expanding NATO interoperability requirements. Three archetypes define competitive positioning: Nordic system integrators with mine countermeasure heritage, Anglo-American full-spectrum platform builders, and Mediterranean specialists with regional export focus. M&A activity and strategic partnerships concentrate engineering talent around autonomy software and sensor fusion capabilities.
Among defense prime consolidators, L3Harris Technologies, Kongsberg Maritime, and Elbit Systems occupy distinct competitive positions. L3Harris exemplifies the broad-spectrum Anglo-American archetype spanning command-and-control interfaces through full vessel platforms. Kongsberg Maritime anchors the Nordic integration specialist tier with captive mine countermeasure system expertise. Elbit Systems represents the Mediterranean-focused specialist model concentrated on naval portfolios for regional and Asia-Pacific export markets.
| Leading Market Players |
|---|
| L3Harris Technologies |
| Northrop Grumman |
| Textron Systems |
| Elbit Systems |
| Exail Technologies |
| Kongsberg Maritime |
| Teledyne Technologies |
| Saronic Technologies |
| Thales Group |
| Others |
Pricing and Supply Chain Analysis
Defense prime consolidators with captive maritime autonomy stacks exercise asymmetric pricing power over mid-tier component suppliers, compressing margins at the subsystem level while platform-level contracts capture premium returns. Sovereign-backed procurement offices in NATO member states enforce long-term offtake agreements that stabilize input costs for qualified vendors while locking out speculative entrants lacking military-grade certification heritage.
Pricing Analysis
High-volume surveillance vessel procurement absorbs cost compression from standardized NATO command-and-control interfaces, while mine countermeasure configurations retain pricing power through Lloyd's Register and DNV redundancy certification requirements. Three-tier pricing structure across defense-grade, dual-use, and commercial configurations separates encrypted datalink platforms from harbor-security craft with limited operational authorization. Pricing pressure stems from lithium-ion cell supply volatility concentrated in East Asian manufacturing clusters. Coast guard procurement offices exhibit highest price sensitivity; naval mine countermeasure programs demonstrate lowest sensitivity due to standoff clearance operational mandates.
Supply Chain Analysis
UK Maritime Autonomous Systems Regulatory Working Group local-content provisions and U.S. Navy Unmanned Campaign Framework domestic-preference clauses are reshaping component sourcing toward Rhode Island and Portsmouth engineering clusters. Maritime lithium-ion battery production draws from South Korean and Japanese cell manufacturers, with synthetic aperture radar processors anchored in U.S. and Israeli semiconductor fabs. Single-source vulnerability in autonomy software stacks poses structural risk given International Maritime Organization MASS code immaturity. Distribution runs through defense prime platform integrators with captive supply of navigation redundancy systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The unmanned surface vessel market functions as a cost-of-compliance arena where Lloyd's Register and DNV prescriptive standards for autonomous navigation redundancy erect certification barriers that favor incumbents with multi-year validation track records.
For Market Incumbents: Anchor fleet modernization relationships through backward integration into lithium-ion battery pack assembly, insulating against East Asian supply volatility. Deepen Portsmouth and Rhode Island engineering presence to capture UK Maritime Autonomous Systems Regulatory Working Group and U.S. Navy Unmanned Campaign Framework procurement preferences. Counter emerging sensor-fusion specialists by acquiring computer vision software boutiques before classification society qualification timelines extend. For New Entrants and Emerging Players: The International Maritime Organization's incomplete MASS code in European waters opens a window for interim guideline consulting services that bridge classification society gaps. Target Australian Defence Force hybrid-propulsion scientific fleet expansion as the most penetrable segment, given Norwegian research institute incumbency in mine countermeasure integration. Pursue coast guard persistent patrol mandates through modular payload bay configurations that sidestep full platform certification requirements. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier autonomy software shops in Israel and Australia with Lloyd's Register pre-qualification progress but incomplete revenue scale. Long-term viability hinges on regulatory code maturation rather than platform unit economics alone. Monitor UK Maritime Autonomous Systems Regulatory Working Group publication velocity as the inflection signal for interoperability benchmark adoption across allied procurement.| Strategic Initiative | Industry Significance |
|---|---|
| Autonomy Software Acquisition | Captures scarce engineering talent in collision-avoidance algorithm development ahead of DNV certification deadlines. |
| Hybrid-Propulsion Manufacturing Scale-Up | Positions vendors for Australian Defence Force and Norwegian research institute environmental monitoring fleet expansion. |
| NATO Interoperability Certification | Unlocks standardized command-and-control interface contracts across U.S. Navy, Royal Navy, and allied procurement offices. |
| Lithium-Ion Supply Agreement | Mitigates East Asian cell production concentration risk through long-term offtake with South Korean or Japanese manufacturers. |
| Sensor Fusion Platform Integration | Consolidates synthetic aperture radar and electro-optical payloads into single-vessel configurations displacing multi-asset missions. |
Research Methodology
Multi-period observation of U.S. Navy procurement award patterns, UK Royal Navy fleet modernization timelines, and Australian Defence Force strategic review implementation anchored the trend analysis, supplemented by interviews with naval program executives, autonomy software engineering leads, classification society certification managers, and coast guard procurement officers. Secondary validation drew from Department of Defense budget justification materials, Lloyd's Register and DNV published guidelines, International Maritime Organization MASS code development documentation, and NATO standardization office interoperability protocols. Bottom-up vessel configuration demand modeling and top-down defense budget allocation analysis were triangulated for consistency.
Segment-weighting across product type, technology architecture, application mission profile, and end-user customer category structured the analytical framework across the projection horizon. Mine countermeasure, surveillance, patrol, research, and logistics vessel categories were modeled separately with distinct endurance and payload assumptions. Autonomous navigation, hybrid propulsion, remote control, acoustic sensor, and optical imaging technology tiers received differential growth trajectory weightings. CAGRs were derived from procurement pipeline visibility and fleet replacement cycle analysis, with lithium-ion supply constraints and classification society certification timelines as industry-specific forecast inputs.
The model assumes a particular technology adoption path for synthetic aperture radar and electro-optical sensor fusion; alternative pathways for computer vision-only navigation would alter the outlook for platform redundancy requirements and insurance economics. Forecasts reflect assumptions regarding International Maritime Organization MASS code ratification velocity and NATO interoperability standard adoption rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unmanned Systems
Military Robots Market
Unmanned Systems
Global Remote Firing System Market
Unmanned Systems
Space and Space Station Robotics Market
Unmanned Systems
Global Military Robotics Autonomous Systems Market
Unmanned Systems
Autonomous Technology Market
Unmanned Systems
Integrated Range Market
Unmanned Systems
Global Unmanned Aerial Vehicle Landing Gears Market
Unmanned Systems
Autonomous Drone Market
Unmanned Systems
Unmanned Surface Vehicle Market
Unmanned Systems
Unmanned Aerial Vehicle Payload and Subsystems Market
Unmanned Systems
Brazil ROV Market
Unmanned Systems
Drone Battery System Market
Unmanned Systems
EMEA Dismounted Soldier Systems Market
Unmanned Systems
Middle-East and Africa AUV & ROV Market
Unmanned Systems
Low-Noise Drone Propulsion Systems Market
Unmanned Systems
Global Submarine Payload Market