
 Commercial Aircraft Collision Avoidance System Market | 2026-2036
Commercial Aircraft Collision Avoidance System Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Aircraft Collision Avoidance System Market Outlook
North American avionics manufacturing is fragmenting as tier-one suppliers and specialized sensor houses compete for platform integration contracts. Honeywell International Inc. leverages its integrated flight deck ecosystem to bundle collision avoidance with flight management systems. Thales Group anchors European linefit programs through Airbus supply agreements. L3Harris Technologies, Inc. competes aggressively in the military-to-commercial technology transfer segment for terrain awareness products.
A commercial aircraft collision avoidance system integrates active radar transponders, passive surveillance receivers, and GPS-aided positioning to detect proximate traffic and terrain threats, issuing resolution advisories to flight crews to prevent controlled flight into terrain and mid-air collisions. The system processes interrogation signals on 1030 MHz and replies on 1090 MHz with vertical speed commands calculated through proprietary algorithms. Traffic Collision Avoidance System products dominate current retrofit revenue streams as aging fleets face regulatory deadlines for Mode S compatibility. GPS-based augmentation segments are expanding fastest among technology categories as satellite-based precision approach systems gain certification for dense terminal airspace operations.
FAA airworthiness directives and EASA certification specifications mandate minimum performance standards for terrain awareness equipment across all turbine-powered aircraft above specified weight thresholds. The EU Green Deal's sustainable aviation fuel trajectory indirectly pressures operators to optimize flight paths through advanced avionics rather than procedural separation alone. Stakeholders must monitor ICAO's Global Aeronautical Distress and Safety System roadmap for mandated autonomous tracking capabilities that could reshape hardware requirements and retrofit scheduling priorities.
Market Dynamics
Airworthiness mandates from the FAA and EASA are compressing retrofit timelines for aging commercial fleets, forcing carriers to accelerate collision avoidance system upgrades ahead of regulatory deadlines or face operational restrictions.
Growth Catalysts
- NextGen Airspace Modernization:The FAA's NextGen initiative mandates ADS-B Out equipage across all turbine aircraft operating in controlled airspace, creating sustained hardware demand for integrated surveillance solutions.
- Asia-Pacific Fleet Expansion:Chinese domestic carriers are ordering narrowbody aircraft at record rates, with factory-installed enhanced ground proximity warning systems becoming standard configuration.
- Mode S Transponder Mandates:ICAO's globally harmonized surveillance standards require compatible collision avoidance architecture, pulling forward replacement cycles for legacy transponder equipment.
Market Restraints
- Semiconductor Supply Concentration:Advanced gallium nitride components for radar front-ends face single-source dependencies in East Asian foundries, exposing lead time volatility.
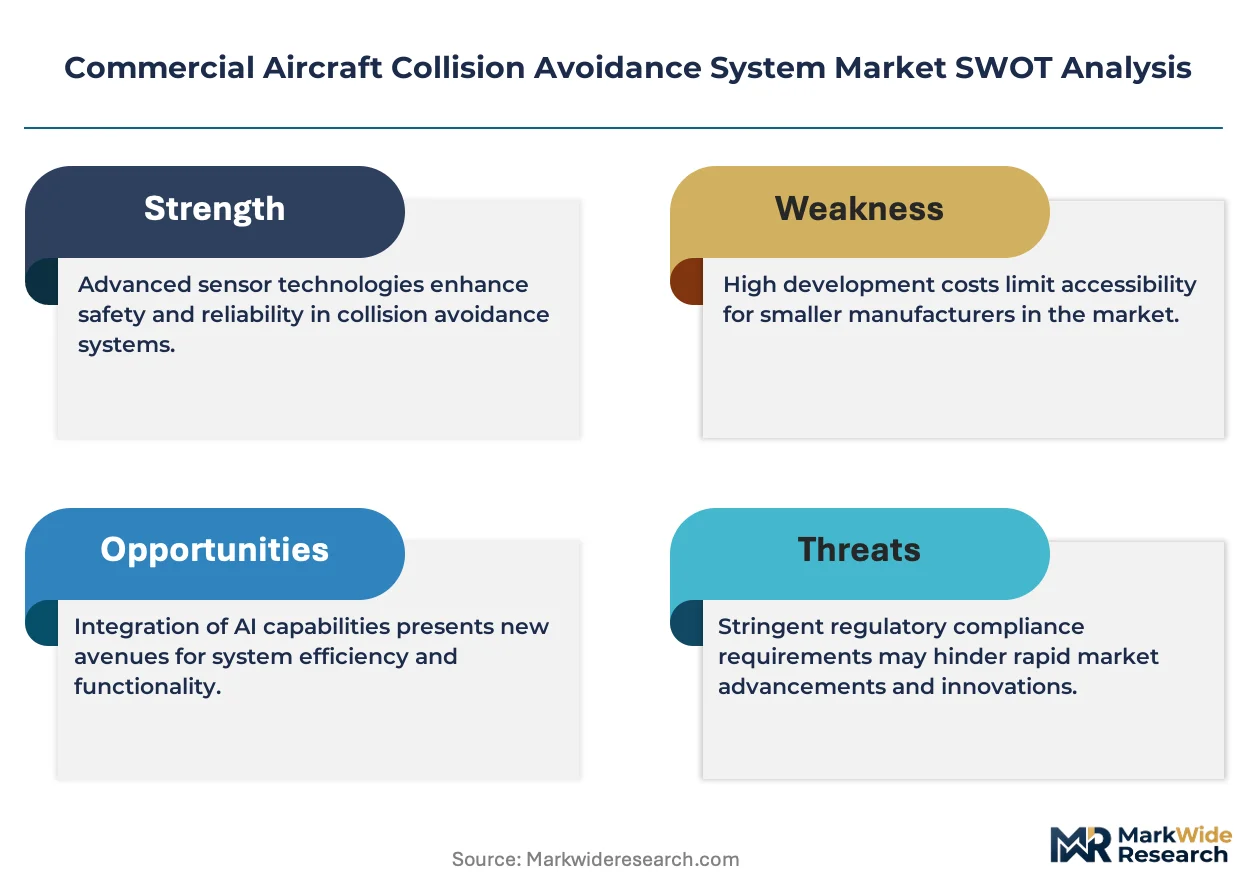
- Certification Cost Burden:EASA's CS-ACNS specifications impose extensive software verification requirements that disproportionately burden smaller avionics suppliers.
- Procedural Separation Persistence:Some low-density airspace operators in Africa and Latin America continue relying on air traffic control vectors rather than autonomous collision avoidance, delaying equipage decisions.
Strategic Opportunities
- Unmanned Traffic Management Integration:Urban air mobility platforms require modified collision avoidance logic, opening adjacent markets for sense-and-avoid algorithm licensing.
- India's UDAN Regional Connectivity:The country's regional aviation scheme is expanding turboprop fleets that must comply with ICAO Annex 6 terrain awareness provisions.
- AI-Assisted Resolution Advisories:Machine learning inference at the edge is converging with traditional TCAS algorithms to reduce nuisance alerts in high-density terminal areas.
Industry Challenges
- DO-178C Software Expertise Scarcity:Certification of safety-critical avionics code requires specialized engineers familiar with formal methods and model-based design.
- Legacy Analog Interface Integration:Retrofit installations must bridge 1970s-era flight director architectures with modern digital collision avoidance processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Aircraft Collision Avoidance System Market |
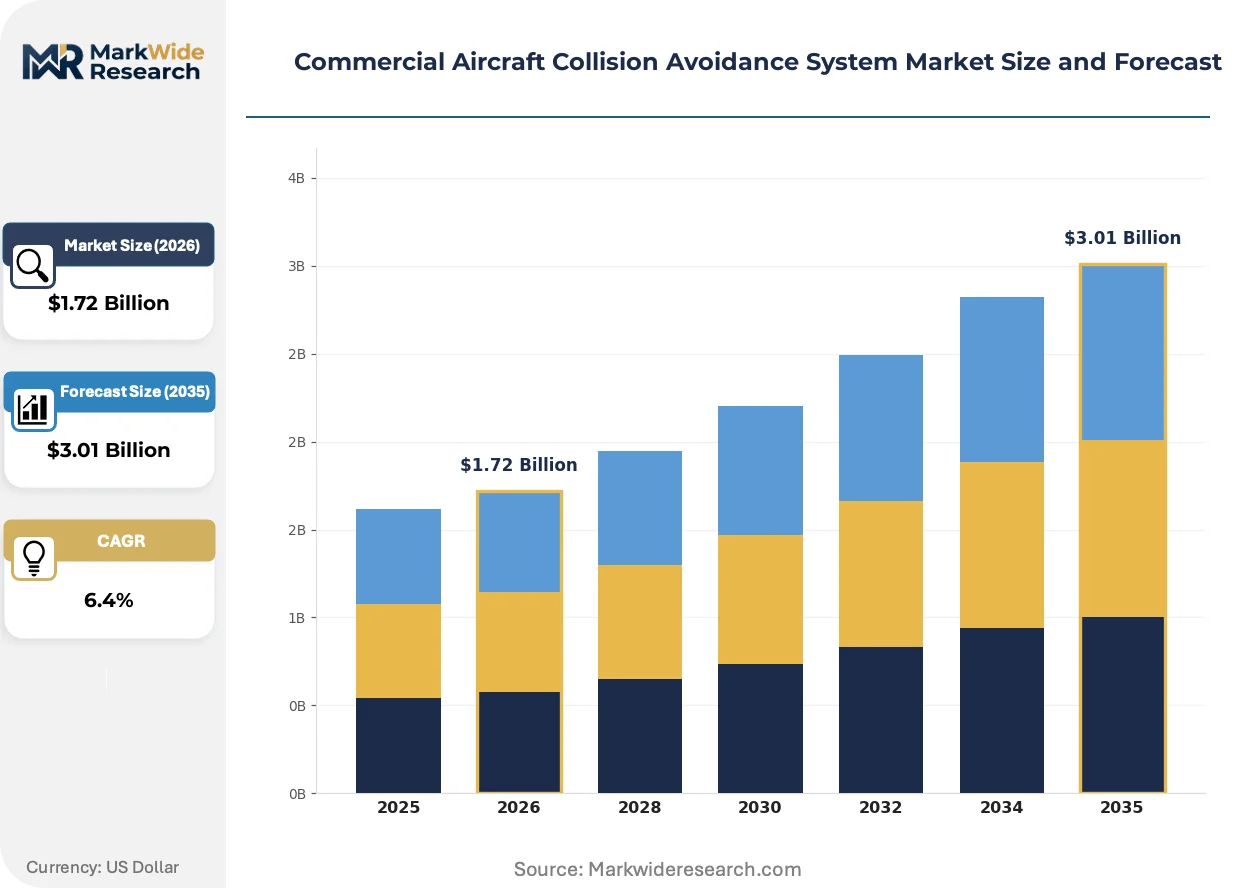
| Market Size in 2026 | $1.72 Billion |
| Market Size in 2035 | $3.01 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
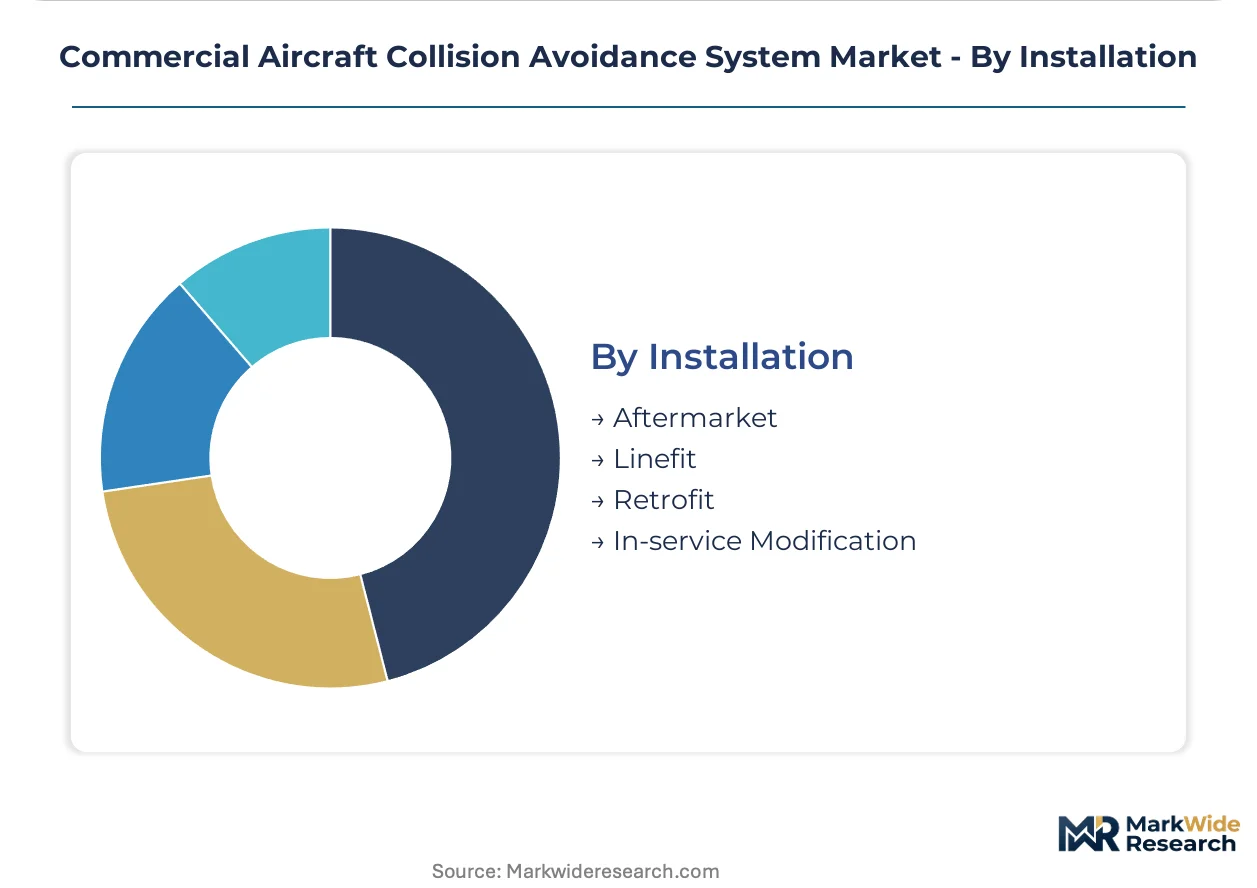
| Segmentation | Product Type: Ground Proximity Warning System, Traffic Collision Avoidance System, Enhanced Ground Proximity Warning System, Flight Data Monitoring System Technology: Active Radar, Passive Radar, LiDAR, GPS End User: Commercial Airlines, Private Aviation, Cargo Operators, Government Agencies Installation: Aftermarket, Linefit, Retrofit, In-service Modification |
| Companies Covered | Honeywell International Inc., Thales Group, L3Harris Technologies, Inc., Garmin Ltd., Collins Aerospace, BAE Systems, Saab AB, Universal Avionics, Leonardo S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Aircraft Collision Avoidance System Market Strategic Shifts
Active surveillance architectures are yielding to hybrid cooperative-noncooperative sensing, compressing hardware footprints while expanding threat detection envelopes beyond traditional transponder-dependent methods.
Multi-static passive radar is collapsing the distinction between onboard and ground-based surveillance by enabling aircraft to detect non-transponder-equipped traffic through ambient signal exploitation. Regional carriers in Australia and Canada are piloting fused sensor configurations that reduce dedicated hardware mass by forty percent. This convergence is collapsing the retrofit cost barrier for smaller turboprop operators previously priced out of full TCAS equipage.
The EU Green Deal's sustainable aviation fuel trajectory is tightening EASA oversight of flight path optimization tools, mandating that terrain awareness systems integrate with performance-based navigation to minimize holding patterns and vectoring delays. Operators serving congested European terminal airspace must now demonstrate continuous descent capability backed by certified predictive terrain algorithms. Narrowbody fleets based at Frankfurt and Amsterdam Schiphol are prioritizing software upgrades that satisfy both fuel efficiency and safety mandates simultaneously.
Airlines are consolidating avionics procurement under fleet-wide lifecycle agreements rather than transactional line-item purchasing, compressing vendor margins in exchange for guaranteed retrofit scheduling priority. Low-cost carriers in Southeast Asia are leading this shift, bundling collision avoidance with flight management and communications suites under ten-year service contracts. This preference consolidation is most visible in Indonesia and Vietnam, where rapid fleet growth gives buyers leverage to demand integrated support packages.
Commercial Aircraft Collision Avoidance System Market Segmentation

Collision avoidance system procurement splits across four distinct dimensions that shape vendor engagement models and certification pathways. Product architecture determines hardware integration complexity, while installation channel governs margin structures and customer relationships.
Product Type:
Cost tier stratification separates factory-standard configurations from premium integrated suites requiring extensive airworthiness recertification.
- Ground Proximity Warning System:Basic terrain alerting architecture processes radio altimeter inputs against internal terrain databases, issuing aural warnings for excessive sink rates and terrain closure. Demand concentrates in emerging market turboprop operators retrofitting legacy fleets to satisfy ICAO Annex 6 provisions ahead of national regulatory deadlines.
- Traffic Collision Avoidance System:Active surveillance equipment interrogates nearby transponders on 1030 MHz and calculates resolution advisories through proprietary tracking algorithms. Narrowbody carriers across Southeast Asia are pulling forward replacement cycles as Mode S mandates compress retrofit timelines for aging equipment.
- Enhanced Ground Proximity Warning System:Combines GPS positioning with terrain and obstacle databases for predictive alerting envelope protection.
- Flight Data Monitoring System:Captures operational parameters for post-flight analysis and proactive safety management.
Traffic Collision Avoidance System commands the established base. The steepest expansion runs through Enhanced Ground Proximity Warning System.
Technology:
Application requirements differentiate cooperative surveillance dependent on transponder-equipped traffic from autonomous non-cooperative sensing for uncontrolled airspace operations.
- Active Radar:Transmits interrogation pulses and processes reply signals to establish range, bearing, and altitude separation from proximate aircraft. FAA NextGen equipage mandates sustain hardware demand across US-registered turbine fleets operating in controlled airspace above specified altitude thresholds.
- Passive Radar:Exploits ambient electromagnetic emissions to detect non-transponder-equipped traffic without dedicated transmission hardware. Australian regional operators are piloting fused sensor configurations that reduce dedicated avionics mass and collapse retrofit cost barriers for smaller turboprop fleets.
- LiDAR:Optical ranging for short-range obstacle detection in terminal maneuvering areas.
- GPS:Satellite-based positioning enabling precision approach and terrain overlay functions.
Active Radar anchors current revenue. Passive architectures are gaining share fastest in regional aviation retrofit programs.
End User:
Customer type segmentation reflects divergent procurement authority, budget cycles, and certification expertise across operator categories.
- Commercial Airlines:Scheduled passenger carriers operating under Part 121 or equivalent national regulations with dedicated engineering departments managing fleet-wide avionics standardization. Chinese domestic carriers are expanding narrowbody orders with factory-installed enhanced ground proximity warning systems as standard configuration.
- Private Aviation:Corporate flight departments and high-net-worth owner-operators with discretionary upgrade timelines and price sensitivity to certification costs.
- Cargo Operators:Dedicated freighter fleets with high aircraft utilization rates demanding rapid turnaround on in-service modifications.
- Government Agencies:State aviation units with sovereign procurement authority and customized operational requirements.
Commercial Airlines generate the dominant revenue share. Private Aviation shows the steepest expansion trajectory as fractional ownership platforms standardize safety equipment across managed fleets.
Installation:
Volume concentration varies dramatically between original equipment linefit programs and aftermarket retrofit campaigns driven by regulatory mandate timing.
- Aftermarket:Post-delivery hardware procurement through independent maintenance facilities or direct vendor relationships outside OEM channels. Indonesian low-cost carriers are consolidating avionics procurement under fleet-wide lifecycle agreements that bundle collision avoidance with communications and navigation suites.
- Linefit:Factory installation during airframe assembly with integrated flight deck design optimization and streamlined certification.
- Retrofit:Scheduled heavy maintenance visits incorporating collision avoidance upgrades to satisfy airworthiness directive compliance.
- In-service Modification:Unscheduled equipment replacement or software updates during operational downtime windows.
Retrofit commands the established base. Linefit is expanding most quickly as narrowbody production rates accelerate and factory-installed safety systems become standard specification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FAA mandates for NextGen airspace modernization and terrain awareness equipment are compressing retrofit timelines across United States-registered fleets. Carriers face operational restrictions without compliant collision avoidance architecture.
United States
Domestic carriers are accelerating TCAS upgrades ahead of 2025-2027 regulatory deadlines for Mode S transponder compatibility. The FAA's ADS-B Out mandate sustains hardware demand for integrated surveillance solutions across turbine fleets operating above specified altitude thresholds. Seattle and Wichita manufacturing clusters concentrate avionics integration expertise for Boeing platform linefit programs.
China
Airlines are expanding narrowbody orders with factory-installed enhanced ground proximity warning systems as standard configuration. The Civil Aviation Administration of China's adoption of ICAO Annex 6 provisions drives equipage across rapidly growing domestic fleets. COMAC's Shanghai assembly operations are prioritizing integrated flight deck ecosystems for C919 deliveries.
Germany
Lufthansa Group's fleet standardization programs are pulling forward replacement cycles for aging transponder equipment across A320 family aircraft. EASA certification specifications for CS-ACNS impose extensive software verification requirements that reshape supplier selection criteria. Hamburg's Airbus final assembly line concentrates linefit demand for European narrowbody production.
United Kingdom
British Airways and easyJet are consolidating avionics procurement under fleet-wide lifecycle agreements bundling collision avoidance with communications suites. The UK CAA's harmonization with EASA airworthiness directives maintains regulatory pressure for terrain awareness upgrades. London Gatwick and Manchester maintenance facilities specialize in rapid retrofit campaigns for low-cost carrier fleets.
Japan
ANA and JAL are retrofitting regional turboprop fleets to satisfy ICAO terrain awareness provisions ahead of 2026 compliance deadlines. METI's aviation technology roadmaps emphasize autonomous tracking capabilities that could reshape hardware requirements. Nagoya's aerospace manufacturing corridor supplies sensor components for integrated surveillance systems.
Commercial Aircraft Collision Avoidance System Market Competitive Environment
Diversified industrial conglomerates and specialized defense-electronics houses split the market between integrated flight deck ecosystems and modular retrofit solutions. Tier-one avionics suppliers leverage platform integration contracts to bundle collision avoidance with adjacent systems. Three archetypes dominate: full-stack flight deck integrators, sensor-specialist component suppliers, and military-to-commercial technology transfer players. Competitive moves concentrate on strategic partnerships for urban air mobility algorithm licensing and capacity expansion for gallium nitride radar front-end production.
Among United States-based conglomerates, Honeywell International Inc. and L3Harris Technologies, Inc. exemplify divergent strategic positioning within the avionics tier. Thales Group anchors European supply relationships through its S.A. structure. These three entities represent the dominant competitive anchors across factory linefit and aftermarket retrofit channels.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Thales Group |
| L3Harris Technologies, Inc. |
| Garmin Ltd. |
| Collins Aerospace |
| BAE Systems |
| Saab AB |
| Universal Avionics |
| Leonardo S.p.A. |
| Others |
Value Chain & Pricing Dynamics
The Shanghai-Singapore air freight corridor's rate volatility cascades through collision avoidance system supply chains, amplifying price spreads between factory-linefit and aftermarket retrofit configurations while compressing margins for smaller avionics houses dependent on East Asian gallium nitride foundries.
Pricing Analysis
Geographic price spreads between North American and Asia-Pacific procurement channels exceed thirty percent for equivalent TCAS hardware configurations. Three-tier pricing structure across integrated flight deck suites, standalone collision avoidance modules, and basic terrain awareness units differentiates by certification grade and after-sales service bundling. Cost compression in the standalone module tier is intensifying because Indonesian and Vietnamese low-cost carriers are consolidating fleet-wide lifecycle agreements. Regional turboprop operators exhibit highest price sensitivity, while flag carriers in China and Germany prioritize integration reliability over unit cost.
Supply Chain Analysis
Gallium nitride wafer fabrication feeds from Taiwan, South Korea, and Japan, with radar front-end assembly concentrating in Malaysia and Thailand. Advanced semiconductor substrates, precision aluminum housing extrusions, and aviation-grade connector assemblies draw from specialized tier-two suppliers. Single-source vulnerability in GaN foundry capacity exposes lead time volatility for ADS-B Out transponder production. Distribution runs through OEM-authorized service centers and independent avionics modification facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The commercial aircraft collision avoidance system market sits in early-cycle expansion as urban air mobility platforms and regional connectivity schemes in India and Southeast Asia pull forward equipage timelines beyond traditional airline retrofit cycles.
For Market Incumbents: Build certification moats through DO-178C software expertise capture and EASA CS-ACNS pre-qualification investments. Lock in gallium nitride foundry capacity through multi-year supply agreements before semiconductor allocation tightens. Anchor platform integration contracts with Airbus and Boeing through flight deck ecosystem bundling to forestall modular retrofit competitors. For New Entrants and Emerging Players: Pursue algorithm licensing opportunities in unmanned traffic management and sense-and-avoid systems for urban air mobility platforms. India's UDAN regional turboprop fleet expansion offers the most penetrable geography, with terrain awareness mandates compressing procurement timelines. Target direct relationships with Indonesian and Vietnamese low-cost carriers bypassing established OEM channel structures. For Investors and Strategic Acquirers: Sensor-specialist component suppliers with gallium nitide radar expertise and EASA certification track records represent priority acquisition archetypes. Long-term viability hinges on software-defined avionics transition and autonomous tracking capability integration per ICAO GADSS roadmaps. Monitor FAA airworthiness directive issuance timing as inflection indicator for retrofit demand surges.| Strategic Initiative | Industry Significance |
|---|---|
| GaN Foundry Capacity Lock-in | Secures radar front-end supply for ADS-B Out production against Taiwan Semiconductor allocation constraints. |
| Urban Air Mobility Algorithm Licensing | Opens adjacent revenue streams through sense-and-avoid software for eVTOL platforms in Dubai and Los Angeles corridors. |
| EASA CS-ACNS Pre-Certification | Accelerates European linefit approval for Airbus A320 family integration programs at Hamburg final assembly. |
| Fleet-Wide Lifecycle Agreements | Bundles collision avoidance with communications suites for Indonesian low-cost carrier ten-year service contracts. |
| DO-178C Software Expertise Acquisition | Addresses critical engineer scarcity for safety-critical avionics code verification and model-based design. |
Study Parameters
Operator-level perspectives from airline fleet managers, avionics procurement directors, MRO facility engineering leads, and regulatory compliance officers anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through FAA airworthiness directive filings, EASA certification bulletins, ICAO surveillance standards documentation, and customs trade data for avionics component flows. Bottom-up equipment demand estimates triangulated against top-down fleet projection models across the analysis window.
Scenario-bracketing framed volume and value outputs across product architecture, installation channel, technology category, and regional regulatory cluster dimensions. CAGRs derived from equipment replacement cycle analysis, mandate compliance deadline clustering, and narrowbody production rate trajectories. Forecast inputs incorporated Mode S transponder mandate timing, NextGen equipage penetration curves, and COMAC C919 delivery schedules.
Sensitivities concentrate around gallium nitride foundry allocation shifts, EASA software verification requirement changes, and ICAO autonomous tracking mandate acceleration. Forecasts reflect documented assumptions on regulatory deadline adherence and fleet growth trajectories. Cross-checking against FAA ADS-B Out equipage benchmarks and Airbus delivery disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Safety Systems
Instrument Landing System (ILS) Market
Aircraft Safety Systems
Aircraft Arresting System Market
Aircraft Safety Systems
Aviation Life Rafts Market
Aircraft Safety Systems
Commercial Aircraft Evacuation System Market
Aircraft Safety Systems
Airborne Lightning Detection System Market
Aircraft Safety Systems
Military Aircraft Collision Avoidance Systems Market
Aircraft Safety Systems
Aircraft Ejection Seats Market
Aircraft Safety Systems
South Korea Aircraft Windshield Wiper and Washer System Market
Aircraft Safety Systems
Aircraft Docking Systems Market
Aircraft Safety Systems
Global Aircraft Brake System Market
Aircraft Safety Systems
Aircraft Braking System Market
Aircraft Safety Systems
Identification Friend or Foe Systems Market
Aircraft Safety Systems
Aerospace Lightning Strike Protection Market
Aircraft Safety Systems
Aircraft Survivability Equipment Market
Aircraft Safety Systems
Aviation Airbags Market
Aircraft Safety Systems
Aircraft Smoke Detection and Fire Extinguishing System Market