
 Automatic Dependent Surveillance-Broadcast (ADS-B) Market | 2026-2036
Automatic Dependent Surveillance-Broadcast (ADS-B) Market Size, Share, and Industry Trends Forecast 2026-2036
Automatic Dependent Surveillance-Broadcast (ADS-B) Market Analysis
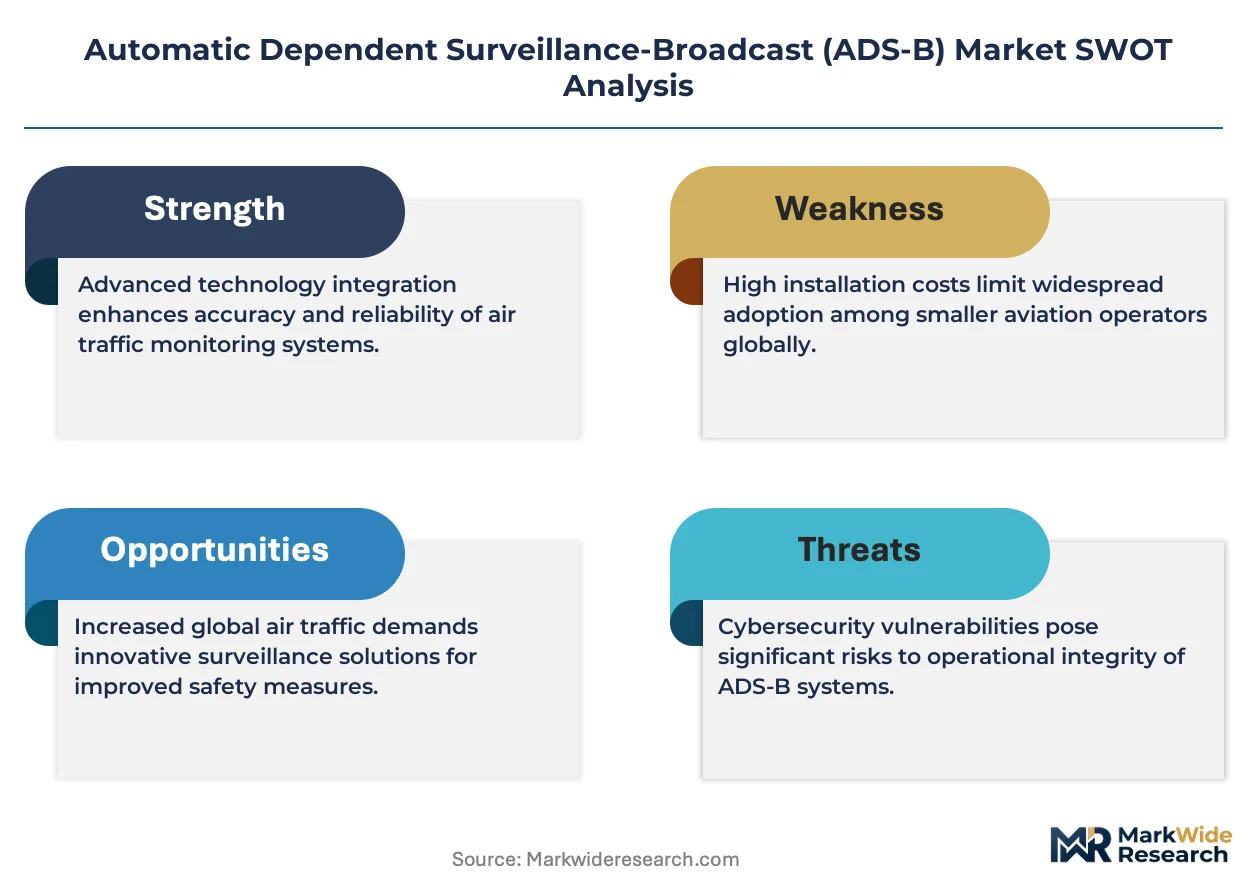
Avionics engineering talent scarcity is redrawing competitive dynamics across the ADS-B supply chain. Garmin Ltd. leverages its vertically integrated manufacturing to control cost structures in general aviation transponders. Honeywell International Inc. anchors the commercial retrofit segment through its established airline service networks. L3Harris Technologies Inc. specializes in military-grade encrypted ADS-B solutions for defense end users.
Automatic Dependent Surveillance-Broadcast constitutes a cooperative surveillance technology where aircraft automatically transmit position, velocity, and identification data via 1090 MHz Extended Squitter or 978 MHz Universal Access Transceiver links to ground stations and other aircraft. The system enables precision air traffic management without traditional radar interrogation. Ground stations represent the mature infrastructure backbone where replacement cycles now dominate new build economics. Avionics commands the fastest-growing product category as mandate deadlines force equipage across aging general aviation and regional jet fleets. Software solutions increasingly concentrate margin pools as operators seek predictive maintenance integration and fleet-wide compliance dashboards.
FAA mandates under 14 CFR 91.225 and EASA implementing rules for ADS-B Out compliance shape retrofit demand curves and certification requirements for equipment manufacturers. The EU Green Deal aviation decarbonization framework indirectly accelerates ADS-B deployment by enabling trajectory-based operations that reduce fuel burn and emissions. Stakeholders must monitor emerging ICAO standards for space-based ADS-B validation as satellite constellations expand coverage beyond terrestrial ground station limits.
Market Dynamics
Mandate-driven retrofit cycles are compressing equipment upgrade timelines across general aviation and regional airline fleets, forcing manufacturers to accelerate certification throughput while managing component scarcity.
Growth Catalysts
- 14 CFR 91.225:FAA ADS-B Out mandates for controlled airspace access drive equipage deadlines across the US general aviation installed base.
- Regional jet operators:EASA implementing rules force avionics refreshes on aging 50-seat fleets operating European trunk routes.
- Space-based ADS-B:Satellite constellation expansion extends surveillance coverage beyond terrestrial ground station limits over oceanic and remote terrain.
Market Restraints
- Semiconductor allocation:Avionics-grade FPGA and RF component lead times stretch 52-78 weeks, throttling transponder production rates.
- Certification backlog:FAA Aircraft Certification Office staffing constraints delay supplemental type certificate approvals for STC-integrated solutions.
- Legacy 1090ES congestion:Spectrum saturation in high-density terminal areas degrades message integrity during peak traffic periods.
Strategic Opportunities
- Brazil:ANAC mandate timelines lag US and European deadlines by 4-7 years, creating extended retrofit demand windows for equipment suppliers.
- Predictive maintenance integration:ADS-B position streams feed fleet health algorithms, opening software subscription revenue pools.
- EU Green Deal aviation:Trajectory-based operations enabled by precise surveillance reduce fuel burn, aligning equipage with emissions compliance budgets.
Industry Challenges
- DO-260B certification expertise:RTCA standard interpretation specialists command 40-60% salary premiums, constraining engineering team scaling.
- Multi-mode transponder integration:Mode S, ADS-B Out, and ADS-B In capability stacking complicates thermal management and antenna placement on smaller airframes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automatic Dependent Surveillance-Broadcast (ADS-B) Market |
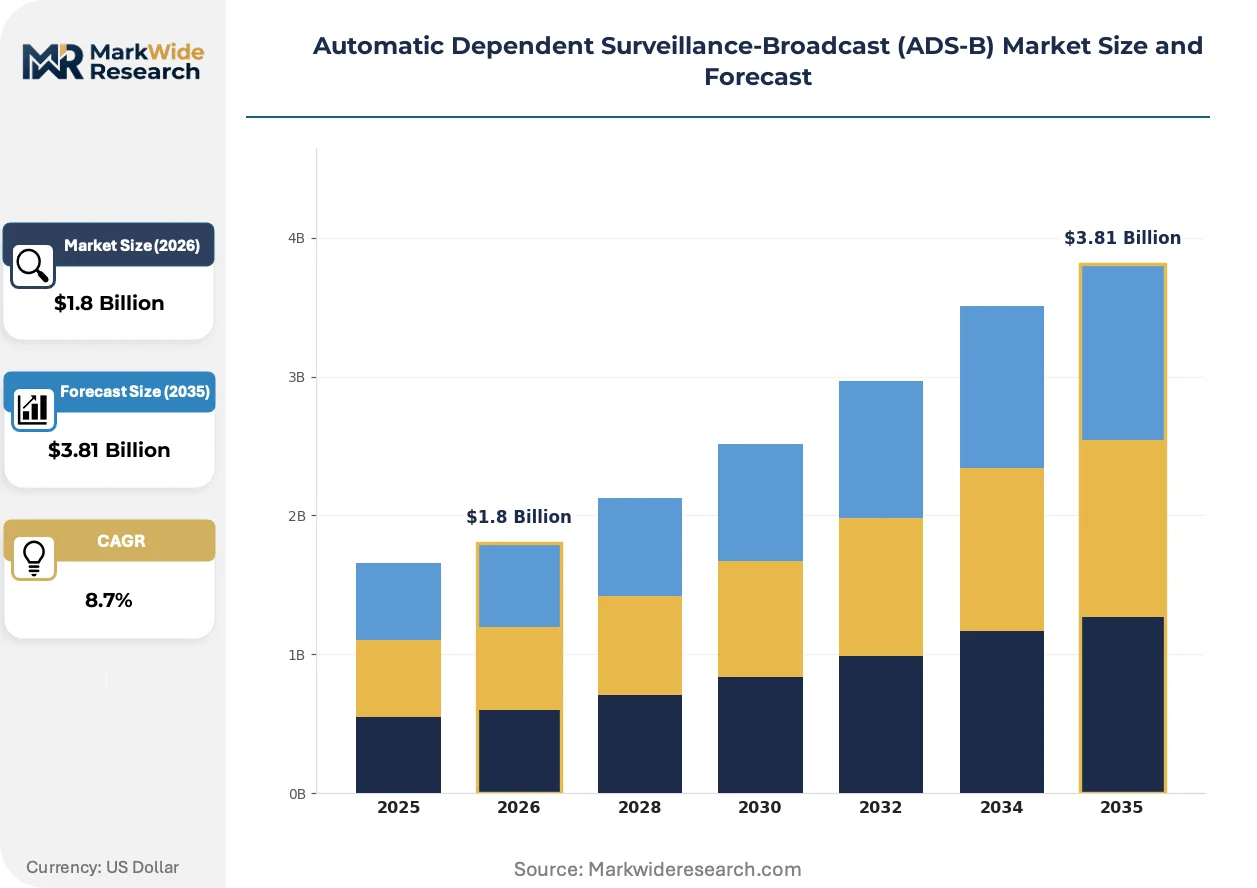
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ground Stations, Avionics, Software Solutions, Data Services End User: Commercial Airlines, General Aviation, Military, Government Agencies Technology: Server-Based, Cloud-Based, Hybrid Systems, Standalone Devices Application: Air Traffic Management, Flight Operations, Aircraft Tracking, Safety Monitoring |
| Companies Covered | Garmin Ltd., Honeywell International Inc., L3Harris Technologies Inc., Thales Group, Collins Aerospace, Indra Sistemas, Aireon LLC, Saab AB, Avidyne Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automatic Dependent Surveillance-Broadcast (ADS-B) Market Emerging Trajectories
Avionics architecture is pivoting toward software-defined functionality, enabling firmware-upgradable surveillance systems that extend hardware lifecycles beyond traditional obsolescence curves.
Multi-function transponder chipsets are miniaturizing. Silicon vendors integrate ADS-B Out, GPS receiver, and attitude reference on single-die solutions. Business jet OEMs adopt these modules for weight reduction on long-range platforms. The technology is miniaturizing antenna and cooling requirements, compressing installation labor hours and STC complexity.
EU Green Deal aviation decarbonization frameworks indirectly accelerate ADS-B deployment. Trajectory-based operations require precise 4D position reporting to optimize descent profiles and reduce holding patterns. European network managers embed ADS-B capability into slot allocation algorithms, affecting equipage priority for carriers serving congested hubs.
Airlines unbundle after-sales service from initial equipment purchase. Carriers negotiate separate maintenance contracts with third-party MRO providers rather than OEM service networks. This fragmentation concentrates in North American and European flag carriers with large mixed fleets, pressuring manufacturer service revenue retention.
Automatic Dependent Surveillance-Broadcast (ADS-B) Market Segmentation
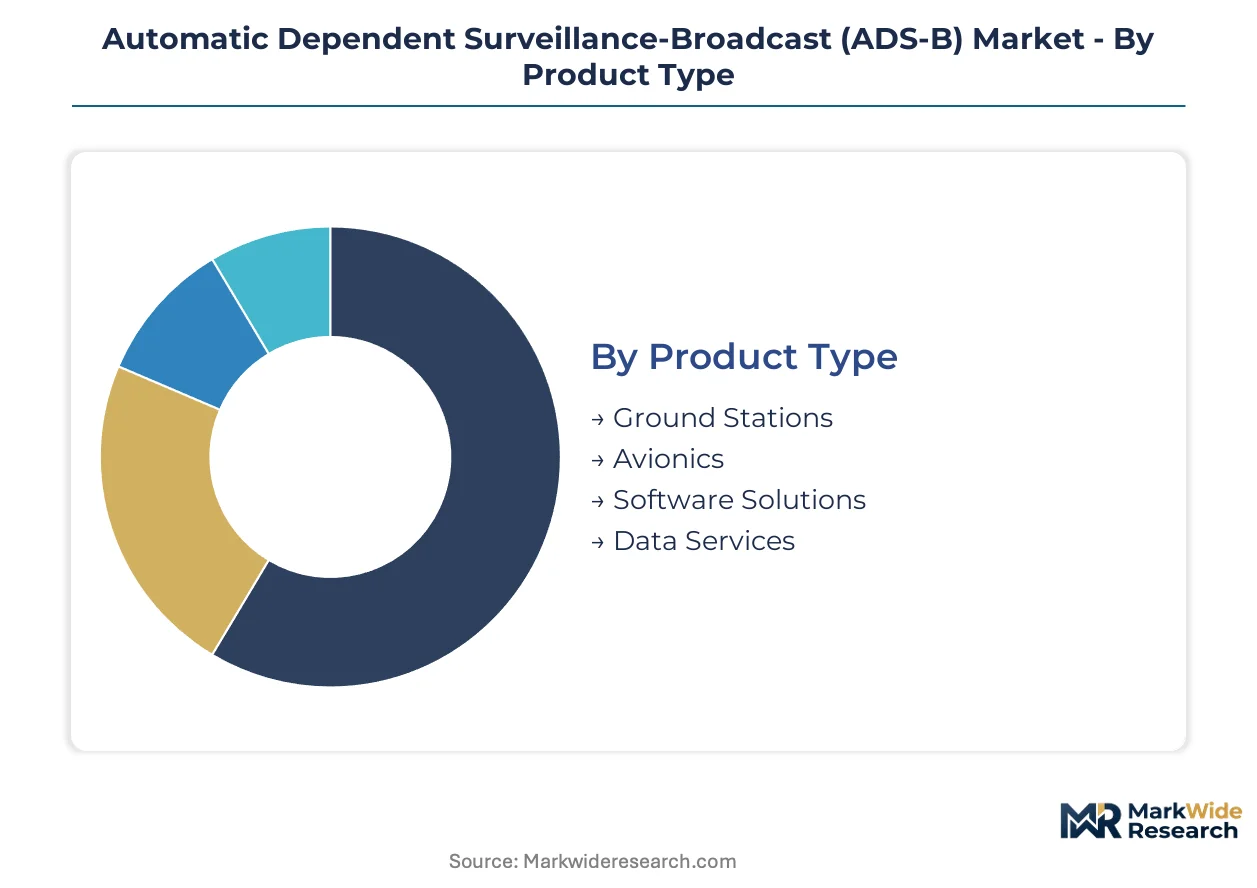
ADS-B market segmentation reveals distinct procurement patterns across product categories. Regulatory mandate timing and fleet composition drive divergent demand curves across each segment dimension.
Product Type:
Ground stations concentrate procurement in North America and Europe where terrestrial infrastructure is mature. Avionics shipments skew toward export markets with pending mandate deadlines.
- Ground Stations:Terrestrial receiver networks operate on 1090 MHz and 978 MHz frequencies with redundant coverage architecture. The United States and Germany host the densest installed bases, though replacement cycles now dominate new build economics as initial mandate waves complete.
- Avionics:Transponder units integrate GPS receivers, altitude encoders, and antenna systems in certified form factors. Brazil and India absorb rising shipment volumes as ANAC and DGCA deadlines approach, stretching OEM certification capacity.
- Software Solutions:Fleet compliance dashboards and predictive maintenance platforms concentrate recurring revenue pools.
- Data Services:Position stream aggregation and analytics layer atop hardware infrastructure.
Ground stations command the established base. The steepest expansion runs through avionics.
End User:
Commercial airlines operate on compressed retrofit timelines driven by airspace access rules. General aviation spreads demand across thousands of individual owners with varied upgrade urgency.
- Commercial Airlines:Flag carriers and low-cost operators maintain dedicated avionics engineering teams to manage STC integration across mixed fleets. United States and European trunk route operators face the most immediate equipage pressure from FAA and EASA mandates.
- General Aviation:Private pilots and flight schools navigate owner-funded upgrade decisions with fragmented purchasing power. The segment spans experimental aircraft builders through certified business jets, creating highly stratified price sensitivity.
- Military:Encrypted transponder requirements and anti-jam specifications drive specialized procurement channels.
- Government Agencies:Coast guard, forestry, and law enforcement fleets pursue mission-specific surveillance integrations.
Commercial airlines anchor current revenue concentration. General aviation is climbing the fastest as mandate deadlines force equipage across aging piston and turboprop fleets.
Technology:
Deployment architecture splits between capital-intensive on-premise systems and operational-expense cloud models. Hybrid configurations dominate mid-scale operators balancing latency requirements against IT overhead.
- Server-Based:On-premise hardware installations deliver sub-100 millisecond latency for high-frequency position updates. Major European air navigation service providers favor this architecture for core air traffic management infrastructure.
- Cloud-Based:Scalable compute resources process ADS-B streams without dedicated data center investment. Regional airlines and charter operators adopt these platforms to avoid avionics engineering headcount expansion.
- Hybrid Systems:Edge processing with cloud aggregation balances real-time and archival workloads.
- Standalone Devices:Portable receivers serve recreational aviation and flight training applications.
Server-based systems retain mission-critical dominance. Cloud-based deployments are gaining share fastest among cost-constrained operators.
Application:
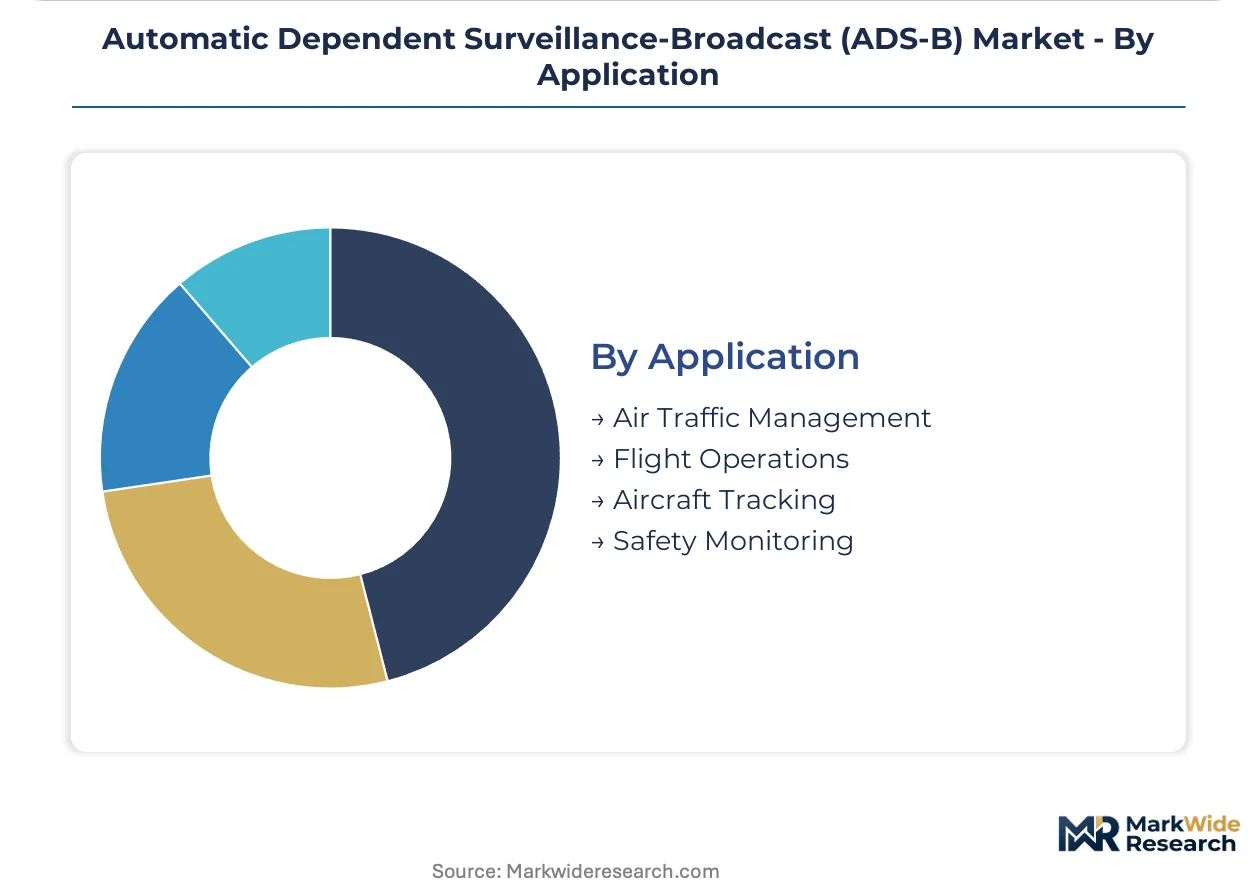
Functional priorities diverge between safety-critical surveillance and operational efficiency use cases. Air navigation service providers prioritize integrity over latency, while airlines emphasize fuel optimization.
- Air Traffic Management:Ground-based surveillance integration enables reduced separation minima and dynamic sectorization. Eurocontrol and FAA NextGen programs anchor demand in the United States and European core routes.
- Flight Operations:Trajectory-based operations and continuous descent approaches reduce fuel burn and emissions. European carriers serving congested hubs embed ADS-B capability into slot allocation algorithms.
- Aircraft Tracking:Beyond-visual-range surveillance supports search and rescue and fleet monitoring.
- Safety Monitoring:Conflict detection and runway incursion alerting layer atop position streams.
Air traffic management holds the installed base. Flight operations shows the steepest trajectory as EU Green Deal decarbonization targets align equipage with emissions compliance budgets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FAA mandates under 14 CFR 91.225 anchor the United States as the dominant geography, compressing retrofit timelines across general aviation and commercial fleets while establishing regulatory templates that other national aviation authorities reference.
United States
Controlled airspace access restrictions and NextGen program investments drive equipage across aging regional jet and turboprop fleets. The FAA Aircraft Certification Office processes supplemental type certificates for integrated transponder solutions. Wichita, Kansas hosts dense concentrations of avionics engineering talent serving STC development for legacy fleet retrofits.
Germany
Eurocontrol network integration and trajectory-based operations deployment create sustained ground station replacement demand. The EU Green Deal aviation decarbonization framework embeds ADS-B capability into slot allocation algorithms at Frankfurt and Munich hubs. The Munich metropolitan area clusters avionics subsystem suppliers serving both commercial airline and business jet OEMs.
Brazil
ANAC mandate timelines lagging US and European deadlines by 4-7 years extend retrofit demand windows for equipment suppliers. The country's national aviation regulator aligns certification requirements with FAA standards to accelerate fleet compliance. São Paulo state concentrates MRO infrastructure where third-party maintenance providers negotiate separate service contracts from OEM networks.
United Kingdom
Heathrow and Gatwick congestion management priorities accelerate ADS-B In equipage for continuous descent approach capabilities. The Civil Aviation Authority implements EASA implementing rules with supplementary noise abatement requirements affecting descent profile optimization. The Thames Valley corridor hosts satellite ground segment providers supporting space-based ADS-B constellation operations.
Australia
Vast oceanic airspace coverage gaps drive space-based ADS-B validation programs for surveillance beyond terrestrial ground station limits. Airservices Australia partners with satellite constellation operators to extend coverage over remote terrain and offshore routes. Brisbane anchors ground infrastructure deployment for Asia-Pacific corridor traffic management integration.
Automatic Dependent Surveillance-Broadcast (ADS-B) Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with consolidated avionics OEMs controlling certification throughput while component suppliers compete on FPGA integration density. The structure divides between vertically integrated transponder manufacturers and modular subsystem specialists. Two strategic archetypes dominate: mandate-driven retrofit service providers and software-defined surveillance platform developers. Competitive moves concentrate on M&A for DO-260B certification expertise and strategic partnerships for satellite ground segment integration.
Within the integrated systems tier, Garmin Ltd. and Honeywell International Inc. exemplify divergent vertical scope strategies, with the former representing captive manufacturing control over general aviation transponder cost structures and the latter anchoring commercial airline retrofit service networks. L3Harris Technologies Inc. occupies a position within the defense-specialist archetype, reflecting demand for encrypted transponder specifications among military end users.
| Leading Market Players |
|---|
| Garmin Ltd. |
| Honeywell International Inc. |
| L3Harris Technologies Inc. |
| Thales Group |
| Collins Aerospace |
| Indra Sistemas |
| Aireon LLC |
| Saab AB |
| Avidyne Corporation |
| Others |
Supply Flow & Price Mechanics
Certification throughput economies at FAA Aircraft Certification Office and EASA designee organizations concentrate supply-side leverage among established OEMs, compressing price floors for STC-integrated solutions while elevating premiums for DO-260B interpretation expertise.
Pricing Analysis
Long-term offtake contracts dominate commercial airline procurement, locking transponder volumes across multi-year fleet retrofit programs. Three-tier pricing structure across certified-transport, general-aviation, and portable-receiver levels reflects certification-grade differentiation and after-sales bundling. Cost compression in general-aviation tiers intensifies because semiconductor allocation constraints throttle production rates. Private pilots and flight schools exhibit highest price sensitivity, while flag carriers with dedicated avionics engineering teams absorb premium positioning for integrated solutions.
Supply Chain Analysis
The United States and Germany anchor avionics subsystem production, with Taiwan and South Korea feeding FPGA and RF component supply. Transponder manufacturing draws from avionics-grade semiconductors, GPS receiver modules, and altitude encoder subassemblies. Single-source vulnerability concentrates in 1090 MHz Extended Squitter chipset supply. Distribution runs through OEM direct sales for commercial airlines and avionics distributors serving general aviation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ADS-B market expansion sits in early-cycle penetration across Brazil, India, and Southeast Asia where mandate deadlines lag established markets by four to seven years, creating extended retrofit demand windows.
For Market Incumbents: Fortify certification capacity investments at FAA and EASA designee organizations to defend throughput advantage against emerging modular-subsystem specialists. Deepen in-house production of FPGA-integrated transponder chipsets to offset semiconductor allocation constraints. Prioritize software-defined surveillance platform development to extend hardware lifecycles beyond traditional obsolescence curves. For New Entrants and Emerging Players: Differentiate on predictive maintenance integration and fleet compliance dashboard subscriptions where recurring-revenue pools concentrate. Target Brazil and India general aviation retrofit segments where ANAC and DGCA deadlines stretch demand curves and OEM certification capacity is constrained. Pursue third-party MRO partnership channels to bypass incumbent airline service network lock-in. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among software solutions providers layering analytics atop hardware infrastructure. Five-to-ten-year viability favors acquisition targets with DO-260B certification expertise and satellite ground segment integration capabilities. Monitor space-based ADS-B validation program milestones as inflection indicator for surveillance coverage expansion beyond terrestrial limits.| Strategic Initiative | Industry Significance |
|---|---|
| DO-260B Certification Investment | Accelerates supplemental type certificate throughput at FAA Aircraft Certification Office. |
| Satellite Ground Segment Partnership | Extends surveillance coverage for Airservices Australia oceanic airspace programs. |
| Software-Defined Transponder Development | Enables firmware-upgradable systems for EU Green Deal trajectory-based operations. |
| Predictive Maintenance Platform Launch | Captures recurring revenue from regional airline fleet health algorithm subscriptions. |
| Brazil Market Expansion | Positions for ANAC mandate deadline surge across São Paulo MRO infrastructure. |
Methodological Framework
Cross-validation between primary interviews with avionics engineering directors, airline fleet managers, and FAA certification specialists and secondary validation through FAA 14 CFR filings, EASA implementing rule documentation, and Eurocontrol network performance reports anchors the qualitative findings. Bottom-up equipment shipment modeling triangulates against top-down mandate deadline analysis across regulatory jurisdictions.
Sensitivity analysis runs across the projection horizon against semiconductor lead time volatility and certification office staffing constraints. Segmentation dimensions modeled include product type, end user, technology deployment architecture, and application function. CAGRs derive from mandate-driven retrofit cycle timing and fleet composition analysis. Forecast inputs incorporate space-based ADS-B constellation deployment schedules and EU Green Deal aviation decarbonization framework implementation.
Material uncertainties — regulatory deadline extensions, semiconductor allocation disruptions, and ICAO space-based validation standard revisions — sit outside the modeled envelope. Forecasts reflect assumptions about mandate enforcement continuity and certification throughput capacity. Recalibration cycles align with material shifts in ANAC and DGCA regulatory timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Navigation and Communication
Defense Advanced GPS Receiver (DAGR) Market
Aircraft Navigation and Communication
Aircraft Turn Coordinator Market
Aircraft Navigation and Communication
Asia-Pacific Air Traffic Management Market
Aircraft Navigation and Communication
America Air Traffic Management Market
Aircraft Navigation and Communication
Global Aircraft Antenna Market
Aircraft Navigation and Communication
In Flight Connectivity Market
Aircraft Navigation and Communication
Global Air Traffic Control Equipment Market
Aircraft Navigation and Communication
Airborne Situational Awareness Systems Market
Aircraft Navigation and Communication
Global Aviation Mapping Software Market
Aircraft Navigation and Communication
5G in Aviation Market
Aircraft Navigation and Communication
Europe Inertial Systems Market
Aircraft Navigation and Communication
Helicopter Meteorological Software Market
Aircraft Navigation and Communication
Airborne High Frequency Radio Market
Aircraft Navigation and Communication
Air Traffic Management Market
Aircraft Navigation and Communication
Airborne Telemetry Market
Aircraft Navigation and Communication
Air Traffic Management Software Market