
 Helicopter Ice Protection Systems Market | 2026-2036
Helicopter Ice Protection Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Helicopter Ice Protection Systems Market Foresight
Certified flight-into-known-icing (FIKI) capability is reorganizing procurement priorities across the helicopter ice protection systems market. Leonardo S.p.A. leverages integrated platform development to bundle ice protection with airframe deliveries. Curtiss-Wright Corporation anchors military aftermarket channels through sustainment contracts with defense operators. Meggitt PLC specializes in electro-thermal mat technologies for main and tail rotor applications.
Helicopter ice protection systems encompass electro-thermal, pneumatic, and hybrid technologies that prevent or remove ice accumulation on rotor blades, engine inlets, and flight control surfaces, maintaining aerodynamic performance and flight safety in sub-zero, moisture-laden conditions. De-icing systems dominate current retrofit spending as operators upgrade legacy fleets to meet evolving airworthiness standards, while anti-icing systems capture premium positioning on new deliveries where line-fit integration reduces installation complexity. Electric technology segments are gaining fastest traction as battery and power distribution advances enable weight reductions compared to bleed-air pneumatic alternatives.
FAA Part 29 certification requirements and EASA CS-29 icing envelopes shape product development roadmaps and market access thresholds for system suppliers. Military procurement through NAVAIR and European defense agencies imposes additional environmental and electromagnetic compatibility standards that filter vendor participation. Stakeholders must monitor evolving hybrid-electric propulsion architectures, as distributed power systems will redefine thermal management budgets and ice protection integration strategies on next-generation rotorcraft platforms.
Market Dynamics
FAA Part 29 certification mandates for flight-into-known-icing capability are compressing retrofit timelines and forcing operators to prioritize certified electro-thermal suites over legacy pneumatic alternatives. Military sustainment contracts and offshore oil fleet renewals concentrate procurement volumes toward qualified suppliers.
Growth Catalysts
- Electro-thermal mat technology:Weight reductions from distributed power architectures enable retrofit feasibility on legacy airframes previously excluded from ice protection upgrades.
- NAVAIR procurement frameworks:US Navy and Marine Corps helicopter modernization programs mandate FIKI capability for maritime patrol and search-and-rescue fleets.
- Gulf Coast offshore services:Oil platform helicopter operators in Louisiana and Texas face seasonal icing exposure that drives recurring de-icing system demand.
Market Restraints
- High-purity nickel-chromium alloy supply:Electro-thermal heating element production depends on concentrated Russian and Chinese metallurgical supply chains subject to export control volatility.
- Certification timeline friction:FAA Part 29 amendment cycles and EASA CS-29 harmonization delays extend product qualification periods beyond typical R&D amortization windows.
- Bleed-air pneumatic legacy lock-in:Existing turbine helicopter architectures with integrated engine bleed systems create switching costs that slow electric technology penetration.
Strategic Opportunities
- Urban air mobility platforms:eVTOL developers require integrated ice protection for commercial certification, creating greenfield demand outside traditional rotorcraft supply relationships.
- Canadian Arctic SAR expansion:Federal fleet renewals for Coast Guard and mounted police helicopter operations specify FIKI as mandatory for year-round northern deployment.
- Battery thermal management convergence:Hybrid-electric propulsion architectures enable shared power distribution between propulsion and ice protection subsystems.
Industry Challenges
- Multiphysics simulation talent scarcity:Coupled aerodynamic, thermal, and electromagnetic modeling for rotor ice accretion requires specialized computational fluid dynamics expertise concentrated at select aerospace engineering programs.
- Legacy avionics integration complexity:Retrofit installations on pre-digital cockpit helicopters demand custom control interface development that fragments engineering resource allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Helicopter Ice Protection Systems Market |
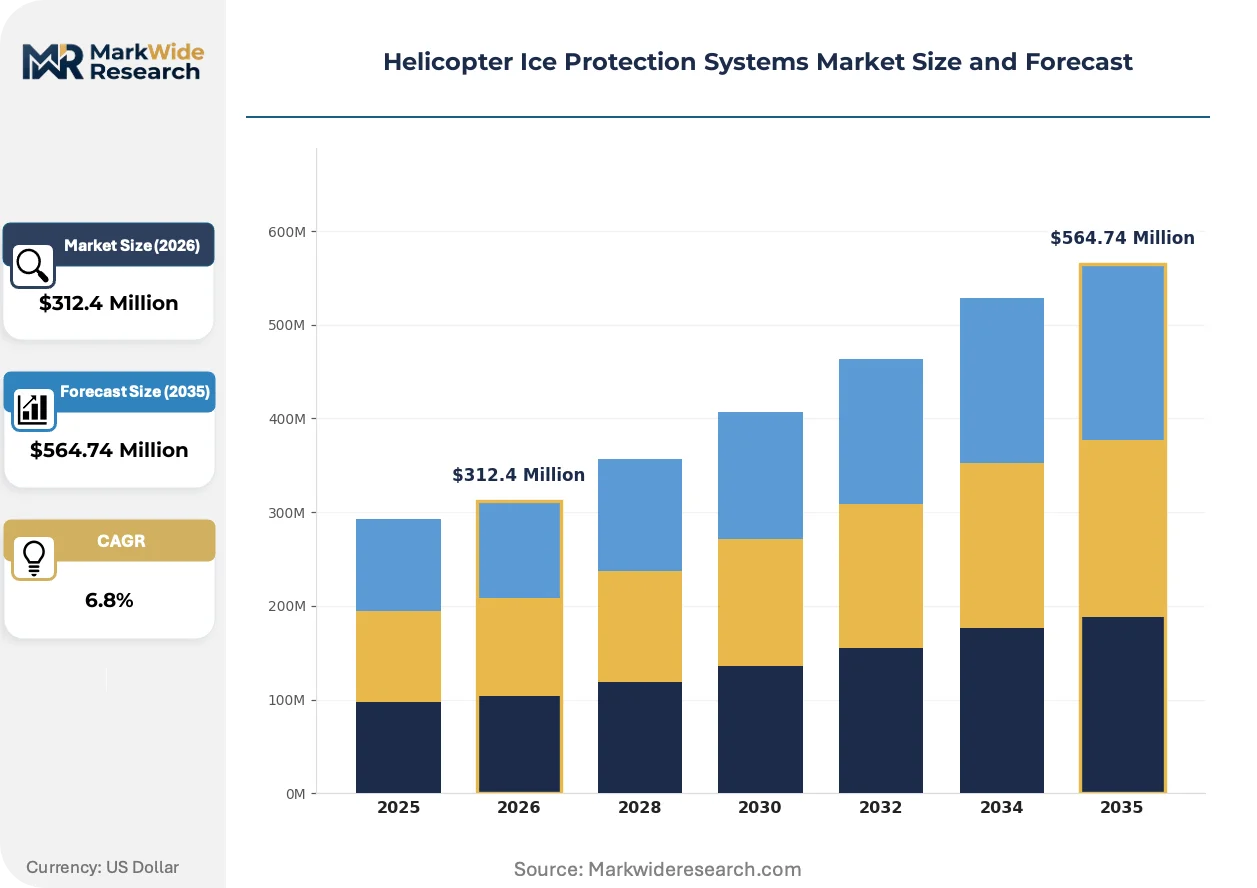
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: De-icing Systems, Anti-icing Systems, Component Heaters, Ice Detection Systems End User: Military, Civil Aviation, Emergency Services, Private Operators Installation Type: Retrofit, Line Fit, Maintenance Upgrade, Modifications Technology: ELECTRIC, Thermal, Pneumatic, Hybrid |
| Companies Covered | Leonardo S.p.A., Curtiss-Wright Corporation, Meggitt PLC, Melrose Industries PLC, Cox & Company, Inc., Liebherr-International AG, Safran SA, Honeywell International Inc., Collins Aerospace, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Helicopter Ice Protection Systems Market Shifts & Advancements
Electrification of thermal management systems is collapsing the traditional boundary between propulsion and protection subsystems. Certification authorities are rewriting airworthiness criteria to accommodate solid-state heating technologies that lack the mechanical complexity of pneumatic boots.
Carbon nanotube heating films embedded in composite rotor skins are supplanting wire-wound resistance mats in next-generation ice protection architectures. Leonardo and Sikorsky derivative programs are specifying these materials for reduced mass and improved heat flux uniformity. The technology is supplanting conventional electro-thermal approaches across premium new-build contracts where line-fit integration permits structural redesign.
EASA CS-29 icing envelope expansions adopted in 2023 now require demonstrated protection performance across supercooled large droplet conditions previously excluded from certification bases. European offshore operators face mandatory compliance deadlines that compress retrofit scheduling. Twin-engine helicopters serving North Sea oil platforms constitute the most affected segment, with leasing companies accelerating pre-lease modification programs.
Aftermarket service contracts are unbundling from original equipment sales as independent MRO providers achieve Part 145 certification for electro-thermal system overhaul. European and North American helicopter operators now source ice protection maintenance separately from airframe heavy checks. This pattern is most visible in the United Kingdom, where Bristow and CHC Helicopter have consolidated third-party service agreements for their SAR and offshore fleets.
Helicopter Ice Protection Systems Market Segmentation
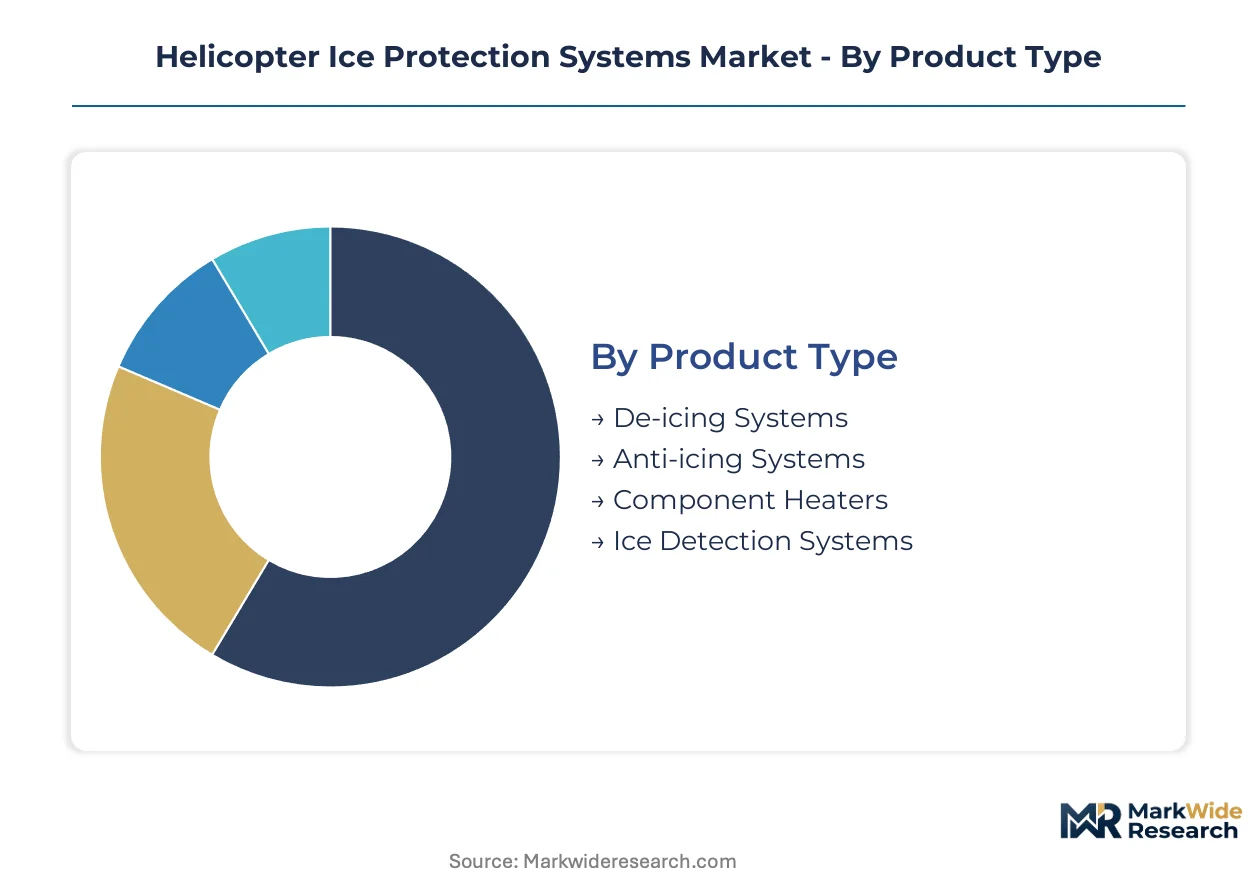
Helicopter ice protection systems fragment across four critical dimensions that determine procurement pathways, certification requirements, and supplier relationships. Each segmentation axis carries distinct regulatory implications and shapes how operators balance retrofit economics against new-build integration costs.
Product Type:
FAA Part 29 and EASA CS-29 certification mandates create divergent performance thresholds across product categories, with FIKI-capable systems commanding premium positioning.
- De-icing Systems:Cyclic heating cycles remove accumulated ice from rotor blades and control surfaces after formation. Retrofit demand concentrates in United States Gulf Coast offshore fleets where seasonal icing exposure drives recurring upgrade schedules.
- Anti-icing Systems:Continuous thermal prevention maintains ice-free surfaces during sustained flight into known icing conditions. New-build helicopter deliveries specify these systems for line-fit integration that reduces installation complexity and weight penalties.
- Component Heaters:Targeted thermal protection for engine inlets, pitot tubes, and sensor housings prevents localized ice accumulation that degrades instrument reliability.
- Ice Detection Systems:Optical and vibrating probe technologies trigger automated heating activation, reducing pilot workload during instrument meteorological conditions.
De-icing systems handle the majority of throughput; anti-icing systems are expanding most quickly on share.
End User:
Procurement patterns vary sharply across operator types, with defense and emergency services imposing stringent environmental and electromagnetic compatibility standards that filter vendor participation.
- Military:NAVAIR procurement frameworks mandate FIKI capability for maritime patrol and search-and-rescue helicopter fleets, with sustainment contracts anchoring aftermarket revenue.
- Civil Aviation:Offshore oil platform operators in Louisiana and Texas face seasonal icing exposure that drives recurring de-icing system demand and fleet renewal cycles.
- Emergency Services:Search-and-rescue helicopter operators require year-round northern deployment capability, with Canadian Arctic fleet renewals specifying mandatory FIKI equipment.
- Private Operators:Corporate and utility helicopter owners prioritize retrofit economics over line-fit premiums, concentrating demand on certified electro-thermal upgrade kits.
Military and civil aviation absorb the dominant procurement volumes; emergency services show the steepest expansion trajectory as Arctic SAR capabilities expand.
Installation Type:
Installation pathway determines engineering resource allocation, with legacy avionics integration complexity fragmenting supplier development priorities across retrofit versus new-build channels.
- Retrofit:Post-delivery installation on existing airframes demands custom control interface development for pre-digital cockpit helicopters, extending qualification timelines.
- Line Fit:Factory-integrated ice protection reduces installation complexity and enables structural optimization, capturing premium positioning on Leonardo and Sikorsky derivative programs.
- Maintenance Upgrade:Scheduled heavy check incorporation of ice protection capabilities spreads capital expenditure across operational budgets.
- Modifications:Special mission configuration changes for seasonal or geographic deployment requirements drive intermittent demand spikes.
Retrofit installations command the largest addressable base; line fit claims the fastest share gain as new-build delivery rates recover.
Technology:
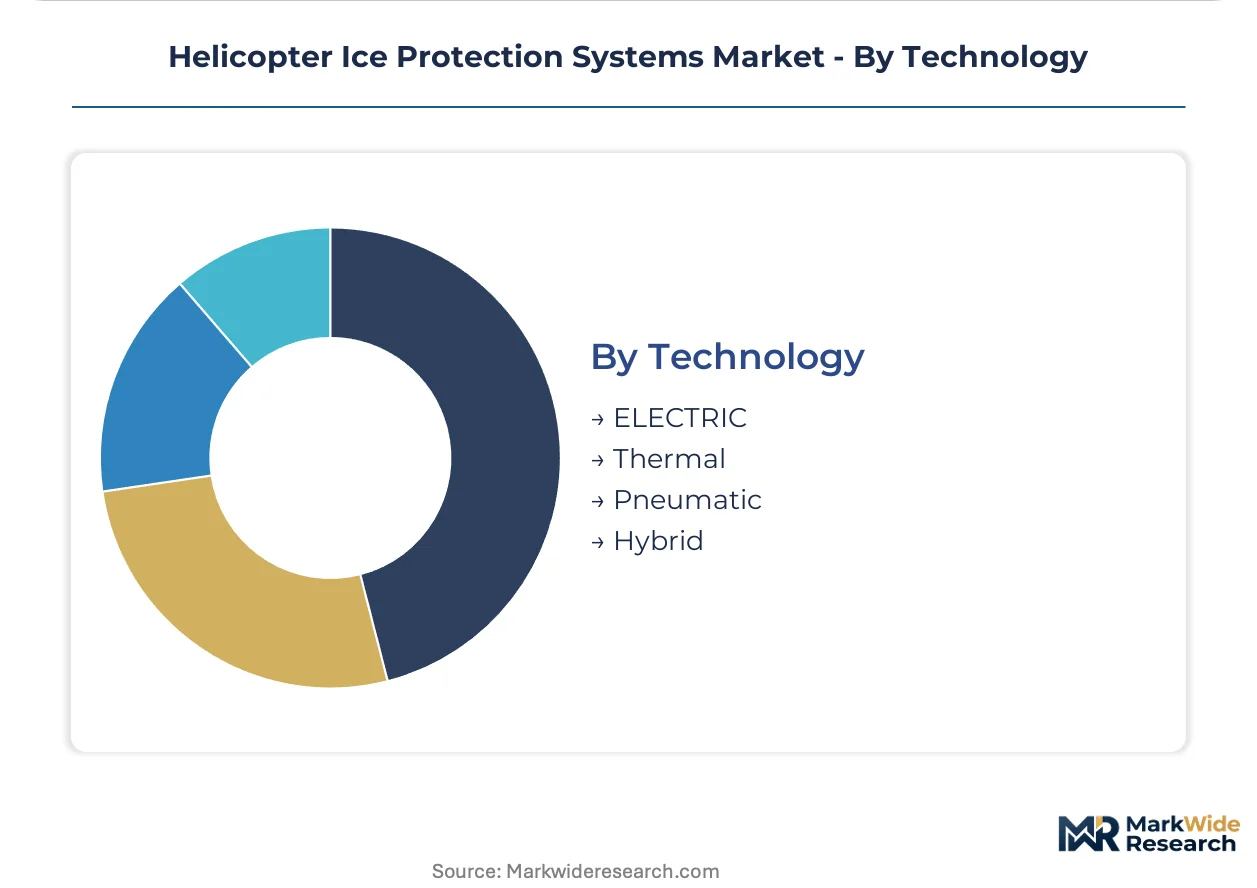
Power distribution architecture evolution is collapsing traditional boundaries between propulsion and protection subsystems, with distributed electric systems enabling weight reductions that expand addressable retrofit markets.
- ELECTRIC:Distributed electro-thermal mat technologies leverage battery and power electronics advances to displace bleed-air alternatives, with carbon nanotube heating films embedding in composite rotor skins for reduced mass.
- Thermal:Resistive wire-wound heating elements in nickel-chromium alloys remain prevalent on legacy platforms, though supply chain concentration in Russian and Chinese metallurgical sources creates procurement risk.
- Pneumatic:Engine bleed-air inflatable boots face switching cost barriers from integrated turbine architectures, limiting penetration outside established fleet bases.
- Hybrid:Combined electro-thermal and pneumatic architectures optimize energy efficiency across varying icing severity conditions.
Electric technology is climbing the fastest on adoption curves; thermal systems retain the largest installed base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows of nickel-chromium heating alloys and electro-thermal subassemblies concentrate from Russian and Chinese metallurgical centers toward Western rotorcraft manufacturers, while finished ice protection systems move from Italian, American, and British assembly plants to offshore helicopter operators across the North Sea and Gulf of Mexico.
United States
NAVAIR procurement frameworks and Gulf Coast offshore oil services generate concentrated demand for FIKI-certified retrofit kits. FAA Part 29 amendment cycles tighten certification timelines for electro-thermal system suppliers. Houston and New Orleans host dense clusters of helicopter operators facing seasonal icing exposure that drives recurring fleet upgrades.
Canada
Federal Arctic search-and-rescue fleet renewals mandate year-round FIKI capability for Coast Guard and mounted police helicopter deployments. Transport Canada harmonizes icing certification requirements with FAA Part 29 standards. Calgary and St. John's serve as operational hubs for North Sea and northern territory helicopter services expanding ice protection retrofits.
United Kingdom
North Sea oil platform helicopter operators face EASA CS-29 supercooled large droplet compliance deadlines that compress retrofit scheduling. Bristow and CHC Helicopter consolidate third-party MRO service agreements for electro-thermal system overhaul. Aberdeen anchors the European offshore helicopter cluster most affected by expanded icing envelope requirements.
Italy
Leonardo S.p.A. bundles ice protection with airframe deliveries on derivative helicopter programs, capturing premium line-fit positioning. EASA certification harmonization with FAA standards shapes product development roadmaps for European suppliers. Milan-Turin aerospace corridor concentrates integrated platform development for next-generation rotorcraft thermal management.
Norway
North Sea offshore helicopter services operate under stringent icing exposure conditions that drive anti-icing system specification on new-build deliveries. Petroleum Safety Authority requirements reinforce FIKI capability for personnel transport to offshore installations. Stavanger hosts concentrated helicopter operator presence tied to oil platform logistics.
Helicopter Ice Protection Systems Market Competitive Landscape
Concentration sits with diversified aerospace conglomerates that leverage integrated platform development and military sustainment contracts to anchor market position. Tiered supplier relationships separate airframe-integrated system providers from component specialists focused on electro-thermal mat technologies. Strategic archetypes include platform-integrated conglomerates bundling ice protection with helicopter deliveries, military aftermarket specialists securing long-term sustainment agreements, and electro-thermal component suppliers targeting retrofit channels. Competitive moves center on certification pre-qualification for expanded EASA icing envelopes and technology licensing for carbon nanotube heating film integration.
Within the platform-integrated tier, Leonardo S.p.A. exemplifies bundled airframe and ice protection development, while Curtiss-Wright Corporation occupies a position anchoring military aftermarket channels through defense operator relationships. Meggitt PLC represents the electro-thermal specialization archetype focused on main and tail rotor applications.
| Leading Market Players |
|---|
| Leonardo S.p.A. |
| Curtiss-Wright Corporation |
| Meggitt PLC |
| Melrose Industries PLC |
| Cox & Company, Inc. |
| Liebherr-International AG |
| Safran SA |
| Honeywell International Inc. |
| Collins Aerospace |
| Others |
Supply & Pricing Matrix
Carbon nanotube heating film substitution for wire-wound nickel-chromium mats is redrawing supplier geography and collapsing the cost premium between electro-thermal and pneumatic architectures. This materials transition concentrates procurement leverage with composite rotor manufacturers in Italy and the United States while fragmenting legacy alloy supply relationships tethered to Russian and Chinese metallurgical centers.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on FAA Part 29 certification tier and line-fit versus retrofit installation complexity. Cost compression in economy-tier retrofit kits is intensifying because independent MRO providers achieve Part 145 certification for electro-thermal overhaul. Civil aviation operators show highest price sensitivity; military sustainment contracts demonstrate lowest sensitivity due to mandated FIKI compliance.
Supply Chain Analysis
Inventory buffers for nickel-chromium alloys have lengthened to eighteen-month coverage as export control volatility disrupts Russian and Chinese supply channels. Raw material sourcing draws from South African platinum group deposits, Australian nickel laterite, and Canadian chromium ferroalloy production. Single-source vulnerability concentrates in high-purity nickel-chromium wire drawing. Distribution runs through Leonardo and Sikorsky airframe integrators for line-fit systems, with aftermarket channels fragmenting toward independent MRO networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in helicopter ice protection are converging around hybrid-electric propulsion architectures that share power distribution between propulsion and thermal management subsystems. This interoperability shift rewards suppliers who architect systems for bidirectional energy flow rather than unidirectional heating loads.
For Market Incumbents: Compound certification pre-qualification advantages by securing EASA CS-29 supercooled large droplet approval ahead of 2023 amendment compliance deadlines. Deepen backward integration into carbon nanotube heating film production to capture margin from materials substitution. Lock in military sustainment contracts through performance-based logistics agreements that extend NAVAIR relationships beyond initial procurement cycles. For New Entrants and Emerging Players: Aftermarket software integration for legacy cockpit ice protection controls represents the most penetrable service-layer gap, as incumbents under-serve pre-digital helicopter retrofits with custom interface development. Target Canadian Arctic search-and-rescue fleet renewals where federal mandates specify mandatory FIKI equipment without established supplier relationships. Pursue battery thermal management convergence partnerships with eVTOL developers seeking integrated ice protection for commercial certification pathways. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed electro-thermal component specialists holding FAA Part 29 certification but lacking platform-integrated airframe relationships. Five-to-ten year viability favors suppliers positioned at the intersection of military aftermarket anchoring and urban air mobility greenfield demand. Watch for carbon nanotube heating film licensing agreements as the inflection signal indicating which mid-cap specialists secure structural integration partnerships with Leonardo or Sikorsky derivative programs.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Pre-Qualification Investment | EASA CS-29 supercooled large droplet approval compresses competitor entry timelines for North Sea operators. |
| Carbon Nanotube Heating Film Licensing | Composite rotor skin integration partnerships with Leonardo capture premium line-fit positioning on derivative programs. |
| Performance-Based Logistics Agreements | NAVAIR sustainment contracts anchor military aftermarket revenue through multi-decade fleet support commitments. |
| Battery Thermal Management Convergence | Shared power distribution architectures with eVTOL developers open greenfield demand outside traditional rotorcraft supply chains. |
| Independent MRO Certification Pursuit | Part 145 electro-thermal overhaul approval fragments aftermarket service relationships away from airframe-integrated providers. |
Research Methodology
Desk research of FAA certification databases, EASA regulatory filings, and NAVAIR procurement records preceded structured interviews with rotorcraft platform engineers, electro-thermal system procurement leads at offshore helicopter operators, military sustainment contract managers, and independent MRO certification specialists. Secondary validation drew from airframe manufacturer technical specifications, metallurgical trade flow data, and helicopter fleet utilization reports. Bottom-up unit economics triangulated against top-down market sizing across technology and installation type segments.
Variance decomposition across product type, end user, installation pathway, and technology dimensions shaped the analytical framework over the projection horizon. Modeled segmentation captured de-icing versus anti-icing system economics, military versus civil procurement patterns, retrofit versus line-fit engineering resource allocation, and electric versus pneumatic power architecture evolution. CAGRs derived from installed base turnover rates, fleet renewal schedules, and regulatory compliance deadline clustering. Forecast inputs incorporated hybrid-electric propulsion development timelines and carbon nanotube heating film commercialization trajectories.
Underlying assumptions cover steady FAA-EASA certification harmonization progress and sustained offshore oil platform helicopter utilization, with deviation risk concentrated in nickel-chromium alloy export control escalation and multiphysics simulation talent scarcity extending product qualification timelines. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Safety Systems
Airborne Collision Avoidance System Market
Aircraft Safety Systems
South Korea Aircraft Windshield Wiper and Washer System Market
Aircraft Safety Systems
Free Fall Sensor Market
Aircraft Safety Systems
Cloud-Connected Aircraft Safety Data Management Platforms Market
Aircraft Safety Systems
Global Aircraft Brakes Market
Aircraft Safety Systems
Military Airborne Collision Avoidance Systems (ACAS) Market
Aircraft Safety Systems
Aircraft Survivability Equipment Market
Aircraft Safety Systems
Aviation Life Rafts Market
Aircraft Safety Systems
Instrument Landing System (ILS) Market
Aircraft Safety Systems
Rescue Hoist System Market
Aircraft Safety Systems
Aircraft Door Dampers Market
Aircraft Safety Systems
Commercial Aircraft Evacuation System Market
Aircraft Safety Systems
Aircraft Evacuation Slide Market
Aircraft Safety Systems
Aircraft Docking Systems Market
Aircraft Safety Systems
Aerospace Lightning Strike Protection Market
Aircraft Safety Systems
Aviation Airbags Market