

Aircraft Radome Impact Detection Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Radome Impact Detection Systems Market Insights
Defense contractors are gaining procurement share as military fleet readiness priorities intensify, reorganizing supplier relationships across the value chain. Collins Aerospace leverages fiber optic sensor integration to sustain technology leadership in embedded monitoring architectures. Northrop Grumman anchors classified platform programs where radome integrity directly affects mission survivability. Safran competes through European manufacturing scale and channel control with Airbus and Dassault supply chains.
Aircraft radome impact detection systems comprise sensor arrays, signal conditioning units, and data processing modules that monitor composite or ceramic nosecone structures for hail, bird strike, and debris damage in real time. Fiber optic sensors dominate current installations due to electromagnetic immunity and multiplexing capacity across large apertures, while acoustic emission sensors capture the fastest growth in military applications requiring passive threat detection. Real-time monitoring technology occupies the deepest margin pools as airlines shift from scheduled inspections to condition-based maintenance models.
FAA airworthiness directives and EASA certification standards mandate damage tolerance documentation for critical structural components, directly expanding retrofit demand among legacy fleet operators. Military procurement further channels through NAVAIR and JAA technical publications that specify impact detection as a reliability requirement for low-observable radomes. Stakeholders must weigh embedded system architectures against wireless retrofit solutions as platform lifecycles extend and certification pathways diverge.
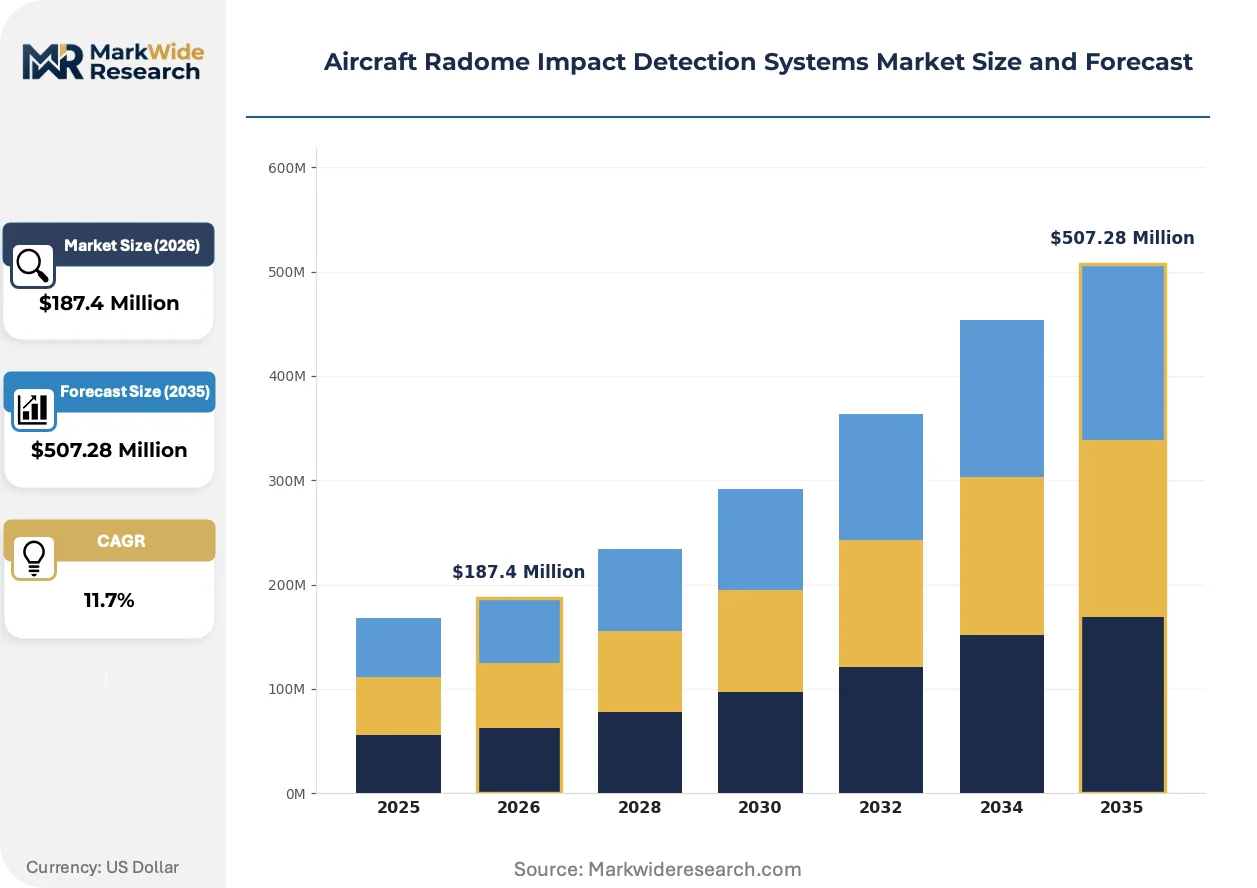
Market Dynamics
Fleet-wide condition-based maintenance mandates from FAA and EASA are collapsing scheduled inspection intervals into continuous structural monitoring, forcing sensor architecture redesigns across both retrofit and new-build programs.
Growth Catalysts
- Airworthiness Directive Compliance:FAA damage tolerance documentation requirements for critical nosecone structures mandate real-time monitoring systems on commercial fleets undergoing heavy maintenance checks.
- Fiber Optic Multiplexing:Electromagnetic immunity and single-fiber coverage of large apertures enable consolidated wiring architectures that reduce installation labor on composite radomes.
- Military Survivability Specifications:NAVAIR technical publications designate impact detection as mandatory for low-observable radomes on next-generation strike platforms, anchoring defense procurement volume.
Market Restraints
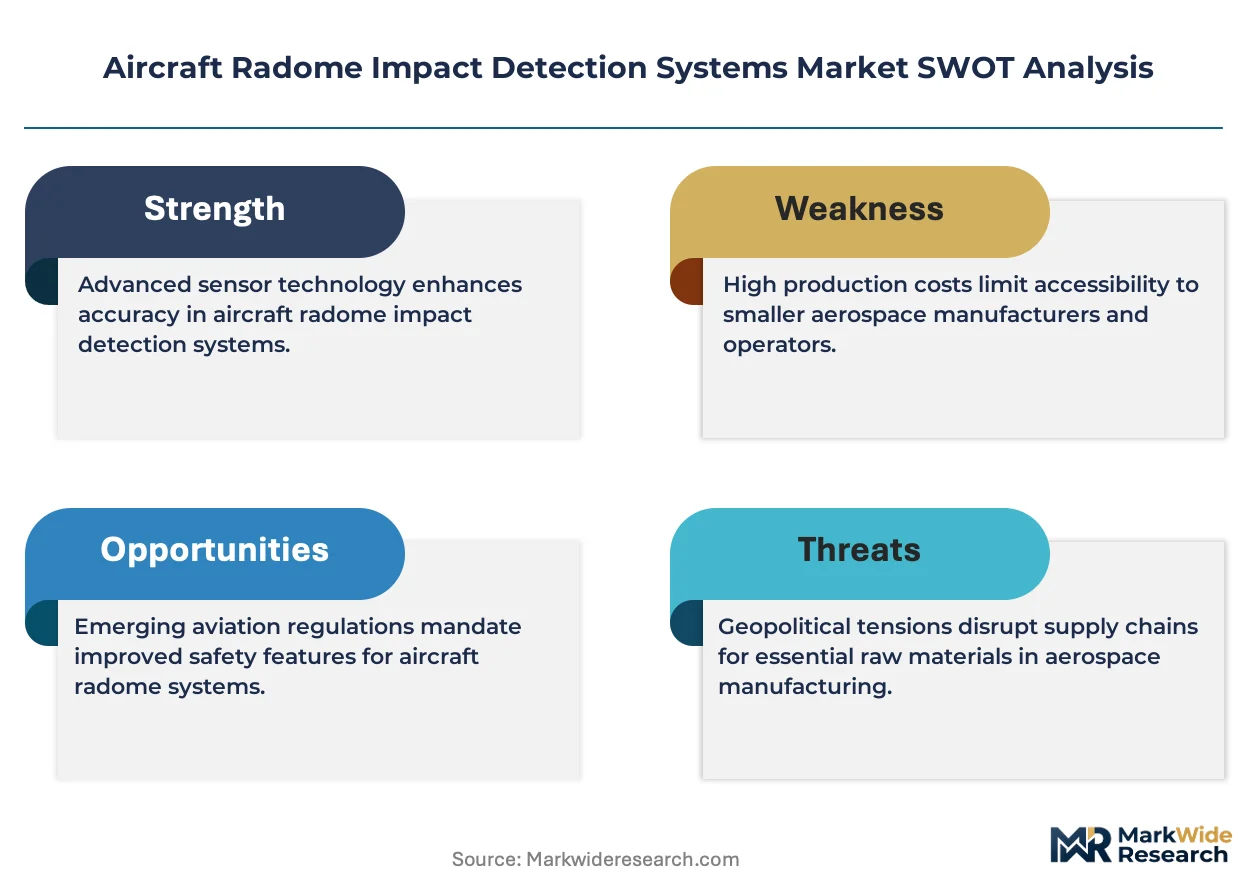
- Specialized Sensor Cost Structure:Precision fiber Bragg grating arrays and photonic interrogators carry 3-4x unit economics versus conventional strain gauges, compressing retrofit ROI on narrow-body fleets.
- Supply Concentration in Photonics:High-performance optical components concentrate among German and Japanese specialty manufacturers, exposing lead time vulnerability to semiconductor foundry allocation.
- Certification Pathway Friction:EASA's evolving CS-25 interpretation for embedded structural health systems creates documentation ambiguity that extends supplemental type certificate timelines.
Strategic Opportunities
- Indian Defense Modernization:Hindustan Aeronautics Limited's indigenous combat aircraft programs lack qualified domestic impact detection suppliers, creating partnership entry points for technology transfer arrangements.
- Acoustic Emission Convergence:Passive threat detection requirements in military applications are driving hybrid fiber-acoustic architectures that capture both impact location and damage progression signatures.
- Wireless Retrofit Channels:Battery-powered surface-mounted sensor networks bypass embedded installation certification burdens, opening aftermarket access to aging regional jet fleets without structural modification.
Industry Challenges
- Multiphysics Simulation Talent Scarcity:Coupled optical-mechanical modeling for radome-specific sensor placement requires expertise spanning photonics, composite mechanics, and electromagnetic propagation that remains concentrated at national laboratories and tier-one primes.
- Platform-Specific Integration Complexity:Each aircraft radome geometry demands custom sensor routing and calibration, preventing scalable hardware platforms and fragmenting engineering resource allocation across low-volume programs.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Radome Impact Detection Systems Market Trends and Innovations
Real-time structural monitoring is compressing maintenance economics from calendar-based to condition-triggered interventions, rewiring supplier relationships and certification strategies across commercial and defense procurement channels.
Distributed fiber optic sensing is decomposing discrete strain gauge installations into continuous spatial measurement domains. Commercial airlines retrofitting A320 and 737 fleets adopt these systems during C-check intervals to eliminate repetitive manual inspections. The technology is decomposing traditional non-destructive testing service contracts into permanent embedded infrastructure, shifting revenue from inspection labor to sensor hardware and data analytics subscriptions.
EASA's evolving CS-25 certification standards for damage tolerance documentation now explicitly reference structural health monitoring as an acceptable compliance pathway. This regulatory recognition accelerates supplemental type certificate approvals for retrofit installations on legacy platforms. European operators with mixed Airbus-Boeing fleets are consolidating procurement specifications to capture economies across maintenance programs, pressuring suppliers toward interoperable data formats.
Airline technical procurement departments now bundle impact detection hardware into power-by-the-hour maintenance contracts rather than capitalizing standalone sensor purchases. Third-party maintenance repair and overhaul providers capture this bundled spend, displacing direct OEM sensor sales in the retrofit channel. This consolidation concentrates supplier negotiation leverage with Lufthansa Technik, ST Engineering, and AAR Corp in North America and Singapore.
Aircraft Radome Impact Detection Systems Market Segmentation
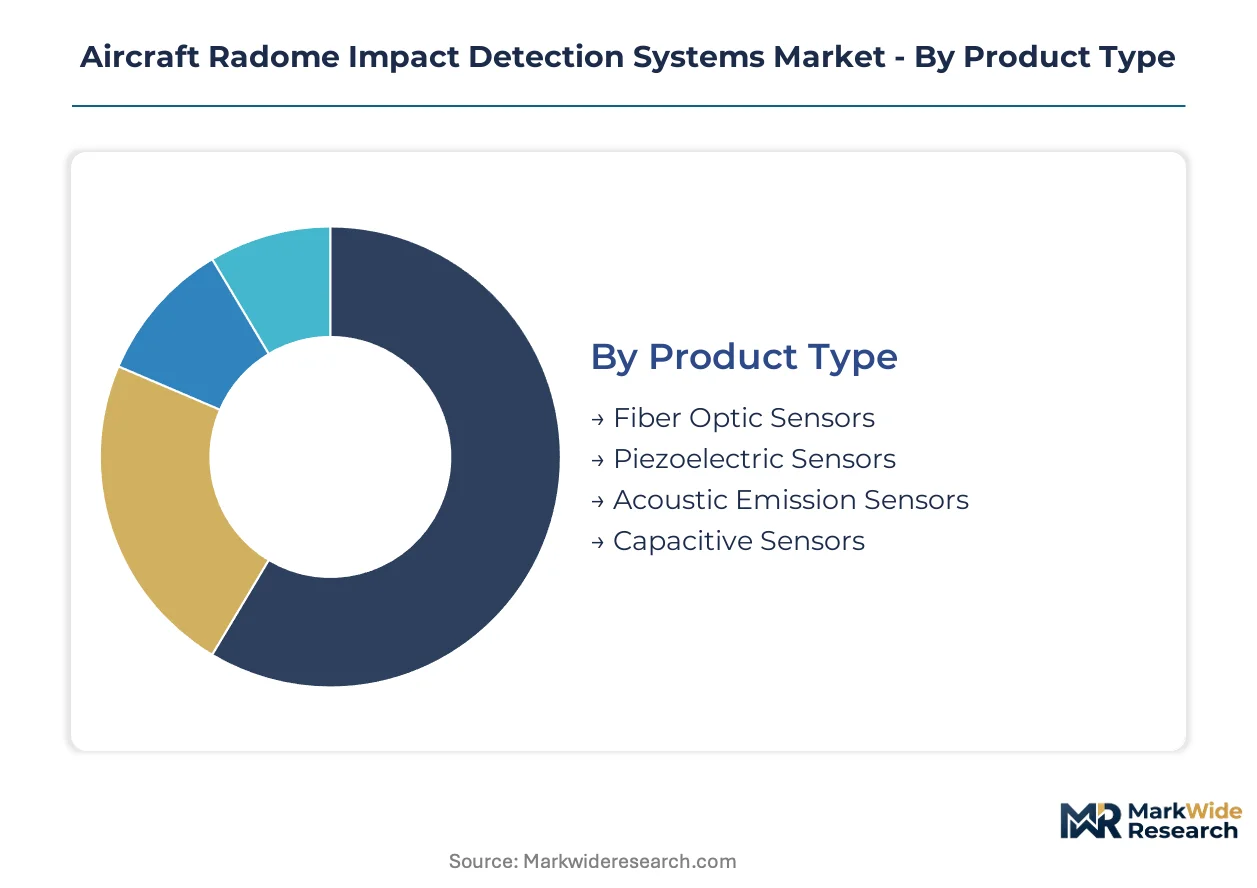
Segmentation in aircraft radome impact detection systems reveals distinct procurement patterns across defense and commercial channels. Each dimension—sensor modality, integration architecture, platform type, and buyer category—carries unique certification requirements and margin structures that reshape supplier positioning.
Product Type:
Fiber optic sensors dominate domestic US and European supply chains where electromagnetic immunity requirements anchor procurement specifications. Piezoelectric alternatives concentrate in Asian manufacturing clusters serving cost-sensitive regional retrofit programs.
- Fiber Optic Sensors:Fiber Bragg grating arrays embedded within composite radome laminates provide distributed strain measurement with single-fiber multiplexing across large apertures. Demand concentrates in Boeing and Airbus new-build programs where FAA and EASA certification pathways favor electromagnetic immunity. Installation labor savings on wide-body nosecones justify premium unit economics.
- Acoustic Emission Sensors:Passive piezoelectric transducers detect stress wave propagation from impact events without continuous excitation power. Military procurement through NAVAIR technical specifications drives adoption on low-observable strike platforms where signature management restricts active sensor emissions. Passive threat detection requirements accelerate hybrid architecture development.
- Piezoelectric Sensors:Constrained lead zirconate titanate elements deliver high-frequency response for localized damage characterization in regional jet applications.
- Capacitive Sensors:Proximity-based dielectric measurement suits metallic radome structures on legacy military transport platforms with limited composite penetration.
Fiber optic sensors hold the largest share; momentum sits with acoustic emission configurations.
Technology:
Real-time monitoring architectures command margin premiums as airlines shift from calendar-based to condition-triggered maintenance. Wireless transmission systems expand fastest in aging fleet retrofit channels where embedded installation certification burdens deter structural modification.
- Real-Time Monitoring:Continuous data acquisition through onboard processing units enables immediate damage localization and severity assessment. Lufthansa Technik and ST Engineering bundle these systems into power-by-the-hour contracts, consolidating procurement leverage with maintenance repair and overhaul providers. Condition-based maintenance mandates from FAA and EASA accelerate supplemental type certificate approvals.
- Wireless Transmission:Battery-powered surface-mounted sensor networks eliminate structural penetration requirements. Regional operators in India and Southeast Asia deploy these on aging A320 and 737 fleets during C-check intervals without airframe modification. Reduced certification friction opens aftermarket access to narrow-body operators with constrained capital budgets.
- Embedded Systems:Factory-integrated sensor routing during radome manufacture captures new-build procurement from Boeing, Airbus, and Dassault supply chains.
- Signal Processing Algorithms:Machine learning-based damage classification software differentiates hail, bird strike, and debris impact signatures for automated maintenance dispatch decisions.
Real-time monitoring captures the deepest margin pools; wireless transmission is climbing the fastest as retrofit demand intensifies.
Application:
Commercial aircraft anchor procurement volume through fleet modernization programs at American Airlines, Delta, and United. Military jets concentrate specification influence with defense primes integrating survivability requirements into platform design.
- Commercial Aircraft:Single-aisle and wide-body fleets from Boeing and Airbus drive sensor installation during heavy maintenance checks. FAA airworthiness directives for damage tolerance documentation mandate structural health monitoring as acceptable compliance pathway. European operators consolidate procurement specifications across mixed fleets to capture maintenance economies.
- Military Jets:Low-observable radomes on next-generation strike platforms require impact detection as mandatory reliability specification per NAVAIR and JAA technical publications. Northrop Grumman and Lockheed Martin anchor classified program demand where radome integrity directly affects mission survivability. Classified platform integration prevents commercial technology transfer.
- Unmanned Aerial Vehicles:Swappable nosecone architectures on tactical drones favor modular sensor packages with rapid field replacement protocols.
- Business Aircraft:Gulfstream and Dassault Falcon operators adopt fiber optic systems for reduced scheduled inspection burden on high-utilization corporate fleets.
Commercial aircraft command the largest installed base; military jets concentrate the steepest technology specification requirements.
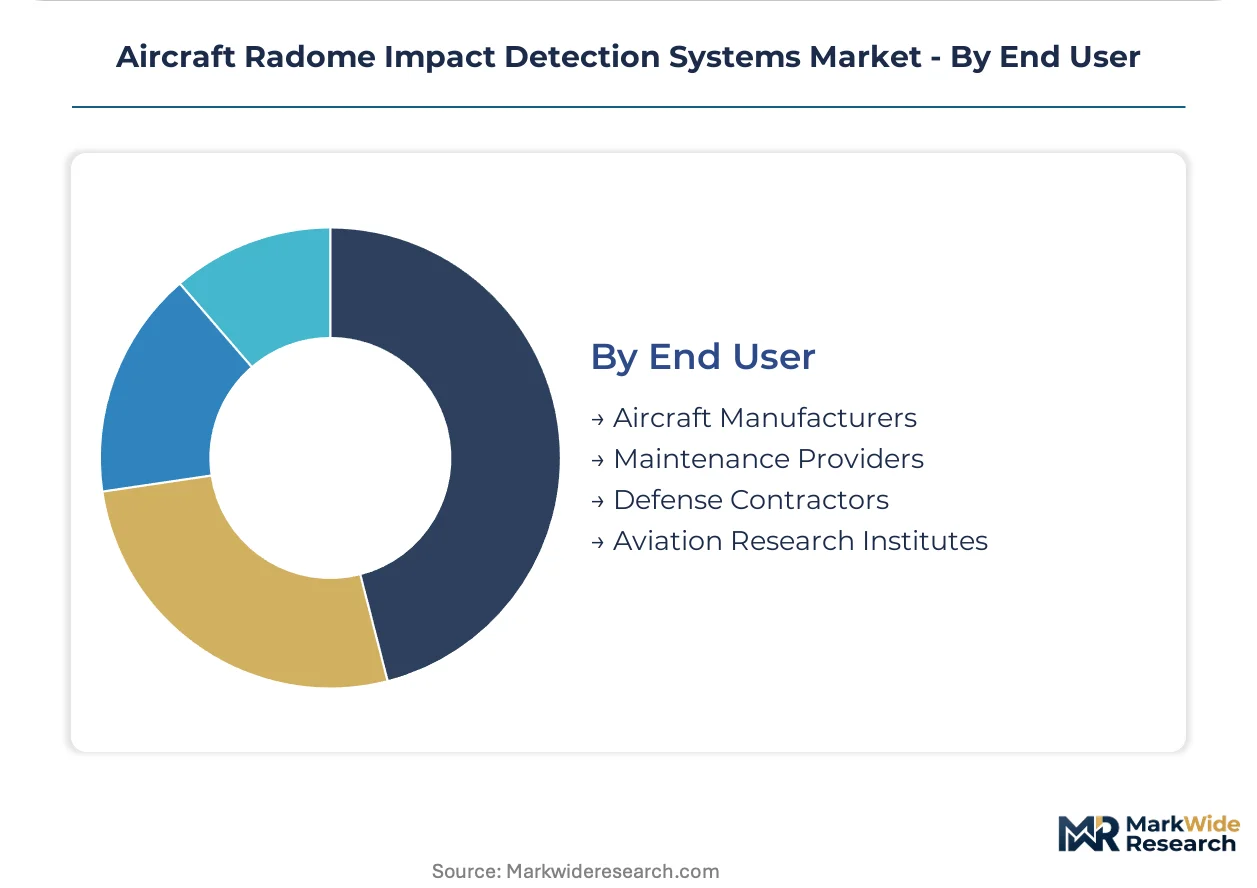
End User:
Aircraft manufacturers integrate sensors during original radome production, capturing specification control. Maintenance providers displace direct OEM sales through bundled power-by-the-hour contracts.
- Aircraft Manufacturers:Boeing, Airbus, and Dassault specify embedded sensor architectures during platform design, locking supplier relationships through production runs. Collins Aerospace and Safran compete for factory installation contracts with interoperable data format commitments. New-build procurement carries longest contract horizons and deepest integration requirements.
- Defense Contractors:Lockheed Martin, Northrop Grumman, and BAE Systems mandate impact detection for low-observable radomes through classified platform specifications. National security restrictions limit supplier pools to cleared domestic manufacturers. Technology transfer barriers protect incumbent positions.
- Maintenance Providers:Lufthansa Technik, AAR Corp, and ST Engineering capture retrofit demand through bundled maintenance contracts displacing standalone sensor capital purchases.
- Aviation Research Institutes:NASA, ONERA, and DLR validate sensor performance through multiphysics simulation and flight test programs shaping future certification standards.
Aircraft manufacturers retain specification control; maintenance providers are gaining procurement share fastest through contract restructuring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Photonics manufacturing concentrates in Germany and Japan, exposing radome sensor supply chains to semiconductor foundry allocation pressures. Defense procurement anchors demand in the United States through NAVAIR specifications for low-observable platforms. Commercial retrofit volumes concentrate where FAA and EASA maintenance mandates intersect with aging narrow-body fleet density.
United States
Boeing anchors new-build demand while defense primes drive classified platform specifications. FAA airworthiness directives for damage tolerance documentation mandate real-time monitoring during heavy maintenance checks. Seattle and Wichita clusters concentrate embedded sensor integration for 737 and 787 production lines.
Germany
Lufthansa Technik bundles impact detection hardware into power-by-the-hour contracts, consolidating procurement leverage across European fleets. EASA CS-25 certification standards explicitly recognize structural health monitoring as compliance pathway. Hamburg and Munich maintenance hubs drive retrofit sensor installations on A320 family aircraft.
France
Airbus and Dassault supply chains anchor factory-integrated sensor specifications for new-build radomes. DGAC coordinates with EASA on supplemental type certificate approvals for embedded structural monitoring. Toulouse and Bordeaux aerospace clusters concentrate composite radome manufacturing with integrated fiber optic architectures.
United Kingdom
BAE Systems and defense procurement channels specify impact detection for Eurofighter and classified platform radomes. CAA alignment with EASA damage tolerance standards accelerates retrofit approvals for legacy narrow-body fleets. Bristol and Broughton manufacturing sites concentrate sensor integration for Airbus wing and nosecone programs.
Japan
Japan Airlines and ANA retrofit programs drive demand during C-check intervals on aging 737 and 767 fleets. METI industrial policy supports domestic fiber optic sensor development to reduce import dependence on German photonics suppliers. Nagoya aerospace cluster concentrates Mitsubishi Heavy Industries radome production for regional jet platforms.
Aircraft Radome Impact Detection Systems Market Competitive Landscape
Concentration sits with diversified aerospace primes and specialized sensor technology providers. Tier-one defense contractors capture classified platform specifications through NAVAIR and JAA reliability mandates, while commercial aftermarket channels consolidate around maintenance repair and overhaul bundling. Three archetypes dominate: integrated avionics suppliers with factory-installation relationships, defense-focused survivability specialists, and photonics component manufacturers supplying embedded sensor arrays. Competitive moves center on strategic partnerships for technology transfer into emerging defense markets and vertical integration into fiber Bragg grating manufacturing to secure optical component supply.
Among diversified aerospace conglomerates, Honeywell International and Raytheon Technologies occupy positions spanning commercial avionics and defense platform integration. Collins Aerospace exemplifies the integrated sensor architecture archetype through its fiber optic embedded monitoring focus. Safran represents European manufacturing scale with channel control across Airbus and Dassault supply chains. Northrop Grumman anchors the defense-specialist tier where radome integrity specifications directly affect mission survivability on classified strike platforms.
| Leading Market Players |
|---|
| Honeywell International |
| Airbus |
| Collins Aerospace |
| Thales Group |
| Raytheon Technologies |
| Boeing |
| Lockheed Martin |
| Northrop Grumman |
| Safran |
| Others |
Pricing and Supply Chain Analysis
Factory-installed fiber optic architectures on Boeing and Airbus new-build programs achieve unit economics 40% below retrofit equivalents, concentrating margin capture with OEM-integrated suppliers while compressing aftermarket price floors. This scale differential forces standalone sensor vendors toward wireless retrofit channels where certification burdens limit price competition.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FAA-certified embedded systems from EASA-aligned wireless retrofits and uncertified regional alternatives. Price differentiation rests on certification grade and volume scale, with narrow-body fleet operators exhibiting highest sensitivity. Pricing pressure stems from photonics component shortages as German and Japanese specialty manufacturers allocate semiconductor foundry capacity to automotive lidar programs.
Supply Chain Analysis
Strait of Hormuz transit exposure for germanium and rare-earth dopants used in fiber Bragg grating manufacture elevates raw material risk premiums across photonics supply chains. Manufacturing concentrates in Germany, Japan, and the United States, drawing from specialty silica preforms, precision optical coatings, and semiconductor-grade photodetectors. Single-source vulnerability in high-performance optical interrogators forces inventory pre-positioning. Distribution runs through Boeing and Airbus tier-one avionics integrators, with maintenance repair and overhaul providers capturing growing retrofit share.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation among European maintenance repair and overhaul providers into power-by-the-hour bundling has shifted procurement leverage away from sensor OEMs, fragmenting buyer power across distinct channel archetypes.
For Market Incumbents: Compound technology leadership in fiber optic multiplexing through captive supply of photonic interrogators, insulating against semiconductor foundry allocation shocks. Lock factory-installation relationships with Boeing and Airbus through interoperable data format commitments that raise switching costs for rival embedded architectures. Prioritize certification investment in EASA CS-25 supplemental type certificate pathways to accelerate retrofit approvals before wireless competitors bypass structural modification requirements. For New Entrants and Emerging Players: Aftermarket data analytics under-serve regional operators in India and Southeast Asia lacking predictive maintenance infrastructure. Target wireless retrofit channels on aging A320 and 737 fleets during C-check intervals, where battery-powered surface-mounted sensors eliminate embedded installation certification burdens. Pursue technology transfer partnerships with Hindustan Aeronautics Limited to access Indian defense modernization programs lacking qualified domestic impact detection suppliers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors photonics component manufacturers with backward integration into fiber Bragg grating production. Long-term viability hinges on securing optical supply chains as automotive lidar demand competes for specialty foundry capacity. Watch for EASA clarification on CS-25 damage tolerance documentation standards as inflection indicator for retrofit market acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Photonics Manufacturing Integration | Captive fiber Bragg grating production insulates Collins Aerospace and Safran against German and Japanese supplier lead time volatility. |
| Wireless Retrofit Platform Launch | Battery-powered surface-mounted networks bypass EASA certification friction for regional operators in India and Southeast Asia. |
| Defense Technology Transfer Partnership | Hindustan Aeronautics Limited collaborations open Indian combat aircraft programs to qualified impact detection suppliers. |
| Maintenance Contract Bundling | Lufthansa Technik and ST Engineering consolidate procurement leverage through power-by-the-hour sensor inclusion. |
| Hybrid Fiber-Acoustic Architecture Development | Passive threat detection capabilities address NAVAIR specifications for low-observable strike platform survivability. |
Research Methodology
A standing panel of avionics procurement directors, airline maintenance executives, fiber optic sensor engineers, and defense program managers provided ongoing calibration across primary interview cycles. Secondary validation drew from FAA airworthiness directive filings, EASA certification documentation, NAVAIR technical publications, and customs records of photonics component trade flows. Bottom-up sensor installation estimates triangulated against top-down fleet modernization projections.
Consistency checks validated volume and value outputs against Boeing and Airbus delivery schedules, defense procurement disclosures, and maintenance repair and overhaul contract announcements. The analytical framework modeled sensor modality, integration architecture, platform type, and buyer category segmentation throughout the forecast period. CAGRs derived from fleet age distributions, regulatory mandate timelines, and technology substitution curves for acoustic emission versus fiber optic modalities.
Forecasts assume regulatory continuity in FAA damage tolerance documentation and EASA CS-25 interpretation; material policy shifts would require re-modeling of retrofit demand timing. Semiconductor foundry allocation volatility and evolving military survivability specifications present specific revision risks. Practitioners should keep alternative scenarios live as photonics supply constraints and defense procurement acceleration evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.