
 Aircraft Door Dampers Market | 2026-2036
Aircraft Door Dampers Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Door Dampers Market Analysis
Consolidation among commercial aviation original equipment manufacturers is realigning supplier relationships across the aircraft door dampers value chain. Collins Aerospace leverages its integrated landing systems portfolio to sustain long-term contracts with major airframers. Moog Inc. anchors the electromechanical segment through precision motion control capabilities. Hutchinson Aerospace competes on elastomer-to-metal bonding expertise for vibration isolation applications.
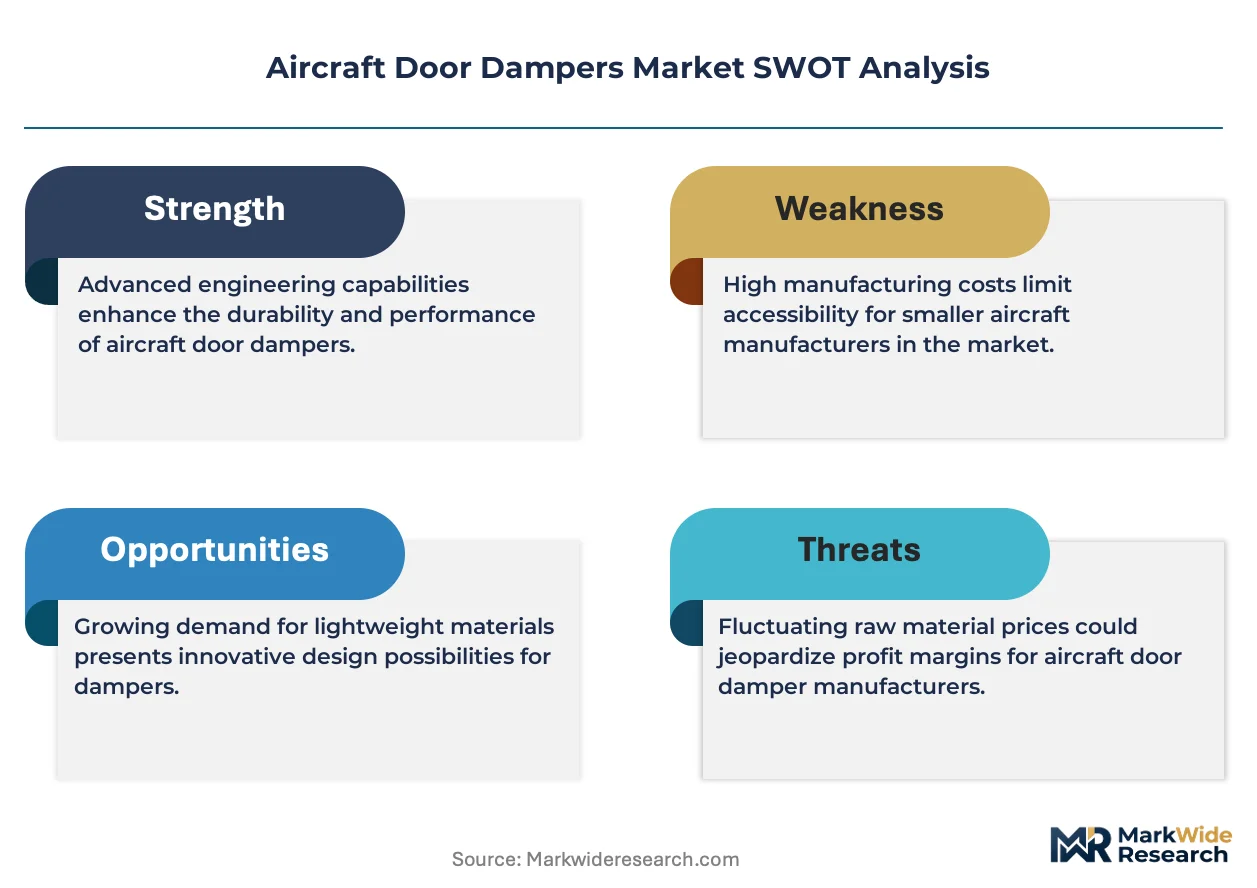
Aircraft door dampers are force-modulating devices installed on fuselage apertures to control opening and closing kinematics, typically operating across temperature ranges from minus 55 to plus 85 degrees Celsius while withstanding cyclic fatigue loads exceeding 100,000 operations. Hydraulic dampers dominate the product type landscape due to proven reliability in heavy cargo door applications, while electromechanical variants capture the fastest growth trajectory as fly-by-wire architectures proliferate. Composite materials within the material segment command premium positioning as airframers pursue gram-level weight reduction targets on next-generation single-aisle programs.
FAA airworthiness directives and EASA certification specifications govern damper fatigue life and fire resistance requirements, compelling manufacturers to maintain dual regulatory compliance capabilities. The EU Green Deal emissions benchmarks and REACH chemical restrictions are reshaping material selection protocols for seals and hydraulic fluids. Stakeholders must monitor evolving MRO network consolidation patterns and airframer vertical integration strategies to anticipate contract migration risks and captive supply decisions.
Market Dynamics
Fly-by-wire architectures are compressing damper replacement cycles as electromechanical actuators displace hydraulic systems across next-generation narrow-body programs. This technology substitution is redrawing supplier qualifications and forcing incumbent hydraulic specialists to diversify their actuator portfolios or cede platform positions.
Growth Catalysts
- FAA Airworthiness Directives:Emergency exit reliability mandates are tightening fatigue-life testing protocols, compelling fleet operators to accelerate damper retrofit schedules on aging narrow-body aircraft.
- Composite Material Adoption:Gram-level weight reduction targets on single-aisle programs are expanding procurement of carbon-fiber-reinforced damper housings from tier-two subsystem integrators.
- China:COMAC C919 production ramp-up is generating localized damper demand through Chengdu and Shanghai final assembly clusters.
Market Restraints
- Specialized Elastomer Supply:Fluorocarbon seal production concentrates among three Japanese compounders, exposing damper assemblers to input cost volatility and allocation risk.
- REACH Chemical Restrictions:EU hydraulic fluid formulation rules are forcing reformulation investments that compress margins on legacy product lines.
- Technical Limitation:Electromechanical dampers face torque-density constraints in wide-body cargo door applications exceeding 2.5-meter aperture widths.
Strategic Opportunities
- India:MRO network expansion at Bengaluru and Hyderabad maintenance clusters is creating aftermarket damper overhaul demand from low-cost carrier fleets.
- Regulatory Tailwind:EU Green Deal emissions benchmarks are incentivizing lightweight damper designs that contribute to airframe efficiency certifications.
- Technology Convergence:Integration of sensor-embedded dampers with predictive maintenance platforms is opening data-service revenue streams for subsystem suppliers.
Industry Challenges
- Certification Timeline Compression:Dual FAA-EASA qualification requirements for new damper designs extend development cycles to 18-24 months, delaying platform entry.
- Electromechanical-Hydraulic Integration:Mixed-fleet operators face inventory complexity managing spare damper pools across incompatible actuator technologies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Door Dampers Market |
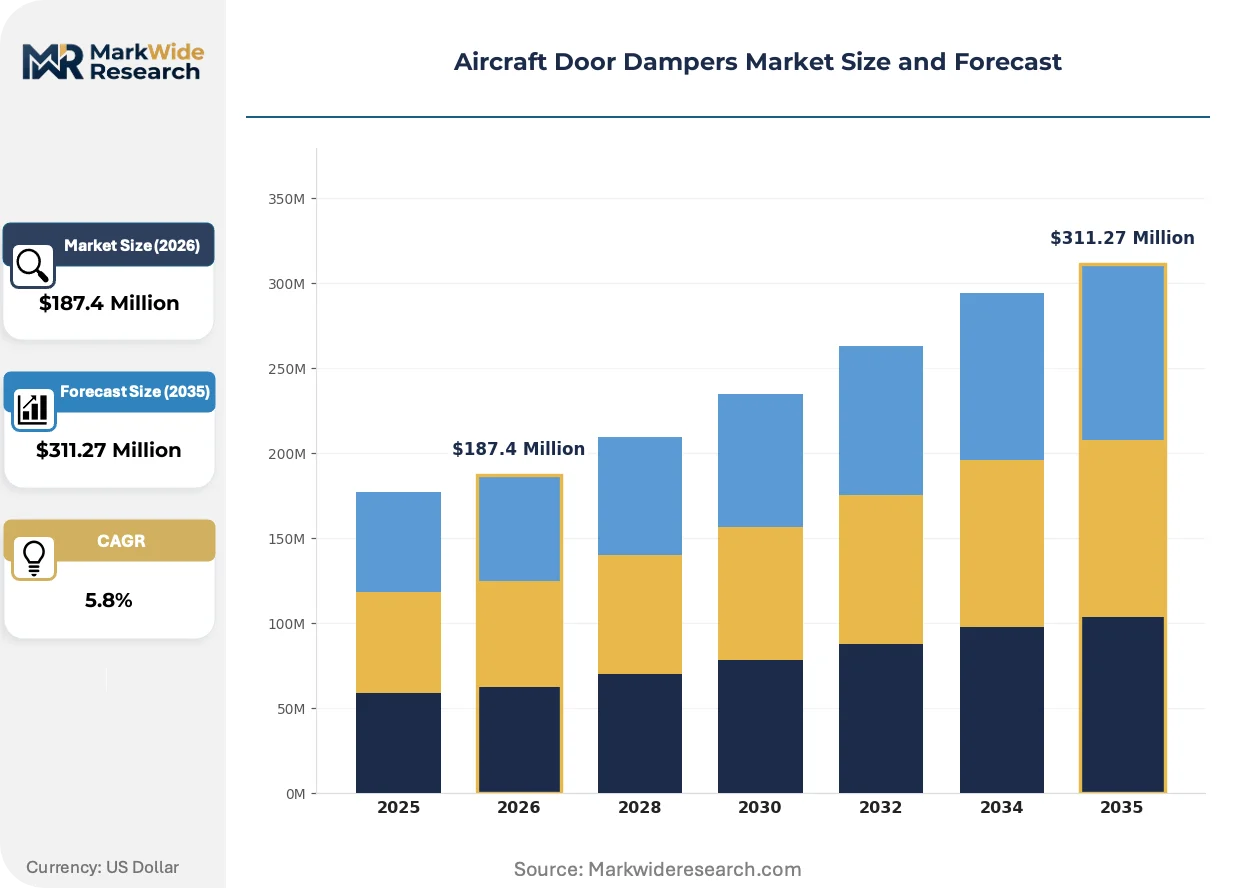
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Dampers, Pneumatic Dampers, Electromechanical Dampers, Passive Dampers Material: Aluminum Alloys, Composite Materials, Steel Alloys, Rubber End User: Commercial Aviation, Military Aviation, Private Aviation, Helicopter Operators Application: Passenger Doors, Cargo Doors, Emergency Exits, Service Hatches |
| Companies Covered | Moog Inc., Hutchinson Aerospace, Collins Aerospace, Trelleborg Sealing Solutions, Sitec Aerospace GmbH, Safran, LORD Corporation, General Aerospace, ITT Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Door Dampers Market Emerging Trajectories
Three intersecting developments are reshaping aircraft door damper engineering: electromechanical actuator maturation, regulatory material restrictions, and fleet-operator procurement consolidation. These forces are compressing product lifecycles and elevating subsystem integration requirements.
Electromechanical damper architectures are unifying position sensing and force modulation within single actuator housings. Narrow-body airframers are specifying these integrated units for passenger entry doors on new programs. This unification is collapsing the traditional separation between motion control and condition monitoring suppliers.
REACH chemical restrictions are prohibiting perfluorinated hydraulic fluid formulations across European-registered aircraft. EASA certification specifications now require alternative fire-resistant fluids that meet revised toxicity thresholds. Hydraulic damper specialists serving Airbus final assembly lines in Germany and France are reformulating seal compounds to maintain compliance.
Low-cost carriers are consolidating aftermarket procurement through single-source subsystem contracts that bundle dampers with door structures. This channel compression is displacing independent component distributors from MRO supply chains. The shift is most visible in Southeast Asia where AirAsia and Lion Air Group maintenance operations have adopted integrated sourcing frameworks.
Aircraft Door Dampers Market Segmentation
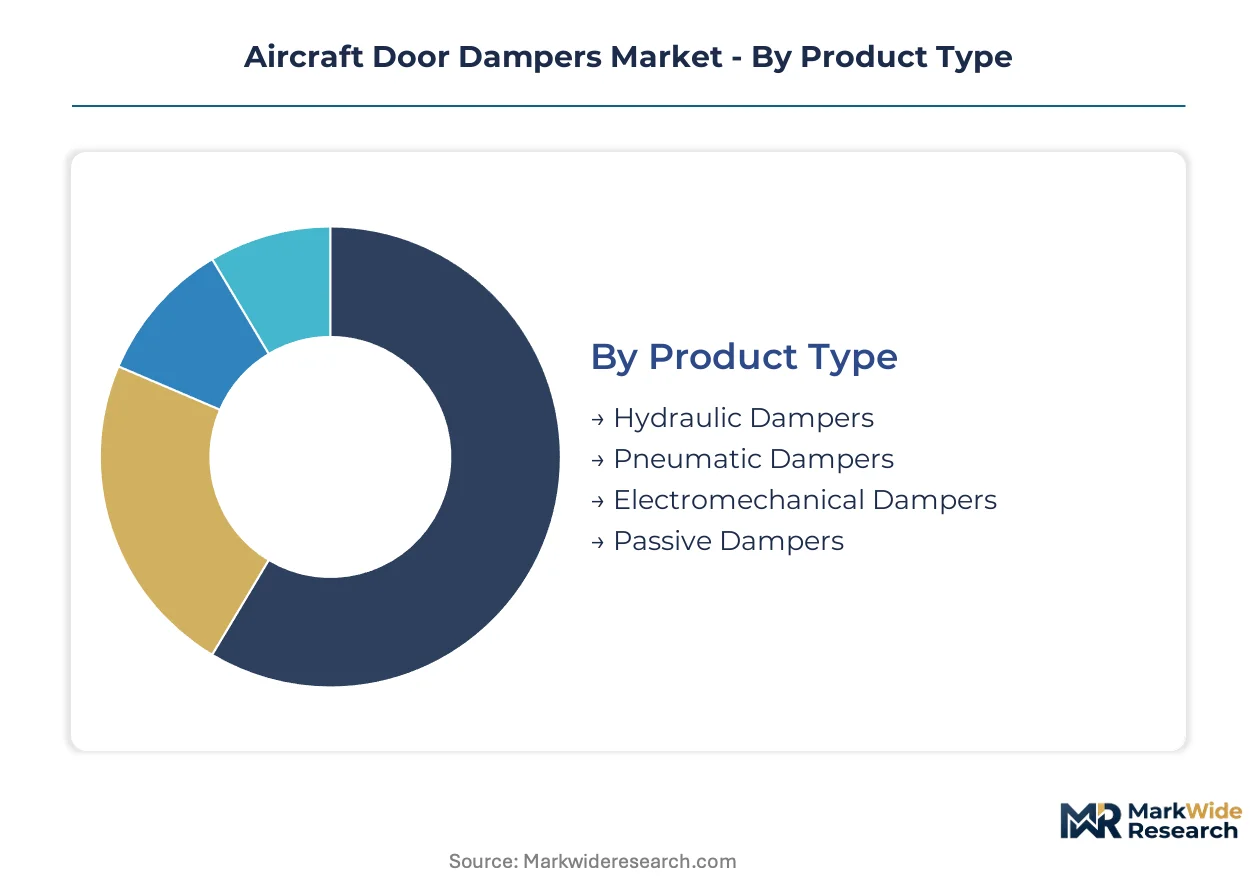
Damper segmentation reveals divergent capital requirements across actuator technologies and material classes. Procurement patterns concentrate where airframer platform decisions lock in supplier relationships for multi-decade production runs.
Product Type:
Hydraulic and electromechanical variants demand the heaviest upfront engineering investment due to precision manufacturing tolerances and dual-certification testing protocols.
- Hydraulic Dampers:Fluid-based force modulation systems utilizing piston-cylinder architectures with specialized seal compounds. Fleet operators in the United States and Germany specify these for wide-body cargo doors where torque density requirements exceed electromechanical limits. FAA fatigue-life directives are accelerating retrofit procurement on aging narrow-body fleets.
- Electromechanical Dampers:Integrated actuator-sensor units delivering position feedback through fly-by-wire interfaces. Airbus A320neo and Boeing 737 MAX programs in France and Washington state are specifying these for passenger entry doors. EASA certification specifications for emergency exit reliability are tightening acceptance protocols.
- Pneumatic Dampers:Compressed-gas systems for lightweight applications.
- Passive Dampers:Spring-damper combinations without active control.
Hydraulic dampers absorb the bulk of installed capacity; electromechanical dampers are expanding most quickly.
Material:
Composite material adoption tracks gram-level weight reduction mandates on next-generation single-aisle programs.
- Composite Materials:Carbon-fiber-reinforced housings and structural elements achieving 30-40% mass reduction versus metallic alternatives. COMAC C919 production in Shanghai and Chengdu is driving localized procurement from tier-two subsystem integrators. EU Green Deal emissions benchmarks are incentivizing lightweight designs that contribute to airframe efficiency certifications.
- Aluminum Alloys:Conventional machined housings for cost-sensitive applications.
- Steel Alloys:High-strength variants for heavy cargo door mechanisms.
- Rubber:Elastomer compounds for seal and vibration isolation components.
Aluminum alloys retain the largest installed base; composite materials are gaining share fastest.
End User:
Commercial aviation commands procurement volume through narrow-body production rates and retrofit cycles.
- Commercial Aviation:Scheduled carriers and low-cost operators maintaining narrow-body and wide-body fleets. AirAsia and Lion Air Group maintenance clusters in Southeast Asia are consolidating aftermarket procurement through integrated subsystem contracts. MRO network expansion at Bengaluru and Hyderabad is creating overhaul demand from Indian low-cost carrier fleets.
- Military Aviation:Defense procurement with specialized tactical requirements.
- Private Aviation:Business jet and general aviation operators.
- Helicopter Operators:Rotary-wing applications with distinct kinematic profiles.
Commercial aviation dominates procurement volume; helicopter operators present specialized engineering requirements.
Application:
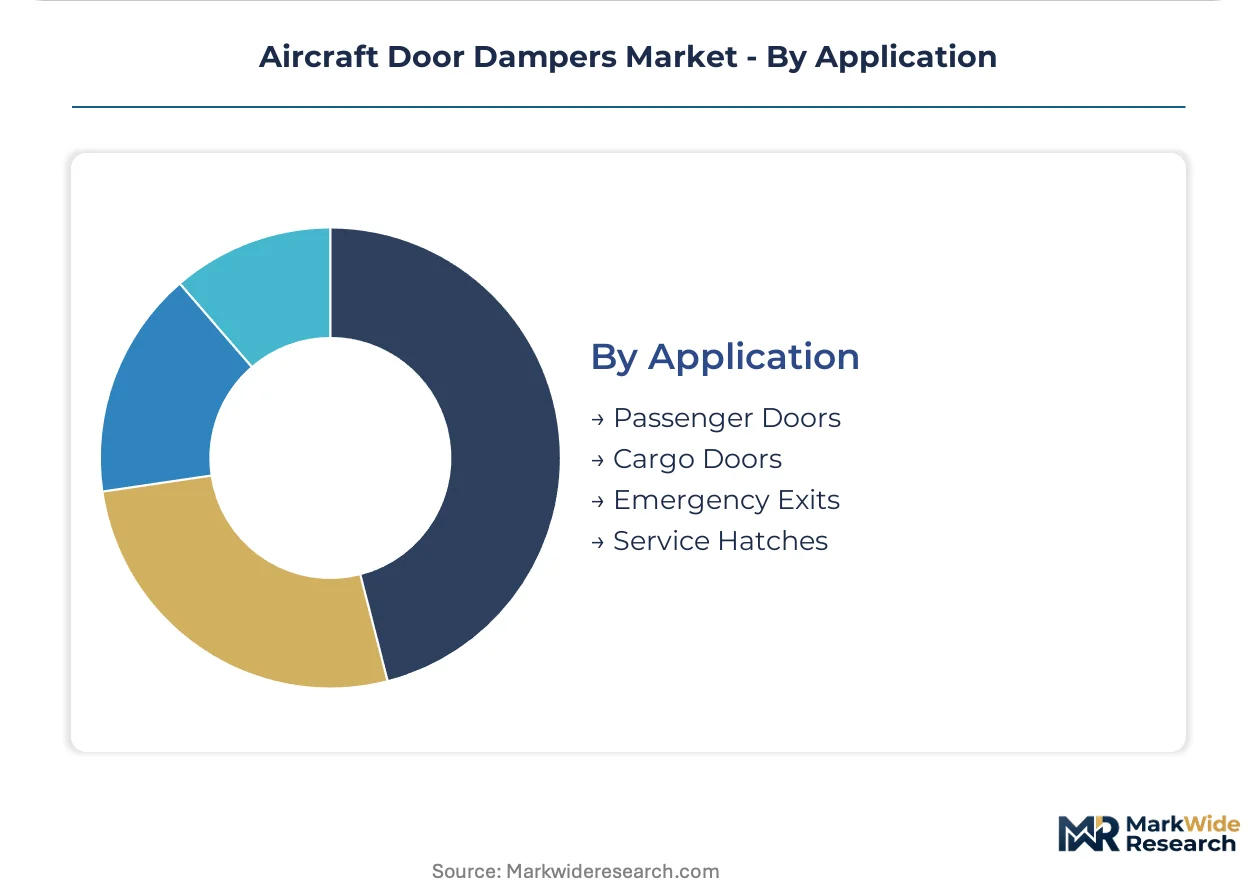
Passenger and cargo door specifications diverge on torque density and cycle frequency requirements.
- Cargo Doors:Large-aperture mechanisms exceeding 2.5-meter widths on wide-body freighter conversions. Boeing 777F and Airbus A350F programs in Washington state and Toulouse are specifying hydraulic architectures for heavy-lift applications. Technical limitations constrain electromechanical alternatives at these aperture scales.
- Passenger Doors:High-cycle entry systems on narrow-body programs.
- Emergency Exits:Rapid-deployment mechanisms with reliability mandates.
- Service Hatches:Maintenance access panels with reduced cycle requirements.
Cargo doors concentrate hydraulic damper deployment; passenger doors are driving electromechanical substitution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Final assembly line concentration in the United States, Germany, and China locks in damper procurement proximity to Boeing, Airbus, and COMAC production sites. Fleet operator retrofit cycles and regulatory compliance timelines vary sharply across these manufacturing clusters.
United States
Boeing 737 MAX and 777F production in Washington state sustains hydraulic damper demand for cargo door applications. FAA airworthiness directives on emergency exit reliability are accelerating narrow-body retrofit schedules across American carrier fleets. Wichita, Kansas hosts specialized MRO operations serving regional jet operators with damper overhaul capabilities.
Germany
Airbus A320neo and A350 final assembly in Hamburg and Toulouse procurement networks drives electromechanical damper specifications for passenger entry systems. EASA certification specifications for fire-resistant hydraulic fluids are compelling seal compound reformulation investments. Bavaria-based subsystem integrators are expanding carbon-fiber-reinforced housing production for weight reduction mandates.
China
COMAC C919 production ramp-up in Shanghai and Chengdu is generating localized damper demand through domestic supplier qualification programs. The country's national aviation regulator is aligning certification protocols with FAA and EASA standards to facilitate export clearance. Yangtze River Delta manufacturing clusters are attracting tier-two damper assemblers for single-aisle program integration.
France
Airbus headquarters procurement decisions in Toulouse anchor electromechanical actuator specifications across European narrow-body programs. EU Green Deal emissions benchmarks are incentivizing lightweight composite damper designs that contribute to airframe efficiency certifications. Occitanie region suppliers are consolidating elastomer-to-metal bonding expertise for vibration isolation applications.
India
Low-cost carrier fleet expansion at IndiGo and SpiceJet is driving aftermarket damper overhaul demand through Bengaluru and Hyderabad MRO clusters. The country's national aviation regulator is tightening maintenance facility certification standards to align with EASA protocols. Maharashtra-based maintenance operations are adopting integrated subsystem contracts that bundle dampers with door structures.
Aircraft Door Dampers Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue electromechanical specialization and composite material integration. The supplier base concentrates around integrated landing systems portfolios, precision motion control capabilities, and elastomer bonding expertise. Three archetypes dominate: diversified aerospace conglomerates with multi-platform contracts, electromechanical specialists with fly-by-wire integration capabilities, and niche seal compounders with fluorocarbon chemistry expertise. Competitive moves center on dual FAA-EASA qualification maintenance and sensor-embedded predictive maintenance platform development.
Among diversified aerospace conglomerates, Collins Aerospace and Safran exemplify integrated systems positioning across landing gear and door actuator portfolios. Moog Inc. occupies a position within the electromechanical specialist tier, anchoring precision motion control supply relationships with narrow-body airframers. Hutchinson Aerospace represents the elastomer-to-metal bonding archetype, with French corporate origins signaling European regulatory compliance depth. Sitec Aerospace GmbH sits within the German precision manufacturing cluster, reflecting Bavaria-based engineering concentration for vibration isolation applications.
| Leading Market Players |
|---|
| Moog Inc. |
| Hutchinson Aerospace |
| Collins Aerospace |
| Trelleborg Sealing Solutions |
| Sitec Aerospace GmbH |
| Safran |
| LORD Corporation |
| General Aerospace |
| ITT Inc. |
| Others |
Supply Flow & Price Mechanics
Fluorocarbon compound price volatility cascades through aircraft door damper manufacturing, compressing margins on hydraulic seal assemblies while elevating procurement premiums for electromechanical actuator specialists serving Airbus and Boeing programs.
Pricing Analysis
High-volume narrow-body retrofits trade on thin margins against certified new-build specifications commanding substantial premiums. Three-tier pricing structure across premium, standard, and economy levels separates FAA-EASA dual-certified units from single-jurisdiction alternatives and uncertified aftermarket substitutes. Cost compression in economy-tier hydraulic dampers is intensifying because REACH-driven fluid reformulation expenses cannot be fully passed to fleet operators. Low-cost carriers in Southeast Asia exhibit acute price sensitivity; defense procurement in the United States demonstrates inelastic demand for reliability-guaranteed configurations.
Supply Chain Analysis
China's domestic-content mandates for COMAC C919 integration are reshaping sourcing patterns, compelling tier-two assemblers to relocate carbon-fiber housing production to Yangtze River Delta clusters. Supply concentrates in the United States, Germany, and China for final assembly line proximity to Boeing, Airbus, and COMAC facilities. Raw material dependencies draw from Japanese fluorocarbon compounders, Bavarian precision machining centers, and French elastomer-to-metal bonding specialists. Single-source vulnerability in specialized seal chemistry exposes damper manufacturers to allocation risk during supply shocks. Distribution runs through airframer-qualified subsystem integrators rather than independent component distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where EASA certification specifications for emergency exit reliability erect substantial barrier-to-entry moats protecting dual-qualified incumbents from unqualified challengers.
For Market Incumbents: Lock in long-term narrow-body platform positions through backward integration into carbon-fiber housing production in Bavaria and Toulouse manufacturing clusters. Electromechanical substitution threats from Moog Inc. precision motion control capabilities demand accelerated sensor-embedded damper development to capture predictive maintenance data-service revenue streams before platform decisions freeze supplier selection.
For New Entrants and Emerging Players: Enter via aftermarket overhaul specialization targeting Bengaluru and Hyderabad MRO clusters serving IndiGo and SpiceJet low-cost carrier fleets. White-space availability concentrates in composite material integration for COMAC C919 domestic supplier qualification programs, where localized content rules disadvantage established Western incumbents. Go-to-market execution should anchor on tier-two subsystem integrator partnerships rather than direct airframer solicitation.
For Investors and Strategic Acquirers: Distressed-cycle entries favor electromechanical specialists with fly-by-wire integration capabilities in United States and French aerospace corridors, where platform standardization around integrated actuator-sensor units creates durable revenue visibility. Long-term viability over the coming decade hinges on sensor-embedded product roadmaps aligned with predictive maintenance platform proliferation. Monitor COMAC C919 production certification milestones as inflection indicator for localized supply chain reconfiguration timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual FAA-EASA Certification Investment | Qualification maintenance secures Boeing and Airbus platform access against regulatory tightening. |
| Composite Housing Production Scale-Up | Carbon-fiber integration addresses EU Green Deal weight reduction mandates for single-aisle programs. |
| Sensor-Embedded Damper Development | Predictive maintenance data services open recurring revenue streams beyond hardware sales cycles. |
| Localized Supplier Qualification | COMAC C919 domestic content compliance unlocks China production ramp-up participation. |
| Seal Compound Reformulation Partnership | REACH-compliant hydraulic fluid compatibility preserves European aftermarket access. |
Methodological Framework
Multi-period observation of narrow-body production rates, MRO network expansion patterns, and regulatory directive issuance anchored the trend analysis, supplemented by interviews with subsystem procurement directors at tier-one airframers, damper engineering leads at tier-two integrators, fleet maintenance managers at low-cost carriers, and elastomer compound specialists at Japanese material suppliers. Secondary validation drew from FAA airworthiness directive databases, EASA certification specification updates, COMAC production disclosure filings, and EU Green Deal implementation guidance documents. Bottom-up damper unit demand estimates triangulated against top-down aerospace component spending projections.
Input-output matrix framing structured the analytical approach, mapping actuator technology substitution elasticities, material cost pass-through coefficients, and regulatory compliance timeline constraints across the projection horizon. Segmentation dimensions modeled encompassed product type, material class, end-user category, application function, and geographic production cluster. CAGRs were derived from production rate forecasts, fleet age distribution analysis, and retrofit cycle timing patterns. Industry-specific inputs included fly-by-wire architecture penetration assumptions and REACH chemical restriction phase-in schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under COMAC export certification delays or fluorocarbon supply allocation crises. Forecasts reflect documented assumptions regarding airframer platform decisions, regulatory harmonization progress, and material substitution economics. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Safety Systems
Military Airborne Collision Avoidance Systems (ACAS) Market
Aircraft Safety Systems
Aircraft Lightning Protection Market
Aircraft Safety Systems
Cloud-Connected Aircraft Safety Data Management Platforms Market
Aircraft Safety Systems
Commercial Aircraft Collision Avoidance System Market
Aircraft Safety Systems
Helicopter Ice Protection Systems Market
Aircraft Safety Systems
Military Aircraft Collision Avoidance Systems Market
Aircraft Safety Systems
Aircraft Smoke Detection and Fire Extinguishing System Market
Aircraft Safety Systems
Commercial Aircraft Evacuation System Market
Aircraft Safety Systems
Aviation Airbags Market
Aircraft Safety Systems
Identification Friend or Foe Systems Market
Aircraft Safety Systems
Aircraft Fire Protection Systems Market
Aircraft Safety Systems
Instrument Landing System (ILS) Market
Aircraft Safety Systems
Aircraft Ejection Seats Market
Aircraft Safety Systems
Aircraft Survival Equipment Market
Aircraft Safety Systems
Airborne Lightning Detection System Market
Aircraft Safety Systems
Aircraft Braking System Market