
 Aircraft Arresting System Market | 2026-2036
Aircraft Arresting System Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Arresting System Market Analysis
Polymer-composite arresting materials are expanding their share of new installations as alternatives to traditional steel cable systems. General Atomics leverages its electromagnetic launch expertise to advance electromechanical arresting technologies for next-generation platforms. Safran SA anchors European supply through its specialized aerospace actuation and braking divisions. QinetiQ Group PLC dominates British military airfield engineering with decades of sovereign capability in barrier system design.
An aircraft arresting system is an engineered ground-based installation designed to safely decelerate an aircraft that overshoots, undershoots, or experiences an aborted takeoff, typically employing energy-absorbing materials, mechanical braking mechanisms, or electromagnetic force to dissipate kinetic energy within defined runway overrun zones. Mechanical arresting systems using woven steel tapes or hook cables remain the most widely deployed configuration across military airfields, while electromechanical variants incorporating regenerative braking and programmable deceleration profiles represent the fastest-growing technology segment. Military aviation applications command the largest installed base due to fighter jet tailhook requirements and NATO standardization protocols, whereas commercial aviation adoption concentrates on engineered materials arresting systems at high-risk runway ends where full structural barriers prove impractical.
The Federal Aviation Administration mandates arresting system performance under Advisory Circular 150/5220-22B, while the European Union Aviation Safety Agency enforces comparable certification standards through CS-ADR-DSN provisions for certified aerodromes. Military procurement channels operate under distinct national defense acquisition regulations, with the U.S. Department of Defense specifying MIL-STD-2560 requirements and individual NATO members aligning through STANAG 3316 interoperability standards. Stakeholders must monitor evolving electromagnetic aircraft launch and recovery system specifications as the U.S. Navy transitions carrier-based arresting technology toward shore-compatible configurations.
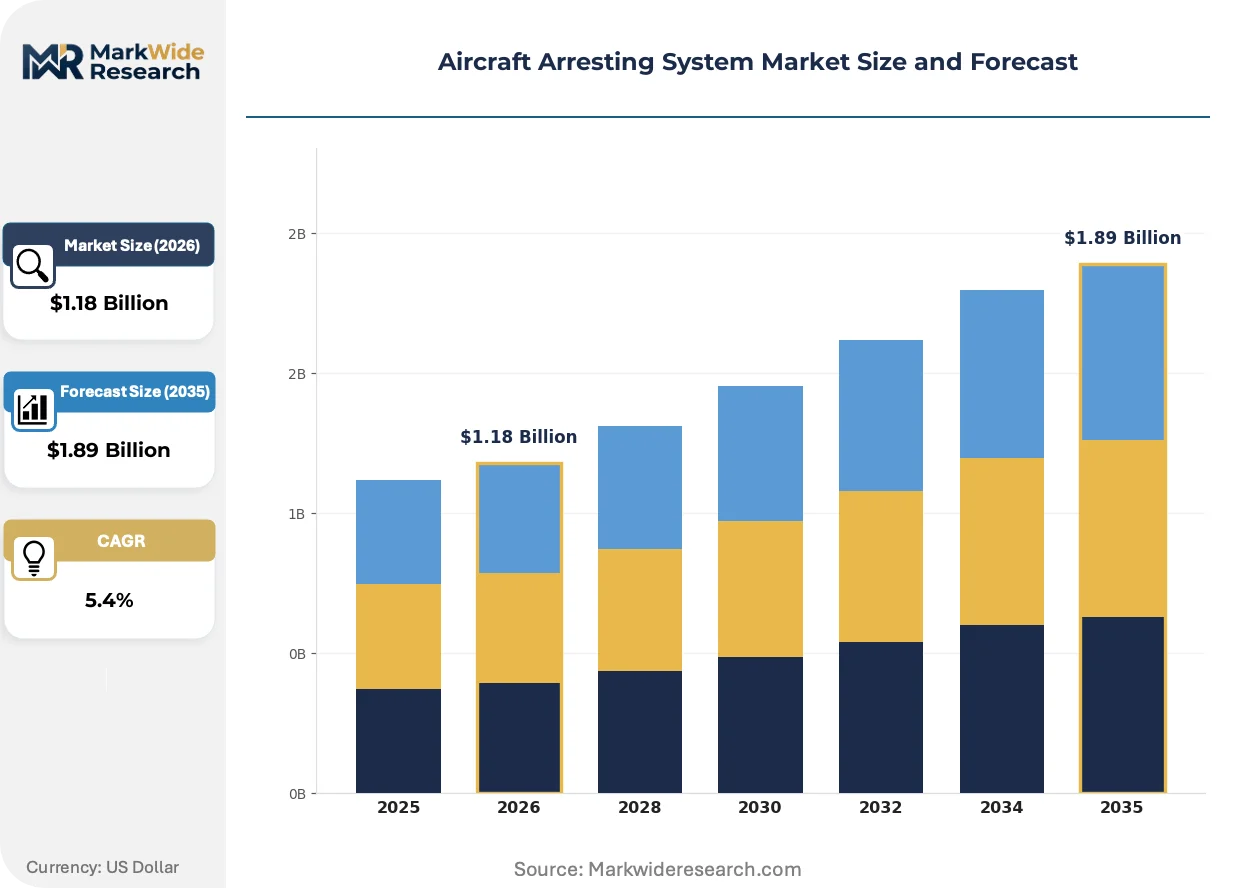
Market Dynamics
NATO airfield modernization programs and electromagnetic arresting technology maturation are compressing procurement cycles while elevating performance benchmarks for kinetic energy dissipation systems.
Growth Catalysts
- FAA Advisory Circular 150/5220-22B:Certification mandates for engineered materials arresting systems at commercial runway ends are expanding addressable infrastructure.
- Electromechanical regenerative braking:Programmable deceleration profiles are attracting military procurement channels seeking tailhook-compatible shore installations.
- Polymer-composite materials:Lightweight energy-absorbing alternatives are penetrating high-risk overrun zones where steel cable deployment proves structurally impractical.
Market Restraints
- Specialized steel alloy supply:Woven tape and hook cable fabrication depends on concentrated metallurgical suppliers facing capacity constraints.
- MIL-STD-2560 compliance timelines:Extended validation protocols for military-grade systems delay revenue recognition across defense procurement channels.
- Runway modification capex:Subsurface foundation reinforcement for arresting bed installation requires substantial civil engineering expenditure at existing airfields.
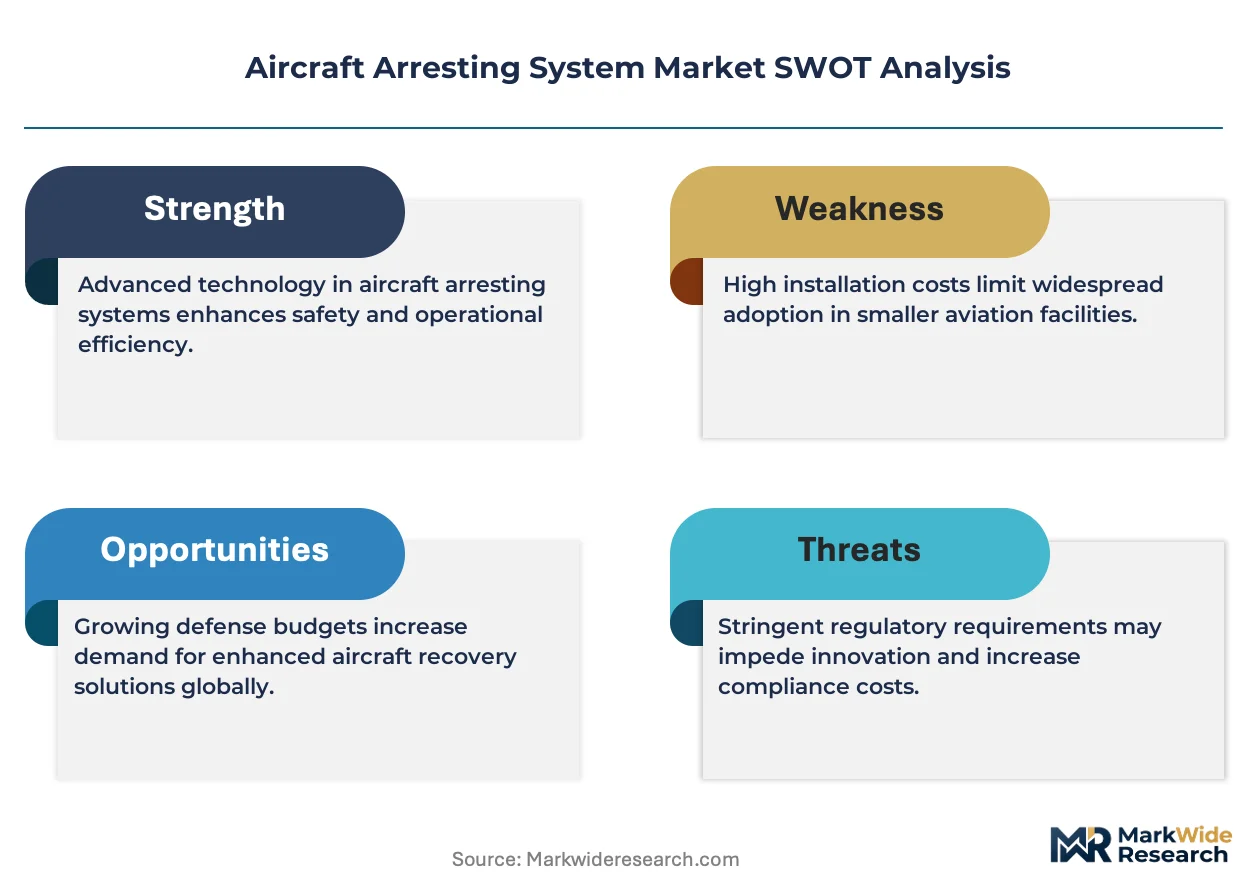
Strategic Opportunities
- Carrier-compatible shore systems:U.S. Navy electromagnetic aircraft launch and recovery specifications are opening dual-use military-civilian technology transfer pathways.
- Urban air mobility vertiports:Electric vertical takeoff and landing infrastructure creates demand for compact arresting solutions in constrained urban environments.
- EASA CS-ADR-DSN alignment:European certified aerodrome design standards are harmonizing with NATO STANAG 3316 interoperability protocols.
Industry Challenges
- Electromagnetic interference certification:Shore-based electromechanical systems must demonstrate compatibility with precision approach radar and instrument landing systems.
- Legacy mechanical integration:Hybrid installations combining woven steel tapes with composite materials require specialized engineering expertise scarce in regional contractors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Arresting System Market |
| Market Size in 2026 | $1.18 Billion |
| Market Size in 2035 | $1.89 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Mechanical, Hydraulic, Electromechanical, Magnetic Application: Military Aviation, Commercial Aviation, Cargo Operations, Emergency Landing End User: Airports, Military Bases, Private Operators, Government Agencies Installation Type: Permanent, Semi-Permanent, Mobile, Temporary |
| Companies Covered | SCAMA AB, QinetiQ Group PLC, General Atomics, Runway Safe Group, Curtiss-Wright Corp, Safran SA, ATECH Inc, WireCo WorldGroup, MacTaggart Scott and Company Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Arresting System Market Emerging Trajectories
Arresting system architecture is pivoting from passive mechanical absorption toward active electromechanical control, compressing deceleration distances while enabling real-time force modulation.
Polymer-composite arresting materials are overtaking traditional steel configurations in new commercial installations. These engineered materials crush predictably under aircraft load, dissipating kinetic energy through controlled deformation rather than friction-based braking. Regional airports with constrained overrun zones are adopting composite beds to avoid extensive earthwork, while major carriers specify them for high-risk runway ends where full structural barriers conflict with terrain.
REACH substance restrictions and EU Green Deal sustainability criteria are tightening material composition requirements for arresting system components deployed at EASA-certified aerodromes. Manufacturers must now document full lifecycle environmental impact for polymer formulations and steel treatments. European suppliers are reformulating composite matrices to eliminate restricted phthalates and heavy-metal stabilizers ahead of 2027 compliance deadlines.
Performance-based service agreements are displacing traditional capital procurement for arresting system maintenance. Military airfield operators in the United States are contracting integrated logistics support covering bed refurbishment, cable replacement, and electromagnetic system calibration under fixed-availability contracts. This shift transfers operational risk to OEM service networks while locking in multi-year revenue streams for specialized providers.
Aircraft Arresting System Market Segmentation
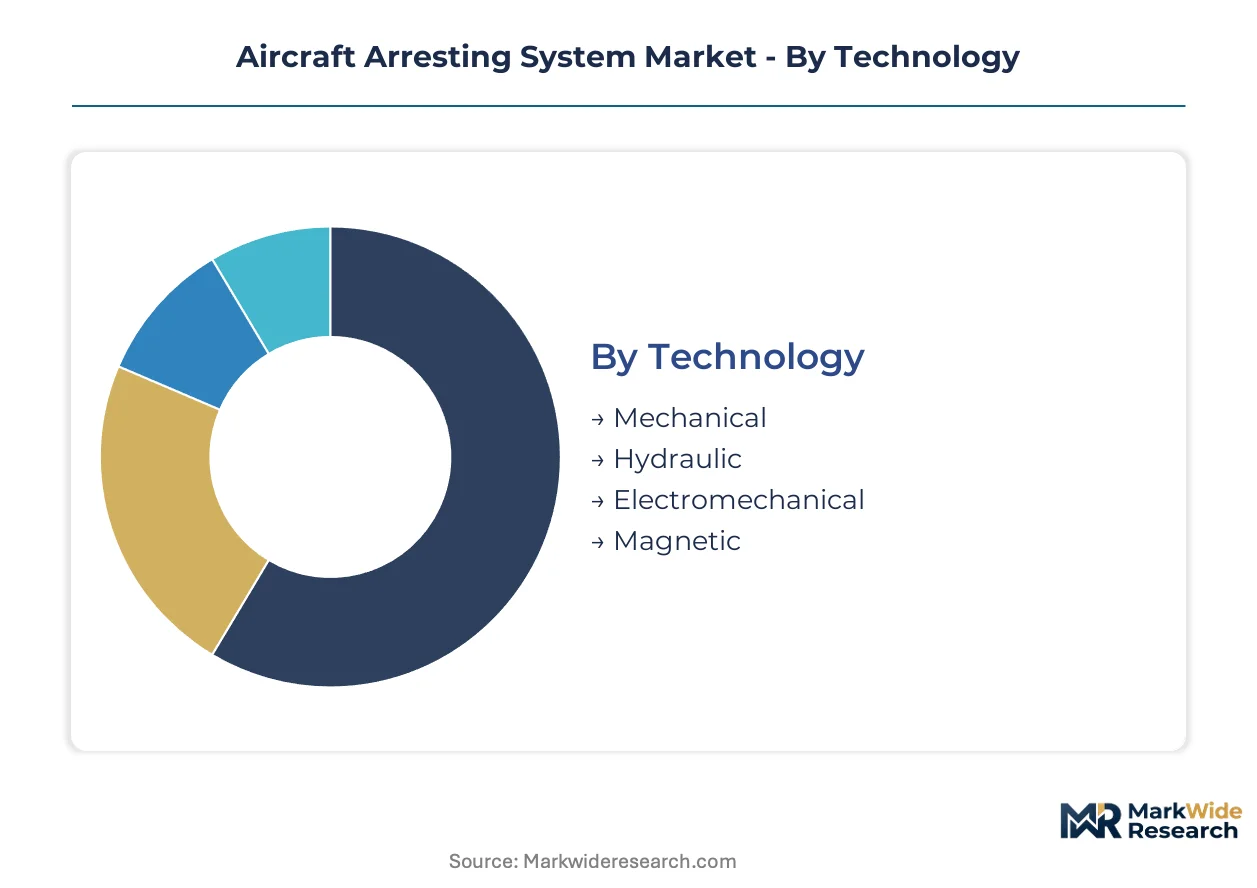
Arresting system procurement splits sharply between integrated airfield infrastructure and standalone deployable units. Technology choices cascade through installation requirements, end-user compliance obligations, and operational tempo demands.
Technology:
Mechanical systems function as embedded airfield infrastructure requiring civil works, while electromechanical and magnetic variants operate as modular installations with reduced foundation demands.
- Mechanical:Woven steel tapes and hook cables dissipate kinetic energy through friction-based braking. Demand concentrates at U.S. military bases maintaining NATO STANAG 3316 interoperability for fighter tailhook operations. Extended MIL-STD-2560 validation timelines constrain supplier capacity.
- Electromechanical:Regenerative braking with programmable deceleration profiles enables real-time force modulation. Shore-based U.S. Navy installations are absorbing General Atomics electromagnetic launch expertise transferred from carrier programs. FAA electromagnetic interference certification with precision approach radar remains pending for several configurations.
- Hydraulic:Fluid-pressure absorption systems deploy at commercial airports requiring predictable maintenance intervals.
- Magnetic:Eddy-current braking variants suit compact urban vertiport installations with severe space constraints.
Mechanical systems lead volumes today; electromechanical configurations are gaining share fastest.
Application:
Cost tier separation distinguishes mission-critical military procurement from risk-mitigation commercial installations.
- Military Aviation:Fighter jet tailhook requirements and NATO standardization protocols command premium procurement budgets. Installations span permanent airfield infrastructure at bases in Germany, the United Kingdom, and Poland under collective defense modernization programs.
- Commercial Aviation:Engineered materials arresting systems at high-risk runway ends serve as insurance against overrun liability. FAA Advisory Circular 150/5220-22B mandates drive U.S. airport capital planning, while EASA CS-ADR-DSN provisions govern European certified aerodromes.
- Cargo Operations:Heavy freighter weight classes demand reinforced subsurface foundations at hub airports.
- Emergency Landing:Standalone deployable units support expeditionary or contingency operations without permanent infrastructure.
Military aviation leads volumes today; commercial aviation is climbing the fastest.
End User:
Customer type determines procurement channel access, with defense acquisition regulations operating independently from civil aviation certification pathways.
- Airports:Civil aviation operators balance FAA and EASA compliance against capital constraint. U.S. commercial airports dominate addressable infrastructure spending for engineered materials systems.
- Military Bases:National defense acquisition regulations specify MIL-STD-2560 performance requirements. NATO members align through STANAG 3316 interoperability standards.
- Private Operators:Corporate flight departments and charter services specify mobile or semi-permanent installations.
- Government Agencies:Non-defense federal installations including emergency response and border patrol units procure temporary configurations.
Military bases lead volumes today; airports are expanding most quickly.
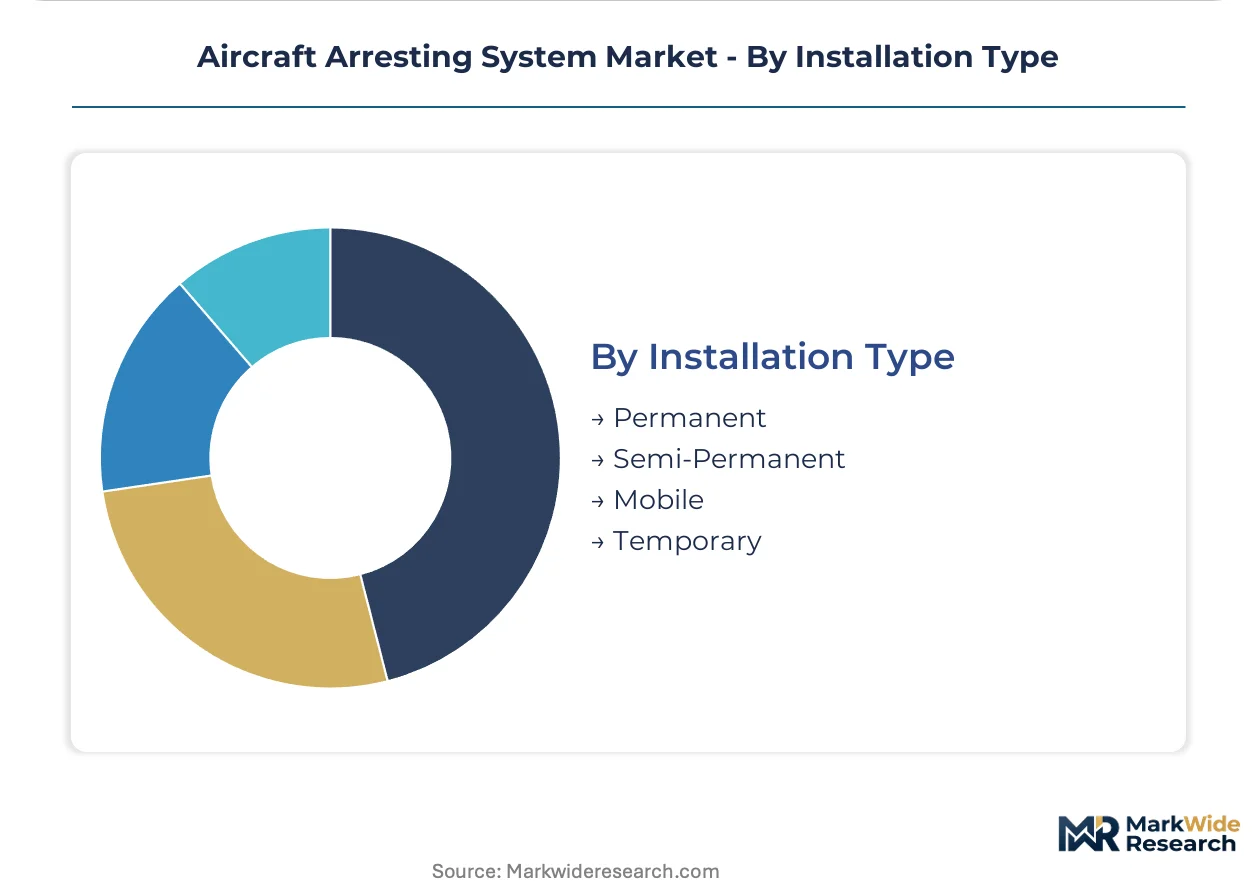
Installation Type:
Foundation permanence correlates directly with operational tempo and relocation flexibility requirements.
- Permanent:Reinforced concrete subsurface structures support continuous high-tempo operations. Civil engineering expenditure for foundation work often exceeds equipment acquisition cost at existing airfields.
- Semi-Permanent:Modular foundations enable relocation with reduced reconstruction overhead. European regional airports favor this tier for phased runway extension projects.
- Mobile:Trailer-mounted or containerized units deploy to contingency locations within hours. Military expeditionary requirements in Eastern Europe are absorbing inventory from specialized providers.
- Temporary:Rapid-installation barriers serve construction zones or emergency runway repairs.
Permanent installations lead volumes today; mobile systems are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States military airfield network concentrates the largest installed base of arresting systems worldwide, with Department of Defense procurement driving NATO interoperability standards across allied territories.
United States
FAA Advisory Circular 150/5220-22B mandates engineered materials arresting systems at commercial runway ends, expanding addressable infrastructure at regional airports. MIL-STD-2560 governs military-grade system validation, compressing supplier capacity through extended compliance timelines. Defense procurement channels concentrate in California and Virginia, where General Atomics advances electromechanical technologies transferred from carrier programs.
Germany
NATO airfield modernization programs absorb substantial arresting system inventory for fighter jet tailhook compatibility at Ramstein and Spangdahlem installations. EU Green Deal sustainability criteria tighten material composition requirements for polymer formulations under REACH substance restrictions. Industrial engineering clusters in Bavaria and North Rhine-Westphalia reformulate composite matrices to eliminate restricted phthalates ahead of 2027 deadlines.
United Kingdom
QinetiQ Group PLC anchors sovereign capability in barrier system design across British military airfields, leveraging decades of specialized engineering expertise. STANAG 3316 interoperability standards align procurement with collective defense modernization programs. Defense engineering concentrates in Hampshire and Wiltshire, where shore-based installations absorb electromagnetic technology maturation from naval aviation programs.
France
Safran SA specialized aerospace actuation and braking divisions supply arresting system components through European procurement channels serving NATO standardization protocols. EASA CS-ADR-DSN provisions govern certified aerodrome design standards for commercial installations at Charles de Gaulle and Orly. Aerospace manufacturing clusters in Toulouse and Paris-Saclay integrate arresting technologies with broader landing gear system portfolios.
Poland
Eastern flank collective defense requirements drive expeditionary mobile system procurement for contingency operations without permanent infrastructure. National defense acquisition regulations specify STANAG 3316 alignment for interoperability with allied fighter deployments. Military engineering activity concentrates in Poznan and Warsaw, where rapid-installation barriers support runway extension projects and emergency response capabilities.
Aircraft Arresting System Market Vendor Landscape
Global majors compete with regional champions across defense procurement channels and commercial aviation certification pathways. The vendor base separates into consolidated primes serving military-grade MIL-STD-2560 requirements and specialized fabricators addressing FAA-engineered materials specifications. Three strategic archetypes dominate: electromagnetic technology specialists transferring naval aviation expertise, polymer-composite material innovators, and sovereign defense engineering houses maintaining national security capabilities. Competitive moves concentrate on technology licensing agreements for shore-based carrier-compatible systems and strategic partnerships addressing urban air mobility vertiport requirements.
Among defense engineering specialists, QinetiQ Group PLC and Safran SA exemplify the sovereign capability archetype, anchoring national supply security for military airfield infrastructure. General Atomics occupies a distinctive position as an electromagnetic technology specialist, representing the carrier-to-shore technology transfer vector that is reshaping procurement specifications. These three entities collectively illustrate how vendor positioning depends on regulatory channel access—FAA commercial certification, MIL-STD-2560 defense validation, or dual-use electromagnetic interoperability—rather than scale alone.
| Leading Market Players |
|---|
| SCAMA AB |
| QinetiQ Group PLC |
| General Atomics |
| Runway Safe Group |
| Curtiss-Wright Corp |
| Safran SA |
| ATECH Inc |
| WireCo WorldGroup |
| MacTaggart Scott and Company Limited |
| Others |
Supply Flow & Price Mechanics
Electromechanical regenerative braking technology maturation is compressing cost differentials between mechanical and programmable arresting systems while concentrating procurement leverage among electromagnetic technology specialists with carrier-program heritage. This shift simultaneously elevates input-cost exposure for specialized steel alloy suppliers and creates tiered sourcing advantages for polymer-composite material innovators.
Pricing Analysis
Input-cost pass-through from specialized steel alloy supply constraints shapes pricing dynamics across mechanical arresting system tiers. Three-tier pricing structure across MIL-STD-2560 certified, STANAG 3316 compliant, and commercial FAA-grade levels reflects certification investment recovery and validation timeline differentials. Cost compression in commercial engineered materials systems is intensifying because polymer-composite alternatives eliminate foundation reinforcement expenditure. Regional airports with constrained capital budgets exhibit highest price sensitivity; U.S. Department of Defense procurement channels demonstrate lowest sensitivity due to mission-critical tailhook compatibility requirements.
Supply Chain Analysis
Domestic-content mandates in U.S. defense procurement regulations and EU Green Deal sustainability criteria are reshaping sourcing patterns for arresting system components. Supply concentration centers on the United States for electromagnetic technology, Germany and France for polymer-composite formulation expertise, and the United Kingdom for sovereign barrier system engineering. Woven steel tape fabrication draws from concentrated metallurgical suppliers; polymer matrix production rests on specialized chemical processing; electromagnetic actuation components hinge on naval aviation program heritage. Single-source vulnerability persists for carrier-compatible electromechanical control systems. Distribution runs through defense procurement channels for military-grade systems and civil aviation infrastructure contractors for commercial installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aircraft arresting system demand functions as a regulatory compounder, with FAA Advisory Circular 150/5220-22B certification mandates creating sustained infrastructure replacement cycles across U.S. commercial airfields.
For Market Incumbents: To counter polymer-composite material displacement of traditional steel configurations, deepen backward integration into specialized alloy supply and accelerate electromagnetic interference certification for precision approach radar compatibility. Anchor procurement channel control through fixed-availability service contracts transferring operational risk from military airfield operators. For New Entrants and Emerging Players: Begin with urban air mobility vertiport installations, where compact magnetic eddy-current braking systems address severe space constraints absent incumbent saturation. Target European regional airports pursuing phased runway extensions with semi-permanent modular foundations. Lead with sustainability-positioned composite formulations eliminating restricted phthalates ahead of REACH compliance deadlines. For Investors and Strategic Acquirers: Valuations sit cheapest among sovereign defense engineering houses with STANAG 3316 interoperability capabilities and carrier-to-shore technology transfer pipelines. Long-term viability over the projection horizon rests on electromagnetic system standardization across NATO allied territories. Watch for U.S. Navy shore-based installation procurement acceleration as the primary inflection indicator for electromechanical segment expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Carrier-Compatible Shore System Development | Dual-use military-civilian technology transfer opens NATO procurement channels beyond traditional defense primes. |
| Polymer-Composite Material Reformulation | Elimination of REACH-restricted phthalates secures EASA CS-ADR-DSN certification access ahead of compliance deadlines. |
| Performance-Based Service Contracting | Integrated logistics support agreements lock multi-year revenue streams while transferring operational risk to OEM networks. |
| Electromagnetic Interference Certification | FAA approval for precision approach radar compatibility removes final barrier to shore-based electromechanical deployment. |
| Urban Vertiport Partnership Formation | Electric vertical takeoff and landing infrastructure creates compact arresting demand in constrained metropolitan environments. |
Methodological Framework
Coverage spans the United States, Germany, the United Kingdom, France, and Poland, with primary inputs from each territory gathered through structured interviews with airfield engineering directors, defense procurement officers, polymer composite R&D leads, and civil aviation certification specialists. Secondary validation drew from FAA Advisory Circular documentation, EASA CS-ADR-DSN provisions, NATO STANAG 3316 standards, Department of Defense MIL-STD-2560 specifications, and customs trade data for specialized steel alloy shipments. Bottom-up installation tracking triangulates against top-down military and civil aviation budget allocations.
Granularity-level modeling distinguishes mechanical, electromechanical, hydraulic, and magnetic technology configurations across permanent, semi-permanent, mobile, and temporary installation types. Segmentation dimensions include military aviation, commercial aviation, cargo operations, and emergency landing applications, with end-user differentiation across airports, military bases, private operators, and government agencies. CAGRs derive from technology substitution curves for polymer-composite materials and procurement cycle compression for electromagnetic systems. Forecast inputs incorporate NATO airfield modernization program announcements and FAA mandate implementation timelines.
Several conditions sit outside the modeled scope, including classified military procurement specifications, carrier-based naval aviation system configurations not adapted for shore use, and speculative urban air mobility infrastructure buildout rates. Forecasts reflect documented assumptions regarding regulatory compliance deadlines and defense budget authorization continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Safety Systems
Cloud-Connected Aircraft Safety Data Management Platforms Market
Aircraft Safety Systems
Rescue Hoist System Market
Aircraft Safety Systems
Commercial Aircraft Collision Avoidance System Market
Aircraft Safety Systems
Commercial Aircraft Carbon Brakes Market
Aircraft Safety Systems
Aviation Life Rafts Market
Aircraft Safety Systems
South Korea Aircraft Windshield Wiper and Washer System Market
Aircraft Safety Systems
Aircraft Ice Protection System Market
Aircraft Safety Systems
Global Aircraft Brake System Market
Aircraft Safety Systems
Aerospace & Aircraft Collision Avoidance System Market
Aircraft Safety Systems
HUD Helmet Market
Aircraft Safety Systems
Helicopter Emergency Flotation System Market
Aircraft Safety Systems
Aircraft Door Dampers Market
Aircraft Safety Systems
Commercial Aircraft Evacuation System Market
Aircraft Safety Systems
Aircraft Evacuation Slide Market
Aircraft Safety Systems
Instrument Landing System (ILS) Market
Aircraft Safety Systems
Free Fall Sensor Market