
 Military Aircraft Collision Avoidance Systems Market | 2026-2036
Military Aircraft Collision Avoidance Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Military Aircraft Collision Avoidance Systems Market Foresight
DO-178C software certification is collapsing the supplier base for military avionics, forcing tier-two electronics houses to partner with established primes or exit the segment. Honeywell International Inc. leverages its integrated flight deck architecture to embed collision avoidance within broader mission systems. L3Harris Technologies, Inc. sustains competitive position through captive production of classified waveform processors. Thales Group anchors European supply chains with national qualification pathways through France's DGA.
Military aircraft collision avoidance systems comprise sensor fusion architectures that integrate radar, electro-optical, and GPS-derived position data to generate real-time threat resolution advisories for pilots or autonomous flight computers, typically operating with sub-second latency requirements and MIL-STD-810 environmental hardening. Airborne systems dominate current procurement as fixed-wing and rotary platforms retrofit stand-alone units ahead of integrated block upgrades. Lidar technology represents the fastest-expanding technology segment, driven by DARPA-funded programs targeting degraded visual environment operations where traditional radar returns prove unreliable. GPS technology segments face margin compression as commoditized commercial receivers receive military SAASM or M-code firmware overlays.
The FAA and DoD jointly govern military-civil airspace interoperability through ADS-B Out mandates and TCAS II hybrid equipage rules, while NATO's STANAG 4671 underpins unmanned system certification across allied procurement pools. EASA's military exemption framework creates divergent compliance pathways for European primes serving domestic versus export customers. Procurement officers must weigh sovereign qualification requirements against interoperability commitments when specifying system architectures.
Market Dynamics
Autonomous sense-and-avoid integration for unmanned combat aircraft is compressing development cycles and forcing primes to rearchitect legacy sensor suites around software-defined fusion engines. The Pentagon's acceleration of UCAV programs is pulling forward qualification timelines that traditionally spanned a decade.
Growth Catalysts
- FAA ADS-B Out mandates:Military-civil interoperability rules are mandating hybrid TCAS II equipage across all airspace classes, forcing fleet-wide retrofits of collision avoidance hardware.
- Degraded visual environment operations:Rotary-wing platforms operating in brownout and whiteout conditions require multi-spectral fusion architectures that embed collision avoidance within mission computers.
- NATO STANAG 4671:Unmanned system certification standards across allied procurement pools are harmonizing technical specifications, expanding addressable market for qualified suppliers.
Market Restraints
- Gallium arsenide substrate costs:RF component fabrication for phased-array radars faces input price volatility as semiconductor foundry capacity concentrates in East Asian supply chains.
- DO-178C certification bottlenecks:Software assurance requirements for Level A criticality systems are collapsing the qualified supplier base to a handful of primes with existing military airworthiness credentials.
- Synthetic vision systems:Enhanced vision technologies that fuse terrain databases with real-time sensor feeds are emerging as functional substitutes for standalone collision avoidance hardware in certain flight regimes.
Strategic Opportunities
- Australian UCAV development:The Loyal Wingman program and subsequent uncrewed fighter initiatives are creating demand for sovereign collision avoidance capabilities outside traditional NATO supply chains.
- AI-driven predictive avoidance:Machine learning trajectory prediction converging with edge-computing inference engines enables anticipatory maneuver planning rather than reactive resolution advisories.
- EASA military exemption pathways:Divergent compliance frameworks for domestic versus export customers create arbitrage opportunities for dual-qualified system architectures.
Industry Challenges
- Software assurance engineering talent:The specialized skill set required for DO-178C Level A artifact generation is scarce, elongating development timelines and inflating labor costs.
- MIL-STD-810H environmental qualification:Hardening requirements for temperature, shock, and electromagnetic interference impose capital-intensive test infrastructure demands on suppliers.
- Legacy analog radar integration:Fielded fighter and transport platforms with 1980s-era architectures require protocol translation layers that introduce latency and certification complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Military Aircraft Collision Avoidance Systems Market |
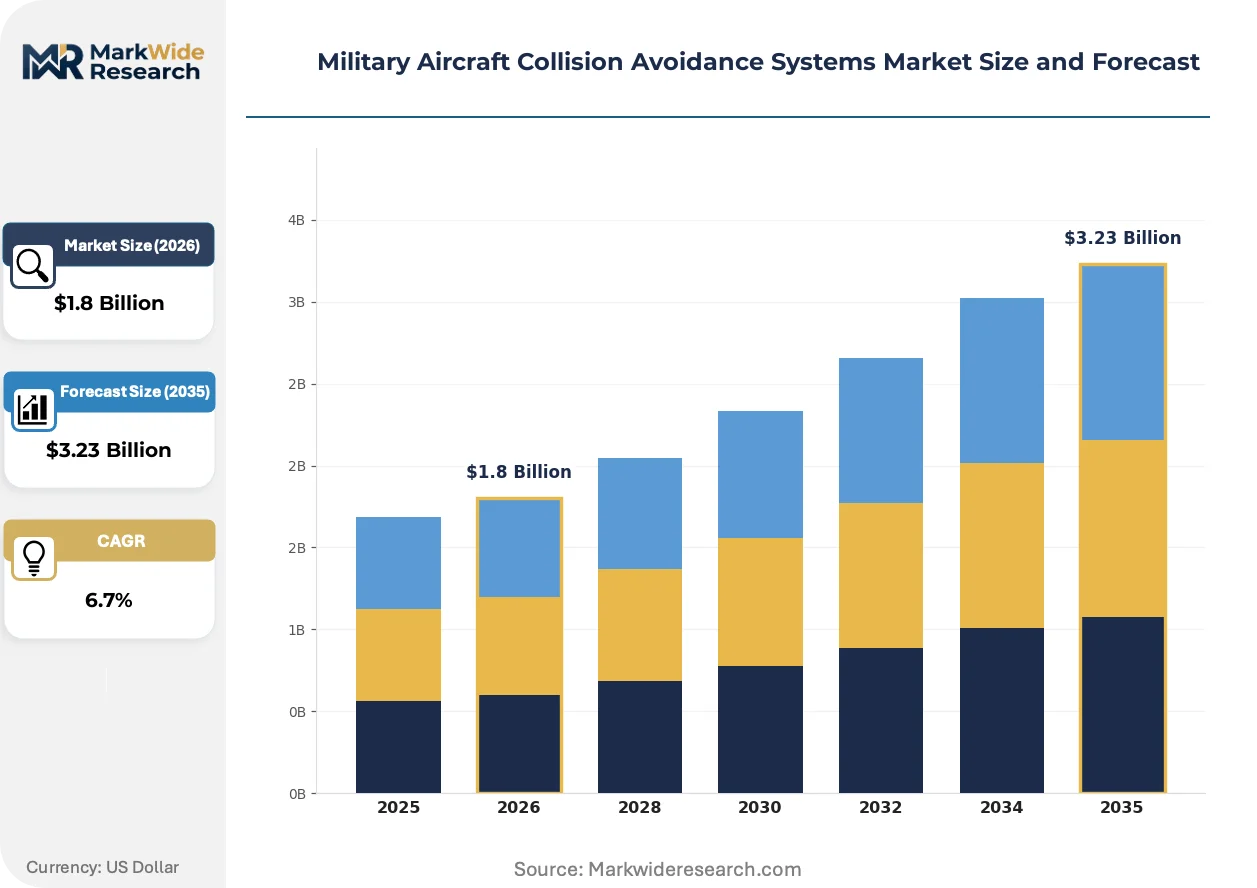
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Ground-Based Systems, Airborne Systems, Integrated Systems, Onboard Systems Technology: Radar Technology, Optical Technology, Lidar Technology, GPS Technology End User: Military Aviation, Defense Contractors, Government Agencies, Aerospace Manufacturers Application: Training Simulators, Airborne Operations, Maintenance Operations, Tactical Missions |
| Companies Covered | Honeywell International Inc., L3Harris Technologies, Inc., Raytheon Technologies Corporation, Leonardo SpA, Thales Group, Northrop Grumman Corporation, BAE Systems plc, Lockheed Martin Corporation, Garmin Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Military Aircraft Collision Avoidance Systems Market Shifts & Advancements
Sensor fusion architectures are evolving from federated multi-box systems toward single-module integrated assemblies that collapse size, weight, and power footprints. This consolidation is enabling installation on platforms previously excluded by volume constraints.
Lidar-based sense-and-avoid is supplanting millimeter-wave radar in rotary-wing applications where foliage penetration and dust clutter degrade traditional returns. Army aviation units operating in desert and jungle environments are specifying multi-beam solid-state lidar as primary sensors for nap-of-earth flight profiles. This displacement is compressing the addressable market for legacy radar suppliers while opening design wins for electro-optical specialists.
The FAA's updated military interoperability mandate is forcing concurrent certification of civil and military variants, eliminating the historical sequencing that allowed military-unique features to lag commercial baselines. This regulatory compression is accelerating technology refresh cycles but eliminating the margin cushion that subsidized military development. Fixed-wing transport and tanker platforms are absorbing the steepest compliance cost increases as their high civil airspace utilization exposes them to enforcement priority.
Defense procurement officers are unbundling collision avoidance from integrated flight deck contracts, creating discrete competitive events for stand-alone subsystems. This disaggregation is fragmenting award values but expanding the vendor pool beyond traditional prime integrators. The United States Air Force is most aggressive in this separation, driven by congressional pressure for vendor diversification and specific small-business set-aside targets.
Military Aircraft Collision Avoidance Systems Market Segmentation
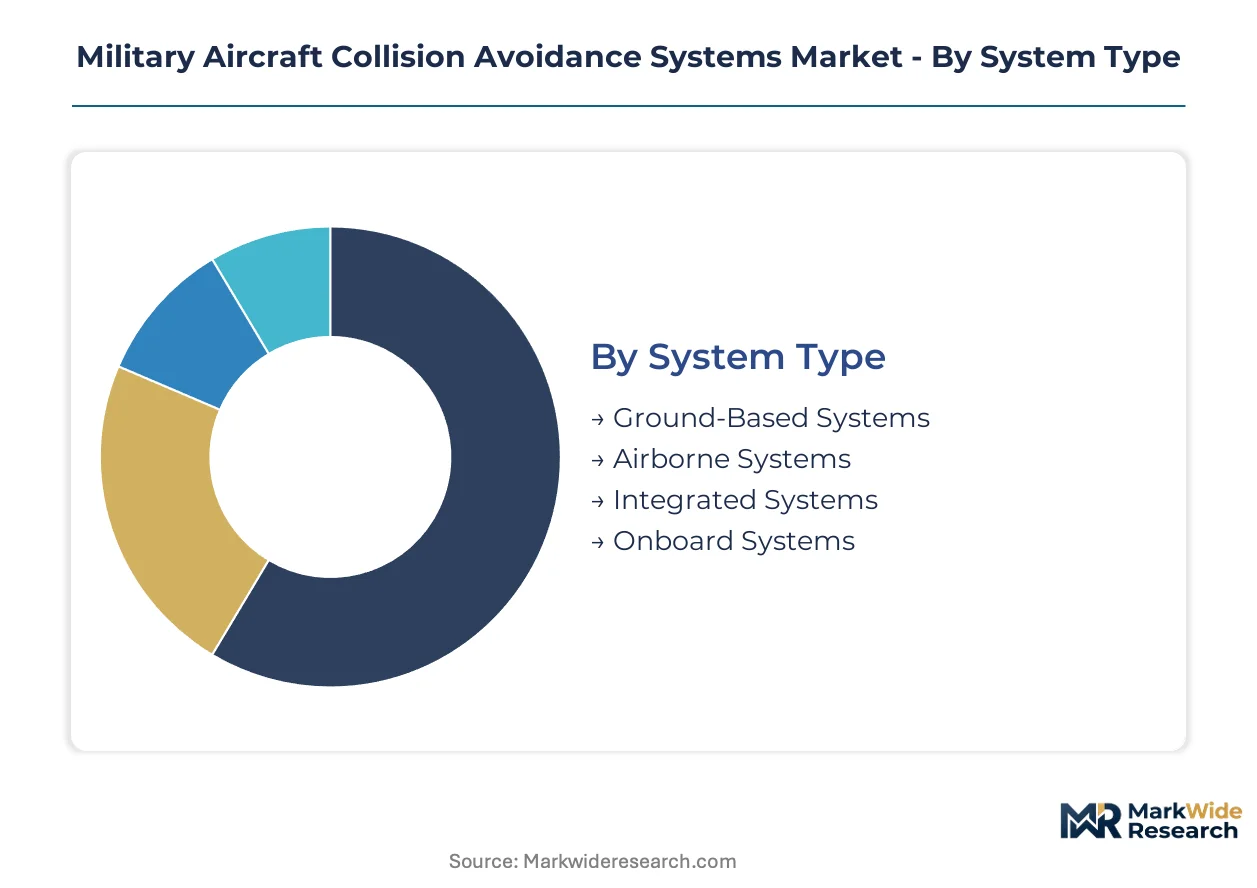
Segmentation in military aircraft collision avoidance systems reveals distinct procurement channels and technical requirements that shape supplier positioning. System architecture choices determine whether primes capture integrated contracts or specialized vendors penetrate subsystem tiers.
System Type:
Channel flow diverges sharply between installed-base retrofits and new-production line-fit, with ground-based training systems flowing through simulation houses while airborne platforms route through airframe OEMs.
- Airborne Systems:Stand-alone collision avoidance units installed on operational fixed-wing and rotary platforms dominate current procurement volumes. The United States Air Force and Army aviation branches are driving retrofit demand as fleets modernize ahead of FAA ADS-B interoperability deadlines.
- Integrated Systems:Embedded architectures fuse collision avoidance within mission computers and flight decks, requiring deep prime integrator relationships. NATO fighter modernization programs and UCAV development contracts concentrate demand in this segment, compressing supplier qualification timelines.
- Ground-Based Systems:Simulation and training infrastructure for pilot instruction flows through specialized defense simulation providers.
- Onboard Systems:Compact units for smaller unmanned platforms and legacy aircraft with severe SWaP constraints.
Airborne systems dominate installed base. Integrated systems are where expansion concentrates.
Technology:
Cost tiering separates military-hardened custom development from commercial-derivative overlays, with lidar and advanced optical commanding premium pricing against commoditized GPS receivers.
- Lidar Technology:Multi-beam solid-state sensors penetrate dust, foliage, and brownout conditions where radar fails. Army rotary-wing units operating nap-of-earth in desert and jungle environments specify lidar as primary sense-and-avoid sensor, displacing legacy millimeter-wave systems.
- Radar Technology:Phased-array and pulse-Doppler architectures remain standard for fixed-wing transport and tanker platforms with all-weather requirements. Gallium arsenide substrate costs and East Asian foundry concentration create input price volatility for RF component fabrication.
- Optical Technology:Electro-optical/infrared fusion supports passive threat detection and degraded visual environment operations.
- GPS Technology:SAASM and M-code military signal overlays on commercial receiver cores face margin compression as firmware upgrades substitute for hardware replacement.
Radar technology anchors legacy platforms. Lidar technology is climbing the fastest as rotary-wing requirements reshape procurement specifications.
End User:
Customer type determines contract structure, with military aviation direct procurement favoring long-term sustainment arrangements while defense contractors optimize for production lot economies.
- Military Aviation:Operational commands within the United States Department of Defense and allied air forces specify performance requirements and qualification pathways. Direct procurement of collision avoidance systems for fighter, transport, and rotary fleets concentrates demand in this segment.
- Defense Contractors:Prime integrators and tier-one suppliers purchase subsystems for incorporation into larger airframe or avionics contracts. Unbundling trends in United States Air Force procurement are expanding discrete competitive events for stand-alone collision avoidance hardware.
- Government Agencies:Research laboratories and test ranges acquire experimental systems for technology evaluation.
- Aerospace Manufacturers:Civil-military hybrid producers serving both markets face compressed certification cycles under FAA military interoperability mandates.
Military aviation commands procurement volume. Defense contractors are where supplier diversification pressure is reshaping competitive access.
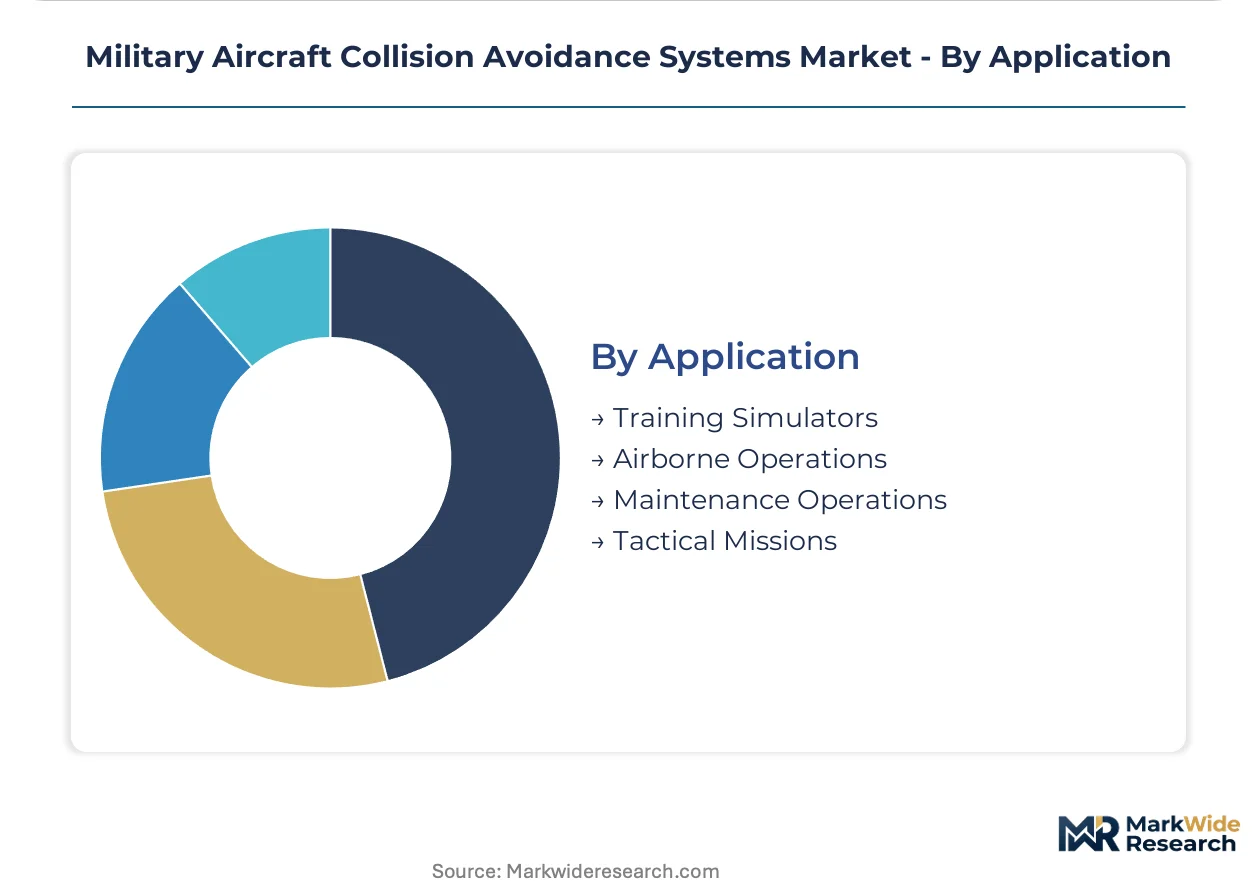
Application:
Maturity gradients separate field-proven operational systems from developmental training and tactical applications with evolving requirements.
- Airborne Operations:Real-time collision avoidance for manned and unmanned flight in civil-military shared airspace represents the core operational requirement. FAA ADS-B Out mandates and TCAS II hybrid equipage rules are forcing fleet-wide hardware retrofits across all airspace classes.
- Tactical Missions:Low-altitude penetration, formation flying, and contested environment operations demand specialized sense-and-avoid modes with reduced electromagnetic signature. DARPA-funded programs and autonomous UCAV development are accelerating technology refresh in this segment.
- Training Simulators:Synthetic environments replicate collision scenarios for pilot instruction without flight risk.
- Maintenance Operations:Ground handling and test flight safety systems protect personnel and equipment during non-operational phases.
Airborne operations anchor program of record spending. Tactical missions are gaining share fastest as autonomy requirements proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement officers in the United States, France, and United Kingdom concentrate the largest program budgets, while Australia and Japan expand sovereign capabilities outside traditional NATO supply chains.
United States
The Pentagon's UCAV acceleration and FAA ADS-B interoperability mandates drive fleet-wide retrofits. The FAA and DoD jointly govern military-civil airspace rules through updated TCAS II hybrid equipage requirements. Greater Boston and the Southwest defense corridor host prime integrators rearchitecting legacy sensor suites for autonomous platforms.
France
NATO fighter modernization and national DGA qualification pathways sustain demand for European-certified architectures. EASA's military exemption framework creates divergent compliance pathways for domestic versus export customers. The Île-de-France aerospace cluster anchors Thales Group's supply chain integration for allied procurement pools.
United Kingdom
RAF Tempest and uncrewed combat aircraft programs compress development cycles for next-generation collision avoidance. The UK Ministry of Defence harmonizes specifications with NATO STANAG 4671 standards. Aerospace engineering concentrates in the Midlands and Southwest England, where BAE Systems plc maintains sovereign integration capabilities.
Germany
Luftwaffe Eurofighter upgrades and FCAS program participation sustain demand for integrated mission systems. The KBA and national airworthiness authorities coordinate with EASA on military exemption certifications. Bavaria and Baden-Württemberg host subsystem suppliers serving both domestic and export contracts.
Australia
The Loyal Wingman program and subsequent uncrewed fighter initiatives create demand outside traditional NATO supply chains. The country's defense department prioritizes sovereign sense-and-avoid capabilities for autonomous platforms. Victoria and South Australia host emerging aerospace clusters developing localized qualification pathways.
Military Aircraft Collision Avoidance Systems Market Competitive Landscape
Player mix skews toward integrated prime contractors with existing military airworthiness credentials. The supplier base consolidates around three tiers: full-mission-system integrators, specialized sensor fusion houses, and commercial-derivative subsystem vendors. DO-178C certification bottlenecks collapse qualified competition to a handful of primes. Dominant competitive moves include strategic partnerships with tier-two electronics houses and portfolio diversification into unmanned platforms.
Within the integrated prime tier, Honeywell International Inc. and L3Harris Technologies, Inc. exemplify archetypes leveraging captive production and flight deck architecture control. Thales Group anchors European positioning through France's DGA national qualification pathways. Raytheon Technologies Corporation and Northrop Grumman Corporation occupy positions within the US defense industrial base, while BAE Systems plc and Leonardo SpA represent UK and Italian sovereign integration capabilities respectively. Lockheed Martin Corporation sits within the full-mission-system integrator archetype, and Garmin Ltd. exemplifies commercial-derivative subsystem vendors adapting military-hardened overlays.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| L3Harris Technologies, Inc. |
| Raytheon Technologies Corporation |
| Leonardo SpA |
| Thales Group |
| Northrop Grumman Corporation |
| BAE Systems plc |
| Lockheed Martin Corporation |
| Garmin Ltd. |
| Others |
Supply & Pricing Matrix
Eighteen-month qualification timelines for DO-178C Level A software artifacts concentrate pricing power with established primes possessing existing military airworthiness credentials, while compressing margins for tier-two electronics houses forced into partnership arrangements. Gallium arsenide substrate volatility and East Asian foundry concentration amplify cost uncertainty for RF component fabrication, feeding back into contract indexation clauses that shift input risk to defense procurement officers.
Pricing Analysis
Cost-plus contracts with Bureau of Labor Statistics employment cost indexation dominate military avionics procurement, insulating primes from software engineering talent inflation while exposing buyers to qualification timeline overruns. Price differentiation separates DO-178C Level A certified architectures from commercial-derivative overlays lacking military environmental hardening. Pricing pressure stems from unbundling trends as the United States Air Force separates collision avoidance from integrated flight deck contracts, fragmenting award values. Defense contractors exhibit highest price sensitivity due to congressional small-business set-aside targets, while operational military aviation commands prioritize performance over unit cost.
Supply Chain Analysis
Japan and South Korea anchor gallium arsenide wafer fabrication for phased-array radar substrates, while Taiwan concentrates advanced semiconductor foundry capacity for sensor fusion processors. Military-hardened supply chains draw from domestic qualification pathways in France, the United Kingdom, and the United States to satisfy sovereign content requirements. Single-source vulnerability concentrates in East Asian substrate processing, where geopolitical friction threatens input continuity. Distribution runs through prime integrator relationships with airframe OEMs and direct military procurement channels, with discrete competitive events expanding access for specialized subsystem vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where sustainment contracts and software upgrade subscriptions expand faster than hardware replacement cycles, driven by compressed FAA-DoD interoperability recertification timelines.
For Market Incumbents: Secure software assurance engineering talent pools through captive training pipelines or acquisition of qualified specialty houses, as DO-178C certification bottlenecks collapse qualified competition. Deepen backward integration into classified waveform processor production to match L3Harris Technologies' captive supply model and defend against emerging electro-optical specialists displacing legacy radar suppliers in rotary-wing applications. For New Entrants and Emerging Players: Differentiate on sovereign qualification pathways outside traditional NATO supply chains, targeting Australia's Loyal Wingman program and subsequent uncrewed fighter initiatives where localized certification requirements create competitive access. Penetrate the lidar technology segment fastest-expanding for degraded visual environment operations, leveraging multi-beam solid-state architectures to displace millimeter-wave radar in Army aviation nap-of-earth profiles. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because DO-178C certification barriers and MIL-STD-810H environmental qualification infrastructure requirements structurally prevent fragmented competition, concentrating returns with scale players possessing existing military airworthiness credentials. Target acquisition candidates among tier-two electronics houses with partial software assurance capabilities requiring prime partnership to complete. Watch for inflection in UCAV program acceleration rates as the Pentagon pulls forward qualification timelines traditionally spanning a decade.| Strategic Initiative | Industry Significance |
|---|---|
| DO-178C Certification Investment | Collapses qualified supplier base to primes with existing military airworthiness credentials. |
| Sensor Fusion Architecture Consolidation | Enables installation on platforms previously excluded by SWaP constraints. |
| Lidar Technology Pivot | Captures rotary-wing demand in brownout and whiteout conditions where radar fails. |
| Sovereign Qualification Pathway Development | Creates competitive access outside traditional NATO supply chains for Australian and Japanese programs. |
| Software-Defined Fusion Engine Rearchitecture | Compresses development cycles for autonomous sense-and-avoid integration in UCAV platforms. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with defense procurement officers, prime integrator program managers, tier-two electronics house engineering directors, military airworthiness qualification leads, and flight test range operators. Secondary validation drew from FAA ADS-B implementation directives, DoD budget justification materials, NATO STANAG 4671 certification documentation, EASA military exemption framework filings, and customs trade data for gallium arsenide substrate flows. Bottom-up build-ups of program-level procurement volumes triangulated against top-down defense budget allocation analysis.
Across the analysis window, forecasts model system type segmentation distinguishing airborne retrofits from integrated new-production architectures, technology tiering separating lidar and radar from commoditized GPS overlays, and end-user channels differentiating direct military procurement from defense contractor subsystem purchases. CAGRs derive from program-of-record acceleration rates, UCAV development timeline compression, and fleet-wide ADS-B interoperability retrofit schedules. Industry-specific inputs include DARPA funding disbursement patterns for degraded visual environment programs and congressional small-business set-aside enforcement trends.
Decision-makers should treat outputs as directional under assumptions of sustained Pentagon UCAV acceleration and stable East Asian semiconductor foundry access; material deviation in either driver would warrant model refresh. Specific risks include synthetic vision systems emerging as functional substitutes for standalone collision avoidance hardware, and gallium arsenide supply disruption from geopolitical friction. Recalibration cycles align with material shifts in FAA-DoD interoperability mandate enforcement and NATO STANAG revision schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Safety Systems
HUD Helmet Market
Aircraft Safety Systems
Aircraft Evacuation Systems Market
Aircraft Safety Systems
Aircraft Docking Systems Market
Aircraft Safety Systems
Helicopter Ice Protection Systems Market
Aircraft Safety Systems
Aerospace & Aircraft Collision Avoidance System Market
Aircraft Safety Systems
Aircraft Smoke Detection and Fire Extinguishing System Market
Aircraft Safety Systems
Airborne Lightning Detection System Market
Aircraft Safety Systems
Commercial Parachute Market
Aircraft Safety Systems
Aircraft Ice Protection System Market
Aircraft Safety Systems
Aircraft Survivability Equipment Market
Aircraft Safety Systems
Aviation Airbags Market
Aircraft Safety Systems
Free Fall Sensor Market
Aircraft Safety Systems
Military Airborne Collision Avoidance Systems (ACAS) Market
Aircraft Safety Systems
Aircraft Arresting System Market
Aircraft Safety Systems
Identification Friend or Foe Systems Market
Aircraft Safety Systems
South Korea Aircraft Windshield Wiper and Washer System Market