
 Global Aircraft Brakes Market | 2026-2036
Global Aircraft Brakes Market Size, Share, and Industry Trends Forecast 2026-2036
Global Aircraft Brakes Market Analysis
Market Overview
Asia-Pacific production capacity for aircraft brake assemblies is fragmenting across multiple national supply bases. Safran leverages its European forging heritage to sustain heat sink output for narrow-body programs. Honeywell International Inc. anchors North American aftermarket channels through proprietary overhaul networks. Collins Aerospace competes on integrated landing system packages that bundle brakes with actuation and steering.
Aircraft brakes are friction-based energy absorption systems that convert kinetic energy into thermal energy during landing and rejected takeoff events, with carbon-carbon composite rotors rated for operational temperatures exceeding 1500°C. They serve the essential function of safe deceleration and ground control across all fixed-wing and rotary-wing platforms. Carbon brakes command premium positioning within the brake type segment due to weight savings and extended life cycles on high-cycle commercial routes. Military aircraft applications within the aircraft type segment favor metallic and carbon-carbon configurations optimized for extreme heat flux and field repairability. OEMs capture the dominant margin pool within the end user segment through bundled landing gear contracts, while maintenance providers absorb growing aftermarket volume as global fleet age extends.
FAA airworthiness directives and EASA certification standards govern brake thermal performance and fatigue life, with both agencies mandating expanded qualification testing for new carbon composite formulations. The EU Green Deal's aviation decarbonization framework pressures manufacturers to reduce brake particulate emissions and improve manufacturing energy efficiency. China's CAAC aligns with FAA thermal test protocols while adding domestic content requirements for locally assembled aircraft programs. Stakeholders must monitor evolving certification reciprocity agreements and carbon border adjustment mechanisms that could restructure regional sourcing economics.
Market Dynamics
Carbon brake heat sink qualification protocols are tightening across FAA and EASA jurisdictions, forcing foundries to retool thermal test facilities and extending new entrant certification timelines by multiple cycles. This regulatory compression is reshaping supplier economics and consolidating qualified vendor pools.
Growth Catalysts
- Narrow-body fleet expansion:Commercial operators in India and Vietnam are accelerating brake replacement schedules as high-cycle route density wears carbon rotors faster than design specifications. MRO providers absorb this volume through captive overhaul networks.
- EU Green Deal aviation framework:The EU Green Deal pressures manufacturers to reduce brake particulate emissions during landing events, creating retrofit demand for low-emission friction formulations on existing A320 and B737 fleets.
- Carbon-carbon composite advancement:Next-generation 3D-woven preforms are extending heat sink life cycles, reducing per-landing operating costs for ultra-high-utilization carriers operating in Middle Eastern climates.
Market Restraints
- Specialized precursor fiber concentration:Polyacrylonitrile precursor supply for carbon brake matrices concentrates among Japanese and US chemical producers, exposing foundries to input cost volatility and allocation constraints during aerospace demand surges.
- EASA thermal qualification backlog:Extended test queue times at European notified bodies are delaying new heat sink variant approvals, freezing product pipelines for 18-24 month windows.
- Metallic brake residual demand:Regional turboprop and military trainer segments continue specifying steel rotor stacks for field repairability, limiting carbon brake penetration in sub-50-seat categories.
Strategic Opportunities
- Urban air mobility integration:eVTOL developers in Germany and China are specifying lightweight carbon brake modules for emergency landing systems, opening a design-in channel outside traditional commercial aviation procurement.
- India PLI scheme localization:India's production-linked incentive scheme for aerospace components is attracting brake assembly joint ventures to serve IndiGo and Air India narrow-body expansion programs.
- Digital twin predictive maintenance:Sensor-embedded heat sinks combined with physics-based degradation models are enabling unbundled brake-life subscription services, shifting revenue from part sales to availability contracts.
Industry Challenges
- High-temperature materials engineering talent scarcity:Carbon-carbon processing expertise concentrates among retiring cohorts at legacy European foundries, constraining capacity expansion at newer Asian facilities.
- Legacy fleet brake obsolescence management:OEMs face conflicting priorities between supporting out-of-production heat sink variants and reallocating engineering resources to next-generation platforms, straining aftermarket service continuity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Aircraft Brakes Market |
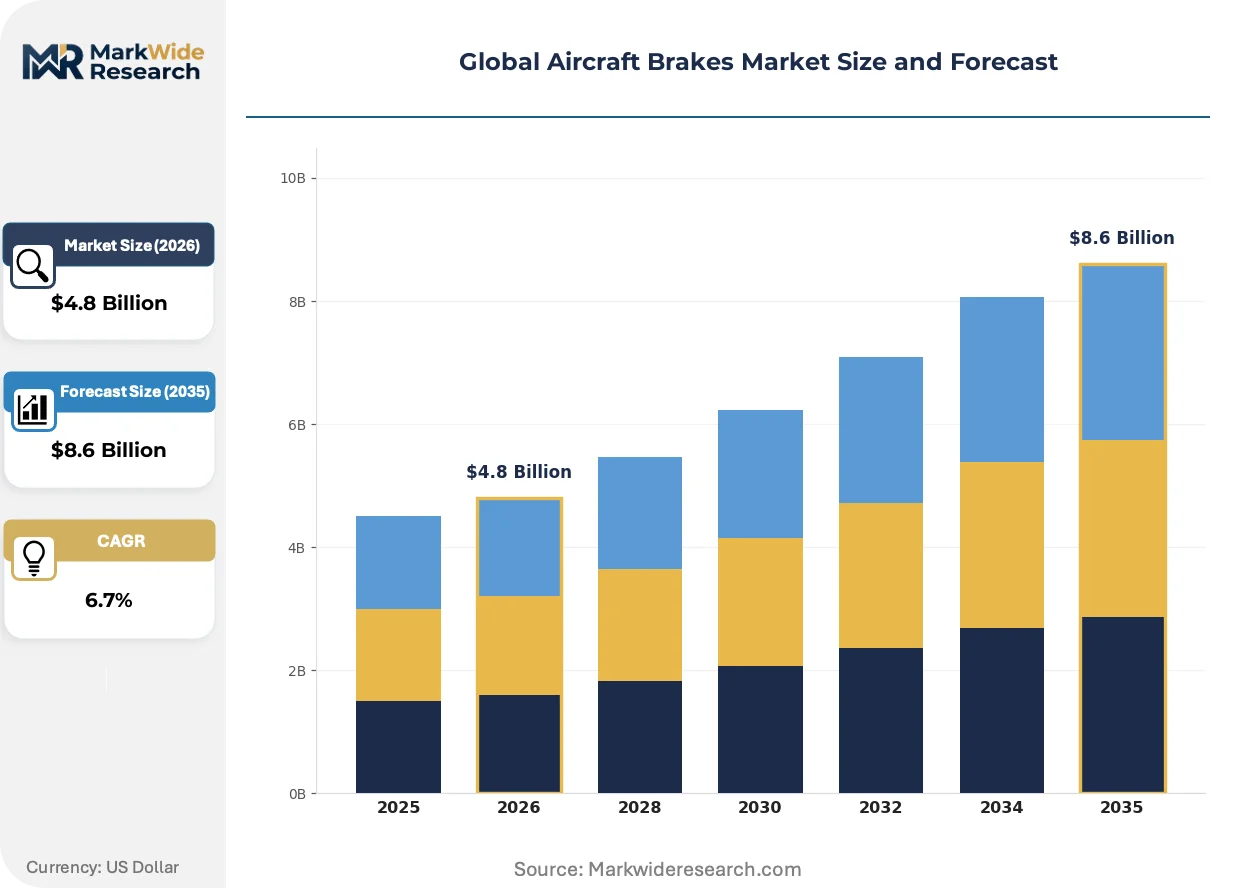
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Brake Type: Disc Brakes, Drum Brakes, Carbon Brakes, Hydraulic Brakes Aircraft Type: Commercial Aircraft, Military Aircraft, Business Jets, Helicopters Material: Metallic, Composite, Carbon-Carbon, Ceramics End User: OEMs, Maintenance Providers, Airlines, Leasing Companies |
| Companies Covered | Safran, Honeywell International Inc., Collins Aerospace, Crane Aerospace & Electronics, Parker-Hannifin Corporation, Meggitt PLC, RTX Corporation, Raytheon Technologies Corporation, Beringer Aero, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Aircraft Brakes Market Emerging Trajectories
Digital thread technologies are penetrating brake manufacturing, compressing design-to-certification cycles and enabling real-time thermal performance monitoring that was previously impossible with analog quality systems.
Additive manufacturing of brake housing geometries is virtualizing traditional sand-casting workflows, allowing Safran and Honeywell to iterate structural designs without hard-tooling lead times. Tier-one suppliers are adopting laser powder bed fusion for titanium brake pistons, cutting prototype cycles from months to weeks. This capability is virtualizing the competitive barrier between high-volume incumbents and agile mid-tier challengers.
EASA's expanded CS-25 thermal endurance requirements are mandating 50% longer qualification test sequences for new carbon formulations, forcing manufacturers to parallelize physical and computational validation. The regulation compresses product launch windows while raising R&D breakeven thresholds. European narrow-body operators absorb compliance costs through extended lease rate factors.
Airline procurement teams are unbundling brake overhaul from landing gear maintenance contracts, creating direct supplier relationships that bypass traditional OEM intermediaries. LCCs in Southeast Asia lead this disintermediation, negotiating heat sink-only supply agreements with foundries. This pattern concentrates in high-utilization fleets where brake life predictability outweighs bundled warranty convenience.
Global Aircraft Brakes Market Segmentation
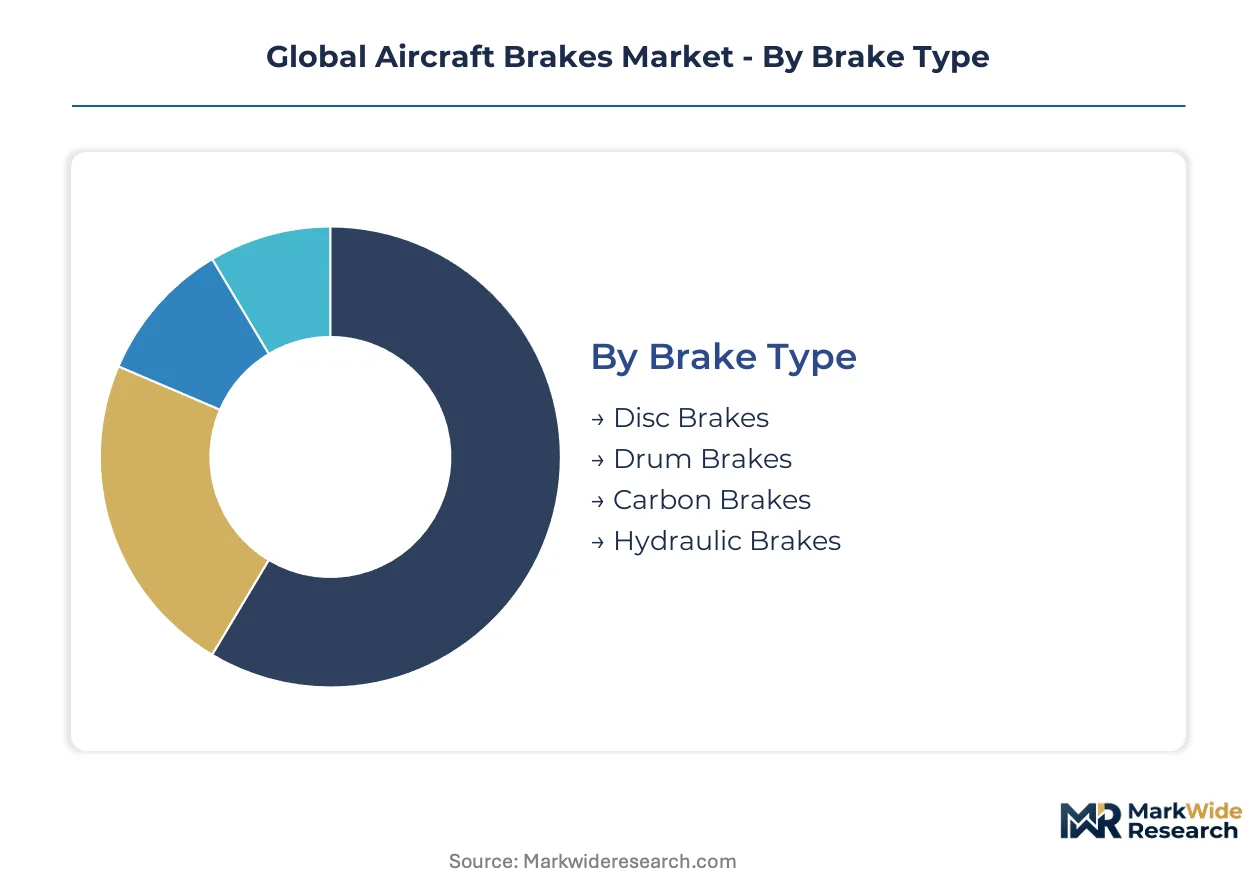
Brake type and material composition determine thermal performance ceilings and replacement economics across fleet categories. Aircraft platform specifications and procurement channel structures create divergent margin pools and certification pathways for suppliers.
Brake Type:
Cost tier separates legacy metallic configurations from advanced carbon systems commanding premium positioning in high-cycle operations.
- Carbon Brakes:Carbon-carbon composite rotors withstand operational temperatures exceeding 1500°C while delivering 30-40% weight reduction over metallic alternatives. Ultra-high-utilization carriers operating Middle Eastern routes specify these for extended heat sink life cycles under extreme thermal loading.
- Disc Brakes:Multiple-rotor disc stacks constitute the dominant commercial aviation architecture, with caliper-actuated friction interfaces governing deceleration rates during landing and rejected takeoff events. Narrow-body fleet expansion in India and Vietnam drives replacement volume through captive MRO networks.
- Drum Brakes:Cylindrical brake shoes expand against inner drum surfaces for simplified mechanical actuation in smaller aircraft categories.
- Hydraulic Brakes:Fluid-pressure actuation systems serve legacy platforms and certain rotary-wing applications requiring precise modulation control.
Carbon brakes command the established base. The steepest expansion runs through disc brake replacement schedules on narrow-body fleets.
Aircraft Type:
Application requirements dictate thermal flux tolerance, weight constraints, and field repairability priorities across platform categories.
- Commercial Aircraft:High-cycle narrow-body and wide-body operations prioritize weight-optimized carbon brakes with predictive wear monitoring. FAA and EASA thermal qualification protocols govern heat sink certification for A320 and B737 family programs.
- Military Aircraft:Extreme heat flux tolerance and rapid field repairability favor metallic and carbon-carbon configurations optimized for austere operating conditions. Combat aircraft specifications prioritize damage tolerance over weight minimization.
- Business Jets:Premium cabin segments specify lightweight carbon brake modules to maximize payload-range performance on long-haul missions.
- Helicopters:Rotorcraft applications emphasize compact packaging and anti-skid integration for dynamic landing conditions on unprepared surfaces.
Commercial aircraft absorb the dominant aftermarket volume. Military platforms sustain specialized foundry capacity through long-term supply agreements.
Material:
Supply concentration and precursor fiber availability constrain formulation choices across temperature and cost specifications.
- Carbon-Carbon:3D-woven preform matrices extend heat sink durability through controlled fiber architecture, reducing per-landing operating costs for carriers with intensive utilization profiles. Japanese and US polyacrylonitrile precursor producers control input supply chains.
- Metallic:Steel and beryllium-copper rotor stacks retain specification in regional turboprop and military trainer segments where field machinability outweighs weight penalties. Steel brake demand concentrates in sub-50-seat categories with limited carbon brake penetration.
- Composite:Hybrid material systems combine metallic substrates with carbon friction surfaces for intermediate performance tiers.
- Ceramics:Oxide and non-oxide ceramic formulations serve niche high-temperature applications requiring oxidation resistance beyond carbon-carbon limits.
Carbon-carbon materials capture premium positioning. Metallic configurations defend residual demand in repairability-critical segments.
End User:
Customer type determines procurement channel structure, contract duration, and margin distribution between OEM bundled sales and aftermarket disintermediation.
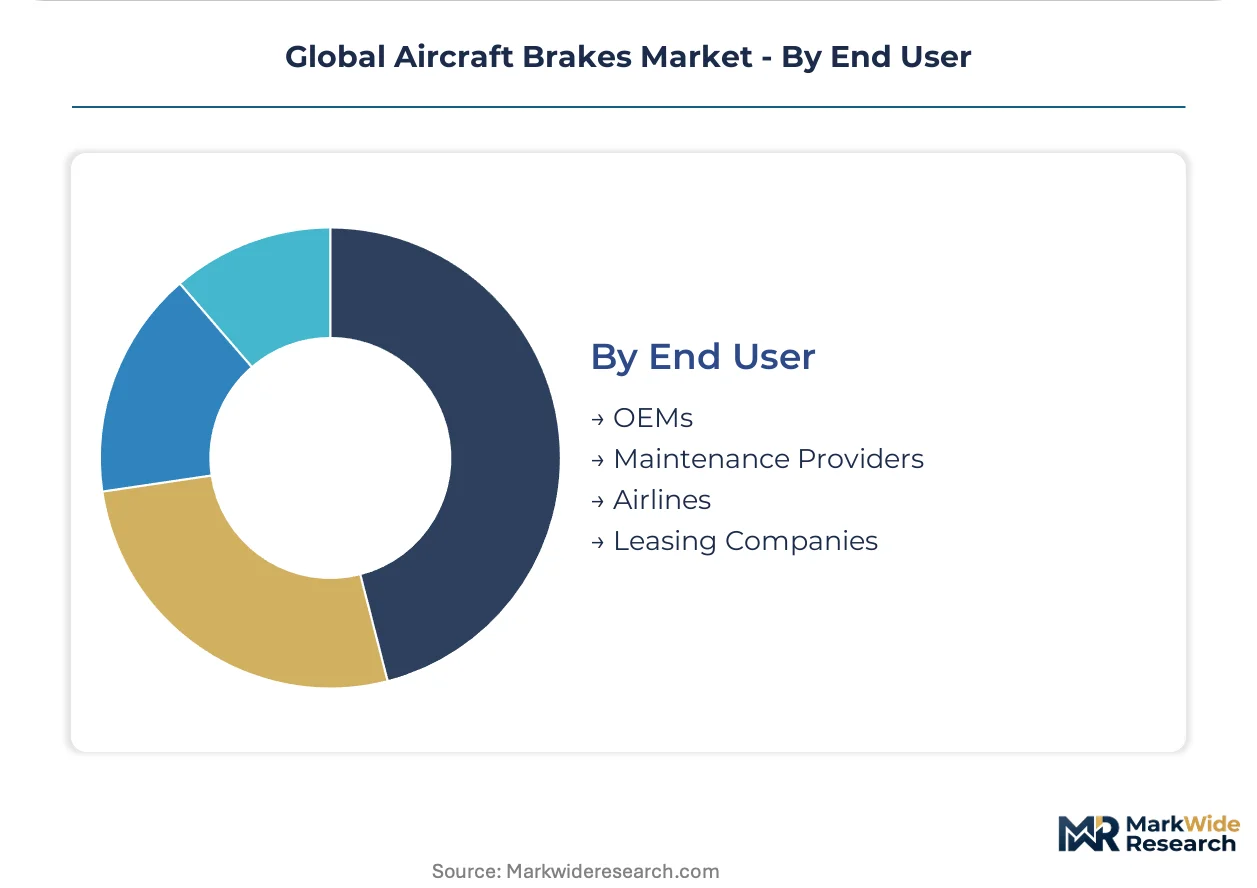
- OEMs:Original equipment manufacturers capture dominant margin pools through bundled landing gear contracts integrating brakes with actuation and steering systems. Collins Aerospace and Safran leverage integrated system packages to lock in initial fitment decisions.
- Maintenance Providers:MRO specialists absorb expanding aftermarket volume as global fleet age extends beyond design service objectives. Southeast Asian LCCs unbundle brake overhaul from landing gear contracts to negotiate direct heat sink supply agreements.
- Airlines:Fleet operators with high route density accelerate replacement schedules and specify performance-based availability contracts over traditional part sales.
- Leasing Companies:Asset owners influence brake specification through return condition requirements and redelivery maintenance reserves.
OEMs retain the anchored revenue base. The fastest share gains emerge through maintenance provider direct procurement relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FAA airworthiness directives anchor the United States as the dominant geography, where legacy fleet modernization drives aftermarket brake volume through specialized overhaul networks.
United States
High-cycle commercial operators accelerate carbon rotor replacement schedules on narrow-body fleets operating dense domestic routes. FAA thermal qualification protocols govern new heat sink certifications, extending approval timelines for modified carbon-carbon formulations. Wichita's aerospace cluster hosts specialized foundries supplying heat-treated brake components to regional MRO facilities.
France
Safran leverages European forging heritage to sustain carbon brake output for A320 family programs serving Air France-KLM and Transavia. EASA CS-25 thermal endurance requirements mandate extended qualification test sequences, compressing product launch windows for new formulations. The Toulouse-Blagnac aerospace corridor concentrates brake assembly integration with landing gear systems.
China
CAAC aligns with FAA thermal test protocols while imposing domestic content requirements on locally assembled C919 and ARJ21 programs. The country's dual carbon goals pressure foundries to reduce manufacturing energy intensity in carbon-carbon processing. Xi'an's aviation industrial base hosts state-owned enterprises developing indigenous brake heat sink capabilities.
Germany
Lufthansa Technik absorbs expanding aftermarket volume through captive overhaul networks serving European LCC brake replacement demand. EU Green Deal aviation decarbonization frameworks pressure manufacturers to reduce brake particulate emissions during landing events. Hamburg's aerospace maintenance cluster specializes in predictive brake life monitoring systems.
India
IndiGo and Air India narrow-body expansion programs accelerate brake replacement schedules on high-utilization domestic routes. The PLI scheme for aerospace components attracts brake assembly joint ventures seeking localization benefits. Bangalore's aerospace manufacturing corridor hosts emerging Tier-2 suppliers qualifying for OEM direct procurement relationships.
Global Aircraft Brakes Market Vendor Landscape
Capability concentration sits with European foundries possessing multi-decade carbon-carbon processing expertise; scale advantage sits with North American conglomerates commanding bundled landing gear contracts. The vendor base organizes into three tiers: integrated system houses, specialized brake foundries, and emerging regional assemblers. Strategic moves center on M&A for thermal test facility capacity and strategic partnerships for precursor fiber supply security.
Within the integrated system tier, Safran, Honeywell International Inc., and Collins Aerospace exemplify divergent competitive positioning. Safran occupies the European heritage foundry archetype with concentrated heat sink production. Honeywell anchors North American aftermarket channels through proprietary overhaul network relationships. Collins represents the bundled landing system approach, integrating brakes with actuation and steering modules. Each configuration reflects distinct geographic regulatory alignment and customer relationship structures.
| Leading Market Players |
|---|
| Safran |
| Honeywell International Inc. |
| Collins Aerospace |
| Crane Aerospace & Electronics |
| Parker-Hannifin Corporation |
| Meggitt PLC |
| RTX Corporation |
| Raytheon Technologies Corporation |
| Beringer Aero |
| Others |
Supply Flow & Price Mechanics
Single-source dependency on Japanese polyacrylonitrile precursor fibers compresses both pricing tier spreads and supply chain resilience, forcing foundries to absorb input volatility while airlines unbundle overhaul contracts to capture cost transparency. This structural concentration rewards vertically integrated heat sink producers with captive fiber relationships while exposing assembly-only players to margin erosion during aerospace demand surges.
Pricing Analysis
North American brake overhaul rates run 15-25% above European equivalents due to FAA-mandated thermal test facility overhead and legacy fleet density. Pricing stratifies across premium carbon-carbon formulations, standard metallic configurations, and economy-tier refurbished heat sinks. Cost compression in the metallic segment intensifies as Indian and Vietnamese operators negotiate direct foundry relationships. Low-cost carriers in Southeast Asia exhibit the highest price sensitivity, while Middle Eastern ultra-high-utilization carriers prioritize life-cycle cost predictability over unit pricing.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning, with CAAC domestic content requirements forcing dual-sourcing strategies for C919 and ARJ21 programs. Manufacturing concentrates in France, the United States, and China, with heat sink forging anchored in European heritage foundries and assembly migrating to Asian joint ventures. Polyacrylonitrile precursor fibers, 3D-woven preforms, and thermal test capacity constitute critical input dependencies. Distribution runs through captive OEM networks for initial fitment and independent MRO channels for aftermarket replacement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market rewards specialized carbon-carbon processing expertise that concentrates among aging European engineering cohorts, creating acquisition premiums for foundries with qualified thermal test facilities and active FAA-EASA certification pipelines.
For Market Incumbents: Harden defensive positions by securing long-term polyacrylonitrile precursor supply agreements with Japanese chemical producers before allocation constraints intensify. Expand thermal test facility capacity in India to capture PLI scheme localization benefits and preempt emerging Asian challengers. Prioritize certification investment for next-generation 3D-woven preform architectures that extend heat sink life cycles under EASA's expanded CS-25 requirements. For New Entrants and Emerging Players: Pursue white-space opportunities in urban air mobility emergency brake modules, where eVTOL developers in Germany and China seek lightweight carbon systems outside traditional commercial aviation procurement channels. Target India's aerospace manufacturing corridor through joint ventures qualifying for PLI scheme benefits. Lead with digital twin predictive maintenance capabilities that shift customer relationships from part sales to availability-based subscriptions. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialized foundries with active certification pipelines and captive precursor relationships. Long-term viability hinges on carbon-carbon processing talent retention and thermal test facility scarcity. Acquisition targets should demonstrate qualified vendor status with both FAA and EASA. Watch EASA thermal qualification queue times as the inflection indicator—backlog reduction signals accelerated product pipeline velocity and margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Fiber Supply | Captive polyacrylonitrile access insulates margins from Japanese producer allocation constraints. |
| Thermal Test Facility Expansion | Added EASA-notified body capacity compresses new heat sink variant approval timelines from 24 months. |
| Digital Twin Predictive Maintenance Platform | Sensor-embedded heat sinks enable subscription revenue models with Lufthansa Technik and Air France-KLM. |
| India PLI Joint Venture Formation | Localization benefits capture IndiGo and Air India narrow-body brake replacement volume. |
| eVTOL Emergency Brake Design Partnership | Urban air mobility channel opens procurement relationships with Lilium and EHang outside incumbent lock-in. |
Methodological Framework
The analysis maps carbon brake heat sinks, metallic disc assemblies, and hydraulic actuation systems, each validated through procurement directors at narrow-body operators, MRO network managers, thermal test facility engineers, and OEM landing gear program leads. Primary fieldwork combined structured interviews with secondary validation against FAA airworthiness directive filings, EASA certification databases, SEC 10-K aerospace segment disclosures, and customs trade data for polyacrylonitrile precursor flows. Bottom-up fleet modeling and top-down OEM contract value triangulation anchored volume estimates.
Forecasts hold constant FAA-EASA regulatory reciprocity frameworks and carbon border adjustment mechanism implementation timelines while varying narrow-body fleet expansion rates and eVTOL certification pathways across the projection horizon. Segmentation dimensions include brake type, aircraft platform category, material composition, and end-user procurement channel. CAGRs derive from fitted growth curves against historical replacement schedule data and thermal performance degradation physics. Industry-specific inputs encompass heat sink life-cycle models under Middle Eastern climate loading and EASA CS-25 thermal endurance test sequence extensions.
Macroeconomic conditions sit as an overlay; deviation in jet fuel price volatility, commercial aviation traffic recovery trajectories, or aerospace supply chain labor availability would shift the trajectory. Forecasts reflect documented assumptions regarding certification timeline norms and precursor fiber supply elasticity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Safety Systems
Aircraft Survival Equipment Market
Aircraft Safety Systems
Cloud-Connected Aircraft Safety Data Management Platforms Market
Aircraft Safety Systems
Free Fall Sensor Market
Aircraft Safety Systems
Aerospace & Aircraft Collision Avoidance System Market
Aircraft Safety Systems
Rescue Hoist System Market
Aircraft Safety Systems
Military Aircraft Collision Avoidance Systems Market
Aircraft Safety Systems
Aircraft Evacuation Slide Market
Aircraft Safety Systems
Commercial Aircraft Carbon Brakes Market
Aircraft Safety Systems
South Korea Aircraft Windshield Wiper and Washer System Market
Aircraft Safety Systems
Global Aircraft Brake System Market
Aircraft Safety Systems
Aircraft Survivability Equipment Market
Aircraft Safety Systems
Helicopter Ice Protection Systems Market
Aircraft Safety Systems
Aircraft Arresting System Market
Aircraft Safety Systems
Military Airborne Collision Avoidance Systems (ACAS) Market
Aircraft Safety Systems
Aircraft Ice Protection System Market
Aircraft Safety Systems
HUD Helmet Market