
 Aircraft Fire Protection Systems Market | 2026-2036
Aircraft Fire Protection Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Fire Protection Systems Market Intelligence
Aftermarket service and component replacement profitability is narrowing due to the extended operational lifespans and predictive maintenance features integrated into next-generation systems. Safran specializes in comprehensive, integrated safety solutions for a wide range of aircraft platforms. Honeywell International Inc. leverages its deep avionics and sensor technology expertise to offer advanced detection systems. Collins Aerospace, a unit of RTX Corporation, competes across the value chain with a broad portfolio targeting both original equipment and MRO channels.
Aircraft fire protection systems are engineered networks designed to detect and extinguish fires in designated zones. These systems incorporate technologies like multi-spectrum infrared flame detectors and automated dispersal of chemical foam or inert gas suppressants. Their primary purpose is to ensure passenger and crew safety by neutralizing fire threats in high-risk areas such as engine compartments, cargo holds, and auxiliary power units. While fire detection remains a foundational requirement, development is focused on advanced gas-based suppression systems that use environmentally compliant agents to replace traditional halon.
The market operates under stringent regulatory oversight from bodies including the FAA in the United States and EASA in Europe. These agencies enforce mandates on system certification, performance standards, and material fire-resistance properties through frameworks like Technical Standard Orders (TSOs). Compliance with these regulations is non-negotiable for market access and directly shapes product development cycles. Suppliers must navigate the technical challenge of developing effective and certified halon alternatives while managing the cost expectations of airline and military operators.
Market Dynamics
The transition away from legacy halon-based agents serves as the central force shaping the aircraft fire protection systems market. This shift, driven by environmental regulations, compels innovation in chemical suppressants and system design across the entire value chain.
Growth Catalysts
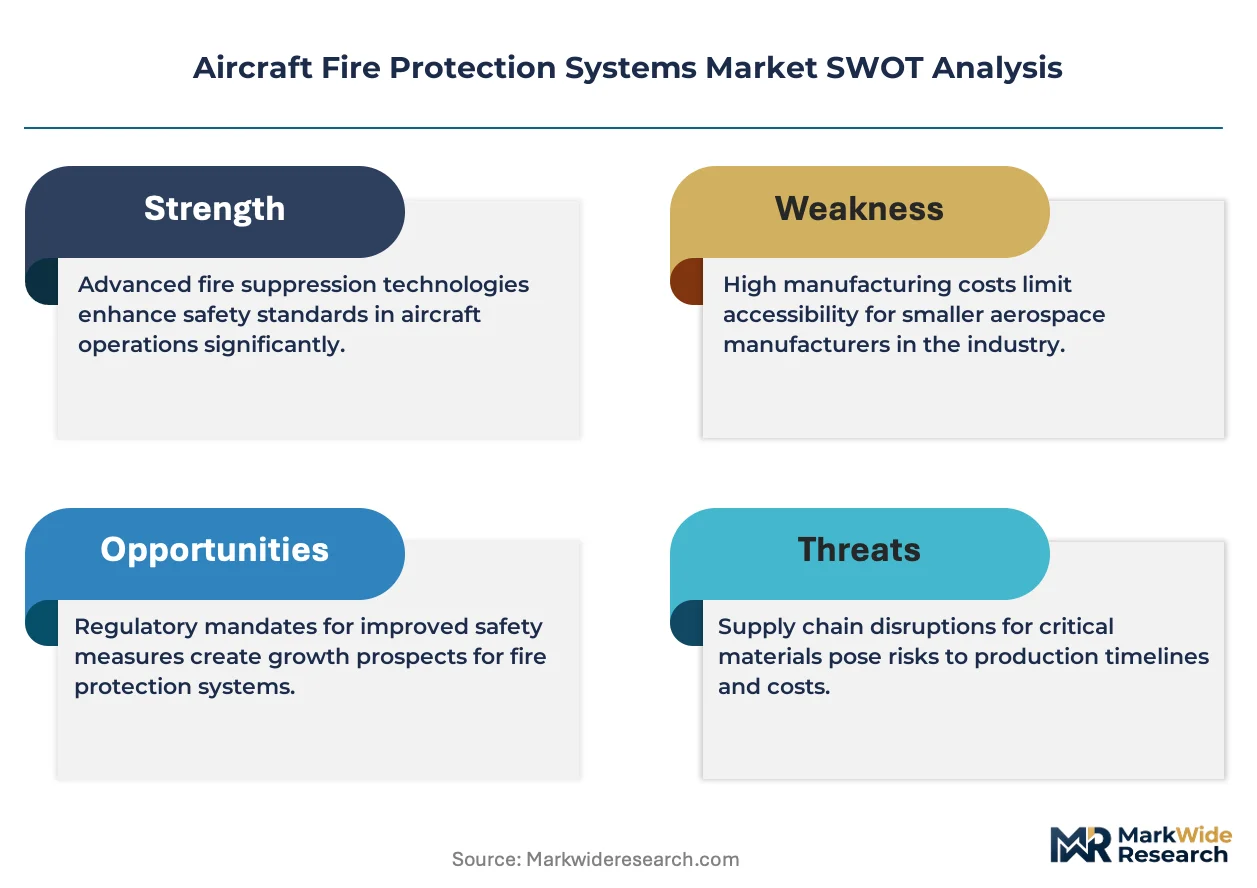
- Regulatory Mandates:The phasedown of halon production and use, enforced by bodies like the FAA and EASA, creates a non-negotiable demand for certified, environmentally compliant replacement systems for both new production and existing aircraft fleets.
- Commercial Fleet Expansion:A rising backlog of commercial aircraft orders, particularly for narrow-body jets, directly translates into volume demand for original equipment fire detection and suppression systems to equip these new airframes.
- Advanced Detection Technology:Demand for enhanced safety is driving the adoption of sophisticated detection technologies, such as multi-spectrum infrared sensors, especially within high-value cargo and engine applications to minimize false alarm rates.
Market Restraints
- High Certification Costs:The significant financial investment and time required to achieve certification for new suppression agents and hardware under stringent FAA and EASA frameworks act as a major barrier to market entry and slow innovation cycles.
- Performance Parity Challenges:Developing halon alternatives that match its unique combination of low toxicity, minimal residue, electrical non-conductivity, and high effectiveness per unit weight remains a persistent technical hurdle for chemical engineers.
- Legacy Fleet Integration:Retrofitting older aircraft with new, physically different fire suppression systems presents significant engineering and logistical complexities, often limiting the addressable market to major overhauls or new builds.
Strategic Opportunities
- Urban Air Mobility (UAM):The development of eVTOL and other novel air mobility platforms creates a new market segment requiring specialized fire protection solutions tailored to the unique risks of high-density lithium-ion battery packs.
- Predictive Maintenance Integration:There is a clear opportunity to embed sensor data from fire protection systems into broader aircraft health monitoring platforms, enabling predictive maintenance alerts for components before they fail and reducing unscheduled downtime.
- MRO Service Expansion:Expanding maintenance, repair, and overhaul capabilities for next-generation, halon-free systems in growing aviation hubs across the Middle East and Asia-Pacific offers a significant service-based revenue stream.
Industry Challenges
- System Integration Complexity:Ensuring seamless communication and functionality between new fire protection systems and legacy avionics suites during retrofit programs is a primary operational challenge for MRO providers and system integrators. *Agent Supply Chain Scalability: Establishing a reliable, global supply chain for novel, environmentally compliant chemical agents at a scale sufficient to support both OEM and aftermarket demand presents a logistical hurdle for manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Fire Protection Systems Market |
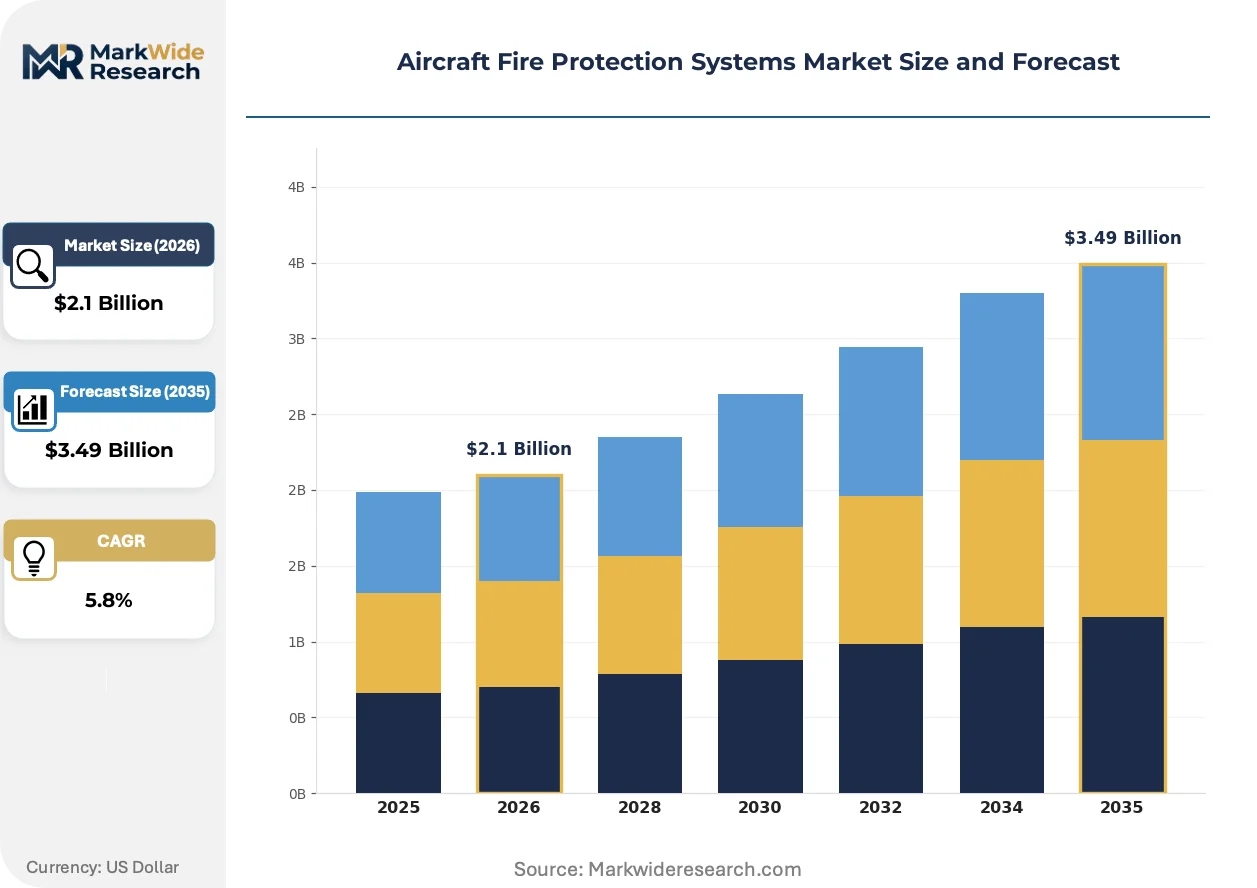
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.49 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Fire Detection, Fire Suppression, Fire Extinguishing, Overheat Protection, Smoke Control Technology: Photoelectric, Ionization, Linear Heat Detection, Thermal, Gas-Based, Chemical Foam Application: Cabin, Cargo Hold, Engine Compartment, Avionics Bay, Auxiliary Power Unit, Landing Gear End User: Commercial Airlines, Military Operators, Business Jets, Aeronautical Maintenance Providers |
| Companies Covered | Safran, Diehl Stiftung and Co. KG, Honeywell International Inc., AMETEK Inc., Curtiss-Wright Corporation, RTX Corporation, Collins Aerospace, Siemens AG, Meggitt plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Fire Protection Systems Market Strategic Shifts & Innovations
Development in the aircraft fire protection market is pivoting from purely reactive suppression to integrated, data-aware safety architectures. This evolution is driven by material science advancements in extinguishing agents and the incorporation of intelligent sensing technologies.
Multi-spectrum infrared flame detectors represent a significant product evolution, using multiple wavelengths to confirm the presence of a genuine fire. New aircraft programs are rapidly adopting these sensors to reduce costly diversions caused by false alarms from non-fire sources. This high-fidelity sensing capability is collapsing the time between an initial alert and a confirmed threat assessment, enabling faster and more decisive automated responses.
The European Union's F-Gas Regulation imposes strict controls on the use of fluorinated greenhouse gases, directly impacting the chemistry of fire suppression. This forces manufacturers to accelerate research into inert gas mixtures and chemical agents with a lower Global Warming Potential (GWP). System suppliers targeting the European market must now prioritize GWP alongside fire-extinguishing performance in their product development roadmaps to ensure compliance.
Airlines are increasingly specifying fire protection systems with integrated health monitoring and diagnostic reporting. This trend disrupts the traditional aftermarket model of selling discrete replacement parts, favoring suppliers that offer systems capable of predicting component failures and optimizing maintenance schedules. This shift is most apparent among major carriers in North America and Europe, where maximizing aircraft availability is a primary operational goal.
Aircraft Fire Protection Systems Market Segmentation
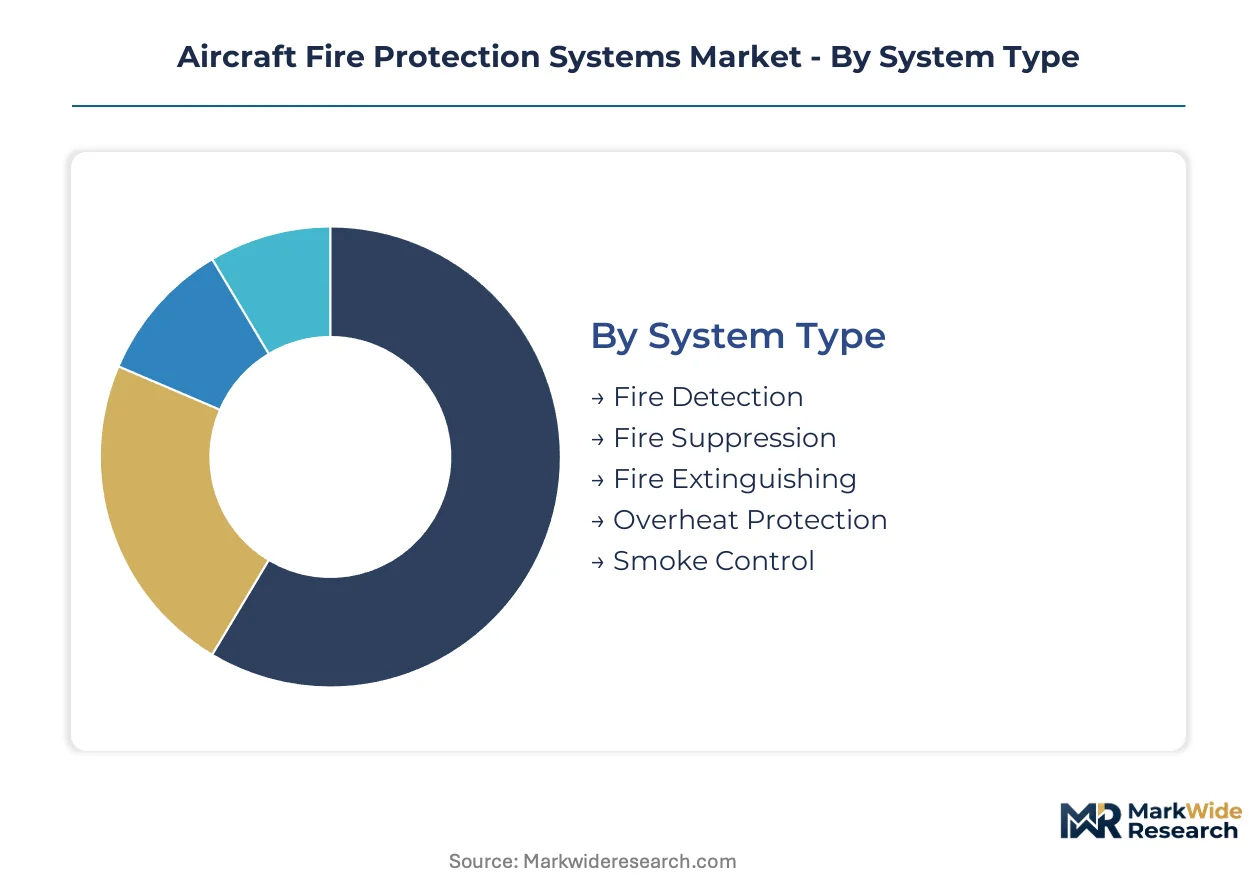
Understanding the distinct segments within the aircraft fire protection systems market reveals varied operational demands and technological preferences. These categories highlight specific engineering challenges and regulatory compliance requirements across different aircraft zones and operator types. Each segment contributes uniquely to the market's overall growth trajectory and innovation landscape.
System Type:
The turnover rates for aircraft fire protection system types vary significantly, reflecting both regulatory mandates and operational wear. Continuous monitoring systems often require more frequent calibration compared to single-use suppression systems.
- Fire Detection:These systems utilize sensors like multi-spectrum infrared detectors to identify the presence of fire or smoke within designated zones. Demand is concentrating in new aircraft production for enhanced safety features.
- Fire Suppression:Designed to extinguish active fires, these systems typically involve the automated release of chemical agents or inert gases. The transition away from halon agents is accelerating demand for new suppression systems.
- Fire Extinguishing:This refers to portable or manual systems used for localized fire control, commonly found in cabin areas.
- Overheat Protection:These systems monitor critical components for excessive temperatures, providing early warnings to prevent fire ignition.
- Smoke Control:Focused on managing smoke propagation within the cabin and cargo areas, these systems enhance visibility and evacuation safety.
Fire Detection anchors the volume base while Fire Suppression gains share at the steepest rate.
Technology:
The maturity of fire protection technologies ranges from well-established sensor types to rapidly evolving suppression agents. Suppression chemistry is undergoing a significant generational shift to meet environmental regulations.
- Gas-Based:These technologies use inert gases or chemical agents with low Global Warming Potential to suppress fires by displacing oxygen or interrupting the combustion chain reaction. Demand is concentrated in new aircraft designs and retrofit programs due to environmental mandates.
- Chemical Foam:Foam-based systems create a barrier to extinguish fires, particularly effective against liquid fuel fires in specific aircraft zones. Their application is critical in areas like engine nacelles.
- Photoelectric:These smoke detectors identify smoke particles by scattering light, commonly used in cabin and cargo areas.
- Ionization:Ionization smoke detectors respond quickly to fast-flaming fires by detecting changes in electrical current caused by smoke particles.
- Linear Heat Detection:These systems provide continuous temperature monitoring along a specific path, signaling an alarm when a critical temperature is reached.
- Thermal:Thermal detectors respond to specific temperature thresholds or rapid temperature rises, offering robust fire detection in harsh environments.
Gas-Based technologies are experiencing the most intense development focus, driven by the urgency of halon replacement.
Application:
The specific application zones within an aircraft present distinct fire risks and require tailored protection system designs. High-energy areas and passenger compartments necessitate different approaches to detection and suppression.
- Engine Compartment:These areas demand robust fire protection due to the presence of fuel, lubricants, and high temperatures, requiring rapid detection and powerful suppression. They are a primary focus for advanced thermal and gas-based systems.
- Cargo Hold:Fire protection in cargo holds focuses on detecting and suppressing fires that could originate from various materials, often requiring inert gas or chemical foam systems. Enhanced detection capabilities are a regulatory priority for these zones.
- Cabin:Passenger cabin fire safety primarily involves smoke detection, portable extinguishers, and smoke control systems to facilitate evacuation.
- Avionics Bay:Protection in avionics bays centers on preventing electrical fires and ensuring minimal damage to sensitive equipment.
- Auxiliary Power Unit:APUs require dedicated fire protection similar to main engines due to fuel and operational heat.
- Landing Gear:Fire protection for landing gear bays focuses on detecting overheating brakes or hydraulic fluid leaks, often using linear heat detection.
Engine Compartment applications command significant investment due to inherent fire risks and stringent safety requirements.
End User:
Different end-user segments exhibit unique procurement cycles, regulatory compliance pressures, and operational budgets for fire protection systems. Each customer type prioritizes distinct aspects for their fleet.
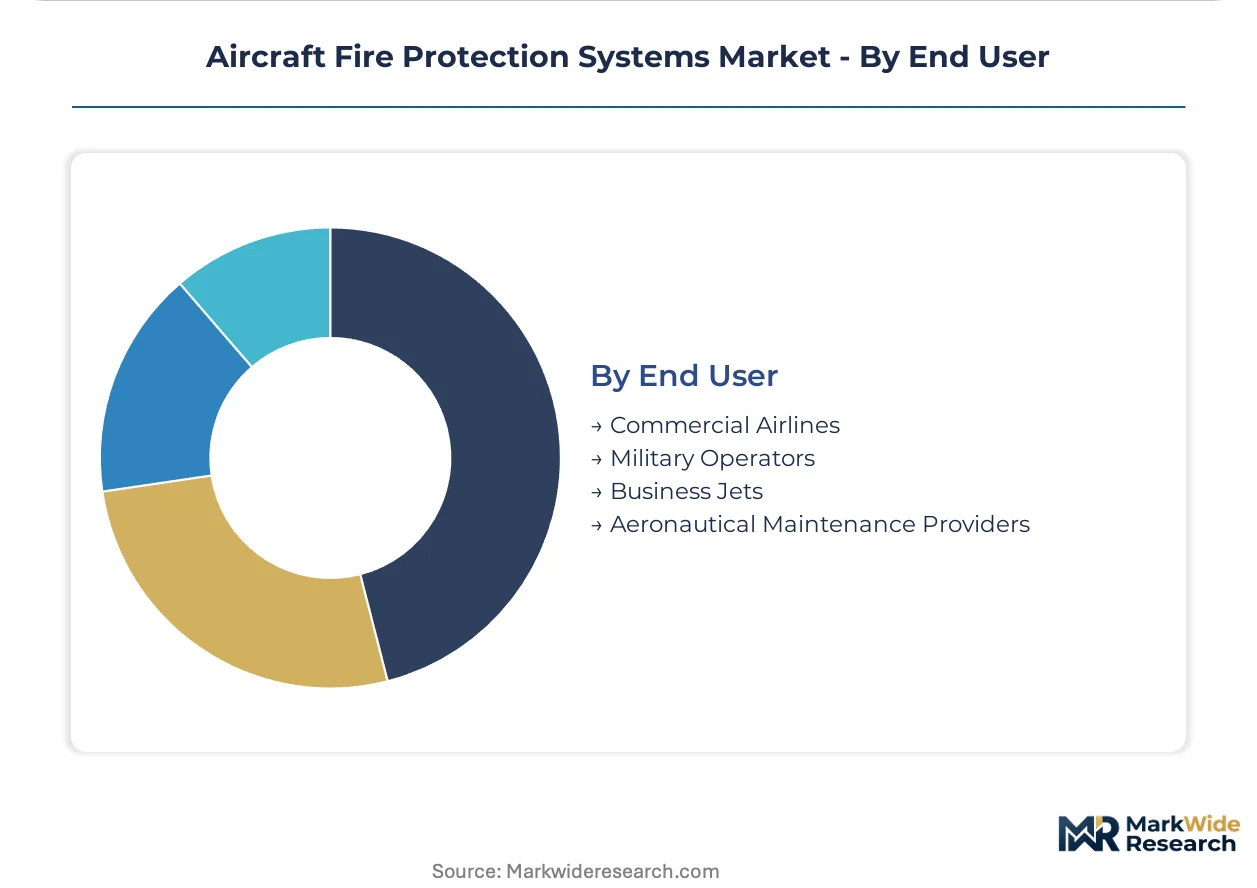
- Commercial Airlines:These operators prioritize cost-effective, highly reliable systems with long service lives and ease of maintenance to maximize aircraft availability. Their fleet expansion drives significant demand for halon alternatives.
- Military Operators:Military applications demand systems with extreme durability, rapid response capabilities, and often specialized fire suppression agents for combat environments. These platforms require robust, high-performance solutions.
- Business Jets:Owners of business jets seek advanced, discreet, and lightweight fire protection solutions that integrate seamlessly with luxury interiors.
- Aeronautical Maintenance Providers:MROs are crucial for the installation, maintenance, and certification of fire protection systems during aircraft overhauls and retrofits.
Commercial Airlines represent the largest volume segment, while Military Operators drive innovation in extreme performance requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global demand for aircraft fire protection systems exhibits varied consumption patterns across key geographies. While some regions prioritize original equipment for new aircraft production, others focus on retrofitting existing fleets to meet updated regulatory standards. This differential approach shapes procurement strategies and technological adoption rates worldwide.
United States
Demand for fire protection systems in the United States is driven by significant new aircraft production and ongoing retrofit programs. The FAA mandates stringent certification for all fire suppression technologies, including halon alternatives. Major aerospace manufacturing hubs like Seattle and Wichita are centers for both OEM integration and MRO activities.
France
France's market is propelled by a robust aerospace manufacturing sector and the need for advanced fire detection in new aircraft. EASA regulations, particularly the F-Gas Regulation, compel the adoption of environmentally compliant suppression agents. Toulouse, a primary aerospace cluster, sees intense development and integration of these next-generation systems.
Germany
German operators prioritize high-reliability fire protection systems for both commercial and military aircraft fleets. European F-Gas Regulation compliance significantly influences product development and procurement decisions within the country. Aerospace research facilities in Bavaria contribute to the advancement of thermal and gas-based detection solutions.
Japan
Japan's aerospace sector demands sophisticated fire protection for its specialized aircraft and growing MRO activities. METI guidelines encourage the use of advanced detection and suppression technologies for both commercial and defense applications. Nagoya's aerospace industry cluster integrates these systems into new aircraft platforms and maintenance programs.
United Arab Emirates
Operators in the United Arab Emirates experience demand from expanding commercial airline fleets and MRO service expansion. MOHAP regulations ensure compliance with international aviation safety standards for fire protection systems. Dubai and Abu Dhabi are becoming critical MRO hubs for the installation and servicing of advanced fire safety equipment.
Aircraft Fire Protection Systems Market Key Industry Players
Capability concentration sits with one tier; scale advantage sits with another, creating a dynamic competitive environment. The market structure for aircraft fire protection systems is characterized by a mix of established aerospace integrators and specialized technology providers. Two strategic archetypes are prominent: large diversified conglomerates offering integrated safety solutions and niche players focused on advanced detection or suppression chemistry. Dominant competitive moves include strategic partnerships for technology co-development and portfolio diversification into halon-alternative solutions.
On the premium-tier vector, Safran exemplifies comprehensive, integrated safety solutions across diverse aircraft platforms. Honeywell International Inc. occupies a strong position through its deep avionics and sensor technology expertise, anchoring advanced detection system offerings. Collins Aerospace, a unit of RTX Corporation, represents a broad portfolio approach, competing across the value chain in both original equipment and MRO channels. These entities reflect the industry's drive towards integrated systems and environmentally compliant technologies.
| Leading Market Players |
|---|
| Safran |
| Diehl Stiftung and Co. KG |
| Honeywell International Inc. |
| AMETEK Inc. |
| Curtiss-Wright Corporation |
| RTX Corporation |
| Collins Aerospace |
| Siemens AG |
| Meggitt plc |
| Others |
Cost & Logistics Intelligence
Trans-Atlantic air freight corridors, critical for high-value aerospace components, significantly influence the cost dynamics of aircraft fire protection systems. This cost structure directly impacts both the supply concentration of specialized agents and the downstream price differentiation for certified solutions.
Pricing Analysis
Long-term contract-based arrangements dominate the pricing model for original equipment fire protection systems supplied to aircraft manufacturers. Price differentiation stems from the specific certification level required by agencies like FAA or EASA and the degree of system customization for unique aircraft platforms. Pricing softness reflects the intense competition among established suppliers for large OEM contracts. Commercial Airlines exhibit the highest price sensitivity, prioritizing cost-effective solutions for fleet-wide deployment, while Military Operators are less sensitive, valuing extreme performance and reliability.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities are common practices to manage the capital intensity of component manufacturing in this sector. Geographic supply concentration for critical components centers on aerospace manufacturing hubs in the United States, France, and Germany. The supply chain depends on specialized chemical agents for suppression and advanced sensor technologies for detection. Agent supply chain scalability represents a structural risk, particularly for novel, environmentally compliant agents. Distribution runs through a dual model, with direct sales to OEMs for new aircraft and MRO channels for aftermarket support and retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market for aircraft fire protection systems faces a scarcity of expertise in developing and integrating certified halon-alternative technologies. This capability gap creates both challenges and opportunities for market participants.
For Market Incumbents:Insulate core market share by accelerating investment in next-generation, GWP-compliant suppression agents and advanced multi-spectrum sensor development. Form strategic partnerships with chemical companies to secure intellectual property for novel agents, mitigating the threat from emerging specialized developers. Deepen vertical integration into critical component manufacturing, particularly for high-temperature alloys and specialized electronics, to control costs and supply. Focus R&D on predictive maintenance features to meet airline demands for increased operational efficiency.
For New Entrants and Emerging Players:Establish a beachhead in niche segments requiring specialized fire protection, such as Urban Air Mobility platforms with high-density battery risks. Target regional airlines or specific retrofit programs that seek cost-effective, certified halon alternatives for older aircraft. Develop advanced detection systems with superior false alarm immunity as a primary go-to-market angle. The cargo hold application segment presents a penetrable entry point due to evolving regulatory priorities for enhanced detection capabilities.
For Investors and Strategic Acquirers:Carve-out targets emerge from diversified aerospace conglomerates that may divest non-core fire protection system divisions lacking halon-alternative expertise. Long-term viability over a five to ten-year window will favor companies with proven certification capabilities for new agents. Look for acquisition targets specializing in advanced sensor technology or novel, low-GWP chemical suppressants. A signal to watch is the accelerated adoption of F-Gas Regulation-compliant systems across major aviation markets, indicating a clear shift in industry demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Halon-Alternative R&D | Secures future market access by developing environmentally compliant suppression agents for new aircraft programs. |
| Acquire Advanced Sensor Technology Firms | Enhances detection capabilities, reducing false alarms and improving system response times for airline operators. |
| Expand MRO Service Network in Asia-Pacific | Captures growing aftermarket revenue streams from expanding commercial fleets in key aviation hubs. |
| Form Strategic Partnerships with Chemical Suppliers | Ensures reliable supply and co-development of novel, certified extinguishing agents for global deployment. |
| Integrate Predictive Maintenance Features | Offers airlines improved operational efficiency and reduced unscheduled downtime through data-driven insights. |
Research Approach
A spread of perspectives from aerospace engineers, MRO managers, airline procurement officers, and regulatory experts converged on the working assumptions for this analysis. The methodology combined extensive primary interviews with rigorous secondary validation. Secondary data sources included FAA and EASA reports, aerospace manufacturing association publications, and chemical industry journals, providing a comprehensive market view. Bottom-up and top-down triangulation ensured data accuracy and consistency across all segments.
Demand-supply-balance principles underpinned the analytical framework to project market trends across the analysis window. The quantitative model systematically assessed segmentation dimensions, including system type, technology, application, end-user, and regional regulatory compliance. Compound Annual Growth Rates were derived from historical data analysis and projected market dynamics, factoring in new aircraft delivery schedules and halon phase-out timelines as key forecast inputs throughout the projection horizon.
Stress conditions across regulatory changes, material science breakthroughs, and economic shifts were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding current market conditions and anticipated technological advancements. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Safety Systems
Aircraft Evacuation Systems Market
Aircraft Safety Systems
Aircraft Ejection Seats Market
Aircraft Safety Systems
HUD Helmet Market
Aircraft Safety Systems
Aircraft Survival Equipment Market
Aircraft Safety Systems
Aircraft Arresting System Market
Aircraft Safety Systems
Helicopter Emergency Flotation System Market
Aircraft Safety Systems
Aircraft Docking Systems Market
Aircraft Safety Systems
Aviation Airbags Market
Aircraft Safety Systems
Aircraft Lightning Protection Market
Aircraft Safety Systems
Identification Friend or Foe Systems Market
Aircraft Safety Systems
Aerospace Lightning Strike Protection Market
Aircraft Safety Systems
Commercial Aircraft Evacuation System Market
Aircraft Safety Systems
Airborne Collision Avoidance System Market
Aircraft Safety Systems
Free Fall Sensor Market
Aircraft Safety Systems
South Korea Aircraft Windshield Wiper and Washer System Market
Aircraft Safety Systems
Aircraft Evacuation Slide Market