
 Commercial Aircraft Evacuation System Market | 2026-2036
Commercial Aircraft Evacuation System Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Aircraft Evacuation System Market Analysis
The divergence between premium and commodity tiers is hardening in the commercial aircraft evacuation system market. Collins Aerospace leverages its integrated avionics-to-safety portfolio to command higher-margin line-fit contracts with major OEMs. Safran sustains competitive positioning through captive manufacturing of pyrotechnic inflation systems. Survitec Group Limited specializes in aftermarket retrofit programs, occupying a distinct service layer beneath factory-installed equipment.
Commercial aircraft evacuation systems encompass inflatable slide-rafts, over-wing exit mechanisms, and door-mounted escape devices engineered to deploy within six seconds and support passenger loads exceeding 800 pounds per lane. These systems utilize coated fabric envelopes, pressurized gas inflators, and automatic deployment sequencers to ensure regulatory-compliant egress during ground emergencies and ditching scenarios. Slide systems dominate factory-installed revenue pools, while retrofit installation types accelerate as aging narrow-body fleets face mandatory compliance upgrades. Life rafts within the product type category generate recurring replacement demand tied to inspection intervals, contrasting with the one-time nature of escape slide procurement.
FAA Technical Standard Orders and EASA Certification Specifications CS-25 govern inflatable evacuation device performance, mandating sea-state survivability and fire-resistance benchmarks that constrain supplier entry. The EU AI Act and CSRD disclosure rules are beginning to shape supply chain documentation requirements for safety-critical aerospace components. Stakeholders must weigh certification pathway investments against the consolidation risk posed by OEMs narrowing approved vendor lists.
Market Dynamics
Fleet modernization cycles and regulatory recertification mandates are compressing procurement timelines for evacuation system suppliers. OEM line-fit contracts now demand six-year service-life guarantees that reshape supplier qualification criteria.
Growth Catalysts
- FAA Technical Standard Order updates:Revised inflation-performance benchmarks for slide-rafts mandate equipment replacement across narrow-body fleets operated by US carriers. Retrofit installation demand accelerates accordingly.
- Coated fabric envelope advances:Polyurethane-coated aramid weaves extend inspection intervals from three to five years. Airlines reduce maintenance downtime and inventory carrying costs.
- Boeing delivery schedules:Sustained narrow-body output in Washington state sustains factory-installed slide system procurement volume through 2030.
Market Restraints
- Pyrotechnic inflator supply concentration:European specialty chemical producers control gas-generator propellant formulations. Input cost volatility constrains margin flexibility for slide-raft assemblers.
- EASA CS-25 Amendment 25-143 compliance:Enhanced fire-resistance testing for evacuation devices extends certification timelines by 14-18 months. Development capital locks up longer before revenue recognition.
- Life raft substitution by slide-raft combinations:Dual-function equipment reduces standalone life raft procurement. Recurring replacement revenue pools contract for single-purpose suppliers.
Strategic Opportunities
- India fleet expansion:IndiGo and Air India narrow-body orders exceed 900 aircraft. Line-fit evacuation system contracts from Mumbai and Delhi MRO hubs represent unpenetrated procurement volume.
- EU AI Act documentation requirements:Automated deployment sequencer algorithms for smart inflation systems require traceability protocols. First-movers capture CSRD-aligned supply chain certification premiums.
- Blockchain-enabled parts provenance:Distributed ledger verification of slide-raft inspection history creates aftermarket service differentiation. Channel innovation targets lessor-owned leased fleet segments.
Industry Challenges
- Certified aerospace seamstress scarcity:Precision sewing of coated fabric envelopes requires FAA-approved personnel. Training pipelines lag replacement demand by 24-36 months.
- Legacy aircraft integration complexity:Retrofit slide systems must interface with 1980s-era door mechanisms. Engineering adaptation costs erode aftermarket contract profitability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Aircraft Evacuation System Market |
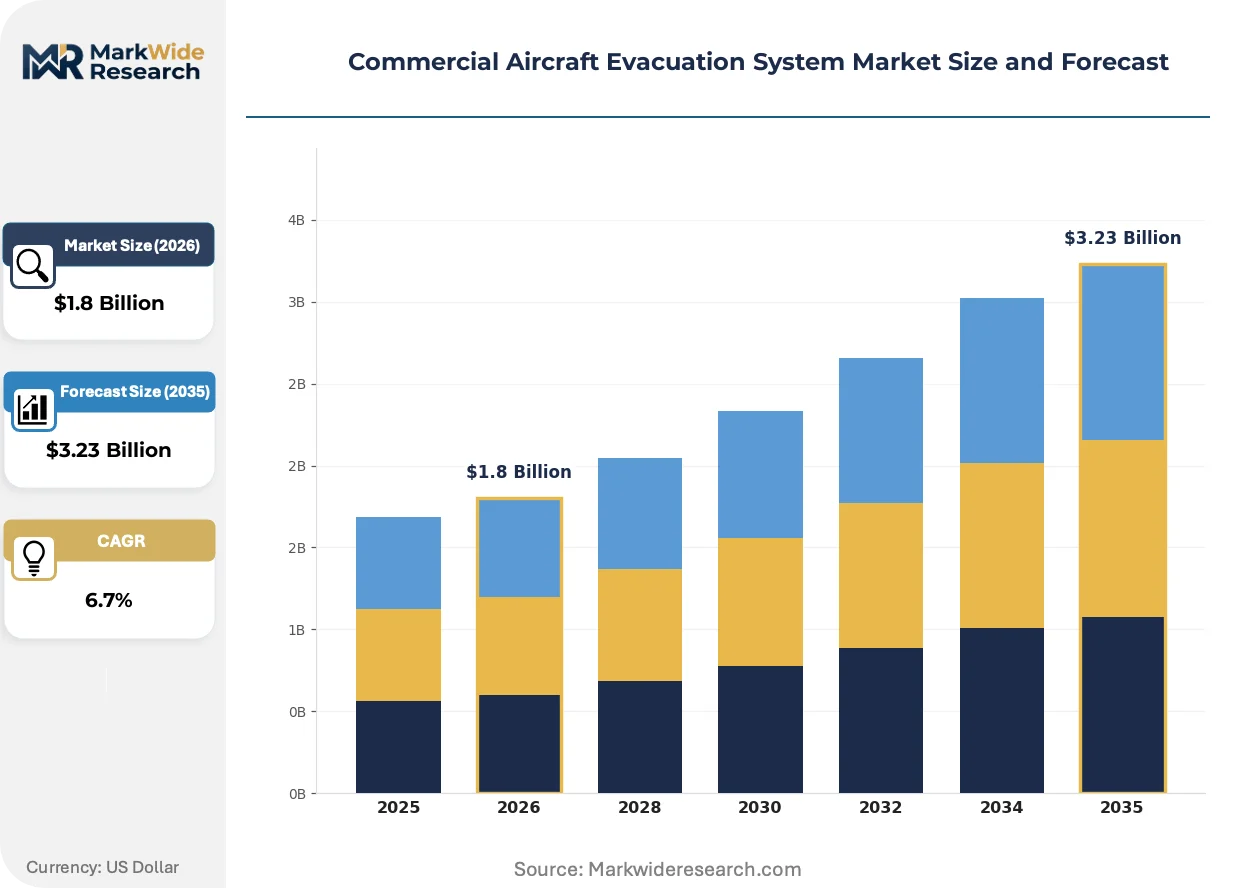
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Slide Systems, Inflatable Slides, Over-Wing Exits, Evacuation Ramps End User: Airlines, OEMs, Military, Cargo Operators Product Type: Escape Slides, Life Rafts, Door Slides, Rescue Equipment Installation Type: Retrofit, Line Fit, Modular, Fixed |
| Companies Covered | Safran, Collins Aerospace, Survitec Group Limited, Trelleborg, EAM Worldwide, Martin-Baker Aircraft, Zodiac Aerospace, GKN Aerospace, Dart Aerospace, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Aircraft Evacuation System Market Emerging Trajectories
Smart deployment technologies and predictive maintenance architectures are redefining evacuation system lifecycle economics. Suppliers now compete on data-enabled service models rather than hardware durability alone.
Sensor-integrated inflation sequencers are automating deployment-timing optimization across variable cabin pressure conditions. Airbus and Boeing now specify these systems for new wide-body programs. The technology is automating manual override protocols that previously required flight-attendant intervention, compressing training cost burdens for carriers.
EASA Certification Specifications CS-25 Amendment 25-145 introduces real-time performance telemetry requirements for ditching-scenario evacuation devices. Manufacturers must embed data-logging capabilities that transmit to regulatory repositories. Narrow-body retrofit programs face the steepest compliance cost escalation as older airframes lack embedded sensor infrastructure.
Carrier procurement departments now unbundle after-sales inspection contracts from initial equipment purchase. Lessors and third-party MRO providers capture service revenue that OEM-aligned suppliers once controlled. This behavioral shift concentrates most visibly among European low-cost carriers operating high-utilization narrow-body fleets.
Commercial Aircraft Evacuation System Market Segmentation
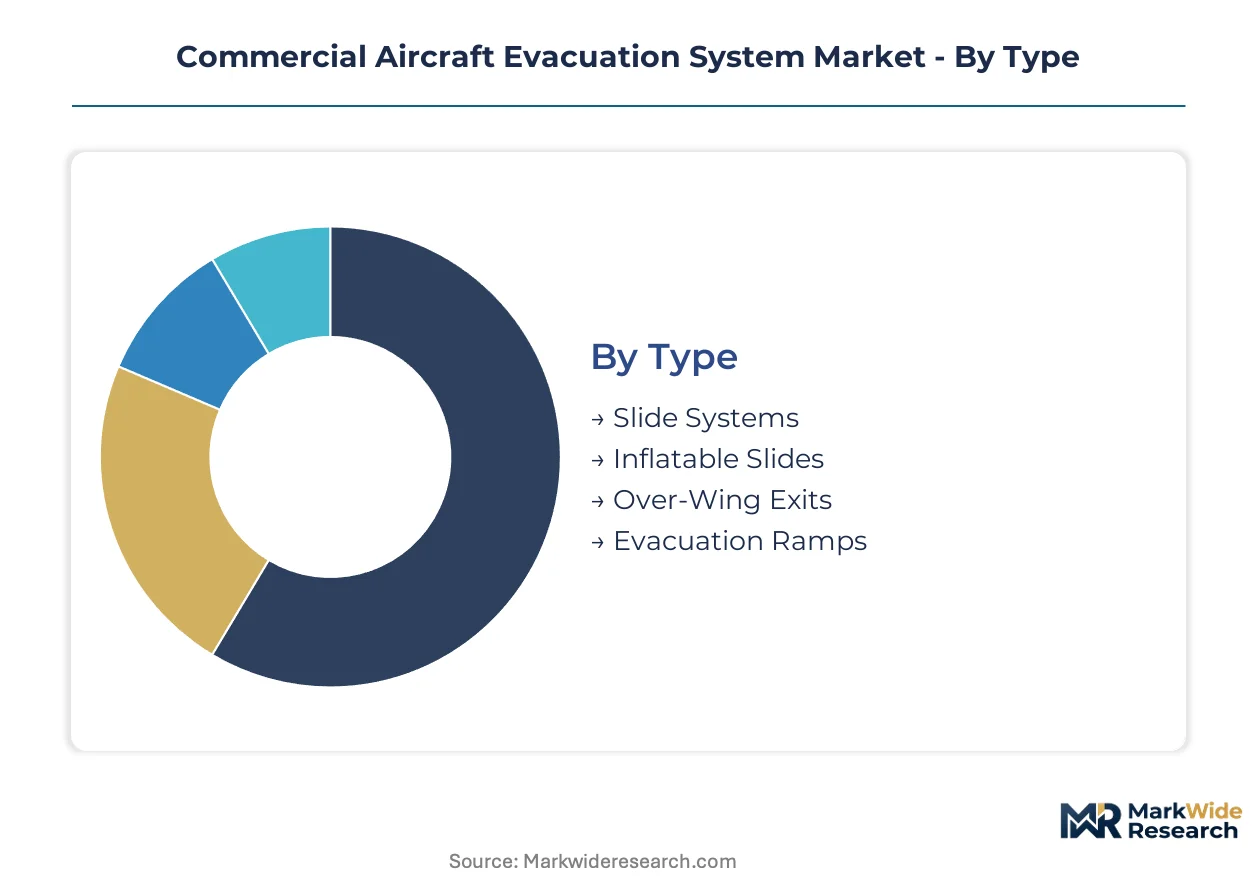
Evacuation system procurement splits across four distinct category axes, each carrying divergent certification burdens and margin profiles. Suppliers must calibrate R&D allocation against the specific FAA Technical Standard Order or EASA CS-25 pathway governing each segment's approval timeline.
Type:
Certification complexity escalates with deployment mechanism sophistication, dictating which segments require full-scale aircraft integration testing versus bench-level validation.
- Slide Systems:Coated fabric envelopes with pressurized gas inflators form the dominant factory-installed configuration. Boeing's narrow-body delivery schedules in Washington state sustain procurement volume, though six-year service-life guarantees now demanded by OEMs compress supplier margins.
- Inflatable Slides:Polyurethane-coated aramid weaves extend inspection intervals from three to five years, reducing airline maintenance downtime. Demand concentrates among US carriers retrofitting aging fleets to meet revised FAA inflation-performance benchmarks.
- Over-Wing Exits:Mechanical egress mechanisms for emergency door configurations.
- Evacuation Ramps:Deployable incline systems for ground-level aircraft exits.
Slide Systems sits at the top of the volume ranking, with Inflatable Slides climbing the fastest.
End User:
Procurement authority distribution shapes pricing power, with direct OEM relationships commanding premium positioning over aftermarket intermediaries.
- Airlines:Fleet operators drive retrofit demand through mandatory compliance upgrades and life-cycle replacement programs. European low-cost carriers increasingly unbundle after-sales inspection contracts from initial equipment purchase, shifting service revenue toward lessors and third-party MRO providers.
- OEMs:Airbus and Boeing specify sensor-integrated inflation sequencers for new wide-body programs, automating deployment-timing optimization. Line-fit contracts demand integrated avionics-to-safety portfolios that only vertically integrated suppliers can deliver.
- Military:Defense procurement channels with specialized survivability requirements.
- Cargo Operators:Freighter conversion programs generating secondary equipment demand.
OEMs capture the steepest expansion trajectory as new aircraft production rates outpace retrofit installation growth.
Product Type:
Replacement frequency divergence separates recurring revenue streams from one-time procurement events.
- Escape Slides:Door-mounted and fuselage-integrated deployment systems for passenger evacuation.
- Life Rafts:Standalone ditching-survival equipment with inspection-interval-driven replacement cycles. Dual-function slide-raft combinations are displacing single-purpose units, contracting recurring revenue pools for dedicated life raft suppliers.
- Door Slides:Integrated exit-door deployment mechanisms with automatic sequencers.
- Rescue Equipment:Supplementary survival and recovery apparatus for extended water scenarios.
Door Slides leads absolute procurement value, while Rescue Equipment gains share fastest from enhanced sea-state survivability mandates.
Installation Type:
Engineering adaptation requirements separate factory-optimized configurations from legacy airframe retrofit challenges.
- Retrofit:Aftermarket installation for aging narrow-body fleets facing FAA Technical Standard Order updates. Engineering costs to interface with 1980s-era door mechanisms erode contract profitability despite accelerating demand volume.
- Line Fit:Factory-integrated systems specified during original aircraft manufacture. EASA CS-25 Amendment 25-143 compliance extends certification timelines by 14-18 months, locking up development capital before revenue recognition.
- Modular:Interchangeable subassembly configurations for flexible fleet deployment.
- Fixed:Permanent structural integration without field-removable components.
Retrofit installation is expanding most quickly as regulatory recertification mandates compress procurement timelines across operational fleets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France concentrates evacuation system engineering around Toulouse's Airbus supply chain, whereas the United States spreads procurement across Boeing's Washington state manufacturing base and Southwest Airlines' retrofit programs in Dallas.
United States
Boeing's narrow-body delivery schedules in Washington state sustain factory-installed slide system procurement volume through 2030. FAA Technical Standard Order updates mandate equipment replacement across aging narrow-body fleets operated by US carriers. Dallas-Fort Worth serves as the operational hub for Southwest Airlines' fleet-wide retrofit programs addressing revised inflation-performance benchmarks.
France
Airbus specifies sensor-integrated inflation sequencers for new wide-body programs assembled in Toulouse. EASA Certification Specifications CS-25 Amendment 25-143 extends certification timelines for evacuation devices by 14-18 months. The Toulouse-Blagnac aerospace cluster anchors European line-fit contract engineering for A350 and A320neo programs.
United Kingdom
Survitec Group Limited specializes in aftermarket retrofit programs from its British operational base, occupying a distinct service layer beneath factory-installed equipment. EASA CS-25 Amendment 25-145 introduces real-time performance telemetry requirements that reshape compliance documentation. The South Coast region around Portsmouth hosts precision sewing operations for coated fabric envelope manufacturing.
Germany
Lufthansa Technik's MRO operations in Hamburg drive third-party inspection contract demand as European carriers unbundle after-sales service from initial equipment purchase. EU AI Act documentation requirements for automated deployment sequencer algorithms create traceability protocol premiums. The Hamburg aerospace cluster concentrates life raft inspection and recertification capacity for northern European operators.
India
IndiGo and Air India narrow-body orders exceed 900 aircraft, generating unpenetrated line-fit evacuation system contract opportunities. The country's national aviation regulator aligns certification pathways with FAA and EASA standards to accelerate foreign supplier qualification. Mumbai and Delhi MRO hubs represent emerging procurement volume for retrofit installation programs as fleet age profiles mature.
Commercial Aircraft Evacuation System Market Vendor Landscape
Top-tier vendors anchor OEM line-fit contracts, while mid-tier specialists capture aftermarket retrofit demand. The market exhibits moderate consolidation around vertically integrated safety-system portfolios and captive pyrotechnic manufacturing capabilities. Three strategic archetypes dominate: integrated avionics-to-safety suppliers, pyrotechnic inflation system specialists, and aftermarket service-focused retrofit providers. Competitive moves concentrate on six-year service-life guarantee commitments and CSRD-aligned supply chain certification premiums.
Within the integrated-system tier, Collins Aerospace and Safran exemplify divergent positioning strategies. Collins occupies the premium line-fit vector through its avionics-to-safety portfolio breadth. Safran anchors the pyrotechnic-captive manufacturing archetype with in-house gas-generator propellant formulation control. Survitec Group Limited represents the aftermarket-specialist model, focusing on retrofit program execution beneath factory-installed equipment layers. These three entities collectively illustrate how certification pathway investments and service model unbundling reshape competitive boundaries.
| Leading Market Players |
|---|
| Safran |
| Collins Aerospace |
| Survitec Group Limited |
| Trelleborg |
| EAM Worldwide |
| Martin-Baker Aircraft |
| Zodiac Aerospace |
| GKN Aerospace |
| Dart Aerospace |
| Others |
Supply Flow & Price Mechanics
FAA-certified aerospace seamstresses in the South Coast region of the United Kingdom command wage premiums that compress supplier margins on coated fabric envelope production, widening the spread between premium line-fit contracts and economy-tier retrofit installations. Labor-cost differentials between precision sewing operations in Portsmouth and automated assembly facilities in Washington state stratify pricing tiers across the evacuation system market.
Pricing Analysis
The unbundling of after-sales inspection contracts from initial equipment purchase is reshaping procurement economics. Three-tier pricing structure across premium, standard, and economy levels reflects divergent certification grades and after-sales service commitments. Cost compression in the retrofit tier is intensifying because engineering adaptation to 1980s-era door mechanisms erodes contract profitability. European low-cost carriers operating high-utilization narrow-body fleets exhibit the highest price sensitivity, while OEM line-fit buyers prioritize six-year service-life guarantees over unit cost.
Supply Chain Analysis
Pyrotechnic inflator supply rests on European specialty chemical producers controlling gas-generator propellant formulations. Raw material dependencies include polyurethane-coated aramid weaves, pressurized gas canisters, and automatic deployment sequencer electronics. Single-source vulnerability in gas-generator chemistry exposes slide-raft assemblers to input cost volatility. Distribution runs through OEM direct procurement channels for line-fit contracts and third-party MRO networks for aftermarket retrofit programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market hinges on inspection-interval extension through coated fabric envelope advances, allowing suppliers to capture premium positioning while airlines reduce maintenance downtime.
For Market Incumbents: Deploy captive manufacturing of pyrotechnic inflation systems to insulate against European specialty chemical supply concentration. Consolidate position by securing six-year service-life guarantee commitments from Airbus and Boeing for new wide-body programs, while accelerating CSRD-aligned supply chain certification to capture documentation premiums before EASA CS-25 Amendment 25-145 telemetry mandates take full effect. For New Entrants and Emerging Players: The price-point gap between premium OEM line-fit contracts and economy-tier retrofit installations represents the most penetrable white space. Target India's unpenetrated procurement volume from IndiGo and Air India narrow-body orders exceeding 900 aircraft. Establish Mumbai and Delhi MRO hub relationships to bypass entrenched OEM-aligned supplier networks. For Investors and Strategic Acquirers: Aerospace OEMs are the most active acquirer in this space, seeking to narrow approved vendor lists and secure vertically integrated safety-system portfolios. Over a multi-year horizon, target mid-tier specialists with captive pyrotechnic manufacturing capabilities and established FAA Technical Standard Order certification pathways. Watch for EASA CS-25 Amendment 25-143 compliance timeline extensions as a signal of development capital lock-up risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pyrotechnic Chemistry | Captive gas-generator production insulates Safran and Collins Aerospace from European specialty chemical supply volatility. |
| Blockchain-Enabled Parts Provenance | Distributed ledger verification creates aftermarket differentiation targeting lessor-owned leased fleet segments. |
| Sensor-Integrated Inflation Sequencer Development | Airbus and Boeing specify automated deployment-timing optimization for new wide-body programs. |
| CSRD-Aligned Supply Chain Certification | EU AI Act documentation requirements for smart inflation systems create first-mover traceability premiums. |
| India MRO Hub Partnership Expansion | Mumbai and Delhi facilities capture unpenetrated line-fit and retrofit procurement from 900-plus narrow-body orders. |
Methodological Framework
Multiple input streams — regulatory filing analysis, production database reconciliation, and procurement contract review — were reconciled to construct market estimates. Primary interviews with evacuation system engineering directors, airline fleet procurement managers, MRO operations heads, and FAA certification specialists were cross-validated against FAA Technical Standard Order databases, EASA CS-25 amendment records, and OEM delivery schedule disclosures. Bottom-up equipment unit analysis and top-down aerospace safety system market allocation were triangulated to verify segment sizing.
Historical delivery patterns were cross-referenced against expert panel input on fleet modernization timing and regulatory recertification mandates. Segmentation dimensions modeled include product type, installation type, end-user category, and geographic production cluster. CAGRs were derived from trend extrapolation adjusted for Boeing narrow-body output schedules and EASA certification timeline impacts. Industry-specific forecast inputs encompass coated fabric envelope inspection interval extensions and pyrotechnic inflator supply constraints.
Caveats apply where FAA Technical Standard Order revision timing or EASA CS-25 amendment implementation delays could materially shift the outlook. Forecasts reflect assumptions about fleet age profiles and carrier retrofit compliance behavior. A small set of triggers — pyrotechnic chemical supply disruptions, certified aerospace seamstress training pipeline bottlenecks, and OEM vendor list consolidation announcements — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Safety Systems
South Korea Aircraft Windshield Wiper and Washer System Market
Aircraft Safety Systems
Helicopter Ice Protection Systems Market
Aircraft Safety Systems
Aircraft Survival Equipment Market
Aircraft Safety Systems
Commercial Aircraft Collision Avoidance System Market
Aircraft Safety Systems
Free Fall Sensor Market
Aircraft Safety Systems
Aircraft Ejection Seats Market
Aircraft Safety Systems
Aircraft Docking Systems Market
Aircraft Safety Systems
Identification Friend or Foe Systems Market
Aircraft Safety Systems
Aviation Life Rafts Market
Aircraft Safety Systems
Global Aircraft Brakes Market
Aircraft Safety Systems
Military Airborne Collision Avoidance Systems (ACAS) Market
Aircraft Safety Systems
Aerospace Lightning Strike Protection Market
Aircraft Safety Systems
Airborne Lightning Detection System Market
Aircraft Safety Systems
HUD Helmet Market
Aircraft Safety Systems
Airborne Collision Avoidance System Market
Aircraft Safety Systems
Aircraft Lightning Protection Market