
 Aircraft Seals Market | 2026-2036
Aircraft Seals Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Seals Market Analysis
Buyer concentration among tier-one airframers and engine OEMs is consolidating, pressuring seal suppliers to absorb long-term pricing commitments while qualifying multi-platform material specifications. Parker Hannifin Corporation leverages its integrated motion and control portfolio to anchor aftermarket service contracts across commercial and military fleets. Trelleborg Sealing Solutions competes through specialized elastomer compounding capabilities that sustain temperature and pressure ratings for next-generation propulsion architectures.
Aircraft seals are precision-engineered elastomeric or metallic components designed to contain fluids, gases, and pressure differentials across operating envelopes spanning minus sixty-five to four hundred fifty degrees Fahrenheit, with Shore A hardness ratings typically between forty and ninety. Their primary purpose is maintaining system integrity in fuel, hydraulic, pneumatic, and environmental control circuits where leakage tolerance measures in drops per minute. Fluoroelastomer formulations dominate engine-adjacent applications where thermal degradation resistance commands premium positioning, while silicone compounds lead in cabin pressurization and environmental sealing where flexibility across temperature swings drives specification. Polyurethane and EPDM alternatives occupy cost-sensitive positions in landing gear and auxiliary systems where duty cycles permit less exotic material selections.
The FAA's airworthiness directives and EASA's certification standards for fire-resistant materials shape material selection and testing protocols, forcing compounders to maintain dual-qualified production lines for transatlantic program participation. EPA regulations on perfluorinated substance emissions are pressuring reformulation of legacy seal chemistries, particularly fluoroelastomer families containing long-chain perfluoroalkyl substances. Stakeholders must monitor evolving substance restrictions while building qualification buffers that prevent single-supplier dependencies in critical sealing tiers.
Market Dynamics
Airframers are consolidating supplier bases for multi-platform qualification, forcing seal compounders to absorb extended development cycles and dual-certification costs across FAA and EASA jurisdictions while maintaining fire-resistant material stocks.
Growth Catalysts
- Next-generation narrow-body ramp-ups:Boeing and Airbus production rate increases are extending seal replacement intervals, driving aftermarket volume through MRO networks in the United States and France.
- FAA airworthiness directive enforcement:Mandatory fire-resistant material upgrades in engine nacelles and auxiliary power units are accelerating specification changes for fluoroelastomer compounds.
- EPDM substitution in landing gear:Cost-sensitive auxiliary systems are adopting ethylene-propylene-diene monomer formulations, opening volume positions in regional jet and general aviation segments.
Market Restraints
- Fluoropolymer feedstock concentration:Specialty monomer supply clusters in Japan and Germany create single-source exposure for high-temperature seal grades.
- REACH perfluorinated substance restrictions:ECHA substance evaluation timelines are forcing reformulation of legacy FKM chemistries before qualification buffers mature.
- Silicone temperature-performance ceiling:Cabin pressurization seals face material limitations when operating envelopes exceed 450°F in next-generation engine bleed systems.
Strategic Opportunities
- Additive manufacturing integration:3D-printed seal geometries and topology-optimized gland designs are compressing prototype-to-qualification timelines for custom aerospace profiles.
- India MRO infrastructure buildout:The country's PLI scheme for aviation components is attracting seal distributors to establish qualification laboratories near Bangalore and Hyderabad clusters.
- EPA long-chain PFAS phase-down:Accelerated substance restrictions in the United States are creating first-mover advantage for compounders with short-chain fluoropolymer alternatives.
Industry Challenges
- Dual-qualified production line maintenance:Compounders must segregate FAA- and EASA-certified batches, complicating inventory management and lot traceability.
- Master batch color-matching precision:Shore A hardness tolerances of ±3 points require compound technicians with specialized elastomer rheology training that remains scarce.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Seals Market |
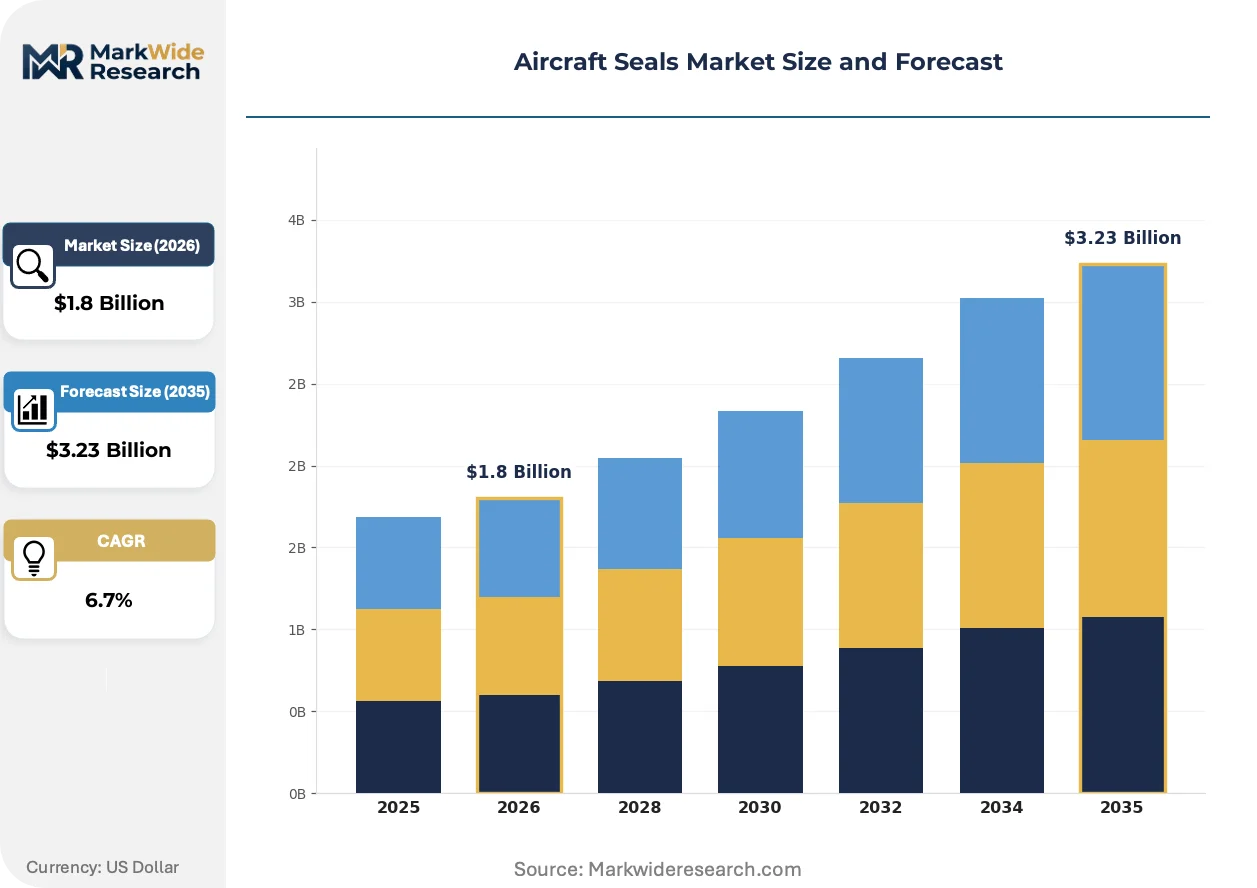
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: O-Rings, Gaskets, Shock Absorbers, Sealing Strips Material: Silicone, Fluoroelastomer, EPDM, Polyurethane End User: Commercial Aviation, Military Aircraft, General Aviation, Spacecraft Application: Fuel Sealing, Hydraulic Systems, Cabin Pressurization, Engine Components |
| Companies Covered | Parker Hannifin Corporation, Trelleborg Sealing Solutions, Saint-Gobain, SKF, Freudenberg Sealing Technologies, Hutchinson, Greene Tweed, Bal Seal Engineering, Technetics Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Seals Market Emerging Trajectories
Material science advances and regulatory chemistry restrictions are converging to reshape how seal suppliers design, qualify, and distribute elastomeric components across commercial and defense aviation programs.
Hybrid fluoro-silicone compounds are modularizing thermal management strategies in engine-adjacent sealing. These materials combine FKM chemical resistance with silicone low-temperature flexibility. Tier-one engine OEMs are adopting them for transition duct and fuel manifold applications. The technology is modularizing what were previously discrete material selection decisions into unified specification platforms.
EASA's F-Gas Regulation and EPA SNAP program restrictions on high-global-warming-potential blowing agents are forcing retooling of silicone sponge production lines. European compounders face accelerated substance substitution timelines. German and French seal manufacturers are responding by qualifying water-blown alternatives ahead of mandated phase-down dates.
Power-by-the-hour maintenance contracts are compressing seal procurement cycles and unbundling component sourcing from airframe OEM kit deliveries. Airlines operating Boeing 737 MAX and Airbus A320neo fleets are demanding direct aftermarket channel access. This pattern is most pronounced in the United States, where Delta and United have established dedicated seal inventory programs with Parker Hannifin distribution centers.
Aircraft Seals Market Segmentation
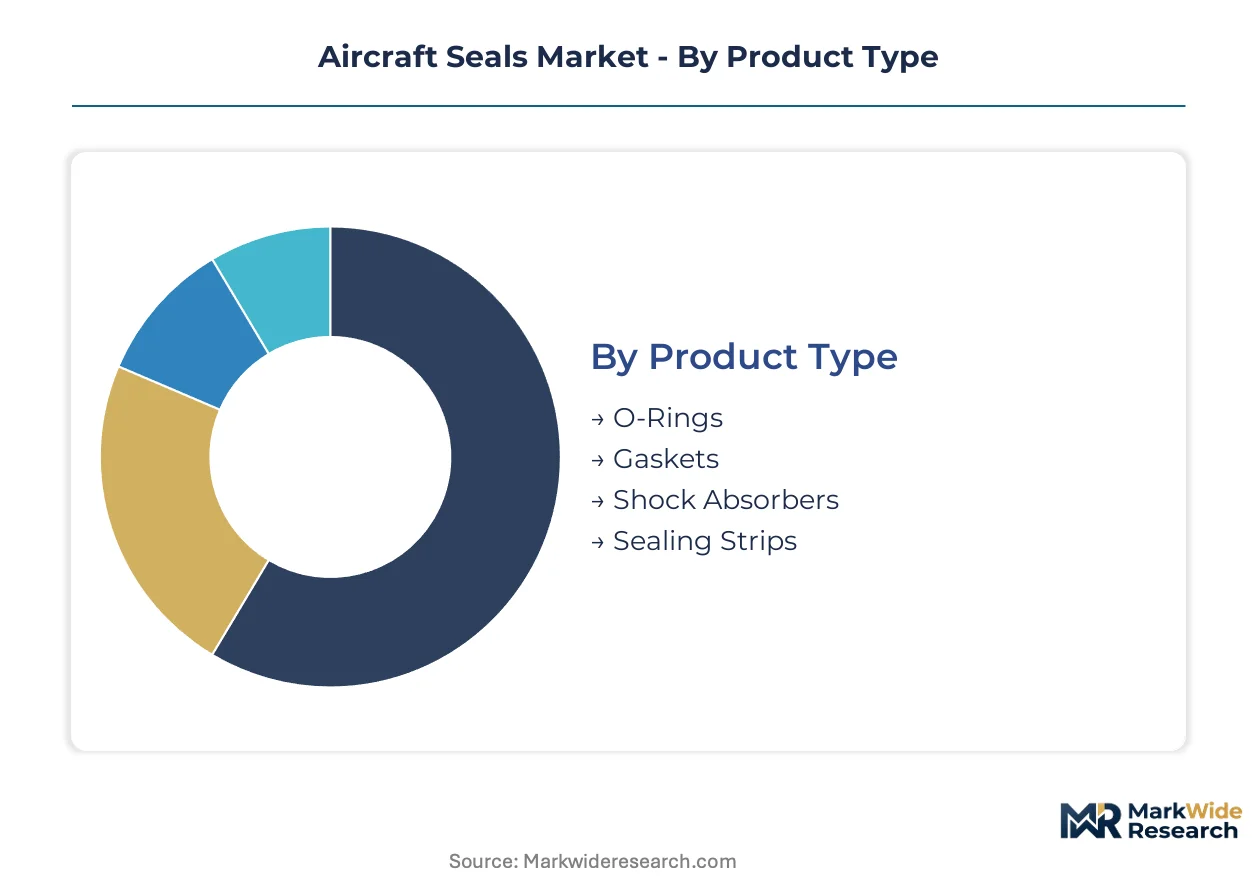
Aircraft seals serve radically different duty cycles across propulsion, fuel, and cabin systems. Specification divergence in temperature envelopes, chemical exposure, and regulatory fire-resistance ratings creates distinct procurement channels and margin profiles for each segment cluster.
Product Type:
Platform architecture and maintenance accessibility determine seal form factor selection, with engine OEMs prioritizing standardized geometries that compress MRO inventory complexity.
- O-Rings:Circular cross-section elastomeric seals installed in machined grooves to contain static and dynamic pressures. Commercial narrow-body production rates in the United States and France are concentrating demand for AMS-R-83485 qualified compounds in fuel manifold and hydraulic actuator applications.
- Gaskets:Flat-sealing elements with complex perimeter profiles mating flanged joints in engine nacelles and auxiliary power units. FAA fire-resistant material directives are accelerating specification upgrades for compressed fiber and solid elastomer variants in Boeing and Airbus engine programs.
- Shock Absorbers:Elastomeric damping elements absorbing kinetic energy in landing gear struts and control surface actuators.
- Sealing Strips:Continuous extruded profiles sealing cabin doors, cargo hatches, and avionics bays against pressure differential and moisture ingress.
O-Rings lead on scale; Gaskets lead on momentum.
Material:
Operating temperature extremes and chemical resistance requirements stratify material selection into premium thermally stable compounds versus cost-optimized alternatives for auxiliary systems.
- Silicone:Polysiloxane-based elastomers maintaining flexibility across minus sixty-five to four hundred fifty degrees Fahrenheit. Cabin pressurization systems in next-generation narrow-bodies are driving volume, though temperature ceilings constrain bleed air duct applications.
- Fluoroelastomer:Fluorocarbon polymer chains delivering hydrocarbon resistance and thermal stability exceeding four hundred degrees Fahrenheit. Engine-adjacent fuel and oil sealing in the United States commands premium positioning due to FAA fire-resistant certification requirements.
- EPDM:Ethylene-propylene-diene monomer compounds occupying cost-sensitive landing gear and environmental sealing where aromatic fuel exposure is absent.
- Polyurethane:Thermoplastic elastomers offering abrasion resistance and load-bearing capacity in hydraulic cylinder and actuator sealing.
Fluoroelastomer dominates revenue contribution; EPDM is expanding most quickly in regional jet retrofits.
End User:
Procurement concentration and qualification burden vary sharply between high-volume commercial fleets and low-volume defense programs with extended certification cycles.
- Commercial Aviation:Scheduled air carrier and cargo operators with power-by-the-hour maintenance contracts. Delta and United inventory programs with Parker Hannifin distribution centers in the United States illustrate direct aftermarket channel access trends.
- Military Aircraft:Defense procurement with MIL-PRF and MIL-STD qualification requirements extending development timelines.
- General Aviation:Business jet and piston aircraft segments with fragmented MRO networks and lower per-unit seal consumption.
- Spacecraft:Launch vehicle and satellite programs requiring ultra-high-vacuum and extreme temperature cycling resistance.
Commercial Aviation leads on scale; Military Aircraft leads on specification rigor.
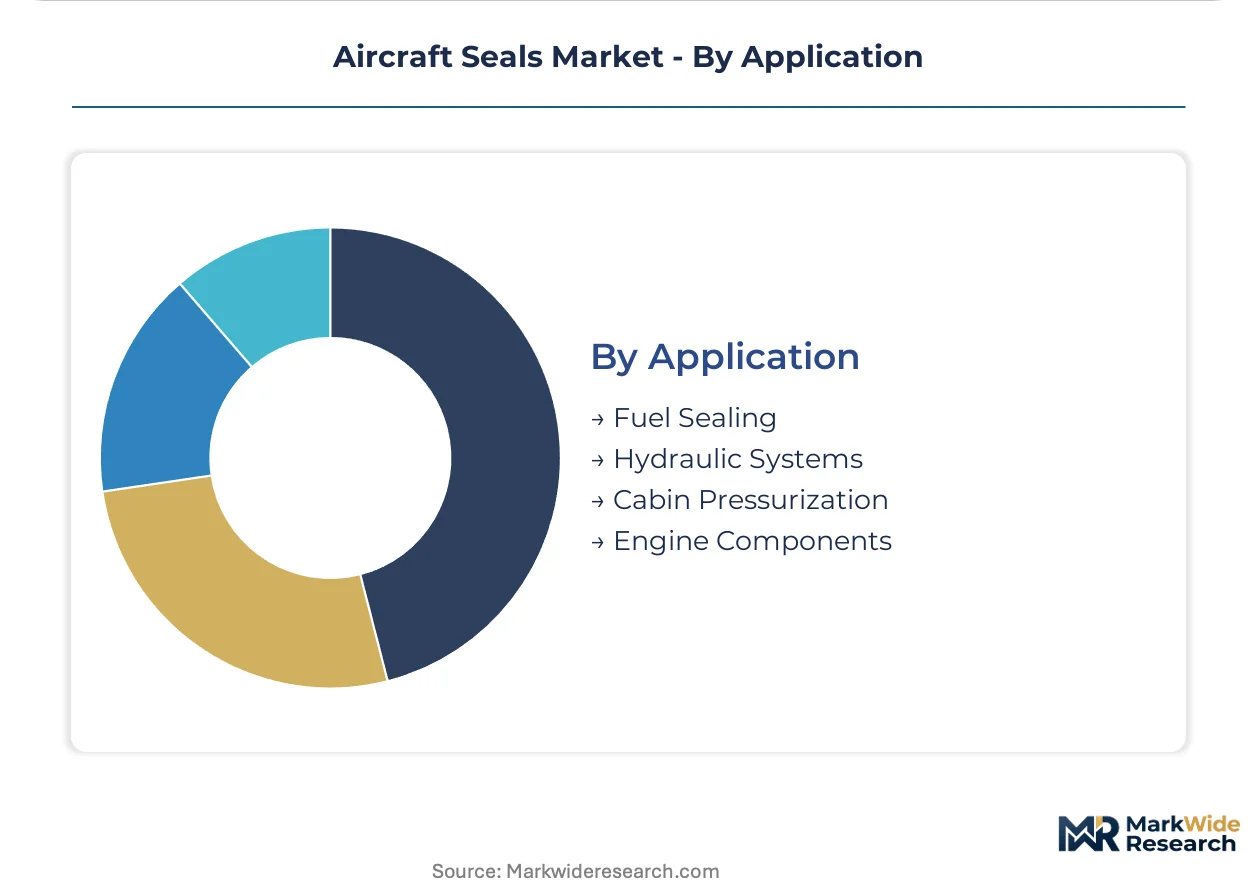
Application:
System criticality and leakage tolerance define material grade and testing protocol, with fuel and engine applications facing the most stringent fire-resistance mandates.
- Fuel Sealing:Static and dynamic seals containing jet fuel and aviation gasoline across wing tanks, engine manifolds, and refueling ports. FAA continued airworthiness directives on fire-resistant materials are forcing compound reformulation for Boeing 737 MAX and Airbus A320neo production.
- Hydraulic Systems:High-pressure seals containing phosphate ester and synthetic hydraulic fluids in flight control actuators and landing gear. Pressure ratings exceeding three thousand psi in next-generation systems are driving fluoroelastomer specification.
- Cabin Pressurization:Door seal, window seal, and environmental control system sealing maintaining altitude pressure differentials.
- Engine Components:Combustor, turbine, and transition duct sealing exposed to maximum thermal and oxidative stress.
Fuel Sealing leads on regulatory exposure; Hydraulic Systems leads on performance specification intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized elastomer compounders and precision seal fabricators concentrate near major airframer assembly sites and dense MRO networks. Talent pools in polymer chemistry and aerospace qualification engineering anchor regional production capacity.
United States
Boeing's final assembly lines in Washington and South Carolina sustain demand for AMS-R-83485 qualified O-rings and fire-resistant gasket materials. FAA continued airworthiness directives on engine nacelle sealing accelerate specification upgrades across the supply base. Parker Hannifin distribution centers in Atlanta and Dallas serve Delta and United inventory programs under power-by-the-hour contracts.
France
Airbus final assembly in Toulouse and engine OEM sourcing from Safran drive consumption of high-temperature fluoroelastomer compounds. EASA certification standards for fire-resistant materials require dual-qualified production lines serving transatlantic programs. Lyon and Grenoble host specialized compounders supplying silicone sealing strips for cabin pressurization systems on A320neo and A350 platforms.
Germany
MTU Aero Engines and Liebherr-Aerospace procurement sustain demand for hydraulic system seals rated above three thousand psi. ECHA substance evaluation timelines under REACH force reformulation of legacy FKM chemistries before qualification buffers mature. Stuttgart and Munich clusters concentrate precision molding capabilities for next-generation propulsion architectures.
United Kingdom
Rolls-Royce engine programs and narrow-body retrofit demand drive aftermarket volume for fuel manifold sealing. The country's national aerospace regulator enforces fire-resistant material standards aligned with EASA frameworks. Derby and Bristol house compounders specializing in hybrid fluoro-silicone compounds for transition duct applications.
India
IndiGo and Air India fleet expansion create MRO demand for EPDM landing gear seals and cost-optimized auxiliary system components. The PLI scheme for aviation components attracts seal distributors to establish qualification laboratories near Bangalore and Hyderabad. Delhi-Mumbai industrial corridors concentrate regional distributors serving general aviation and regional jet segments.
Aircraft Seals Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across material formulation, qualification engineering, and aftermarket distribution channels. Market structure tiers around integrated motion-control portfolios, specialized elastomer compounding capabilities, and precision fabrication for engine-adjacent applications. Three archetypes dominate: diversified industrials with aerospace divisions, pure-play sealing specialists with proprietary compound libraries, and precision fabricators serving single-platform qualification requirements. Capacity expansion in India and strategic partnerships for additive manufacturing qualification represent dominant competitive vectors.
Within the diversified industrial tier, Parker Hannifin Corporation anchors aftermarket service contract penetration across commercial and military fleets. Trelleborg Sealing Solutions occupies a position exemplifying specialized elastomer compounding capabilities for temperature and pressure-rated applications. Saint-Gobain represents the materials science conglomerate archetype with cross-industrial polymer expertise applied to aerospace qualification requirements.
| Leading Market Players |
|---|
| Parker Hannifin Corporation |
| Trelleborg Sealing Solutions |
| Saint-Gobain |
| SKF |
| Freudenberg Sealing Technologies |
| Hutchinson |
| Greene Tweed |
| Bal Seal Engineering |
| Technetics Group |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap compounders in Germany and Japan anchor specialty fluoroelastomer production, translating concentrated technical expertise into pricing discipline that resists commoditization pressure from tier-one airframer procurement consolidation.
Pricing Analysis
The bundled-versus-unbundled service split separates airframe OEM kit deliveries from direct aftermarket channel contracts. Three-tier pricing structure across AMS-qualified premium compounds, dual-certified standard grades, and cost-optimized EPDM alternatives stratifies buyer segments. Cost compression in regional jet auxiliary systems intensifies because IndiGo and Air India procurement teams negotiate EPDM landing gear seals on spot-market terms. General aviation operators exhibit highest price sensitivity; engine OEMs running power-by-the-hour contracts with Parker Hannifin distribution centers show lowest.
Supply Chain Analysis
Dual-sourcing requirements mandated by Boeing and Airbus procurement protocols force compounders to maintain parallel qualified production lines across FAA and EASA jurisdictions. Specialty monomer feedstock clusters in Japan and Germany create geographic supply concentration for high-temperature FKM grades. Raw material dependencies center on fluoropolymer resin, silicone base polymer, and peroxide curing agents. Single-source vulnerability runs through Japanese monomer producers serving next-generation propulsion architectures. Distribution runs through tier-one distributor networks anchored near final assembly sites in Washington, Toulouse, and Bangalore.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Aircraft Seals Market functions as a geographic-arbitrage play where ECHA substance evaluation timelines under REACH force faster reformulation cycles in Europe than EPA phase-down schedules in the United States, creating qualification cost differentials.
For Market Incumbents: Deploy additive manufacturing qualification investments to compress prototype-to-production timelines for custom aerospace profiles. Consolidate backward integration into specialty monomer supply to offset Japanese feedstock concentration risk. Counter emerging pure-play specialists by locking multi-platform material specifications through exclusive airframer development contracts.
For New Entrants and Emerging Players: EPA long-chain PFAS phase-down in the United States opens a window for short-chain fluoropolymer alternatives before qualification buffers mature. Target IndiGo and Air India fleet expansion in India for EPDM landing gear seals where PLI scheme subsidies offset initial certification burden. Pursue direct qualification laboratory partnerships near Bangalore MRO clusters as go-to-market anchor.
For Investors and Strategic Acquirers: Valuations sit cheapest among precision fabricators serving single-platform military qualification requirements with extended development timelines. Five-to-ten year viability hinges on compound libraries surviving regulatory chemistry restrictions. Signal to watch: EASA-FAA regulatory divergence on fire-resistant material testing protocols forcing dual-certification cost spikes.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Certification Capacity Expansion | Parallel FAA-EASA qualified production lines secure Boeing and Airbus multi-platform contracts. |
| Short-Chain Fluoropolymer Reformulation | EPA PFAS phase-down creates first-mover positioning for alternative FKM chemistries. |
| India Qualification Laboratory Buildout | PLI scheme subsidies attract seal distributors to Bangalore and Hyderabad MRO corridors. |
| Additive Manufacturing Integration | 3D-printed seal geometries compress prototype timelines for next-generation propulsion architectures. |
| Power-by-the-Hour Contract Anchoring | Direct aftermarket channel access with Delta and United locks out distributor competition. |
Methodological Framework
Direct dialogue with seal compounder R&D directors, airframer procurement managers, MRO inventory planners, and FAA certification engineers grounded qualitative findings in operational reality. Secondary validation drew from FAA airworthiness directive filings, EASA certification databases, SEC 10-K disclosures from diversified industrials, and customs trade data on fluoropolymer resin imports. Bottom-up and top-down triangulation cross-checked segment-level volume assumptions against aggregate market sizing.
Bottom-up modeling built from platform-level seal content per aircraft multiplied by production rate forecasts across the analysis window. Segmentation dimensions included material chemistry, product form factor, application system criticality, and end-user procurement concentration. CAGRs derived from fitted growth curves applied to baseline replacement cycle data and fleet expansion projections. Industry-specific inputs incorporated next-generation narrow-body ramp schedules and regulatory chemistry restriction phase-down timelines.
Revisions become necessary when FAA-EASA regulatory divergence on fire-resistant material testing protocols materializes or when Japanese monomer supply disruptions extend qualification buffers. Deviation in EPA PFAS phase-down enforcement velocity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Amphibious Aircraft Market
Aircraft
Australia Aviation Market
Aircraft
Turboprop Aircraft Market
Aircraft
Wind Tunnel Market
Aircraft
Aircraft Fairings Market
Aircraft
Air Speed Indicator Market
Aircraft
Global Commercial Aircraft Disassembly Market
Aircraft
Aircraft Jack Market
Aircraft
Strategic Bomber Market
Aircraft
Medium and Heavy-Lift Helicopters Market
Aircraft
Middle-East and Africa Freighter Aircraft Market
Aircraft
Flap Track Fairing Drag Reduction Upgrade Kits Market
Aircraft
Aircraft Windshield Wiper and Washer System Market
Aircraft
Southeast Asia Business Jet Market
Aircraft
Europe Helicopters Market
Aircraft
Two-Seater Ultralight Helicopters Market