
 Aviation High Speed Motor Market | 2026-2036
Aviation High Speed Motor Market Size, Share, and Industry Trends Forecast 2026-2036
Aviation High Speed Motor Market Analysis
OEM-direct procurement channels is reshaping how aviation high speed motors reach integrators, with tier-one aerospace suppliers consolidating vendor lists to reduce qualification overhead. Safran Electrical & Power leverages its integrated powertrain portfolio to control supply relationships across European and North American airframers. Honeywell International anchors its position through sustained R&D investment in electromechanical systems for hybrid-electric propulsion architectures. MagNiX specializes in high-torque-density designs that compete directly with conventional turbine-based auxiliary power systems.
Aviation high speed motors are electromechanical devices engineered to operate above ten thousand revolutions per minute, typically employing permanent magnet or switched reluctance topologies with liquid cooling circuits to manage thermal loads in confined nacelle spaces. Their primary function is converting electrical energy into mechanical shaft power for propulsion, actuation, or generation in airborne platforms where weight and volumetric efficiency are critical constraints. Brushless DC motor variants occupy the dominant share of current installations due to established manufacturing processes and controller compatibility, though switched reluctance architectures are gaining traction for fault-tolerant military applications where magnet supply security matters. The 100-200 kW power rating band represents the fastest-expanding segment, driven by regional hybrid-electric commuter aircraft programs that require motors sized between auxiliary units and full propulsion systems.
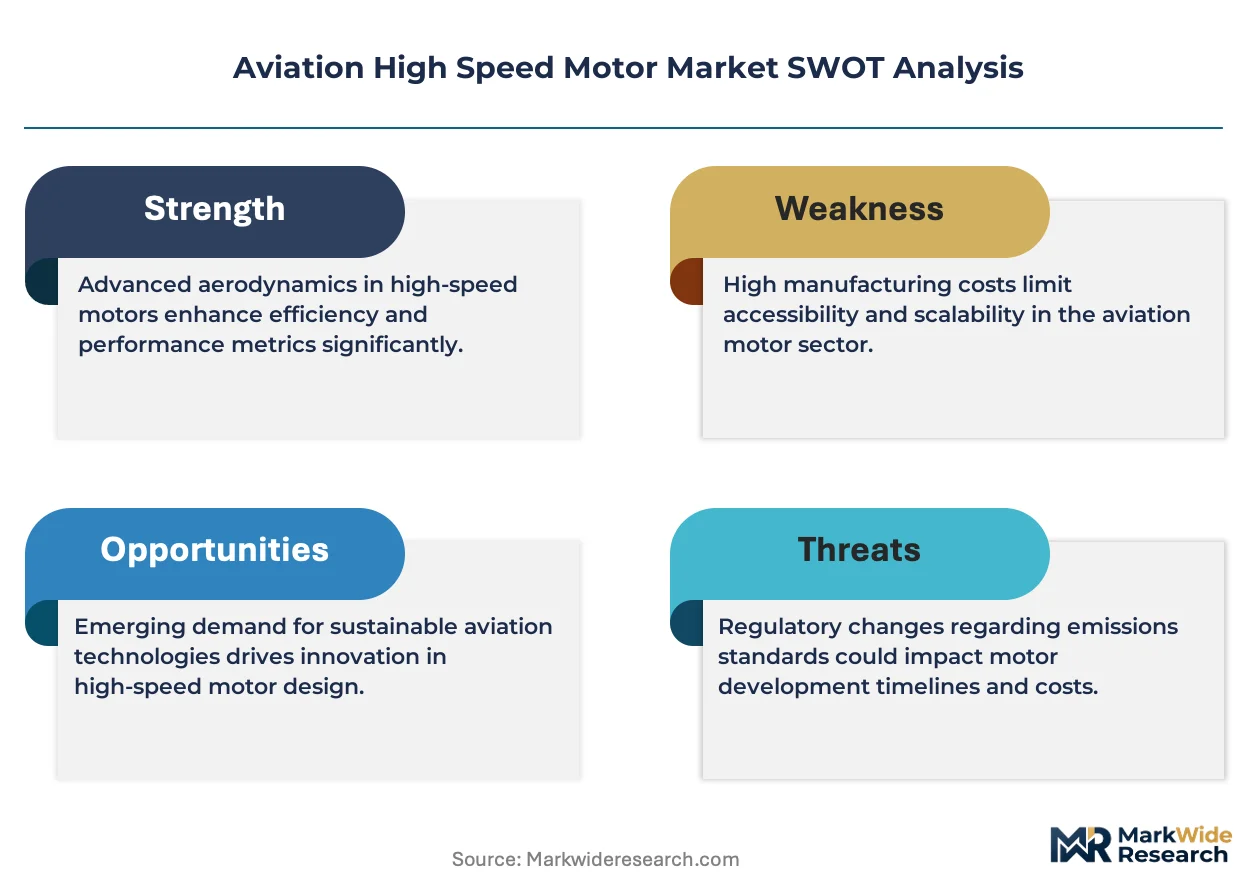
FAA Part 33 airworthiness standards and EASA CS-E certification requirements jointly dictate motor efficiency, containment, and electromagnetic interference thresholds that manufacturers must satisfy before production approval. The EU Green Deal's Fit for 55 framework and the US Inflation Reduction Act's sustainable aviation fuel and electrification tax credits are accelerating airframe OEM commitments to electric and hybrid propulsion platforms. Stakeholders must monitor evolving certification harmonization between FAA and EASA for electric propulsion units, as divergent timelines could fragment market access and strand development investments.
Market Dynamics
Permanent magnet supply security is forcing motor designers toward rare-earth-free topologies as China controls magnet refining capacity and Western defense procurement rules tighten material provenance requirements.
Growth Catalysts
- EU Green Deal Fit for 55:Binding emissions targets for aviation are compelling regional airframers to electrify short-haul routes, creating certified demand for high-speed motor integration.
- Switched reluctance motor advancement:Fault-tolerant architectures without permanent magnets are penetrating military rotorcraft where magnet supply disruption poses operational risk.
- Urban air mobility:eVTOL platform development in the United States is consuming 100-200 kW class motors for distributed electric propulsion configurations.
Market Restraints
- Copper and silicon steel price volatility:Raw material input costs for stator laminations and windings fluctuate with energy-intensive smelting economics, compressing contract manufacturing margins.
- Single-source magnet dependency:Neodymium-dysprosium supply concentrates in Chinese processing facilities, exposing Western motor producers to export restriction risk.
- Thermal management ceiling:Liquid cooling circuit density limits power-to-weight ratios below turbine benchmarks for long-haul applications.
Strategic Opportunities
- India domestic aviation expansion:UDAN regional connectivity schemes are stimulating demand for sub-19 seat hybrid-electric aircraft requiring compact propulsion motors.
- US Inflation Reduction Act electrification credits:Tax incentives for sustainable aviation technology are lowering effective R&D costs for motor-airframe integration programs.
- Additive manufacturing convergence:Topology-optimized stator housings produced through laser powder bed fusion are reducing part count and assembly labor.
Industry Challenges
- FAA Part 33 certification timelines:Novel electric propulsion architectures lack established compliance precedent, extending validation cycles beyond program schedules.
- Multiphysics simulation talent scarcity:Electromagnetic-thermal-structural co-design expertise resides in a limited pool of specialized engineers concentrated in aerospace hubs.
- Legacy airframe electrical architecture incompatibility:Retrofit motor integration demands complete power distribution redesigns incompatible with aging voltage standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aviation High Speed Motor Market |
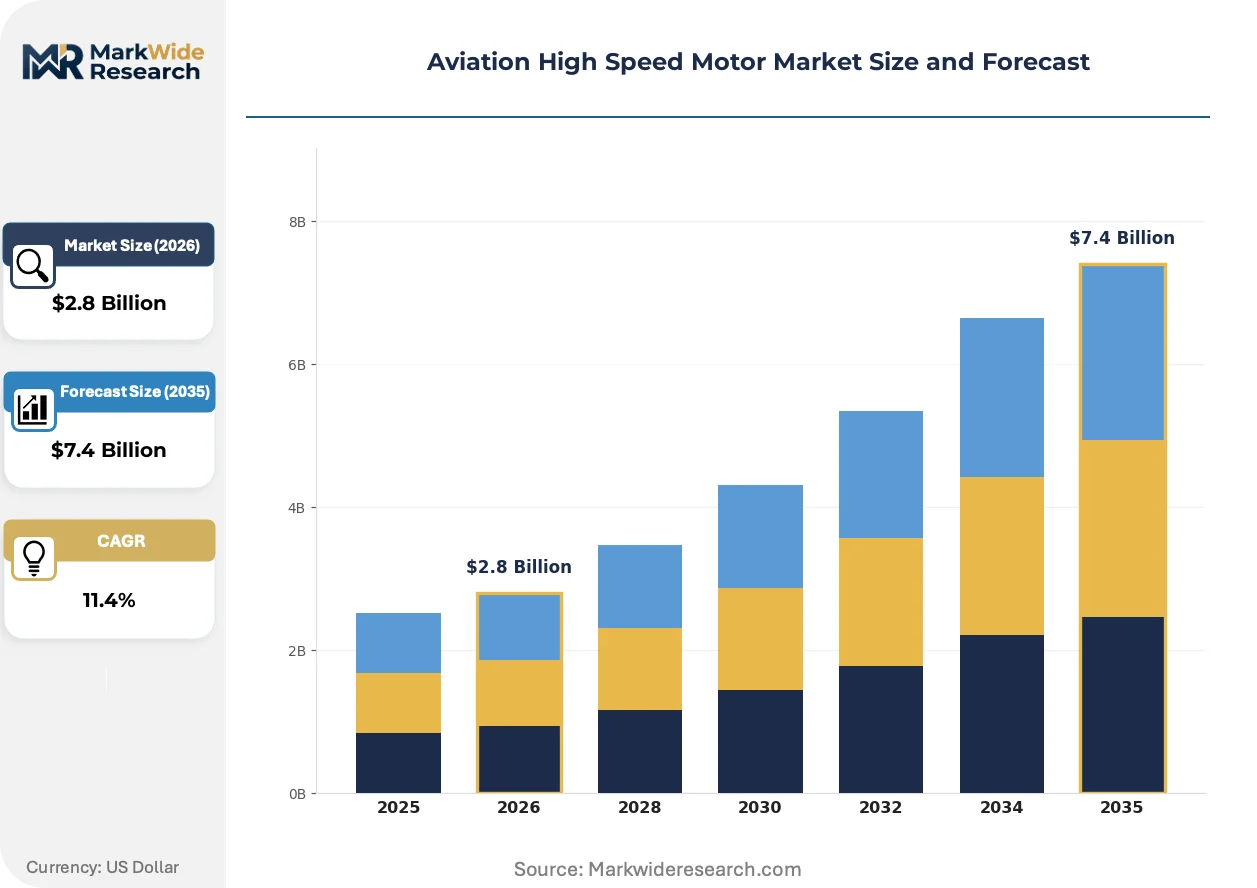
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Motor Type: Brushless DC, Switched Reluctance, Synchronous, Asynchronous End User: Commercial Aviation, Military Aircraft, Unmanned Aerial Vehicles, Spacecraft Power Rating: 10-50 kW, 50-100 kW, 100-200 kW, 200+ kW Application: Propulsion Systems, Auxiliary Power Units, Unmanned Systems, Avionics |
| Companies Covered | Safran Electrical & Power, Honeywell International, MagNiX, H3X Technologies Inc., Emrax d.o.o., MGM COMPRO, Windings Inc., ARC Systems Inc., Allied Motion Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aviation High Speed Motor Market Emerging Trajectories
Motor topology selection is diverging between commercial and defense procurement tracks as material security concerns override pure performance optimization in dual-use applications.
Axial-flux permanent magnet machines are hybridizing conventional radial motor architectures with pancake geometries that halve axial length for nacelle-constrained installations. Regional commuter OEMs in France and Germany are qualifying these designs for 2027 service entry. The topology is compressing motor volume without sacrificing torque density, enabling wing-embedded propulsion.
EASA CS-E electric propulsion certification amendments are mandating electromagnetic interference containment and fault-current isolation that exceed prior aerospace electrical standards. Motor manufacturers must redesign shielding and filtering subsystems. The 100-200 kW segment is absorbing the largest compliance cost increases as these units power passenger-carrying platforms.
Airframers are consolidating vendor relationships around integrated powertrain suppliers capable of delivering motor-inverter-thermal packages under single qualification. Tier-one aerospace suppliers in the United States and United Kingdom are absorbing specialist motor houses to capture this specification authority. The channel shift is marginalizing standalone motor producers lacking controller or cooling system capabilities.
Aviation High Speed Motor Market Segmentation
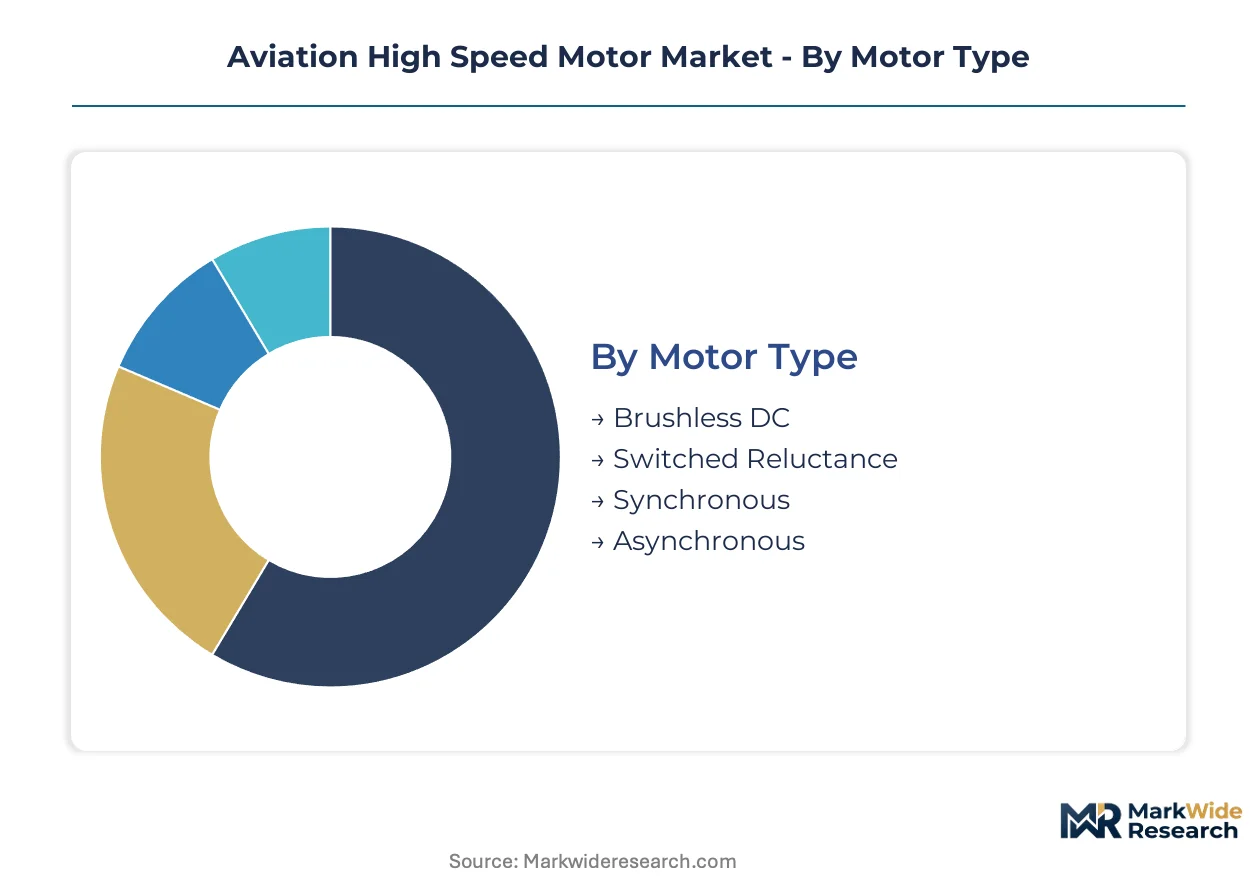
Aviation high speed motor procurement patterns diverge sharply across motor topology, end-use platform, and power class. Certification requirements and thermal constraints create distinct competitive dynamics within each segment cluster.
Motor Type:
Brushless DC motors turn inventory fastest due to established controller ecosystems and airframer familiarity, while switched reluctance designs face extended qualification cycles for magnet-free verification.
- Brushless DC:Permanent magnet rotor designs with silicon steel stator laminations achieve power densities exceeding 5 kW/kg in liquid-cooled configurations. Commercial aviation propulsion systems in France and Germany source these motors for 2027 regional commuter entries, constrained by neodymium supply concentration in Chinese processing facilities.
- Switched Reluctance:Magnet-free topologies employ salient-pole rotors and concentrated windings for fault-tolerant operation. Military rotorcraft programs in the United States specify these architectures where magnet supply disruption poses operational readiness risk, trading efficiency for material security.
- Synchronous:Wound-field or permanent magnet variants serve high-precision avionics actuation with tight speed regulation.
- Asynchronous:Induction motor designs persist in legacy auxiliary power applications where weight tolerance permits lower power density.
Brushless DC dominates installed base. Switched reluctance is where expansion concentrates as defense procurement rules tighten material provenance requirements.
End User:
Platform certification tiers create cost stratification, with manned commercial programs absorbing premium qualification overhead and unmanned systems operating under expedited pathways.
- Commercial Aviation:FAA Part 33 and EASA CS-E certification mandates govern propulsion motor approval for passenger-carrying aircraft. Regional hybrid-electric commuter programs in the United States and European Union absorb the largest compliance investment, driven by EU Green Deal emissions binding targets.
- Military Aircraft:MIL-STD-810 environmental testing and DO-178C software assurance apply to mission-critical propulsion. Fault-tolerant switched reluctance motors are gaining specification share in United States Army Future Vertical Lift initiatives where electromagnetic survivability matters.
- Unmanned Aerial Vehicles:Expedited FAA Part 107 and military waiver pathways accelerate motor qualification for tactical platforms.
- Spacecraft:Vacuum-rated thermal management and radiation-hardened electronics impose specialized design requirements for satellite reaction wheels and gimbal drives.
Commercial aviation commands qualification expenditure. Military aircraft is where technology diversification accelerates fastest.
Power Rating:
Volume concentration sits in mid-range bands where production scale meets application breadth, while extremes serve niche performance requirements.
- 100-200 kW:Liquid-cooled permanent magnet machines in this band power distributed electric propulsion for urban air mobility platforms. eVTOL developers in the United States consume production slots from specialist motor houses as FAA certification pathways mature.
- 10-50 kW:Compact brushless DC units serve unmanned systems and auxiliary actuation with minimal thermal overhead.
- 50-100 kW:Intermediate ratings bridge auxiliary power and primary propulsion for sub-regional aircraft.
- 200+ kW:High-output synchronous machines target full-electric commuter aircraft and hybrid-electric turboprop replacements.
100-200 kW carries the steepest expansion trajectory. 10-50 kW maintains volume leadership in unit shipments.
Application:
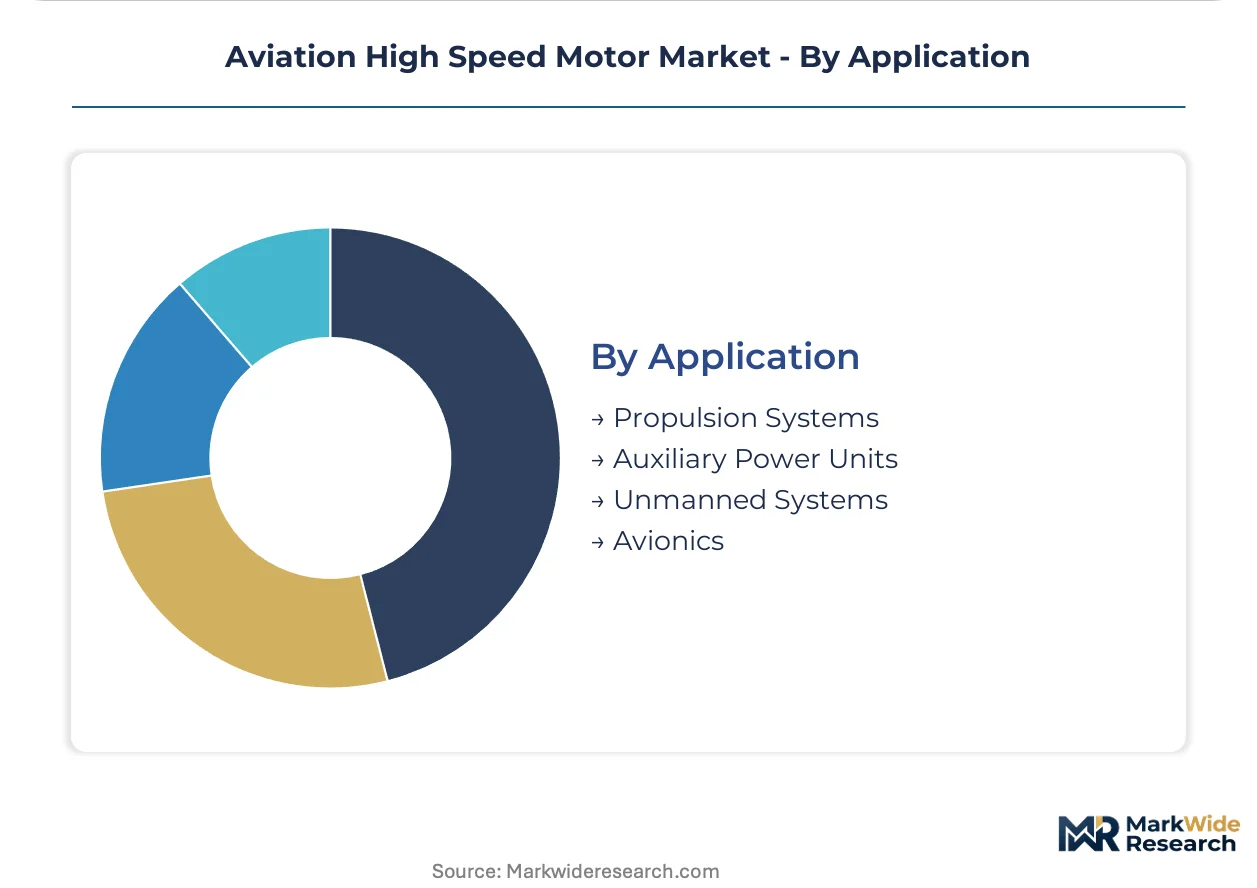
Propulsion system integration demands the deepest airframer collaboration, while auxiliary units permit standalone procurement.
- Propulsion Systems:Primary electric motors for thrust generation require nacelle-integrated thermal management and electromagnetic interference containment. Wing-embedded axial-flux designs from French and German OEMs compress axial length for boundary-layer ingestion configurations.
- Auxiliary Power Units:Turbine-replacement electric generators supply aircraft electrical loads on ground and emergency power in flight. MagNiX high-torque-density designs compete directly with conventional auxiliary turbines in United States regional fleet retrofits.
- Unmanned Systems:Distributed propulsion arrays for tactical drones prioritize power-to-weight over efficiency optimization.
- Avionics:Precision actuation motors for flight control surfaces demand fault-tolerant encoder feedback and rapid transient response.
Propulsion systems absorb development investment. Auxiliary power units is where fleet retrofit demand concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in United States procurement channels where NASA and Department of Energy joint funding commands premium qualification standards, while European manufacturers absorb compliance cost premiums under EASA CS-E amendments without equivalent pricing leverage.
United States
Urban air mobility platforms and eVTOL developers in California and Texas drive 100-200 kW motor consumption. FAA Part 33 certification pathways tighten performance verification standards for electric propulsion units. NASA Glenn Research Center in Ohio hosts high-speed motor research programs advancing boundary-layer ingestion configurations.
Germany
Regional hybrid-electric commuter aircraft programs in Bavaria and Baden-Württemberg qualify axial-flux permanent magnet designs for 2027 service entry. EU Green Deal Fit for 55 binding emissions targets compel short-haul route electrification. Munich-area OEMs integrate wing-embedded propulsion systems with compressed axial length.
France
Safran Electrical & Power anchors integrated powertrain supply relationships across European and North American airframers. EASA CS-E electric propulsion certification amendments mandate electromagnetic interference containment exceeding prior aerospace standards. Toulouse aerospace cluster concentrates motor-airframe integration programs.
United Kingdom
Tier-one aerospace suppliers absorb specialist motor houses to capture specification authority for motor-inverter-thermal packages. UK Ministry of Defence procurement rules tighten material provenance requirements for rare-earth components. Midlands aerospace corridor hosts electromechanical systems development for hybrid-electric architectures.
India
UDAN regional connectivity schemes stimulate demand for sub-19 seat hybrid-electric aircraft requiring compact propulsion motors. BIS certification alignment with EASA standards accelerates qualification pathways for imported motor technologies. Bangalore and Hyderabad clusters concentrate unmanned aerial vehicle motor integration for tactical platforms.
Aviation High Speed Motor Market Vendor Landscape
Integrated powertrain suppliers and standalone motor specialists split the market along qualification capability lines. Consolidation pressures favor vendors delivering complete motor-inverter-thermal packages under single qualification cycles. Three archetypes dominate: aerospace conglomerates with captive electromechanical divisions, specialist high-speed motor houses with topology-optimized designs, and tier-one suppliers absorbing upstream capability. Dominant competitive moves include vertical integration of controller and cooling system capabilities, plus geographic expansion through EASA-FAA dual qualification investments.
Among aerospace-integrated conglomerates, Safran Electrical & Power and Honeywell International exemplify the powertrain-integrated archetype controlling supply relationships across multiple airframer accounts. MagNiX occupies a specialist position within the high-torque-density segment, representing standalone motor houses competing directly with conventional turbine-based auxiliary power systems. These three anchors illustrate the competitive tension between breadth and depth strategies.
| Leading Market Players |
|---|
| Safran Electrical & Power |
| Honeywell International |
| MagNiX |
| H3X Technologies Inc. |
| Emrax d.o.o. |
| MGM COMPRO |
| Windings Inc. |
| ARC Systems Inc. |
| Allied Motion Technologies |
| Others |
Supply Flow & Price Mechanics
Chinese neodymium-dysprosium processing concentration funnels margin capture toward magnet-dependent motor tiers while rare-earth-free alternatives command configuration premiums. OEM-direct procurement channels compress distributor markups as tier-one aerospace suppliers consolidate vendor lists.
Pricing Analysis
Configured-to-order axial-flux designs for wing-embedded propulsion carry 40-60% premiums over standard radial configurations due to topology-optimized stator housings and nacelle-integrated thermal management. FAA Part 33 certification tier and EASA CS-E electromagnetic containment grade drive price differentiation alongside volume scale and after-sales service bundling. Cost compression in the 10-50 kW auxiliary segment intensifies because copper and silicon steel price volatility erodes contract manufacturing margins. Unmanned aerial vehicle integrators exhibit highest price sensitivity; commercial aviation propulsion programs absorb premium qualification overhead with lowest sensitivity.
Supply Chain Analysis
Tariff exposure between China and Western defense procurement jurisdictions dominates supply chain risk planning for permanent magnet-dependent producers. Manufacturing concentrates in China, Germany, and the United States, with stator laminations drawing from Japanese silicon steel mills and copper windings sourcing from Chilean smelters. Single-source magnet vulnerability rests on Chinese export restriction risk rather than extraction scarcity. Distribution runs through OEM-direct channels with tier-one aerospace suppliers controlling specification authority for motor-inverter-thermal packages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aviation high speed motor revenue pools increasingly attach to thermal management retrofit contracts and field service agreements expanding faster than hardware unit shipments. Predictive maintenance subscriptions for liquid-cooled permanent magnet systems represent the fastest-recurring layer.
For Market Incumbents: Entrench specification authority by absorbing controller and cooling system capabilities before standalone motor houses capture integrated powertrain contracts. Magnet supply disruption poses the central threat; backward integration into rare-earth-free topology R&D or captive magnet recycling programs provides defensive leverage. Certification investment in dual FAA-EASA qualification pathways locks out emerging competitors lacking validation capital. For New Entrants and Emerging Players: Build out additive manufacturing competence for topology-optimized stator housings serving India's UDAN regional connectivity schemes where BIS-EASA alignment accelerates import qualification. The 50-100 kW auxiliary-to-primary bridge segment offers most penetrable white space with lower FAA Part 33 compliance overhead than passenger-carrying propulsion. Target unmanned aerial vehicle tactical platforms through expedited military waiver pathways rather than commercial certification queues. For Investors and Strategic Acquirers: Capital is best deployed toward specialist motor houses with axial-flux topology libraries and existing EASA CS-E pre-qualification data packages. Five-to-ten year viability hinges on rare-earth-free design portfolios resilient to Western defense procurement rule tightening. The signal to watch is FAA-EASA certification harmonization timeline convergence; divergence would strand dual-qualification investments and favor regionally focused acquisition targets.| Strategic Initiative | Industry Significance |
|---|---|
| Topology-Optimized Additive Manufacturing | Laser powder bed fusion of stator housings reduces part count for French and German OEM axial-flux programs. |
| Dual FAA-EASA Qualification Investment | Single certification cycles for electric propulsion units prevent market access fragmentation for United States and European Union airframers. |
| Rare-Earth-Free Motor Architecture Development | Switched reluctance designs satisfy United States Army Future Vertical Lift material security requirements without magnet supply exposure. |
| Thermal Management System Integration | Nacelle-embedded liquid cooling packages capture specification authority from standalone motor producers lacking inverter capabilities. |
| Regional Certification Alignment Pursuit | BIS-EASA harmonization accelerates Indian UDAN scheme motor qualification pathways for sub-19 seat hybrid-electric aircraft. |
Methodological Framework
Desk research of FAA Part 33 certification precedent databases, EASA CS-E amendment filings, and NASA Glenn Research Center technical reports preceded structured interviews with electric propulsion system architects, thermal management specialists, and airframer procurement directors. Primary fieldwork with tier-one aerospace supplier engineering teams and specialist motor house R&D leads combined with secondary validation against customs records for silicon steel and copper winding trade flows. Bottom-up installation forecasts and top-down aviation electrification budget allocations were triangulated.
Assumptions held FAA-EASA certification harmonization progress and copper price volatility within observed ranges while varying urban air mobility platform deployment timelines and defense procurement rule stringency. The analytical framework segmented by motor topology, power rating band, end-use platform certification tier, and regional regulatory cluster across the projection horizon. CAGRs derived from airframe OEM electrification commitment schedules and NASA-Department of Energy joint funding trajectories. Forecast inputs included eVTOL motor slot bookings and regional commuter aircraft program entry-into-service dates.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by aerospace conglomerates or sudden Chinese magnet export restrictions would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Power Systems
Aircraft Turbocharger Market
Aircraft Power Systems
Aviation Actuator System Market
Aircraft Power Systems
Thrust Vector Control (TVC) Systems Market
Aircraft Power Systems
Aerospace Battery Technology Market
Aircraft Power Systems
Aircraft Auxiliary Power Unit Market
Aircraft Power Systems
UAV Propulsion System Market
Aircraft Power Systems
Aircraft Fluid Power Components Market
Aircraft Power Systems
Aircraft Circuit Breakers Market
Aircraft Power Systems
Low-Carbon Propulsion Market
Aircraft Power Systems
Aircraft Hydraulic Seat Actuation Systems Market
Aircraft Power Systems
Global Aircraft Electrification Market
Aircraft Power Systems
Aircraft Turboprop Propeller System Market
Aircraft Power Systems
Commercial Aircraft Propeller Systems Market
Aircraft Power Systems
Aircraft Hydraulic Actuators Market
Aircraft Power Systems
Aircraft Cooling Turbines Market
Aircraft Power Systems
More Electric Aircraft Market