
 Aerospace Lightning Strike Protection Market | 2026-2036
Aerospace Lightning Strike Protection Market Size, Share, and Industry Trends Forecast 2026-2036
Aerospace Lightning Strike Protection Market Intelligence
The EU Green Deal is realigning material selection across European aerospace supply chains, pushing airframers toward lighter conductive substrates that cut fuel burn while maintaining Faraday-cage integrity. TE Connectivity Ltd. leverages its grounding and interconnect portfolio to capture retrofit demand from aging narrow-body fleets. Dexmet Corporation specializes in expanded metal foils that OEMs embed within carbon-fiber layups for controlled current dissipation. Henkel Corporation anchors the adhesive-conductive coating segment, supplying paste systems that bond dissimilar substrates while preserving electrical continuity.
Aerospace lightning strike protection encompasses engineered materials and electrical architectures that safely conduct, dissipate, or divert atmospheric electrical energy away from critical aircraft structures and avionics, typically employing copper or aluminum meshes, conductive polymers, and engineered grounding paths with surface resistances below specified thresholds to prevent puncture or ignition of fuel vapors. The primary purpose is preserving airworthiness certification and passenger safety during thunderstorm penetration. Composite Materials lead product-type value pools because Boeing and Airbus have pushed carbon-fiber primary structures past fifty percent of airframe weight, forcing parallel investment in embedded conductivity. Smart Materials within technology segmentation represent the fastest-expanding category, as piezoelectric and self-monitoring layers promise real-time damage detection post-strike. Drones as an application segment occupy an emerging margin pool, with urban air mobility platforms requiring miniature, weight-optimized protection schemes absent from manned-aviation legacy designs.
FAA airworthiness standards under Part 25.581 and EASA CS-25.581 mandate repeatable lightning test evidence for type certification, creating structural demand for validated protection packages that third-party test houses certify. China's CAAC harmonizes with these baselines while adding domestic GB/T compliance layers for locally assembled COMAC platforms, complicating market access for non-Chinese suppliers. ISO 14001 and AS9100 quality frameworks further filter supplier eligibility, particularly for military end users requiring dual-use traceability. Stakeholders must monitor whether solid-state active protection systems displace passive mesh architectures as voltage-handling thresholds rise on next-generation electric-propulsion aircraft.
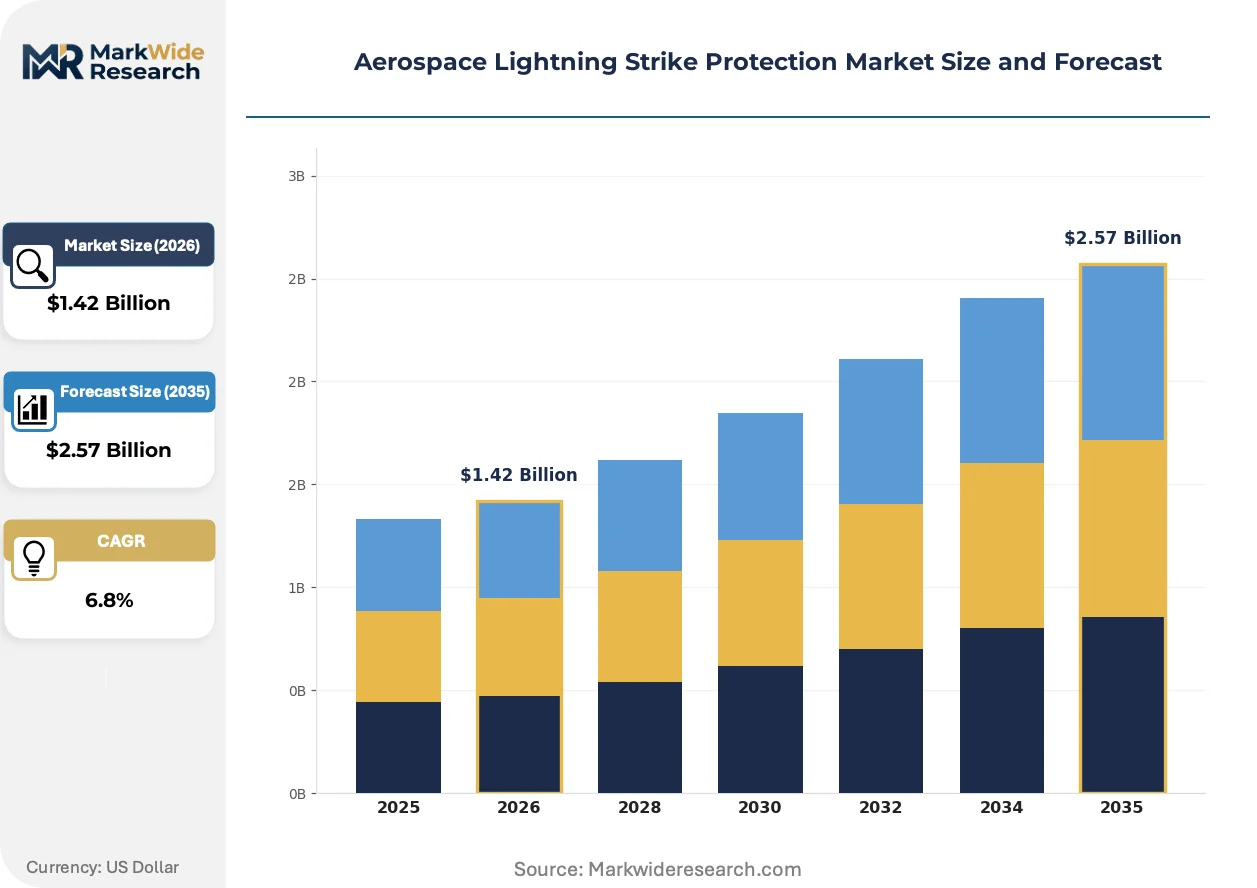
Market Dynamics
The aerospace lightning strike protection sector faces a structural pivot as composite airframes displace aluminum in commercial aircraft, forcing parallel reinvention of conductive pathways that were once inherent to metal structures. FAA and EASA certification timelines now determine program schedules, embedding protection validation into the critical path of new aircraft development.
Growth Catalysts
- EU Green Deal fuel-efficiency mandates:European airframers accelerate adoption of lighter conductive substrates to reduce fuel burn while maintaining Faraday-cage integrity across carbon-fiber primary structures.
- Urban air mobility proliferation:Electric vertical take-off and landing platforms require miniature, weight-optimized protection schemes absent from manned-aviation legacy designs.
- China's COMAC fleet expansion:Domestic assembly of C919 and ARJ21 platforms under CAAC harmonized standards generates localized demand for certified protection packages.
Market Restraints
- Copper and aluminum price volatility:Expanded metal foil and mesh architectures remain exposed to commodity input swings that compress margin pools for protection system integrators.
- Testing infrastructure concentration:Validated lightning strike test facilities cluster in the United States, Germany, and France, creating geographic bottlenecks for certification throughput.
- Passive mesh displacement risk:Solid-state active protection systems threaten conventional embedded conductivity as voltage-handling thresholds rise on next-generation electric-propulsion aircraft.
Strategic Opportunities
- India defense aerospace modernization:Indigenous fighter and unmanned combat air vehicle programs under the country's PLI scheme create entry points for protection system suppliers meeting dual-use traceability requirements.
- Self-monitoring smart materials convergence:Piezoelectric layers integrated with conductive substrates enable real-time damage detection post-strike, differentiating premium protection offerings.
- Retrofit channel activation:Aging narrow-body fleets require upgraded protection systems to maintain airworthiness, opening aftermarket revenue streams distinct from OEM line-fit contracts.
Industry Challenges
- Multiphysics simulation talent scarcity:Lightning strike modeling demands expertise coupling electromagnetic, thermal, and structural analysis that outpaces current workforce supply.
- AS9100 and ISO 14001 certification timelines:Quality framework compliance for military end users extends supplier qualification cycles, delaying revenue recognition for new market entrants.
- Legacy fleet integration complexity:Protection system upgrades on aging aluminum airframes must reconcile with existing bonding and grounding architectures without triggering full recertification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerospace Lightning Strike Protection Market |
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conductive Coatings, Composite Materials, Bonding Straps, Lightning Diversion Systems Application: Aircraft, Helicopters, Drones, Satellites Technology: Active Protection, Passive Protection, Smart Materials, Grounding Solutions End User: OEMs, MRO Service Providers, Military, Private Operators |
| Companies Covered | Eaton Corporation plc, TE Connectivity Ltd., Honeywell International Inc., Henkel Corporation, Amphenol Corporation, Raytheon Technologies Corporation, Safran S.A., Dexmet Corporation, Parker-Hannifin Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerospace Lightning Strike Protection Market Strategic Shifts & Innovations
Computational design tools and additive manufacturing are compressing development cycles for protection architectures, enabling topology-optimized conductive geometries that were previously unmanufacturable. Material science advances now permit conductivity functions to merge with structural loads in single components.
Expanded metal foils embedded within carbon-fiber layups are automating current dissipation pathways that previously required manual mesh placement and bonding. Major commercial OEMs specify these architectures for wing and fuselage sections exceeding fifty percent composite content. The automation of conductivity integration is compressing labor content in protection system installation while improving repeatability across production lines.
EASA CS-25.581 and FAA Part 25.581 harmonization around high-intensity radiated field and lightning test evidence is tightening documentation requirements for type certification. Manufacturers must submit repeatable test data from accredited facilities, elevating the strategic value of in-house or captive testing capabilities. European suppliers with EASA-approved test houses are capturing disproportionate share of new platform development programs.
Airframe OEMs now unbundle protection system specification from airframe contracts, creating direct procurement relationships between tier-one protection suppliers and engineering teams. This disintermediation of traditional aerostructures integrators concentrates technical dialogue with specialists who control conductivity modeling IP. The pattern is most visible in Germany and France, where Airbus engineering centers maintain dedicated lightning protection engineering groups with vendor-direct engagement authority.
Aerospace Lightning Strike Protection Market Segmentation
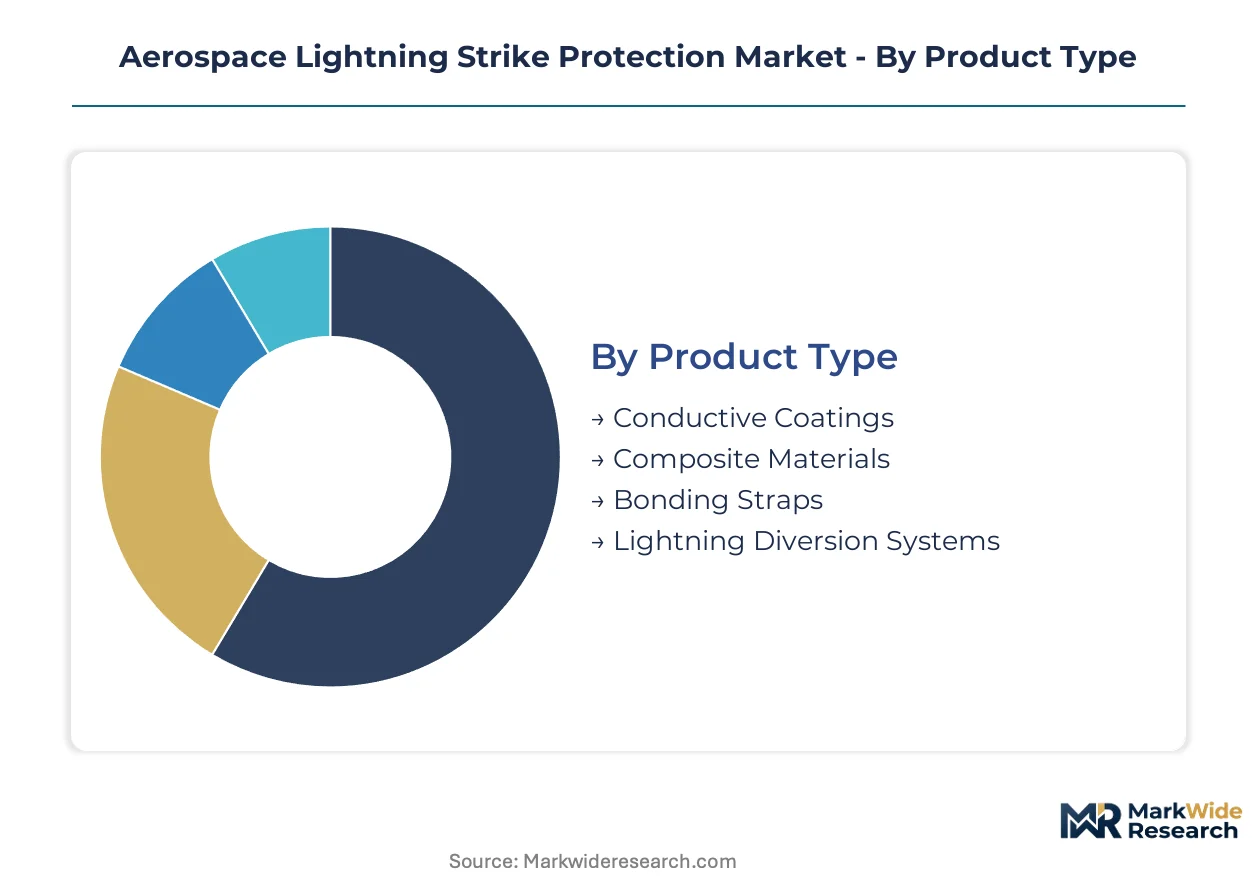
Lightning strike protection systems face divergent certification pathways depending on segment composition. FAA Part 25.581 and EASA CS-25.581 requirements vary sharply across product types and end-user categories, forcing suppliers to maintain parallel qualification tracks.
Product Type:
FAA and EASA certification timelines diverge most sharply here: conductive coatings require environmental qualification under RTCA DO-160, while composite-embedded architectures demand structural bonding substantiation that extends approval cycles.
- Composite Materials:Carbon-fiber layups with embedded expanded metal foils or conductive meshes now constitute the primary conductivity architecture for modern airframes. Boeing and Airbus specifications for wing and fuselage sections exceeding fifty percent composite content drive procurement concentration in the United States, Germany, and France.
- Conductive Coatings:Polymer-based systems containing silver, copper, or carbon fillers provide surface conductivity without structural reinforcement. EU Green Deal fuel-efficiency mandates accelerate substitution of heavier metal foils on European platforms where weight reduction carries premium value.
- Bonding Straps:Flexible copper or aluminum jumpers maintain electrical continuity between dissimilar structural elements.
- Lightning Diversion Systems:Discrete components including static wicks and air terminals that preferentially attract and dissipate strike energy.
Leading the category by volume: Composite Materials. Growing fastest: Conductive Coatings.
Application:
Volume concentration and margin structure split cleanly between manned and unmanned platforms, with certification burden intensity inversely correlated with platform size.
- Aircraft:Commercial and business aviation platforms generate the dominant revenue pool. FAA Part 25.581 compliance for transport-category aircraft demands full-scale zone testing that only accredited facilities in the United States, Germany, and France currently provide.
- Drones:Urban air mobility and commercial UAV segments require miniature, weight-optimized protection absent from manned-aviation legacy designs. EASA SC-VTOL and FAA Part 107 harmonization efforts are compressing certification timelines for electric vertical take-off platforms.
- Helicopters:Rotorcraft face unique strike exposure patterns due to operational altitude profiles and hover capability in weather.
- Satellites:Space-based assets require protection against electrostatic discharge and plasma interaction rather than atmospheric lightning.
Highest certification burden: Aircraft. Steepest expansion trajectory: Drones.
Technology:
Intellectual property concentration and manufacturing complexity separate segments with vastly different supplier margin profiles and capital requirements.
- Passive Protection:Expanded metal foils and conductive meshes embedded during composite manufacture dominate installed base. Automation of layup integration is compressing labor content while improving repeatability across Boeing and Airbus production lines.
- Smart Materials:Piezoelectric and self-monitoring layers enable real-time damage detection post-strike, commanding premium positioning. Development activity concentrates in German and French research clusters with Airbus engineering collaboration.
- Active Protection:Solid-state systems using plasma or field-modulation approaches threaten conventional architectures as voltage-handling thresholds rise on next-generation electric-propulsion aircraft.
- Grounding Solutions:Engineered current return paths and equipotential bonding networks integrated with airframe electrical systems.
Dominant by installed value: Passive Protection. Gaining share fastest: Smart Materials.
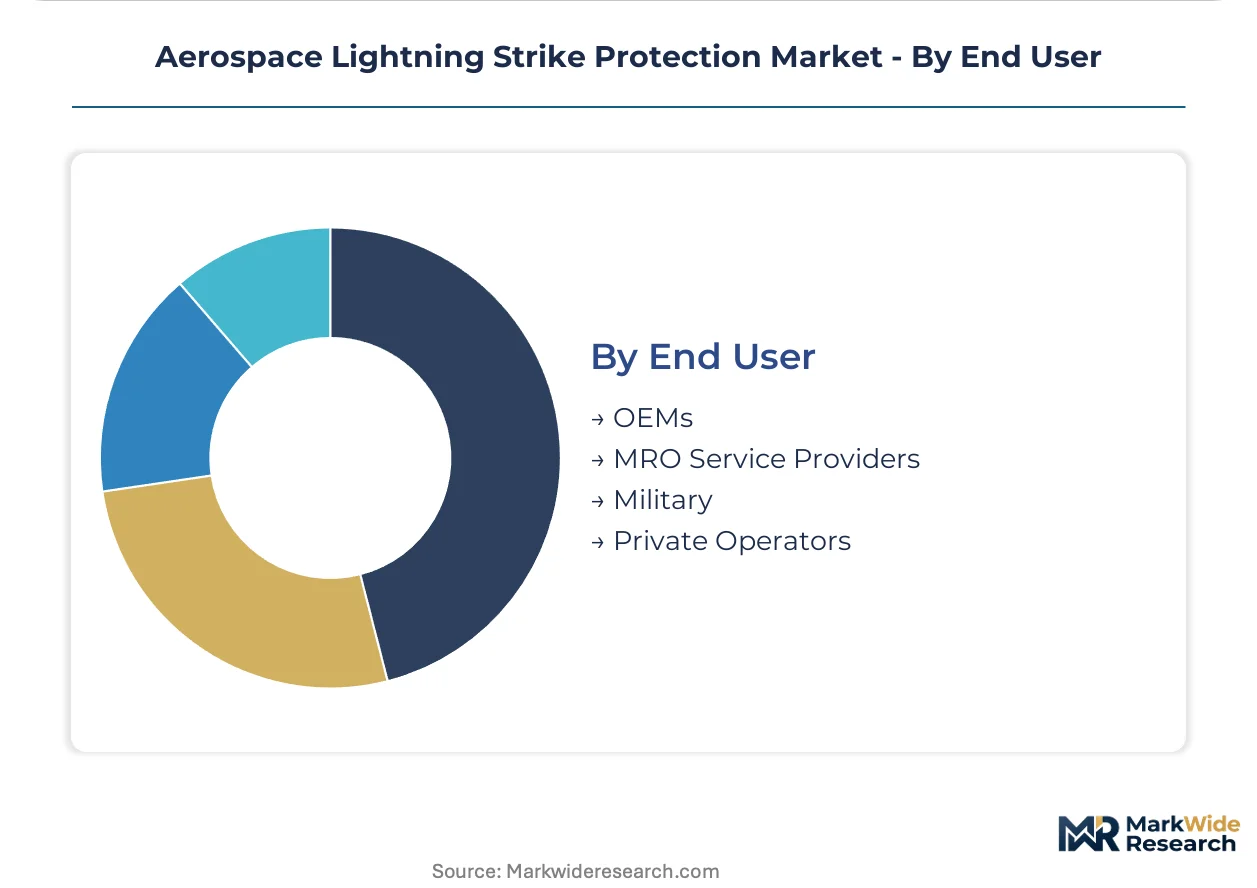
End User:
Procurement authority and technical specification control fragment across customer types with incompatible qualification timelines and contract structures.
- OEMs:Boeing, Airbus, and COMAC maintain direct engineering relationships with protection system specialists, disintermediating traditional aerostructures integrators. Airframers now unbundle protection specification from airframe contracts, concentrating dialogue with conductivity modeling IP holders.
- MRO Service Providers:Aging narrow-body fleets require upgraded protection systems to maintain airworthiness, opening aftermarket revenue streams distinct from OEM line-fit contracts. TE Connectivity leverages its grounding portfolio to capture retrofit demand from aging fleets.
- Military:Dual-use traceability requirements under AS9100 and ISO 14001 extend supplier qualification cycles for defense end users.
- Private Operators:Business aviation and general aviation customers procure through tier-one system integrators rather than direct specification.
Highest contract value concentration: OEMs. Fastest channel expansion: MRO Service Providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seattle anchors North American aerospace lightning protection engineering, hosting Boeing's primary development centers where expanded metal foil specifications for carbon-fiber wings originate. Toulouse and Hamburg engineering clusters drive European conductive substrate innovation under tightening EASA certification timelines. COMAC's Shanghai assembly lines generate parallel demand for CAAC-validated protection packages as China's indigenous fleet scales.
United States
Boeing's 787 and 777X programs drive embedded conductivity demand across carbon-fiber primary structures exceeding fifty percent airframe weight. FAA Part 25.581 mandates zone testing evidence that only accredited U.S. facilities currently provide for transport-category certification. Seattle and Charleston engineering centers maintain direct vendor relationships with protection specialists, bypassing traditional aerostructures integrators.
Germany
Airbus Hamburg and Bremen facilities specify lightweight conductive coatings to meet EU Green Deal fuel-efficiency targets on A320neo and A350 platforms. EASA CS-25.581 harmonization with FAA standards creates dual-certification pathways for protection system suppliers. Munich and Dresden research clusters concentrate smart materials development, integrating piezoelectric layers for real-time strike damage detection.
France
Toulouse engineering centers unbundle protection specification from airframe contracts, concentrating procurement authority with conductivity modeling IP holders. EASA-approved lightning test houses in Paris-Saclay and Bordeaux capture disproportionate share of new platform development programs. Saint-Nazaire composite manufacturing lines automate expanded metal foil integration into A350 fuselage sections.
China
COMAC's C919 and ARJ21 assembly in Shanghai generates localized demand for GB/T-compliant protection packages beyond FAA-EASA baselines. CAAC harmonization with international standards adds domestic compliance layers that complicate market access for non-Chinese suppliers. Xi'an and Chengdu military aviation clusters drive parallel demand for AS9100-traceable protection systems on indigenous fighter programs.
United Kingdom
Rolls-Royce Derby and Bristol engineering centers specify protection systems for next-generation electric-propulsion aircraft development. UK defense aerospace programs under the Tempest fighter initiative create dual-use demand for qualified protection suppliers. BAE Systems' Lancashire and Hampshire facilities maintain captive lightning test capabilities for military platform certification.
Aerospace Lightning Strike Protection Market Key Industry Players
Premium-margin players sit above commodity-margin players across certification complexity and conductivity modeling IP ownership. The market structures around three tiers: global electrical interconnect specialists with captive test facilities, engineered materials firms controlling expanded metal foil automation, and adhesive-chemical suppliers integrating conductive functions into structural bonding systems. Consolidation pressures concentrate among mid-scale protection integrators lacking in-house electromagnetic simulation capabilities. Dominant competitive moves include backward integration into conductive substrate manufacturing and strategic partnerships with composite airframe tier-one suppliers.
Within the electrical systems tier, TE Connectivity Ltd. and Amphenol Corporation occupy positions defined by grounding and interconnect portfolios that span OEM line-fit and MRO retrofit channels. Dexmet Corporation exemplifies the engineered materials archetype, with corporate identity signaling specialization in expanded metal architectures. Henkel Corporation anchors the chemical-adhesive segment, representing integration of conductivity functions into paste systems that bond dissimilar substrates. These three company structures illustrate how protection market value pools separate between electrical pathway control, materials automation, and surface conductivity chemistry.
| Leading Market Players |
|---|
| Eaton Corporation plc |
| TE Connectivity Ltd. |
| Honeywell International Inc. |
| Henkel Corporation |
| Amphenol Corporation |
| Raytheon Technologies Corporation |
| Safran S.A. |
| Dexmet Corporation |
| Parker-Hannifin Corporation |
| Others |
Cost & Logistics Intelligence
London Metal Exchange copper price volatility cascades through aerospace lightning protection supply chains, compressing margin pools for expanded metal foil integrators while amplifying pricing power for adhesive-chemical suppliers with polymer-based conductivity alternatives. Tier-one protection system buyers face escalating procurement costs when commodity spikes coincide with EASA certification backlogs, forcing selective substitution toward conductive coatings that trade some performance for weight and cost efficiency.
Pricing Analysis
Certification-grade throughput anchors value-based pricing across protection system tiers, with EASA-approved test evidence commanding premium positioning over baseline FAA-compliant alternatives. Three-tier pricing structure across premium, standard, and economy levels separates smart materials with real-time damage detection from passive mesh architectures and commodity bonding straps. Cost compression in conductive coatings is intensifying because EU Green Deal weight mandates drive substitution of heavier metal foils, though OEM engineering groups remain least price-sensitive due to airworthiness liability exposure.
Supply Chain Analysis
Regional distribution centers in Seattle, Toulouse, and Hamburg maintain hub-and-spoke patterns that feed composite manufacturing lines at Boeing, Airbus, and their tier-one aerostructures partners. Supply concentration in the United States, Germany, and France draws from copper and aluminum smelters, carbon-fiber prepreg suppliers, and specialized adhesive formulators. Single-source vulnerability around EASA-accredited lightning test facilities creates geographic bottlenecks that extend lead times for certification packages. Distribution runs through direct procurement relationships between protection specialists and airframe OEM engineering centers, bypassing traditional aerostructures integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aerospace lightning strike protection sits in a technology-transition phase as solid-state active protection systems displace legacy passive mesh architectures on next-generation electric-propulsion aircraft. Smart materials with embedded piezoelectric sensing layers represent the most viable bridge technology for suppliers seeking premium positioning.
For Market Incumbents: Deploy captive lightning test facility investment as the priority lever to defend against EASA certification bottlenecks that threaten program schedules. Backward integration into conductive substrate manufacturing secures margin control against copper price volatility, while exclusive engineering relationships with Airbus and Boeing platform teams create switching costs that emerging entrants cannot replicate.
For New Entrants and Emerging Players: MRO service providers represent the most accessible channel partner type for bypassing OEM line-fit barriers controlled by entrenched specialists. India's indigenous fighter and unmanned combat air vehicle programs under the PLI scheme offer white-space demand with dual-use traceability requirements that filter out commodity competitors. Target aftermarket retrofit contracts for aging narrow-body fleets where airworthiness recertification urgency overrides brand loyalty to incumbent suppliers.
For Investors and Strategic Acquirers: Distressed-cycle entries favor engineered materials specialists with EASA-approved test capabilities in France and Germany during periods of certification backlog. Long-term viability hinges on conductivity modeling IP ownership rather than manufacturing scale, as computational design tools compress development cycles. Watch for solid-state active protection system technical maturation as the inflection signal that would strand passive mesh manufacturing assets.
| Strategic Initiative | Industry Significance |
|---|---|
| Smart Materials Development | Piezoelectric layers with real-time damage detection command premium positioning from Airbus engineering collaboration. |
| Captive Test Facility Investment | EASA-approved lightning test houses in Paris-Saclay capture disproportionate share of new platform development programs. |
| Retrofit Channel Activation | Aging narrow-body fleet airworthiness requirements open aftermarket revenue streams distinct from OEM line-fit contracts. |
| Conductive Coating Substitution | EU Green Deal weight mandates accelerate polymer-based alternatives that reduce fuel burn on A320neo and A350 platforms. |
| Regional Certification Localization | CAAC GB/T compliance layers for COMAC C919 assembly complicate market access and favor domestic supplier partnerships. |
Research Approach
Independent corroboration across primary interviews with lightning protection engineering directors, EASA certification specialists, composite manufacturing procurement leads, and MRO service operations managers underwrites the qualitative findings. Secondary validation draws from FAA Part 25.581 regulatory filings, EASA CS-25.581 certification databases, AS9100 quality framework audit records, and customs trade data for copper and aluminum mesh imports. Bottom-up segment sizing triangulates against top-down aerospace production forecasts from Boeing and Airbus delivery schedules.
Historical reference periods anchor the forecast window to demonstrated certification timeline patterns and composite airframe adoption curves across prior platform generations. The analytical framework models product type, application platform, technology generation, and end-user procurement channel across the projection horizon. CAGRs derive from segment-level volume trajectories weighted by certification burden intensity and material substitution elasticities, with electric-propulsion aircraft content per vehicle serving as a critical demand amplifier.
Several conditions sit outside the modeled scope, including unannounced military platform specifications, breakthrough active protection system technical maturation, and raw material price shocks exceeding historical volatility bands. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Safety Systems
Aircraft Docking Systems Market
Aircraft Safety Systems
Commercial Aircraft Carbon Brakes Market
Aircraft Safety Systems
Aircraft Ejection Seats Market
Aircraft Safety Systems
Aircraft Lightning Protection Market
Aircraft Safety Systems
Aircraft Fire Protection Systems Market
Aircraft Safety Systems
HUD Helmet Market
Aircraft Safety Systems
Aircraft Ice Protection System Market
Aircraft Safety Systems
Global Aircraft Brakes Market
Aircraft Safety Systems
Cloud-Connected Aircraft Safety Data Management Platforms Market
Aircraft Safety Systems
Aircraft Evacuation Systems Market
Aircraft Safety Systems
Aviation Life Rafts Market
Aircraft Safety Systems
Aviation Airbags Market
Aircraft Safety Systems
Airborne Collision Avoidance System Market
Aircraft Safety Systems
Aircraft Evacuation Slide Market
Aircraft Safety Systems
Aircraft Door Dampers Market
Aircraft Safety Systems
Aircraft Survivability Equipment Market