
 NIJ III Ballistic Bullet Resistant Panel Market | 2026-2036
NIJ III Ballistic Bullet Resistant Panel Market Size, Share, and Industry Trends Forecast 2026-2036
NIJ III Ballistic Bullet Resistant Panel Market Insights
North American armor manufacturers is restructuring supply chains around domestic aramid fiber spinning and ceramic tile pressing capacity. DuPont leverages its Kevlar production base in Richmond, Virginia to sustain vertical integration advantages across the value chain. Honeywell International anchors its position through Spectra fiber operations and controls a significant share of UHMWPE-based soft armor insert supply to military and law enforcement channels.
NIJ III ballistic bullet resistant panels are composite or monolithic protective elements engineered to defeat 7.62x51mm M80 NATO ball ammunition with specified backface deformation limits, typically constructed from ceramic strike faces bonded to aramid or polyethylene fiber backings. Hard armor plates dominate procurement volumes for military vehicle and personal protection applications, while hybrid panels represent the fastest-growing category as end users seek weight reduction without sacrificing multi-hit capability. Ultra-High Molecular Weight Polyethylene material segments command premium positioning in maritime and airborne platforms where every kilogram translates to fuel and payload penalties.
FBI ballistic resistance testing protocols, NIJ Standard-0101.06 certification requirements, and evolving Special Threat testing guidelines shape product development roadmaps and market access conditions for domestic and international suppliers. The Department of Justice and Department of Defense jointly influence procurement specifications through interoperability mandates and Berry Amendment compliance for domestically sourced fibers and substrates. Stakeholders must monitor the NIJ Standard-0101.07 revision timeline and its potential reclassification of threat levels, which would trigger recertification cycles and reshape competitive positioning across material categories and product formats.
Market Dynamics
The NIJ III ballistic panel market is experiencing acute pressure from the Berry Amendment's domestic sourcing mandates, which are forcing manufacturers to reconfigure fiber and ceramic substrate supply chains around captive US production capacity rather than offshore alternatives.
Growth Catalysts
- DoD Modernization Budgets:Department of Defense procurement allocations for soldier protection systems are expanding order volumes for hard armor plates across Army and Marine Corps units.
- NIJ Standard-0101.06:This certification framework mandates third-party laboratory testing for ballistic resistance, creating compulsory replacement cycles as threat-level specifications tighten.
- Ceramic Composite Advances:Silicon carbide and boron carbide strike-face formulations are reducing areal density while maintaining multi-hit integrity against 7.62x51mm threats.
Market Restraints
- Aramid Fiber Concentration:Domestic Kevlar and Twaron spinning capacity remains concentrated among three North American facilities, creating single-source vulnerability for woven backings.
- High-Grade Ceramic Input Costs:Sintered silicon carbide tile production requires energy-intensive hot pressing, exposing margins to natural gas and electricity price volatility.
- Extended NIJ Certification Timelines:Third-party ballistics laboratory backlog stretches compliance testing to 8-14 months, delaying product launches and revenue recognition.
Strategic Opportunities
- Maritime Platform Penetration:Naval Special Warfare and Coast Guard maritime security units are adopting UHMWPE-dominant panels for flotation-critical applications where ceramic weight is prohibitive.
- Federal Vehicle Upfit Programs:Department of Homeland Security armored vehicle retrofit initiatives are creating dedicated procurement channels for door and firewall panel suppliers.
- Hybrid Panel Convergence:Ceramic-polyethylene hybrid architectures are capturing law enforcement demand by bridging the weight gap between pure ceramic and pure fiber solutions.
Industry Challenges
- Ballistics Engineering Talent Scarcity:Specialized expertise in terminal ballistics modeling and composite failure analysis is concentrated among retiring defense-sector veterans.
- Legacy System Integration Friction:New lightweight plates must interface with existing plate carrier designs and quick-release mechanisms, constraining form factor innovation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | NIJ III Ballistic Bullet Resistant Panel Market |
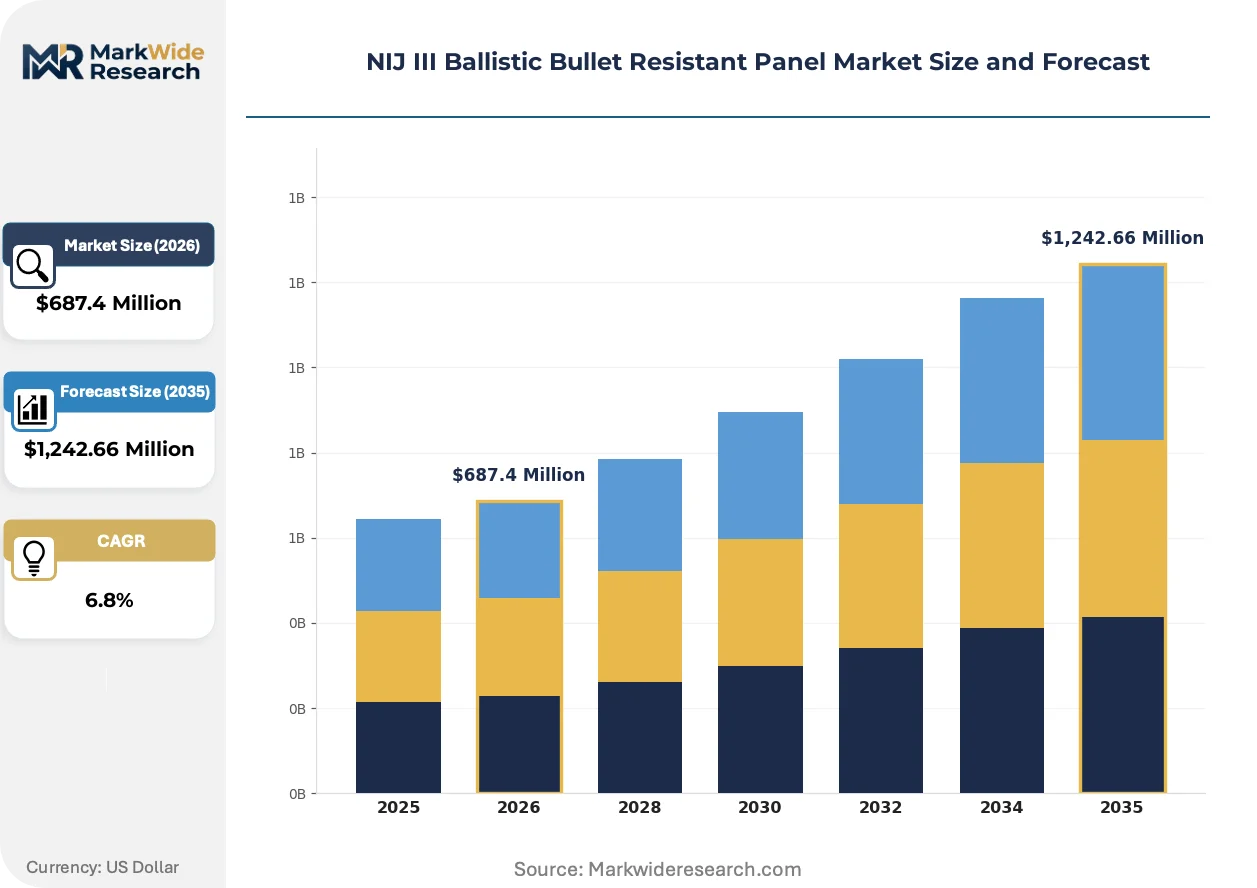
| Market Size in 2026 | $687.4 Million |
| Market Size in 2035 | $1,242.66 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hard Armor Plates, Soft Armor Inserts, Hybrid Panels, Ceramic Composite, Steel Plates Material: Aramid Fiber, Ultra-High Molecular Weight Polyethylene, Ceramic, Steel Alloy, Polycarbonate End User: Law Enforcement Agencies, Military Units, Private Security Firms, Correctional Facilities Application: Personal Protection, Vehicle Armor, Tactical Shields, Infrastructure Security |
| Companies Covered | DuPont, Honeywell International, Armorcore, Armortex, Total Security Solutions, China North Industries Group Co., Ltd., Palram Americas Ltd., Roechling, Insulgard, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
NIJ III Ballistic Bullet Resistant Panel Market Trends and Innovations
Computational design tools and automated fiber placement are compressing development cycles for next-generation armor systems while regulatory pressure intensifies around domestic content verification.
Automated preform stitching is automating the layup of multi-layer aramid and UHMWPE backings that previously required manual assembly. Armor contractors serving military procurement channels are adopting robotic sewing cells to reduce labor content and improve ply alignment consistency. This automation is compressing unit economics for high-volume orders while enabling thickness tolerances that manual processes cannot replicate.
The NIJ Standard-0101.07 revision timeline is forcing manufacturers to pre-position testing protocols for potential threat-level reclassifications. Ballistics laboratories are expanding conditioned-testing capabilities to address the new standard's environmental exposure requirements. Domestic suppliers with in-house NIJ-certified test facilities are accelerating certification cycles relative to competitors dependent on third-party labs.
Law enforcement agencies are consolidating purchases through state-level cooperative procurement contracts rather than municipal independent sourcing. Texas and Florida state procurement offices are negotiating master agreements that aggregate demand from hundreds of local departments. This buyer concentration is squeezing regional distributors and favoring manufacturers with direct state-contract eligibility.
NIJ III Ballistic Bullet Resistant Panel Market Segmentation
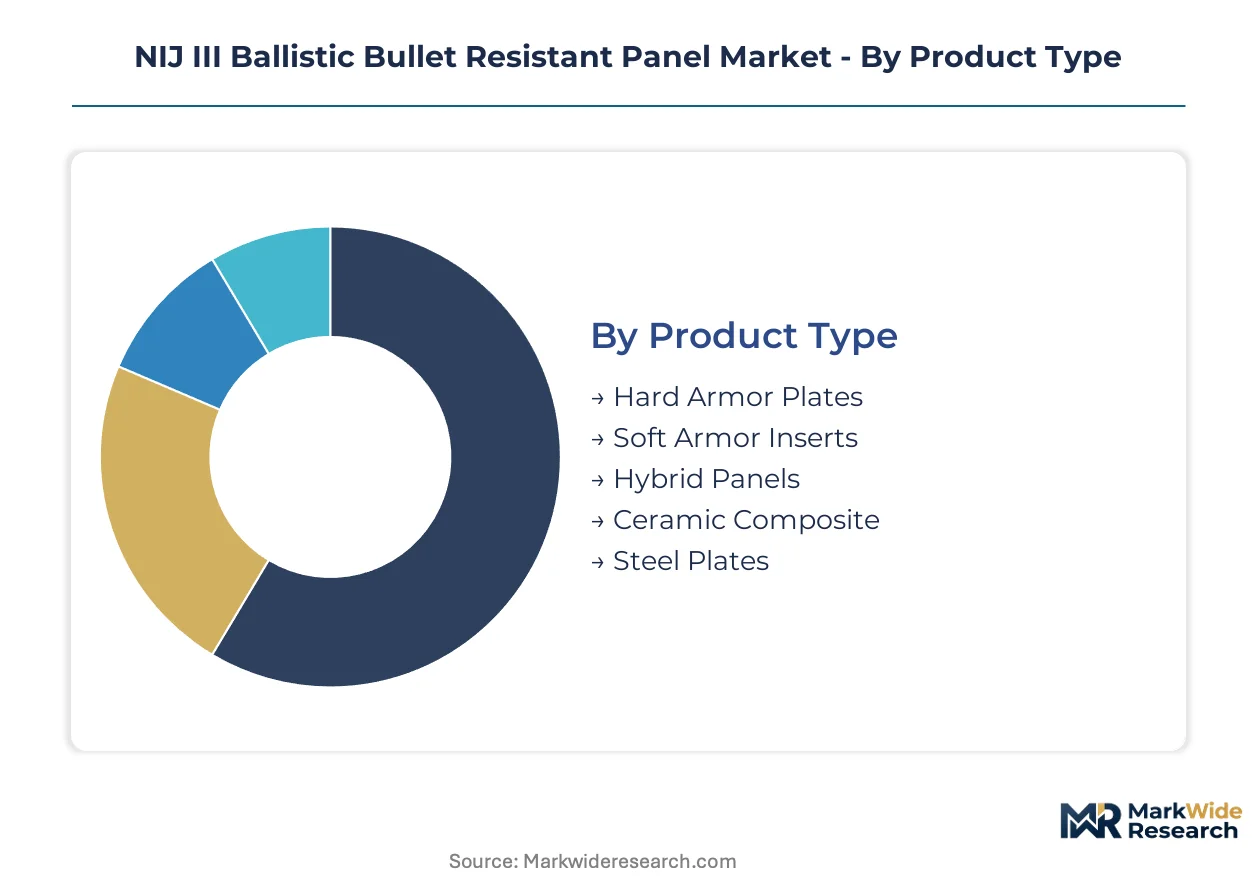
NIJ III panel procurement diverges sharply across protection architectures, material substrates, and operational environments. End-users select configurations based on weight constraints, multi-hit requirements, and platform integration demands rather than ballistic rating alone.
Product Type:
Ceramic strike-face bonding techniques and fiber backing architectures define performance tiers across protection formats.
- Hard Armor Plates:Monolithic or composite plates with ceramic strike faces bonded to aramid or UHMWPE backings dominate military procurement. Army and Marine Corps modernization programs sustain order volumes for SAPI and ESAPI form factors despite weight penalties.
- Hybrid Panels:Ceramic-polyethylene layered architectures bridge pure ceramic and pure fiber solutions. Law enforcement agencies in Texas and Florida state cooperative contracts favor these configurations for patrol applications where vehicle egress speed matters.
- Soft Armor Inserts:Woven aramid or laminated UHMWPE panels provide flexible protection against fragmentation and handgun threats.
- Ceramic Composite:Silicon carbide and boron carbide tile arrays deliver multi-hit capability against rifle threats.
- Steel Plates:Spall-coated steel substrates offer cost-sensitive protection with durability trade-offs.
Mature deployment sits with Hard Armor Plates. Newer deployment is concentrated in Hybrid Panels.
Material:
Domestic fiber spinning capacity and ceramic sintering infrastructure constrain supply elasticity across substrate categories.
- Ultra-High Molecular Weight Polyethylene:Spectra and Dyneema fiber laminates command premium positioning in maritime and airborne platforms. Naval Special Warfare units specify UHMWPE-dominant panels where flotation requirements override ceramic ballistic efficiency.
- Aramid Fiber:Kevlar and Twaron woven backings provide proven multi-hit absorption for soft armor and plate backing applications. Domestic spinning capacity concentrated in Virginia and South Carolina facilities creates single-source vulnerability for military procurement.
- Ceramic:Silicon carbide and boron carbide strike faces require energy-intensive hot pressing operations.
- Steel Alloy:Ballistic-grade steel substrates serve cost-constrained segments with spall mitigation coatings.
- Polycarbonate:Transparent armor applications integrate polycarbonate layers with glass or ceramic for viewport protection.
Volume concentration rests with Aramid Fiber. Steepest expansion trajectory belongs to Ultra-High Molecular Weight Polyethylene.
End User:
Budget authority and threat profile determine specification stringency across institutional buyer categories.
- Military Units:Department of Defense procurement channels mandate NIJ Standard-0101.06 or equivalent military specifications with Berry Amendment compliance for fiber sourcing. Army PEO Soldier and Marine Corps Systems Command drive standardization around plate carrier integration.
- Law Enforcement Agencies:Municipal, county, and state departments operate through cooperative procurement contracts or independent sourcing. FBI ballistic resistance testing protocols influence specification requirements beyond baseline NIJ certification.
- Private Security Firms:Executive protection and high-risk facility contractors purchase commercial-off-the-shelf configurations.
- Correctional Facilities:Perimeter and transport applications emphasize stab resistance alongside ballistic ratings.
Specification leadership sits with Military Units. Procurement volume expansion is concentrated in Law Enforcement Agencies.
Application:
Platform integration constraints and mobility requirements segment demand across protection scenarios.
- Personal Protection:Individual plate carrier and vest configurations prioritize weight reduction and wearability. Plate form factors must interface with existing quick-release mechanisms and cummerbund designs, constraining dimensional innovation.
- Vehicle Armor:Door panel, firewall, and floorboard applications for armored sedans and tactical vehicles require curved geometries and multi-hit durability. Department of Homeland Security upfit programs create dedicated procurement channels for verified suppliers.
- Tactical Shields:Handheld and deployable shield configurations balance transparency, weight, and coverage area.
- Infrastructure Security:Fixed installation panels for checkpoint and facility hardening emphasize cost efficiency over mobility.
Standardization maturity sits with Personal Protection. Specification evolution is concentrated in Vehicle Armor.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Virginia's Kevlar spinning facilities and South Carolina's aramid fiber production anchor North American supply security for military-grade ballistic substrates. Procurement patterns diverge sharply across national defense budgets, domestic content mandates, and threat environment severity.
United States
Department of Defense modernization budgets and DHS vehicle upfit programs sustain the world's largest NIJ III panel procurement volume. Berry Amendment compliance requirements mandate domestic fiber sourcing, privileging Richmond, Virginia-based Kevlar production and Honeywell's Spectra operations. Army PEO Soldier standardization drives SAPI and ESAPI form factor demand across active-duty and National Guard units.
Germany
Bundeswehr soldier protection modernization and federal police GSG-9 tactical unit expansion generate sustained ceramic composite demand. KBA vehicle armoring regulations for diplomatic and executive protection fleets create certified supplier qualification requirements. Bavaria's industrial base hosts precision ceramic pressing operations serving NATO interoperability specifications.
China
China North Industries Group's vertical integration from silicon carbide sintering to finished plate production supplies domestic military and paramilitary channels. GB standards for ballistic resistance testing operate parallel to NIJ protocols, creating dual-certification complexity for export-oriented manufacturers. Yangtze River Delta ceramic processing clusters concentrate hot-pressing capacity for boron carbide strike faces.
United Kingdom
Ministry of Defence Integrated Review commitments to soldier lethality modernization expand hard armor plate orders for Army and Royal Marine units. UK Defence Standard 00-35 environmental testing requirements exceed baseline NIJ protocols, favoring suppliers with in-house conditioned-testing capabilities. Midlands-based ballistics engineering consultancies support MoD procurement technical evaluation.
Israel
IDF active-duty and reserve force protective equipment refresh cycles sustain above-average per-capita panel consumption. Ministry of Defense Directorate of Defense Research and Development funding accelerates lightweight hybrid panel adoption for urban warfare mobility requirements. Tel Aviv-area defense contractors specialize in ceramic-polyethylene bonding techniques for multi-hit integrity.
NIJ III Ballistic Bullet Resistant Panel Market Competitive Landscape
Global majors compete with regional champions across fiber spinning and ceramic pressing capabilities, creating tiered supply security structures. The vendor base stratifies between captive fiber producers, independent plate fabricators, and vehicle armor integrators. Three archetypes dominate: vertically integrated fiber-to-plate manufacturers, specialized ceramic strike-face suppliers, and vehicle upfit system integrators. Capacity expansion and Berry Amendment compliance certification represent the primary competitive moves reshaping procurement eligibility.
Within the fiber-dominant tier, DuPont and Honeywell International exemplify upstream control strategies through captive aramid and UHMWPE production. China North Industries Group occupies a position as a state-integrated defense industrial complex participant with sintering-to-assembly vertical scope. Roechling represents the European engineering plastics specialist archetype, while Armorcore and Armortex sit within the independent plate fabrication segment serving law enforcement and private security channels.
| Leading Market Players |
|---|
| DuPont |
| Honeywell International |
| Armorcore |
| Armortex |
| Total Security Solutions |
| China North Industries Group Co., Ltd. |
| Palram Americas Ltd. |
| Roechling |
| Insulgard |
| Others |
Pricing and Supply Chain Analysis
Sintered silicon carbide tile production costs flow downstream through three distinct pricing tiers, with energy-intensive hot pressing operations in Virginia and South Carolina facilities anchoring premium positioning for Berry Amendment-compliant military procurement while offshore ceramic sourcing feeds cost-sensitive law enforcement channels.
Pricing Analysis
Warranty and multi-hit performance guarantees bundle with premium NIJ III plates, while stripped-down configurations dominate municipal procurement. Three-tier pricing structure across premium, standard, and economy levels separates military-specification plates with captive fiber backings from hybrid panels for patrol use and imported steel substrates for corrections budgets. Price differentiation hinges on NIJ Standard-0101.06 certification grade and domestic fiber content verification. Cost compression in the economy tier is intensifying because state cooperative contracts aggregate demand and squeeze regional distributors. Private security contractors exhibit the highest price sensitivity, while Department of Defense procurement channels prioritize performance over unit cost.
Supply Chain Analysis
Regional distribution centers in Richmond, Virginia and Greenville, South Carolina anchor hub-and-spoke fulfillment patterns for military and federal law enforcement channels. Geographic supply concentration centers on the United States for aramid fiber spinning, China for silicon carbide sintering, and Germany for boron carbide pressing. Raw material dependencies draw from petroleum-derived UHMWPE resin, alumina precursor chemicals, and high-purity silicon metal. Single-source vulnerability in domestic Kevlar and Twaron spinning capacity creates supply chain risk for woven backing substrates. Distribution runs through direct military procurement channels, state cooperative contracting offices, and specialized law enforcement distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around Berry Amendment compliance capabilities, with domestic fiber sourcing mandates forcing plate fabricators without captive supply relationships toward acquisition or exit.
For Market Incumbents: To counter third-party ballistics laboratory backlog extending certification timelines to 8-14 months, DuPont and Honeywell International should deepen in-house NIJ-certified test facility investments to accelerate product launch cycles. Capacity addition in South Carolina aramid spinning facilities would reduce single-source vulnerability for military procurement channels. Certification investment in NIJ Standard-0101.07 pre-positioning protocols will reshape competitive positioning when threat-level reclassifications trigger recertification cycles. For New Entrants and Emerging Players: Maritime platform procurement for Naval Special Warfare and Coast Guard flotation-critical applications represents an underserved buyer archetype where UHMWPE-dominant panels command premium positioning without ceramic weight penalties. State-level cooperative contracting in Texas and Florida offers the most penetrable procurement channel, aggregating demand from hundreds of municipal departments into master agreements. Direct state-contract eligibility through GSA schedule registration provides the essential go-to-market angle for bypassing regional distributor squeeze. For Investors and Strategic Acquirers: Extended NIJ certification timelines stretching beyond 12 months is the leading indicator that independent plate fabricators without in-house test facilities face working capital strain and delayed revenue recognition, creating acquisition targets at distressed valuations. Long-term viability in this market rests on backward integration into fiber spinning or ceramic pressing, not assembly-only positioning. The inflection signal to monitor is Department of Justice announcements on NIJ Standard-0101.07 implementation dates, which will trigger immediate recertification spending and reshape material category winners.| Strategic Initiative | Industry Significance |
|---|---|
| In-House NIJ Certification Investment | Accelerates product launch timelines relative to competitors dependent on third-party laboratory backlog. |
| Domestic Fiber Spinning Capacity Expansion | Secures Berry Amendment compliance eligibility for Army and Marine Corps modernization procurement channels. |
| Ceramic-Polyethylene Hybrid Architecture Development | Captures law enforcement demand bridging weight gaps between pure ceramic and pure fiber solutions. |
| State Cooperative Contract Eligibility | Unlocks aggregated municipal demand in Texas and Florida procurement consolidation trends. |
| Maritime Platform Specification Targeting | Penetrates Naval Special Warfare and Coast Guard channels where flotation requirements override ceramic efficiency. |
Research Methodology
Document review covered NIJ Standard-0101.06 certification protocols, Department of Defense procurement disclosures, and FBI ballistic resistance testing guidelines, complemented by interviews with ballistics laboratory directors, Army PEO Soldier procurement officers, state cooperative contracting administrators, and ceramic composite R&D leads. Secondary validation drew from Department of Justice regulatory filings, Berry Amendment compliance databases, and customs records for silicon carbide and boron carbide imports. Bottom-up unit economics for plate fabrication and top-down defense budget allocation analysis were triangulated against manufacturer production capacity estimates.
Segment-level demand outputs across the projection horizon reflect modeled procurement volumes for hard armor plates, hybrid panels, and soft armor inserts by military units, law enforcement agencies, and private security firms. Material substrate segmentation incorporated Ultra-High Molecular Weight Polyethylene, aramid fiber, and ceramic composite price elasticity assumptions. CAGRs were derived from defense modernization budget trajectory analysis and state-level cooperative contracting penetration rates. NIJ Standard-0101.07 revision timeline uncertainty and Berry Amendment enforcement intensity served as scenario-weighting inputs.
Revisions become necessary when NIJ certification protocol changes, Department of Defense budget reallocation decisions, or energy price volatility in ceramic sintering operations materialize beyond modeled assumptions. Forecasts reflect documented procurement patterns and stated regulatory timelines rather than speculative policy shifts. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Mortar Ammunition Market
Weapons and Ammunition
APAC Ballistic Missile Market
Weapons and Ammunition
Riflescope Market
Weapons and Ammunition
Intercontinental Ballistic Missile Market
Weapons and Ammunition
North America Nuclear Bombs and Missiles Market
Weapons and Ammunition
Electrical Weapon Market
Weapons and Ammunition
Sniper Rifle Market
Weapons and Ammunition
Mortar Artillery System Market
Weapons and Ammunition
North Korea Nuclear Bombs and Missiles Market
Weapons and Ammunition
Particle Beam Directed Energy Weapon Market
Weapons and Ammunition
Global Ammunition Market
Weapons and Ammunition
Hypersonic Missile Market
Weapons and Ammunition
Bomb Suppression Blanket (BSB) Ballistic Blankets V50 Standard Market
Weapons and Ammunition
Man-Portable Rocket Launcher Market
Weapons and Ammunition
Ballistic Composite Market
Weapons and Ammunition
High Power Microwave Directed Energy Weapons Market