
 Aerospace & Aircraft Collision Avoidance System Market | 2026-2036
Aerospace & Aircraft Collision Avoidance System Market Size, Share, and Industry Trends Forecast 2026-2036
Aerospace & Aircraft Collision Avoidance System Market Insights
Multi-source procurement for avionics subsystems is restructuring supply relationships across the collision avoidance value chain. Honeywell International Inc. leverages its integrated flight-deck portfolio to anchor long-term airline contracts. Thales Group competes through sovereign manufacturing bases in France and radar technology leadership. Garmin Ltd. specializes in compact, certified systems for business jets and general aviation retrofit channels.
Aerospace and aircraft collision avoidance systems comprise integrated sensor suites, processing algorithms, and cockpit displays that detect proximate traffic terrain threats and command resolution advisories to pilots, typically operating on 1090 MHz or 978 MHz frequencies with sub-100-foot altitude accuracy. The primary purpose is preventing controlled flight into terrain and mid-air collisions across all flight phases from takeoff to final approach. Traffic Collision Avoidance System hardware retains the largest installed base among product categories though Automatic Dependent Surveillance-Broadcast installations accelerate fastest as regulatory deadlines approach. Radar-Based technology dominates current revenue pools while GPS-Based architectures capture expanding share in unmanned platforms where size weight and power constraints predominate.
The FAA mandates ADS-B Out equipage under 14 CFR 91.225 while EASA enforces equivalent requirements through its CS-ACNS certification specifications, and China's CAAC implements parallel GB standards for domestic airspace access. These frameworks compel fleet-wide upgrades rather than selective new-aircraft fitment, embedding recurring demand into maintenance schedules. Stakeholders must monitor divergence between regional certification timelines as non-compliance risks route restrictions and slot penalties.
Market Dynamics
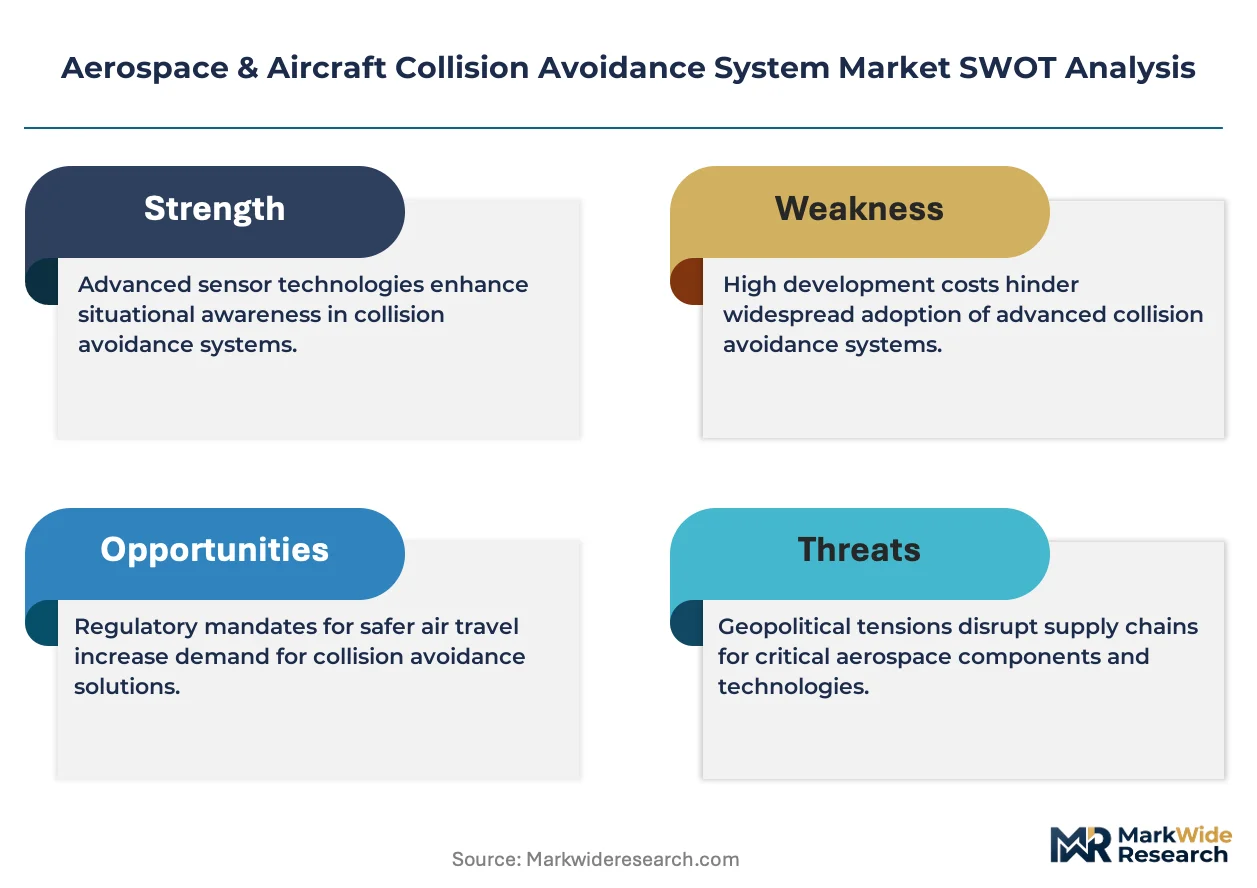
FAA mandates for ADS-B Out equipage under 14 CFR 91.225 are compressing procurement timelines across commercial fleets, forcing carriers to accelerate retrofit programs rather than phase installations gradually. This regulatory pressure is restructuring supplier relationships and maintenance scheduling across the entire value chain.
Growth Catalysts
- ADS-B Out Mandate:FAA's 14 CFR 91.225 requires fleet-wide equipage for controlled airspace access, embedding recurring demand into airline maintenance schedules rather than selective new-aircraft fitment.
- Commercial Airline Fleet Modernization:Major carriers face compressed compliance deadlines that accelerate procurement of next-generation surveillance tools across aging narrow-body and wide-body aircraft.
- Unmanned Aerial Systems Expansion:GPS-Based architectures capture expanding share in drone platforms where size, weight, and power constraints predominate over traditional radar solutions.
Market Restraints
- Avionics Certification Costs:FAA TSO-C154c and TSO-C166b certification requirements impose substantial validation expenses that disproportionately burden regional operators and general aviation segments.
- Supply Concentration in RF Components:Specialized 1090 MHz and 978 MHz transceiver manufacturing concentrates among a limited supplier base, creating vulnerability to semiconductor foundry allocation decisions.
- Technical Limitation in Non-Cooperative Detection:Current TCAS and ADS-B systems cannot detect aircraft without operational transponders, leaving gaps in coverage for certain military and non-compliant general aviation traffic.
Strategic Opportunities
- Urban Air Mobility Integration:Emerging eVTOL and advanced air mobility platforms in the United States require purpose-built detect-and-avoid systems that merge radar, optical, and cooperative surveillance modalities.
- Business Aviation Retrofit Channel:Part 91 operators with legacy Mode C transponders represent an underpenetrated segment requiring compact, certified ADS-B solutions that minimize installation downtime.
- Convergence of AI and Sensor Fusion:Machine learning algorithms processing multi-source traffic data are enabling predictive conflict resolution that reduces nuisance alerts and improves pilot acceptance rates.
Industry Challenges
- Certified Software Engineer Scarcity:DO-178C compliance expertise remains concentrated among a limited workforce pool, extending development timelines for new algorithm deployments.
- Legacy System Integration Complexity:Retrofitting ADS-B capability into 1990s-era flight decks requires custom antenna placement, wiring harness modifications, and display interface adaptations that vary by aircraft type.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerospace & Aircraft Collision Avoidance System Market |
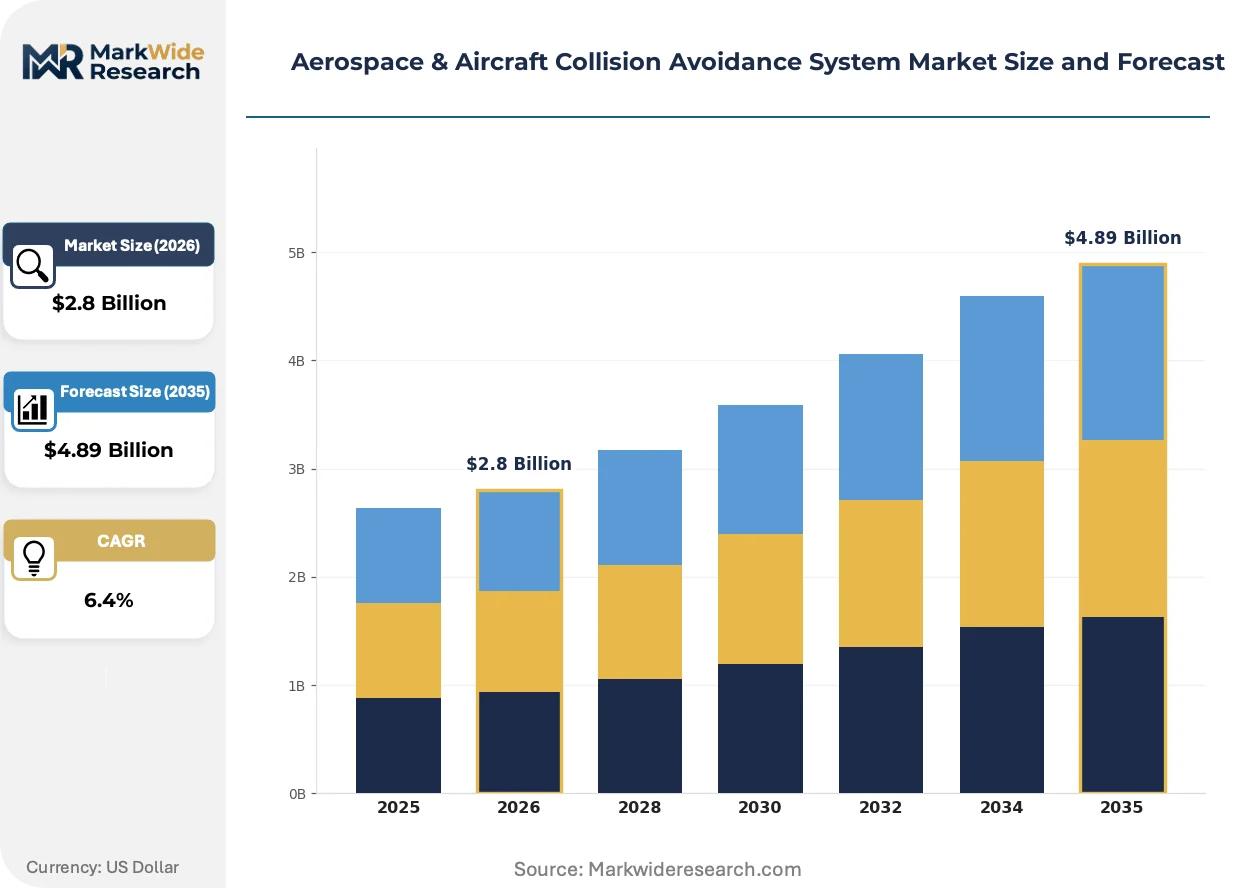
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traffic Collision Avoidance System, Ground Proximity Warning System, Automatic Dependent Surveillance-Broadcast, Radar Warning Receiver, Airborne Collision Avoidance System Technology: Radar-Based, GPS-Based, Infrared-Based, Ultrasonic, Optical Sensors Application: Commercial Airlines, Military Fighters, Business Jets, Unmanned Aerial Vehicles, Cargo Transport End User: Defense Agencies, Airlines, Private Jet Operators, Drone Manufacturers, Air Traffic Control Authorities |
| Companies Covered | Honeywell International Inc., Thales Group, Garmin Ltd., BAE Systems Plc, L3Harris Technologies Inc., Saab Group, Rockwell Collins Inc., Lockheed Martin Corporation, FLARM Technology Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerospace & Aircraft Collision Avoidance System Market Trends and Innovations
Surveillance technology architectures are bifurcating between cooperative systems that depend on equipped traffic and autonomous sensors that detect non-cooperative targets. This divergence is creating parallel development tracks with distinct certification pathways and buyer segments.
Multi-static primary radar networks are electrifying the detect-and-avoid landscape for unmanned platforms. These ground-based sensor arrays provide non-cooperative surveillance without airborne payload penalties. Urban air mobility developers in the United States are adopting this infrastructure-dependent model to bypass SWaP limitations. The technology is electrifying route certification possibilities for autonomous cargo drones that previously required expensive onboard radar.
EASA's CS-ACNS certification specifications are tightening equipage requirements for European-registered aircraft operating in single European sky airspace. Airlines must now demonstrate dual-frequency 1090ES and UAT capability for full operational credit. Narrow-body operators based in France and Germany are responding by bundling avionics upgrades with scheduled heavy maintenance checks to minimize revenue impact.
Airlines are consolidating avionics procurement under fleet-wide enterprise agreements rather than aircraft-by-aircraft transactions. This behavioral shift concentrates negotiating leverage with major carriers and compresses supplier margins. The phenomenon is most visible among US legacy network carriers managing mixed Boeing and Airbus fleets under unified surveillance standards.
Aerospace & Aircraft Collision Avoidance System Market Segmentation
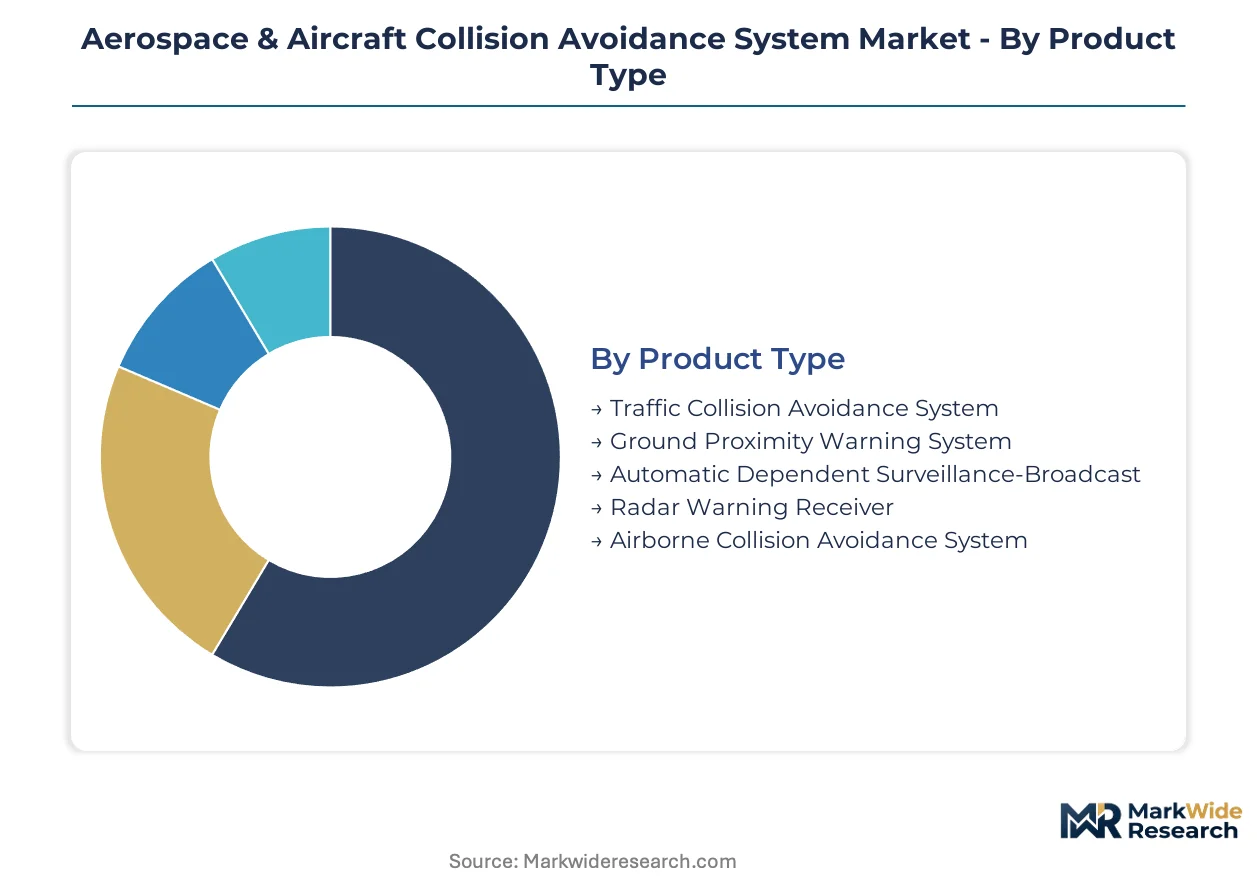
Collision avoidance procurement patterns diverge sharply across product architectures, sensor modalities, and operator categories. Fleet composition and regulatory equipage mandates reshape demand concentration within each segment boundary.
Product Type:
Capital intensity peaks with integrated flight-deck systems requiring extensive certification and antenna infrastructure, while modular retrofits demand lower upfront outlays.
- Traffic Collision Avoidance System:Mature 1090 MHz interrogator-transponder architecture generates resolution advisories through coordinated aircraft-to-aircraft communication. Commercial airlines in the United States absorb the majority of replacement demand as legacy TCAS II units approach obsolescence.
- Automatic Dependent Surveillance-Broadcast:GPS-derived position reporting with 978 MHz UAT and 1090ES dual-frequency capability. The FAA mandate under 14 CFR 91.225 compresses installation timelines across Part 121 and Part 135 operators.
- Ground Proximity Warning System:Terrain awareness processor using radar altimetry and database correlation.
- Radar Warning Receiver:Electronic warfare subsystem detecting hostile radar emissions.
- Airborne Collision Avoidance System:Integrated multi-sensor fusion platform with predictive algorithms.
Traffic Collision Avoidance System absorbs the bulk of installed capacity; Automatic Dependent Surveillance-Broadcast is expanding most quickly.
Technology:
Development cost structures separate field-proven radar architectures from emerging sensor modalities still navigating certification pathways.
- Radar-Based:Pulsed or continuous-wave RF emission with Doppler processing for range and velocity determination. Military fighters and commercial transport aircraft in the United States retain this technology for all-weather reliability.
- GPS-Based:Satellite navigation with augmentation systems enabling sub-10-meter position accuracy. Drone manufacturers favor this modality for minimal size, weight, and power penalties.
- Infrared-Based:Thermal signature detection for passive non-cooperative tracking.
- Ultrasonic:Short-range proximity sensing for terminal area maneuvering.
- Optical Sensors:Visible-spectrum and near-infrared cameras with machine vision processing.
Radar-Based technology commands the largest revenue pool; GPS-Based architectures show the steepest expansion trajectory.
Application:
Operational tempo and fleet renewal cycles determine procurement volume, with high-utilization segments amortizing equipage costs across more flight hours.
- Commercial Airlines:Scheduled passenger carriers operating under Part 121 with mandatory equipage requirements. Narrow-body operators face compressed retrofit windows as FAA deadlines approach.
- Unmanned Aerial Vehicles:Remotely piloted and autonomous platforms requiring detect-and-avoid capability for beyond-visual-line-of-sight operations. Urban air mobility developers in the United States drive specification evolution.
- Military Fighters:Manned combat aircraft with threat-agnostic situational awareness requirements.
- Business Jets:Part 91 and Part 135 operators with discretionary upgrade schedules.
- Cargo Transport:Dedicated freighter fleets with overnight operational patterns.
Commercial Airlines represent the dominant demand source; Unmanned Aerial Vehicles are climbing the fastest.
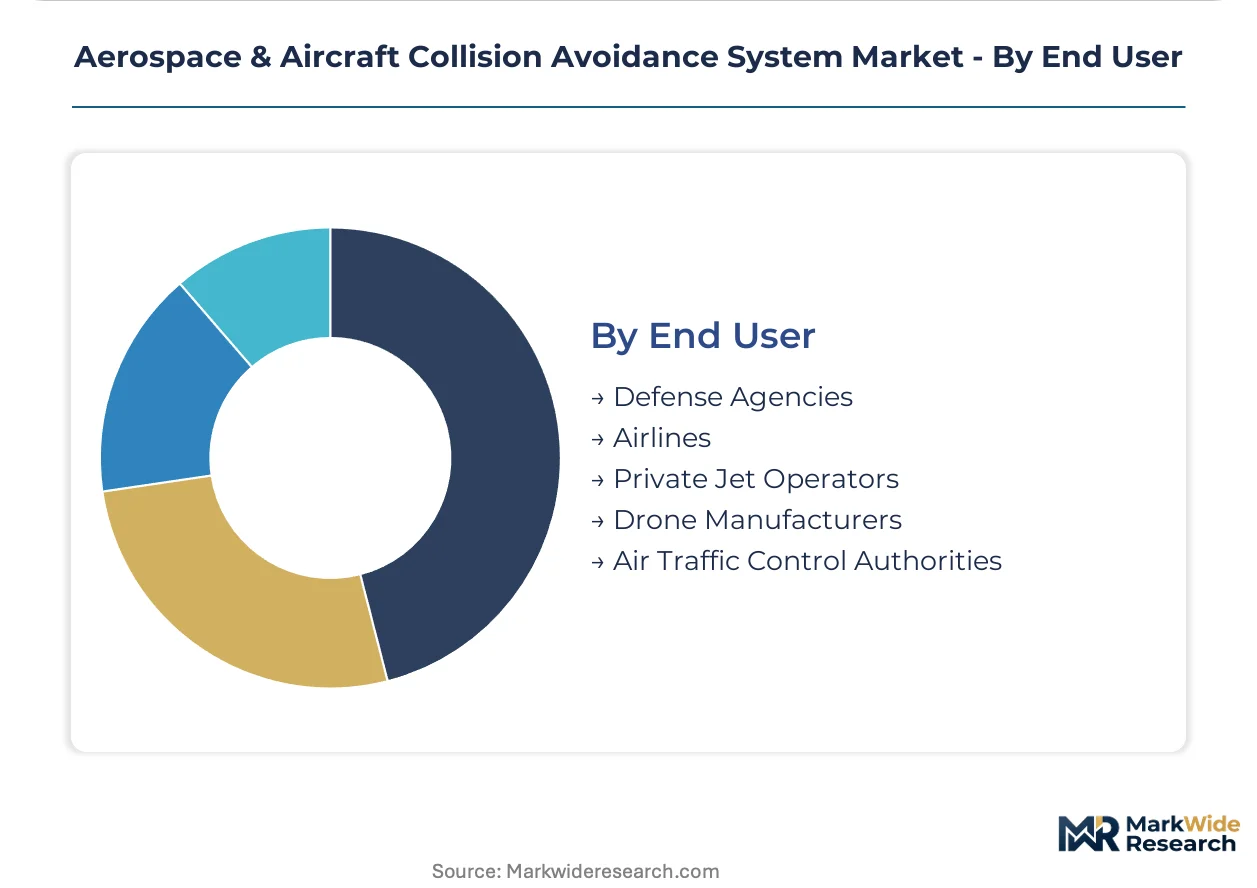
End User:
Budget authority and procurement sophistication vary across institutional buyers, from defense acquisition programs to individual owner-operators.
- Airlines:Network carriers with centralized fleet management and enterprise avionics agreements. Legacy US carriers bundle surveillance upgrades with heavy maintenance checks.
- Defense Agencies:Military procurement commands with platform-specific integration requirements. The US Department of Defense drives specifications for interoperable threat detection.
- Private Jet Operators:Fractional ownership and charter providers with fragmented decision-making.
- Drone Manufacturers:Original equipment designers integrating sense-and-avoid at the factory level.
- Air Traffic Control Authorities:Ground infrastructure operators deploying multi-static surveillance networks.
Airlines concentrate the majority of commercial procurement; Drone Manufacturers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon wafer fabrication for RF transceiver components concentrates in East Asian foundries, yet system integration and airworthiness certification gravitate toward established aerospace clusters in North America and Western Europe where regulatory agencies maintain primary jurisdiction.
United States
Major network carriers operate mixed Boeing and Airbus fleets requiring unified surveillance standards under FAA 14 CFR 91.225 mandates. The FAA compresses ADS-B Out equipage timelines for Part 121 operators, embedding recurring demand into heavy maintenance schedules. Seattle-Tacoma and Dallas-Fort Worth aerospace corridors host integration facilities where legacy flight decks undergo retrofit modification.
France
Thales Group anchors sovereign manufacturing capacity for radar and cooperative surveillance systems serving European narrow-body operators. EASA's CS-ACNS certification specifications tighten dual-frequency 1090ES and UAT requirements for single European sky access. Toulouse and Paris-Saclay clusters concentrate avionics engineering talent for next-generation fusion algorithms.
Germany
Lufthansa Technik and regional MRO providers bundle avionics upgrades with scheduled C-checks to minimize revenue impact from EASA compliance deadlines. The country's national aviation regulator enforces equipage verification through continued airworthiness management organizations. Bavaria's precision electronics sector supplies RF components for 1090 MHz transceiver modules.
United Kingdom
BAE Systems Plc maintains defense-oriented collision avoidance capabilities for Eurofighter and F-35 platform integration. The UK Civil Aviation Authority parallels EASA timelines for ADS-B equipage while preserving national regulatory autonomy post-Brexit. Farnborough and Broughton aerospace facilities specialize in military-specific threat detection architectures.
China
CAAC implements GB standards for domestic airspace access that parallel FAA and EASA cooperative surveillance mandates. COMAC's C919 program creates indigenous demand for integrated collision avoidance suites on new narrow-body aircraft. Shanghai and Xi'an aviation clusters develop domestic alternatives to foreign TCAS and ADS-B hardware.
Aerospace & Aircraft Collision Avoidance System Market Competitive Landscape
Long-term enterprise agreements dominate the current landscape as airlines consolidate avionics procurement under fleet-wide contracts rather than aircraft-by-aircraft transactions. The vendor base stratifies across three tiers: diversified conglomerates with integrated flight-deck portfolios, sovereign defense contractors with radar technology leadership, and compact-system specialists serving general aviation retrofit channels. Two competitive moves define current positioning: backward integration into RF component manufacturing to secure 1090 MHz transceiver supply, and strategic partnerships with urban air mobility developers for detect-and-avoid system co-development.
Among diversified conglomerates with integrated flight-deck portfolios, Honeywell International Inc. and Rockwell Collins Inc. exemplify the scale-driven archetype that anchors long-term airline contracts through comprehensive avionics suites. Thales Group occupies a position within the sovereign defense contractor tier, leveraging radar technology leadership and French manufacturing bases to serve European carrier requirements. Garmin Ltd. represents the compact-system specialist archetype, targeting business aviation and general aviation retrofit channels where installation downtime minimization drives purchasing decisions.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Thales Group |
| Garmin Ltd. |
| BAE Systems Plc |
| L3Harris Technologies Inc. |
| Saab Group |
| Rockwell Collins Inc. |
| Lockheed Martin Corporation |
| FLARM Technology Ltd |
| Others |
Pricing and Supply Chain Analysis
Legacy carrier fleet managers in the United States negotiate enterprise avionics contracts that embed long-term service commitments into upfront hardware pricing, compressing supplier margins through bundled procurement power. FAA compliance deadlines under 14 CFR 91.225 concentrate buyer leverage with narrow-body operators facing simultaneous retrofit obligations across hundreds of airframes.
Pricing Analysis
Warranty and field service bundling separates premium-tier suppliers from commodity transceiver vendors, with integrated flight-deck providers capturing extended maintenance contracts while modular retrofit specialists compete on installation speed. Certification grade under TSO-C154c and TSO-C166b specifications creates price stratification across FAA-validated hardware versus uncertified components. Cost compression in the general aviation channel intensifies as Garmin and compact-system specialists target Part 91 owner-operators with minimized downtime offerings. Regional carriers exhibit highest price sensitivity due to thin operating margins, whereas legacy network carriers prioritize fleet-wide standardization over unit cost minimization.
Supply Chain Analysis
Freight costs for specialized RF components from Taiwan and South Korean foundries elevate landed costs for 1090 MHz transceiver modules destined for North American integration facilities. Silicon wafer fabrication concentrates in East Asian semiconductor facilities, while antenna manufacturing draws from Bavarian precision electronics suppliers and Mexican cable assembly operations. Single-source vulnerability in 978 MHz UAT chipset supply creates exposure to foundry allocation decisions by major semiconductor contractors. Distribution runs through authorized avionics dealers and direct airline procurement channels, with heavy maintenance facilities in Seattle-Tacoma and Dallas-Fort Worth serving as final integration nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around suppliers with captive certification expertise and fleet-wide contract scale, as FAA mandate compression squeezes regional avionics vendors unable to absorb DO-178C compliance costs.
For Market Incumbents: Anticipate margin pressure from enterprise procurement consolidation by securing backward integration into 1090 MHz RF component manufacturing, insulating against semiconductor foundry allocation volatility. Lock long-term airline contracts through predictive algorithm R&D investments that reduce nuisance alert rates and improve pilot acceptance, defending against emerging sensor-fusion entrants targeting urban air mobility platforms. For New Entrants and Emerging Players: Enter via the business aviation retrofit channel where installation downtime sensitivity exceeds price elasticity, targeting Part 91 operators with legacy Mode C transponders requiring compact ADS-B solutions. Pursue strategic partnerships with eVTOL developers in the United States for detect-and-avoid system co-development, leveraging GPS-based architectures that bypass traditional radar certification pathways. For Investors and Strategic Acquirers: The window for entry favors vertically integrated mid-cap specialists with DO-178C software engineering benches and established FAA TSO relationships, positioned between diversified conglomerates and pure-play component vendors. Monitor EASA CS-ACNS certification timeline acceleration as the inflection signal for European narrow-body retrofit demand expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into RF Transceiver Manufacturing | Secures 1090 MHz supply against Taiwan and South Korean foundry allocation volatility. |
| AI-Driven Sensor Fusion Development | Enables predictive conflict resolution that reduces pilot nuisance alerts and improves acceptance. |
| Urban Air Mobility Partnership Formation | Positions suppliers for eVTOL detect-and-avoid specifications evolving under FAA oversight. |
| Enterprise Fleet-Wide Contract Consolidation | Concentrates negotiating leverage with US legacy carriers managing mixed Boeing and Airbus fleets. |
| Dual-Frequency 1090ES and UAT Certification Investment | Meets EASA CS-ACNS requirements for full operational credit in single European sky airspace. |
Research Methodology
Multi-period observation of FAA ADS-B equipage compliance rates, airline heavy maintenance scheduling patterns, and avionics OEM order backlogs anchored the trend analysis, supplemented by interviews with fleet engineering directors at major US network carriers, avionics procurement leads at regional airlines, MRO facility managers in Seattle-Tacoma and Dallas-Fort Worth corridors, and certification engineers at FAA-approved manufacturing facilities. Secondary validation drew from FAA 14 CFR 91.225 regulatory filings, EASA CS-ACNS certification databases, airline 10-K equipment expenditure disclosures, and semiconductor foundry capacity reports. Bottom-up segment sizing triangulated against top-down fleet equipage projections.
Segment-weighting approaches distributed value across product architectures, sensor modalities, and operator categories, with Technology and Application dimensions receiving differential coefficients based on unmanned platform expansion rates. Modeled projections spanned the analysis window with CAGRs derived from regulatory deadline impact curves and fleet age distribution analysis. Forecast inputs incorporated RF component lead time volatility and certified software engineer labor pool constraints.
Revisions become necessary when FAA mandate enforcement intensity shifts, EASA timeline acceleration occurs, or semiconductor foundry allocation crises disrupt 1090 MHz transceiver supply. Stakeholders should weight assumptions against their own operating context and fleet composition characteristics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Safety Systems
Helicopter Ice Protection Systems Market
Aircraft Safety Systems
Aircraft Ice Protection System Market
Aircraft Safety Systems
Global Aircraft Brakes Market
Aircraft Safety Systems
Helicopter Emergency Flotation System Market
Aircraft Safety Systems
Global Aircraft Brake System Market
Aircraft Safety Systems
Cloud-Connected Aircraft Safety Data Management Platforms Market
Aircraft Safety Systems
Aircraft Docking Systems Market
Aircraft Safety Systems
Airborne Lightning Detection System Market
Aircraft Safety Systems
Aircraft Door Dampers Market
Aircraft Safety Systems
Commercial Aircraft Carbon Brakes Market
Aircraft Safety Systems
Aircraft Arresting System Market
Aircraft Safety Systems
Military Aircraft Collision Avoidance Systems Market
Aircraft Safety Systems
Instrument Landing System (ILS) Market
Aircraft Safety Systems
Military Airborne Collision Avoidance Systems (ACAS) Market
Aircraft Safety Systems
Identification Friend or Foe Systems Market
Aircraft Safety Systems
Aircraft Evacuation Slide Market