
 Aircraft Survival Equipment Market | 2026-2036
Aircraft Survival Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Survival Equipment Market Outlook
Software-defined maintenance subscriptions is restructuring how survival equipment vendors capture lifetime value from military and commercial contracts. L3Harris Technologies, Inc. leverages its avionics heritage to bundle predictive diagnostics with beacon replacement cycles. Saab AB anchors its Nordic installed base through long-term fleet support agreements with Scandinavian air forces.
Aircraft survival equipment encompasses inflatable and rigid systems engineered to sustain aircrew life following ditching, ejection, or crash events, typically incorporating hydrostatic release mechanisms rated to depths exceeding 200 meters and 406 MHz satellite-linked distress signaling. The equipment serves to extend survival windows until rescue coordination centers achieve fix and dispatch. Emergency beacons and signaling equipment command premium pricing due to satellite constellation interoperability requirements and battery shelf-life mandates. Life rafts and floatation devices represent mature, volume-driven categories where procurement consolidation among airlines compresses margins.
FAA Technical Standard Orders govern emergency locator transmitter performance in US-registered aircraft, while EASA Certification Specifications impose equivalent requirements across European Union member states. NATO standardization agreements further harmonize military survival kit configurations across allied air forces. Stakeholders must monitor evolving satellite search-and-rescue architecture transitions from COSPAS-SARSAT to MEOSAR compatibility as a determinant of product obsolescence and retrofit demand.
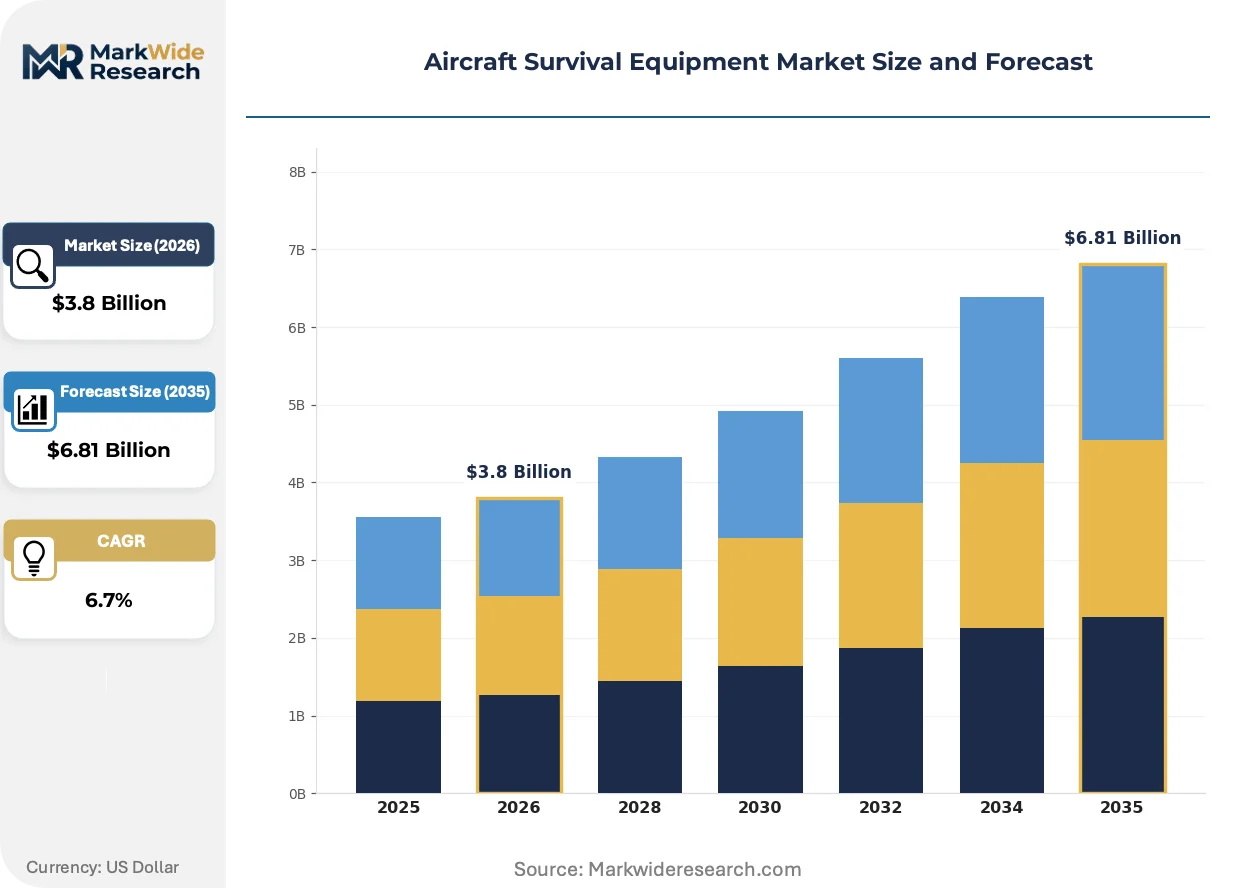
Market Dynamics
The transition from COSPAS-SARSAT to MEOSAR satellite architecture is forcing universal beacon replacement cycles across military and commercial fleets, compressing equipment lifespans and accelerating procurement velocity for satellite-interoperable distress signaling systems.
Growth Catalysts
- FAA Technical Standard Orders:Mandated 406 MHz ELT performance standards for US-registered aircraft are triggering fleet-wide retrofit programs among regional carriers and corporate aviation operators.
- MEOSAR compatibility:Next-generation satellite search-and-rescue infrastructure demands beacon hardware capable of mid-earth orbit signal processing, opening replacement demand across NATO-aligned air forces.
- Hydrostatic release mechanisms:Deep-water rating requirements exceeding 200 meters are differentiating premium survival equipment from commodity flotation devices in offshore helicopter operations.
Market Restraints
- Lithium battery supply concentration:Beacon battery shelf-life mandates tie equipment viability to cell chemistry sourced predominantly from East Asian manufacturers, creating single-source vulnerability.
- EASA Certification Specifications:Parallel but non-identical approval pathways with FAA TSOs impose duplicate testing burdens, extending time-to-market for dual-certified products.
- Airline procurement consolidation:Group purchasing organizations at major carriers compress margins on life rafts and flotation devices, commoditizing mature product categories.
Strategic Opportunities
- Software-defined maintenance:Predictive diagnostics subscriptions bundled with beacon replacement cycles capture lifetime value beyond initial hardware sales.
- Scandinavian fleet support agreements:Long-term service contracts with Nordic air forces anchor installed bases through multi-decade platform lifecycles.
- India defense modernization:Indigenous fighter and helicopter programs create demand for localized survival equipment production under offset requirements.
Industry Challenges
- MEOSAR certification timelines:Satellite constellation interoperability testing delays product launches by 18-24 months, straining R&D amortization schedules.
- Legacy beacon integration:Retrofit compatibility with aging aircraft electrical systems demands custom harness engineering, fragmenting production runs.
- Specialized survival systems engineering:Deep expertise in hydrostatic release mechanism design and satellite signaling protocols concentrates among retiring workforce cohorts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Survival Equipment Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Life Rafts, Survival Kits, Life Vests, Emergency Beacons Application: Commercial Aviation, Military Operations, General Aviation, Rescue Missions Technology: Inflatable Systems, Hydrostatic Releases, Floatation Devices, Signaling Equipment End User: Aerospace Manufacturers, Airlines, Military Agencies, Safety Organizations |
| Companies Covered | Elbit Systems Ltd., Thales Group, Northrop Grumman Corporation, L3Harris Technologies, Inc., Saab AB, BAE Systems plc, Safran, Leonardo S.p.A, RTX Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Survival Equipment Market Strategic Shifts
Digitalization of maintenance workflows and satellite architecture transitions are restructuring how survival equipment vendors capture value and how operators manage compliance across distributed fleets.
Next-generation emergency locator transmitters incorporating return-link service capability are electrifying beacon functionality, enabling rescue coordination centers to confirm distress signal receipt directly to aircrew. NATO procurement agencies are mandating this two-way capability in next-generation combat search-and-rescue specifications. The technology is electrifying competitive positioning by separating satellite-interoperable suppliers from legacy one-way beacon manufacturers.
EASA Certification Specification ETSO-C126b and FAA TSO-C126b harmonization efforts are reducing dual-approval friction for emergency locator transmitters across Atlantic markets. Manufacturers achieving synchronized certification gain 8-12 month market access advantages over competitors pursuing sequential approvals. European rotorcraft operators and US fractional ownership fleets represent the primary beneficiaries of streamlined type acceptance.
Airline technical purchasing departments are consolidating survival equipment procurement through integrated fleet management platforms, displacing fragmented spot-buying through maintenance-repair-overhaul intermediaries. This channel compression favors vendors offering multi-product catalogs spanning beacons, rafts, and signaling devices. The shift is most pronounced among low-cost carriers operating standardized narrow-body fleets across Southeast Asian and Middle Eastern hubs.
Aircraft Survival Equipment Market Segmentation
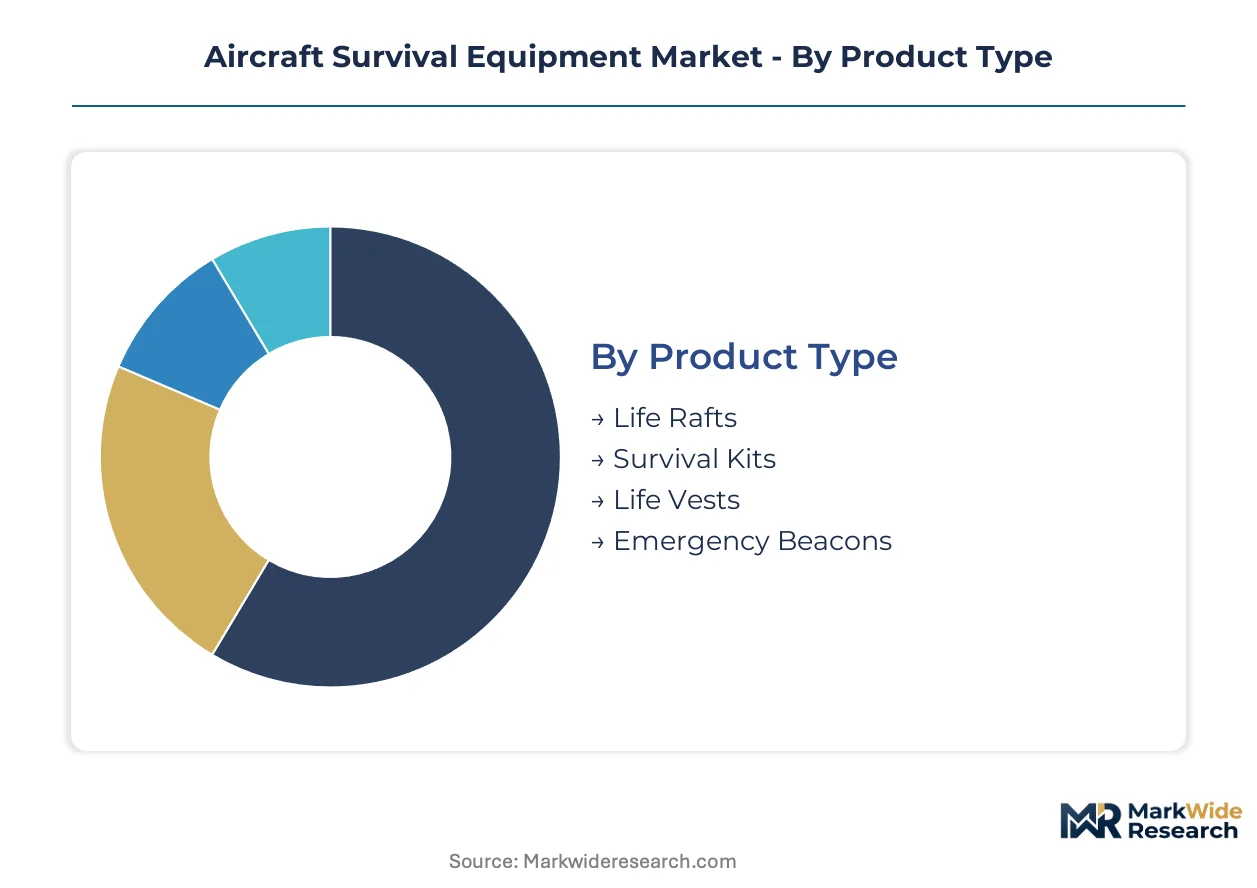
Segmentation in aircraft survival equipment reveals how procurement authority, technical certification requirements, and operational environment shape vendor-customer relationships across distinct buying centers.
Product Type:
Purchase decisions hinge on regulatory replacement cycles versus platform lifecycle durability.
- Emergency Beacons:These 406 MHz satellite-linked transmitters incorporate return-link service capability for two-way rescue confirmation. FAA and EASA mandates for MEOSAR compatibility are compressing replacement intervals across US and European fleets.
- Life Rafts:Multi-chamber inflatable systems rated for 200-meter hydrostatic release depths serve offshore helicopter operators in the North Sea and Gulf of Mexico. Consolidated airline procurement is squeezing margins on standard commercial configurations.
- Survival Kits:NATO-standardized packages combine signaling, medical, and sustenance modules for combat search-and-rescue missions.
- Life Vests:Inherently buoyant and inflatable variants address divergent requirements between overwater commercial routes and military ejection scenarios.
Volume sits with life rafts; growth tilts toward emergency beacons.
Application:
Operational tempo and crew risk exposure determine specification stringency and price elasticity.
- Military Operations:Combat search-and-rescue specifications demand MEOSAR-compatible beacons with return-link service, hydrostatic releases exceeding 200 meters, and NATO-standardized kit configurations. Procurement flows through defense agencies in the United States, United Kingdom, and Germany with multi-year fleet support agreements.
- Commercial Aviation:Scheduled carriers prioritize life raft fleet standardization and ELT retrofit compliance over feature differentiation. Low-cost carriers in Southeast Asia and the Middle East are consolidating procurement through integrated fleet management platforms.
- General Aviation:Fractional ownership and corporate operators seek streamlined dual FAA-EASA certification paths for beacon installations.
- Rescue Missions:Civil defense and coast guard agencies specify signaling equipment for coordinated multi-vessel operations.
Military operations absorb premium pricing; commercial aviation drives unit scale.
Technology:
Intellectual property concentration in signaling protocols and release mechanism engineering creates supplier stickiness.
- Signaling Equipment:Satellite constellation interoperability requirements and battery shelf-life mandates govern beacon viability. MEOSAR certification timelines extend product development cycles by 18-24 months, favoring incumbents with established testing relationships.
- Hydrostatic Releases:Deep-water rating requirements differentiate premium survival systems for offshore helicopter fleets operating in Norwegian and UK North Sea sectors.
- Inflatable Systems:Multi-chamber life raft architectures dominate commercial aviation procurement with mature manufacturing processes.
- Floatation Devices:Standardized life vests face commodity pricing pressure from consolidated airline technical purchasing.
Signaling equipment commands margin premiums; inflatable systems generate volume throughput.
End User:
Buying center structure—OEM specification, airline fleet management, or defense procurement—shapes contract terms and service attachment rates.
- Military Agencies:NATO standardization agreements harmonize survival kit configurations across allied air forces. Long-term fleet support agreements with Scandinavian defense ministries anchor installed bases through multi-decade platform lifecycles.
- Airlines:Group purchasing organizations at major carriers compress margins on life rafts and flotation devices. Technical departments are displacing MRO intermediaries through direct vendor relationships.
- Aerospace Manufacturers:OEMs specify survival equipment for new platform deliveries, with Indian indigenous fighter and helicopter programs creating localized production requirements under offset agreements.
- Safety Organizations:Civil aviation authorities and coast guard agencies influence certification standards and fleet retrofit mandates.
Airlines move the highest unit volumes; military agencies secure the longest contract tenures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of aircraft survival equipment concentrates among NATO-aligned defense industrial bases, while consumption spreads across commercial aviation hubs and military procurement agencies. The United States dominates both manufacturing and defense acquisition, with European and Asian markets following distinct regulatory and operational requirements.
United States
FAA Technical Standard Orders for 406 MHz ELT performance drive fleet-wide retrofit programs among regional carriers and corporate operators. The Pentagon's combat search-and-rescue specifications mandate MEOSAR-compatible beacons with return-link service for next-generation platforms. Defense contractors cluster around Washington DC, Florida, and California, where L3Harris Technologies anchors avionics integration and predictive diagnostics services.
Germany
EASA Certification Specifications impose equivalent distress signaling requirements across EU member states, with German aerospace regulators enforcing parallel testing protocols. The country's defense ministry participates in NATO standardization agreements harmonizing survival kit configurations across allied air forces. Industrial activity concentrates in Bavaria and Baden-Württemberg, where precision engineering capabilities support hydrostatic release mechanism production for offshore helicopter fleets.
United Kingdom
UK North Sea offshore helicopter operations generate specialized demand for life rafts rated to 200-meter hydrostatic release depths. The Civil Aviation Authority coordinates with EASA on beacon certification timelines, though post-Brexit regulatory divergence creates approval friction for dual-certified products. BAE Systems and related defense suppliers in Lancashire and Bristol sustain military survival equipment production for Royal Air Force platforms.
France
Safran and Thales Group anchor domestic production of satellite-interoperable signaling equipment serving both military and commercial segments. French regulators align with EASA mandates while maintaining national defense procurement autonomy through Direction Générale de l'Armement specifications. The Île-de-France region hosts avionics engineering clusters developing next-generation beacon architectures for MEOSAR compatibility.
India
Indigenous fighter and helicopter programs under the Ministry of Defence create localized production requirements through offset agreements. The Directorate General of Civil Aviation implements beacon certification standards converging with FAA and EASA frameworks. Defense manufacturing corridors in Maharashtra and Karnataka attract survival equipment vendors seeking multi-decade platform support contracts.
Aircraft Survival Equipment Market Competitive Environment
Top-tier vendors anchor defense procurement channels, while mid-tier specialists serve commercial aviation spot-buying and regional airline fleet standardization. The market exhibits tiered concentration with aerospace conglomerates controlling military contracts and independent manufacturers competing on life raft volume. Strategic archetypes include avionics-integrated platform providers, hydrostatic release engineering specialists, and consolidated inflatable system fabricators. Competitive moves center on long-term fleet support agreements and predictive diagnostics bundling.
Among defense-focused conglomerates, Elbit Systems Ltd., Thales Group, and Northrop Grumman Corporation exemplify tier-one positioning through multi-decade military platform relationships. These Israel-, France-, and US-based entities occupy positions spanning integrated avionics, satellite signaling protocols, and combat search-and-rescue system architecture. Their market presence reflects sustained R&D amortization across MEOSAR certification timelines and NATO standardization compliance.
| Leading Market Players |
|---|
| Elbit Systems Ltd. |
| Thales Group |
| Northrop Grumman Corporation |
| L3Harris Technologies, Inc. |
| Saab AB |
| BAE Systems plc |
| Safran |
| Leonardo S.p.A |
| RTX Corporation |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up specialists in inflatable systems have consolidated life raft manufacturing across France and Italy, compressing margins for commodity flotation devices while concentrating pricing power in premium hydrostatic release mechanisms for NATO defense contracts.
Pricing Analysis
Cost-down pressure on life rafts accelerates because airline group purchasing organizations in Southeast Asia and the Middle East have displaced MRO intermediaries with direct fleet management platforms. Three-tier pricing structure across MEOSAR-certified beacons, standard 406 MHz units, and legacy COSPAS-SARSAT hardware separates satellite-interoperable suppliers from commoditized one-way signal devices. Certification grade drives differentiation, with FAA-EASA dual approval commanding premium positioning over single-jurisdiction products. Commercial aviation technical departments exhibit highest price sensitivity, while military procurement agencies absorb premium pricing for return-link service capability.
Supply Chain Analysis
Indian domestic-content mandates under Ministry of Defence offset agreements are reshaping sourcing patterns for combat search-and-rescue kits, compelling foreign vendors to establish production corridors in Maharashtra and Karnataka. Lithium cell chemistry for beacon batteries draws from concentrated East Asian manufacturers, creating single-source vulnerability for shelf-life-dependent equipment. Hydrostatic release mechanism engineering rests on precision capabilities in Bavaria and Baden-Württemberg. Tariff exposure on satellite signaling components threatens margin structures. Distribution runs through defense procurement agencies for military contracts and integrated fleet management platforms for commercial carriers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into predictive diagnostics software represents the decisive upstream lever, as L3Harris and Saab demonstrate through maintenance subscription bundling that extends revenue capture beyond hardware replacement cycles.
For Market Incumbents: To counter MEOSAR certification timeline delays that strain R&D amortization, anchor installed bases through multi-decade fleet support agreements with Scandinavian defense ministries and deepen backward integration into battery cell supply through captive partnerships with East Asian manufacturers. For New Entrants and Emerging Players: Enter via white-space targeting of Indian indigenous fighter and helicopter programs under offset localization requirements, where foreign-established production corridors face limited domestic competition. Pursue coast guard and civil defense agencies in rescue missions as the most penetrable application segment, leveraging streamlined single-jurisdiction certification paths. For Investors and Strategic Acquirers: Distressed-cycle entries favor hydrostatic release engineering specialists with deep-water rating capabilities in the UK North Sea sector, where offshore helicopter operator consolidation creates acquisition opportunities. Watch MEOSAR satellite constellation interoperability testing completion as the inflection signal distinguishing viable beacon architectures from stranded legacy inventory.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Diagnostics Subscription Bundling | L3Harris leverages avionics heritage to capture lifetime value beyond beacon replacement cycles. |
| Dual FAA-EASA Certification Harmonization | Manufacturers achieving synchronized approval gain market access advantages over sequential applicants. |
| Indian Offset Localization Production | Foreign vendors establish Maharashtra and Karnataka corridors to satisfy Ministry of Defence requirements. |
| MEOSAR-Compatible Beacon Development | Return-link service capability separates NATO-compliant suppliers from legacy one-way manufacturers. |
| Long-Term Fleet Support Agreements | Saab anchors Nordic installed bases through multi-decade Scandinavian air force platform lifecycles. |
Study Parameters
Document review covered FAA Technical Standard Orders, EASA Certification Specifications, and NATO standardization agreements, complemented by interviews with defense procurement officers, airline technical purchasing directors, beacon engineering leads, and MRO platform managers. Secondary validation drew from COSPAS-SARSAT satellite architecture documentation, hydrostatic release mechanism patent filings, and customs trade data on lithium battery cell imports. Bottom-up equipment unit forecasting triangulated against top-down defense aviation spending allocations.
Segmentation outputs reflect product type, application, technology, and end-user dimensions modeled across the projection horizon. CAGRs were derived from procurement velocity analysis tied to regulatory replacement cycle mandates and satellite infrastructure transition timelines. Forecast inputs incorporated MEOSAR certification pipeline delays and airline fleet standardization patterns.
Forecast precision tightens around the base case; tail outcomes carry wider variance under lithium supply disruption or MEOSAR constellation deployment delays. Forecasts reflect assumptions on regulatory harmonization progress and defense budget continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Safety Systems
Free Fall Sensor Market
Aircraft Safety Systems
Military Airborne Collision Avoidance Systems (ACAS) Market
Aircraft Safety Systems
Aircraft Evacuation Slide Market
Aircraft Safety Systems
Aircraft Door Dampers Market
Aircraft Safety Systems
Aircraft Docking Systems Market
Aircraft Safety Systems
Airborne Lightning Detection System Market
Aircraft Safety Systems
Aircraft Smoke Detection and Fire Extinguishing System Market
Aircraft Safety Systems
Military Aircraft Collision Avoidance Systems Market
Aircraft Safety Systems
Identification Friend or Foe Systems Market
Aircraft Safety Systems
Instrument Landing System (ILS) Market
Aircraft Safety Systems
South Korea Aircraft Windshield Wiper and Washer System Market
Aircraft Safety Systems
Aerospace & Aircraft Collision Avoidance System Market
Aircraft Safety Systems
Commercial Aircraft Evacuation System Market
Aircraft Safety Systems
Aircraft Fire Protection Systems Market
Aircraft Safety Systems
Rescue Hoist System Market
Aircraft Safety Systems
Helicopter Ice Protection Systems Market