
 Global Aircraft Brake System Market | 2026-2036
Global Aircraft Brake System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Aircraft Brake System Market Foresight
Electromechanical actuation is reconfiguring how aircraft brake systems integrate with fly-by-wire architectures and centralize control authority. Safran Landing Systems leverages its European manufacturing footprint to sustain long-term supply agreements with Airbus. Honeywell International Inc. dominates the North American aftermarket through its dense MRO service network.
Aircraft brake systems are friction-based energy dissipation assemblies that convert kinetic energy into thermal energy during landing and rejected takeoff, typically employing carbon-carbon composite discs rated for temperatures exceeding 1,500°C to withstand repeated thermal cycling. The primary commercial purpose is to ensure safe deceleration within runway length constraints while minimizing wear and maintenance intervals. Electromechanical systems are capturing share from hydraulic architectures as airlines prioritize weight reduction and reduced fluid maintenance. Commercial aircraft types anchor the largest revenue pool, though business jet retrofits represent the fastest-growing installation segment as fractional ownership fleets age.
FAA airworthiness directives and EASA certification standards govern brake system approval, with both regulators mandating rigorous dynamometer testing and thermal overload demonstration before fleet entry. The EU Green Deal's aviation decarbonization targets are pressuring OEMs to design lighter brake assemblies that reduce fuel burn across flight profiles. Stakeholders must monitor how brake-by-wire architectures alter liability structures between airframers and tier-one suppliers as control authority shifts from mechanical to electronic domains.
Market Dynamics
Electromechanical brake-by-wire architectures are displacing hydraulic systems as the dominant control paradigm, compressing maintenance intervals and redistributing liability between airframers and tier-one suppliers across certification regimes.
Growth Catalysts
- EU Green Deal aviation targets:Mandates for reduced fuel burn are accelerating adoption of lighter carbon-carbon composite brake assemblies in narrow-body fleets operating European routes.
- Commercial fleet expansion:Aircraft deliveries to low-cost carriers in India and Southeast Asia are expanding the installed base requiring aftermarket brake services.
- FAA certification harmonization:Streamlined approval pathways for brake system upgrades are reducing time-to-market for next-generation thermal management designs.
Market Restraints
- Raw material concentration:Specialty carbon fiber precursors for disc manufacturing concentrate among Japanese and US chemical suppliers, creating input cost volatility.
- Certification timeline friction:EASA dynamometer testing requirements extend development cycles for new brake architectures by 18-24 months versus legacy approvals.
- Technical thermal limits:Current carbon-carbon composites face degradation thresholds above 1,650°C that constrain rejected takeoff performance margins for wide-body aircraft.
Strategic Opportunities
- Urban air mobility integration:Electric vertical takeoff and landing platforms require dedicated lightweight brake systems with rapid thermal dissipation profiles.
- India defense modernization:Indigenous fighter programs under the country's military procurement framework are opening localized brake system sourcing requirements.
- Predictive maintenance convergence:Brake-wear sensors combined with fleet analytics platforms enable condition-based replacement contracts versus fixed-interval overhauls.
Industry Challenges
- Electromechanical system integration:Fly-by-wire brake architectures demand software certification expertise that legacy hydraulic specialists lack, creating talent acquisition bottlenecks.
- Legacy fleet retrofit complexity:Aging Boeing 737NG and Airbus A320ceo platforms require structural modifications to accommodate brake-by-wire upgrades, extending downtime windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Aircraft Brake System Market |
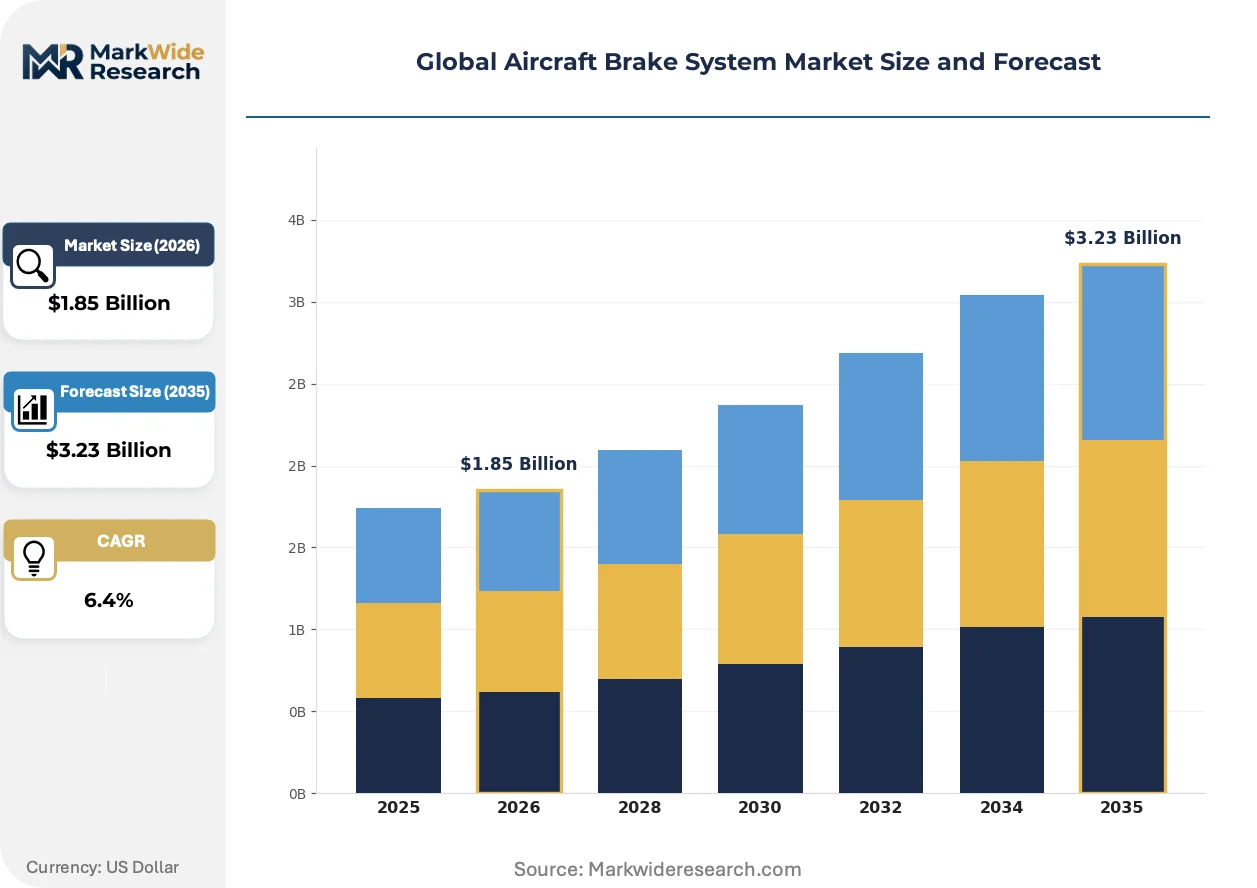
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic, Electromechanical, Pneumatic, Brake-by-wire Aircraft Type: Commercial, Military, Business Jet, Helicopter Installation Type: Retrofitting, Line Fit, Modular, System Upgrade End User: OEMs, Maintenance Repair Overhaul (MRO), Fleet Operators, Defense Contractors |
| Companies Covered | Honeywell International Inc., Safran Landing Systems, Collins Aerospace, Parker-Hannifin Corporation, Crane Aerospace & Electronics, Raytheon Technologies Corporation, Meggitt plc, Beringer Aero, Grove Aircraft Landing Gear Systems Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Aircraft Brake System Market Shifts & Advancements
Brake system evolution centers on three vectors: control architecture digitization, material thermal performance advancement, and aftermarket service model restructuring. Each trajectory carries distinct competitive implications for OEMs and MRO providers.
Carbon-carbon composite brake discs are migrating from hydraulic to electromechanical actuation environments. Narrow-body operators in North America and Europe are retrofitting brake-by-wire systems during scheduled landing gear overhauls. This migration from mechanical to electronic control authority is compressing maintenance intervals while redistributing warranty liability toward software-integrated suppliers.
EASA certification standards for thermal overload demonstration have tightened dynamometer testing protocols. Brake manufacturers must now document performance across expanded temperature ranges before fleet entry approval. Wide-body programs serving trans-Pacific routes face the steepest compliance adjustments, with OEMs redesigning heat sink geometries to meet revised heat flux requirements.
Airline procurement teams are unbundling brake system acquisition from long-term MRO contracts. Low-cost carriers in Southeast Asia now source hardware from OEMs while negotiating separate service agreements with independent maintenance providers. This pattern is most visible in Indonesia and Vietnam, where rapid fleet growth has fragmented supplier relationships and compressed contract renewal cycles.
Global Aircraft Brake System Market Segmentation
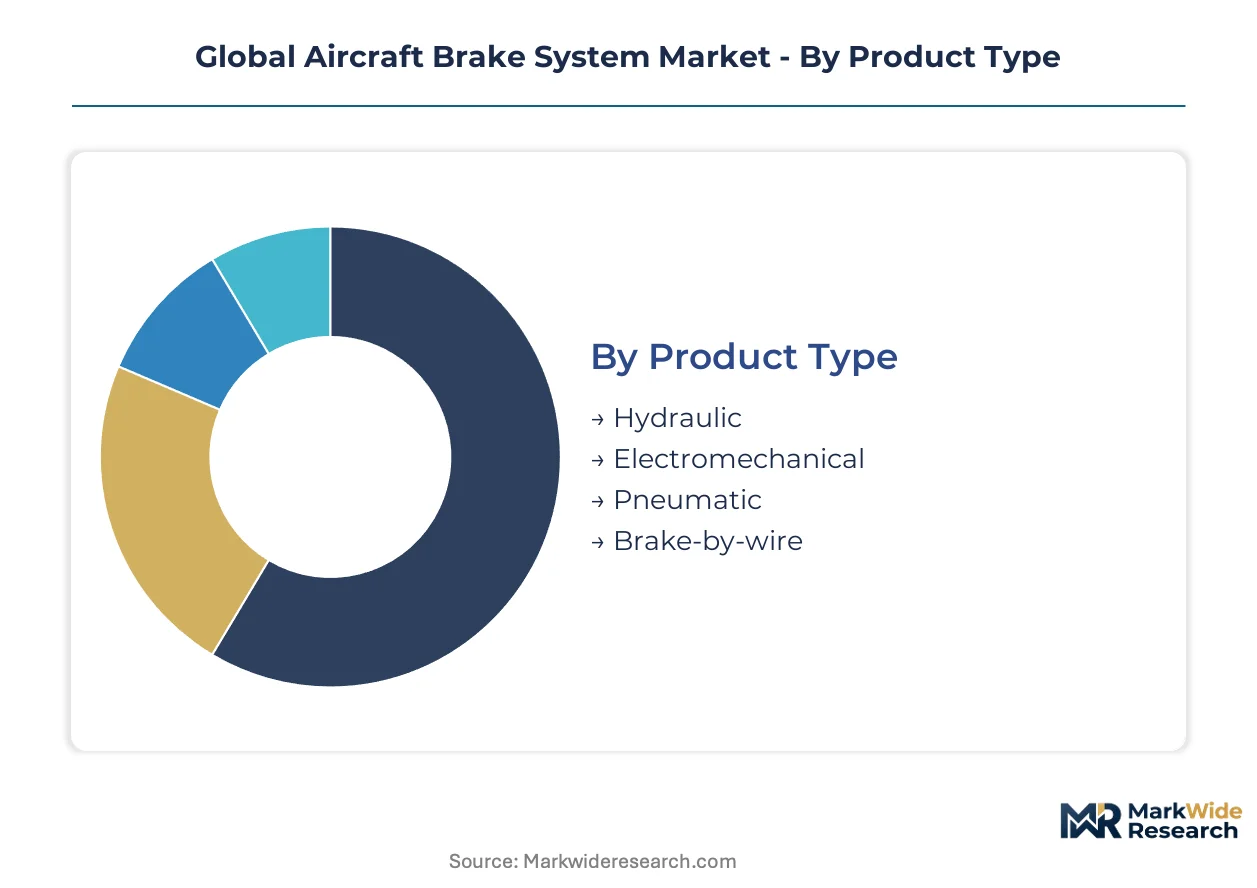
Aircraft brake system segmentation reveals how technology migration, fleet composition, and procurement restructuring are fragmenting traditional supply relationships. Each dimension captures distinct value migration patterns between hydraulic incumbents and electromechanical challengers.
Product Type:
The use-case spectrum spans legacy hydraulic architectures through fully digitized brake-by-wire platforms, with thermal management requirements and maintenance economics driving portfolio decisions across fleet types.
- Electromechanical:Motor-driven actuation eliminates hydraulic fluid circuits and compresses scheduled maintenance intervals. Narrow-body operators in the United States and Germany are retrofitting these systems during landing gear overhauls to reduce turnaround downtime and simplify line maintenance procedures.
- Brake-by-wire:Fully electronic control architectures integrate with fly-by-wire flight control systems, centralizing brake authority in cockpit computers. Airbus A320neo and Boeing 787 line-fit programs specify these configurations for weight reduction and reduced pilot workload during autobrake operations.
- Hydraulic:Conventional fluid-powered systems dominate legacy fleet installed bases requiring minimal modification.
- Pneumatic:Compressed-air actuation persists in regional turboprop applications where system simplicity outweighs precision requirements.
The dominant share belongs to Hydraulic systems, while Electromechanical configurations are closing the gap fastest.
Aircraft Type:
Cost tier segmentation separates high-cycle commercial operations from low-volume defense programs with divergent thermal performance and certification requirements.
- Commercial:Narrow-body and wide-body platforms operating 8-12 daily cycles demand carbon-carbon composite discs rated for temperatures exceeding 1,500°C. Low-cost carriers in India and Southeast Asia are expanding aftermarket brake procurement as fleet utilization rates climb above global averages.
- Business Jet:Fractional ownership fleets and corporate flight departments prioritize reduced maintenance intervals over absolute thermal capacity. Embraer Phenom and Bombardier Challenger retrofit programs represent concentrated demand pockets as pre-2010 airframes age into heavy maintenance events.
- Military:Fighter and transport programs specify hardened brake systems for unimproved runway operations with foreign object damage tolerance.
- Helicopter:Rotorcraft brake requirements concentrate on parking and emergency functions rather than rejected takeoff scenarios.
Commercial aviation commands the largest revenue pool, though Business Jet retrofits are expanding most quickly.
Installation Type:
Customer type preferences split between original equipment manufacturers seeking design integration and aftermarket operators minimizing aircraft downtime.
- Line Fit:Factory-installed brake systems at final assembly allow OEMs to optimize thermal management with landing gear geometry. Boeing and Airbus procurement teams negotiate multi-year supply agreements covering entire aircraft families.
- Retrofitting:In-service brake replacements and technology upgrades occur during scheduled C-check intervals. Independent MRO providers in Singapore and the United Arab Emirates are capturing retrofit volume from airline-affiliated maintenance units.
- System Upgrade:Architecture conversions from hydraulic to electromechanical control demand structural modifications and software recertification.
- Modular:Pre-assembled brake units enable rapid line replacement with minimal specialized tooling.
Line Fit installations hold the dominant position, while Retrofitting activity is gaining share fastest as fleet age profiles deepen.
End User:
Supply concentration varies sharply between captive OEM production and fragmented independent maintenance networks.
- OEMs:Airframe manufacturers specify brake systems during aircraft design and control initial fleet configuration. Safran Landing Systems and Honeywell International maintain long-term supply agreements covering multiple aircraft programs with pricing indexed to production rate commitments.
- Maintenance Repair Overhaul (MRO):Independent and airline-affiliated service providers manage brake overhauls, disc replacements, and thermal stack refurbishment. FAA Part 145 and EASA Part 145 certified facilities in the United States, Germany, and China compete for aftermarket volume through turnaround time guarantees.
- Fleet Operators:Airlines and leasing companies are unbundling hardware procurement from service contracts, sourcing brakes directly from manufacturers while negotiating separate maintenance agreements.
- Defense Contractors:Military procurement frameworks specify domestic content requirements and security-cleared production facilities.
OEMs retain the dominant share, though MRO providers are climbing the fastest as airlines fragment supplier relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Airline procurement teams and MRO service providers concentrate brake system demand across three distinct geographies: the United States for its massive installed fleet base, Germany for its precision manufacturing ecosystem, and China for its expanding domestic aviation market. Each territory presents unique certification requirements and supply chain configurations.
United States
Commercial carriers operating Boeing and Airbus fleets generate sustained aftermarket brake demand through high-cycle utilization rates. FAA airworthiness directives govern brake system approvals, with Part 145 certified facilities concentrated in Dallas-Fort Worth and Atlanta. These clusters handle thermal stack refurbishment for narrow-body operators prioritizing turnaround speed.
Germany
Lufthansa Technik and independent MRO providers anchor European brake overhaul capacity for carbon-carbon composite discs. EASA certification standards mandate rigorous dynamometer testing, extending development timelines for new thermal management designs. The Hamburg aviation cluster specializes in wide-body brake system integration with landing gear overhaul programs.
China
Domestic fleet expansion by COMAC and imported Boeing and Airbus aircraft is accelerating brake procurement from local MRO networks. The country's national aviation regulator enforces certification alignment with international standards while promoting indigenous supplier development. Shanghai and Beijing host the densest concentrations of brake system warehousing and distribution infrastructure.
India
Low-cost carriers including IndiGo and SpiceJet are expanding narrow-body fleets at rates exceeding global averages, driving aftermarket brake volume. The Directorate General of Civil Aviation oversees type certification and airworthiness approvals for imported brake systems. Mumbai and Delhi-NCR serve as primary logistics hubs for brake disc imports and redistribution to regional maintenance stations.
United Arab Emirates
Emirates and Etihad Airways operate some of the world's largest wide-body fleets, generating concentrated demand for high-capacity brake systems rated for extreme thermal loads. The General Civil Aviation Authority regulates brake system approvals with standards harmonized to EASA frameworks. Dubai International Airport's free zone hosts specialized landing gear and brake overhaul facilities serving transit traffic across Africa and South Asia.
Global Aircraft Brake System Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a market structure consolidating around tier-one aerospace suppliers with captive airline relationships and long-term OEM supply agreements. The vendor base separates into three strategic archetypes: full-system integrators commanding airframer line-fit contracts, component specialists dominating aftermarket thermal stack refurbishment, and regional MRO service providers capturing retrofit installation volume. Competitive moves center on vertical integration into carbon fiber precursor supply and strategic partnerships with emerging urban air mobility platforms.
Among North American-based conglomerates, Honeywell International Inc., Collins Aerospace, and Parker-Hannifin Corporation occupy positions spanning the full-system integrator archetype. Honeywell exemplifies the channel-controlling model through dense MRO service networks, while Collins Aerospace represents the aerospace-division consolidation pattern within larger industrial portfolios. Parker-Hannifin sits within the motion-control specialization tier, with its corporate structure reflecting diversified industrial exposure rather than pure-play aviation focus. These three entities collectively anchor the competitive landscape through their representation of scale-driven, diversified, and specialist strategic positions.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Safran Landing Systems |
| Collins Aerospace |
| Parker-Hannifin Corporation |
| Crane Aerospace & Electronics |
| Raytheon Technologies Corporation |
| Meggitt plc |
| Beringer Aero |
| Grove Aircraft Landing Gear Systems Inc. |
| Others |
Supply & Pricing Matrix
Undercapacity in Japanese carbon fiber precursor manufacturing is tightening feedstock availability and amplifying pricing power among specialty chemical suppliers serving brake disc foundries.
Pricing Analysis
Cost-plus contracts with petroleum-based indexation dominate brake system procurement between OEMs and tier-one suppliers. Price differentiation rests on EASA certification tier and fleet volume scale, with narrow-body operators commanding steeper discounts than wide-body programs. Pricing pressure stems from raw material volatility in acrylonitrile feedstocks, compressing margins for non-integrated manufacturers. Low-cost carriers in Southeast Asia exhibit highest price sensitivity, while flag carriers in Germany and the United States prioritize thermal performance over unit cost.
Supply Chain Analysis
Upstream polyacrylonitrile fiber production concentrates in Japan, the United States, and Germany, with Toray and Mitsubishi Chemical anchoring global precursor capacity. Brake disc manufacturing draws from specialty carbon fiber, phenolic resin binders, and precision-machined steel housings. Single-source vulnerability in Japanese precursor supply creates exposure to trade route disruptions and currency fluctuation. Distribution runs through OEM captive networks for line-fit programs, while independent MRO providers source via regional warehousing hubs in Singapore and Dubai.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brake-by-wire electrification represents a high-growth disruption, with FAA-EASA harmonization on software certification standards creating a regulatory inflection point for control architecture migration.
For Market Incumbents: Pre-empt emerging specialist encroachment by securing captive carbon fiber precursor supply through backward integration or long-term offtake agreements with Japanese chemical suppliers. Accelerate software certification capabilities to capture brake-by-wire liability shifts from hydraulic incumbents. Channel control through MRO network density remains defensible against independent service providers.
For New Entrants and Emerging Players: Establish a beachhead in urban air mobility brake systems, where thermal dissipation requirements for electric vertical takeoff platforms remain undefined and incumbent lock-in is weakest. Target Indian defense modernization programs with localized production commitments satisfying indigenous content mandates. Pursue predictive maintenance partnerships with fleet analytics platforms as a go-to-market angle bypassing traditional OEM sales cycles.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among MRO service providers with condition-based maintenance contracts, offering superior cash-flow predictability versus hardware-dependent OEMs. Acquisition targets should display software-integrated brake system portfolios and EASA Part 145 certification breadth. Monitor brake-wear sensor data monetization rates as the signal to watch for predictive maintenance adoption inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Fiber Precursor Backward Integration | Captive acrylonitrile supply secures margin protection against Japanese chemical supplier pricing power. |
| Brake-by-Wire Software Certification Investment | EASA ED-12C compliance opens line-fit contracts on Airbus A320neo and Boeing 787 programs. |
| Urban Air Mobility Brake System Development | Dedicated lightweight thermal management designs capture emerging eVTOL platform specifications. |
| Predictive Maintenance Platform Partnership | Brake-wear sensor data integration with fleet analytics enables condition-based replacement contracts. |
| Indian Defense Localization Facility | Domestic production alignment with indigenous fighter procurement frameworks opens military sourcing. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FAA airworthiness directives, EASA certification standards, and OEM procurement disclosures. Primary interviews engaged brake system engineering directors, MRO facility managers, airline fleet procurement officers, and carbon fiber supply specialists. Secondary validation drew from SEC 10-K filings of listed aerospace suppliers, trade customs data on carbon fiber precursor imports, and dynamometer testing protocol documentation. Bottom-up fleet demand modeling and top-down OEM production rate triangulation anchored market size estimation.
Forecast inputs span commercial aircraft delivery schedules, MRO visit interval compression from brake-by-wire adoption, and regional fleet utilization rates across the projection horizon. Segmentation dimensions include actuation architecture, aircraft platform category, installation type, and end-user procurement structure. CAGRs were derived from installed base expansion and technology replacement cycle analysis. Industry-specific inputs incorporate EASA thermal overload testing timeline extensions and EU Green Deal weight reduction mandates.
Stress conditions across carbon fiber precursor supply disruption, FAA certification timeline delays, and wide-body fleet retirement acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on technology migration rates and regulatory harmonization progress. Cross-checking against IATA fleet forecasts and OEM published delivery guidance is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Safety Systems
Commercial Aircraft Carbon Brakes Market
Aircraft Safety Systems
Aircraft Survivability Equipment Market
Aircraft Safety Systems
Airborne Collision Avoidance System Market
Aircraft Safety Systems
Commercial Parachute Market
Aircraft Safety Systems
Cloud-Connected Aircraft Safety Data Management Platforms Market
Aircraft Safety Systems
Identification Friend or Foe Systems Market
Aircraft Safety Systems
Commercial Aircraft Collision Avoidance System Market
Aircraft Safety Systems
Airborne Lightning Detection System Market
Aircraft Safety Systems
Aviation Life Rafts Market
Aircraft Safety Systems
Aircraft Survival Equipment Market
Aircraft Safety Systems
Military Airborne Collision Avoidance Systems (ACAS) Market
Aircraft Safety Systems
Helicopter Ice Protection Systems Market
Aircraft Safety Systems
Aerospace & Aircraft Collision Avoidance System Market
Aircraft Safety Systems
Helicopter Emergency Flotation System Market
Aircraft Safety Systems
Aircraft Fire Protection Systems Market
Aircraft Safety Systems
Instrument Landing System (ILS) Market