
 Cloud-Connected Aircraft Safety Data Management Platforms Market | 2026-2036
Cloud-Connected Aircraft Safety Data Management Platforms Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud-Connected Aircraft Safety Data Management Platforms Market Insights
Multi-source data aggregation from flight recorders, ground sensors, and satellite feeds is restructuring how operators manage safety intelligence. GE Aerospace leverages its digital aviation portfolio to anchor cloud-native analytics for engine and airframe health monitoring. Honeywell sustains competitive pressure through specialized avionics integration that bridges legacy aircraft with modern data pipelines. Safran competes by dominating the European regulatory compliance segment with platforms aligned to EASA certification requirements.
Cloud-connected aircraft safety data management platforms comprise distributed software architectures that ingest, normalize, and analyze flight operational quality assurance data through satellite communication and air-to-ground network links, typically processing parameters at millisecond resolution to enable real-time anomaly detection. These systems serve airlines, manufacturers, and aviation safety authorities by centralizing incident reporting, risk analysis, and predictive maintenance workflows across heterogeneous fleets. Real-time monitoring platforms occupy the largest deployment share due to regulatory mandates for continuous flight data access, while predictive maintenance modules represent the fastest-expanding segment as carriers seek to convert unplanned repairs into scheduled interventions. Cloud-based deployment leads in new installations, though hybrid cloud configurations retain significant share among operators with stringent data sovereignty requirements.
The FAA's Safety Management System directive and EASA's equivalent framework shape platform requirements by mandating standardized data formats and audit trails for safety-critical events. ISO 27001 and IEC 62443 certifications function as de facto market access prerequisites for vendors serving defense-adjacent aviation segments. Stakeholders must monitor evolving cybersecurity standards from the FAA and EASA, as cloud-connected architectures expand attack surfaces that regulators are actively addressing through mandatory incident disclosure protocols.
Market Dynamics
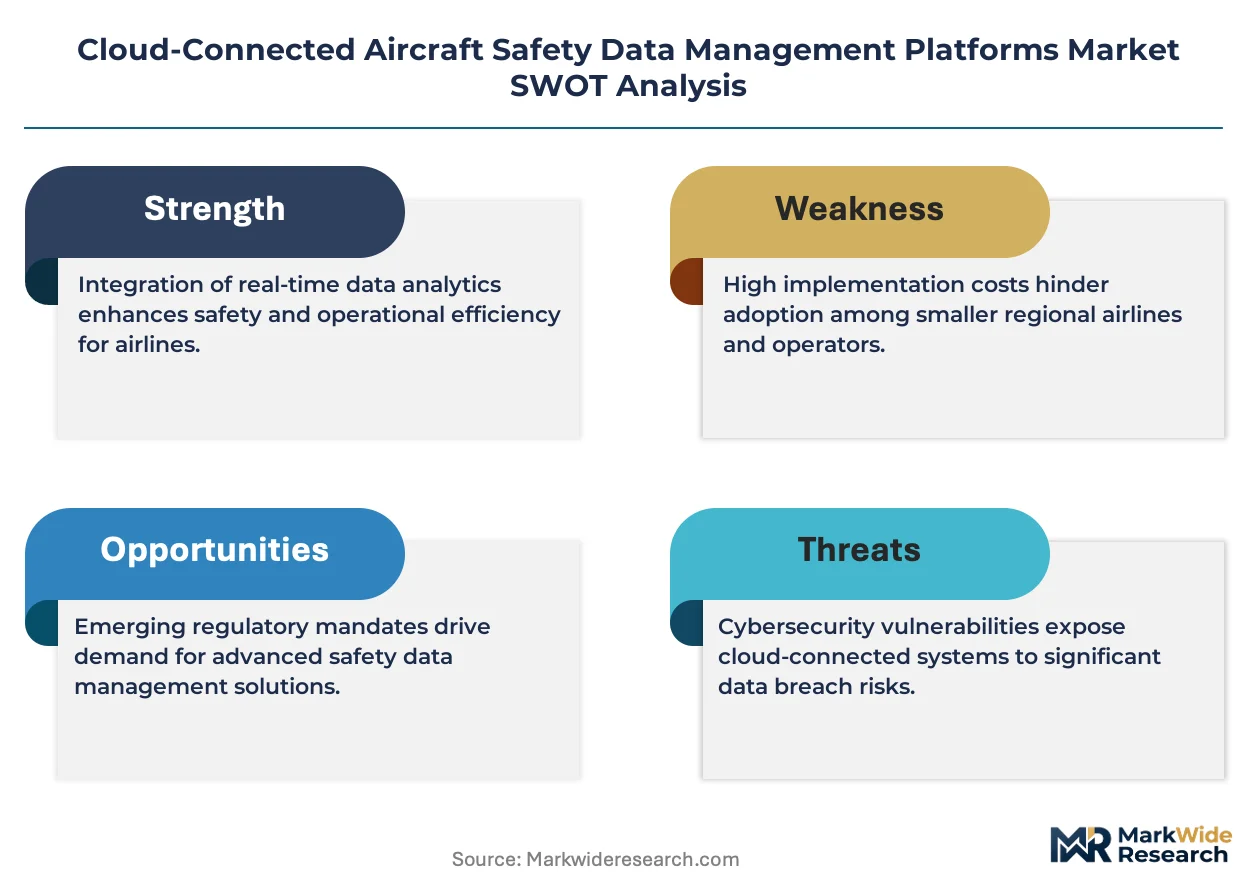
Regulatory mandates from the FAA and EASA are compressing platform standardization timelines while forcing airlines to consolidate fragmented safety data architectures onto unified cloud infrastructures.
Growth Catalysts
- FAA Safety Management System mandate:Airlines operating in United States airspace must deploy standardized data formats and audit trails, creating immediate platform procurement requirements.
- Predictive maintenance algorithms:Machine learning models processing millisecond-resolution flight parameters enable carriers to convert unplanned repairs into scheduled interventions.
- Satellite communication bandwidth expansion:Low Earth orbit constellations are reducing air-to-ground data transmission costs for real-time anomaly detection.
Market Restraints
- Data sovereignty requirements:Operators in Germany and France mandate hybrid cloud configurations that fragment platform architectures and inflate deployment costs.
- Cybersecurity certification complexity:ISO 27001 and IEC 62443 compliance timelines extend vendor sales cycles by eight to fourteen months.
- Legacy avionics incompatibility:Aircraft manufactured before 2010 lack standardized digital interfaces, requiring expensive retrofit hardware.
Strategic Opportunities
- India's aviation expansion:The country's Directorate General of Civil Aviation is implementing safety management frameworks that mirror FAA requirements, creating first-mover advantages for compliant platform vendors.
- Edge computing convergence:Onboard processing units paired with satellite uplinks enable real-time analytics without ground dependency.
- Maintenance-repair-overhaul channel integration:Third-party MRO providers in Singapore and Dubai are building white-label platform capabilities for regional carriers.
Industry Challenges
- Aviation data science talent scarcity:Platform vendors compete for engineers with dual expertise in flight operations and cloud architecture.
- Fleet heterogeneity integration:Airlines operating mixed Boeing and Airbus fleets face data normalization complexity across incompatible recorder formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud-Connected Aircraft Safety Data Management Platforms Market |
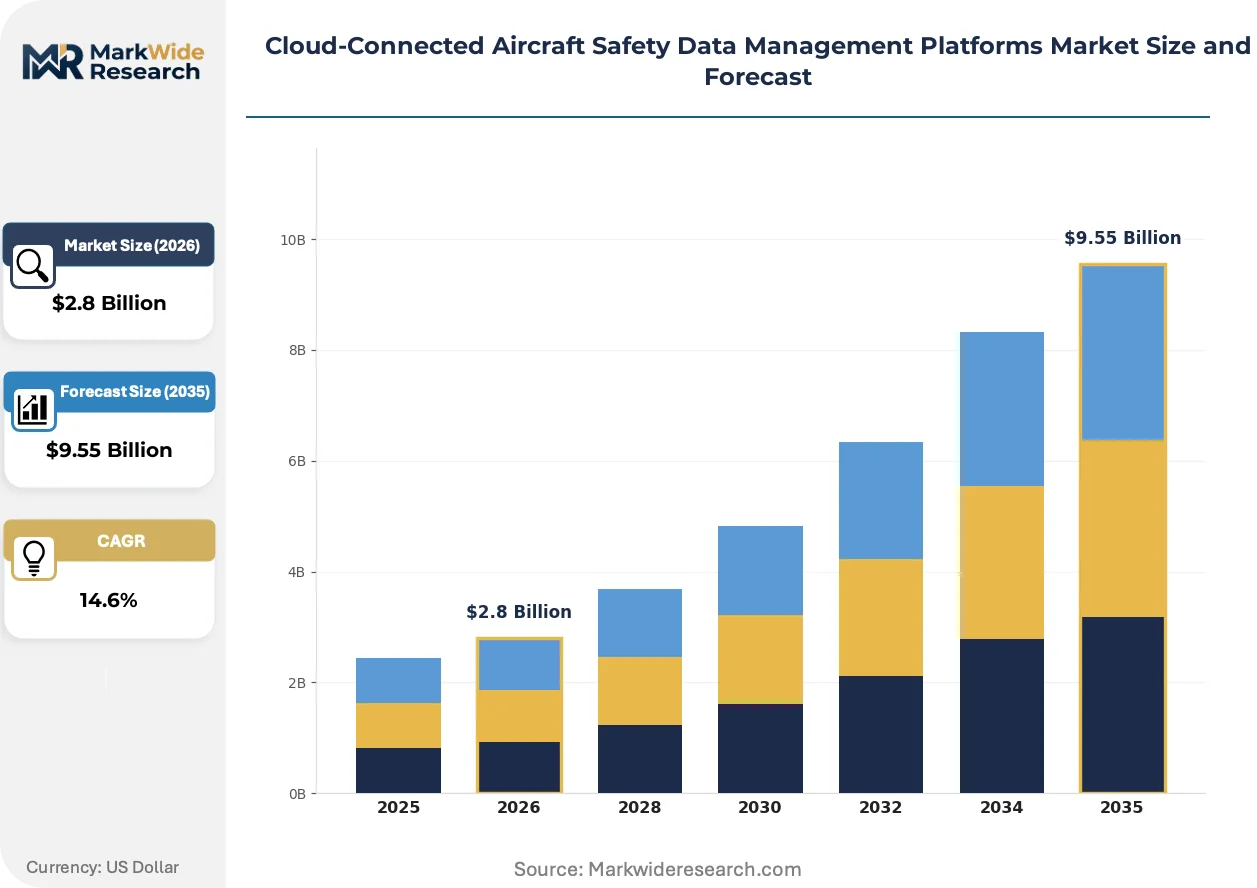
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform Type: Real-Time Monitoring, Incident Reporting, Risk Analysis, Predictive Maintenance, Compliance Management Connectivity Technology: Satellite Communication, Air-to-Ground Networks, LTE, 5G, Wi-Fi End User: Airlines, Aircraft Manufacturers, Aviation Safety Authorities, MRO Providers, Flight Schools Deployment Mode: Cloud-Based, Hybrid Cloud, On-Premises, Edge Computing |
| Companies Covered | GE Aerospace, Honeywell, L3Harris Technologies, Teledyne Technologies, Safran, Curtiss-Wright, Collins Aerospace, SITA, IBM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud-Connected Aircraft Safety Data Management Platforms Market Trends and Innovations
Distributed ledger architectures and edge-native processing are restructuring how safety-critical data moves between aircraft, ground stations, and regulatory repositories.
Digital twin technology is electrifying airframe health monitoring by creating persistent virtual replicas of physical aircraft systems. Major carriers in the United States are deploying these models across widebody fleets to simulate stress fractures and component degradation. The technology is electrifying competitive differentiation as operators race to demonstrate predictive accuracy to insurers and lessors.
EASA's forthcoming cybersecurity certification framework for cloud-connected avionics will mandate encrypted data pipelines and incident disclosure protocols. The regulation forces platform vendors to redesign authentication architectures and submit to third-party penetration testing. European operators face eighteen-month compliance windows that favor established vendors with existing certification infrastructure.
Airline procurement departments are unbundling safety data management from traditional flight operations software contracts. Low-cost carriers in Southeast Asia are sourcing standalone platforms through subscription models rather than bundled enterprise licenses. This shift is most visible in Indonesia and Vietnam, where rapid fleet expansion outpaces legacy vendor implementation capacity.
Cloud-Connected Aircraft Safety Data Management Platforms Market Segmentation
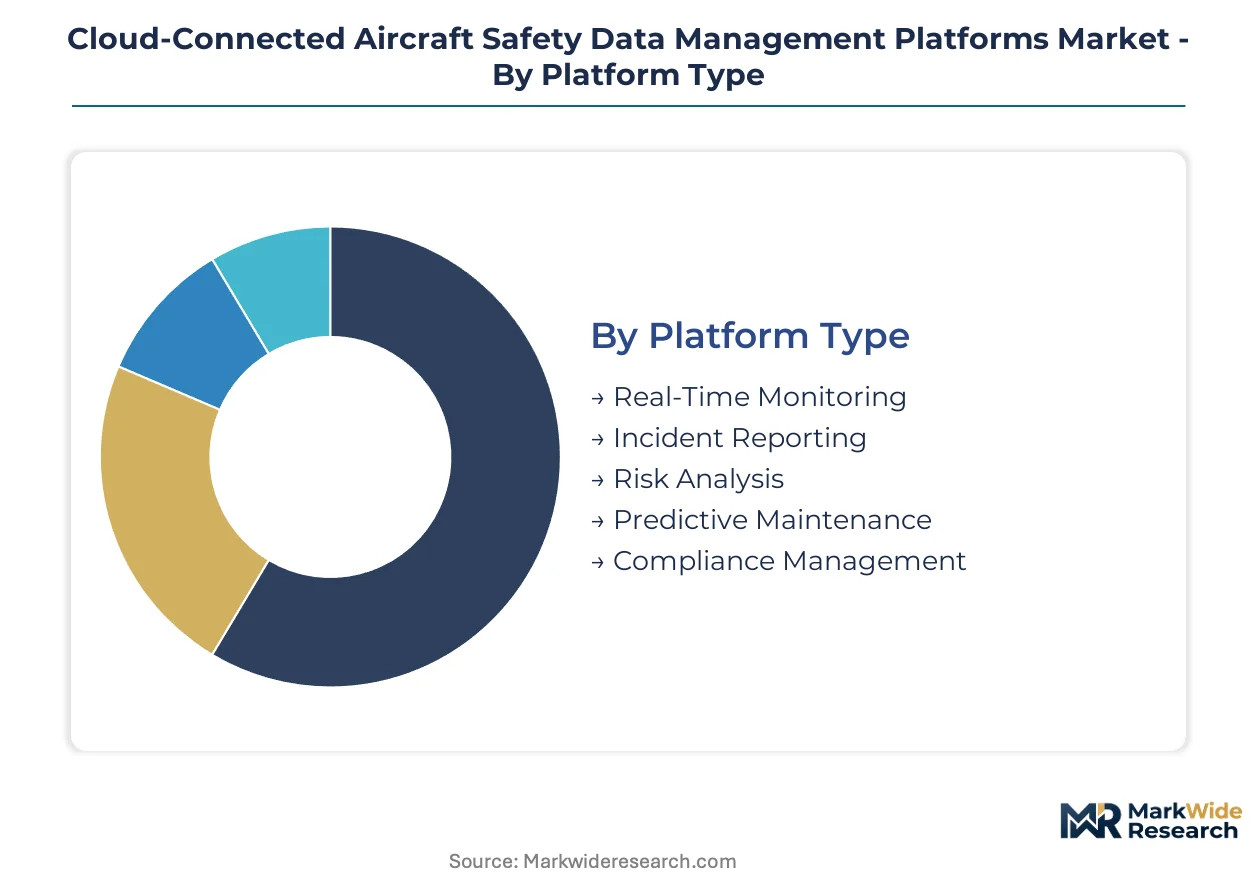
Platform segmentation reveals how carriers balance regulatory mandates against operational priorities. Each dimension—function, connectivity, user type, and infrastructure—carries distinct procurement cycles and integration requirements that reshape vendor competitive positioning.
Platform Type:
Upgrade cycles for legacy flight data recorders are compressing as FAA and EASA mandates force carriers toward unified architectures that merge multiple safety functions.
- Real-Time Monitoring:Continuous ingestion of millisecond-resolution flight parameters through satellite uplinks enables immediate anomaly flagging. United States major carriers deploy these systems across widebody fleets to satisfy FAA continuous data access requirements.
- Predictive Maintenance:Machine learning models processing engine and airframe telemetry convert unscheduled repairs into planned interventions. Demand concentrates among low-cost carriers in Southeast Asia seeking to maximize aircraft utilization rates.
- Incident Reporting:Standardized digital formats replace paper-based safety reporting for regulatory submission.
- Risk Analysis:Aggregation of historical flight data with weather and terrain databases identifies systemic safety patterns.
- Compliance Management:Automated audit trails and certification documentation reduce manual regulatory preparation.
Volume placements concentrate in Real-Time Monitoring; the faster expansion belongs to Predictive Maintenance.
Connectivity Technology:
Cost tier differentiation separates premium satellite constellations from terrestrial alternatives, with hybrid configurations dominating mid-market carrier procurement.
- Satellite Communication:Low Earth orbit networks deliver global coverage with latency under 100 milliseconds for oceanic routes. United States and European flag carriers prioritize these links for fleet-wide standardization despite higher per-megabyte costs.
- Air-to-Ground Networks:Cellular towers along flight corridors provide economical data transmission over continental landmasses. Regional operators in India leverage these networks for domestic route coverage where satellite redundancy is unnecessary.
- 5G:Ultra-reliable low-latency specifications enable high-bandwidth applications during ground operations.
- LTE:Mature infrastructure supports basic telemetry transmission where bandwidth requirements remain modest.
- Wi-Fi:Gate and tarmac connectivity supplements primary links for bulk data offload.
Procurement volumes favor Air-to-Ground Networks for continental operators; Satellite Communication gains share fastest among intercontinental fleets.
End User:
Customer type determines platform complexity, with airlines demanding full operational integration while safety authorities prioritize standardization over feature depth.
- Airlines:Full-stack platforms integrating flight operations, maintenance scheduling, and crew training data. Network carriers in the United States consolidate fragmented legacy systems onto cloud-native architectures.
- MRO Providers:White-label platform capabilities for third-party maintenance shops in Singapore and Dubai serving regional carriers without in-house data science teams.
- Aircraft Manufacturers:Embedded health monitoring systems shipped as original equipment on new production lines.
- Aviation Safety Authorities:Standardized ingestion pipelines for incident data collection and trend analysis.
- Flight Schools:Simplified dashboards tracking training aircraft utilization and student progress.
Airlines account for the dominant installation base; MRO Providers are climbing the fastest as outsourcing expands.
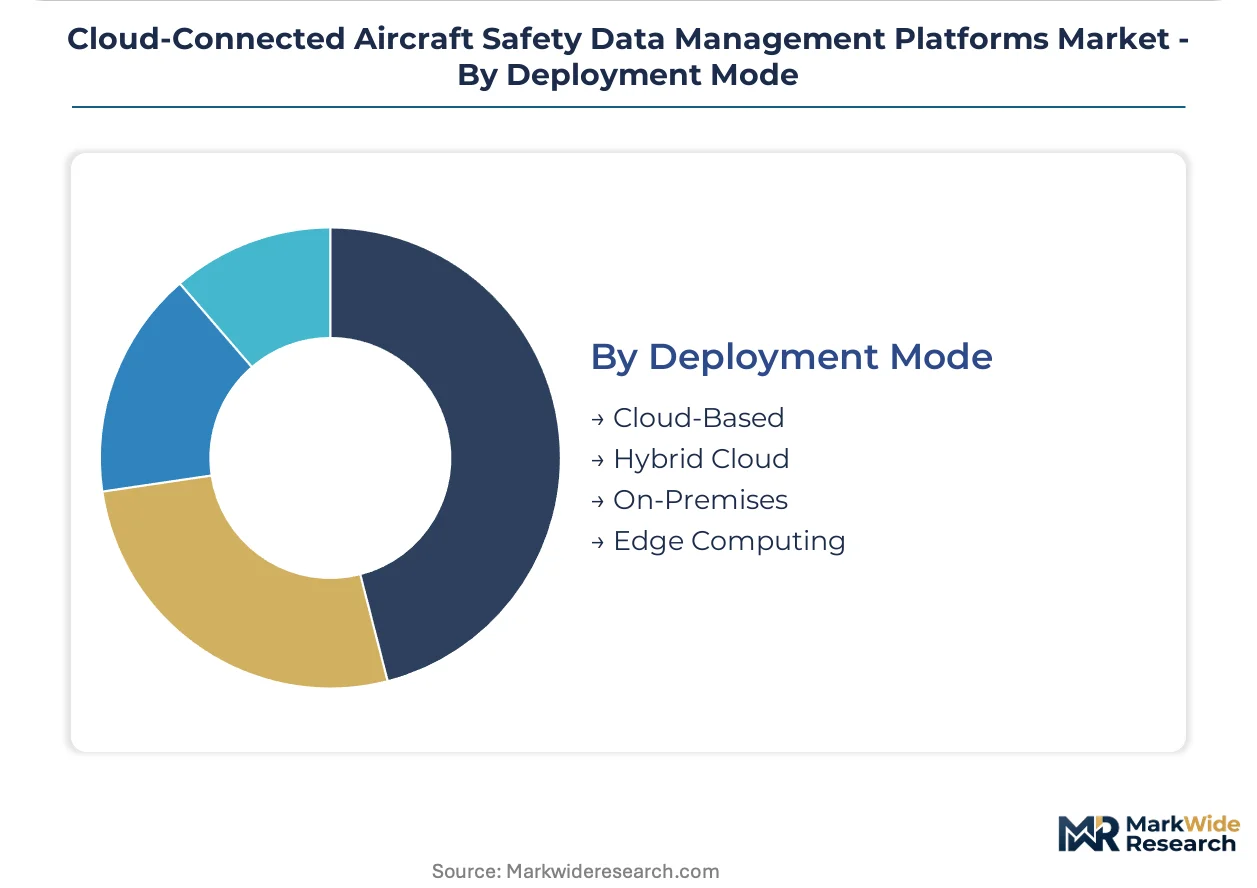
Deployment Mode:
Data sovereignty requirements fragment infrastructure choices, with European operators facing stricter localization mandates than counterparts elsewhere.
- Cloud-Based:Fully managed SaaS architectures with automatic scaling and vendor-managed security patching. New airline entrants in India and Vietnam favor this model for rapid fleet expansion without capital infrastructure investment.
- Hybrid Cloud:Sensitive operational data remains on-premises while analytics workloads process in public cloud environments. German and French operators mandate this configuration under national data protection frameworks.
- On-Premises:Complete air-gapped operation for defense-adjacent aviation segments with classified mission profiles.
- Edge Computing:Onboard processing units enabling real-time analytics without ground dependency for remote operations.
Cloud-Based deployments lead new installations; Hybrid Cloud configurations are gaining share fastest among established European operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley's cloud infrastructure anchors platform development for aviation safety data architectures, while regulatory mandates in Washington D.C. and Brussels reshape procurement requirements across carrier networks.
United States
FAA Safety Management System directives compel major carriers to consolidate fragmented safety data onto unified cloud architectures. The mandate requires standardized data formats and continuous audit trails for all Part 121 operators. Seattle's aerospace cluster hosts integration facilities where Alaska Airlines and Delta Air Lines deploy predictive maintenance modules across mixed fleets.
Germany
Lufthansa Group's fleet standardization drives demand for hybrid cloud configurations satisfying national data sovereignty frameworks. The country's Federal Aviation Office enforces strict localization requirements for operational flight data under GDPR-aligned aviation protocols. Munich's technical operations center serves as a regional hub where MRO providers white-label platform capabilities for Central European carriers.
France
Air France-KLM's transatlantic operations require satellite communication redundancy for oceanic route coverage. EASA's forthcoming cybersecurity certification framework mandates encrypted pipelines and third-party penetration testing for cloud-connected avionics. Toulouse's aerospace corridor concentrates platform development activity alongside Airbus manufacturing and Safran's digital aviation division.
Singapore
Changi Airport's hub status attracts third-party MRO providers building white-label platform capabilities for Southeast Asian carriers without in-house data science teams. The Civil Aviation Authority of Singapore aligns safety management frameworks with FAA and EASA standards to maintain bilateral agreements. Seletar Aerospace Park hosts integration facilities serving Indonesia's rapid fleet expansion.
India
IndiGo and SpiceJet's narrowbody growth creates procurement urgency for cloud-native platforms without capital infrastructure investment. The Directorate General of Civil Aviation implements safety management frameworks mirroring FAA requirements for international route access. Bangalore's aviation technology cluster attracts platform vendors establishing regional support centers for domestic carrier networks.
Cloud-Connected Aircraft Safety Data Management Platforms Market Competitive Landscape
Global majors compete with regional champions across certification infrastructure and regulatory relationships, producing a tiered structure where scale-driven vendors face pressure from compliance-specialized competitors. The vendor base separates into three strategic archetypes: diversified aerospace conglomerates leveraging digital portfolios, avionics specialists bridging legacy aircraft with modern pipelines, and IT services firms adapting enterprise cloud architectures for aviation applications. Dominant competitive moves include strategic partnerships with satellite communication providers and vertical integration into onboard processing hardware.
Within the diversified aerospace tier, GE Aerospace, Honeywell, and Safran exemplify contrasting geographic and regulatory positioning strategies. GE Aerospace anchors North American platform development through its digital aviation portfolio. Honeywell occupies a position bridging legacy avionics integration with modern data pipeline requirements. Safran sits within the European compliance segment, representing the regulatory-specialist archetype aligned to EASA certification frameworks.
| Leading Market Players |
|---|
| GE Aerospace |
| Honeywell |
| L3Harris Technologies |
| Teledyne Technologies |
| Safran |
| Curtiss-Wright |
| Collins Aerospace |
| SITA |
| IBM |
| Others |
Pricing and Supply Chain Analysis
EASA's forthcoming cybersecurity certification framework gates both qualified supply and premium-tier pricing access, as vendors must redesign authentication architectures and submit to third-party penetration testing to serve European operators. The mandate fragments procurement pools between certified and non-certified suppliers while compressing margins for those lacking existing certification infrastructure.
Pricing Analysis
Warranty and service bundling separates platform vendors into divergent pricing tiers, with full-stack maintenance contracts commanding substantial premiums over bare software licenses. SaaS subscription models dominate new airline procurement, though price differentiation hinges on ISO 27001 certification status and real-time data resolution capabilities. Pricing pressure stems from low-cost carriers in Southeast Asia unbundling safety data management from traditional flight operations contracts. Regional operators without intercontinental exposure exhibit the highest price sensitivity, while United States major carriers prioritize regulatory compliance over cost minimization.
Supply Chain Analysis
Domestic-content mandates in Germany and France are reshaping sourcing patterns, forcing hybrid cloud configurations that fragment platform architectures and inflate deployment costs. Component manufacturing concentrates in the United States, France, and Singapore, with specialized avionics hardware drawing from semiconductor foundries in Taiwan and South Korea. Supply chain risk centers on single-source vulnerability for millisecond-resolution flight data processors. Distribution runs through direct vendor-airline relationships for major carriers, while regional operators access platforms via third-party MRO providers in Singapore and Dubai.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-connected aircraft safety data management platforms sit at a technology-transition phase, with edge-native processing architectures displacing ground-dependent analytics pipelines across commercial aviation fleets.
For Market Incumbents: Lock in regulatory certification moats by accelerating EASA cybersecurity framework compliance ahead of eighteen-month windows. Consolidate satellite communication partnerships to control air-to-ground data transmission costs as Low Earth orbit constellations expand. The threat of specialized IT services firms adapting enterprise cloud architectures for aviation applications demands preemptive vertical integration into onboard processing hardware. For New Entrants and Emerging Players: Launch via white-label platform capabilities targeting third-party MRO providers in Singapore and Dubai serving regional carriers without in-house data science teams. India's aviation expansion offers the most penetrable geography, as the Directorate General of Civil Aviation implements safety management frameworks mirroring FAA requirements. A subscription-based go-to-market angle bypasses capital-constrained airline procurement cycles. For Investors and Strategic Acquirers: EASA's publication of detailed cybersecurity certification timelines is the leading indicator that compliance-specialized vendors will command acquisition premiums over undifferentiated platform providers. Long-term viability favors vendors with existing certification infrastructure and established regulatory relationships across multiple jurisdictions. The signal to monitor is airline procurement department unbundling of safety data management from bundled enterprise flight operations contracts.| Strategic Initiative | Industry Significance |
|---|---|
| Satellite Communication Partnership | Low Earth orbit constellation alliances reduce air-to-ground transmission costs for oceanic route coverage. |
| Edge Computing Hardware Integration | Onboard processing units enable real-time analytics without ground dependency for remote operations. |
| EASA Cybersecurity Certification | Encrypted data pipelines and penetration testing protocols open European operator procurement channels. |
| MRO Channel White-Label Platform | Third-party maintenance shops in Singapore and Dubai extend reach to capital-constrained regional carriers. |
| Hybrid Cloud Architecture Development | Data sovereignty-compliant configurations satisfy German and French national localization mandates. |
Research Methodology
Independent corroboration across primary interviews with airline operations executives, platform engineering directors, aviation safety authority officials, and MRO procurement leads underwrites the qualitative findings. Secondary validation draws from FAA Safety Management System directives, EASA certification framework publications, satellite communication provider technical disclosures, and airline fleet expansion announcements. Bottom-up triangulation across individual carrier procurement cycles combines with top-down analysis of regulatory mandate implementation timelines.
Comparable-period anchoring to historical platform deployment cycles and certification completion rates structured the forecast window. The analytical framework segments by platform function, connectivity technology, end-user type, and deployment mode, with additional granularity across regional regulatory clusters. CAGRs derive from fitted growth curves applied to documented procurement volumes and announced fleet modernization programs. Forecast inputs incorporate Low Earth orbit constellation deployment schedules and evolving cybersecurity standard adoption trajectories.
The model assumes a particular technology adoption path; alternative pathways for edge-native processing architectures would alter the outlook. Forecasts reflect assumptions regarding regulatory mandate enforcement consistency and satellite communication cost reduction trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Safety Systems
Aircraft Ice Protection System Market
Aircraft Safety Systems
Aviation Airbags Market
Aircraft Safety Systems
Commercial Parachute Market
Aircraft Safety Systems
Helicopter Ice Protection Systems Market
Aircraft Safety Systems
Aircraft Evacuation Slide Market
Aircraft Safety Systems
Commercial Aircraft Collision Avoidance System Market
Aircraft Safety Systems
Aircraft Smoke Detection and Fire Extinguishing System Market
Aircraft Safety Systems
Military Aircraft Collision Avoidance Systems Market
Aircraft Safety Systems
HUD Helmet Market
Aircraft Safety Systems
Free Fall Sensor Market
Aircraft Safety Systems
Global Aircraft Brakes Market
Aircraft Safety Systems
Identification Friend or Foe Systems Market
Aircraft Safety Systems
Aircraft Fire Protection Systems Market
Aircraft Safety Systems
Aircraft Ejection Seats Market
Aircraft Safety Systems
Aircraft Evacuation Systems Market
Aircraft Safety Systems
Commercial Aircraft Evacuation System Market