
 AI in Medical Diagnostics Market | 2026-2036
AI in Medical Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
AI in Medical Diagnostics Market Intelligence
Algorithm development capacity from specialized technology firms is shifting the competitive landscape away from traditional medical device manufacturers. Google Health leverages its vast data processing capabilities to develop novel diagnostic tools. Aidoc specializes in AI solutions for radiology workflows, while PathAI differentiates its offerings by focusing on improving pathology diagnostics and companion diagnostic development.
AI in medical diagnostics involves the application of machine learning, particularly deep learning algorithms like convolutional neural networks, to interpret complex medical data. These systems assist clinicians by identifying patterns in imaging, pathology slides, and genomic data that may be imperceptible to the human eye. Within applications, radiology and oncology represent the largest areas of use due to high data volumes. Imaging analysis software constitutes the dominant product type, driven by its direct integration into existing diagnostic workflows.
Regulatory bodies including the US FDA and Europe's EMA are establishing clearer approval pathways for Software as a Medical Device. These frameworks, alongside China's NMPA regulations, govern clinical validation requirements and post-market surveillance. Navigating the evolving standards for algorithm transparency and data privacy will determine long-term market access and provider trust.
Market Dynamics
The central dynamic shaping the market is the friction between rapid, data-driven algorithm development by specialized technology firms and the methodical, evidence-based validation required by regulatory bodies and clinical practitioners for safe adoption into patient care workflows.
Growth Catalysts
- Voluminous Clinical Data:The increasing digitization of healthcare records and medical images creates vast datasets, particularly in radiology and pathology, which are essential for training and validating sophisticated deep learning algorithms.
- Clarified Regulatory Pathways:Frameworks like the FDA's guidance for Software as a Medical Device (SaMD) provide clearer, more predictable routes for developers to secure approval for AI-driven diagnostic tools in the United States.
- Healthcare System Pressures:Demand for improved diagnostic accuracy and throughput, driven by aging populations and workforce shortages in specialties like radiology, compels providers to evaluate and adopt AI to enhance efficiency.
Market Restraints
- High Integration Costs:Significant capital investment is required to integrate AI diagnostic systems with existing hospital IT infrastructure, such as Picture Archiving and Communication Systems (PACS) and Electronic Health Records (EHR), creating a barrier for smaller facilities.
- Lack of Regulatory Harmonization:Disparate requirements for algorithm validation and data privacy between regulatory bodies like the US FDA, Europe's EMA, and China's NMPA complicate global product launches and increase compliance costs.
- Algorithm Explainability Issues:The "black box" nature of some complex neural networks can impede clinical adoption, as physicians require transparent, interpretable outputs to trust AI-generated recommendations and maintain ultimate diagnostic responsibility.
Strategic Opportunities
- Expansion into Emerging Markets:Untapped opportunities exist in Asia-Pacific and Latin American countries that are rapidly upgrading their healthcare infrastructure and are more open to adopting novel technologies to leapfrog legacy systems.
- AI in Precision Medicine:Applying AI algorithms to analyze genomic and proteomic data presents a significant opportunity to advance personalized medicine, identify novel biomarkers, and accelerate companion diagnostic development for targeted therapies.
- Digital Pathology Automation:The convergence of AI software with whole-slide imaging systems enables the automation of quantitative analysis for pathology, improving consistency and efficiency in cancer diagnosis and grading.
Industry Challenges
- Specialized Talent Scarcity:A persistent shortage of professionals with combined expertise in clinical medicine, data science, and regulatory affairs hinders the pace of product development, validation, and successful clinical implementation.
- Data Privacy and Security:Adhering to stringent patient data protection regulations, such as HIPAA in the US and GDPR in Europe, while accessing diverse datasets for model training remains a significant operational and legal challenge.
- Interoperability with Legacy Systems:Ensuring seamless data exchange and workflow integration between new AI applications and entrenched, often proprietary, hospital information systems is a major technical hurdle for vendors and providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI in Medical Diagnostics Market |
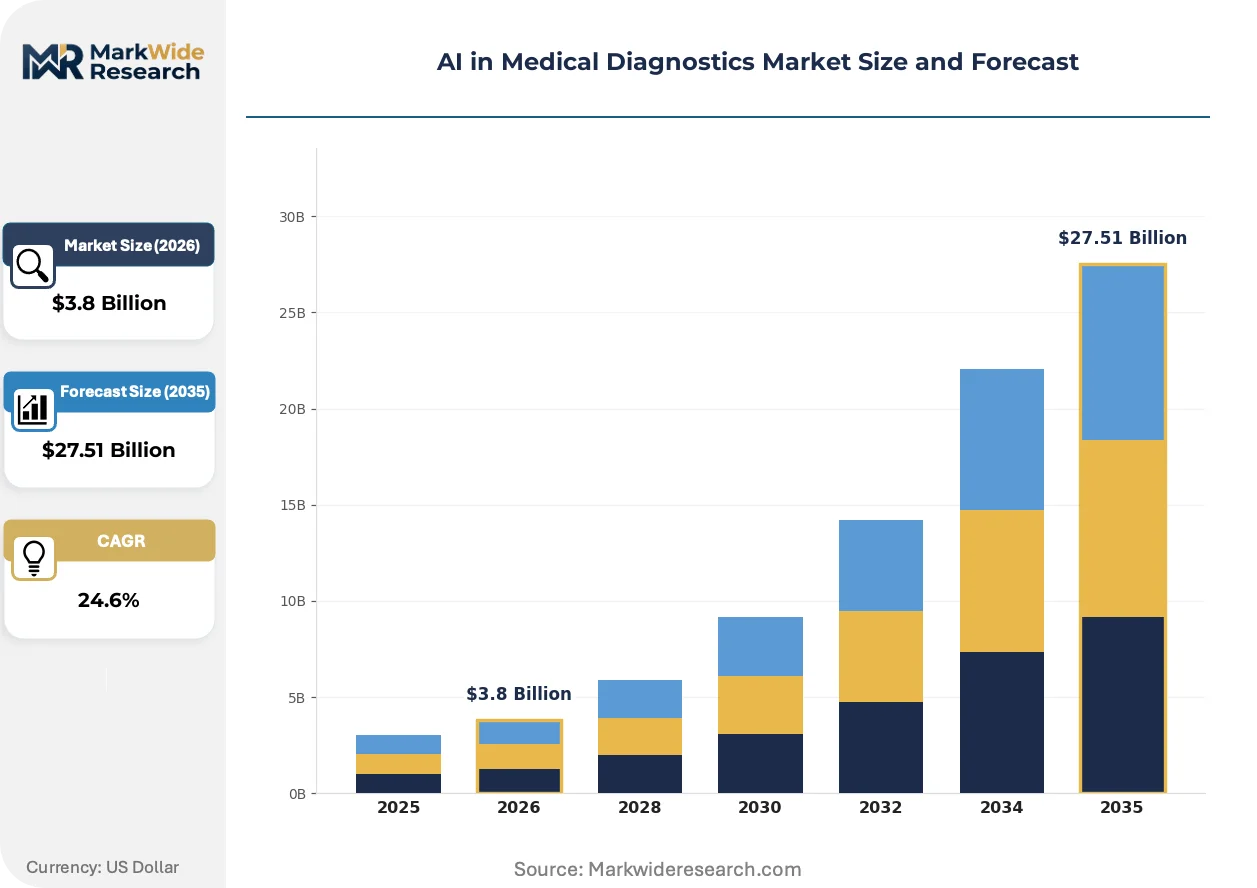
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $27.51 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Imaging Analysis Software, Diagnostic Algorithms, Clinical Decision Support Systems, Predictive Analytics Platforms, Natural Language Processing Tools Application: Radiology, Pathology, Cardiology, Neurology, Oncology, Ophthalmology End User: Hospitals, Diagnostic Laboratories, Ambulatory Surgical Centers, Telemedicine Providers, Specialty Clinics Deployment: Cloud-Based Solutions, On-Premises Installation, Hybrid Models, Edge Computing Platforms |
| Companies Covered | Aidoc, IBM Watson Health, Medtronic, Airs Medical, Google Health, Tempus, Viz.ai, Biofourmis, PathAI, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI in Medical Diagnostics Market Strategic Shifts & Innovations
A fundamental shift is occurring as AI transitions from a research concept to an integrated clinical utility. This evolution is defined by technologies that enhance data access without compromising privacy and by regulatory frameworks adapting to the unique nature of software-based medical devices.
Federated learning allows AI models to be trained across multiple institutions without centralizing sensitive patient data. Large hospital networks and research consortia are adopting this method to build more robust algorithms from diverse population datasets. This distributed approach is converging with cloud computing platforms, enabling the scalable development of generalizable models while respecting strict data privacy and residency rules.
The European Union's AI Act classifies AI systems according to risk, imposing strict obligations on high-risk applications like medical diagnostics. This legislation mandates rigorous conformity assessments, quality management systems, and post-market surveillance for SaMD. Developers targeting the European market, particularly in cardiology and oncology, are now embedding regulatory compliance and risk management into the earliest stages of their design process.
Hospitals are moving from purchasing single-point AI tools to adopting comprehensive platforms. This model consolidates multiple diagnostic algorithms, such as for stroke detection and cancer screening, into a unified interface, simplifying IT management and vendor relationships. This trend is most visible within large Integrated Delivery Networks in the United States, which seek to standardize diagnostic support tools across their entire system.
AI in Medical Diagnostics Market Segmentation
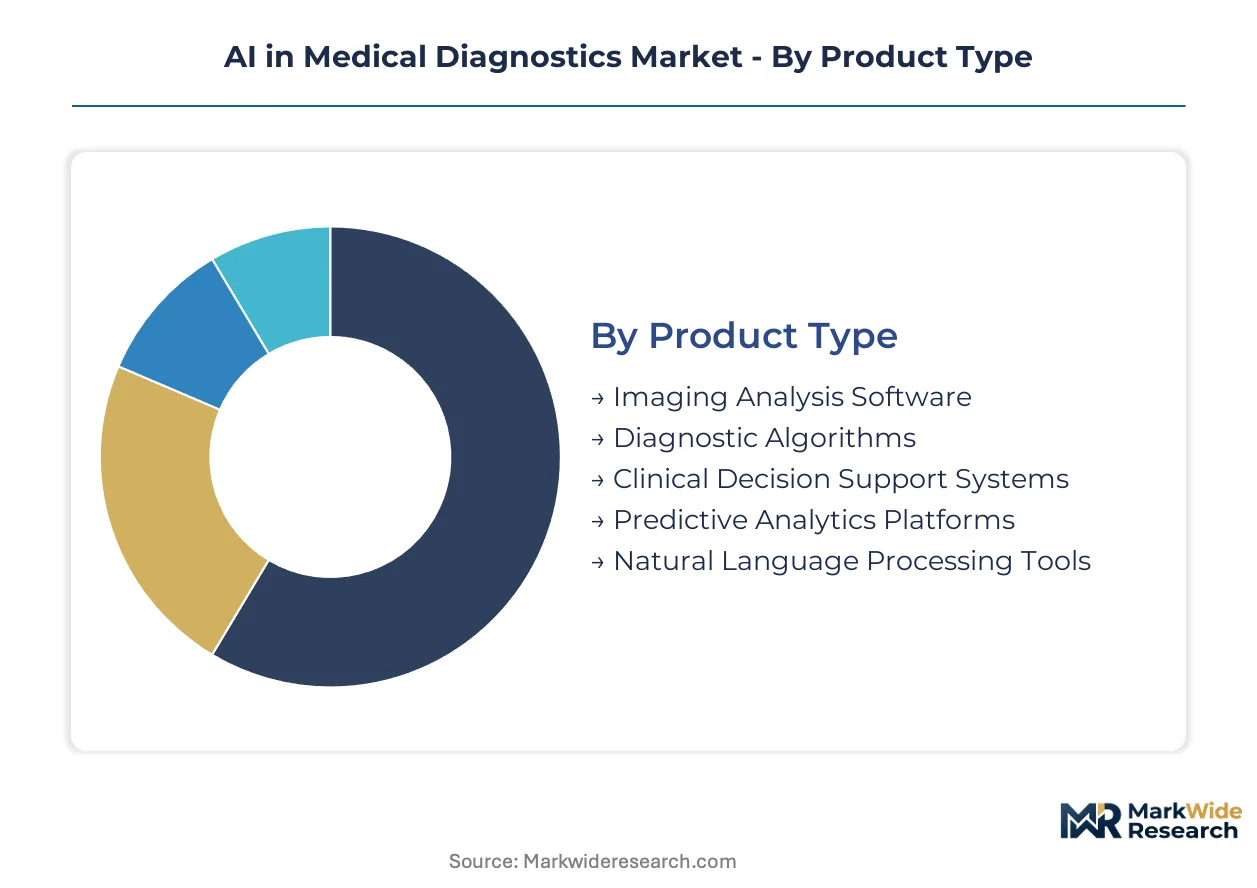
The AI in medical diagnostics market is segmented to understand how different technological solutions, clinical applications, user types, and deployment models contribute to its overall growth and adoption. This granular view reveals specific areas of innovation and commercial concentration for developers and healthcare providers.
Product Type:
The market delineates solutions based on their functional integration, ranging from standalone tools to embedded analytical engines.
- Imaging Analysis Software:These systems apply deep learning algorithms, particularly convolutional neural networks, to interpret medical images such as X-rays, CT scans, and MRIs. Demand concentrates in hospital radiology departments seeking to automate detection of anomalies and reduce radiologist workload in countries like the United States.
- Diagnostic Algorithms:Specialized machine learning models provide automated interpretations or risk scores based on various data inputs, including lab results, patient history, and genetic markers. Their expansion is driven by the need for enhanced diagnostic accuracy and efficiency in complex disease areas like oncology across major healthcare systems.
- Clinical Decision Support Systems:These AI tools integrate patient data with medical knowledge bases to offer evidence-based recommendations to clinicians at the point of care. They aim to improve diagnostic consistency and treatment planning.
- Predictive Analytics Platforms:Such platforms utilize AI to forecast disease progression, patient outcomes, or the likelihood of specific medical events based on historical and real-time data. They support proactive healthcare management.
- Natural Language Processing Tools:NLP applications extract and interpret unstructured data from electronic health records, clinical notes, and medical literature. These tools facilitate data mining for research and clinical insights.
Volume placements concentrate in Imaging Analysis Software; the faster expansion belongs to Diagnostic Algorithms.
Application:
Market segmentation by application highlights the clinical areas where AI diagnostic tools are most impactful, reflecting specific data availability and diagnostic challenges.
- Radiology:This segment represents the largest area of AI application, leveraging vast datasets of medical images for automated detection of diseases like cancer, stroke, and fractures. High data volumes and the need for efficiency are driving adoption in major healthcare markets such as Germany and Japan.
- Oncology:AI tools in oncology assist with cancer detection, staging, and treatment planning by analyzing pathology slides, genomic data, and imaging. The complexities of cancer diagnosis and personalized treatment approaches fuel innovation in this application across research institutions and specialized clinics.
- Pathology:AI algorithms enhance the analysis of whole-slide images in digital pathology, automating tasks like cell counting, tissue classification, and tumor grading. This improves diagnostic consistency and throughput.
- Cardiology:AI aids in interpreting electrocardiograms, echocardiograms, and cardiac MRI scans for early detection of heart conditions and risk assessment. It supports improved patient management.
- Neurology:AI solutions assist in diagnosing neurological disorders such as Alzheimer's, Parkinson's, and epilepsy by analyzing brain imaging and neurological data. These tools offer new insights into complex conditions.
- Ophthalmology:AI algorithms are used for automated screening and diagnosis of eye diseases like diabetic retinopathy and glaucoma from retinal images. This supports early intervention and prevention of blindness.
Radiology applications currently hold the largest share; however, Oncology applications are gaining share most quickly.
End User:
The market differentiates by the primary healthcare settings adopting AI diagnostics, reflecting variations in infrastructure, budgets, and patient volumes.
- Hospitals:Hospitals represent the dominant end-user segment due to their extensive diagnostic departments, high patient throughput, and significant investment capacity for advanced AI systems. Large hospital networks in countries like the United Kingdom are central to broad-scale AI deployment.
- Diagnostic Laboratories:These facilities utilize AI for automating analysis of pathology slides, genomic sequences, and other lab results, enhancing accuracy and efficiency in high-volume testing environments. Specialized labs in France are increasingly integrating AI tools for complex biomarker analysis.
- Ambulatory Surgical Centers:ASCs are increasingly adopting AI for pre-operative diagnostics and post-operative monitoring, streamlining patient pathways and improving outcome predictions. Their focus on efficiency drives selective AI integration.
- Telemedicine Providers:AI integrates with telemedicine platforms to offer remote diagnostic support, particularly for image analysis and preliminary symptom assessment. This expands access to specialist care.
- Specialty Clinics:Clinics focused on specific medical areas like dermatology or ophthalmology deploy AI for targeted diagnostic assistance. These clinics benefit from specialized AI tools for precise condition identification.
Hospitals command the largest user base; Telemedicine Providers are experiencing the steepest expansion trajectory.
Deployment:
Deployment models categorize how AI diagnostic solutions are hosted and accessed, influencing scalability, data security, and integration complexity.
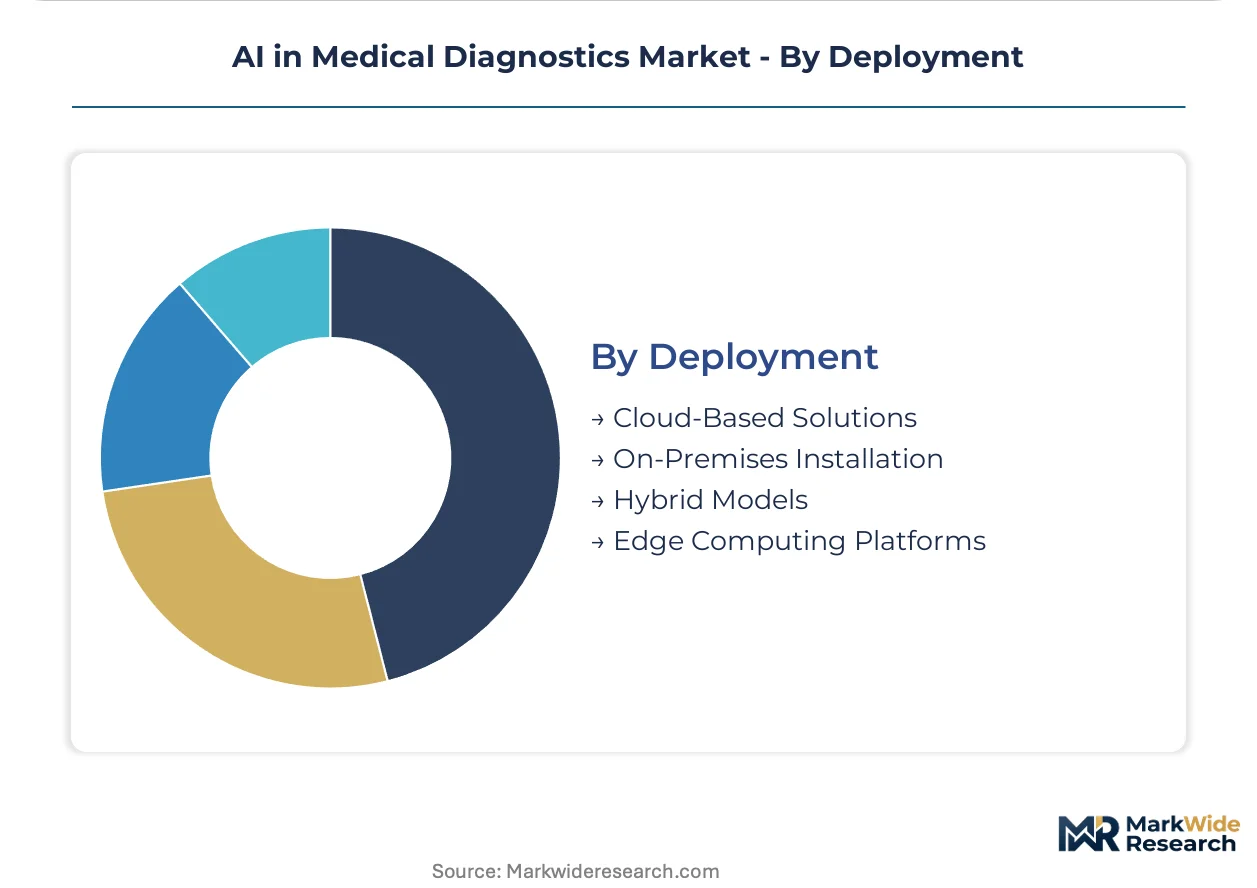
- Cloud-Based Solutions:These platforms host AI algorithms and data processing on remote servers, offering high scalability, lower upfront costs, and flexible access from various locations. Adoption is high among smaller facilities and in regions with developing IT infrastructure, such as parts of India.
- On-Premises Installation:AI systems are deployed directly within a healthcare provider's local IT infrastructure, providing maximum control over data security and integration with existing legacy systems. Large academic medical centers in the United States often prefer this model for sensitive patient data.
- Hybrid Models:These solutions combine elements of both cloud and on-premises deployment, allowing healthcare organizations to store sensitive data locally while leveraging cloud resources for scalable computation. This approach balances security and flexibility.
- Edge Computing Platforms:AI processing occurs closer to the data source, such as directly on medical devices or local servers, reducing latency and improving data privacy for real-time diagnostic applications. This model is gaining traction for immediate insights.
On-Premises Installation holds significant market presence; Cloud-Based Solutions are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States, with its robust R&D investment, anchors the global AI in medical diagnostics market. Advanced healthcare infrastructure facilitates rapid technology development and clinical integration. This environment drives significant innovation across diagnostic modalities.
United States
The United States exhibits strong demand for AI in medical diagnostics, driven by advanced healthcare infrastructure and significant R&D investment. The FDA's Software as a Medical Device (SaMD) guidance provides clear regulatory pathways for developers. Boston's life sciences cluster, alongside California's tech hubs, fosters innovation in AI algorithm development and deployment.
Germany
Germany's demand for AI diagnostics stems from its high-quality healthcare system and aging population pressures. The EMA's evolving regulatory frameworks, alongside national guidelines, shape market access for AI solutions. Munich and Berlin's medical technology ecosystems actively integrate AI into radiology workflows.
Japan
Japan's healthcare system requires improved diagnostic accuracy and efficiency, particularly in radiology, due to an aging demographic. The PMDA establishes approval pathways for AI medical devices, ensuring clinical validation. Tokyo's research institutions and medical centers collaborate on AI development for imaging analysis.
China
China's demand for AI in medical diagnostics is escalating, supported by rapid healthcare infrastructure upgrades and a large patient base. The NMPA regulations govern clinical validation and post-market surveillance for AI diagnostic tools. Shanghai's burgeoning biotech sector and Beijing's AI research centers drive significant development.
France
France demonstrates increasing demand for AI tools within diagnostic laboratories, aiming to enhance analysis efficiency. The ANSM, along with EU AI Act provisions, clarifies regulatory expectations for AI-driven solutions. Paris's health technology incubators focus on specialized AI applications for complex biomarker analysis.
AI in Medical Diagnostics Market Key Industry Players
Global majors compete with regional champions across technology development, clinical validation, and market reach. The market structure exhibits a tiered landscape, with established medical device manufacturers alongside specialized AI technology firms. Strategic archetypes include pure-play AI developers focusing on specific clinical areas, diversified tech giants leveraging extensive data, and traditional healthcare companies integrating AI into their existing product lines. Dominant competitive moves involve strategic partnerships for data access and clinical validation, alongside portfolio diversification into new diagnostic applications.
Specialists in AI-driven diagnostics like Aidoc exemplify focused innovation within radiology workflows, developing solutions for rapid anomaly detection. Google Health, a diversified tech giant, represents the broader trend of leveraging vast data processing capabilities to develop novel diagnostic tools across multiple medical domains. PathAI anchors the segment focused on improving pathology diagnostics and companion diagnostic development, showcasing the specialized application of AI to enhance precision in cancer diagnosis. These firms highlight the market's blend of broad technological prowess and deep clinical expertise.
| Leading Market Players |
|---|
| Aidoc |
| IBM Watson Health |
| Medtronic |
| Airs Medical |
| Google Health |
| Tempus |
| Viz.ai |
| Biofourmis |
| PathAI |
| Others |
Cost & Logistics Intelligence
Specialized AI talent concentration in technology hubs like California and Boston inflates development costs, influencing differentiated pricing tiers for advanced diagnostic software solutions. This talent scarcity directly impacts the premium attached to highly sophisticated algorithms.
Pricing Analysis
Warranty and service-level agreement bundling often dictates the perceived value of AI diagnostic solutions, influencing overall pricing. The dominant pricing model leans towards subscription-based SaaS tiers, with value-based pricing emerging for high-impact diagnostic algorithms. Price differentiation stems from algorithm accuracy validation and integration complexity with existing hospital IT. Pricing softness reflects competition among specialized AI firms for market share in radiology. Smaller hospitals demonstrate higher price sensitivity compared to large integrated delivery networks.
Supply Chain Analysis
Logistics and data transfer costs for large medical datasets influence the regional deployment of AI diagnostic solutions, particularly for on-premises installations. The supply of foundational AI research and development concentrates in the United States, China, and Germany. This segment relies on high-performance computing infrastructure and secure cloud services as key components. Data privacy regulations across different regions represent a significant supply chain risk. Distribution runs through direct sales teams to large hospital networks and partnerships with medical device distributors for broader reach.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The AI in medical diagnostics market presents a significant cost-of-compliance story, where stringent regulatory frameworks like the EU AI Act create a barrier-to-entry moat for well-resourced, compliant players. Navigating these evolving standards demands substantial investment in validation and quality management systems.
For Market Incumbents: Cement existing hospital network relationships by offering comprehensive AI platforms that consolidate multiple diagnostic algorithms. Diversify solution portfolios into high-growth areas like digital pathology automation to counter single-point solution providers. Leverage established clinical validation processes and regulatory expertise as a lever against emerging pure-play AI firms. This strategy mitigates the threat from new entrants with specialized, but unintegrated, tools.
For New Entrants and Emerging Players: Specialty clinics in emerging markets, seeking efficiency gains, represent an underserved buyer archetype. Target precision medicine applications in oncology, leveraging AI to identify novel biomarkers, as a white-space opportunity. Focus on cloud-based solutions to lower integration costs for smaller facilities, particularly in Asia-Pacific countries. A direct-to-specialist go-to-market angle can bypass established hospital procurement complexities.
For Investors and Strategic Acquirers: The window for entry favors strategic acquirers seeking to consolidate fragmented AI capabilities in the 5-10 year outlook. Target mid-sized AI firms with validated algorithms in high-volume applications like radiology or pathology, especially those with strong intellectual property. Acquisition targets should possess clear regulatory approval pathways and demonstrated clinical utility. A key signal to watch is the expansion of AI reimbursement codes across major healthcare systems.
| Strategic Initiative | Industry Significance |
|---|---|
| Pursue Multi-Algorithm Platform Development | Consolidates diverse diagnostic capabilities, simplifying hospital IT management. |
| Invest in Federated Learning Solutions | Enables robust model training from diverse datasets while preserving patient privacy. |
| Secure Global Regulatory Certifications | Expands market access and builds provider trust across international geographies. |
| Develop AI for Precision Oncology | Addresses complex diagnostic challenges in cancer care, fostering personalized treatment. |
| Forge Partnerships with EHR/PACS Vendors | Ensures seamless integration and workflow adoption within existing hospital systems. |
Research Approach
Trade association data, regulatory filings, and medical journal publications anchored secondary inputs for this study. Primary interviews with clinicians, hospital procurement managers, AI developers, and regulatory affairs specialists provided crucial market insights. This approach combined qualitative data with quantitative analysis. Bottom-up data aggregation and top-down market sizing validated all findings.
Market granularity was modeled across product types, clinical applications, end-users, and deployment models at a country level over the projection horizon. The analytical framework integrated historical growth trends with future adoption drivers. Compound annual growth rates were derived from a weighted average of segment-specific expansion rates. Healthcare expenditure and R&D investment in AI served as key forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory shifts and technological breakthroughs. Forecasts reflect assumptions regarding clinical adoption rates and integration costs. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Diagnostics
Asia-Pacific Single Cell Analysis Market
Medical Diagnostics
Europe Circulating Tumor Cells (CTC) Liquid Biopsy Market
Medical Diagnostics
US Molecular Diagnostics Market
Medical Diagnostics
Liver Biopsy Market
Medical Diagnostics
Dosimetry Market
Medical Diagnostics
Blood Platelet Market
Medical Diagnostics
Medical Isotope Market
Medical Diagnostics
Rapid Medical Diagnostic Kits Market
Medical Diagnostics
Protein Sequencing Market
Medical Diagnostics
Real-Time PCR, Digital PCR, and End-Point PCR Market
Medical Diagnostics
Medical Marker Bands Market
Medical Diagnostics
In-Situ Hybridization (ISH) Market
Medical Diagnostics
Global HLA Typing for Transplant Market
Medical Diagnostics
Fluorescence Cell Market
Medical Diagnostics
Karyotype Analysis Service Market
Medical Diagnostics
Artificial Intelligence (AI) in Medical Diagnostics Market