
 Opioid Use Disorder Treatment Market | 2026-2036
Opioid Use Disorder Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Opioid Use Disorder Treatment Market Analytics
Capital-intensity divergence between implantable depot manufacturers and generic oral tablet producers is unwinding competitive dynamics in opioid use disorder treatment. Alkermes plc leverages its extended-release naltrexone platform to sustain premium positioning in relapse prevention therapy. Indivior PLC anchors its market presence through sublingual film formulations that differentiate on bioavailability and patient adherence metrics.
Opioid use disorder treatment encompasses pharmacological interventions designed to reduce cravings, block euphoric effects, or manage withdrawal symptoms through agonist, partial agonist, or antagonist mechanisms, typically requiring DEA-scheduled distribution and specialized prescriber certification. These therapies serve clinical protocols spanning emergency detoxification through long-term maintenance to prevent fatal overdose recurrence. Buprenorphine formulations dominate volume due to expanded prescribing authority under federal waiver programs, while injectable depot therapies capture disproportionate value per patient course despite narrower eligibility criteria. Oral delivery modes retain the largest patient base across rehabilitation centers and outpatient clinics, though transdermal and sublingual formats are gaining protocol inclusion for populations with adherence challenges.
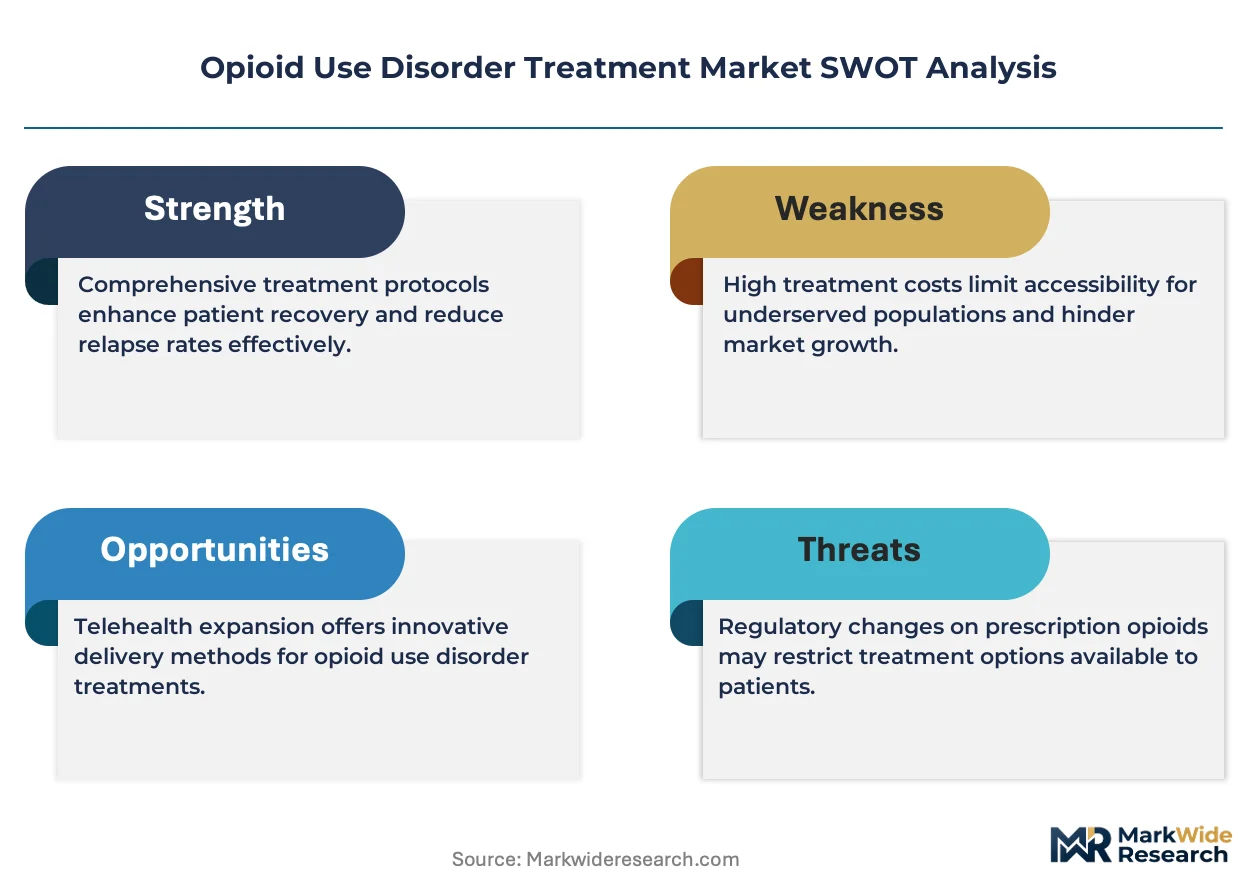
FDA scheduling requirements under the Controlled Substances Act, DEA production quotas for Schedule II-III medications, and SAMHSA practice guidelines collectively determine prescriber capacity, formulary placement, and reimbursement thresholds for medication-assisted treatment. State-level Medicaid expansion decisions and parity enforcement under the Mental Health Parity and Addiction Equity Act further shape patient access geography. Stakeholders must monitor evolving REMS modifications and proposed legislation around prescribing flexibility, as these regulatory levers will determine which delivery modes and therapy areas capture incremental investment priority.
Market Dynamics
Federal prescribing flexibility reforms and Medicaid expansion decisions are restructuring patient access geography faster than manufacturing capacity can realign, creating acute regional mismatches between buprenorphine waiver capacity and untreated population density.
Growth Catalysts
- DEA Production Quota Adjustments:Annual Schedule III quota increases for buprenorphine API are expanding raw material availability for generic tablet manufacturers.
- Telehealth Prescribing Waivers:Post-pandemic flexibilities under SAMHSA guidelines are extending medication-assisted therapy reach into rural counties with prescriber shortages.
- Harm Reduction Infrastructure:State-level syringe service program legalization is creating distribution nodes that co-locate naloxone with treatment referrals.
Market Restraints
- REMS Burden:Risk Evaluation and Mitigation Strategies for extended-release injectables impose prescriber certification costs that compress prescriber pools.
- API Concentration:Active pharmaceutical ingredient manufacturing for naltrexone concentrates in Indian and Chinese chemical parks, exposing supply chains to export control volatility.
- Substitution Threat:Illicit fentanyl analogues with higher potency profiles are displacing pharmaceutical opioids in street markets, eroding maintenance therapy retention.
Strategic Opportunities
- Justice-Involved Populations:State correctional systems represent underpenetrated channels where medication-assisted therapy initiation prior to release reduces fatal overdose post-incarceration.
- Long-Acting Formulation Convergence:Combination depot therapies merging buprenorphine with naloxone are opening patent-protected lifecycle extensions beyond oral generic erosion.
- 340B Program Expansion:Federally qualified health centers leveraging pharmaceutical pricing discounts are capturing margin to subsidize uninsured patient courses.
Industry Challenges
- Addiction Medicine Workforce Gap:Fellowship-trained physician shortages in Appalachia and the Southwest are creating treatment deserts despite medication availability.
- Interoperability Friction:State prescription drug monitoring program data standards vary, complicating cross-border patient tracking for mobile populations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Opioid Use Disorder Treatment Market |
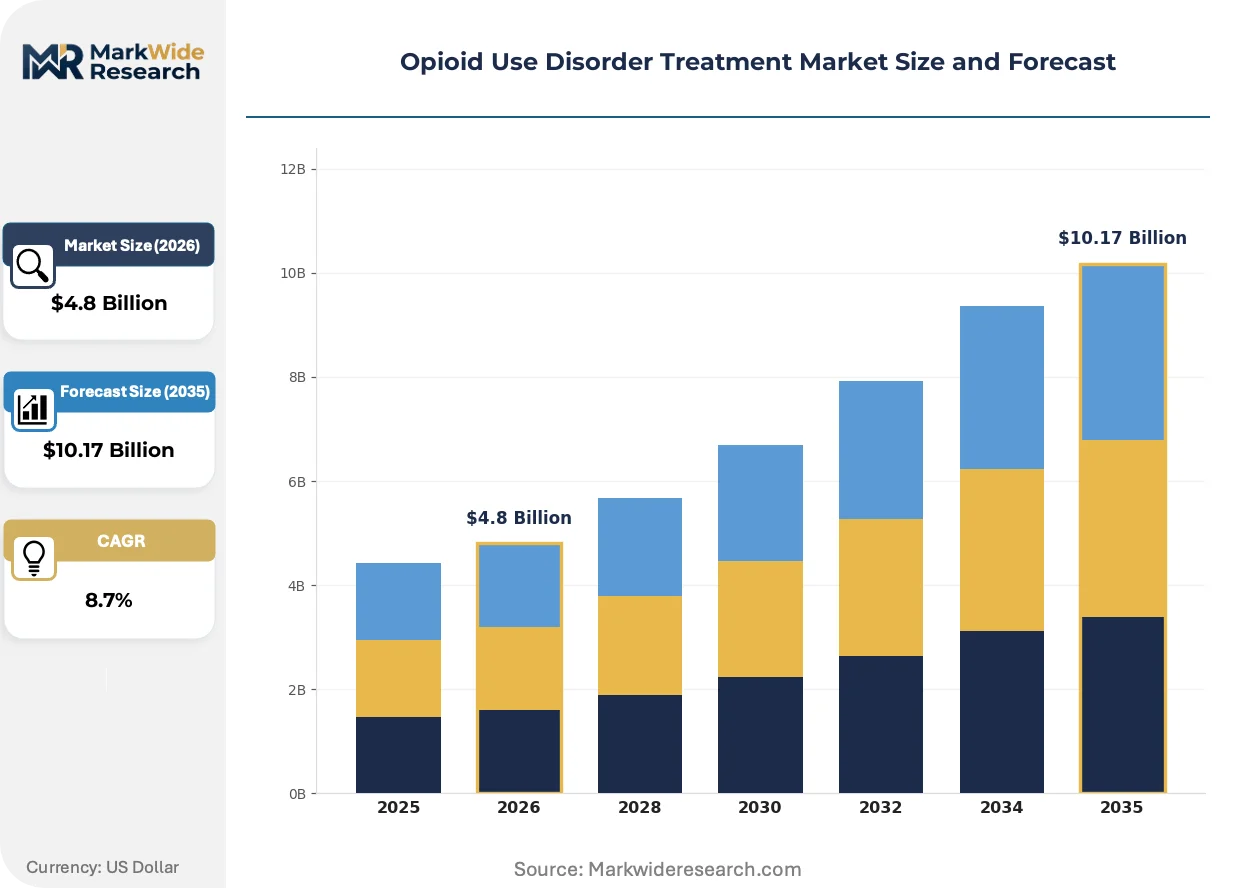
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Buprenorphine, Methadone, Naltrexone, Lofexidine Delivery Mode: Oral, Injectable, Transdermal, Sublingual End User: Hospitals, Rehabilitation Centers, Outpatient Clinics, Home Healthcare Therapy Area: Detoxification, Maintenance, Relapse Prevention, Pain Management |
| Companies Covered | Titan Pharmaceuticals, Inc., BioDelivery Sciences International Inc., Indivior PLC, Hikma Pharmaceuticals PLC, Viatris Inc., Alkermes plc, Mallinckrodt Pharmaceuticals, Camurus AB, Orexo AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Opioid Use Disorder Treatment Market Evolving Landscape
Delivery mode innovation is fragmenting the historical oral-tablet monopoly, with implantable and injectable formats capturing protocol share in populations with documented adherence failures.
Extended-release naltrexone implants are displacing daily oral antagonist regimens in criminal justice and employer-mandated treatment protocols. Correctional health systems and occupational medicine programs are adopting six-month depot formulations to eliminate dosing supervision costs. This displacement is compressing pharmacy benefit manager rebate structures for oral generics while creating captive distribution relationships between implant manufacturers and institutional purchasers.
SAMHSA practice guideline revisions are expanding prescribing authority to nurse practitioners and physician assistants without waiver requirements. This regulatory relaxation is multiplying prescriber capacity in Federally Qualified Health Centers and rural health clinics. Primary care integration is accelerating fastest in states with full Medicaid expansion and parity enforcement infrastructure.
Patient preference for discreet medication administration is driving sublingual film demand in workplace and family-concealment contexts. Employer-sponsored treatment programs and collegiate health services are prioritizing film formulations over identifiable tablet packaging. This behavioral pivot is most visible in suburban and exurban counties where stigma concerns exceed cost sensitivity in benefit design.
Opioid Use Disorder Treatment Market Segmentation
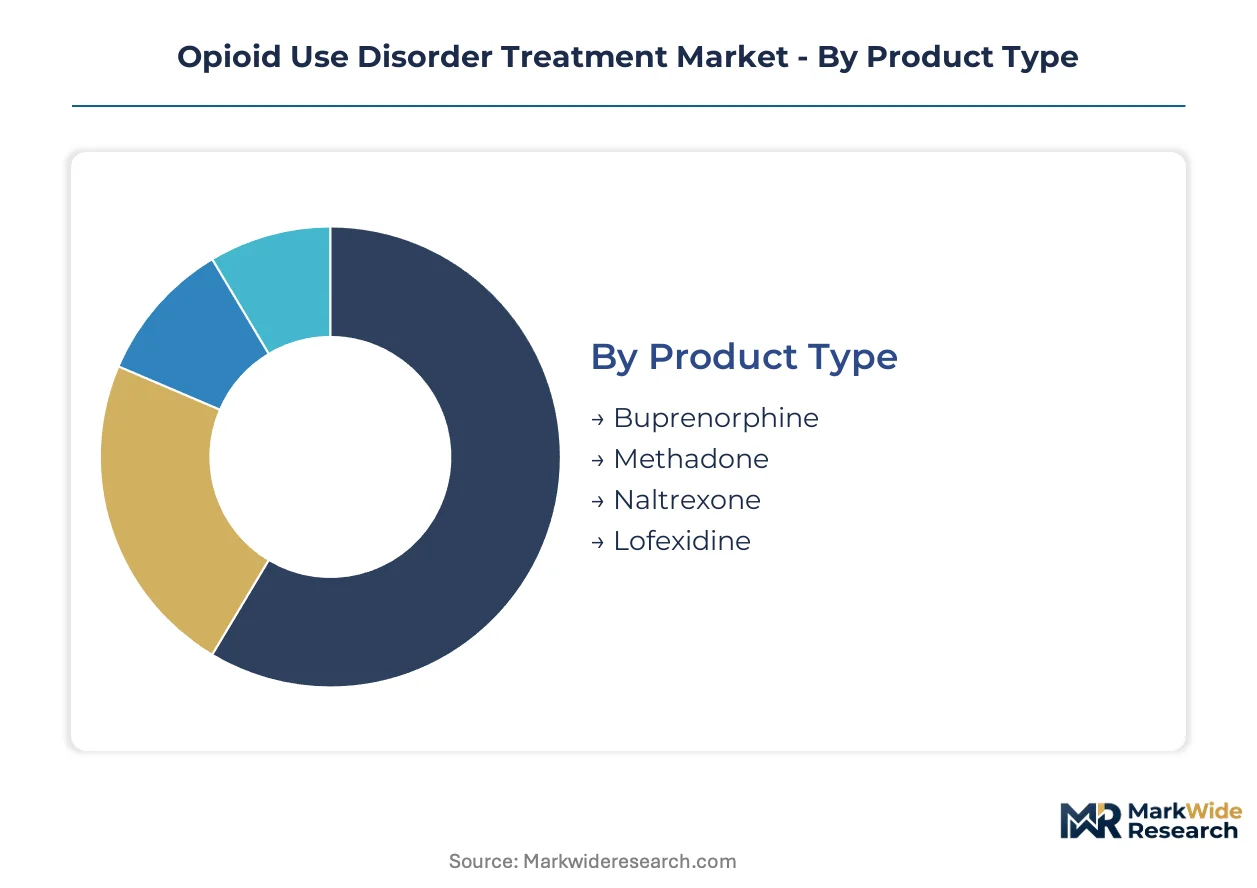
Segmentation in opioid use disorder treatment determines reimbursement pathways, prescriber certification requirements, and distribution channel economics. Each dimension intersects with DEA scheduling, SAMHSA guidelines, and state Medicaid formularies to create distinct commercial environments.
Product Type:
Buprenorphine formulations flow through outpatient clinics and office-based prescribers under federal waiver programs, while methadone remains restricted to OTP-certified facilities. Naltrexone depots channel through specialty pharmacies and institutional purchasers. Lofexidine distributes primarily through hospital discharge protocols.
- Buprenorphine:Partial opioid agonist available in monotherapy and naloxone-combination formulations. Demand concentrates in Federally Qualified Health Centers across states with full Medicaid expansion, driven by SAMHSA prescribing flexibility extending to nurse practitioners and physician assistants.
- Methadone:Full agonist requiring daily supervised dosing at Opioid Treatment Programs. Retention concentrates in urban corridors with established OTP infrastructure, constrained by NIMBY zoning restrictions and transportation barriers for rural patients.
- Naltrexone:Extended-release injectable and oral antagonist formulations. Institutional procurement through correctional health systems and employer-mandated programs is displacing oral regimens.
- Lofexidine:Alpha-2 adrenergic agonist for acute withdrawal symptom management. Hospital-based initiation protocols in academic medical centers drive prescribing.
By volume, buprenorphine leads. By growth pace, naltrexone depot formulations are expanding most quickly.
Delivery Mode:
Cost tier stratification separates premium-priced depot injectables from commodity oral generics, with reimbursement spreads determining prescriber incentives and patient access patterns.
- Oral:Tablets and liquid formulations dominate Medicaid formularies and 340B program purchasing. Volume concentrates in rehabilitation centers and community health centers where cost minimization governs protocol design.
- Injectable:Long-acting depot formulations command premium reimbursement through medical benefit billing rather than pharmacy benefits. Correctional systems and occupational medicine programs are adopting six-month formulations to eliminate adherence supervision costs.
- Transdermal:Patch formulations for buprenorphine address populations with swallowing difficulties or gastrointestinal absorption variability. Hospice and palliative care channels show concentrated uptake.
- Sublingual:Film formulations prioritize discreet administration for workplace and stigma-sensitive contexts. Employer-sponsored programs and collegiate health services drive demand in suburban counties.
By patient count, oral administration leads. By value per course, injectable depots command the steepest premium trajectory.
End User:
Customer type determines prescriber credentialing requirements, physical infrastructure investment, and regulatory compliance burden across treatment settings.
- Hospitals:Emergency departments initiate buprenorphine through "warm handoff" protocols linking to outpatient continuation. Academic medical centers with addiction medicine fellowships drive protocol innovation.
- Rehabilitation Centers:Residential programs integrate medication-assisted therapy with behavioral interventions. Length-of-stay compression by commercial insurers is shortening induction windows.
- Outpatient Clinics:Federally Qualified Health Centers and rural health clinics leverage telehealth waivers to extend reach into prescriber-shortage counties. Nurse practitioner prescribing authority is multiplying capacity fastest in Medicaid expansion states.
- Home Healthcare:Mobile health units and visiting nurse programs serve homebound populations and justice-involved individuals under community supervision. State Medicaid home health benefit design determines penetration.
By treatment volume, outpatient clinics lead. By expansion rate, home healthcare models are gaining share fastest in rural and justice-involved populations.
Therapy Area:
Maturity stages separate established maintenance protocols from emerging relapse prevention applications in criminal justice and occupational settings.
- Detoxification:Medically supervised withdrawal management in inpatient and residential settings. Hospital-based protocols are shortening average length of stay under bundled payment pressure.
- Maintenance:Long-term agonist therapy to reduce overdose mortality and improve functional outcomes. Retention challenges from illicit fentanyl displacement are compressing average treatment duration.
- Relapse Prevention:Extended-release naltrexone for post-detoxification and post-incarceration transitions. State correctional systems represent underpenetrated channels with demonstrated mortality reduction.
- Pain Management:Buprenorphine for chronic pain in patients with concurrent opioid use disorder. DEA quota allocation tensions between addiction treatment and pain indications are creating supply friction.
By patient volume, maintenance therapy leads. By clinical priority shift, relapse prevention protocols are climbing the fastest in institutional purchasing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States, where extended-release depot formulations command medical-benefit reimbursement premiums that generic oral tablets in India cannot approach. Medicaid expansion geography and DEA waiver density determine patient access patterns across both markets. Federal funding flows and state-level parity enforcement create divergent commercial environments for medication-assisted therapy.
United States
Federally Qualified Health Centers in Medicaid expansion states drive buprenorphine volume through nurse practitioner prescribing authority. SAMHSA telehealth waivers extend reach into rural counties with prescriber shortages. Appalachia and the Southwest face treatment deserts despite medication availability, as fellowship-trained physician gaps persist.
Germany
Substitution therapy protocols in North Rhine-Westphalia and Bavaria emphasize methadone maintenance through specialized addiction medicine centers. The country's national pharmaceutical regulator, the Federal Institute for Drugs and Medical Devices, maintains strict opioid substitution guidelines. Berlin-Brandenburg clusters host harm reduction services co-locating naloxone distribution with treatment referrals.
United Kingdom
Community pharmacy-based opioid substitution programs in London and the Midlands expand supervised consumption capacity. NHS England funding allocations prioritize long-acting injectable formulations for populations with adherence challenges. Scotland's public health approach integrates naloxone provision with housing and social services.
India
Active pharmaceutical ingredient manufacturing for naltrexone concentrates in Gujarat and Maharashtra chemical parks, exposing supply chains to export control volatility. The Central Drugs Standard Control Organization regulates buprenorphine formulations under narcotic control schedules. Hyderabad-based contract manufacturers supply generic oral tablets to African and Southeast Asian markets.
Australia
Take-home naloxone programs in New South Wales and Victoria create distribution nodes linking to medication-assisted therapy referrals. The Therapeutic Goods Administration approval pathways for depot formulations lag FDA timelines by 18-24 months. Queensland's rural health networks pilot telehealth prescribing for remote Indigenous communities.
Opioid Use Disorder Treatment Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with extended-release depot specialists commanding premium reimbursement while generic oral tablet producers compete on manufacturing scale. The market structures around three tiers: patent-protected formulation innovators, authorized generic filers, and commodity API-to-tablet integrators. Dominant competitive moves include strategic partnerships between depot manufacturers and institutional purchasers, plus portfolio diversification into combination therapies.
Among specialty pharmaceutical developers, Alkermes plc and Indivior PLC exemplify the formulation innovation archetype, while Hikma Pharmaceuticals PLC represents the vertically integrated generic producer tier. These anchors occupy positions that reflect divergent capital intensity requirements and prescriber certification dependencies.
| Leading Market Players |
|---|
| Titan Pharmaceuticals, Inc. |
| BioDelivery Sciences International Inc. |
| Indivior PLC |
| Hikma Pharmaceuticals PLC |
| Viatris Inc. |
| Alkermes plc |
| Mallinckrodt Pharmaceuticals |
| Camurus AB |
| Orexo AB |
| Others |
Value Network & Pricing Analysis
DEA production quota utilization rates for buprenorphine API shape both manufacturing scale thresholds and generic tablet price floors across the United States. Capacity concentration in high-volume oral tablet producers compresses margins for commodity formulations while creating premium capture opportunities for depot injectable specialists.
Pricing Analysis
The customization-premium spread between standard oral generics and configured-to-order depot formulations structures reimbursement arbitrage across pharmacy and medical benefit channels. A three-tier pricing structure across premium depot injectables, standard sublingual films, and economy oral tablets governs Medicaid formulary placement and prescriber incentive alignment. Price differentiation rests on DEA certification tier and prescriber waiver density rather than manufacturing cost alone. Cost compression in the oral generic tier is intensifying because of Indian API oversupply, while employer-sponsored programs show lowest price sensitivity for discreet film formulations.
Supply Chain Analysis
Just-in-time inventory strategies dominate generic oral tablet distribution through retail pharmacy chains, while strategic stockpiling of extended-release naltrexone depots characterizes institutional procurement by correctional systems. Active pharmaceutical ingredient manufacturing concentrates in India, China, and the United States, with buprenorphine base material drawing from Gujarat chemical parks and naltrexone precursors anchored in Chinese bulk synthesis facilities. Supply chain risk centers on single-source vulnerability for depot formulation polymers used in six-month implantable devices. Distribution runs through specialty pharmacies for injectables and 340B-eligible entities for oral generics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics inflection in medication-assisted therapy is accelerating through SAMHSA interoperability mandates linking prescription drug monitoring programs across state lines, creating data-network effects that favor integrated care delivery systems over fragmented prescriber pools.
For Market Incumbents: Compound prescriber certification capacity through nurse practitioner training partnerships in Medicaid expansion states to offset physician shortage constraints. Defend depot formulation margins by deepening institutional purchasing relationships with state correctional systems before authorized generic entry erodes exclusivity windows. Vertical integration into polymer supply for long-acting injectables mitigates single-source API concentration risk from Indian chemical parks.
For New Entrants and Emerging Players: Differentiate on telehealth-enabled induction protocols that bypass brick-and-mortar OTP infrastructure constraints in rural treatment deserts. Target justice-involved populations through pre-release medication initiation programs in state correctional systems, the most penetrable channel with demonstrated mortality reduction outcomes. A direct-to-payer contracting model with Medicaid managed care organizations offers fastest formulary access without legacy pharmacy benefit manager rebate structures.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among extended-release depot manufacturers with six-month dosing intervals and institutional procurement contracts. Long-term viability over the projection horizon favors platform players integrating digital adherence monitoring with physical drug delivery. Acquisition target archetype: specialty pharmaceutical developers with FDA-approved depot formulations and underutilized manufacturing capacity. The signal to watch as inflection indicator is DEA production quota reallocation between buprenorphine and traditional pain management opioids.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Phase III readouts for combination buprenorphine-naloxone depots extend patent-protected lifecycle beyond oral generic erosion. |
| Regulatory Approval Pathway | REMS modifications for extended-release injectables determine prescriber pool expansion and geographic reach into waiver-shortage counties. |
| Manufacturing Scale-Up | Depot formulation capacity additions in the United States reduce API concentration risk from Indian and Chinese chemical parks. |
| Pipeline Diversification | Alpha-2 agonist combinations for withdrawal management address hospital discharge protocol gaps in academic medical centers. |
| Strategic Partnership | Telehealth platform integrations with Federally Qualified Health Centers multiply prescriber capacity in rural Medicaid expansion states. |
Research Methodology
Operator-level perspectives from addiction medicine physicians, DEA-authorized nurse practitioners, pharmacy benefit managers, and state Medicaid formulary directors anchored the qualitative base for this analysis. Primary interviews with formulary access specialists and 340B program administrators combined with secondary validation against FDA approval databases, SAMHSA waiver registries, CMS Medicare/Medicaid utilization files, and state prescription drug monitoring program reports. Bottom-up patient-volume estimates by delivery mode and top-down spending projections by payer source underwent triangulation to reconcile demand-side and supply-side perspectives.
Sensitivity analysis across the modeling period tested alternative scenarios for DEA production quota trajectories, Medicaid expansion state participation rates, and telehealth prescribing waiver permanence. The analytical framework segmented volume and value outputs by product type, delivery mode, end-user setting, and therapy area, with regional regulatory clusters capturing state-level parity enforcement variation. CAGRs derived from patient enrollment trends, dosing frequency assumptions, and reimbursement rate evolution across pharmacy versus medical benefit billing. Industry-specific forecast inputs included buprenorphine waiver density maps and correctional system medication-assisted therapy adoption curves.
The analysis sits within stated boundaries; outcomes outside sustained federal funding for substance use disorder services and stable DEA scheduling classifications would require recalibration. Forecasts reflect documented assumptions regarding prescriber capacity expansion rates and institutional procurement cycle timing. Practitioners should keep alternative scenarios live as SAMHSA guideline revisions and proposed legislation around prescribing flexibility evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Addiction Treatment
Global Addiction Treatment Market
Addiction Treatment
Alcohol Use Disorder Treatment Market
Addiction Treatment
Substance Abuse Treatment Market
Addiction Treatment
Drug Free Depression Treatment Market
Addiction Treatment
Global Substance Use Disorder Treatment Market
Addiction Treatment
Opioid Induced Constipation Treatment Market
Addiction Treatment
Cocaine Intoxication Treatment Market
Addiction Treatment
Nicotine De-Addiction Products Market
Addiction Treatment
Opioid Use Disorder (OUD) Market
Addiction Treatment
Methadone Market
Addiction Treatment
Smokeless Tobacco Treatment Market
Addiction Treatment
Opioid Withdrawal Treatment Market
Addiction Treatment
US Mental Health and Addiction Treatment Centers Market
Addiction Treatment
US Ketamine Clinics Market