
 Karyotype Analysis Service Market | 2026-2036
Karyotype Analysis Service Market Size, Share, and Industry Trends Forecast 2026-2036
Karyotype Analysis Service Market Insights
Next-generation sequencing integration is fragmenting the traditional karyotype analysis technology stack, splitting service workflows between high-throughput platforms and legacy cytogenetic methods. Thermo Fisher Scientific leverages its instrument-to-service pipeline to anchor clinical laboratory contracts across North America. Labcorp competes through its national diagnostics network, sustaining volume advantages in routine chromosome screening. Creative Bioarray specializes in custom research-grade karyotyping, occupying a narrower but defensible niche in preclinical toxicology studies.
Karyotype analysis service denotes the laboratory examination of chromosome number, structure, and banding patterns in metaphase cells, typically employing G-banding at 400-550 band resolution or fluorescence in situ hybridization with labeled DNA probes to detect translocations, aneuploidy, and microdeletions. Its primary purpose spans prenatal diagnosis of chromosomal abnormalities, hematologic malignancy characterization, and constitutional disorder confirmation in pediatric and reproductive medicine. Diagnostic Testing leads service type revenue as hospital laboratories outsource complex cytogenetic interpretations, while Research Services capture expanding demand from pharmaceutical toxicology programs. Array CGH technology segments gain traction for submicroscopic copy-number variant detection, though fluorescence in situ hybridization retains dominance in targeted oncology panels where specific gene rearrangements guide therapy selection.
FDA oversight of laboratory-developed tests and CLIA certification requirements shape operational compliance burdens for US-based service providers, while EMA's In Vitro Diagnostic Regulation in Europe imposes new clinical evidence standards on chromosome analysis kits used in diagnostic workflows. China's NMPA accelerates review pathways for innovative genetic testing services under revised medical device classification rules. Stakeholders must monitor evolving payer coverage policies for non-invasive prenatal screening alternatives that threaten conventional karyotype volumes in routine obstetric practice.
Market Dynamics
Next-generation sequencing platforms are compressing turnaround times for chromosome analysis from weeks to days, forcing service laboratories to retire G-banding microscopes and retrain cytogenetic technologists for bioinformatics pipelines.
Growth Catalysts
- EMA MDR Implementation:The EU's Medical Device Regulation mandates enhanced clinical evidence for IVD kits, pushing hospital laboratories toward certified service providers with established quality management systems.
- Oncology Precision Medicine:Hematologic malignancy characterization now requires karyotype-FISH panels to guide targeted therapy selection, expanding clinical volumes in cancer centers.
- China's Revised Medical Device Rules:NMPA's accelerated review pathways for innovative genetic testing services enable faster market entry for chromosome analysis platforms in domestic fertility clinic networks.
Market Restraints
- Fluorophore Supply Concentration:Specialized FISH probe manufacturing concentrates among a handful of European and North American suppliers, creating input cost volatility for service laboratories.
- Technical Resolution Limits:Conventional G-banding at 400-550 band resolution fails to detect submicroscopic copy-number variants, ceding ground to array CGH for constitutional disorder diagnosis.
- NIPT Substitution Threat:Cell-free DNA screening for common aneuploidies now dominates routine prenatal risk assessment, eroding conventional amniocentesis karyotyping volumes in obstetric practice.
Strategic Opportunities
- Preclinical Toxicology Services:Pharmaceutical sponsors require GLP-compliant karyotyping for chromosomal aberration studies, opening dedicated contract research revenue streams.
- India's Fertility Clinic Expansion:Assisted reproduction center networks in Mumbai, Delhi, and Bangalore lack in-house cytogenetics capacity, creating outsourcing demand for preimplantation genetic diagnosis support.
- AI-Assisted Karyotyping:Machine learning classifiers for chromosome band pattern recognition are converging with cloud-based image analysis, enabling remote interpretation services.
Industry Challenges
- Cytogeneticist Workforce Scarcity:Board-certified clinical laboratory geneticists require 5-7 years of specialized training, creating recruitment bottlenecks for high-complexity test interpretation.
- LIMS Integration Complexity:Legacy laboratory information management systems require costly middleware development to interface with NGS data pipelines and regulatory reporting modules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Karyotype Analysis Service Market |
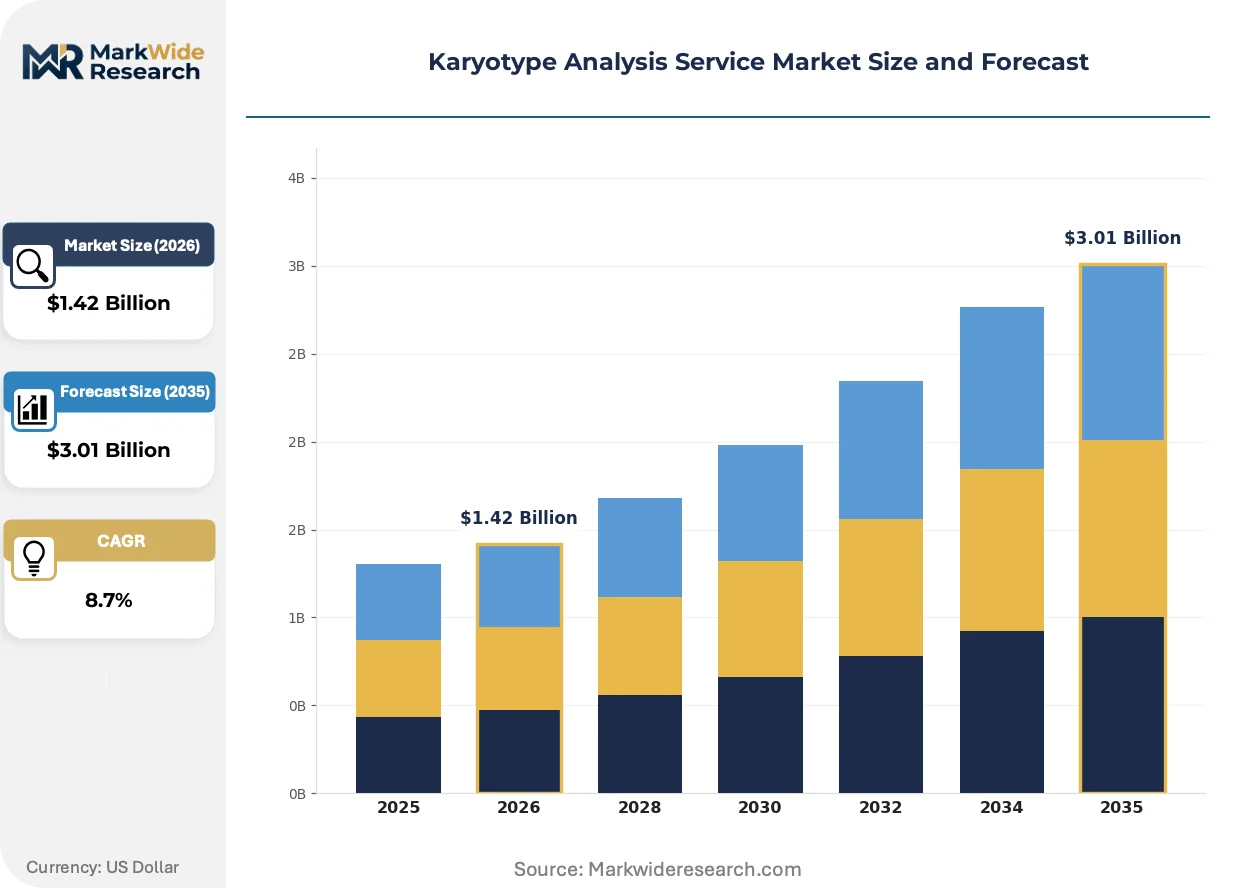
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $3.01 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Diagnostic Testing, Genetic Counseling, Research Services, Clinical Trials Application: Cancer Diagnosis, Prenatal Testing, Genetic Disorders, Reproductive Health End User: Hospitals, Laboratories, Research Institutions, Fertility Clinics Technology: Fluorescence In Situ Hybridization, Microscopy, Array CGH, Next-Generation Sequencing |
| Companies Covered | Thermo Fisher Scientific, Labcorp, Igenomix, Creative Bioarray, Applied StemCell, Cell Guidance Systems, KaryoLogic, Inc, Creative Biolabs, Beijing Abaco Biotechnology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Karyotype Analysis Service Market Trends and Innovations
Chromosome analysis workflows are fragmenting across multiple technology platforms, with service providers rebuilding operational models around digital pathology infrastructure and automated sample tracking systems.
Optical genome mapping is rendering obsolete conventional metaphase preparation for structural variant detection in hematologic malignancy workups. Academic medical centers in Germany and the United States are adopting Bionano Genomics platforms for rapid leukemia karyotyping. The technology is rendering obsolete manual chromosome counting and band pattern interpretation in high-volume oncology reference laboratories.
CLIA certification requirements for laboratory-developed tests now mandate ongoing proficiency testing and personnel competency documentation for cytogenetic analysis. FDA oversight of companion diagnostics used in targeted oncology therapy selection is tightening analytical validation standards for FISH probe kits. Hospital laboratories in the United States are consolidating chromosome analysis outsourcing to maintain compliance with evolving quality system regulations.
Direct-to-physician digital reporting platforms are replacing faxed PDF karyotype summaries in fertility clinic networks. Reproductive endocrinology practices now expect real-time case management portals with integrated genetic counselor consultation scheduling. This channel shift is most visible in United States metropolitan markets where electronic health record integration drives purchasing decisions for reference laboratory contracts.
Karyotype Analysis Service Market Segmentation
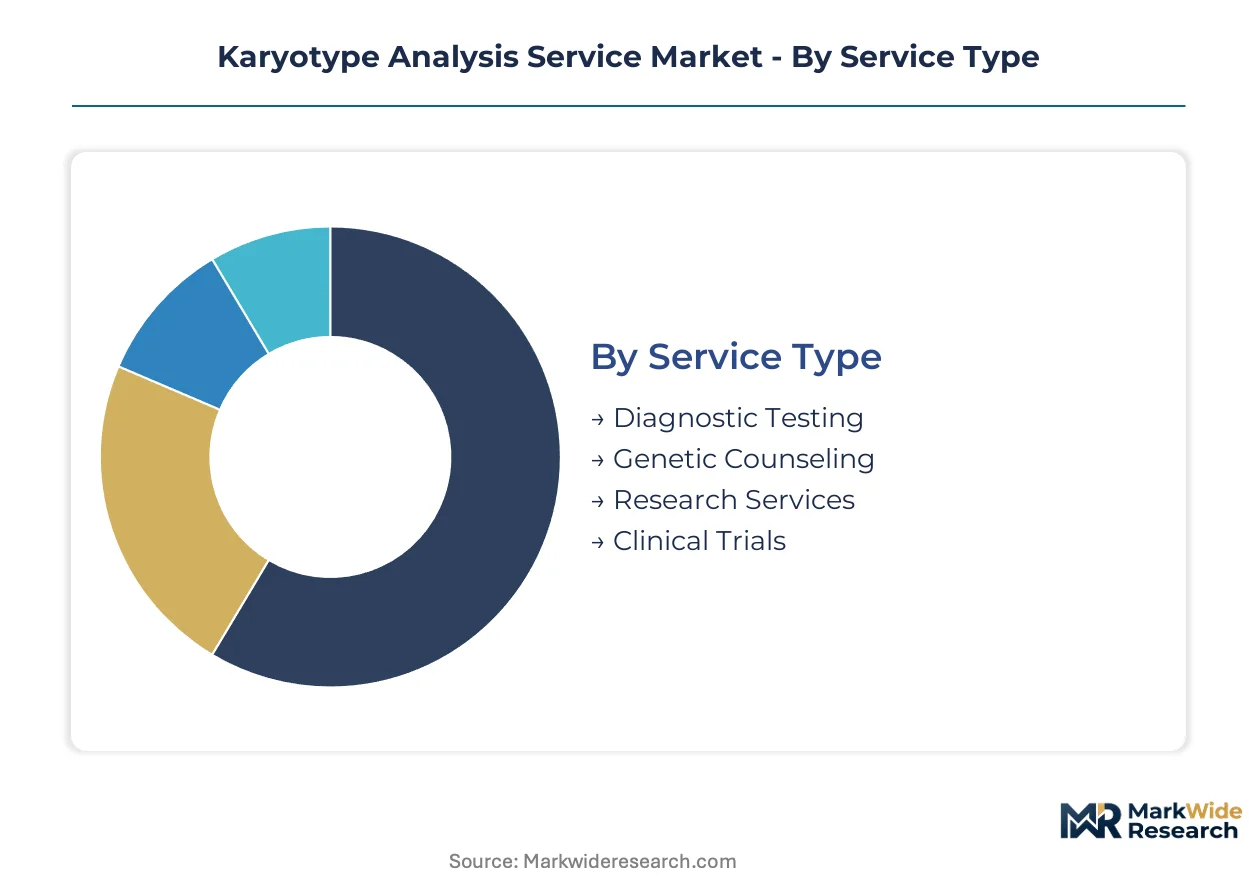
Karyotype analysis service providers configure their operational models around distinct service tiers, each carrying different margin profiles and regulatory obligations. Segmentation clarity enables laboratories to allocate capital between high-throughput diagnostic platforms and specialized research collaborations.
Service Type:
Mature revenue streams coexist with emerging specialized offerings across the service spectrum.
- Diagnostic Testing:Chromosome analysis for constitutional disorders and malignancy characterization operates under CLIA and CAP accreditation requirements. Hospital laboratories in the United States and Germany outsource complex interpretations to maintain compliance with evolving quality system regulations.
- Research Services:Preclinical toxicology karyotyping for pharmaceutical sponsors demands GLP compliance and dedicated protocol design. Contract research organizations in China and India are expanding chromosomal aberration study capacity to capture toxicology outsourcing from Western sponsors.
- Genetic Counseling:Interpretation support and physician consultation services bridge cytogenetic findings with clinical decision-making.
- Clinical Trials:Prospective patient screening and pharmacogenomic companion testing for oncology trials.
Diagnostic Testing handles the majority of throughput; Research Services is the fastest mover on share.
Application:
Volume concentration varies sharply between routine screening and complex diagnostic workups.
- Cancer Diagnosis:Hematologic malignancy karyotyping guides targeted therapy selection through FISH panels for specific gene rearrangements. Oncology reference laboratories in Germany and the United States are adopting optical genome mapping platforms to compress leukemia characterization turnaround times.
- Prenatal Testing:Conventional amniocentesis karyotyping faces volume pressure from cell-free DNA screening alternatives in routine obstetric practice.
- Genetic Disorders:Constitutional abnormality confirmation for pediatric and adult patients with developmental delays or unexplained phenotypes.
- Reproductive Health:Preimplantation genetic diagnosis support for assisted reproduction centers in Mumbai, Delhi, and Bangalore lacking in-house cytogenetics capacity.
Cancer Diagnosis commands premium pricing per case; Reproductive Health is climbing the fastest as fertility clinic networks expand across Asia.
End User:
Customer type determines service level agreements, turnaround expectations, and integration complexity.
- Hospitals:Academic medical centers require comprehensive cytogenetic interpretation with integrated pathology consultation. Consolidation of chromosome analysis outsourcing is accelerating as hospital laboratories retire legacy G-banding microscopes.
- Laboratories:Reference and commercial laboratories compete on national logistics networks and electronic health record integration.
- Research Institutions:Academic collaborators demand flexible protocol adaptation and publication-grade documentation.
- Fertility Clinics:Reproductive endocrinology practices expect real-time case management portals with genetic counselor consultation scheduling.
Hospitals anchor the installed base; Fertility Clinics show the steepest expansion trajectory as assisted reproduction center networks proliferate.
Technology:
Platform selection dictates capital intensity, personnel requirements, and competitive differentiation.
- Fluorescence In Situ Hybridization:Targeted probe panels for specific gene rearrangements retain dominance in oncology workflows where therapy selection depends on discrete chromosomal breakpoints. FISH manufacturing concentration among European and North American suppliers creates input cost volatility.
- Next-Generation Sequencing:High-throughput platforms compress chromosome analysis turnaround from weeks to days, forcing retraining of cytogenetic technologists for bioinformatics pipelines.
- Microscopy:Conventional G-banding at 400-550 band resolution remains necessary for constitutional disorder diagnosis despite resolution limitations.
- Array CGH:Submicroscopic copy-number variant detection for developmental delay and autism spectrum disorder evaluations.
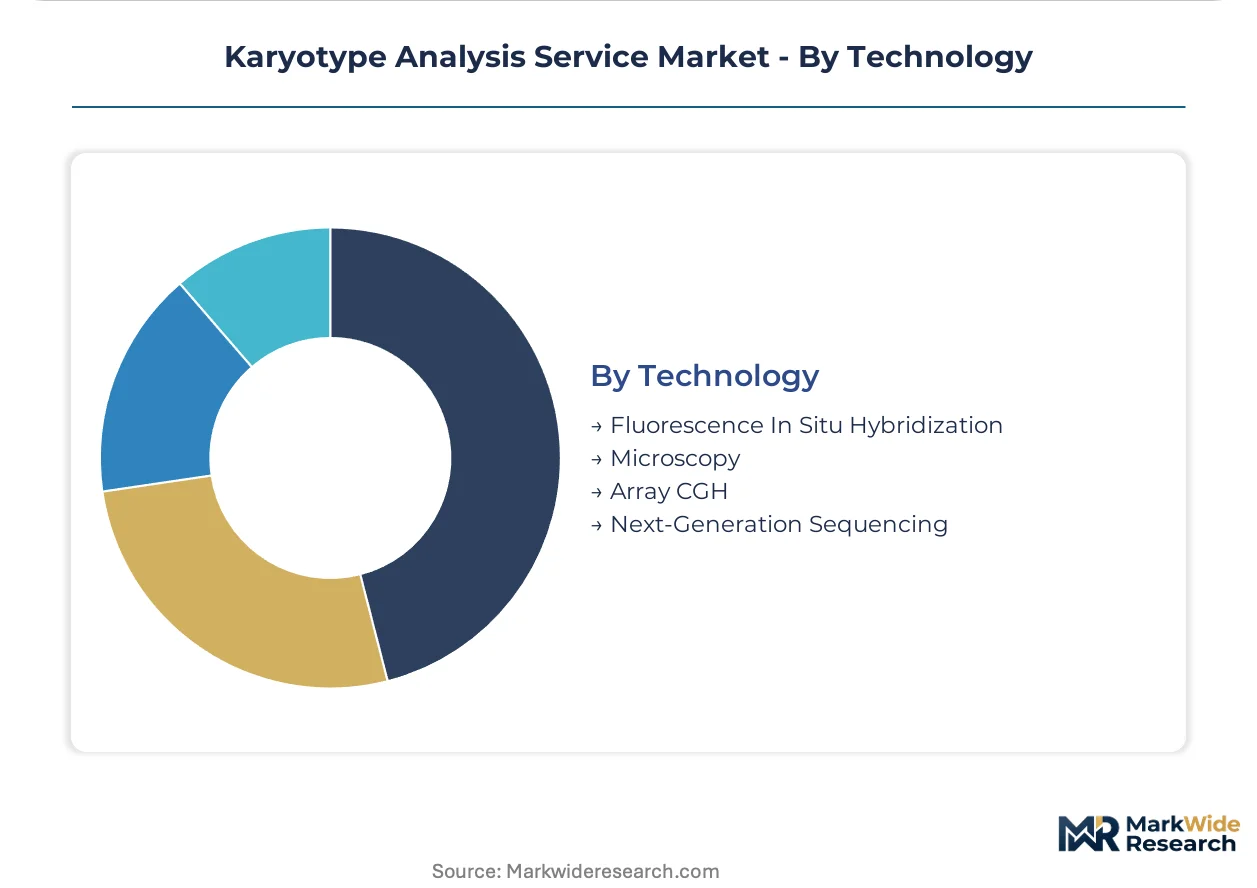
Fluorescence In Situ Hybridization maintains the largest installed instrument base; Next-Generation Sequencing is gaining share fastest as service laboratories rebuild workflows around digital infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Service exports from United States-based laboratories flow into Canadian fertility networks and European research consortia, while Chinese providers supply chromosome analysis to Southeast Asian assisted reproduction centers.
United States
Hospital laboratory outsourcing and fertility clinic network expansion drive service demand. FDA oversight of laboratory-developed tests and CLIA certification requirements shape operational compliance. Academic medical centers in Boston and San Francisco adopt optical genome mapping for rapid leukemia characterization.
Germany
Oncology precision medicine protocols and hematologic malignancy research programs expand clinical volumes. EMA's In Vitro Diagnostic Regulation imposes new clinical evidence standards on chromosome analysis kits. Reference laboratories in Munich and Heidelberg consolidate complex cytogenetic interpretations for hospital networks.
China
Domestic fertility clinic scaling and pharmaceutical toxicology outsourcing create dual demand channels. NMPA accelerates review pathways for innovative genetic testing services under revised medical device classification rules. Assisted reproduction centers in Beijing and Shanghai lack in-house cytogenetics capacity, driving outsourcing to certified service providers.
India
Assisted reproduction center proliferation in metropolitan markets generates preimplantation genetic diagnosis demand. The country's national pharmaceutical regulator maintains quality standards for diagnostic laboratory accreditation. Fertility clinic networks in Mumbai, Delhi, and Bangalore contract chromosome analysis services from domestic and international providers.
United Kingdom
National Health Service prenatal screening protocol revisions tighten quality requirements for cytogenetic services. The national health technology assessment body evaluates coverage for non-invasive prenatal screening alternatives. London-based reference laboratories serve both domestic hospital networks and European research collaborations.
Karyotype Analysis Service Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented service tiers. Full-service diagnostic networks leverage national logistics and electronic health record integration. Niche research-grade providers occupy defensible positions in preclinical toxicology and custom protocol design. Strategic moves concentrate on technology platform transitions and geographic expansion into underserved fertility clinic markets.
Among North American full-service networks, Thermo Fisher Scientific and Labcorp represent scale-driven archetypes with instrument-to-service pipelines and national diagnostic footprints. Creative Bioarray occupies a specialist position in custom research-grade karyotyping for pharmaceutical toxicology programs. These three entities exemplify the competitive spectrum from integrated platform control to narrow application expertise.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Labcorp |
| Igenomix |
| Creative Bioarray |
| Applied StemCell |
| Cell Guidance Systems |
| KaryoLogic, Inc |
| Creative Biolabs |
| Beijing Abaco Biotechnology |
| Others |
Pricing and Supply Chain Analysis
Single-source fluorophore dependency for FISH probe manufacturing determines both the premium-to-economy pricing spread across service tiers and the geographic clustering of certified laboratory networks. European and North American suppliers of specialized fluorescent dyes wield disproportionate leverage over input costs, compressing margins for mid-tier providers while entrenching price premiums for vertically integrated platform operators.
Pricing Analysis
The technology-generation pricing gap separates legacy G-banding microscopy services from next-generation sequencing platforms and emerging optical genome mapping workflows. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with CLIA-CAP dual-accredited laboratories commanding substantial premiums over research-grade providers. Cost compression in standard-tier diagnostic testing is intensifying because NGS automation reduces per-sample labor content. Fertility clinics show highest price sensitivity due to cash-pay patient volumes, while pharmaceutical toxicology sponsors demonstrate lowest sensitivity given GLP compliance requirements.
Supply Chain Analysis
Export-control regime restrictions on high-resolution imaging components and specialized fluorophore chemistries limit technology transfer to certain jurisdictions, constraining supply chain configuration. Manufacturing concentrates in Germany, the United States, and Japan for precision optical instruments, while China dominates consumables production for standard-grade reagents. Raw material dependencies include rare-earth fluorophores, high-purity glass substrates, and synthetic DNA probe libraries. Single-source vulnerability pervades the FISH probe segment where three European suppliers control specialized dye synthesis. Distribution runs through instrument leasing programs bundled with per-test reagent supply contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment creates durable competitive advantages. CLIA certification requirements and multi-year proficiency testing obligations generate switching costs that protect incumbent positions.
For Market Incumbents: Entrench platform control through backward integration into fluorophore manufacturing and captive supply of specialized probe chemistries. Expand capacity in India's fertility clinic corridors before domestic competitors achieve scale. NIPT substitution technology threatens conventional prenatal karyotyping volumes; counter by embedding optical genome mapping into oncology reference laboratory contracts.
For New Entrants and Emerging Players: Pursue white-space opportunities in preclinical toxicology karyotyping for Chinese pharmaceutical sponsors seeking GLP-compliant chromosomal aberration studies. India's assisted reproduction center networks in Mumbai and Delhi represent the most penetrable geography given cytogenetics capacity shortages. A cloud-based AI-assisted karyotyping service model enables remote interpretation without capital-intensive instrument deployment.
For Investors and Strategic Acquirers: EMA MDR implementation reshapes the acquisition landscape by elevating quality management system valuations. Long-term viability centers on laboratories with established clinical evidence dossiers and hospital network integration. Target acquisition archetype: mid-scale providers with dual CLIA-CAP accreditation and existing fertility clinic channel relationships. The signal to watch is NMPA accelerated review pathway approvals for domestic Chinese chromosome analysis platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| Optical Genome Mapping Platform Deployment | Bionano Genomics instrumentation compresses leukemia characterization turnaround at German academic medical centers. |
| GLP-Compliant Toxicology Service Expansion | Preclinical chromosomal aberration studies capture pharmaceutical outsourcing from Western sponsors to Chinese CROs. |
| AI-Assisted Karyotyping Development | Machine learning classifiers for chromosome band pattern recognition enable remote interpretation services. |
| Fertility Clinic Network Integration | Real-time case management portals with genetic counselor scheduling secure reference laboratory contracts in US metropolitan markets. |
| Fluorophore Manufacturing Backward Integration | In-house probe synthesis reduces input cost volatility from European and North American supplier concentration. |
Research Methodology
Cross-validation between primary stakeholder interviews and secondary regulatory filings anchors the qualitative findings in documented operational realities. Conversations with clinical laboratory directors, cytogenetic technologists, fertility clinic operations managers, and pharmaceutical toxicology study directors combined with FDA 510(k) submissions, EMA In Vitro Diagnostic Regulation guidance documents, and NMPA medical device classification rulings. Bottom-up service volume estimates from hospital outsourcing patterns and top-down market sizing from instrument installation bases triangulate to consistent ranges.
Calibration against historical technology substitution patterns in molecular diagnostics informs the projection framework. Segmentation dimensions modeled include service type tier, technology platform generation, application area, end-user category, and regional regulatory cluster. CAGRs derive from fitted adoption curves for NGS platform displacement of conventional microscopy. Industry-specific forecast inputs incorporate fertility clinic network expansion rates and oncology precision medicine protocol penetration.
Sensitivities concentrate around NIPT substitution velocity, fluorophore supply disruptions, and regulatory timeline shifts for novel platform approvals. Forecasts reflect assumptions about CLIA certification continuity and hospital laboratory outsourcing momentum. Material shifts in cell-free DNA screening reimbursement policy or export control restrictions on imaging components would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Diagnostics
Telepathology Market
Medical Diagnostics
Circulating Tumor Cells (Ctcs) Prognostic Technologies Market
Medical Diagnostics
Flow Cytometry Market
Medical Diagnostics
MUC1 Antibody Market
Medical Diagnostics
Fluid Biopsy Market
Medical Diagnostics
Middle East and Africa Circulating Tumor Cells (CTC) Liquid Biopsy Market
Medical Diagnostics
Dosimetry Market
Medical Diagnostics
Medical Isotope Market
Medical Diagnostics
Global Histology and Cytology Market
Medical Diagnostics
Global Hydrophobic Interaction Chromatography Market
Medical Diagnostics
Rapid Medical Diagnostic Kits Market
Medical Diagnostics
Stem Cell Panel Market
Medical Diagnostics
Stem Cell Characterization Kits Market
Medical Diagnostics
Global Complete Blood Count Device Market
Medical Diagnostics
North America Flow Cytometry Market
Medical Diagnostics
Real-Time PCR, Digital PCR, and End-Point PCR Market