
 Asia Pacific Open System MRI Market | 2026-2036
Asia Pacific Open System MRI Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Open System MRI Market Outlook
Fragmentation across India's private diagnostic chains and China's county-level hospitals is recalibrating procurement patterns for open system MRI equipment. GE Healthcare leverages its established service infrastructure across secondary cities in India. Siemens Healthineers anchors its position through localized manufacturing partnerships that reduce import duty exposure. Shanghai United Imaging Healthcare Co., Ltd competes aggressively on total cost of ownership for mid-field open systems.
Open system MRI employs a vertically oriented or laterally open magnet architecture, typically operating at field strengths below 1.0 Tesla, designed to eliminate the enclosed tunnel geometry of conventional closed-bore scanners and accommodate patients with anxiety disorders, obesity, or limited mobility. The technology serves diagnostic imaging workflows where patient compliance and positioning flexibility outweigh the absolute signal-to-noise ratio advantages of high-field closed systems. Low Magnetic Field systems occupy the volume tier across price-sensitive Southeast Asian markets, while Functional MRI applications command premium positioning in research institutions across Japan and South Korea. Hybrid MRI configurations represent the fastest-growing technology segment as interventional suites in Australia's major teaching hospitals integrate intraoperative imaging capability.
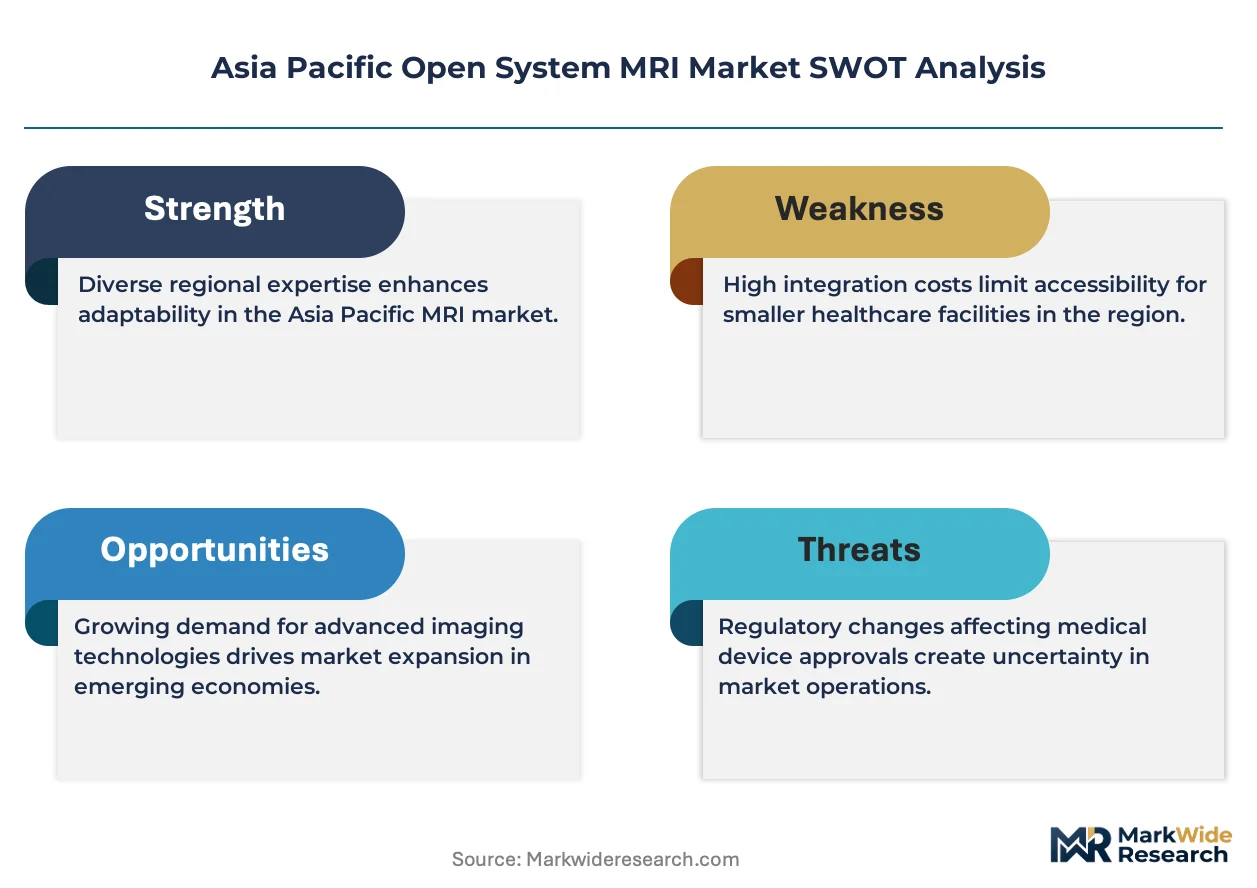
Japan's PMDA enforces stringent electromagnetic compatibility and clinical efficacy standards that extend product development timelines for open system platforms seeking market authorization. China's NMPA and India's CDSCO maintain divergent labeling requirements for magnetic field exposure limits, complicating regional product standardization strategies for multinational manufacturers. Australia's TGA alignment with IEC 60601-2-33 facilitates faster regulatory convergence with European technical standards. Stakeholders must weigh the trade-off between centralized high-field hub models and distributed open-system networks as reimbursement frameworks evolve across Asia Pacific markets.
Market Dynamics
China's NMPA streamlined registration pathways are accelerating domestic manufacturing scale-up, compressing import dependency timelines and recalibrating competitive positioning across Southeast Asian procurement networks.
Growth Catalysts
- India's CDSCO labeling harmonization:Simplified magnetic field exposure documentation reduces technical barriers for private diagnostic chains expanding into tier-2 cities.
- Hybrid MRI-CT interventional suites:Australian teaching hospitals drive demand for intraoperative imaging configurations that merge open-architecture accessibility with real-time guidance capability.
- Obesity prevalence patterns:Southeast Asian healthcare infrastructure adapts scanner specifications to accommodate bariatric patient populations previously excluded from diagnostic workflows.
Market Restraints
- Helium supply concentration:Cryogen dependency on limited liquefaction capacity in Qatar and Algeria exposes superconducting magnet maintenance costs to input volatility.
- Signal-to-noise ratio ceiling:Low-field open systems below 0.5 Tesla cannot resolve fine neurological structures, restricting application scope in neuro-oncology diagnostics.
- Japan's PMDA electromagnetic compatibility testing:Extended validation timelines for open-platform architectures delay product launches by 18-24 months versus closed-bore equivalents.
Strategic Opportunities
- Indonesia's archipelago distribution gap:Mobile open-MRI units on vessel-based platforms could serve island populations outside fixed hospital infrastructure.
- China's county-level hospital upgrade mandate:Central government procurement subsidies for domestically manufactured mid-field systems create volume anchors for local producers.
- Artificial intelligence reconstruction convergence:Deep learning-based noise reduction algorithms compensate for low-field signal limitations, expanding diagnostic utility of sub-1.0 Tesla platforms.
Industry Challenges
- Clinical applications engineering shortage:Open-system positioning protocols require specialized training absent from standard radiography curricula across Philippine and Vietnamese technician programs.
- Legacy PACS integration complexity:Heterogeneous hospital IT environments in India's fragmented private diagnostic sector obstruct seamless image workflow deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Open System MRI Market |
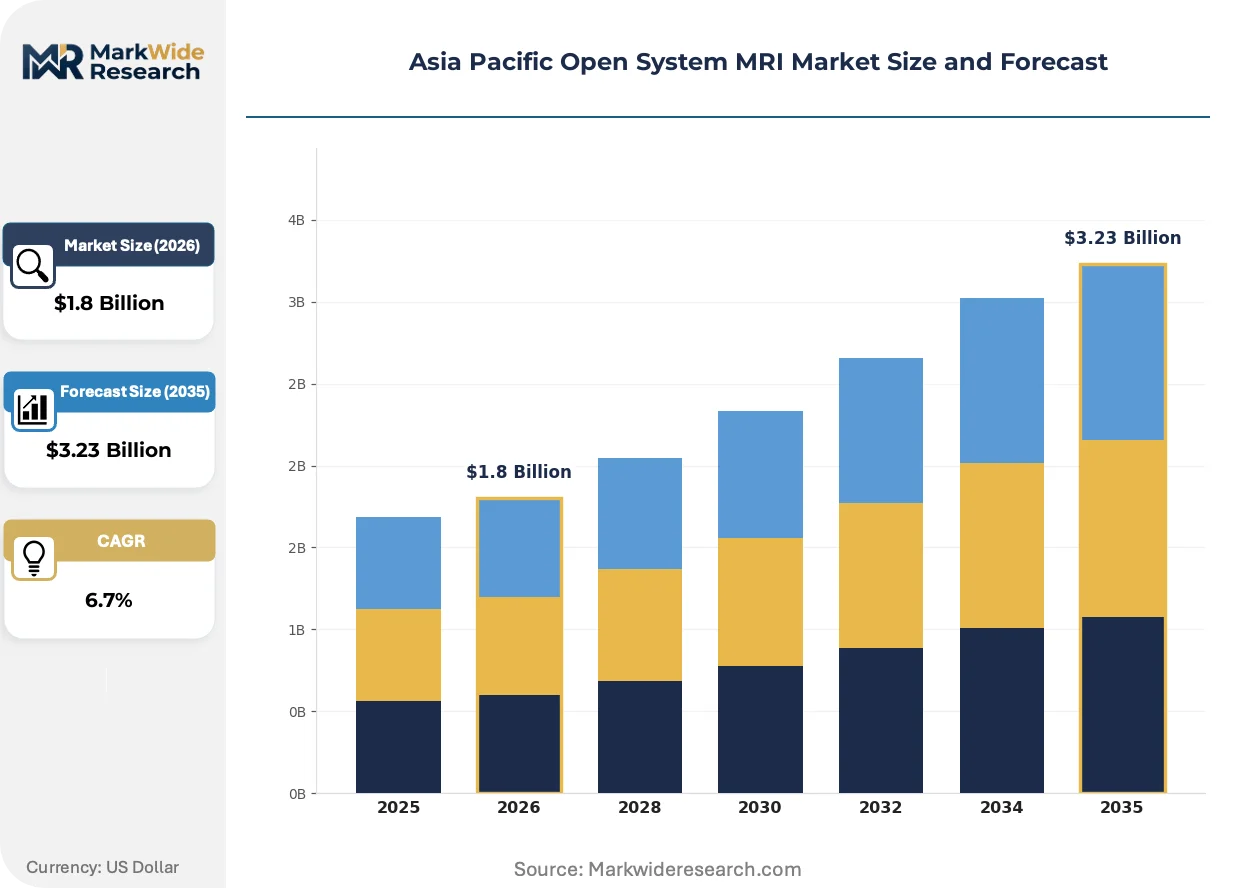
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Closed MRI, Open MRI, Extremity MRI, Portable MRI End User: Hospitals, Diagnostic Centers, Research Institutions, Imaging Clinics Technology: High Magnetic Field, Low Magnetic Field, Hybrid MRI, Functional MRI Application: Neurology, Orthopedics, Oncology, Cardiology |
| Companies Covered | GE Healthcare, Philips Healthcare, Siemens Healthineers, Canon Medical Systems, Fujifilm Corporation, Shenzhen Mindray Bio-Medical Electronics Co., Ltd, Shanghai United Imaging Healthcare Co., Ltd, Beijing Wandong Medical Technology Co., Ltd, Time Medical Holding, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Open System MRI Market Strategic Shifts
Magnet architecture evolution and regulatory pathway acceleration are compressing the traditional trade-off between patient accessibility and diagnostic resolution. Three developments merit particular attention.
Permanent magnet open-MRI technology is decentralizing diagnostic capacity beyond tertiary hospital hubs. These systems eliminate cryogen dependency and reduce siting requirements, enabling deployment in outpatient clinics and mobile screening units across Thailand's provincial health networks. Community radiology groups in Malaysia's Selangor state are adopting 0.35 Tesla permanent magnet platforms for musculoskeletal screening, shifting volume from centralized high-field facilities.
Australia's TGA alignment with IEC 60601-2-33 technical standards is accelerating regulatory convergence with European electromagnetic safety benchmarks. This harmonization reduces redundant testing burdens for manufacturers seeking multi-jurisdiction approval, compressing time-to-market for open-platform innovations. South Korean medical device exporters leverage this pathway to streamline access across Commonwealth markets.
Diagnostic chains are unbundling equipment acquisition from service contracts, forcing manufacturers to compete on discrete lifecycle cost components. India's consolidated private imaging networks now negotiate magnet replacement and software upgrade terms separately from initial hardware procurement. This disaggregation pressures vendor margins while rewarding modular platform architectures with transparent upgrade economics.
Asia Pacific Open System MRI Market Segmentation
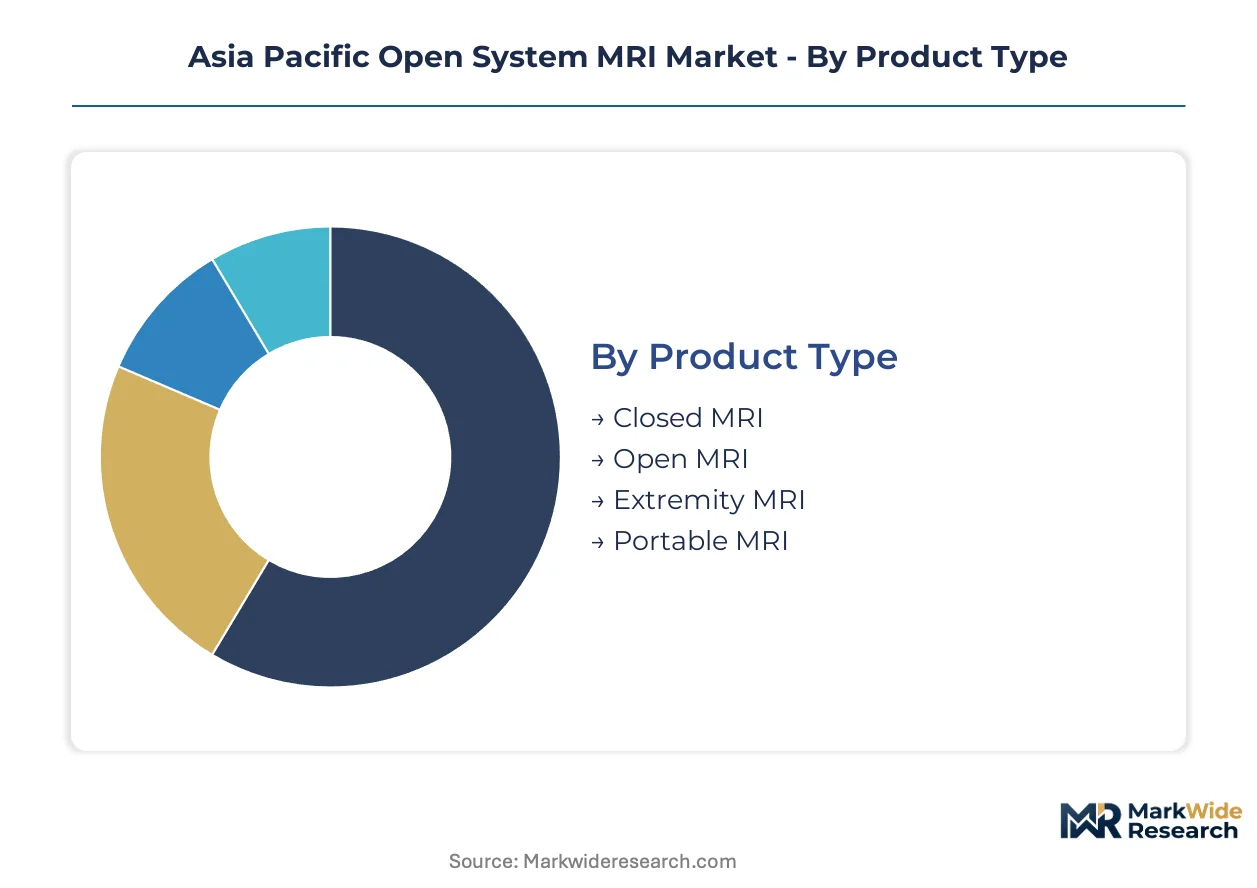
Open system MRI procurement decisions across Asia Pacific hinge on magnet architecture, clinical application scope, and siting constraints. Each segmentation dimension carries distinct regulatory burdens and reimbursement pathways that reshape vendor competitive strategy.
Product Type:
Japan's PMDA maintains separate electromagnetic compatibility dossiers for each magnet configuration, while Australia's TGA streamlines review for platforms aligning with IEC 60601-2-33 standards.
- Closed MRI:Conventional tunnel-based superconducting systems operate at 1.5 Tesla and above. Hospital procurement in South Korea concentrates here for neuro-oncology workflows where signal-to-noise ratio governs diagnostic confidence.
- Open MRI:Vertically or laterally open architectures below 1.0 Tesla eliminate claustrophobia barriers. India's tier-2 cities drive volume for these systems as private diagnostic chains target bariatric and anxiety-prone patient populations previously excluded from imaging protocols.
- Extremity MRI:Dedicated limb-scanning platforms with compact permanent magnets serve orthopedic-focused outpatient clinics across Thailand's provincial health networks.
- Portable MRI:Mobile and point-of-care configurations address archipelago distribution gaps in Indonesia and the Philippines.
Open MRI sits at the top of the volume ranking, with Portable MRI climbing the fastest as island nations confront fixed infrastructure limitations.
End User:
Reimbursement frameworks vary sharply across customer types, with research institutions commanding premium pricing and hospitals negotiating on total cost of ownership metrics.
- Hospitals:Tertiary medical centers in China's county-level hospital upgrade mandate anchor procurement volume. These facilities balance throughput demands against siting constraints for superconducting systems.
- Diagnostic Centers:India's consolidated private imaging networks now disaggregate equipment acquisition from service contracts, forcing modular platform architectures with transparent upgrade economics.
- Research Institutions:Functional MRI applications in Japanese and South Korean university hospitals command premium positioning for neuroscientific investigation protocols.
- Imaging Clinics:Community radiology groups in Malaysia's Selangor state adopt 0.35 Tesla permanent magnet platforms for musculoskeletal screening, shifting volume from centralized facilities.
Hospitals dominate installed base, though Diagnostic Centers are expanding most quickly as India's private chains penetrate secondary cities.
Technology:
Field strength selection directly determines cryogen dependency, siting requirements, and clinical application breadth across Asia Pacific procurement networks.
- High Magnetic Field:Superconducting systems at 1.5 Tesla and above require liquid helium and specialized infrastructure. Japan's PMDA enforces stringent electromagnetic compatibility standards that extend development timelines for these platforms.
- Low Magnetic Field:Sub-1.0 Tesla permanent magnet and resistive systems eliminate cryogen requirements. Southeast Asian price-sensitive markets favor these for basic musculoskeletal and abdominal imaging where absolute resolution is secondary to accessibility.
- Hybrid MRI:Interventional suite configurations merge open-architecture accessibility with real-time guidance capability. Australian teaching hospitals drive adoption for intraoperative imaging workflows.
- Functional MRI:Blood-oxygen-level-dependent imaging for neuroscientific research commands specialized software and gradient performance. South Korean and Japanese academic medical centers anchor demand.
Low Magnetic Field systems hold the broadest installed base, while Hybrid MRI gains share fastest as interventional radiology expands across Australian and Chinese tertiary centers.
Application:
Clinical indication determines field strength requirements, scan duration protocols, and reimbursement coding complexity across national health systems.
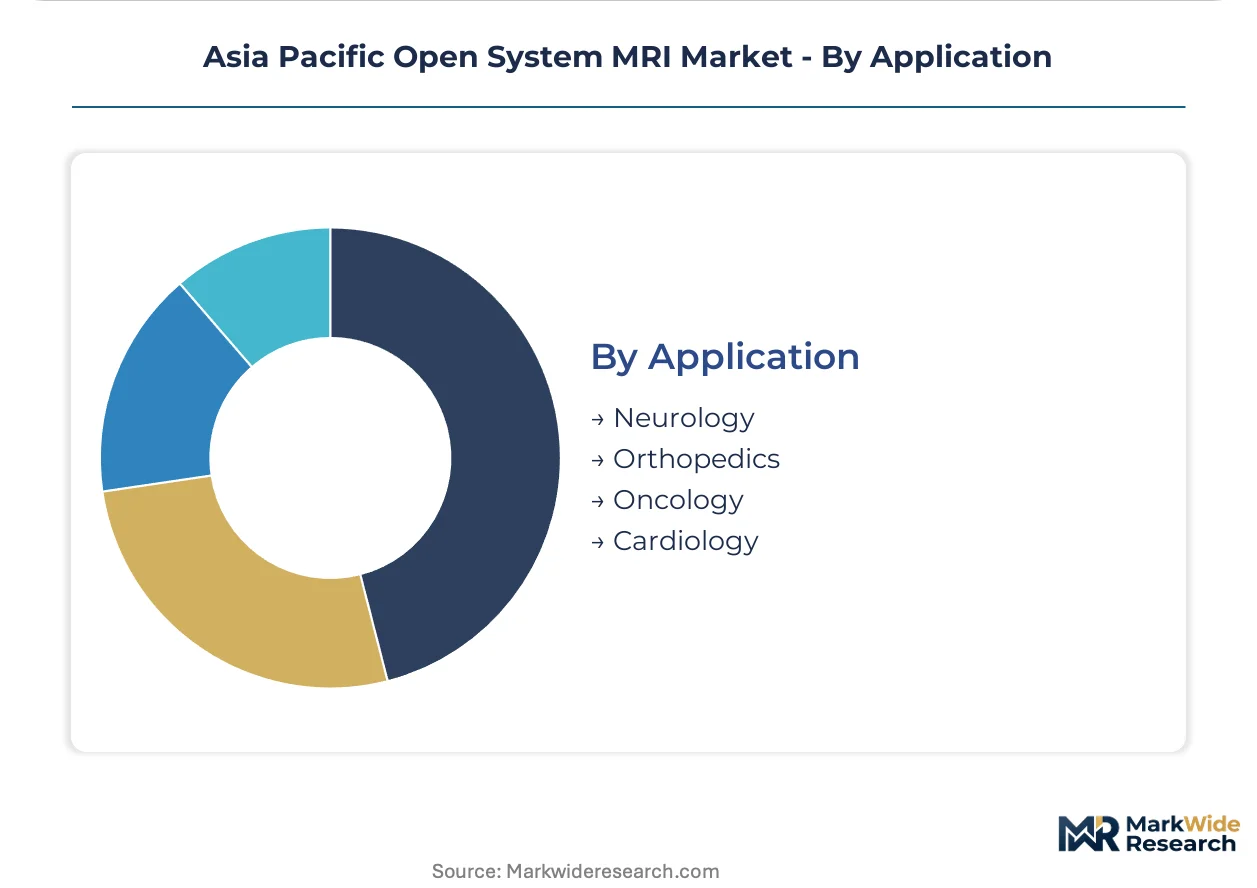
- Neurology:Brain and spinal cord imaging demands high-field closed systems for fine structural resolution. Japan's aging population concentrates procurement here for neurodegenerative disease protocols.
- Orthopedics:Musculoskeletal applications tolerate lower field strengths and shorter scan times. Community clinics across Thailand and Malaysia favor open systems for joint and spine imaging.
- Oncology:Tumor detection and staging workflows require contrast-enhanced sequences best supported by high-field platforms. China's county hospital upgrades prioritize this application for cancer screening mandates.
- Cardiology:Cardiac MRI remains underdeveloped relative to other applications, with specialized sequences requiring advanced gradient performance concentrated in South Korean and Australian reference centers.
Orthopedics leads by procedure volume, with Oncology showing the steepest expansion trajectory as China's screening programs mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's county-level hospital procurement outpaces India's private diagnostic chain expansion, though both markets favor open-architecture systems for distinct patient access challenges. Japan maintains premium positioning through research-grade functional imaging demand. Southeast Asian markets concentrate on cost-optimized permanent magnet platforms.
China
County-level hospital upgrades and NMPA streamlined registration accelerate domestic manufacturing scale-up. Central government procurement subsidies for mid-field systems create volume anchors for local producers. Yangtze River Delta manufacturing clusters supply permanent magnet platforms to provincial health networks across western provinces.
India
Private diagnostic chains deploy lower-field open systems in tier-2 cities to serve previously underserved bariatric and claustrophobic populations. CDSCO labeling harmonization for magnetic field exposure documentation reduces technical barriers for equipment imports. Maharashtra and Karnataka imaging networks consolidate procurement through disaggregated equipment-service contracts.
Japan
Research institutions command premium positioning for functional MRI applications in neuroscientific investigation protocols. PMDA electromagnetic compatibility testing extends product development timelines by 18-24 months versus closed-bore equivalents. Kanto region university hospitals anchor demand for advanced gradient performance systems.
Australia
Teaching hospitals drive adoption of hybrid MRI-CT interventional suites for intraoperative imaging workflows. TGA alignment with IEC 60601-2-33 technical standards accelerates regulatory convergence with European electromagnetic safety benchmarks. New South Wales and Victoria tertiary centers integrate open-architecture accessibility with real-time guidance capability.
South Korea
Academic medical centers anchor demand for blood-oxygen-level-dependent functional MRI requiring specialized software and gradient performance. MFDS maintains streamlined review pathways for platforms meeting international technical standards. Seoul Capital Area research hospitals concentrate procurement of neuroscientific investigation-grade systems.
Asia Pacific Open System MRI Market Competitive Environment
North American and European producers anchor one tier; Chinese specialists hold volume positioning through localized manufacturing partnerships. The vendor base stratifies across three tiers: established multinationals with service infrastructure depth, emerging domestic champions with cost-optimized platforms, and regional specialists in permanent magnet technology. Strategic moves center on modular platform architectures with transparent upgrade economics and backward integration into magnet component supply.
Among China-based manufacturers, Shanghai United Imaging Healthcare Co., Ltd and Beijing Wandong Medical Technology Co., Ltd exemplify the domestic champion archetype competing on total cost of ownership metrics. GE Healthcare occupies a position representing established multinational service infrastructure across secondary cities. Siemens Healthineers sits within the tier leveraging localized manufacturing partnerships to reduce import duty exposure.
| Leading Market Players |
|---|
| GE Healthcare |
| Philips Healthcare |
| Siemens Healthineers |
| Canon Medical Systems |
| Fujifilm Corporation |
| Shenzhen Mindray Bio-Medical Electronics Co., Ltd |
| Shanghai United Imaging Healthcare Co., Ltd |
| Beijing Wandong Medical Technology Co., Ltd |
| Time Medical Holding |
| Others |
Value Chain & Pricing Dynamics
Liquid helium spot pricing volatility feeds directly into superconducting magnet maintenance contracts across Southeast Asian procurement networks, compressing margins on high-field systems while permanent magnet platforms capture price-sensitive volume in India's tier-2 cities.
Pricing Analysis
Capacity additions in China's Yangtze River Delta manufacturing clusters are reshaping price floors for mid-field open systems across Asia Pacific procurement networks. Three-tier pricing structure across premium, standard, and economy levels separates research-grade functional MRI configurations from basic musculoskeletal screening platforms. Price differentiation rests on NMPA registration status and localized manufacturing partnerships that reduce import duty exposure. Cost compression in the economy tier is intensifying because domestic Chinese producers compete aggressively on total cost of ownership metrics.
Supply Chain Analysis
Dual-sourcing requirements for superconducting wire and gradient coil assemblies are mandating multi-supplier qualification across Japanese and South Korean OEM procurement teams. Magnet manufacturing concentrates in China, Japan, and Germany, while cryogen liquefaction draws from Qatar and Algeria. Raw material dependencies include niobium-titanium superconducting filaments, rare-earth permanent magnet alloys, and liquid helium. Single-source vulnerability in cryogen supply exposes maintenance cost structures to input volatility. Distribution runs through hospital procurement committees and consolidated diagnostic chain central purchasing offices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunity concentrates in permanent magnet platforms where helium elimination and simplified siting requirements enable premium pricing in underserved geographies.
For Market Incumbents: Anchor service infrastructure depth across India's secondary cities to defend against domestic Chinese entrants competing on equipment cost. Deepen backward integration into gradient coil manufacturing to offset superconducting wire price volatility. Prioritize modular platform architectures that separate hardware procurement from software upgrade contracts, responding to diagnostic chain disaggregation trends. For New Entrants and Emerging Players: Capture Indonesia's archipelago distribution gap through vessel-based mobile MRI units serving island populations outside fixed hospital infrastructure. Target bariatric and claustrophobic patient segments in Philippine provincial health networks where permanent magnet siting flexibility outweighs resolution limitations. Pursue hospital system partnerships emphasizing total cost of ownership transparency against multinational service bundling. For Investors and Strategic Acquirers: Consolidation pressure builds where fragmented private diagnostic chains in India seek capital for tier-2 city expansion. Long-term viability favors platforms with AI reconstruction capabilities that compensate low-field signal limitations. Acquisition target archetype: regional permanent magnet specialists with established NMPA or CDSCO registration pathways. Watch helium supply contract renegotiation timing as margin inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Permanent Magnet Platform Expansion | Eliminates cryogen dependency and reduces siting costs for provincial clinic deployment. |
| NMPA Streamlined Registration Pathway | Accelerates domestic manufacturing scale-up and compresses import dependency timelines. |
| AI Reconstruction Software Development | Deep learning noise reduction expands diagnostic utility of sub-1.0 Tesla systems. |
| Mobile MRI Vessel Deployment | Archipelago-based units address Indonesia's fixed infrastructure distribution gaps. |
| Disaggregated Service Contract Unbundling | Separate hardware, magnet replacement, and upgrade terms respond to diagnostic chain procurement evolution. |
Study Parameters
Bottom-up hospital and diagnostic center procurement modeling reconciled against top-down magnet manufacturer shipment tracking forms the analytical core of this study. Primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and radiology department heads combined with secondary validation from NMPA registration databases, CDSCO device approvals, customs import records, and hospital procurement disclosures. Triangulation across stakeholder inputs and regulatory filings ensures coverage of both demand-side adoption patterns and supply-side capacity expansion.
Input-output matrices map field strength selection, magnet architecture, and end-user type against procurement volume and pricing tier across the projection horizon. Segmentation dimensions include product configuration, clinical application, technology tier, and geographic regulatory cluster. CAGRs derive from weighted average of historical shipment trajectories and forward-looking procurement pipeline assessments. Forecast inputs incorporate NMPA registration pathway acceleration, county-level hospital upgrade subsidy disbursement, and helium supply contract restructuring patterns.
Regulatory pathway delays, cryogen supply disruption, and AI reconstruction algorithm clinical validation setbacks are the dominant revision risks to modeled outcomes. Forecasts reflect assumptions on procurement subsidy continuity and technician training program scaling. Deviation in NMPA review timeline compression would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
China Computed Tomography Market
Medical Imaging
China Medical Imaging Market
Medical Imaging
China Diagnostic Imaging Equipment Market
Medical Imaging
Global AI for Radiology Market
Medical Imaging
UK Imaging Services Market
Medical Imaging
Italy Diagnostic Imaging Equipment Market
Medical Imaging
New Born Eye Imaging Systems Market
Medical Imaging
South Korea Magnetic Resonance Imaging Market
Medical Imaging
Global Artificial Intelligence in Ultrasound Imaging Market
Medical Imaging
AI Fetal Ultrasound View Detection Software Market
Medical Imaging
Smart X-Ray Detectors Market
Medical Imaging
Precision Cancer Imaging Market
Medical Imaging
Italy Digital X-Ray Market
Medical Imaging
Radiation Dose Management Market
Medical Imaging
Middle East and Africa Digital X-Ray Devices Market
Medical Imaging
Brazil Nuclear Imaging Market