
 Dosimetry Market | 2026-2036
Dosimetry Market Size, Share, and Industry Trends Forecast 2026-2036
Dosimetry Market Analysis
German precision instrumentation manufacturing is hardening as the dominant supply base for radiation measurement equipment. PTW Freiburg leverages decades of calibration protocol development to anchor European hospital procurement channels. Thermo Fisher Scientific competes through integrated life science portfolios that extend dosimetry into broader analytical workflows. Mirion Technologies specializes in nuclear power and defense applications, occupying a differentiated tier with ruggedized product architectures.
Dosimetry encompasses the measurement and quantification of ionizing radiation exposure through devices that detect gamma rays, X-rays, and particle emissions using solid-state crystals, gas-filled chambers, or luminescent materials. These systems deliver dose readings in grays or sieverts to protect workers, validate therapeutic beams, and ensure regulatory compliance across medical and industrial settings. Electronic dosimeters now lead product type demand due to instant digital readout capabilities that reduce clinical workflow friction. Optically stimulated luminescent technology represents the fastest-growing segment as healthcare systems replace older film-based systems with reusable, higher-precision alternatives. Hospitals command the largest end user share, though oncology centers concentrate margin pools through specialized high-dose verification requirements.
The FDA governs medical dosimetry device approval through 510(k) and PMA pathways that mandate clinical validation of dose accuracy claims. EPA and OSHA standards for occupational radiation exposure create parallel compliance demand across industrial and healthcare employers. The EU Medical Device Regulation imposes stricter post-market surveillance and clinical evidence requirements that reshape competitive access across European markets. Stakeholders must monitor convergence between AI-enabled dose calculation software and hardware calibration standards as regulatory frameworks evolve to address algorithmic patient safety.
Market Dynamics
The FDA's tightened calibration requirements for radiation therapy devices are forcing oncology centers to replace legacy film-badge systems with real-time electronic monitoring, compressing replacement cycles and concentrating procurement authority among specialized radiation safety officers.
Growth Catalysts
- EU Medical Device Regulation (MDR):Stricter post-market surveillance mandates across European hospital networks are accelerating validation protocols for dose verification systems, pulling forward equipment refresh timelines.
- Optically stimulated luminescent (OSL) technology:Reusable crystal-based sensors are displacing single-use film badges in high-throughput clinical environments, reducing per-patient measurement costs.
- German precision manufacturing clusters:Concentrated instrumentation expertise around Freiburg anchors European supply chains for calibration-grade ionization chambers, shortening lead times for hospital procurement.
Market Restraints
- Helium-3 supply concentration:Neutron detection applications depend on scarce isotope stocks concentrated in US and Russian defense reserves, constraining production scalability for mixed-field dosimeters.
- MDR clinical evidence requirements:Extended validation timelines for new device submissions create regulatory friction that delays market entry for innovative sensor architectures.
- Silicon photomultiplier cost volatility:Solid-state detector production faces input cost pressure from specialized semiconductor foundry capacity constraints.
Strategic Opportunities
- AI-enabled dose calculation software:Convergence between machine learning algorithms and hardware calibration standards is creating new service revenue streams around predictive maintenance.
- Underpenetrated industrial radiography:Non-destructive testing facilities in India and Brazil remain below replacement saturation for electronic personal dosimeters.
- OSHA recordkeeping modernization:Updated occupational exposure documentation mandates are driving employer upgrades from quarterly to continuous monitoring systems.
Industry Challenges
- Metrology talent scarcity:Qualified radiation physicists capable of traceable calibration to national standards are concentrated in aging workforce cohorts across US and European hospital systems.
- Legacy system integration complexity:Hospital information systems require custom middleware to aggregate data from heterogeneous dosimeter fleets, extending deployment timelines.
- ISO 17025 accreditation timelines:Third-party laboratory certification for calibration services faces backlogs that delay service provider market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dosimetry Market |
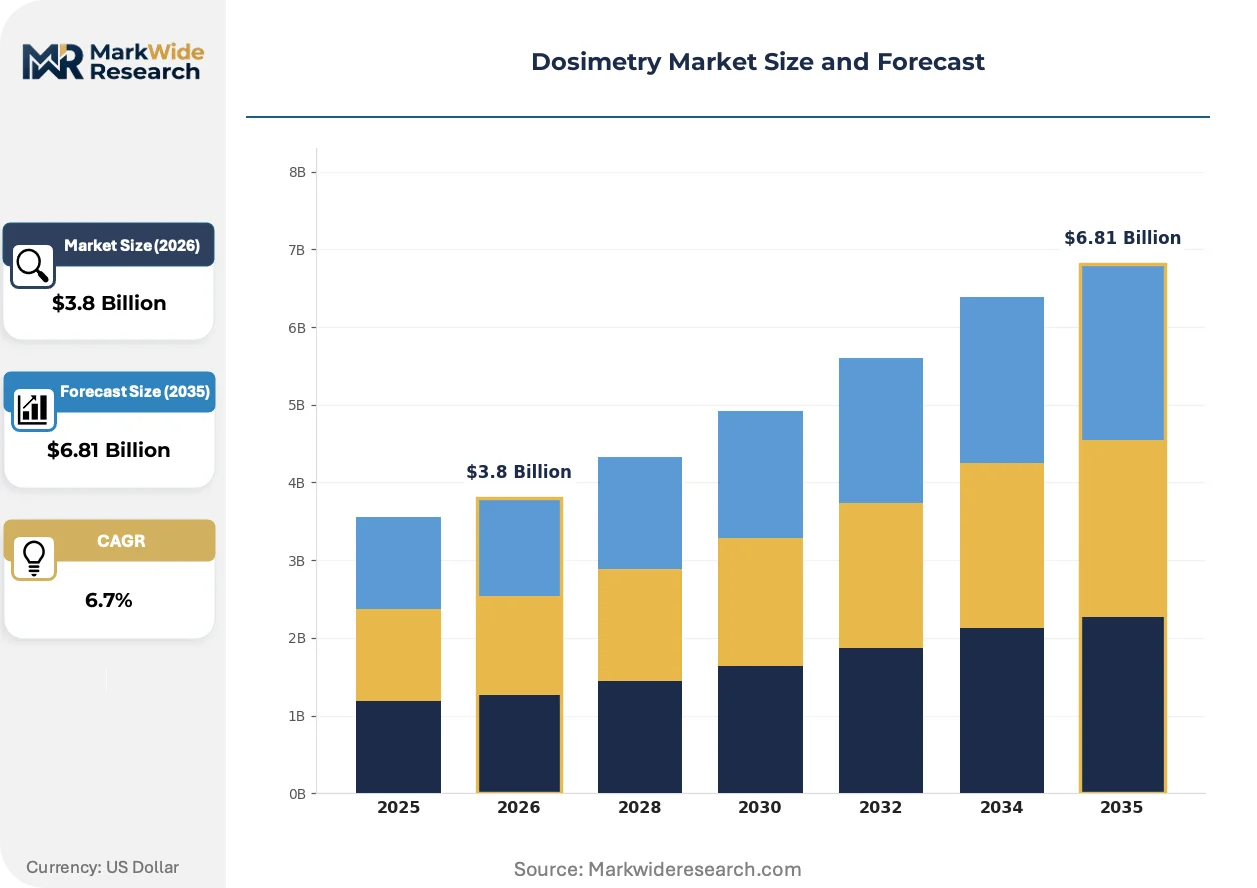
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermoluminescent Dosimeters, Electronic Dosimeters, Film Dosimeters, Optically Stimulated Luminescent Dosimeters Application: Radiation Therapy, Diagnostic Imaging, Nuclear Medicine, Research Applications End User: Hospitals, Diagnostic Laboratories, Research Institutions, Oncology Centers Technology: Solid State, Gas Filled, Liquid Scintillation, In-Vivo |
| Companies Covered | Fuji Electric, PTW Freiburg, Mirion Technologies, Ludlum Measurements, IBA Dosimetry, Landauer, Fluke Biomedical, AMETEK, Thermo Fisher Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dosimetry Market Emerging Trajectories
Real-time connectivity and predictive analytics are restructuring how radiation safety data flows through clinical and industrial environments, shifting value capture from hardware sales toward integrated compliance platforms.
Cloud-connected electronic dosimeters are decentralizing radiation safety oversight by enabling remote monitoring of distributed workforces without centralized badge collection infrastructure. Mining operations and nuclear maintenance contractors are adopting these systems fastest, eliminating logistical bottlenecks that previously limited monitoring coverage. This architecture is compressing the addressable market for traditional dosimetry service bureaus that relied on physical badge processing.
The EU AI Act's risk classification framework is reshaping algorithmic patient safety requirements for automated dose calculation software used in radiotherapy planning. Developers must now document training data provenance and establish human oversight protocols before CE marking. German and Dutch oncology software vendors are restructuring quality management systems to accommodate these documentation burdens.
Hospital procurement departments are consolidating vendor relationships for radiation safety equipment under single-source framework agreements that bundle dosimetry hardware with calibration services and regulatory reporting. This pattern displaces the historical model of separate purchasing for badges, readers, and third-party analysis. The shift is most visible in US integrated delivery networks and NHS Trusts in England.
Dosimetry Market Segmentation
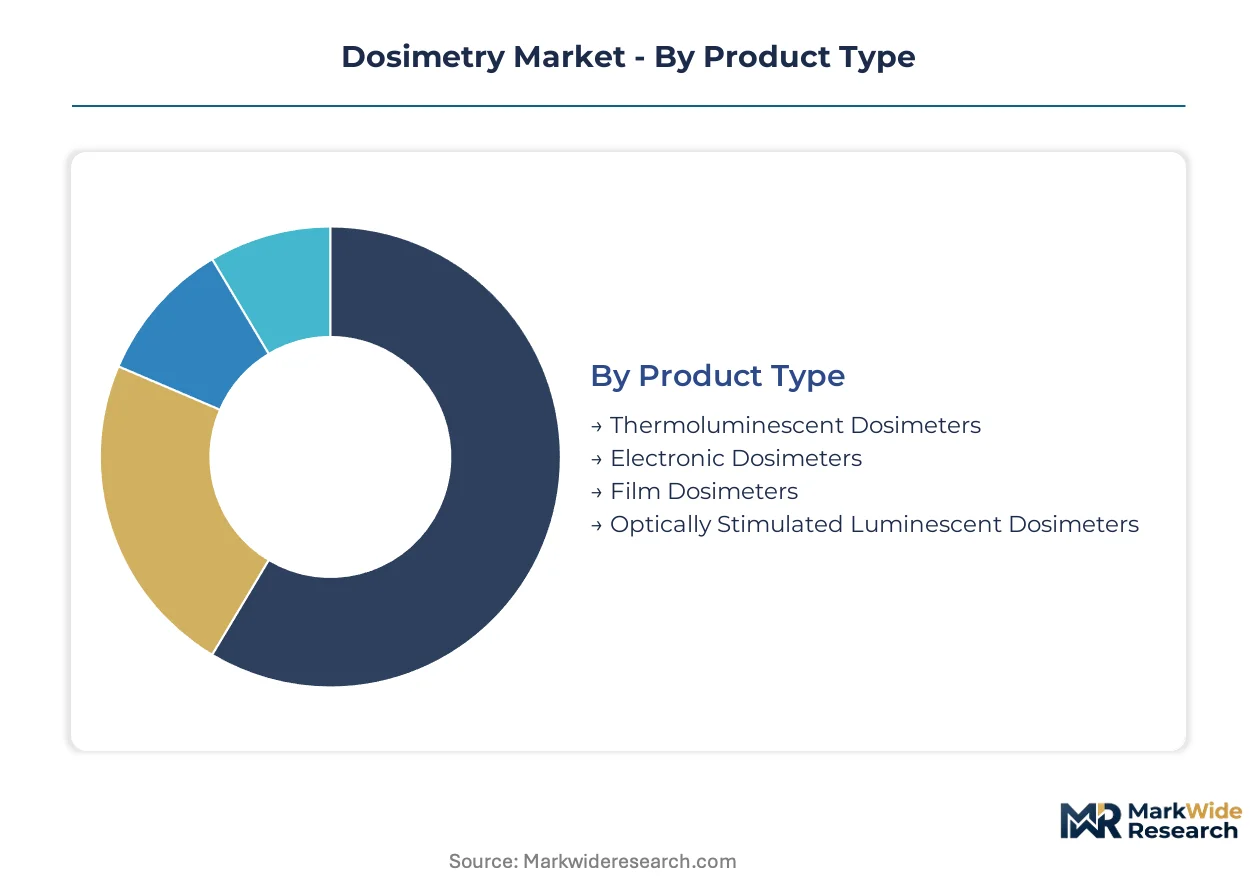
Dosimetry procurement splits across technical specifications, clinical workflows, and regulatory compliance tiers. Buyers prioritize instant digital readout capabilities in high-throughput oncology environments while cost-sensitive industrial users favor reusable sensor formats.
Product Type:
Cost tier differentiation separates premium real-time systems from budget film-based alternatives with stark capability gaps.
- Electronic Dosimeters:Semiconductor-based detectors with instant digital displays and alarm thresholds. Oncology centers in Germany and the United States concentrate procurement here as FDA calibration mandates compress replacement cycles for legacy systems.
- Optically Stimulated Luminescent Dosimeters:Reusable aluminum oxide crystal sensors activated by laser stimulation. Hospital networks across England and France are displacing film badges to reduce per-patient measurement costs and eliminate chemical processing infrastructure.
- Thermoluminescent Dosimeters:Lithium fluoride crystals requiring post-exposure heating for readout. Personal monitoring services in Japan retain this format for its tissue-equivalence precision.
- Film Dosimeters:Silver halide emulsion strips with optical density correlation to exposure. Industrial radiography contractors in India continue procurement for mixed-field neutron-gamma environments where electronic alternatives face helium-3 supply constraints.
Volume sits with Electronic Dosimeters; growth tilts toward Optically Stimulated Luminescent Dosimeters.
Application:
Margin concentration follows radiation dose intensity rather than procedure frequency.
- Radiation Therapy:High-dose external beam and brachytherapy verification requiring traceable calibration to national standards. German university hospitals anchor European demand as EU MDR post-market surveillance mandates accelerate equipment refresh.
- Diagnostic Imaging:CT fluoroscopy and interventional radiography staff monitoring with lower per-exposure thresholds. NHS Trusts in England bundle procurement with oncology center framework agreements.
- Nuclear Medicine:Cyclotron and radiopharmaceutical handling environments with isotope-specific calibration requirements. Canadian health authorities specify sealed ionization chambers for technetium-99m production facilities.
- Research Applications:Particle accelerator and synchrotron beamline characterization demanding custom energy response curves. CERN procurement specifications influence European laboratory standards.
Revenue concentrates in Radiation Therapy; expansion accelerates fastest in Diagnostic Imaging.
End User:
Procurement authority centralizes where radiation safety officers command dedicated capital budgets.
- Oncology Centers:Specialized high-dose verification with dedicated medical physics departments. United States integrated delivery networks consolidate vendor relationships under single-source agreements bundling hardware, calibration, and regulatory reporting.
- Hospitals:Broad departmental coverage spanning radiology, nuclear medicine, and cardiac catheterization labs. French public hospital groups standardize on PTW Freiburg ionization chambers for cross-facility compatibility.
- Diagnostic Laboratories:Point-of-care imaging and mobile screening operations with decentralized staff. Brazilian private laboratory chains drive Latin American demand for cloud-connected electronic badges.
- Research Institutions:National laboratories and university physics departments with custom protocol requirements. Oak Ridge National Laboratory specifications shape United States federal procurement templates.
Installed base dominates Hospitals; margin capture tilts toward Oncology Centers.
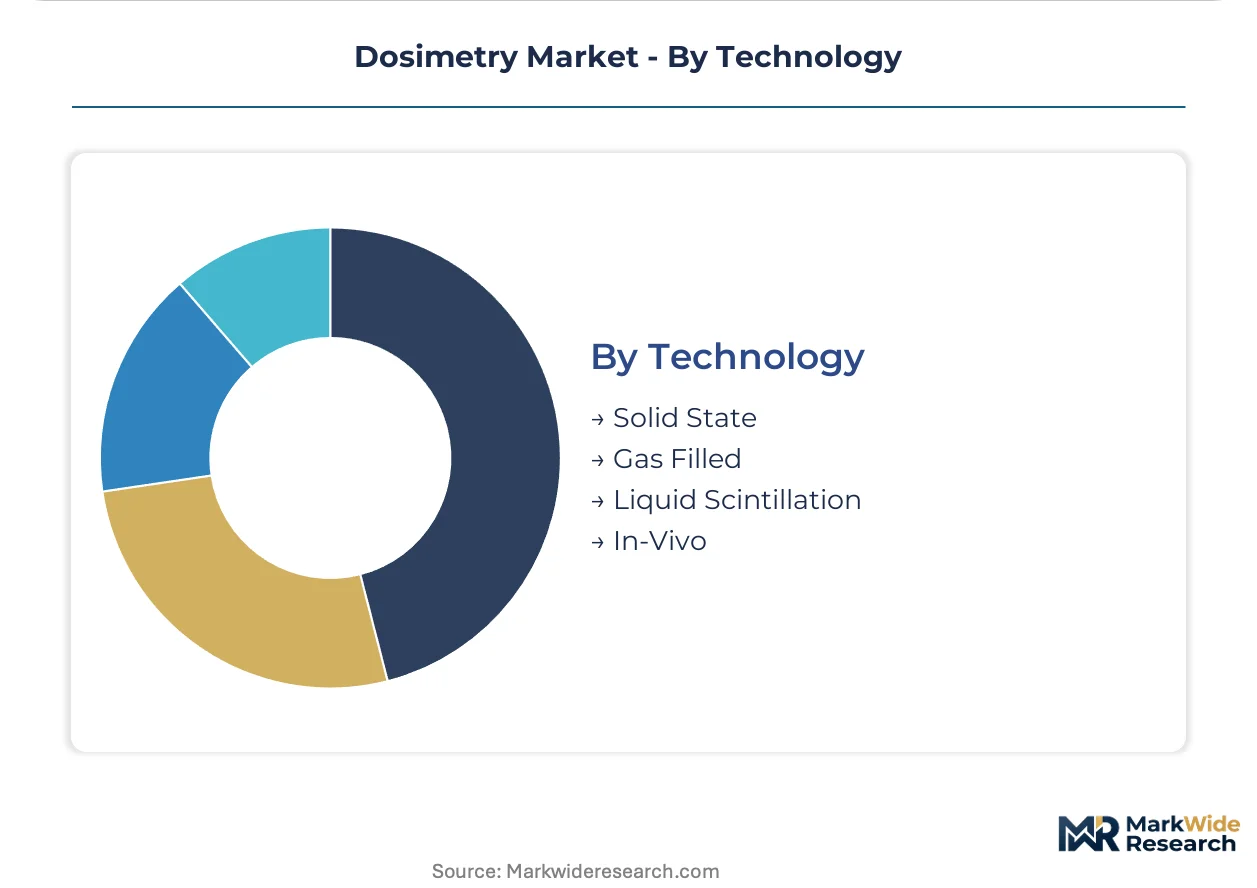
Technology:
Supply concentration in semiconductor foundries versus gas handling infrastructure shapes competitive access.
- Solid State:Silicon photomultiplier and diode architectures enabling miniaturized wearable formats. Japanese automotive suppliers are repurposing radiation-hardened CMOS capacity for medical dosimetry contracts.
- Gas Filled:Ionization chambers and proportional counters with tissue-equivalent gas mixtures. German precision manufacturing clusters around Freiburg anchor European supply for calibration-grade instruments.
- Liquid Scintillation:Organic fluor cocktails for low-energy beta and alpha discrimination. Environmental monitoring agencies in Canada specify this format for tritium detection in nuclear facility effluent.
- In-Vivo:Implantable or intracavitary sensors for real-time organ dose tracking during brachytherapy. Dutch oncology software vendors integrate these with AI-enabled dose calculation platforms facing EU AI Act documentation requirements.
Production volume clusters in Solid State; technology leadership concentrates in Gas Filled.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision manufacturing clusters around Freiburg anchor European supply chains for calibration-grade ionization chambers. The United States concentrates oncology center procurement authority under integrated delivery networks. Japanese semiconductor foundries repurpose radiation-hardened CMOS capacity for medical dosimetry contracts.
United States
Oncology centers scale procurement of real-time monitoring systems as the FDA tightens calibration requirements for radiation therapy devices. OSHA recordkeeping modernization drives employer upgrades from quarterly to continuous monitoring systems. The Oak Ridge National Laboratory in Tennessee shapes federal procurement templates for research-grade instrumentation.
Germany
University hospitals anchor European demand for high-dose external beam verification as EU MDR post-market surveillance mandates accelerate equipment refresh. The national regulator enforces stricter post-market surveillance through the EU Medical Device Regulation. Precision manufacturing clusters around Freiburg shorten lead times for hospital procurement of calibration-grade instruments.
Japan
Personal monitoring services retain thermoluminescent formats for tissue-equivalence precision in occupational health applications. METI oversees standards for radiation-hardened semiconductor production. Automotive suppliers in the Chubu region repurpose CMOS foundry capacity for medical dosimetry contracts.
France
Public hospital groups standardize on cross-facility compatible ionization chambers for radiation therapy verification. ANSM enforces clinical evidence requirements for device market entry. The Île-de-France region concentrates procurement authority for NHS-equivalent hospital networks.
United Kingdom
NHS Trusts bundle procurement for diagnostic imaging staff monitoring with oncology center framework agreements. The national health system consolidates vendor relationships under single-source agreements. England's integrated delivery networks drive standardization across radiology and nuclear medicine departments.
Dosimetry Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue AI-enabled dose calculation software and cloud-connected monitoring platforms. The vendor base concentrates around precision instrumentation manufacturers with decades of calibration protocol development. Three archetypes dominate: German precision manufacturers, diversified life science conglomerates, and specialized nuclear defense contractors. Competitive moves center on strategic partnerships for regulatory compliance bundling and portfolio diversification into predictive maintenance services.
Among German precision manufacturers, PTW Freiburg and IBA Dosimetry exemplify the calibration-grade instrumentation archetype with concentrated expertise around Freiburg manufacturing clusters. Thermo Fisher Scientific represents the diversified life science conglomerate model, extending dosimetry into broader analytical workflows. Mirion Technologies occupies a differentiated position within the nuclear defense contractor tier, anchoring ruggedized product architectures for power generation and military applications.
| Leading Market Players |
|---|
| Fuji Electric |
| PTW Freiburg |
| Mirion Technologies |
| Ludlum Measurements |
| IBA Dosimetry |
| Landauer |
| Fluke Biomedical |
| AMETEK |
| Thermo Fisher Scientific |
| Others |
Supply Flow & Price Mechanics
EU MDR post-market surveillance mandates gate qualified supply and premium-tier pricing access by forcing calibration-grade instrumentation vendors to absorb extended validation timelines and ISO 17025 accreditation costs that smaller competitors cannot shoulder. This regulatory filter compresses margin pools toward incumbent precision manufacturers while elevating entry barriers for economy-tier alternatives.
Pricing Analysis
Warranty and calibration service bundling separates premium-tier electronic dosimeters from unbundled film-badge alternatives that carry no ongoing technical support obligations. Pricing stratifies across premium, standard, and economy tiers based on traceability certification to national standards and volume procurement scale under hospital framework agreements. Cost compression in the economy tier intensifies because helium-3 supply constraints force neutron detection manufacturers toward higher-cost alternative sensor architectures. Industrial radiography contractors in India exhibit the highest price sensitivity, while German university hospitals prioritize calibration-grade precision over unit cost.
Supply Chain Analysis
Regional distribution centers in Freiburg, Nashville, and Chubu anchor hub-and-spoke patterns that shorten lead times for hospital procurement of ionization chambers and solid-state detectors. Manufacturing concentrates in Germany, the United States, and Japan, where precision instrumentation expertise and radiation-hardened semiconductor foundry capacity co-locate. Production draws from scarce helium-3 stocks concentrated in US and Russian defense reserves, silicon photomultiplier substrates facing foundry capacity constraints, and aluminum oxide crystal feedstocks for OSL sensors. Single-source vulnerability in neutron detection isotopes threatens mixed-field dosimeter scalability. Distribution runs through authorized service bureaus that bundle hardware with calibration and regulatory reporting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Helium-3 supply concentration props pricing power for neutron-capable instrumentation by constraining production scalability and preserving incumbent control over mixed-field verification segments.
For Market Incumbents: Cement calibration protocol dominance by acquiring ISO 17025-accredited third-party laboratories facing accreditation backlogs, neutralizing service-based competitive threats. Deepen backward integration into silicon photomultiplier supply through captive semiconductor foundry partnerships in Japan, insulating against input cost volatility from capacity constraints. For New Entrants and Emerging Players: Direct-to-clinician digital platforms bypass consolidated hospital procurement committees and enable SaaS-tiered pricing for AI-enabled dose calculation software. White-space concentration sits with cloud-connected electronic badges for Brazilian diagnostic laboratory chains and Indian industrial radiography contractors where replacement saturation remains below European levels. Partner with Dutch oncology software vendors facing EU AI Act documentation burdens to embed hardware-software bundles. For Investors and Strategic Acquirers: FDA 510(k) clearance acceleration for real-time monitoring systems is the leading indicator that replacement cycle compression will sustain equipment refresh demand. The five-to-ten-year viability window favors precision instrumentation specialists with decades of calibration protocol development over diversified life science conglomerates. Target acquisition archetype: German mid-cap manufacturers with captive Freiburg manufacturing clusters and established European hospital network relationships. Monitor helium-3 supply release schedules from US defense reserves as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR post-market surveillance mandates reshape competitive access across European hospital networks. |
| Hospital System Partnership | NHS Trusts bundle procurement under single-source agreements displacing fragmented badge-reader-analysis purchasing. |
| Software Companion Development | AI-enabled dose calculation platforms face EU AI Act risk classification and documentation requirements. |
| Backward Integration | Captive silicon photomultiplier supply insulates against Japanese foundry capacity constraints. |
| Calibration Service Expansion | ISO 17025 accreditation backlogs create acquisition targets for incumbent service network densification. |
Methodological Framework
FDA 510(k) and PMA filings, EU MDR post-market surveillance databases, and hospital procurement contract records formed the secondary backbone for calibration protocol and regulatory pathway mapping. Primary interviews with radiation safety officers, medical physicists, hospital purchasing committee members, and biomedical engineers combined with secondary validation to triangulate replacement cycle timing and procurement authority concentration. Bottom-up and top-down approaches cross-checked equipment refresh timelines against framework agreement consolidation patterns.
Bottom-up modeling anchored volume estimates in oncology center capital expenditure disclosures and industrial radiography contractor fleet data across the projection horizon. Segmentation by product type, application intensity, end-user procurement authority, and technology supply concentration shaped the analytical framework. CAGRs derived from equipment replacement cycle compression under tightened FDA calibration requirements and EU MDR validation protocol acceleration. Forecast inputs incorporated helium-3 supply release schedules and silicon photomultiplier foundry capacity expansion announcements.
The model holds under stable regulatory enforcement intensity and continued helium-3 supply rationing; deviation in defense reserve release schedules or semiconductor foundry capacity expansion would shift competitive access patterns. Forecasts reflect documented assumptions around replacement saturation timelines and framework agreement consolidation velocity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Diagnostics
In-Situ Hybridization (ISH) Market
Medical Diagnostics
Asia-Pacific Single Cell Analysis Market
Medical Diagnostics
Circulating Tumor Cells (Ctcs) Prognostic Technologies Market
Medical Diagnostics
Global HLA Typing for Transplant Market
Medical Diagnostics
Global Circulating Tumor Cells Market
Medical Diagnostics
Fluorescence Cell Market
Medical Diagnostics
Rapid Medical Diagnostic Kits Market
Medical Diagnostics
Global Histology and Cytology Market
Medical Diagnostics
Global Complete Blood Count Device Market
Medical Diagnostics
US Molecular Diagnostics Market
Medical Diagnostics
Artificial Intelligence (AI) in Medical Diagnostics Market
Medical Diagnostics
Asia Pacific Immunohistochemistry Market
Medical Diagnostics
Electroretinogram Market
Medical Diagnostics
Europe Circulating Tumor Cells (CTC) Liquid Biopsy Market
Medical Diagnostics
North America Circulating Tumor Cells (CTC) Liquid Biopsy Market
Medical Diagnostics
MUC1 Antibody Market