
 Europe Circulating Tumor Cells (CTC) Liquid Biopsy Market | 2026-2036
Europe Circulating Tumor Cells (CTC) Liquid Biopsy Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Circulating Tumor Cells (CTC) Liquid Biopsy Market Foresight
Multi-sourced kit procurement from specialized European suppliers is expanding as hospital laboratories diversify beyond single-vendor molecular platforms. QIAGEN leverages its nucleic acid extraction expertise to anchor distribution across German and French clinical networks. Thermo Fisher Scientific sustains competitive positioning through integrated sequencing-to-analysis workflows. Menarini Silicon Biosystems specializes in rare-cell isolation instrumentation with regulatory clearance breadth across EU member states.
Circulating tumor cells are epithelial-derived malignant cells shed from primary or metastatic tumors into peripheral blood, typically isolated through immunomagnetic enrichment or microfluidic separation at concentrations as low as one cell per milliliter of whole blood, with downstream analysis enabling real-time genotyping and treatment-response monitoring without invasive tissue biopsy. Isolating technologies capture the largest installed base but face margin compression as microfluidics-based platforms achieve comparable sensitivity at lower per-test cost. Detection kits for lung cancer indication command premium positioning given the prevalence of EGFR-mutation tracking in European treatment guidelines.
EMA's centralized marketing authorization framework governs companion diagnostic claims for CTC-based assays, while IVDR's Class C device classification elevates clinical evidence requirements for commercial access. Germany's national reimbursement body, the G-BA, increasingly evaluates liquid biopsy evidence in early-benefit assessments for oncologics. Stakeholders must monitor how France's HAS and England's NICE calibrate health technology appraisal criteria for CTC tests against tissue-based comparators.
Market Dynamics
The EU IVDR's Class C device classification is compressing commercial timelines for CTC assay developers while German university hospitals accelerate protocol standardization for metastatic monitoring workflows.
Growth Catalysts
- EMA centralized authorization pathway:Streamlined companion diagnostic claims for CTC-based assays reduce regulatory fragmentation across member states.
- Precision oncology clusters:Munich, Heidelberg, and Berlin hospital networks are embedding liquid biopsy into routine metastatic cancer surveillance protocols.
- Microfluidic sensitivity gains:New isolation platforms achieve single-cell detection thresholds at reduced per-test cost compared to immunomagnetic legacy systems.
Market Restraints
- IVDR clinical evidence burden:Class C device requirements demand expanded performance documentation that extends commercialization timelines by 18-24 months for novel assays.
- Reimbursement uncertainty:France's HAS and England's NICE have not established consistent health technology appraisal criteria for CTC tests against tissue biopsy comparators.
- Input concentration risk:Specialized microfluidic chip manufacturing concentrates in a limited supplier base, creating vulnerability for kit producers.
Strategic Opportunities
- Spain and Italy hospital penetration:Oncology departments in Barcelona and Milan remain underpenetrated relative to German adoption rates for CTC monitoring protocols.
- Multi-cancer early detection convergence:Integration of CTC isolation with circulating tumor DNA analysis opens pan-cancer screening applications beyond current single-indication focus.
- G-BA early-benefit assessment alignment:Germany's national reimbursement body increasingly evaluates liquid biopsy evidence alongside oncologic drug approvals, creating parallel reimbursement pathways.
Industry Challenges
- Bioinformatics specialist scarcity:Clinical laboratories face recruitment gaps for computational biologists capable of interpreting single-cell genomic data from CTC isolates.
- Legacy platform integration friction:Hospital IT systems require substantial reconfiguration to incorporate real-time CTC genotyping results into electronic health records.
- CE marking timeline compression:IVDR notified body capacity constraints are extending technical documentation review periods for novel microfluidic devices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Circulating Tumor Cells (CTC) Liquid Biopsy Market |
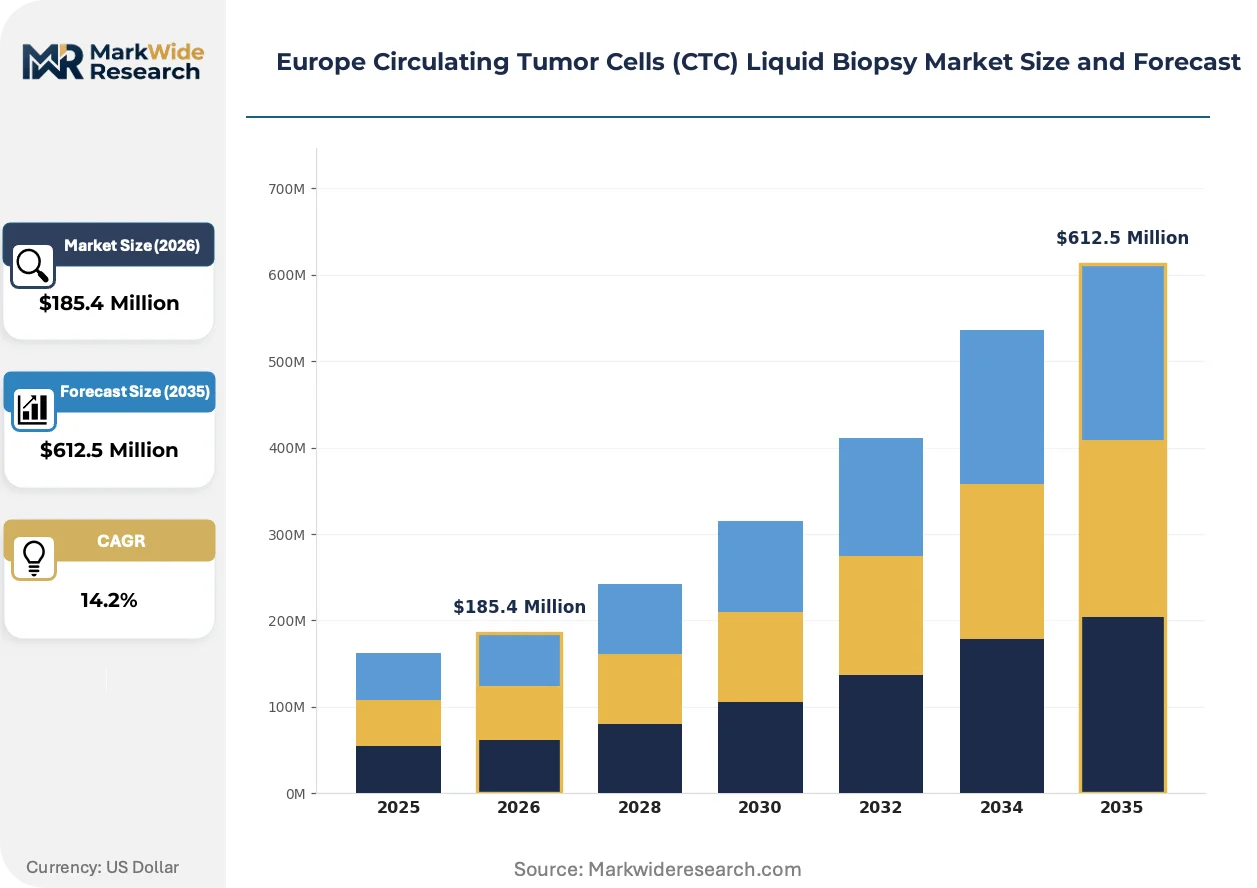
| Market Size in 2026 | $185.4 Million |
| Market Size in 2035 | $612.5 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Isolating Technologies, Detection Kits, Analysis Software, Consumables Indication: Breast Cancer, Lung Cancer, Colorectal Cancer, Prostate Cancer End User: Clinical Laboratories, Hospitals, Research Institutes, Diagnostic Centers Technology: CTC Enrichment, PCR, Microfluidics, Imaging Techniques |
| Companies Covered | Menarini Silicon Biosystems, QIAGEN, Thermo Fisher Scientific, Guardant Health, F. Hoffmann-La Roche Ltd., Bio-Techne, Illumina, Exact Sciences Corporation, Inivata Ltd, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Circulating Tumor Cells (CTC) Liquid Biopsy Market Shifts & Advancements
Microfluidic isolation platforms are compressing cost structures while regulatory frameworks and procurement models undergo parallel restructuring across European healthcare systems.
Automated microfluidic cell capture technology is decentralizing CTC isolation from centralized reference laboratories to hospital-based clinical pathology departments. Mid-sized oncology centers in France and the Netherlands are deploying benchtop systems that previously required dedicated core facilities. This shift is decentralizing test access and compressing turnaround times for treatment-monitoring decisions.
REACH substance restrictions on certain magnetic nanoparticle formulations are forcing reformulation of immunomagnetic enrichment reagents. Manufacturers are accelerating transitions to microfluidic-dependent workflows that reduce reliance on coated particle systems. Lung cancer indication assays face the most immediate compliance pressure given their reliance on established immunomagnetic protocols.
Hospital procurement consortia are consolidating molecular diagnostic purchasing across multi-site networks. French public hospital groups and German university medical center alliances are negotiating framework agreements that displace single-site vendor relationships. This concentration is most visible in the Ile-de-France and Baden-Württemberg regions where procurement scale determines assay menu access.
Europe Circulating Tumor Cells (CTC) Liquid Biopsy Market Segmentation
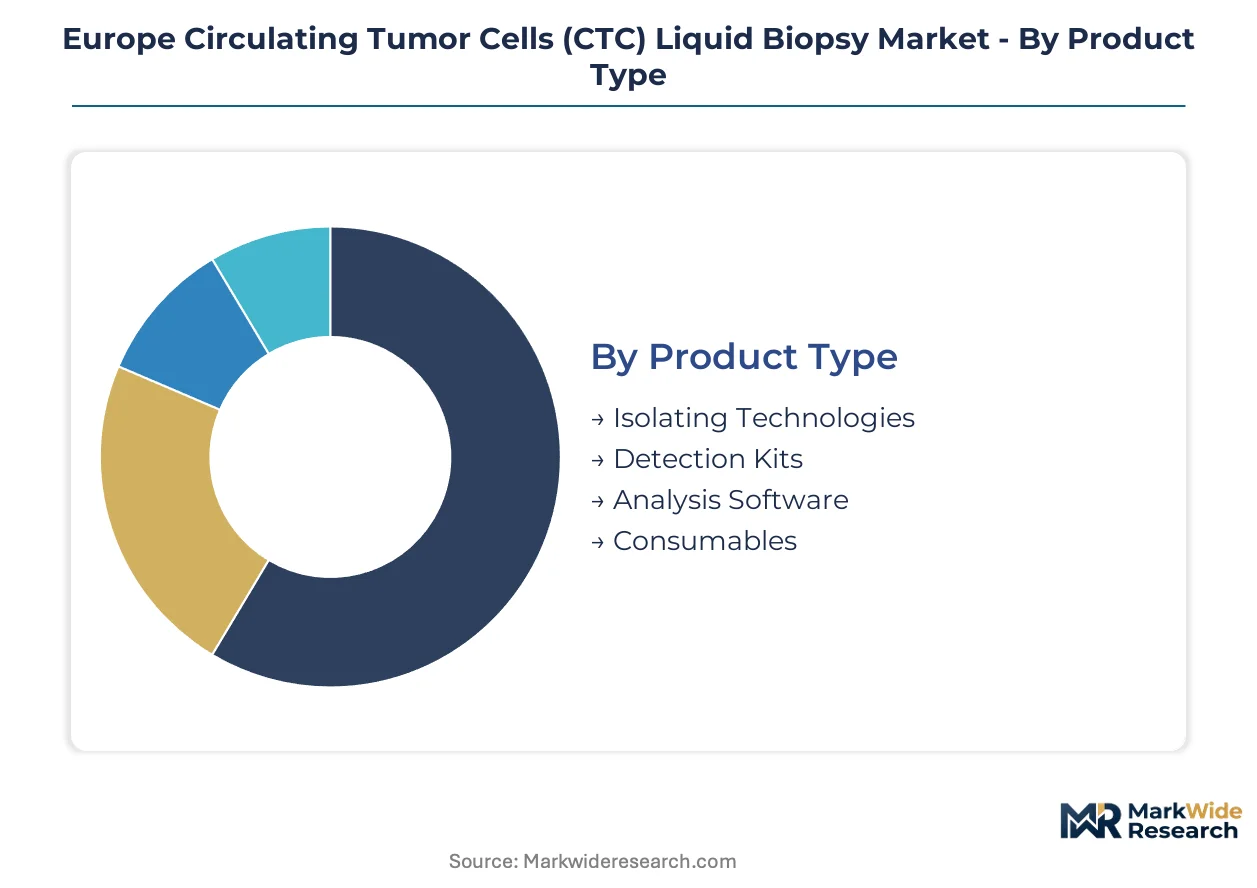
Technology choices in CTC liquid biopsy determine workflow integration costs and reimbursement pathways across European hospital networks. Segmentation reveals where capital equipment upgrades concentrate versus consumable-driven recurring revenue models.
Product Type:
Equipment refresh cycles accelerate as IVDR compliance deadlines force replacement of legacy immunomagnetic platforms with validated microfluidic systems.
- Isolating Technologies:Immunomagnetic enrichment devices and microfluidic cell capture systems process peripheral blood samples to extract viable circulating tumor cells at single-cell sensitivity thresholds. German university hospitals in Munich and Heidelberg are prioritizing automated platforms that integrate directly with pathology laboratory information systems to reduce manual handling errors.
- Detection Kits:Reagent sets enable immunofluorescent staining and molecular characterization of isolated CTCs, with lung cancer EGFR-mutation panels commanding premium positioning in French and German clinical guidelines. Demand concentrates in high-throughput reference laboratories serving multiple hospital sites under framework procurement agreements.
- Analysis Software:Bioinformatics platforms interpret single-cell genomic data from CTC isolates, requiring specialized computational infrastructure.
- Consumables:Microfluidic chips, collection tubes, and buffer solutions generate recurring revenue tied to test volumes rather than capital budgets.
Isolating Technologies sits at the top of the volume ranking, with Detection Kits climbing the fastest.
Indication:
Clinical utility evidence thresholds vary by tumor type, with reimbursement bodies demanding indication-specific survival data before granting parallel diagnostic pathway status.
- Lung Cancer:EGFR-mutation tracking in non-small cell lung carcinoma drives the largest installed base of CTC monitoring protocols, with German G-BA early-benefit assessments increasingly referencing liquid biopsy alongside tissue biopsy for treatment selection. French HAS evaluation frameworks are tightening evidence requirements for companion diagnostic claims in this indication.
- Breast Cancer:HER2-status monitoring and treatment-response surveillance in metastatic patients represent established applications with mature clinical evidence bases. Demand clusters in specialized oncology centers across the Ile-de-France and Baden-Württemberg hospital networks.
- Colorectal Cancer:RAS-mutation analysis for anti-EGFR therapy selection is gaining protocol adoption in Dutch and Belgian academic medical centers.
- Prostate Cancer:AR-V7 testing for abiraterone/enzalutamide resistance prediction remains concentrated in research-intensive settings pending broader reimbursement.
Lung Cancer captures the largest revenue concentration, with Colorectal Cancer expanding most quickly as Dutch protocols standardize.
End User:
Site-of-care migration shifts test volume from centralized reference laboratories toward hospital-based pathology departments with microfluidic benchtop capabilities.
- Hospitals:University medical centers and tertiary oncology units embed CTC isolation into routine metastatic monitoring workflows, with Berlin and Barcelona hospital groups negotiating multi-site procurement frameworks. IVDR Class C device requirements are compressing vendor qualification timelines for in-house laboratory developed tests.
- Clinical Laboratories:National reference networks in France and Germany process high-volume CTC characterization for regional hospital consortia, maintaining economies of scale that resist decentralization pressures.
- Research Institutes:Academic centers in Heidelberg and Milan drive protocol innovation for multi-cancer early detection applications.
- Diagnostic Centers:Private pathology groups in Switzerland and the Netherlands are acquiring microfluidic platforms to capture community oncology referrals.
Hospitals command the dominant share of new platform installations, with Diagnostic Centers gaining share fastest among decentralized service models.
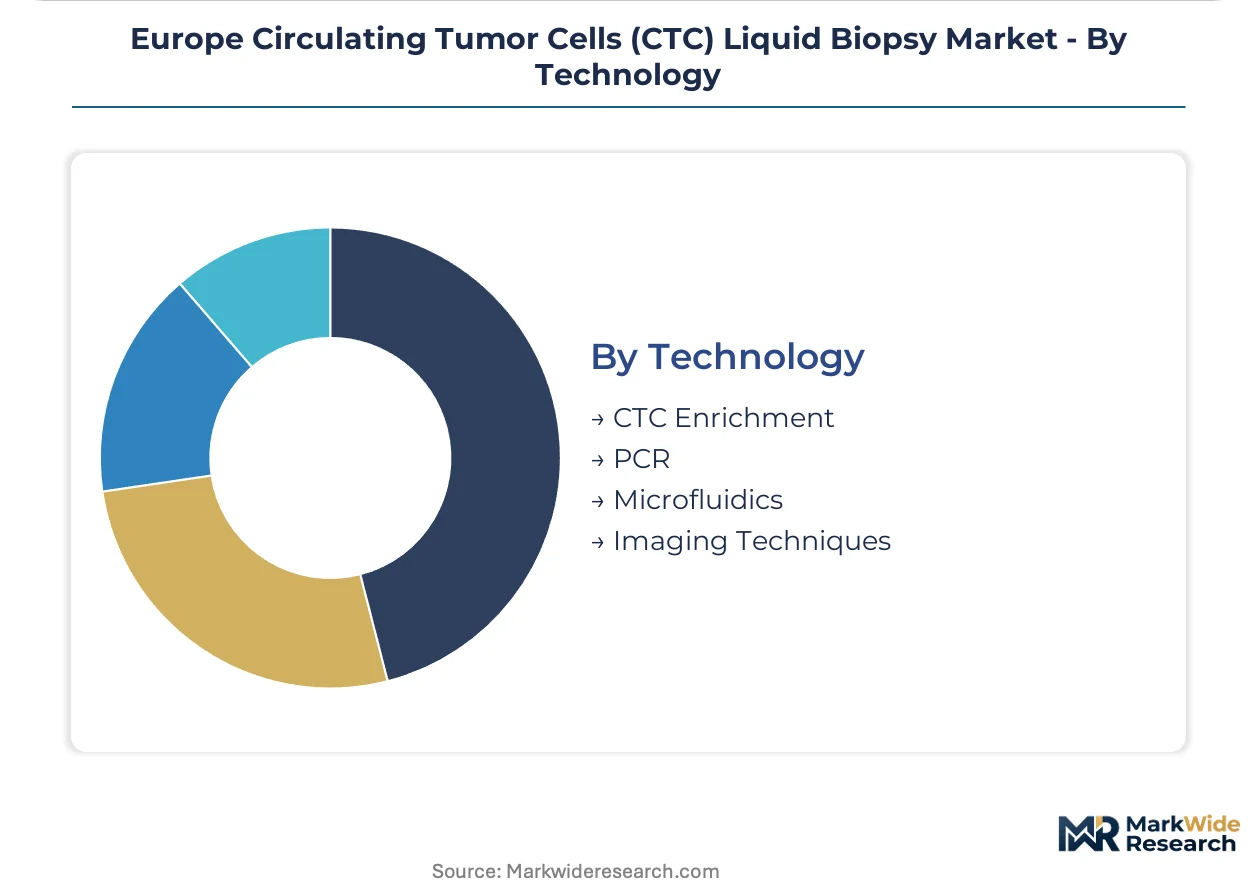
Technology:
Platform selection determines regulatory pathway complexity and per-test cost structures as REACH restrictions reshape reagent supply chains.
- Microfluidics:Chip-based cell capture achieves single-cell detection sensitivity at reduced consumable cost compared to immunomagnetic legacy systems, with Dutch mid-sized oncology centers deploying benchtop configurations that previously required dedicated core facilities. ECHA REACH substance restrictions on magnetic nanoparticle formulations are accelerating transition toward microfluidic-dependent workflows.
- CTC Enrichment:Density gradient and size-based separation methods retain installed base in cost-sensitive settings but face margin compression from microfluidic sensitivity gains.
- PCR:Digital PCR and allele-specific amplification enable mutation detection from limited CTC-derived DNA input material.
- Imaging Techniques:High-resolution microscopy and automated cell scoring algorithms complete the analytical workflow for phenotypic characterization.
Microfluidics leads technology transition investments, with PCR showing the steepest expansion trajectory as companion diagnostic claims multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Munich-Heidelberg-Berlin precision oncology clusters anchor European CTC liquid biopsy demand through university hospital network procurement frameworks and IVDR-compliant protocol standardization.
Germany
G-BA early-benefit assessments for oncologics increasingly reference liquid biopsy evidence alongside tissue biopsies, compressing vendor qualification timelines for in-house laboratory developed tests. The IVDR Class C device classification elevates clinical documentation requirements for commercial market access. Baden-Württemberg hospital groups negotiate multi-site procurement frameworks that displace single-site vendor relationships.
France
HAS evaluation frameworks tighten evidence requirements for companion diagnostic claims in lung cancer indications, creating reimbursement uncertainty for novel CTC assays. The Ile-de-France region concentrates demand through public hospital group purchasing consortia. Paris-area oncology centers embed CTC isolation into routine metastatic monitoring workflows ahead of national protocol standardization.
Netherlands
Dutch mid-sized oncology centers deploy benchtop microfluidic systems that previously required dedicated core facilities, decentralizing test access beyond reference laboratories. ECHA REACH substance restrictions on magnetic nanoparticle formulations accelerate transition toward microfluidic-dependent workflows. Rotterdam and Utrecht academic medical centers drive RAS-mutation analysis protocol adoption for colorectal cancer therapy selection.
Spain
Barcelona hospital groups remain underpenetrated relative to German adoption rates for CTC monitoring protocols, presenting expansion opportunities for platform vendors. The Spanish national health system's regional decentralization creates fragmented procurement landscapes. Catalonia's precision medicine initiatives concentrate research-intensive applications in academic medical centers pending broader reimbursement.
Switzerland
Swissmedic regulatory pathways for companion diagnostics align with EMA centralized authorization frameworks, streamlining cross-border commercialization for German and French assay developers. Private pathology groups acquire microfluidic platforms to capture community oncology referrals outside university hospital networks. Zurich and Geneva diagnostic centers lead decentralized service model adoption.
Europe Circulating Tumor Cells (CTC) Liquid Biopsy Market Competitive Landscape
Global majors compete with regional champions across distribution reach and regulatory clearance breadth, producing a tiered structure where scale-driven sequencing-to-analysis workflows coexist with specialized rare-cell isolation instrumentation. Three archetypes dominate: integrated life science conglomerates with nucleic acid extraction expertise, precision oncology platform specialists with EU regulatory depth, and emerging liquid biopsy pure-plays leveraging companion diagnostic partnerships. Competitive moves concentrate on IVDR notified body qualification acceleration and multi-site hospital procurement framework capture.
Within the specialized instrumentation tier, Menarini Silicon Biosystems exemplifies EU regulatory clearance breadth across member states, while QIAGEN anchors German and French clinical network distribution through nucleic acid extraction expertise. Thermo Fisher Scientific occupies a position among integrated workflow providers sustaining competitive positioning through sequencing-to-analysis integration. These three represent the dominant competitive anchors shaping procurement dynamics in precision oncology clusters.
| Leading Market Players |
|---|
| Menarini Silicon Biosystems |
| QIAGEN |
| Thermo Fisher Scientific |
| Guardant Health |
| F. Hoffmann-La Roche Ltd. |
| Bio-Techne |
| Illumina |
| Exact Sciences Corporation |
| Inivata Ltd |
| Others |
Supply & Pricing Matrix
Hospital procurement consortia across Baden-Württemberg and Ile-de-France are mandating multi-year framework agreements that compress per-test pricing while demanding validated microfluidic platform compatibility, forcing assay developers to absorb input-cost volatility through supply chain restructuring rather than price pass-through.
Pricing Analysis
Input-cost pass-through from specialized microfluidic chip manufacturing is partially absorbed by kit producers rather than fully transferred to hospital buyers, compressing margins on consumable-heavy revenue models. Three-tier pricing structure across premium, standard, and economy levels separates automated platform-integrated assays from manual benchtop configurations and research-grade reagent sets. Pricing pressure stems from REACH-driven reformulation costs for immunomagnetic enrichment reagents. Mid-sized oncology centers in the Netherlands and Spain exhibit the highest price sensitivity, while German university medical centers prioritize sensitivity specifications over per-test economics.
Supply Chain Analysis
Dual-sourcing requirements from French and German hospital procurement groups are mandating qualified secondary suppliers for microfluidic chip fabrication and nucleic acid extraction reagents, reducing single-source dependency risks. Manufacturing concentrates in Germany, the Netherlands, and Switzerland for precision microfluidic components, while magnetic nanoparticle formulations draw from specialized chemical suppliers in Belgium and France. Supply chain risk centers on ECHA REACH substance restrictions that force rapid reagent reformulation without guaranteed regulatory equivalence timelines. Distribution runs through regional reference laboratory networks that consolidate kit procurement across multi-site hospital alliances.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Europe's CTC liquid biopsy market rests on microfluidic platform cost-down curves and the premium-tier shift toward automated pathology-integrated workflows that command pricing power over manual alternatives.
For Market Incumbents: Deploy IVDR notified body pre-submission pathways to compress Class C device approval timelines before 2025 regulatory deadlines. Accelerate backward integration into microfluidic chip manufacturing to reduce dependency on limited European foundry capacity. Consolidate procurement framework capture in Munich and Heidelberg hospital networks before Spanish and Italian markets standardize protocols. For New Entrants and Emerging Players: Enter via Barcelona and Milan oncology departments where CTC monitoring protocols remain underpenetrated relative to German adoption benchmarks. Target mid-sized Dutch centers deploying benchtop microfluidic systems that bypass reference laboratory gatekeepers. Lead with lung cancer EGFR-mutation detection kits that align with established French and German clinical guideline requirements. For Investors and Strategic Acquirers: Asymmetric upside sits with microfluidic platform specialists holding broad EU regulatory clearance breadth and hospital LIS integration capabilities. Long-term viability over the next decade hinges on companion diagnostic claim expansion beyond single-indication assays. Watch for G-BA early-benefit assessment decisions that establish parallel reimbursement pathways for liquid biopsy alongside tissue-based comparators.| Strategic Initiative | Industry Significance |
|---|---|
| IVDR Class C Device Pathway Acceleration | EMA centralized authorization reduces regulatory fragmentation across German and French member states. |
| Microfluidic Platform Hospital Integration | Direct LIS connectivity in Heidelberg and Berlin pathology departments displaces manual data entry workflows. |
| Multi-Cancer Early Detection Convergence | CTC-circulating tumor DNA integration opens pan-cancer screening beyond current lung-breast-colorectal focus. |
| REACH-Compliant Reagent Reformulation | Magnetic nanoparticle substitution with chip-based capture maintains assay performance under ECHA restrictions. |
| Procurement Framework Consolidation | Baden-Württemberg and Ile-de-France hospital alliances displace single-site vendor relationships through scale. |
Research Methodology
Coverage spans Germany, France, the Netherlands, Spain, and Switzerland, with primary inputs from each market's hospital procurement committees, pathology laboratory directors, regulatory affairs specialists at assay developers, and GPO contracts managers. Secondary validation draws from EMA centralized authorization filings, IVDR technical documentation databases, G-BA early-benefit assessment records, and hospital procurement framework agreements. Bottom-up test volume modeling triangulates against top-down market sizing from platform installation data and consumable shipment patterns.
Granularity-level modeling operates at technology-platform-by-indication-by-end-user resolution, with separate projections for microfluidic versus immunomagnetic isolation systems, lung versus breast versus colorectal cancer indications, and hospital-based pathology departments versus centralized reference laboratories. CAGRs derive from fitted growth curves anchored to IVDR implementation timelines and procurement framework renewal cycles. Industry-specific forecast inputs include ECHA REACH compliance deadlines and HAS evaluation framework revisions for companion diagnostic claims.
Inputs from hospital procurement databases and regulatory filing records were available through the study window; gaps in real-time microfluidic chip manufacturing capacity data introduce uncertainty bands around platform deployment timelines. Forecasts reflect assumptions on IVDR notified body capacity constraints and G-BA reimbursement decision pacing. Deviation in ECHA substance restriction enforcement timing or HAS evidence requirement tightening would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Diagnostics
Fluorescence Cell Market
Medical Diagnostics
Cellular Pathology Market
Medical Diagnostics
Stem Cell Panel Market
Medical Diagnostics
Medical Isotope Market
Medical Diagnostics
In-Situ Hybridization (ISH) Market
Medical Diagnostics
Liver Biopsy Market
Medical Diagnostics
Stem Cell Characterization Kits Market
Medical Diagnostics
Global ELISA Analyzer Market
Medical Diagnostics
Medical Marker Bands Market
Medical Diagnostics
US Molecular Diagnostics Market
Medical Diagnostics
Asia-Pacific Flow Cytometry Market
Medical Diagnostics
Global Hydrophobic Interaction Chromatography Market
Medical Diagnostics
Karyotype Analysis Service Market
Medical Diagnostics
Asia-Pacific Single Cell Analysis Market
Medical Diagnostics
Global Histology and Cytology Market
Medical Diagnostics
Rapid Medical Diagnostic Kits Market