
 Medical Isotope Market | 2026-2036
Medical Isotope Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Isotope Market Foresight
Consolidation among hospital purchasing networks is realigning procurement leverage across the Medical Isotope supply base. Cardinal Health sustains one of the largest radiopharmacy distribution footprints in North America. Curium dominates European production of SPECT isotopes through its reactor-linked manufacturing network. GE Healthcare leverages cyclotron infrastructure to secure regional supply continuity for PET tracers.
Medical isotopes are unstable atomic nuclei that emit radiation at predictable half-lives, typically produced through neutron bombardment in research reactors or charged-particle acceleration, then formulated into radiopharmaceuticals for disease detection and targeted therapy. Tc-99m remains the workhorse isotope for cardiac and bone imaging, though supply fragility from aging reactors has intensified interest in accelerator-based alternatives. Lu-177 represents the fastest-expanding product category, driven by its precision in targeting neuroendocrine tumors and expanding prostate cancer trials. Cancer Treatment applications command the deepest margin pools, while Diagnostic Procedures still generate the highest procedure volume across hospital networks.
The FDA regulates radiopharmaceutical manufacturing under current Good Manufacturing Practice standards, while the Nuclear Regulatory Commission governs isotope handling, transport, and disposal protocols that shape operational costs. The European Medicines Agency enforces the EU GMP Annex guidelines for sterile radioactive products, creating divergent compliance burdens for cross-border suppliers. Stakeholders must monitor which production technologies secure regulatory equivalency across jurisdictions, as this determines scalable market access without redundant facility investment.
Market Dynamics
The Medical Isotope Market pivots on reactor-to-accelerator supply substitution as aging nuclear research infrastructure faces decommissioning schedules across OECD nations. This structural transition is compressing traditional production economics while opening capital deployment into charged-particle systems.
Growth Catalysts
- FDA Streamlined Pathways:Accelerated review timelines for novel radiopharmaceuticals under breakthrough therapy designation are compressing commercialization cycles for precision oncology agents.
- Theranostic Program Expansion:Academic medical centers are scaling paired diagnostic-therapy service lines, creating pull-through demand for Lu-177 and companion imaging isotopes.
- Medicare Reimbursement Alignment:United States payment policy increasingly favors precision radiotherapy modalities, directing hospital capital toward targeted alpha and beta emitter programs.
Market Restraints
- Reactor Concentration Risk:Five aging government-owned reactors supply the majority of Mo-99 feedstock, with scheduled maintenance windows creating predictable supply interruptions.
- HEU Conversion Friction:Elimination of highly enriched uranium from medical isotope production requires capital-intensive target redesign and regulatory requalification.
- Short Half-Life Logistics:Tc-99m's six-hour decay window forces same-day manufacturing and delivery, eliminating inventory buffers and amplifying geographic supply inequality.
Strategic Opportunities
- Accelerator-Based Production:Commercial cyclotron and electron accelerator networks offer distributed manufacturing models that circumvent reactor dependency and reduce transport radii.
- Alpha-Emitter Therapeutics:Actinium-225 and lead-212 development programs address resistant metastatic disease indications with higher linear energy transfer than beta alternatives.
- India Domestic Supply:Indigenous research reactor capacity expansion under the Department of Atomic Energy creates import substitution potential for the subcontinent's imaging base.
Industry Challenges
- Radiochemist Talent Scarcity:Synthesis of clinical-grade radiopharmaceuticals requires specialized expertise at the intersection of nuclear chemistry and GMP manufacturing, with training pipelines failing to match program expansion.
- Cross-Border Shipment Complexity:Each national nuclear regulator imposes distinct documentation, packaging, and carrier certification requirements that fragment continental distribution efficiency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Isotope Market |
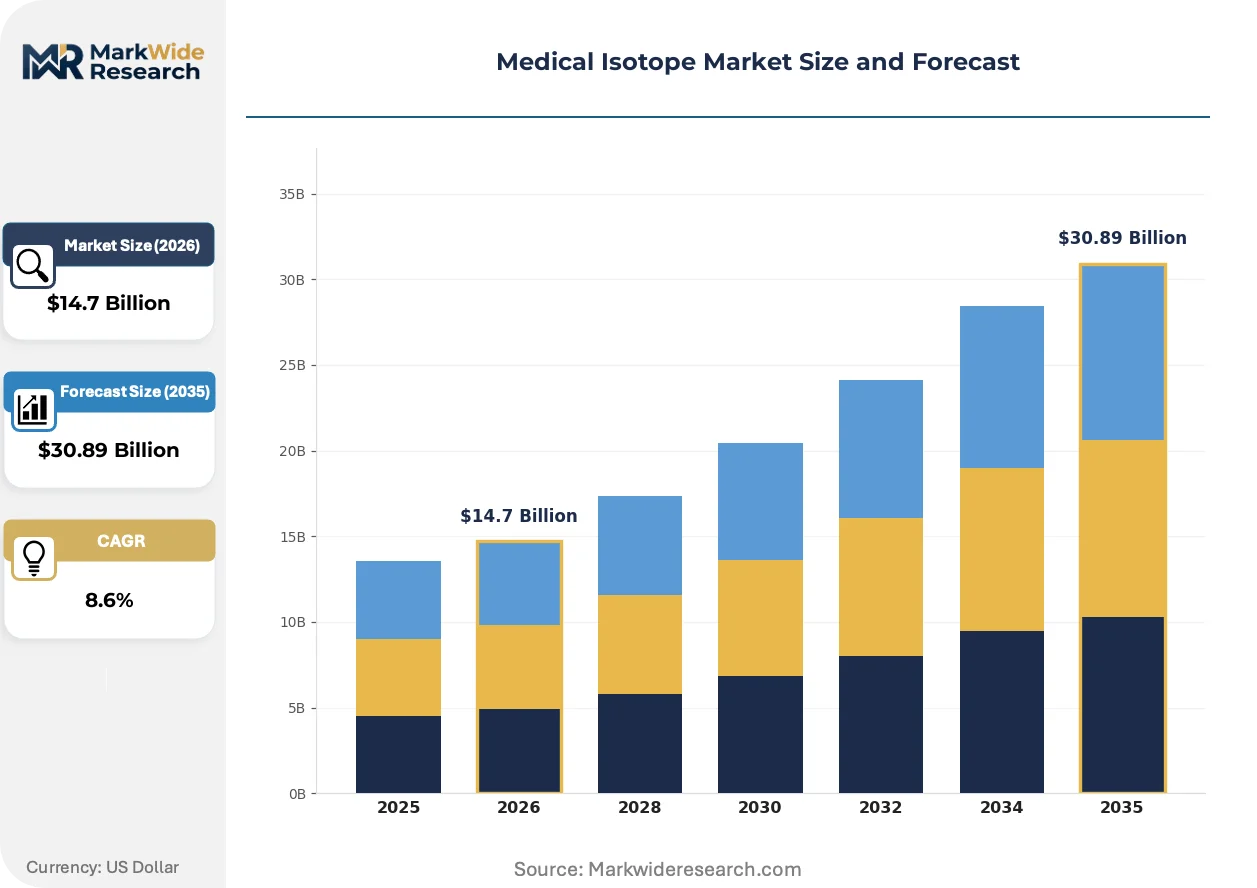
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $30.89 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tc-99m, I-131, Co-60, Lu-177 Application: Cancer Treatment, Imaging, Diagnostic Procedures, Pain Management Delivery Mode: Injectable, Oral Administration, Inhalation, Topical End User: Hospitals, Diagnostic Centers, Research Laboratories, Outpatient Clinics |
| Companies Covered | Cardinal Health, NorthStar Medical Radioisotopes, Curium, Lantheus Holdings, GE Healthcare, BWX Technologies, NTP Radioisotopes, Eckert & Ziegler, Nordion, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Isotope Market Shifts & Advancements
Production technology diversification is fragmenting the Medical Isotope supply architecture away from centralized reactor dependence toward distributed accelerator networks and novel target systems.
Non-uranium molybdenum targets paired with neutron capture production methods are electrifying supply security discussions among hospital procurement officers. European and North American health systems are piloting these systems to eliminate HEU from their supply chains entirely. The technology is electrifying competitive positioning for regional cyclotron operators seeking to displace reactor-sourced Mo-99.
EMA's revised GMP Annex guidelines for sterile radioactive medicinal products are tightening environmental monitoring and personnel exposure documentation requirements. Manufacturing facilities across EU member states are retrofitting cleanroom infrastructure and revalidating batch release protocols. Small-scale radiopharmacy operators in Southern Europe are consolidating into centralized production hubs to absorb compliance overhead.
Hospital networks are consolidating radiopharmaceutical purchasing through specialty GPOs that aggregate volume across oncology, cardiology, and nuclear medicine service lines. Traditional distributor relationships are compressing as these purchasing entities demand direct manufacturer contracting with transparent cost-plus pricing. This concentration is most pronounced in the United States, where three national health systems now control a significant share of diagnostic imaging isotope procurement.
Medical Isotope Market Segmentation
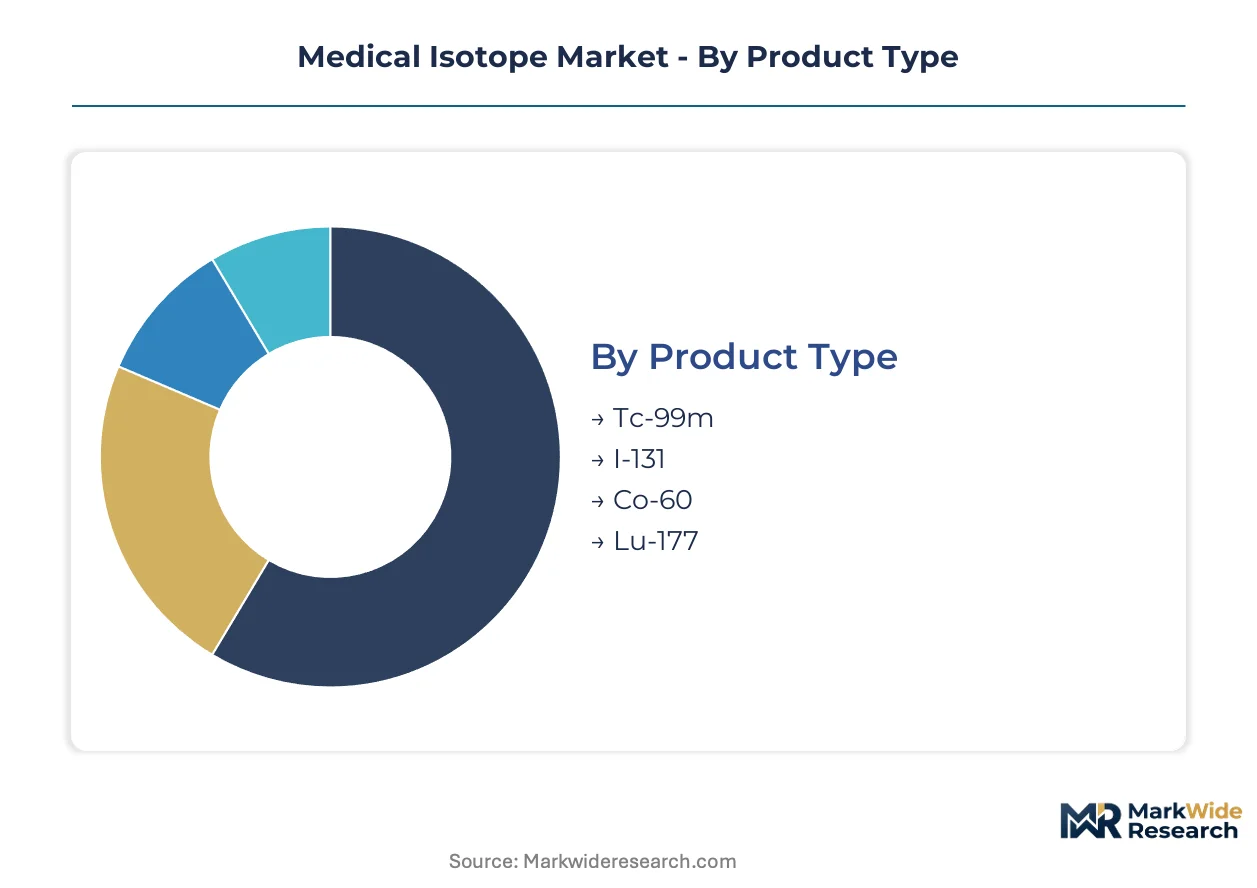
Medical isotope procurement patterns diverge sharply across clinical settings, with reimbursement structures and half-life constraints dictating inventory strategies. Segment-level demand fragmentation requires suppliers to maintain parallel production and distribution architectures.
Product Type:
Clinical utility and decay characteristics separate high-volume diagnostic tracers from precision therapeutic emitters.
- Tc-99m:A metastable technetium isotope emitting 140 keV gamma radiation ideal for gamma camera detection. United States hospital networks consume the bulk of global supply for cardiac stress testing and bone metastasis screening, though reactor concentration risk forces same-day logistics networks.
- Lu-177:A beta-emitting lutetium isotope with 6.7-day half-life enabling centralized radiolabeling and regional distribution. Academic medical centers in Germany and the United States are expanding theranostic programs pairing Lu-177 DOTATATE therapy with Ga-68 imaging, climbing the fastest among all product categories.
- I-131:A gamma and beta emitter with 8-day half-life for thyroid ablation and hyperthyroidism management.
- Co-60:A high-energy gamma source with 5.3-year half-life for external beam radiotherapy equipment sterilization.
Volume sits with Tc-99m; growth tilts toward Lu-177.
Application:
Reimbursement intensity and procedure complexity create distinct margin profiles across clinical use cases.
- Cancer Treatment:Targeted radionuclide therapy using alpha and beta emitters delivers cytotoxic radiation to tumor cells with minimal systemic exposure. United States Medicare's transitional pass-through payment for radiopharmaceuticals has accelerated hospital investment in Lu-177 and Ra-223 programs, though prior authorization requirements vary by carrier.
- Diagnostic Procedures:Functional imaging using SPECT and PET tracers generates the highest procedure volume across hospital networks. India's expanding diagnostic center base under the Ayushman Bharat scheme is pulling imported Mo-99/Tc-99m generators, though domestic BRIT production aims to reduce import dependency.
- Imaging:Anatomical and functional visualization across cardiology, neurology, and oncology departments.
- Pain Management:Palliative radiopharmaceuticals for bone metastasis pain relief in advanced cancer patients.
Procedure volume concentrates in Diagnostic Procedures; value capture shifts toward Cancer Treatment.
Delivery Mode:
Regulatory classification and handling requirements segment manufacturing infrastructure by administration route.
- Injectable:Intravenous and intra-arterial administration of radiopharmaceuticals requires aseptic processing under GMP Annex 1 guidelines. European manufacturing facilities are consolidating sterile filling capacity as EMA tightens environmental monitoring requirements, with centralized hubs replacing satellite radiopharmacy operations.
- Oral Administration:Capsule and liquid formulations for thyroid and palliative therapies permit longer distribution radii due to stable shelf life.
- Inhalation:Aerosolized radioisotopes for ventilation-perfusion lung imaging.
- Topical:Surface-applied sources for ophthalmic and dermatologic applications.
Regulatory burden clusters around Injectable; Oral Administration offers the broadest geographic reach.
End User:
Capital intensity and patient throughput determine purchasing power and contract structure preferences.
- Hospitals:Integrated delivery networks with in-house nuclear medicine departments and cyclotron infrastructure. United States health systems including Mayo Clinic and Cleveland Clinic are insourcing Lu-177 production through on-site radiochemistry laboratories, bypassing commercial distributor markups.
- Diagnostic Centers:Outpatient imaging facilities dependent on daily Tc-99m generator deliveries and contracted radiopharmacy services.
- Research Laboratories:Academic and commercial sites developing novel radiolabeled antibodies and alpha-emitter conjugates.
- Outpatient Clinics:Community-based practices administering I-131 thyroid therapies and limited diagnostic injections.
Contract value aggregates at Hospitals; site expansion is fastest among Diagnostic Centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States hospital networks concentrate the deepest procurement pools for precision radiotherapy isotopes, while European reactor infrastructure and Asian domestic production investments are rebalancing historical supply dependencies.
United States
Medicare reimbursement alignment with precision radiotherapy modalities drives hospital capital allocation toward Lu-177 and alpha-emitter programs. FDA breakthrough therapy designations compress commercialization timelines for novel radiopharmaceuticals. Mayo Clinic and Cleveland Clinic anchor theranostic program expansion through in-house radiochemistry laboratories.
Germany
Academic medical centers scale paired diagnostic-therapy service lines, creating concentrated demand for Ga-68 companion imaging isotopes. EMA revised GMP Annex guidelines tighten sterile radioactive product manufacturing standards. Bavarian and Baden-Württemberg manufacturing hubs consolidate cleanroom infrastructure to absorb compliance overhead.
India
Ayushman Bharat scheme expansion pulls imported Mo-99/Tc-99m generators into diagnostic center networks. Department of Atomic Energy indigenous reactor capacity targets import substitution for imaging base. Mumbai and Hyderabad clusters anchor domestic production scale-up under BIS pharmaceutical standards.
Canada
Chalk River reactor decommissioning accelerates accelerator-based production pilot programs for Mo-99 security. Health Canada aligns radiopharmaceutical oversight with FDA GMP equivalence pathways. Ontario manufacturing corridors test non-uranium target systems for regional supply continuity.
France
Curium's reactor-linked SPECT isotope network supplies European hospital networks with Tc-99m generators. ANSM enforces environmental monitoring protocols for sterile radioactive medicinal products. Île-de-France radiopharmacy operations consolidate into centralized hubs under EMA compliance frameworks.
Medical Isotope Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue accelerator-based distributed manufacturing models. The vendor base stratifies across reactor-dependent incumbents, cyclotron-network operators, and radiopharmacy consolidators. Three archetypes dominate: integrated health system suppliers, regional production specialists, and theranostic platform developers. Capacity expansion and strategic partnerships constitute the dominant competitive vectors as reactor decommissioning schedules compress.
Among North American health system suppliers, Cardinal Health and Lantheus Holdings exemplify radiopharmacy distribution scale, while Curium anchors European reactor-linked production networks. GE Healthcare occupies a position bridging cyclotron infrastructure with regional supply continuity frameworks. These three entities represent distinct geographic and technological positioning without overlapping core production dependencies.
| Leading Market Players |
|---|
| Cardinal Health |
| NorthStar Medical Radioisotopes |
| Curium |
| Lantheus Holdings |
| GE Healthcare |
| BWX Technologies |
| NTP Radioisotopes |
| Eckert & Ziegler |
| Nordion |
| Others |
Supply & Pricing Matrix
Captive reactor-to-generator integration at Curium and Cardinal Health anchors both supply security and pricing power for technetium generators, locking hospital networks into long-term offtake contracts that insulate incumbent producers from spot-market volatility while compressing margins for distributor-dependent competitors.
Pricing Analysis
Volume concentrates in high-throughput Tc-99m cardiac imaging where per-dose pricing faces compression from Medicare reimbursement ceilings, while margins deepen in Lu-177 theranostic programs where academic medical centers accept premium positioning for precision oncology. Price differentiation hinges on cold-chain reliability certification and vertical integration depth, with reactor-linked producers commanding standard-plus tiers against accelerator-based challengers. Cost compression in the diagnostic tier is intensifying because diagnostic centers aggregate purchasing through specialty GPOs. Community hospitals exhibit the highest price sensitivity due to thin nuclear medicine department margins, while integrated delivery networks with in-house cyclotrons demonstrate the least.
Supply Chain Analysis
Return flows of depleted Mo-99 generators and residual Lu-177 precursor materials require licensed reverse-logistics networks with specialized radiological handling, adding cost layers that reactor-dependent incumbents absorb more efficiently than distributed accelerator operators. Production concentrates in Belgium, the Netherlands, and South Africa for Mo-99 feedstock, with regional cyclotron networks expanding in the United States and Germany. The supply chain draws from highly enriched uranium conversion programs and neutron-irradiated molybdenum targets as critical inputs. Single-source vulnerability at the five aging research reactors supplying global Mo-99 feedstock constitutes the dominant structural risk. Distribution runs through radiopharmacy hubs with same-day delivery radius constraints imposed by Tc-99m decay windows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Reactor decommissioning schedules across OECD nations are forcing accelerated consolidation, eliminating capital-constrained players unable to fund accelerator-based production transitions or absorb EMA GMP Annex compliance overhead.
For Market Incumbents: Extend cyclotron network coverage into underserved United States regions before NorthStar Medical Radioisotopes and regional challengers secure hospital anchor contracts, while deepening HEU-free target qualification to preempt regulatory displacement. Lock in academic medical center partnerships through theranostic program co-development, using Lu-177 DOTATATE therapy pull-through to defend generator market share against distributor erosion. For New Entrants and Emerging Players: Specialty GPOs represent the fastest path to volume aggregation, particularly those serving community hospital networks frustrated by Cardinal Health delivery reliability gaps. Target India's diagnostic center expansion under Ayushman Bharat, where import substitution incentives favor domestic BRIT partnerships over established European suppliers. Lead with non-uranium Mo-99 production claims to differentiate from reactor-dependent incumbents in procurement RFPs. For Investors and Strategic Acquirers: Exit pathways concentrate in mid-cap accelerator operators with FDA breakthrough therapy-designated radiopharmaceutical pipelines and established hospital system relationships. Long-term viability favors entities with dual diagnostic-therapeutic isotope portfolios rather than single-product dependencies. Watch for Medicare pass-through payment rulemaking on alpha-emitters as the inflection signal for hospital capital allocation shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Accelerator Network Expansion | Distributed cyclotron infrastructure reduces reactor dependency and shortens Tc-99m delivery radii for hospital networks. |
| HEU-Free Target Qualification | Non-uranium molybdenum systems secure regulatory equivalency across FDA and EMA jurisdictions without redundant facility investment. |
| Theranostic Program Partnership | Ga-68 Lu-177 paired service lines at Mayo Clinic and Cleveland Clinic anchor academic medical center loyalty. |
| GPO Contract Consolidation | Specialty purchasing entities aggregate oncology cardiology nuclear medicine volume, compressing traditional distributor markups. |
| Alpha-Emitter Pipeline Development | Actinium-225 programs address resistant metastatic indications with higher linear energy transfer than beta alternatives. |
Research Methodology
Multi-period observation of reactor maintenance schedules, Medicare reimbursement rulemaking, and FDA breakthrough therapy designations anchored the trend analysis, supplemented by interviews with nuclear medicine department heads, radiopharmacy operations managers, GPO contracts specialists, and Department of Atomic Energy officials. Secondary validation drew from FDA 510(k) filings, EMA GMP Annex revision drafts, CMS Medicare payment rulemaking dockets, and IAEA research reactor databases. Bottom-up procedure volume modeling at hospital networks triangulated against top-down isotope production capacity estimates from OECD nuclear energy reports.
The input-output matrix mapped reactor and cyclotron production capacity against diagnostic procedure demand across cardiac, oncology, and neurology service lines, with segmentation by isotope half-life constraints, administration route regulatory classification, and end-user capital intensity. CAGRs were derived from elasticity-adjusted demand projections and supply-side capacity expansion schedules across the analysis window. Forecast inputs incorporated Medicare transitional pass-through payment policy trajectories and EMA environmental monitoring compliance cost assumptions for sterile radioactive manufacturing.
Caveats apply where reactor decommissioning delays, HEU conversion program setbacks, or radiochemist training pipeline failures could materially shift the outlook for supply continuity and pricing dynamics. Practitioners should monitor FDA breakthrough therapy designation velocity and Medicare alpha-emitter reimbursement rulemaking for early signals of hospital capital reallocation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Diagnostics
Stem Cell Characterization Kits Market
Medical Diagnostics
Global Hydrophobic Interaction Chromatography Market
Medical Diagnostics
Global Circulating Tumor Cells Market
Medical Diagnostics
Global Histology and Cytology Market
Medical Diagnostics
AI in Medical Diagnostics Market
Medical Diagnostics
Asia-Pacific Flow Cytometry Market
Medical Diagnostics
Blood Platelet Market
Medical Diagnostics
Global HLA Typing for Transplant Market
Medical Diagnostics
MUC1 Antibody Market
Medical Diagnostics
Dosimetry Market
Medical Diagnostics
Liver Biopsy Market
Medical Diagnostics
Global Complete Blood Count Device Market
Medical Diagnostics
Telepathology Market
Medical Diagnostics
Karyotype Analysis Service Market
Medical Diagnostics
Stem Cell Panel Market
Medical Diagnostics
Fluid Biopsy Market