
 Europe Colorectal Cancer Diagnostics Market | 2026-2036
Europe Colorectal Cancer Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Colorectal Cancer Diagnostics Market Foresight
Market Context
Software-defined image analytics is shifting how diagnostic platforms capture recurring revenue across European healthcare networks. Illumina, Inc. leverages its sequencing infrastructure to anchor molecular screening contracts with national health services. Thermo Fisher Scientific Inc. competes through integrated workflow automation that reduces laboratory turnaround times. Siemens Healthineers AG dominates the installed base of CT and MRI systems, extending service agreements that lock in multi-year maintenance streams.
Technical Definition and Segment Structure
Europe colorectal cancer diagnostics encompasses imaging, molecular, and histopathological methods for detecting malignant neoplasms in the colon and rectum, typically employing multi-slice CT protocols with sub-millimeter spatial resolution to identify polyps and stage tumors for surgical planning. Genetic tests represent the fastest-expanding segment as liquid biopsy platforms displace repeat tissue sampling in metastatic monitoring, while endoscopy maintains the largest procedure volume due to its dual diagnostic-therapeutic function in polypectomy. Hospitals command the dominant share of capital expenditure for imaging modalities, though diagnostic laboratories are capturing growing volumes of fecal immunochemical and circulating tumor DNA assays through decentralized network expansion.
Regulatory Environment
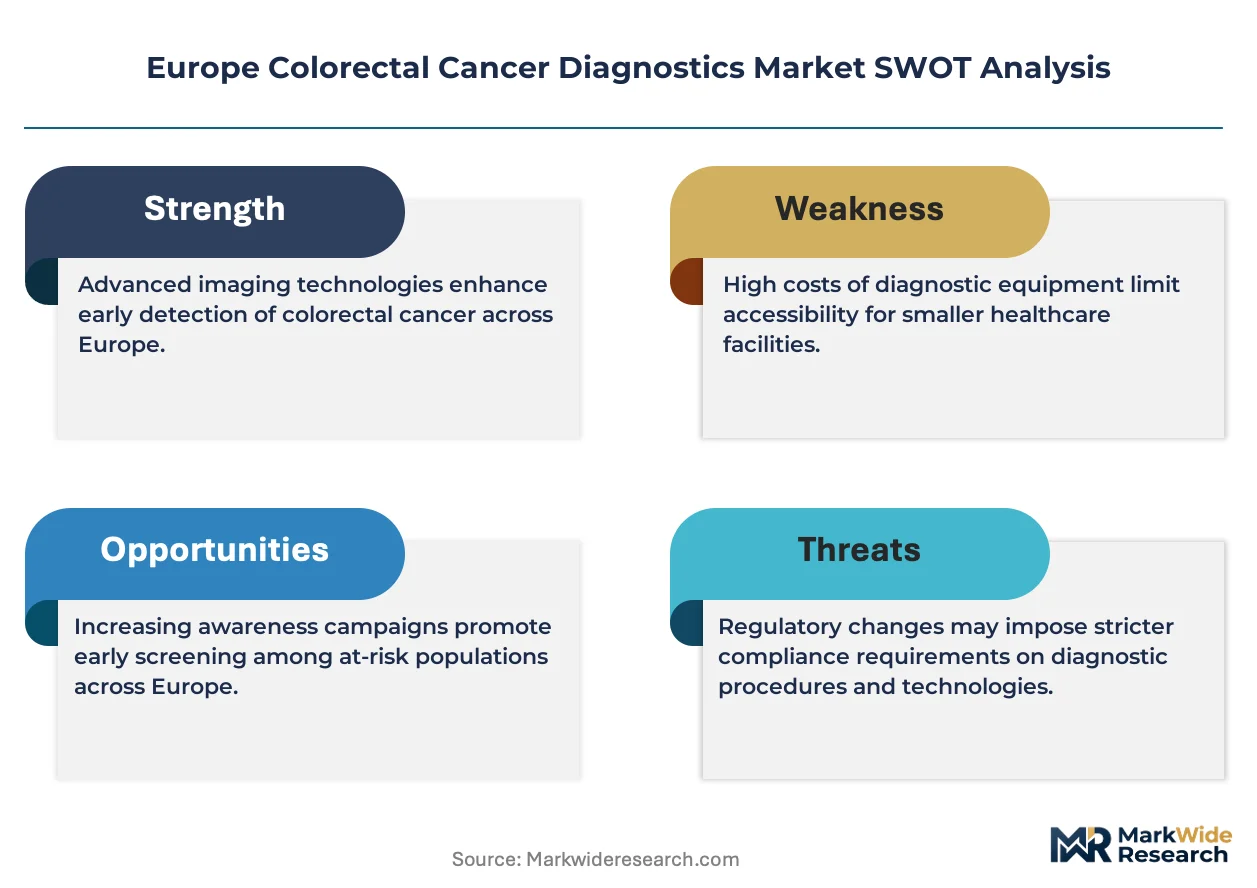
The European Medicines Agency oversees in vitro diagnostic performance standards under the In Vitro Diagnostic Regulation, while CE marking requirements govern market access for imaging equipment and molecular platforms across member states. The EU AI Act introduces conformity obligations for machine-learning-assisted polyp detection systems, creating compliance costs that favor established manufacturers with dedicated regulatory affairs teams. Stakeholders must monitor how national reimbursement authorities calibrate coverage decisions between proven endoscopic methods and emerging blood-based screening technologies.
Market Dynamics
Hospital procurement departments across Germany, France, and the United Kingdom are consolidating molecular diagnostic contracts under framework agreements that favor vendors with integrated sequencing-to-reporting workflows, compressing vendor margins while locking in multi-year service commitments.
Growth Catalysts
- EU Green Deal procurement mandates:Sustainable healthcare procurement criteria redirect capital toward energy-efficient imaging platforms, accelerating replacement cycles for legacy CT and MRI systems in tertiary oncology centers.
- Liquid biopsy platform maturation:Circulating tumor DNA assays are displacing repeat tissue sampling in metastatic monitoring, creating recurring revenue streams for laboratories serving regional hospital networks.
- Germany's integrated diagnostic pathways:Dense networks of oncology centers are shortening time-to-treatment by embedding molecular testing within standardized care protocols, driving fecal immunochemical test volumes.
Market Restraints
- CE marking complexity under IVDR:The In Vitro Diagnostic Regulation imposes heightened clinical evidence requirements on novel biomarker assays, extending time-to-market for innovative screening technologies by 18-24 months.
- Sequencing reagent supply concentration:Critical consumables for next-generation sequencing platforms originate from a narrow supplier base concentrated in North American and East Asian manufacturing clusters, exposing European laboratories to freight volatility and currency risk.
- Endoscopic capacity constraints:Colonoscopy throughput remains capped by gastroenterologist availability and procedure room utilization rates, creating bottlenecks that stool-based screening methods cannot fully bypass without confirmatory follow-up.
Strategic Opportunities
- France's decentralized laboratory expansion:Regional health authorities are licensing satellite diagnostic facilities in Normandy and Brittany, creating first-mover advantage for vendors with portable molecular testing platforms.
- AI-assisted polyp detection convergence:Machine-learning algorithms paired with high-definition endoscopy systems are reducing adenoma miss rates, opening reimbursement negotiations with national health technology assessment bodies.
- Direct-to-consumer screening channels:Pharmacy-based fecal immunochemical test distribution is bypassing traditional physician referral pathways in the United Kingdom, capturing health-conscious demographic segments outside organized screening programs.
Industry Challenges
- Computational pathology talent scarcity:Laboratories deploying digital whole-slide imaging systems face recruitment gaps for bioinformaticians capable of integrating AI classifiers with laboratory information management systems.
- Legacy imaging equipment interoperability:PACS integration requirements for new molecular reporting platforms demand costly middleware development to bridge decades-old radiology infrastructure with cloud-based analytics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Colorectal Cancer Diagnostics Market |
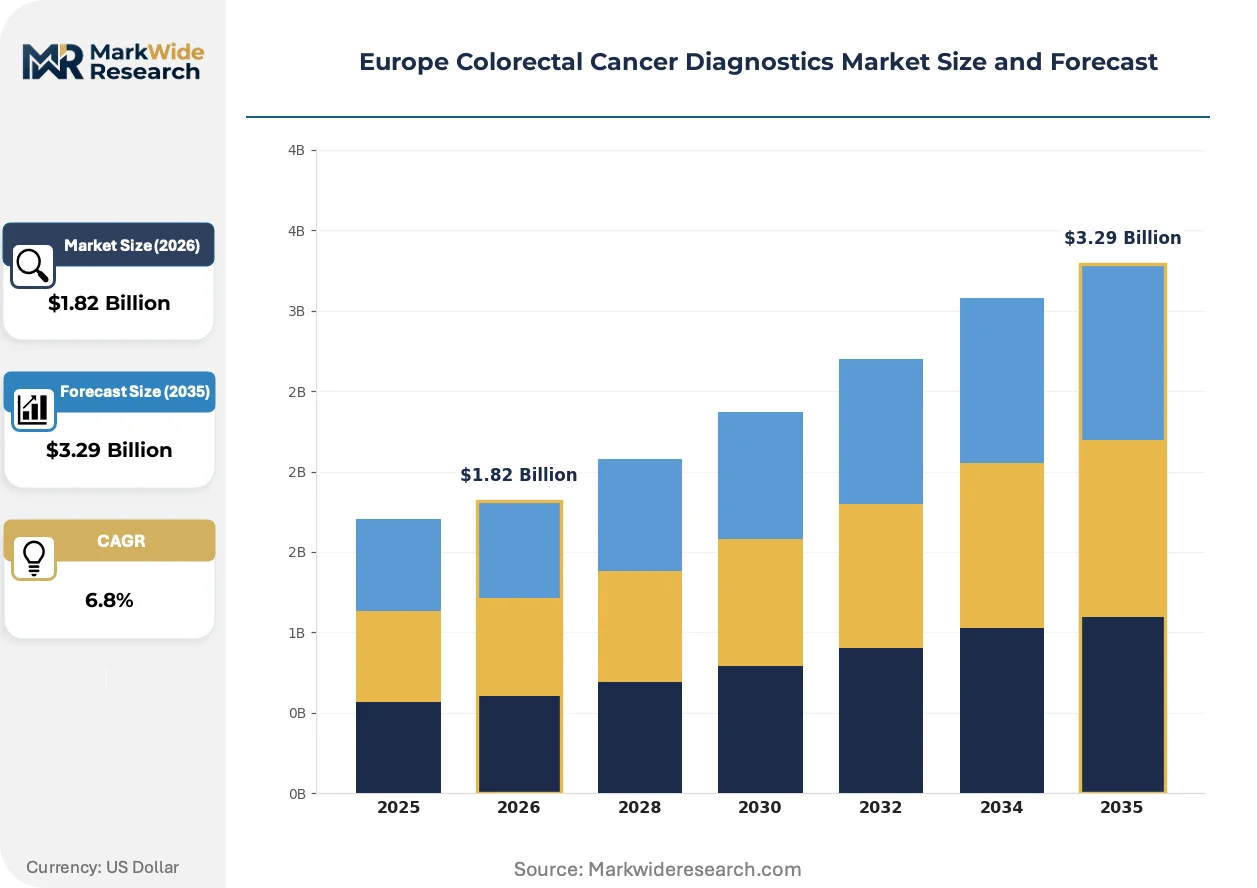
| Market Size in 2026 | $1.82 Billion |
| Market Size in 2035 | $3.29 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Imaging Techniques, Biopsy Kits, Tumor Markers, Genetic Tests Technology: Computed Tomography, Magnetic Resonance Imaging, Endoscopy, PET Scans End User: Hospitals, Diagnostic Laboratories, Cancer Research Centers, Outpatient Clinics Application: Early Detection, Monitoring, Screenings, Recurrence Testing |
| Companies Covered | Illumina, Inc., Koninklijke Philips N.V., Thermo Fisher Scientific Inc., Quest Diagnostics Incorporated, F. Hoffmann-La Roche Ltd., Abbott Laboratories, Epigenomics AG, Siemens Healthineers AG, Sysmex Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Colorectal Cancer Diagnostics Market Shifts & Advancements
Software-defined diagnostic platforms are collapsing the traditional separation between imaging hardware and analytical software, enabling vendors to capture value through subscription-based algorithm updates rather than capital equipment sales alone.
Multi-cancer early detection blood tests are expanding into asymptomatic screening populations, with commercial laboratories in the United Kingdom and Germany negotiating pilot contracts with private insurers to establish clinical utility evidence ahead of statutory reimbursement decisions. National health services are monitoring these pilots to calibrate coverage policy, creating a pathway for blood-based screening to complement existing fecal and endoscopic methods.
The EU AI Act introduces conformity assessment obligations for machine-learning-assisted polyp detection systems, requiring manufacturers to document training data provenance and algorithmic performance across diverse patient populations. Gastroenterology device manufacturers with dedicated regulatory affairs teams are accelerating CE marking submissions to secure first-mover positioning, while smaller developers face compliance costs that favor partnership with established imaging platform vendors.
Hospital procurement departments are unbundling maintenance contracts from imaging equipment purchases, negotiating separate service agreements with third-party technical service organizations or in-house biomedical engineering teams. This shift is most visible in Spain and Italy, where regional health system budget pressures are driving preference for multi-vendor service platforms over single-source OEM commitments.
Europe Colorectal Cancer Diagnostics Market Segmentation
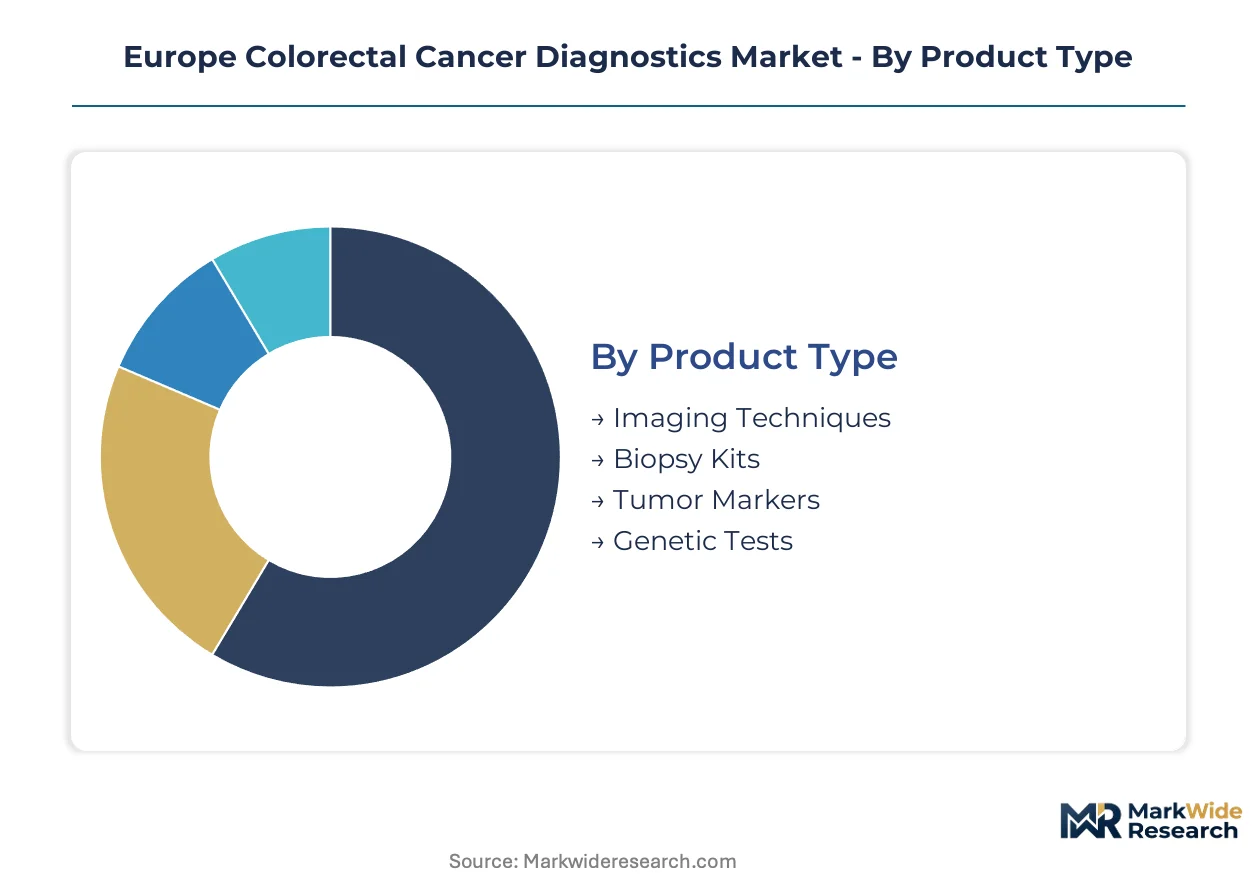
Segmentation in the Europe colorectal cancer diagnostics market reveals how capital deployment, clinical workflow integration, and reimbursement pathways shape vendor strategy. Understanding where imaging hardware, molecular assays, and service contracts concentrate revenue helps identify which technology transitions will displace incumbent platforms.
Product Type:
Capital intensity varies sharply across product categories, with imaging systems requiring multimillion-euro installations and genetic tests demanding sequencing infrastructure but lower per-unit hardware outlays.
- Imaging Techniques:Multi-slice CT colonography and MRI enterography systems dominate hospital capital budgets across Germany and France. Siemens Healthineers and GE Healthcare lock in multi-year service agreements that extend revenue streams well beyond initial equipment sales.
- Genetic Tests:Next-generation sequencing panels and circulating tumor DNA assays are expanding fastest among regional laboratory networks in the United Kingdom and Netherlands. Reagent rental models reduce upfront capital barriers while embedding vendors in recurring consumable revenue.
- Biopsy Kits:Disposable forceps and polypectomy snares follow colonoscopy procedure volumes in Spain and Italy.
- Tumor Markers:CEA and CA 19-9 immunoassays retain utility in metastatic monitoring despite sensitivity limitations.
Most installed capacity flows through Imaging Techniques. Expansion is steepest in Genetic Tests.
Technology:
Procedure volume and reimbursement rates determine which modalities capture clinician preference and capital allocation across European health systems.
- Endoscopy:Optical colonoscopy remains the clinical gold standard for simultaneous detection and therapeutic polypectomy. Gastroenterologist availability and procedure room throughput constrain volume growth in France and the United Kingdom.
- Computed Tomography:CT colonography offers non-invasive screening for patients contraindicated for sedation, with Germany's statutory health insurers expanding coverage for incomplete optical colonoscopies.
- Magnetic Resonance Imaging:Pelvic MRI dominates rectal cancer staging for surgical planning in tertiary oncology centers.
- PET Scans:FDG-PET utilization concentrates in metastatic staging and treatment response assessment.
Endoscopy carries the highest procedure volume. CT colonography is gaining share fastest among non-invasive alternatives.
End User:
Procurement authority and reimbursement pathways fragment demand across facility types with diverging capital constraints and test menu requirements.
- Hospitals:Tertiary oncology centers in Germany and France consolidate imaging procurement under framework agreements, favoring vendors with integrated molecular-to-imaging workflows and dedicated regulatory affairs teams.
- Diagnostic Laboratories:Decentralized networks in the United Kingdom and Spain are capturing growing fecal immunochemical and circulating tumor DNA volumes through hub-and-spoke logistics models.
- Cancer Research Centers:Academic medical centers drive adoption of experimental multi-cancer early detection blood tests ahead of statutory reimbursement.
- Outpatient Clinics:Ambulatory endoscopy centers in Italy face margin pressure from regional health system budget constraints.
Hospitals command the dominant capital expenditure share. Diagnostic Laboratories are expanding volume fastest through decentralized network buildout.
Application:
Clinical utility evidence and reimbursement coverage determine which applications attract vendor investment and health system prioritization.
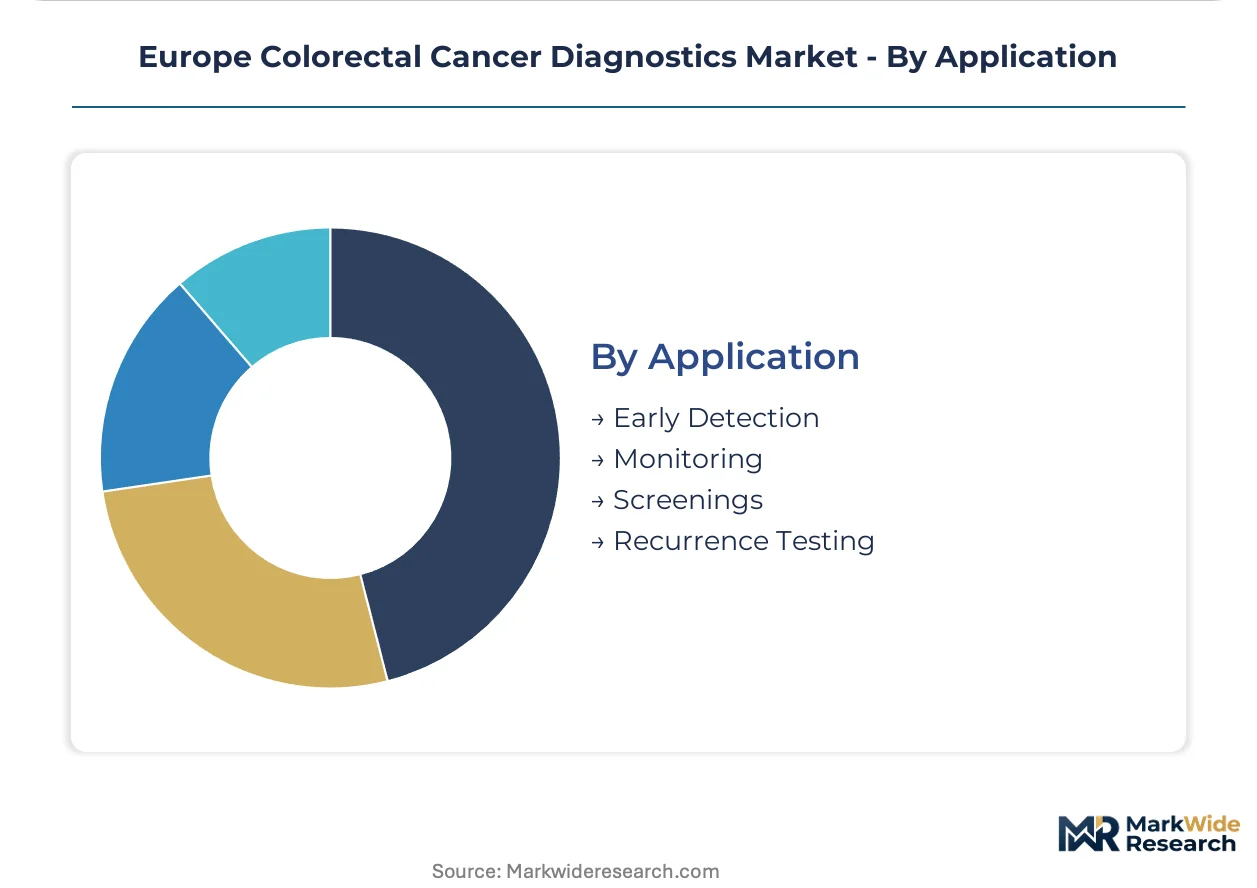
- Screenings:Organized fecal immunochemical test programs in the United Kingdom and Germany drive population-scale volume, with positive cases triaged to colonoscopy confirmation.
- Early Detection:Blood-based multi-cancer tests are entering pilot contracts with private insurers in Germany and Switzerland to establish clinical utility ahead of statutory coverage decisions.
- Monitoring:Circulating tumor DNA assays displace repeat tissue biopsies in metastatic patient management.
- Recurrence Testing:Post-surgical surveillance protocols combine CEA monitoring with scheduled imaging.
Screenings absorb the largest test volume. Early Detection is climbing the fastest as blood-based platforms seek reimbursement entry.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's dense network of oncology centers processes diagnostic volumes that dwarf France's hospital consolidation efforts, yet both markets now redirect procurement capital toward energy-efficient imaging platforms under EU Green Deal mandates.
Germany
Hospital procurement departments across Bavaria and North Rhine-Westphalia consolidate molecular diagnostic contracts under framework agreements favoring integrated sequencing-to-reporting workflows. The EU Green Deal's sustainable healthcare procurement criteria accelerate replacement cycles for legacy CT systems in tertiary centers. Berlin-Brandenburg hosts Siemens Healthineers' service operations that lock in multi-year maintenance streams across federal hospital networks.
France
Regional health authorities in Normandy and Brittany license satellite diagnostic facilities, creating first-mover opportunities for portable molecular testing platforms. ANSM oversight of in vitro diagnostic performance standards shapes CE marking pathways for novel biomarker assays. The Île-de-France cluster concentrates AI-assisted polyp detection development as manufacturers accelerate submissions under the EU AI Act.
United Kingdom
Pharmacy-based fecal immunochemical test distribution bypasses traditional physician referral pathways, capturing health-conscious demographics outside organized screening programs. NICE reimbursement negotiations calibrate coverage between proven endoscopic methods and emerging blood-based screening technologies. London's academic medical centers pilot multi-cancer early detection blood tests ahead of statutory coverage decisions.
Netherlands
Diagnostic laboratories in the Randstad region capture growing circulating tumor DNA volumes through hub-and-spoke logistics models serving regional hospital networks. The EU In Vitro Diagnostic Regulation imposes clinical evidence requirements that extend time-to-market for innovative screening technologies. Eindhoven's health technology corridor attracts vendors with portable molecular platforms targeting decentralized expansion.
Spain
Regional health system budget pressures in Madrid and Catalonia drive preference for multi-vendor service platforms over single-source OEM commitments. Ambulatory endoscopy centers face margin compression from procurement unbundling of maintenance contracts. Barcelona's biomedical research clusters support pilot programs for machine-learning-assisted diagnostic workflows.
Europe Colorectal Cancer Diagnostics Market Competitive Landscape
Top-tier vendors anchor hospital capital expenditure for imaging modalities, while mid-tier molecular diagnostic specialists compete for decentralized laboratory contracts across regional networks. The vendor base stratifies between integrated platform providers with multi-year service agreements and focused assay developers seeking recurring reagent revenue. Three archetypes dominate: sequencing infrastructure anchors, imaging system incumbents with locked-in maintenance streams, and liquid biopsy platform specialists. Competitive positioning hardens through framework procurement consolidation and regulatory compliance scale advantages under IVDR and EU AI Act obligations.
Among North American-origin platform developers, Illumina, Inc. and Thermo Fisher Scientific Inc. occupy positions that exemplify contrasting strategic archetypes—sequencing infrastructure anchoring versus integrated workflow automation. Siemens Healthineers AG represents the imaging incumbent model with extensive installed base leverage. These three entities illustrate how vendor origin and platform focus shape competitive positioning within procurement environments that increasingly favor multi-year service commitments over discrete equipment transactions.
| Leading Market Players |
|---|
| Illumina, Inc. |
| Koninklijke Philips N.V. |
| Thermo Fisher Scientific Inc. |
| Quest Diagnostics Incorporated |
| F. Hoffmann-La Roche Ltd. |
| Abbott Laboratories |
| Epigenomics AG |
| Siemens Healthineers AG |
| Sysmex Corporation |
| Others |
Supply & Pricing Matrix
Next-generation sequencing reagent rental models are collapsing upfront capital barriers for European laboratories while simultaneously concentrating vendor pricing power among North American consumable suppliers. This dual shift compresses margins for regional diagnostic laboratories in Germany and the Netherlands even as it locks in recurring revenue streams for platform developers.
Pricing Analysis
Capacity additions in the United Kingdom's decentralized laboratory networks are reshaping price floors for fecal immunochemical tests, forcing incumbent vendors toward subscription-based algorithm licensing for AI-assisted polyp detection systems. Three-tier pricing structure across premium, standard, and economy levels separates integrated sequencing-to-reporting workflows from standalone assay kits and basic imaging hardware. Cost compression in economy-tier biopsy consumables is intensifying because regional health authorities in Spain and Italy unbundle maintenance contracts from equipment purchases. Diagnostic laboratories exhibit highest price sensitivity due to reagent rental dependency, while tertiary oncology centers in Germany demonstrate lowest sensitivity given locked-in multi-year service agreements.
Supply Chain Analysis
Specialized bioinformatician shortages in German and Dutch sequencing hubs are constraining throughput expansion for liquid biopsy platforms despite installed hardware capacity. Critical consumables for next-generation sequencing originate from manufacturing clusters concentrated in the United States and South Korea, with European laboratories drawing from this narrow supplier base for polymerase reagents and flow cell components. Single-source vulnerability in sequencing chemistry exposes regional networks to freight volatility and currency risk. Distribution runs through hub-and-spoke logistics models serving hospital networks across the Randstad and Greater London regions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Europe colorectal cancer diagnostics rests on software-defined diagnostic platforms capturing recurring algorithm revenue, while the EU Green Deal redirects procurement capital toward energy-efficient imaging replacements that sustain premium pricing.
For Market Incumbents: Anchor multi-year service agreements through integrated molecular-to-imaging workflows that embed Siemens Healthineers and Illumina infrastructure within German hospital procurement frameworks. Defend against liquid biopsy platform specialists by accelerating CE marking submissions under IVDR before novel biomarker assays reach market. Prioritize regulatory affairs team scale to absorb compliance cost burdens that disadvantage smaller developers. For New Entrants and Emerging Players: The mid-tier price gap between premium AI-assisted endoscopy systems and economy-grade fecal immunochemical tests opens white-space positioning for portable molecular platforms in France's satellite diagnostic facilities. Target Normandy and Brittany regional health authority licensing rounds ahead of framework procurement consolidation. Pursue pharmacy-based distribution partnerships in the United Kingdom to bypass physician referral bottlenecks. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier assay developers lacking integrated sequencing infrastructure but holding IVDR-compliant biomarker panels. Long-term viability over the projection horizon favors vendors with locked-in reagent rental models and hospital system partnerships. Monitor NICE reimbursement negotiations for blood-based screening technologies as the inflection signal for multi-cancer early detection platform viability.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | IVDR compliance accelerates market access for novel biomarker assays ahead of competitors. |
| Hospital System Partnership | Framework agreements with German oncology centers lock in multi-year sequencing consumable revenue. |
| Software Companion Development | AI-assisted polyp detection algorithms open reimbursement negotiations with NICE and ANSM. |
| Reimbursement Strategy | Private insurer pilot contracts in Switzerland establish clinical utility for blood-based screening. |
| Backward Integration | In-house reagent production reduces exposure to North American supply concentration and currency risk. |
Research Methodology
Multiple input streams — hospital procurement database analysis, laboratory information system audits, and regulatory filing review — were reconciled against primary interviews with molecular diagnostic laboratory directors, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. Secondary validation drew from EMA IVDR submission databases, NHS England procurement disclosures, ANSM device registrations, and statutory health insurer framework agreement documents. Bottom-up test volume modeling and top-down capital expenditure triangulation anchored market sizing across the analysis window.
Data-stream reconciliation enabled segmentation modeling across product type, technology modality, end-user facility category, and clinical application. CAGRs were derived from installed base expansion rates, procedure volume trajectories, and reimbursement coverage shifts throughout the forecast period. Industry-specific inputs incorporated EU AI Act compliance timelines, IVDR transition deadlines, and EU Green Deal procurement mandate implementation schedules.
Caveats apply where EMA regulatory guidance revisions, national reimbursement authority coverage determinations, or sequencing reagent supply disruptions could materially shift the outlook. Forecasts reflect assumptions regarding IVDR compliance cost absorption and AI Act conformity assessment timelines. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Cushing's Syndrome Diagnostics and Therapeutics Market
Diagnostics
Autoimmunity Immunoassay Market
Diagnostics
Europe Lung Cancer Diagnostics Market
Diagnostics
Sperm Count Test Market
Diagnostics
Glucose Tolerance Test Market
Diagnostics
South Korea in Vitro Diagnostics Market
Diagnostics
In Vitro Diagnostic (IVD) Reagent Market
Diagnostics
Germany in-Vitro Diagnostics Market
Diagnostics
Pancreatic Cyst Diagnostics Market
Diagnostics
BRIC in-Vitro Diagnostics (IVD) Market
Diagnostics
Diagnostic Testing of Stds Market
Diagnostics
United States Melanoma Diagnostics & Therapeutics Market
Diagnostics
Global Respiratory Diagnostics Market
Diagnostics
Molecular Diagnostics Market
Diagnostics
Anatomic Pathology Market
Diagnostics
Prostate Cancer Diagnostics Market