
 Global HLA Typing for Transplant Market | 2026-2036
Global HLA Typing for Transplant Market Size, Share, and Industry Trends Forecast 2026-2036
Global HLA Typing for Transplant Market Foresight
ISO 15189 medical laboratory accreditation is reorganizing competitive access in HLA typing, raising barriers for smaller diagnostic operators. Thermo Fisher Scientific leverages its end-to-end sequencing platform to anchor high-volume transplant center contracts across North America. QIAGEN sustains its position through specialized reagent portfolios that dominate PCR-SSP workflows in European tissue-typing laboratories. Illumina competes by extending its NovaSeq architecture into clinical-grade HLA applications with regulated analytical pipelines.
HLA typing encompasses molecular characterization of human leukocyte antigen gene variants to determine histocompatibility between organ donors and recipients, employing sequence-specific primer amplification, hybridization-based probe arrays, or high-throughput sequencing with resolution thresholds distinguishing allele-level from antigen-level matching. The technology segment shows next-generation sequencing capturing margin pools from Sanger methods as transplant centers demand higher-resolution haplotype data for unrelated donor matching. Reagents and kits occupy the largest product type share due to recurring consumable demand tied to pre-transplant workup volumes, while software segments are gaining traction from integrated informatics that automate allele calling against IMGT/HLA databases.
FDA oversight of HLA typing devices as Class II or Class III in vitro diagnostics shapes product development timelines and clinical validation requirements for US market entry. EMA's In Vitro Diagnostic Regulation mandates performance studies and notified body certification for European commercialization, tightening post-market surveillance obligations. WHO's Nomenclature Committee for Factors of the HLA System governs allele classification standards that underpin regulatory submissions across jurisdictions. Stakeholders must monitor convergence between national transplant registries and molecular data standards to anticipate procurement specifications.
Market Dynamics
Next-generation sequencing is compressing the technology stack in HLA typing, forcing transplant centers to retire PCR-based workflows and consolidate vendor relationships around high-throughput platforms that deliver allele-level resolution for unrelated donor matching.
Growth Catalysts
- Rising Solid Organ Transplant Volumes:Kidney and liver transplant programs in the United States, Germany, and Japan are expanding waitlist processing capacity, driving recurring demand for high-resolution HLA matching prior to surgical scheduling.
- ISO 15189 Accreditation Mandates:Medical laboratory quality standards are elevating performance thresholds for histocompatibility testing, compelling transplant centers to upgrade molecular diagnostic infrastructure.
- Donor Registry Digitization:National bone marrow donor programs are integrating molecular HLA data into searchable databases, requiring standardized allele-level genotyping to expand unrelated donor pools.
Market Restraints
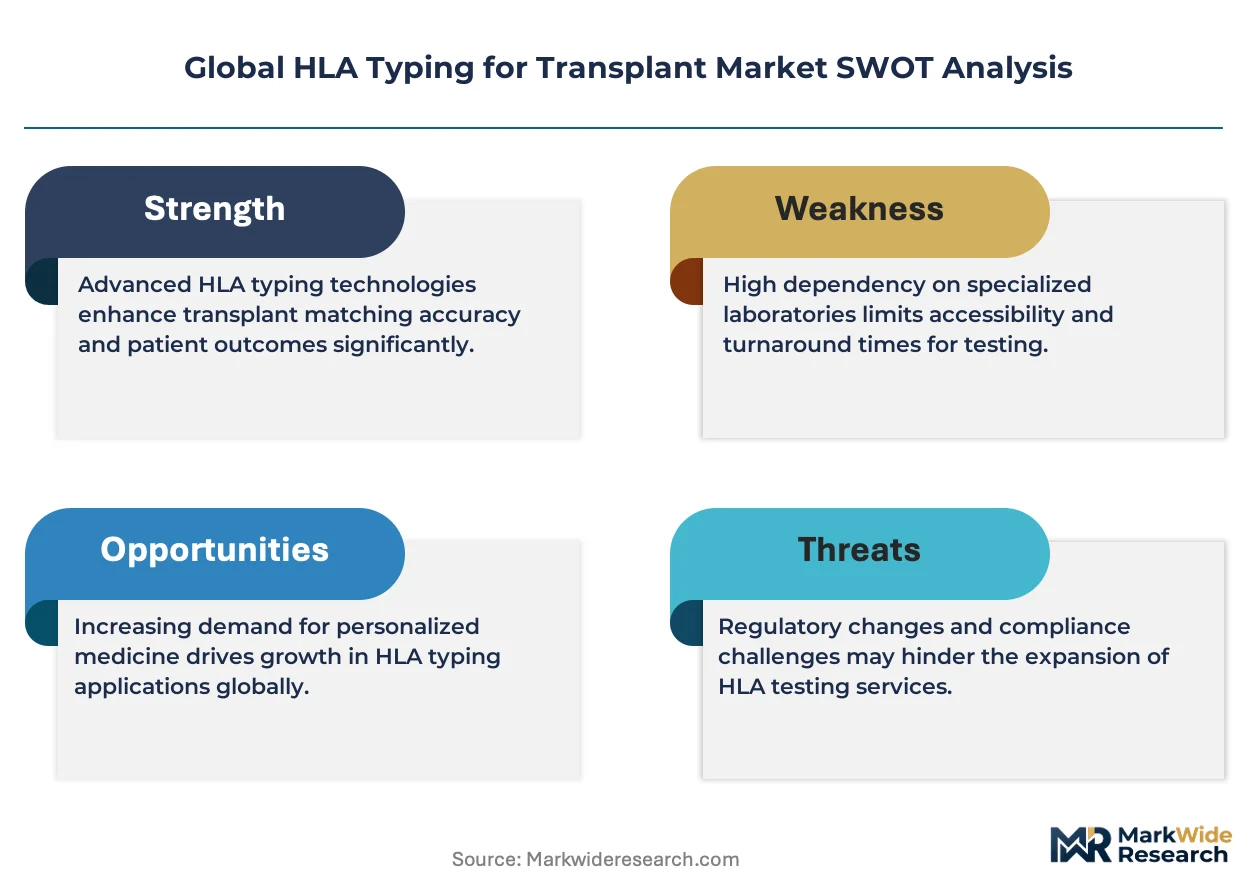
- Capital Intensity of Sequencing Infrastructure:NovaSeq and comparable platforms require substantial upfront investment and dedicated bioinformatics personnel, limiting adoption to high-volume academic medical centers.
- Reagent Supply Concentration:Specialized PCR-SSP chemistries and NGS library prep kits depend on concentrated manufacturing in Germany and the United States, exposing procurement to single-source risk.
- FDA Class II/III Device Pathways:In vitro diagnostic validation timelines for clinical-grade HLA typing extend product development cycles and delay revenue recognition for novel assay formats.
Strategic Opportunities
- India's Transplant Infrastructure Expansion:The country's national organ allocation network is modernizing tissue-typing capabilities, creating first-mover advantage for vendors establishing local laboratory partnerships.
- Automation-Convergence:Integration of liquid-handling robotics with NGS workflows reduces manual sample prep variability and enables unattended overnight processing in high-throughput reference laboratories.
- EMA IVDR Transition:The In Vitro Diagnostic Regulation's performance study requirements favor established manufacturers with notified body relationships, compressing competitive access for smaller reagent suppliers.
Industry Challenges
- Bioinformatics Talent Scarcity:Allele calling against IMGT/HLA databases requires specialized computational biology expertise that outpaces training program output in most transplant center labor markets.
- Legacy System Integration Friction:Electronic health record connectivity with laboratory information management systems stalls deployment timelines as IT departments reconcile incompatible data standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global HLA Typing for Transplant Market |
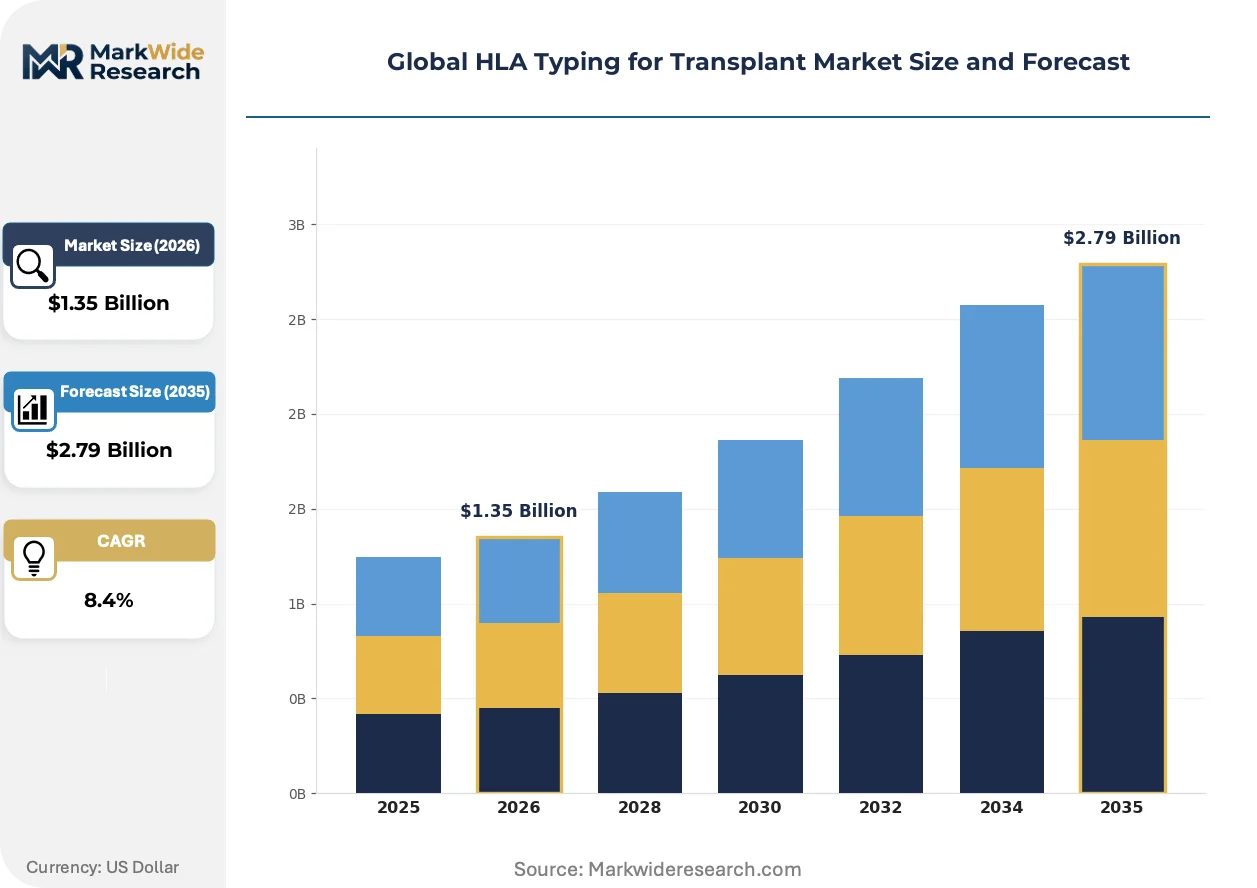
| Market Size in 2026 | $1.35 Billion |
| Market Size in 2035 | $2.79 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Kits, Sequencers, Software, Microarrays, Accessories Technology: Sanger Sequencing, Next-Generation Sequencing, PCR-SSP, PCR-SSO, Flow Cytometry, Luminex Application: Bone Marrow Transplant, Kidney Transplant, Liver Transplant, Heart Transplant, Lung Transplant, Stem Cell Transplant End User: Transplant Centers, Diagnostic Laboratories, Blood Banks, Research Institutes, Biopharmaceutical Companies |
| Companies Covered | Thermo Fisher Scientific, QIAGEN, Illumina, F. Hoffmann-La Roche, Bio-Rad Laboratories, CareDx, Becton, Dickinson and Company, Abbott Laboratories, Immucor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global HLA Typing for Transplant Market Shifts & Advancements
Sequencing depth and analytical pipeline sophistication are becoming primary competitive differentiators as transplant centers prioritize haplotype phasing accuracy over per-sample cost minimization in donor-recipient matching protocols.
Long-read sequencing platforms from Pacific Biosciences and Oxford Nanopore are supplanting short-read Illumina workflows in reference laboratories requiring complete gene coverage across HLA-A, -B, -C, -DRB1, -DQB1, and -DPB1 loci. Major histocompatibility laboratories in the United States and Japan are piloting these systems to resolve ambiguous allele combinations that confound Sanger and short-read methods. The structural consequence is a bifurcation in service tiers: high-volume centers invest in long-read infrastructure while smaller programs outsource complex cases to specialized reference networks.
The European Medicines Agency's In Vitro Diagnostic Regulation is tightening post-market surveillance obligations for HLA typing devices, mandating annual performance reporting and adverse event documentation that increases compliance staffing requirements. Manufacturers with existing notified body certifications under the prior directive gain transitional advantage while new entrants face extended timeline risk. German and French transplant registries are aligning procurement specifications with IVDR technical documentation standards, effectively pre-qualifying vendors with established European regulatory dossiers.
Transplant centers are consolidating molecular testing contracts under multi-year sole-source agreements that bundle instrumentation, reagents, and bioinformatics support into fixed annual fees. This displaces the historical model of per-test reagent purchasing and fragmented vendor relationships. The United States market exhibits the most pronounced concentration, with large health systems leveraging procurement scale to extract platform exclusivity commitments from sequencing vendors in exchange for guaranteed minimum volume thresholds.
Global HLA Typing for Transplant Market Segmentation
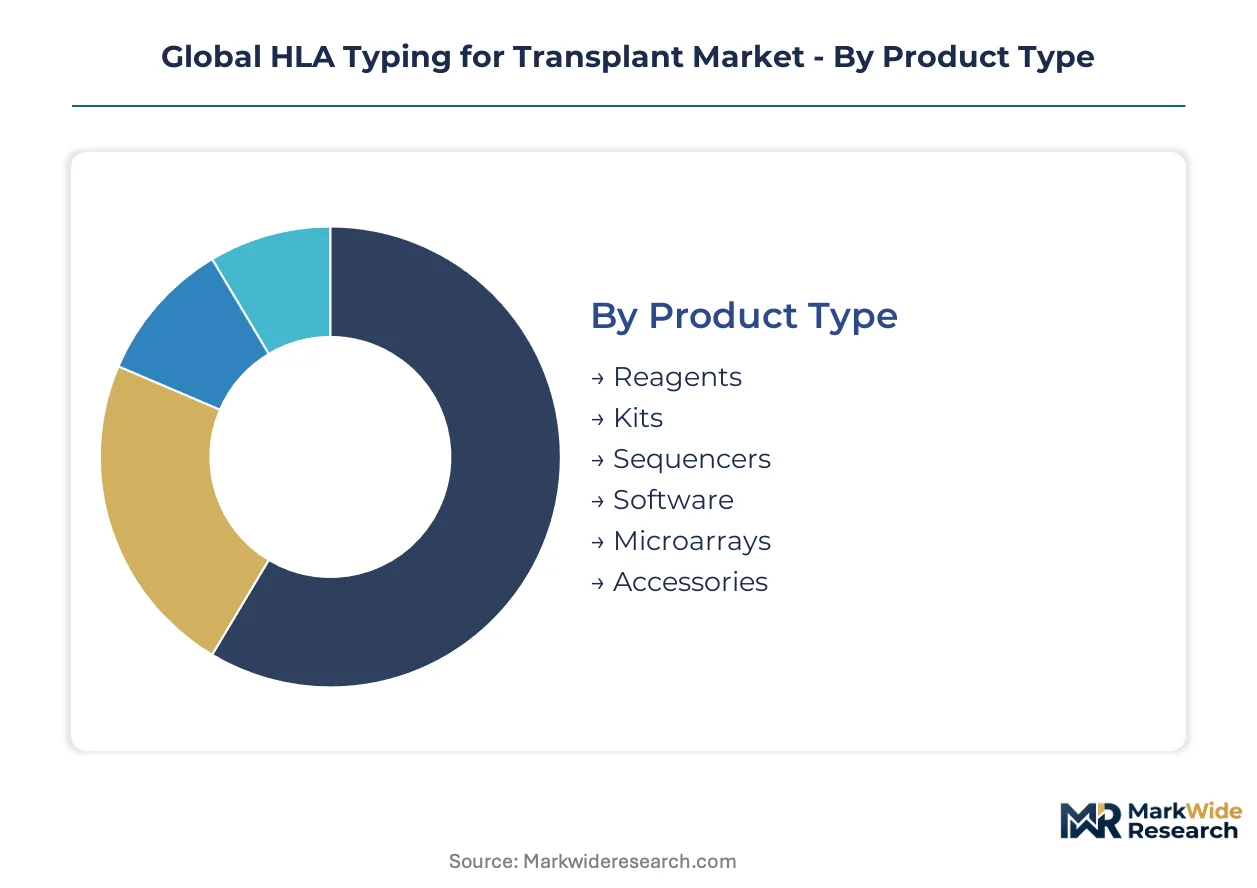
HLA typing segmentation reveals how technology substitution and procurement consolidation reshape commercial opportunity across molecular diagnostics. Product categories face divergent margin pressures while application demand concentrates in high-volume solid organ programs.
Product Type:
Sequencers and software face the strongest substitution pressure as next-generation sequencing platforms displace discrete instrumentation with integrated workflow solutions.
- Reagents:Specialized PCR-SSP chemistries, NGS library preparation kits, and hybridization probes constitute recurring consumable demand tied to pre-transplant workup volumes. Transplant centers in the United States and Germany account for the majority of procurement as these countries maintain the highest kidney and liver transplant program throughput.
- Kits:Assay bundles combine amplification primers, master mixes, and allele-specific detection reagents for standardized HLA-A, -B, -C, -DRB1 locus coverage. Japanese tissue-typing laboratories favor kit formats that minimize lot-to-lot variability under PMDA quality guidelines.
- Sequencers:Illumina NovaSeq and comparable high-throughput platforms deliver allele-level resolution for unrelated donor matching.
- Software:Allele calling algorithms automate IMGT/HLA database alignment and haplotype phasing.
- Microarrays:Solid-phase probe arrays enable medium-resolution antigen-level typing for deceased donor rapid screening.
- Accessories:Pipette tips, reaction plates, and quality control materials support laboratory workflow continuity.
Reagents anchor the volume base while software gains share at the steepest rate as transplant centers prioritize integrated informatics over discrete consumable purchasing.
Technology:
Cost tier differentiation separates capital-intensive sequencing infrastructure from lower-resolution methods serving rapid-turnaround deceased donor screening.
- Next-Generation Sequencing:High-throughput short-read and emerging long-read platforms deliver phased allele-level genotyping across HLA class I and II loci. Major academic medical centers in the United States and Japan are consolidating procurement around these systems to support unrelated donor registry matching.
- Sanger Sequencing:First-generation capillary electrophoresis methods retain niche application for confirmatory testing and single-locus resolution where NGS infrastructure is unavailable.
- PCR-SSP:Sequence-specific primer amplification provides rapid low-to-medium resolution typing for time-sensitive deceased donor compatibility assessment.
- PCR-SSO:Sequence-specific oligonucleotide probe hybridization enables medium-resolution batch screening of donor samples.
- Flow Cytometry:Cell-based crossmatch assays detect donor-specific antibodies in recipient serum.
- Luminex:Bead-based multiplex platforms quantify anti-HLA antibody profiles for sensitized patient risk stratification.
PCR-SSP retains the largest installed base in European reference laboratories while next-generation sequencing climbs the fastest as transplant centers retire legacy amplification workflows.
Application:
Volume concentration in kidney transplantation creates procurement scale advantages for vendors serving high-throughput histocompatibility laboratories.
- Kidney Transplant:Renal allograft programs generate the highest HLA typing volume due to living donor evaluation, deceased donor allocation, and post-transplant monitoring protocols. United States transplant centers process the largest waitlist volumes globally.
- Bone Marrow Transplant:Hematopoietic stem cell transplantation demands the most stringent allele-level matching for unrelated donor searches. National marrow donor programs in Germany and Japan drive standardization requirements.
- Liver Transplant:Hepatic allograft allocation requires HLA typing for sensitized recipient antibody profiling and living donor compatibility.
- Heart Transplant:Cardiac transplantation programs utilize HLA typing for virtual crossmatch prediction in highly sensitized candidates.
- Lung Transplant:Pulmonary allograft centers employ HLA antibody monitoring for chronic rejection surveillance.
- Stem Cell Transplant:Cord blood banking and haploidentical donor programs expand molecular typing demand beyond traditional bone marrow registries.
Kidney transplant anchors the volume base while bone marrow transplant gains share at the steepest rate as unrelated donor registry digitization accelerates allele-level genotyping requirements.
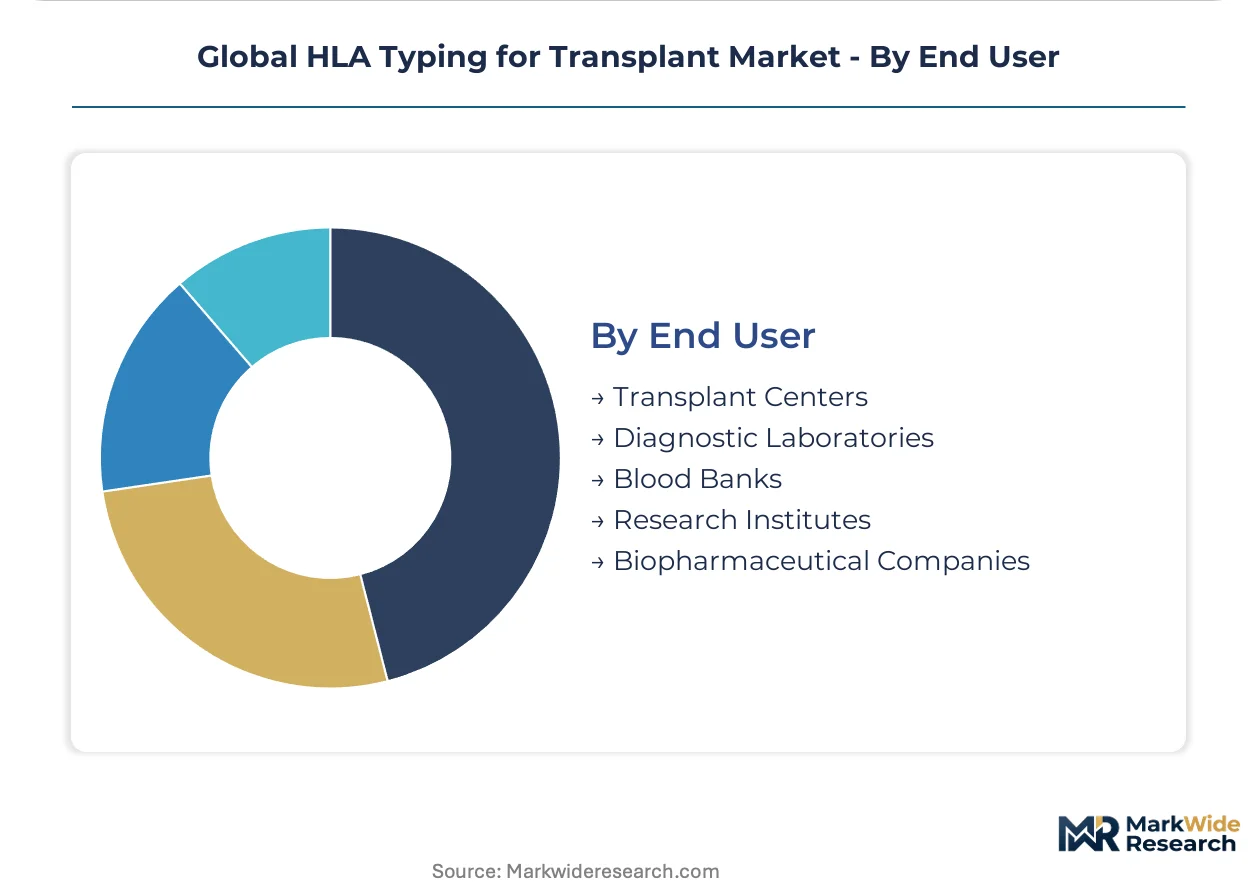
End User:
Customer type stratification reflects divergent purchasing authority between hospital-integrated transplant centers and independent reference laboratories.
- Transplant Centers:Hospital-integrated surgical programs command the largest procurement budgets for comprehensive pre- and post-transplant HLA services. United States health systems are consolidating molecular testing contracts under multi-year sole-source agreements.
- Diagnostic Laboratories:Independent reference laboratories and academic medical center pathology departments provide outsourced HLA typing for smaller transplant programs lacking in-house sequencing infrastructure.
- Blood Banks:Transfusion services perform HLA antibody screening and platelet donor HLA matching for refractory patients.
- Research Institutes:Immunogenetics research programs utilize HLA typing for disease association studies and population genetics.
- Biopharmaceutical Companies:Drug developers employ HLA typing for clinical trial stratification and pharmacogenomic biomarker qualification.
Transplant centers anchor the volume base while diagnostic laboratories gain share at the steepest rate as outsourcing consolidates complex case referral networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-volume transplant centers in the United States, Germany, and Japan concentrate procurement authority for molecular HLA typing infrastructure, with academic medical centers in these countries setting technical specifications that cascade to smaller programs through reference laboratory networks.
United States
FDA Class II/III device pathways govern clinical-grade HLA typing assay commercialization, extending validation timelines for novel sequencing formats. The United Network for Organ Sharing maintains molecular data standards that shape vendor procurement specifications across hospital-integrated transplant programs. Major histocompatibility laboratories in Boston and Houston anchor national reference testing capacity for complex unrelated donor matching.
Germany
EMA In Vitro Diagnostic Regulation mandates notified body certification and annual performance reporting for HLA typing devices sold into European transplant centers. The German Bone Marrow Donor Center drives standardization requirements for allele-level genotyping across unrelated donor registries. Industrial clusters in Munich and Heidelberg concentrate sequencing infrastructure serving Central European transplant networks.
Japan
PMDA quality guidelines favor kit formats that minimize lot-to-lot variability in high-throughput tissue-typing workflows. The Japan Marrow Donor Program integrates molecular HLA data into searchable databases, requiring standardized allele-level genotyping for unrelated donor pool expansion. Transplant centers in Tokyo and Osaka lead adoption of long-read sequencing platforms for complete gene coverage across HLA loci.
India
The national organ allocation network is modernizing tissue-typing capabilities, creating procurement opportunities for vendors establishing local laboratory partnerships. The country's national pharmaceutical regulator oversees in vitro diagnostic registration requirements for imported HLA typing reagents and instruments. Transplant infrastructure expansion concentrates in Mumbai and Delhi, where private hospital chains are building in-house molecular diagnostics capacity.
United Kingdom
NHS Blood and Transplant coordinates national procurement frameworks for histocompatibility testing services across English transplant centers. The Medicines and Healthcare products Regulatory Agency enforces compliance with IVDR technical documentation standards for commercial HLA typing assay supply. London and Manchester anchor reference laboratory networks handling complex case referrals from smaller regional transplant programs.
Global HLA Typing for Transplant Market Competitive Landscape
Player mix skews toward diversified life sciences conglomerates with end-to-end sequencing platforms and specialized diagnostic reagent suppliers with entrenched PCR workflows. Market structure exhibits tiered concentration, with three to four platform vendors capturing high-volume academic medical center contracts while regional reagent specialists serve smaller transplant programs. Dominant competitive moves include multi-year sole-source agreements bundling instrumentation and consumables, and strategic partnerships with national donor registries to embed technical standards.
Among North American platform vendors, Thermo Fisher Scientific and Illumina occupy positions exemplifying the integrated workflow archetype, while QIAGEN represents the specialized reagent portfolio approach dominant in European tissue-typing laboratories. These three companies anchor the competitive landscape through distinct strategic postures: end-to-end sequencing infrastructure, high-throughput short-read architecture, and PCR-SSP chemistry dominance respectively.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| QIAGEN |
| Illumina |
| F. Hoffmann-La Roche |
| Bio-Rad Laboratories |
| CareDx |
| Becton, Dickinson and Company |
| Abbott Laboratories |
| Immucor |
| Others |
Supply & Pricing Matrix
Ninety-day reagent inventory buffers at major transplant centers concentrate procurement leverage around sequencing platform vendors, compressing margin pools for standalone consumable suppliers while amplifying pricing power for integrated workflow providers. This inventory dynamic anchors contract structures to volume-commitment tiers that penalize spot purchasing.
Pricing Analysis
Cost-plus contracts with raw-material indexation dominate reagent supply agreements, locking transplant centers into annual price adjustments tied to polymerase and oligonucleotide commodity benchmarks. Price differentiation hinges on ISO 15189 certification tier and sequencing resolution grade, with allele-level NGS workflows commanding premium positioning against antigen-level PCR-SSP alternatives. Pricing pressure stems from health system procurement consolidation, as United States hospital networks extract volume discounts through sole-source agreements. Academic medical centers exhibit lowest price sensitivity due to grant-funded instrumentation, while community transplant programs face acute budget constraints.
Supply Chain Analysis
Inbound logistics costs from Port of Hamburg congestion and trans-Atlantic container availability constraints amplify landed costs for German-manufactured PCR-SSP chemistries. Supply concentrates in the United States, Germany, and Japan, with specialized polymerases, synthetic oligonucleotides, and sequencing flowcells drawing from concentrated chemical synthesis clusters. Single-source vulnerability pervades NGS library preparation kits, where sole qualified suppliers expose procurement to disruption. Distribution runs through direct vendor-to-laboratory contracts for high-volume centers, with regional distributors serving smaller transplant programs lacking dedicated procurement staff.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated health systems, as United States hospital network mergers concentrate procurement authority under centralized laboratory services divisions that extract platform exclusivity commitments.
For Market Incumbents: Consolidate reagent supply relationships through backward integration into oligonucleotide synthesis, securing captive capacity against specialty chemical supply shocks. Lock in transplant center loyalty by embedding bioinformatics support teams within customer laboratories, creating switching costs that resist competitive displacement from emerging long-read sequencing entrants. For New Entrants and Emerging Players: FDA breakthrough device designation fast-track offers regulatory pathway acceleration for novel HLA typing assays, enabling compressed validation timelines against established PCR-SSP workflows. Target India's transplant infrastructure expansion as the most penetrable geography, where local laboratory partnerships circumvent import registration barriers. Lead with automation-convergence value propositions that reduce manual sample prep labor, addressing acute bioinformatics talent scarcity. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue infrastructure play because transplant volume growth and registry digitization sustain consumable demand regardless of sequencing technology substitution waves. Prioritize acquisition targets with notified body certifications under EMA IVDR, where regulatory dossiers constitute scarce assets that compress competitive access. Watch for long-read sequencing adoption inflection in Japanese reference laboratories as signal of platform transition timing.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EMA IVDR technical documentation accelerates European commercialization for notified body-certified manufacturers. |
| Hospital System Partnership | Sole-source agreements with United States health systems lock in multi-year volume commitments against competitive bidding. |
| Software Companion Development | Integrated allele calling algorithms automate IMGT/HLA database alignment, reducing customer bioinformatics staffing requirements. |
| Reimbursement Strategy | Molecular diagnostic coding alignment with CMS Medicare coverage expands addressable market for clinical-grade HLA testing. |
| Regulatory Approval Pathway | FDA Class II 510(k) clearance for NGS-based HLA typing devices enables United States market entry against legacy PCR methods. |
Research Methodology
Desk research of FDA 510(k) filings, EMA IVDR technical documentation, and IMGT/HLA database release records preceded structured interviews with histocompatibility laboratory directors, transplant surgeon procurement committees, and sequencing platform product managers. Primary fieldwork across United States, German, and Japanese transplant centers validated secondary estimates of reagent consumption patterns and instrument placement cycles. Bottom-up modeling of transplant center throughput and top-down triangulation against national registry digitization budgets converged on volume projections.
Variance decomposition across technology substitution rates, reimbursement policy shifts, and regulatory timeline uncertainty shaped scenario-weighted outputs over the projection horizon. Segmentation modeling captured product type, technology platform, transplant application, and end-user facility scale dimensions. CAGRs derived from transplant volume growth elasticities and technology penetration S-curves, with allele-level genotyping adoption curves calibrated against unrelated donor registry expansion targets.
Decision-makers should treat outputs as directional under base assumptions of sustained ISO 15189 accreditation mandates and stable Medicare molecular diagnostic reimbursement; material deviation would warrant model refresh. Forecasts embed assumptions regarding NGS platform consolidation timelines and PCR-SSP retirement curves specific to national regulatory environments. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Diagnostics
Carrier Screening Market
Medical Diagnostics
Fluid Biopsy Market
Medical Diagnostics
Dosimetry Market
Medical Diagnostics
North America Flow Cytometry Market
Medical Diagnostics
Global Circulating Tumor Cells Market
Medical Diagnostics
In-Situ Hybridization (ISH) Market
Medical Diagnostics
Electroretinogram Market
Medical Diagnostics
Liver Biopsy Market
Medical Diagnostics
Europe Circulating Tumor Cells (CTC) Liquid Biopsy Market
Medical Diagnostics
Middle East and Africa Circulating Tumor Cells (CTC) Liquid Biopsy Market
Medical Diagnostics
US Molecular Diagnostics Market
Medical Diagnostics
Asia-Pacific Single Cell Analysis Market
Medical Diagnostics
Global ELISA Analyzer Market
Medical Diagnostics
Medical Isotope Market
Medical Diagnostics
Global Hydrophobic Interaction Chromatography Market
Medical Diagnostics
Rapid Medical Diagnostic Kits Market