
 Asia-Pacific Single Cell Analysis Market | 2026-2036
Asia-Pacific Single Cell Analysis Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Single Cell Analysis Market Insights
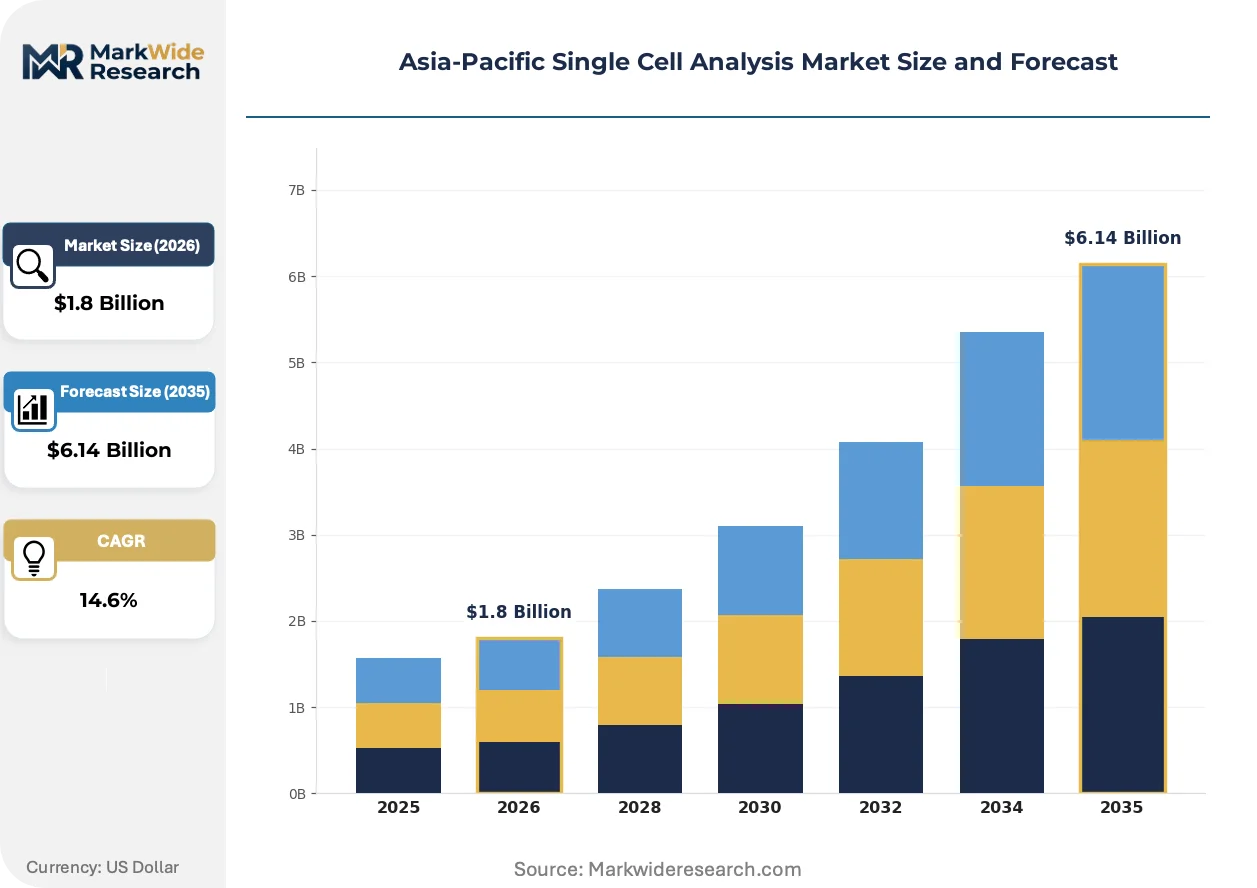
Chinese reagent manufacturing capacity is recalibrating as domestic biotech clusters scale single-cell consumables output. Bio-Rad Laboratories leverages its flow cytometry installed base to sustain service revenue across East Asian academic centers. Thermo Fisher Scientific anchors regional distribution through its Shanghai innovation campus, while 10x Genomics competes on Chromium platform density in Singapore and Australian genomics hubs.
Single cell analysis isolates individual cells from heterogeneous populations for genomic, transcriptomic, or proteomic profiling using microfluidic partitioning, droplet encapsulation, or fluorescence-activated sorting with resolution below one picogram of nucleic acid material. The technique enables drug target validation, immune repertoire mapping, and clonal evolution tracking in precision medicine pipelines. Flow cytometry retains the largest installed base across Asia-Pacific academic hospitals, while next-generation sequencing-linked microfluidics captures the fastest expansion as pharmaceutical companies integrate single-cell RNA-seq into target discovery workflows. Oncology dominates application demand, though neuroscience is gaining share in Japan and South Korea where stem cell research funding has deepened.
Japan's PMDA governs cell-processing facility standards for clinical single-cell diagnostics, while China's NMPA regulates in vitro diagnostic reagent registration including circulating tumor cell isolation kits. Australia's TGA oversees laboratory-developed test frameworks that affect clinical adoption timelines for mass cytometry panels. Stakeholders must monitor harmonization gaps between national medical device classifications and evolving single-cell platform software as a medical device determinations across the region.
Market Dynamics
Pharmaceutical pipelines in China and Japan are consolidating single-cell workflows into immuno-oncology target discovery, compressing platform procurement cycles and reconfiguring reagent supply relationships across East Asian biotech clusters.
Growth Catalysts
- Japan's PMDA regenerative medicine pathways:Streamlined cell-processing facility approvals accelerate clinical adoption of single-cell diagnostics in academic medical centers.
- Shanghai-Shenzhen biotech cluster concentration:Domestic consumables manufacturing scales to replace imported reagent volumes in high-throughput genomics facilities.
- Microfluidic partitioning density gains:Droplet encapsulation throughput improvements enable pharmaceutical companies to map immune repertoires at population scale.
Market Restraints
- Fluorophore and oligonucleotide import dependency:Reagent input costs fluctuate with currency exposure and cross-border logistics bottlenecks.
- Flow cytometry installed base lock-in:Academic hospitals defer next-generation sequencing-linked microfluidics upgrades due to capital recovery cycles on existing fluorescence-activated sorting infrastructure.
- NMPA in vitro diagnostic registration timelines:Circulating tumor cell isolation kit approvals extend commercialization lead times for platform developers.
Strategic Opportunities
- South Korea stem cell research funding:Government neuroscience initiatives create demand for clonal evolution tracking in precision medicine pipelines.
- Singapore-Australia genomics hub density:Chromium platform competition intensifies, opening service revenue models for regional distribution partners.
- TGA laboratory-developed test frameworks:Mass cytometry panel clinical adoption accelerates as regulatory clarity improves for diagnostic laboratories.
Industry Challenges
- Bioinformatics pipeline integration:Pharmaceutical companies face workflow friction connecting single-cell RNA-seq outputs to legacy target validation databases.
- Software-as-medical-device classification ambiguity:National medical device determinations vary across PMDA, NMPA, and TGA jurisdictions, complicating multi-country platform launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Single Cell Analysis Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flow Cytometry, Microfluidics, Mass Cytometry, PCR Application: Oncology, Immunology, Stem Cell Research, Neuroscience End User: Academic Research, Pharmaceutical Companies, Biotechnology Firms, Clinical Laboratories Technology: Next-Generation Sequencing, Imaging, Spectrometry, Single-Cell RT-PCR |
| Companies Covered | Bio-Rad Laboratories, Merck KGaA, 10x Genomics, Thermo Fisher Scientific, Standard BioTools, Agilent Technologies, Illumina, Beckman Coulter, Becton, Dickinson and Company, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Single Cell Analysis Market Trends and Innovations
Platform architectures are fragmenting into componentized subsystems, allowing end-users to mix sequencing hardware, microfluidic cartridges, and analysis software from competing suppliers rather than accepting bundled configurations.
Combinatorial indexing for single-cell transcriptomics is modularizing. Academic consortia in Australia and Singapore are adopting split-pool ligation protocols to bypass droplet microfluidics entirely. The approach compresses per-cell library preparation costs and enables researchers to repurpose existing Illumina sequencers without Chromium platform commitments.
Japan's PMDA revised its regenerative medicine safety and efficacy guidelines to incorporate real-world evidence from single-cell monitoring. Cell-processing facilities must now demonstrate clonal purity thresholds before therapeutic release. Oncology pipeline sponsors in Osaka and Tokyo are reconfiguring manufacturing quality systems to capture longitudinal single-cell data.
Consolidated procurement by multi-site hospital networks is displacing principal investigator-driven instrument purchases. China's municipal health bureaus in Shanghai and Shenzhen now negotiate enterprise licenses for single-cell analysis suites across affiliated academic hospitals. This concentrates vendor negotiation leverage and accelerates standardization of consumables specifications.
Asia-Pacific Single Cell Analysis Market Segmentation
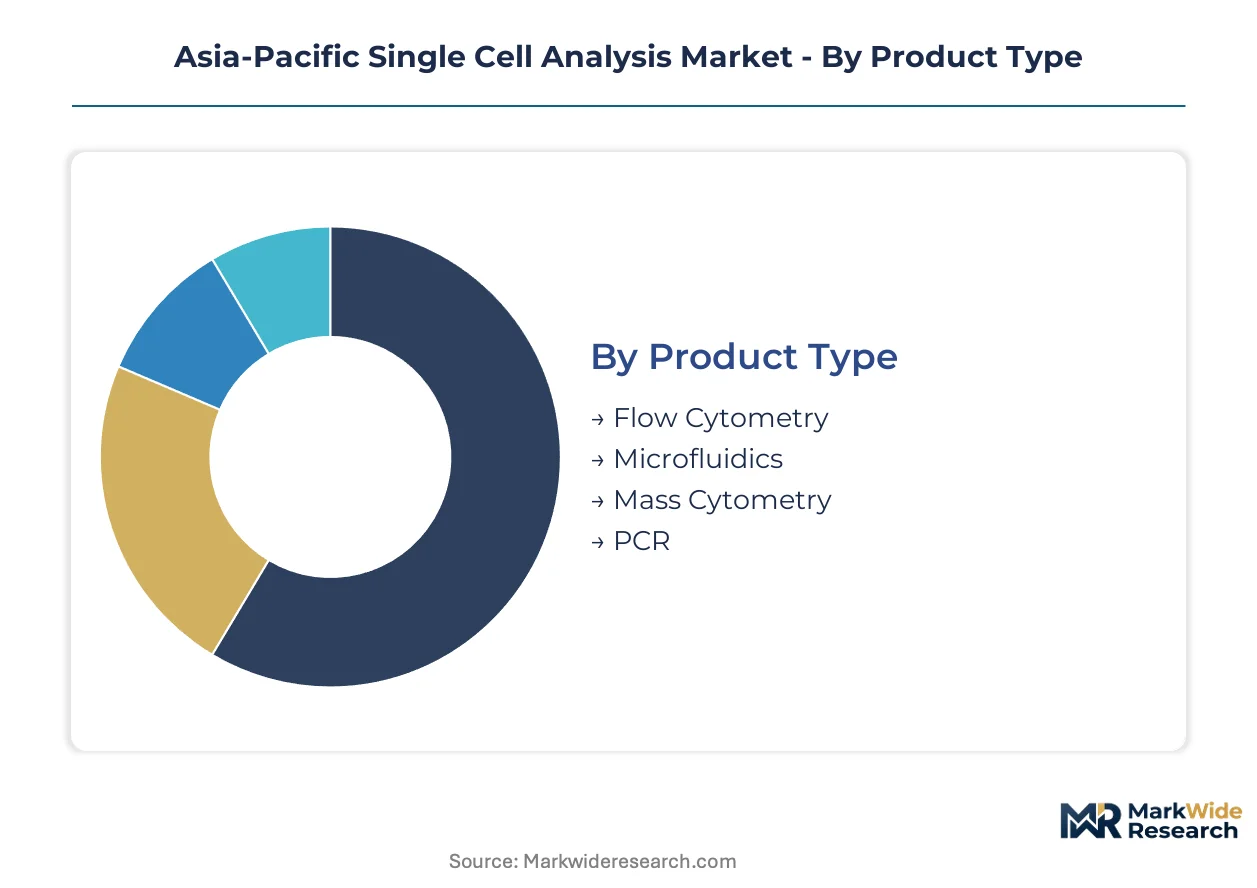
Single-cell analysis platforms require differentiated regulatory pathways across Asia-Pacific, with PMDA cell-processing facility standards governing clinical applications in Japan while NMPA in vitro diagnostic reagent registration shapes commercial timelines in China. Segmentation reveals how certification burdens concentrate in clinical end-uses versus research-only workflows, driving vendor portfolio specialization across the region's heterogeneous approval landscapes.
Product Type:
Flow cytometry platforms carry lighter PMDA and NMPA burdens for research use, while mass cytometry and clinical microfluidics face extended validation requirements for diagnostic deployment in hospital laboratories.
- Flow Cytometry:Fluorescence-activated sorting systems dominate installed bases across academic medical centers in Japan and Australia, with service revenue sustaining vendor relationships as capital recovery cycles delay replacement purchases. Shanghai's municipal health bureaus negotiate enterprise licenses for hospital networks, compressing procurement timelines for standardized flow cytometry panels.
- Microfluidics:Droplet encapsulation systems enable pharmaceutical companies in China and Japan to map immune repertoires at population scale, though NMPA in vitro diagnostic registration extends commercialization lead times for circulating tumor cell isolation applications. Chromium platform competition intensifies in Singapore and Australian genomics hubs.
- Mass Cytometry:Metal-isotope tagging systems face TGA laboratory-developed test framework scrutiny in Australia, with clinical adoption accelerating as regulatory clarity improves for diagnostic laboratories.
- PCR:Single-cell RT-PCR workflows leverage existing thermal cycler infrastructure across East Asian biotech clusters, minimizing capital barriers for entry-level single-cell transcriptomics.
Flow cytometry sits at the top of the volume ranking, with microfluidics climbing the fastest as pharmaceutical pipelines consolidate single-cell workflows into immuno-oncology target discovery.
Application:
Oncology applications command premium pricing tiers due to companion diagnostic pathways, while neuroscience and stem cell research segments operate under lighter regulatory frameworks with faster procurement cycles.
- Oncology:Immuno-oncology pipelines in Osaka and Tokyo drive demand for clonal purity threshold monitoring, with PMDA revised regenerative medicine guidelines now incorporating real-world evidence from single-cell data. Cell-processing facilities must demonstrate longitudinal tracking capabilities before therapeutic release.
- Immunology:Immune repertoire mapping concentrates in pharmaceutical companies across Shanghai-Shenzhen biotech clusters, with microfluidic partitioning density gains enabling population-scale analysis. Domestic consumables manufacturing scales to replace imported reagent volumes.
- Stem Cell Research:South Korea government neuroscience initiatives create demand for clonal evolution tracking, with funding deepening in Seoul and Daejeon research institutes for precision medicine pipeline development.
- Neuroscience:Academic consortia in Australia and Singapore adopt split-pool ligation protocols to bypass droplet microfluidics, compressing per-cell library preparation costs for brain cell atlas projects.
Oncology commands the dominant revenue share, with neuroscience gaining share fastest as stem cell research funding deepens in Japan and South Korea.
End User:
Academic research centers purchase through principal investigator-driven channels, while pharmaceutical companies and clinical laboratories shift toward consolidated procurement with enterprise licensing requirements.
- Academic Research:University hospitals in Tokyo and Sydney retain flow cytometry installed base lock-in, deferring next-generation sequencing-linked microfluidics upgrades due to capital recovery cycles on existing fluorescence-activated sorting infrastructure.
- Pharmaceutical Companies:Immuno-oncology sponsors in China and Japan compress platform procurement cycles, reconfiguring reagent supply relationships across East Asian biotech clusters as single-cell RNA-seq integrates into target discovery workflows.
- Biotechnology Firms:Shanghai and Shenzhen domestic biotech clusters scale single-cell consumables output, recalibrating reagent manufacturing capacity as import substitution accelerates for fluorophore and oligonucleotide inputs.
- Clinical Laboratories:Australia's TGA oversees laboratory-developed test frameworks affecting mass cytometry panel adoption timelines, with diagnostic laboratories awaiting regulatory clarity before clinical deployment.
Academic research maintains the largest installed base, with pharmaceutical companies expanding most quickly as single-cell workflows consolidate into immuno-oncology pipelines.
Technology:
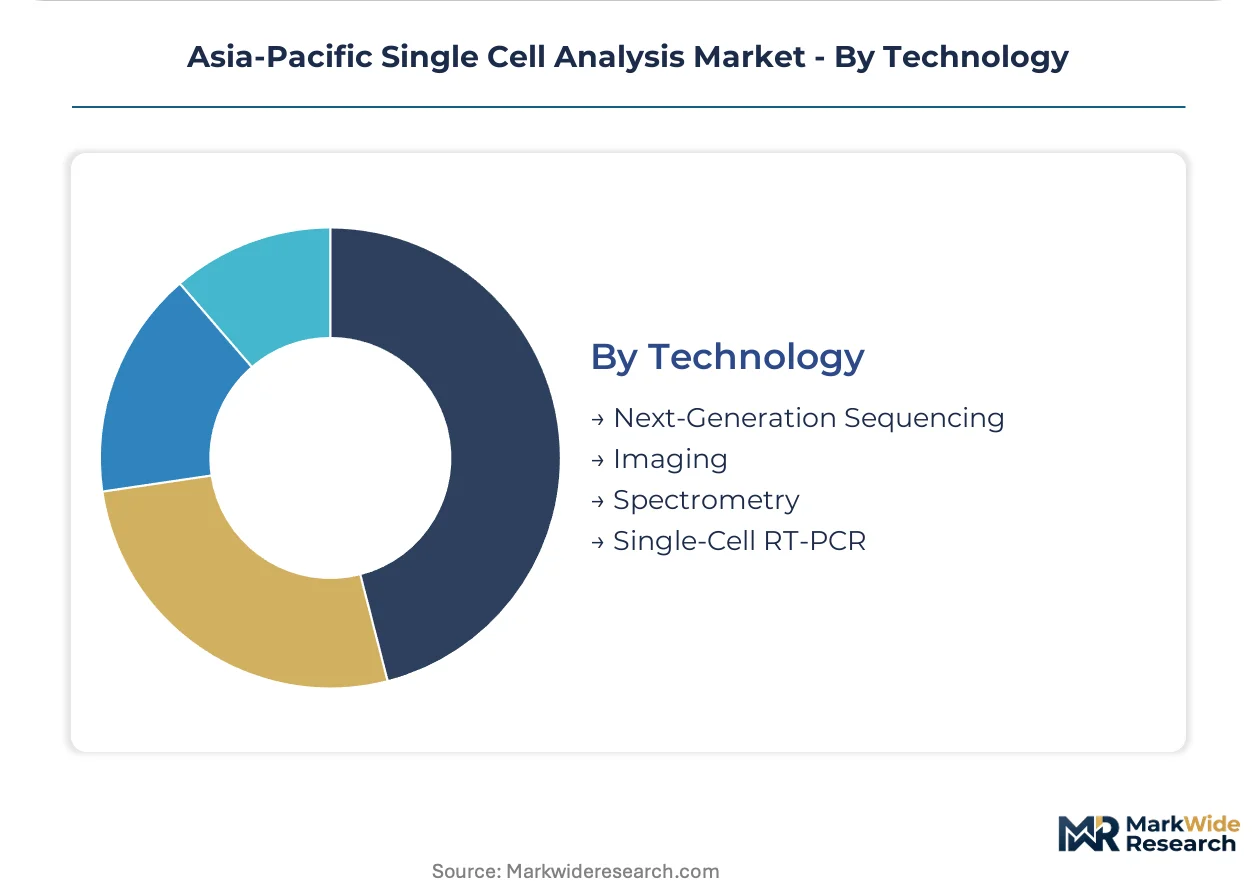
Next-generation sequencing-linked platforms face bioinformatics pipeline integration challenges, while imaging and spectrometry technologies offer more direct connectivity to legacy target validation databases.
- Next-Generation Sequencing:Microfluidic partitioning density gains enable droplet encapsulation throughput improvements, though pharmaceutical companies face workflow friction connecting single-cell RNA-seq outputs to legacy target validation databases.
- Imaging:High-content screening systems bypass software-as-medical-device classification ambiguity, operating under clearer PMDA and NMPA medical device determinations than analysis software platforms.
- Spectrometry:Mass cytometry metal-isotope detection requires specialized operator training, limiting deployment to reference laboratories in Melbourne and Singapore with established cytometry expertise.
- Single-Cell RT-PCR:Established thermal cycler protocols minimize regulatory revalidation burdens, enabling faster deployment in China's municipal hospital networks with standardized procurement specifications.
Next-generation sequencing leads technology investment, with imaging systems gaining traction fastest as regulatory clarity improves for hardware-centric platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping single-cell analysis deployment across Asia-Pacific, with platform developers migrating clinical validation work toward jurisdictions offering clearer cell-processing facility standards and faster regenerative medicine approval pathways.
China
Shanghai and Shenzhen biotech clusters are scaling domestic consumables manufacturing to replace imported fluorophore and oligonucleotide volumes. NMPA in vitro diagnostic reagent registration governs circulating tumor cell isolation kit approvals, extending commercialization timelines for foreign platform developers. Municipal health bureaus now negotiate enterprise licenses for single-cell analysis suites across affiliated academic hospitals.
Japan
Osaka and Tokyo oncology pipeline sponsors drive demand for clonal purity threshold monitoring in cell-processing facilities. PMDA streamlined regenerative medicine safety and efficacy guidelines to incorporate real-world evidence from single-cell data, accelerating platform adoption in academic medical centers. Manufacturing quality systems are reconfiguring to capture longitudinal single-cell tracking before therapeutic release.
South Korea
Seoul and Daejeon research institutes are deepening stem cell research funding for precision medicine pipeline development. Government neuroscience initiatives create demand for clonal evolution tracking capabilities. MFDS oversight of cell therapy manufacturing standards shapes platform procurement specifications for domestic biotechnology firms.
Australia
Melbourne and Sydney genomics hubs are adopting split-pool ligation protocols to bypass droplet microfluidics entirely, compressing per-cell library preparation costs. TGA laboratory-developed test frameworks affect mass cytometry panel clinical adoption timelines for diagnostic laboratories. Academic consortia are repurposing existing Illumina sequencers without Chromium platform commitments.
Singapore
Biomedical research institutes are intensifying Chromium platform competition, opening service revenue models for regional distribution partners. The city-state's genomics hub density attracts platform developers seeking Southeast Asian market access. Enterprise procurement patterns favor standardized consumables specifications across multi-site research networks.
Asia-Pacific Single Cell Analysis Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue microfluidic component specialization and software-as-service models. The market structure reflects a bifurcation between flow cytometry incumbents with deep installed bases and sequencing-linked platform developers capturing pharmaceutical workflow integration. Three archetypes dominate: integrated system vendors, consumables-focused specialists, and regional service providers. Competitive moves concentrate on strategic partnerships for bioinformatics pipeline integration and geographic expansion through distribution licensing.
Within the integrated system tier, Thermo Fisher Scientific anchors regional distribution through its Shanghai innovation campus, while 10x Genomics exemplifies the microfluidic density play in Singapore and Australian genomics hubs. Bio-Rad Laboratories occupies a position sustaining service revenue across East Asian academic centers. These three entities represent contrasting approaches to market access—direct infrastructure investment, platform specialization, and installed base leverage.
| Leading Market Players |
|---|
| Bio-Rad Laboratories |
| Merck KGaA |
| 10x Genomics |
| Thermo Fisher Scientific |
| Standard BioTools |
| Agilent Technologies |
| Illumina |
| Beckman Coulter |
| Becton, Dickinson and Company |
| Others |
Pricing and Supply Chain Analysis
Fluorophore and oligonucleotide import costs cascade through three distinct pricing tiers as reagent inputs move from cross-border logistics into Shanghai-Shenzhen biotech cluster manufacturing. Currency exposure and customs bottlenecks compress margins at the economy tier while premium microfluidic platforms absorb volatility through bundled service contracts.
Pricing Analysis
Distributor margins on imported consumables widen the gap between research-use and clinical-grade reagent pricing. Three-tier pricing structure across premium, standard, and economy levels reflects NMPA certification status and volume scale. Cost compression in the economy tier intensifies because domestic manufacturers in Shenzhen undercut imported fluorophore pricing. Academic research centers exhibit highest price sensitivity, while pharmaceutical companies in Osaka and Tokyo prioritize throughput reliability over per-cell cost.
Supply Chain Analysis
China's domestic-content mandates for cell-processing facility materials are reshaping sourcing patterns for PMDA-regulated therapeutic manufacturers. Supply concentrates in China for microfluidic cartridge fabrication, Japan for precision optics components, and South Korea for electronic subsystems. Raw material dependencies span photoresists for chip fabrication, rare-earth elements for mass cytometry metal tags, and synthetic oligonucleotides for barcoding chemistry. Single-source vulnerability in photoresist supply threatens platform production timelines. Distribution runs through regional innovation campuses in Shanghai and Singapore with direct-to-laboratory fulfillment for high-throughput genomics facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory-arbitrage opportunities emerge between Japan's PMDA streamlined regenerative medicine pathways and China's extended NMPA in vitro diagnostic timelines, creating cost differentials for clinical validation work.
For Market Incumbents: Deploy installed-base service contracts to lock in academic hospital networks before municipal health bureaus consolidate procurement. Capture reagent supply relationships across East Asian biotech clusters as domestic manufacturing scales. Counter emerging entrant pressure from componentized microfluidic specialists by certifying Chromium-compatible consumables under NMPA quality system requirements. For New Entrants and Emerging Players: Premium-to-economy pricing gaps in circulating tumor cell isolation kits open white-space in Australia's TGA-regulated diagnostic laboratories. Target South Korea's government-funded neuroscience initiatives for clonal evolution tracking platforms. Penetrate Singapore's genomics hub density through service-revenue partnerships with regional distributors lacking in-house bioinformatics capabilities. For Investors and Strategic Acquirers: Consolidation pressure builds where software-as-medical-device classification ambiguity fragments multi-country platform launches. Long-term viability favors consumables-focused specialists with captive fluorophore manufacturing and NMPA registration expertise. Signal to watch: PMDA harmonization with TGA laboratory-developed test frameworks accelerating cross-regional clinical adoption timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Harmonization Investment | Aligns PMDA cell-processing standards with TGA frameworks to compress multi-country launch cycles. |
| Domestic Reagent Manufacturing Scale-Up | Captures Shanghai-Shenzhen biotech cluster demand as import substitution accelerates for oligonucleotide inputs. |
| Bioinformatics Pipeline Integration | Connects single-cell RNA-seq outputs to pharmaceutical legacy target validation databases in Osaka and Tokyo. |
| Enterprise Licensing Partnership | Secures municipal health bureau procurement consolidation across affiliated academic hospital networks. |
| Split-Pool Ligation Protocol Adoption | Enables Australian and Singapore consortia to bypass droplet microfluidics using existing Illumina infrastructure. |
Research Methodology
Direct dialogue with platform development executives, regulatory affairs specialists at PMDA and NMPA, hospital procurement managers in Shanghai and Sydney, and bioinformatics pipeline architects grounded qualitative findings. Secondary validation drew from PMDA regenerative medicine guideline revisions, NMPA in vitro diagnostic registration databases, TGA laboratory-developed test framework determinations, and MFDS cell therapy manufacturing standards. Bottom-up triangulation across reagent manufacturing capacity and top-down validation against pharmaceutical pipeline expenditure patterns reinforced segmentation outputs.
Market size and growth trajectory outputs reflect modeling across product type, application, end user, and technology dimensions over the projection horizon. CAGRs were derived from pharmaceutical single-cell workflow integration rates and academic hospital capital equipment replacement cycles. Industry-specific inputs included microfluidic partitioning density improvement curves and stem cell research funding allocations from Seoul and Daejeon government neuroscience initiatives.
The model assumes a particular technology adoption path; alternative pathways for combinatorial indexing and split-pool ligation protocols would alter the outlook for droplet microfluidics platform demand. Forecasts reflect assumptions around PMDA-NMPA regulatory harmonization progress and domestic-content mandate enforcement intensity in Chinese biotech clusters. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Diagnostics
AI in Medical Diagnostics Market
Medical Diagnostics
Stem Cell Characterization Kits Market
Medical Diagnostics
Electroretinogram Market
Medical Diagnostics
Protein Sequencing Market
Medical Diagnostics
Global Hydrophobic Interaction Chromatography Market
Medical Diagnostics
MUC1 Antibody Market
Medical Diagnostics
Rapid Medical Diagnostic Kits Market
Medical Diagnostics
Carrier Screening Market
Medical Diagnostics
Dosimetry Market
Medical Diagnostics
Flow Cytometry Market
Medical Diagnostics
Middle East and Africa Circulating Tumor Cells (CTC) Liquid Biopsy Market
Medical Diagnostics
Global Histology and Cytology Market
Medical Diagnostics
North America Flow Cytometry Market
Medical Diagnostics
X Ray Crystallography Market
Medical Diagnostics
Global Circulating Tumor Cells Market
Medical Diagnostics
Fluid Biopsy Market