
 Blood Platelet Market | 2026-2036
Blood Platelet Market Size, Share, and Industry Trends Forecast 2026-2036
Blood Platelet Market Analysis
AABB accreditation is bifurcating the competitive landscape between certified collection networks and regional operators lacking scale. America's Blood Centers leverages its distributed center model to sustain geographic coverage across multiple states. Terumo BCT anchors the equipment supply tier through automated collection systems that dominate apheresis workflows. The American National Red Cross differentiates via integrated testing and distribution infrastructure that controls last-mile delivery to hospitals.
Blood platelets are anucleated cytoplasmic fragments derived from megakaryocytes, measuring 2-3 micrometers in diameter and containing alpha granules rich in growth factors; they function physiologically in hemostasis and are harvested clinically through apheresis or whole blood processing for transfusion therapy. Platelet concentrate leads product type revenue due to established reimbursement in surgical settings, while platelet-rich plasma shows the fastest expansion in orthopedic and dermatology outpatient clinics where regenerative protocols gain traction. Hospitals command the dominant end user share through emergency transfusion dependency, though blood banks are consolidating processing capacity to capture margin pools from pathogen-reduction service fees.
FDA blood banking regulations and AABB standards govern collection, testing, and storage protocols in the United States, while EMA and the EU Blood Directive establish equivalent frameworks across Europe, with both jurisdictions tightening pathogen reduction mandates that reshape supplier qualification requirements. The EU Medical Device Regulation adds device-level compliance burdens for apheresis equipment and additive solution manufacturers. Stakeholders must monitor evolving reimbursement for pathogen-reduced versus conventional platelet units as payers recalibrate cost-effectiveness thresholds.
Market Dynamics
Pathogen reduction mandates from FDA and EMA are restructuring collection economics, forcing blood centers to absorb technology upgrade costs while hospitals demand equivalently priced units regardless of processing method.
Growth Catalysts
- EMA Blood Directive amendments:European regulators now require nucleic acid testing for emerging pathogens, expanding the addressable market for inactivation technologies across collection networks.
- Apheresis automation:Closed-system collection platforms reduce contamination risk and extend shelf life, driving hospital preference for single-donor units in cardiac surgery suites.
- Japan's aging demographic:Chronic myeloproliferative disorders in patients over 75 sustain prophylactic platelet demand in Tokyo-Osaka hospital corridors.
Market Restraints
- Plasma-derived additive solutions:Volatility in albumin and plasma fractionation feedstock costs compresses margins for platelet concentrate manufacturers.
- US collection network concentration:Three national blood center alliances control over sixty percent of apheresis capacity, creating supply vulnerability during regional disasters.
- Five-day storage limitation:Bacterial detection protocols and temperature excursion risks prevent inventory buffer accumulation.
Strategic Opportunities
- Germany's outpatient orthopedic expansion:Platelet-rich plasma protocols for tendon repair and osteoarthritis are migrating from hospital settings to ambulatory surgical centers.
- Pathogen-reduced premium tiering:Payers in Switzerland and the Netherlands are piloting reimbursement differentials that reward bacterially inactivated units.
- Cold-chain drone delivery:Last-mile logistics innovation enables same-day delivery to rural trauma centers previously served by overnight courier.
Industry Challenges
- Apheresis technician certification:Six-month training pipelines and examination backlogs constrain collection capacity expansion.
- Legacy LIS integration:Hospital blood bank information systems require costly middleware to interface with pathogen reduction device data streams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blood Platelet Market |
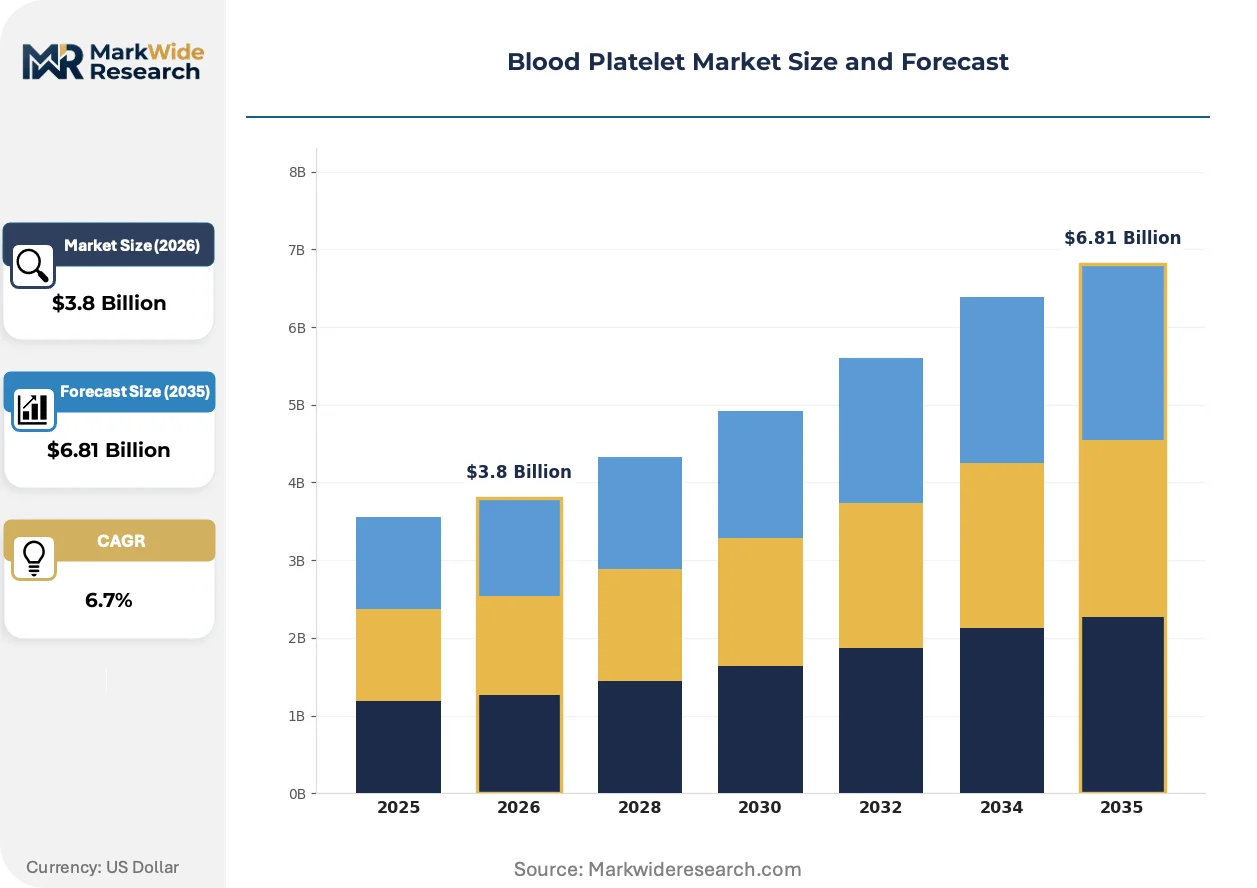
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Platelet-Rich Plasma, Platelet Concentrate, Whole Blood, Platelet Gel End User: Hospitals, Blood Banks, Laboratories, Research Institutions Therapy Area: Orthopedics, Dermatology, Cardiology, Dentistry Delivery Mode: Injectable, Topical, Infusion, Others |
| Companies Covered | America's Blood Centers, American National Red Cross, Japanese Red Cross Society, European Blood Alliance, OneBlood, Canadian Blood Services, French Red Cross, Australian Red Cross, Terumo BCT, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blood Platelet Market Emerging Trajectories
Automation and biosafety protocols are converging to redefine operational standards across collection, processing, and distribution workflows in blood banking.
Interception pathogen reduction technology using amotosalen and ultraviolet light is supplanting conventional gamma irradiation for platelet bacterial and viral inactivation. Major academic medical centers in Boston and Philadelphia have completed fleet conversions, compressing the market for traditional irradiation service providers. The shift enables seven-day storage extensions that reshape hospital inventory economics.
FDA's 2019 bacterial risk control guidance and subsequent draft recommendations on large-volume delayed sampling are tightening collection facility compliance burdens. Blood centers must now implement enhanced quality systems or face consent decree exposure. The regulatory friction falls hardest on mid-sized regional operators lacking dedicated regulatory affairs staff.
Hospital blood management committees are consolidating supplier relationships to capture volume-based contracting leverage previously exercised at individual facility level. Multi-hospital health systems in California and Texas now mandate sole-source agreements for apheresis platelets, displacing the fragmented purchasing patterns of the past decade. The concentration effect is most pronounced in integrated delivery networks controlling trauma designation.
Blood Platelet Market Segmentation
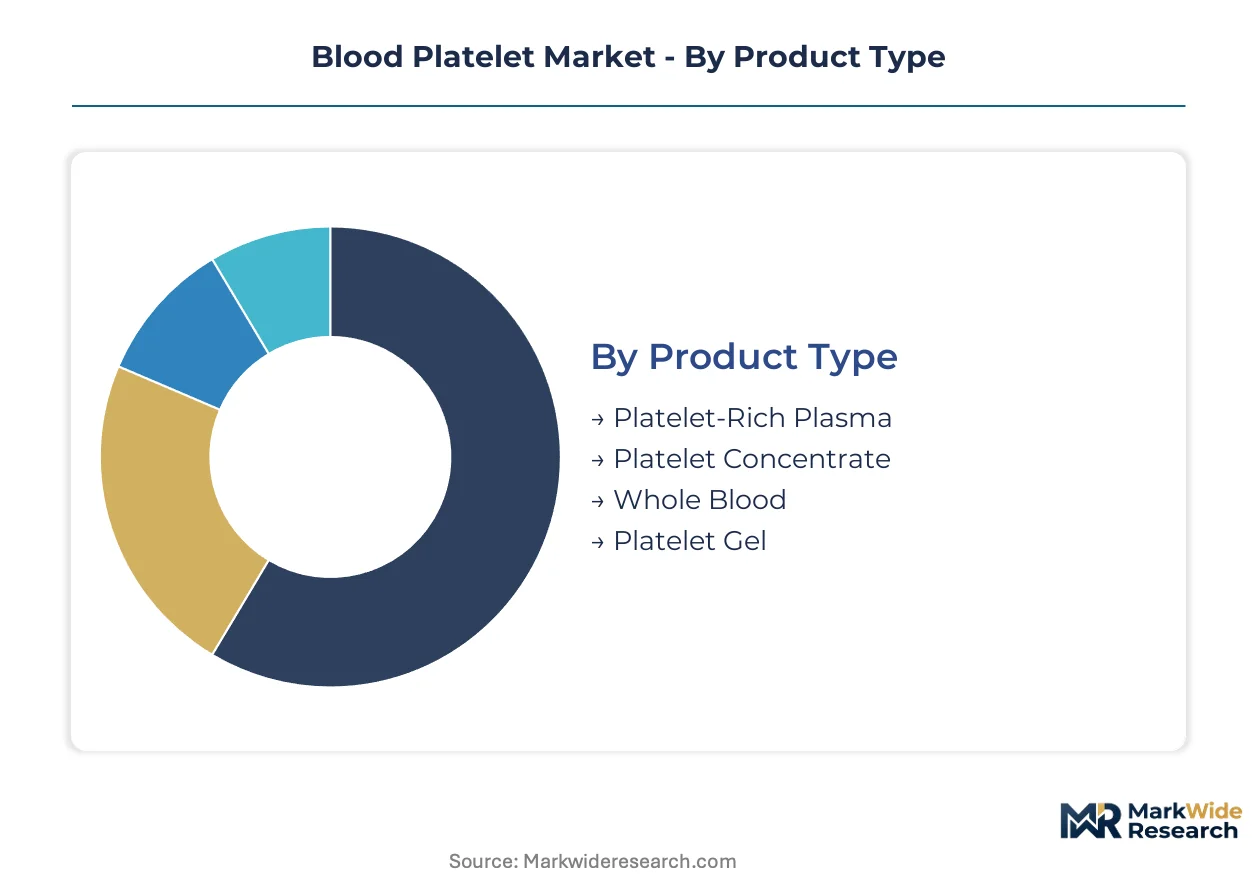
Blood platelet segmentation reflects divergent regulatory pathways across product categories and end-use settings. FDA and EMA standards create tiered compliance burdens that reshape procurement economics for hospitals versus outpatient clinics.
Product Type:
FDA blood banking regulations and EMA pathogen reduction mandates apply asymmetrically across product categories, with transfusion-grade materials facing stricter inactivation requirements than autologous preparations.
- Platelet Concentrate:Derived from whole blood processing or apheresis collection, this segment carries established reimbursement codes in surgical transfusion protocols. Demand concentrates in United States trauma centers and German cardiac surgery suites where massive transfusion protocols consume inventory rapidly.
- Platelet-Rich Plasma:Autologous preparation from patient blood draws bypasses allogeneic donor screening requirements under FDA 21 CFR 1271. Orthopedic outpatient clinics in Germany and dermatology practices in Japan are expanding centrifugation capacity to capture regenerative therapy margins previously retained by hospital-based specialists.
- Whole Blood:Military and rural trauma applications sustain niche demand where component separation infrastructure is unavailable.
- Platelet Gel:Surgical hemostat applications in dental and orthopedic settings leverage autologous sourcing to avoid allogeneic regulatory burdens.
Established volume favors Platelet Concentrate; emerging adoption favors Platelet-Rich Plasma.
End User:
Customer type determines capital intensity and regulatory exposure, with integrated health systems consolidating purchasing leverage across facility networks.
- Hospitals:Emergency transfusion dependency and surgical volume sustain dominant procurement scale. United States academic medical centers in Boston and Philadelphia have completed pathogen reduction fleet conversions, displacing conventional irradiation suppliers.
- Blood Banks:Centralized processing facilities capture margin pools from pathogen-reduction service fees as EMA amendments expand nucleic acid testing requirements.
- Laboratories:Quality control and reference testing demand specialized platelet concentrates for assay standardization.
- Research Institutions:Cell therapy and regenerative medicine protocols consume research-grade platelet lysates for ex vivo expansion media.
Procurement consolidation favors Hospitals; margin expansion favors Blood Banks.
Therapy Area:
Clinical application dictates reimbursement tier and regulatory classification, with surgical indications commanding premium pricing over cosmetic protocols.
- Orthopedics:Tendon repair and osteoarthritis protocols in Germany's ambulatory surgical centers are migrating platelet-rich plasma from hospital settings, enabled by outpatient reimbursement pilots in Switzerland and the Netherlands.
- Cardiology:Platelet concentrate transfusion supports cardiac surgery suites and interventional cardiology procedures with established DRG-based reimbursement.
- Dermatology:Aesthetic and wound healing applications face variable payer coverage, constraining volume in United States and Japanese markets.
- Dentistry:Implant site preparation and socket preservation utilize platelet gel formulations with minimal regulatory friction.
Reimbursement stability favors Cardiology; volume acceleration favors Orthopedics.
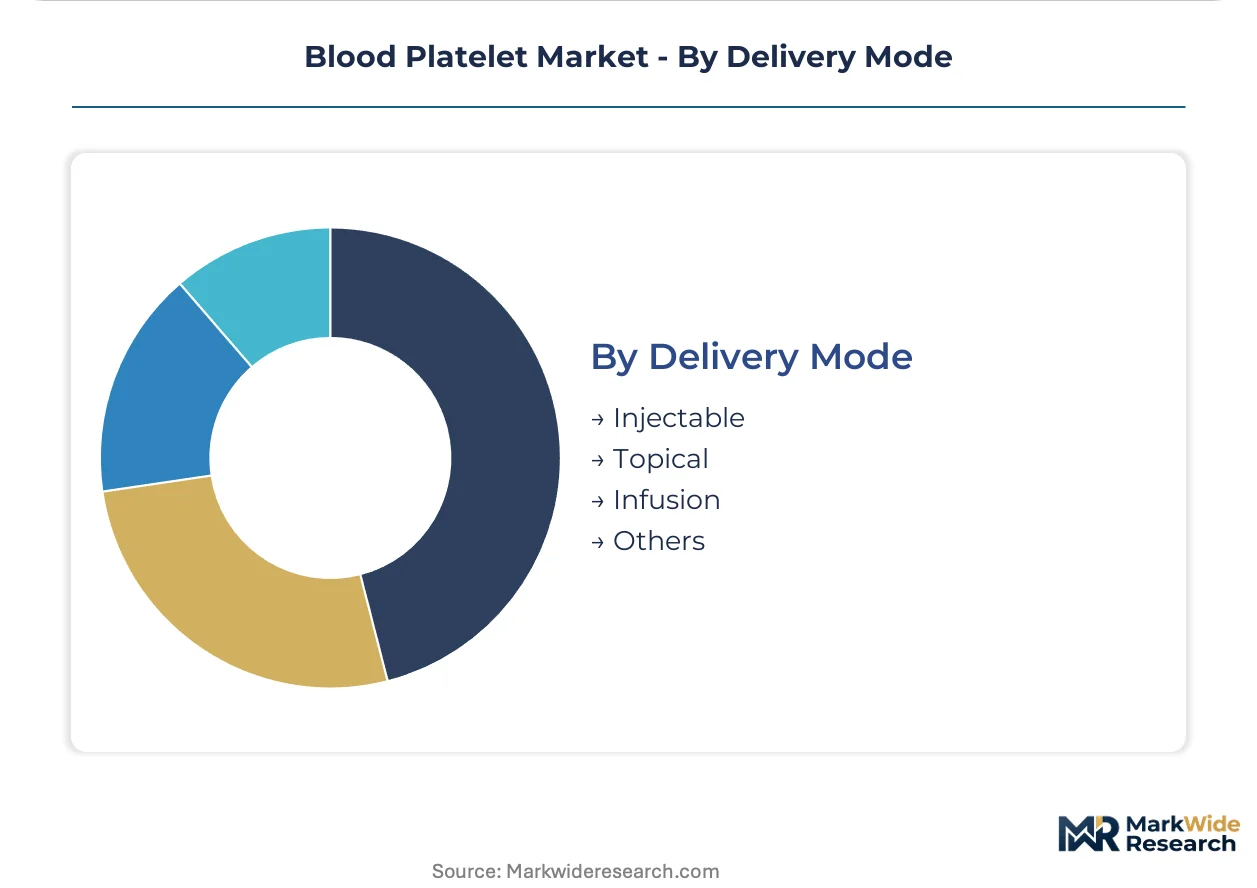
Delivery Mode:
Administration route shapes cold-chain requirements and shelf-life economics, with parenteral formats facing stricter sterility assurance than topical applications.
- Infusion:Intravenous platelet concentrate delivery dominates transfusion medicine with five-day storage limitations and bacterial detection protocols preventing inventory buffer accumulation.
- Injectable:Intra-articular and soft-tissue injections of platelet-rich plasma bypass hospital blood bank infrastructure, enabling point-of-care preparation in orthopedic clinics.
- Topical:Surgical site application of platelet gel eliminates systemic absorption concerns, reducing regulatory documentation burdens.
- Others:Nasal and ophthalmic delivery formats remain investigational with limited commercial penetration.
Transfusion scale favors Infusion; clinic autonomy favors Injectable.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital blood bank procurement concentrates in aging economies with established trauma networks and cardiac surgery corridors. United States health systems, German ambulatory surgical centers, and Japanese metropolitan hospitals drive differential demand patterns across product formats.
United States
Academic medical centers in Boston and Philadelphia completed fleet conversions to pathogen-reduced platelet inventories, displacing conventional irradiation suppliers. FDA blood banking regulations and AABB standards enforce nucleic acid testing and bacterial detection protocols that reshape collection economics. Three national blood center alliances control over sixty percent of apheresis capacity, creating supply vulnerability during regional disasters.
Germany
Ambulatory surgical centers in Bavaria and North Rhine-Westphalia are expanding platelet-rich plasma protocols for tendon repair and osteoarthritis, migrating procedures from hospital settings. EMA Blood Directive amendments now require nucleic acid testing for emerging pathogens, expanding addressable markets for inactivation technologies. The country's distributed blood center network captures margin pools from pathogen-reduction service fees.
Japan
Chronic myeloproliferative disorders in patients over seventy-five sustain prophylactic platelet demand across Tokyo-Osaka hospital corridors. METI and PMDA oversight governs collection standards and additive solution approvals with tightening quality system requirements. Japanese Red Cross Society infrastructure dominates collection capacity in the Kanto and Kansai metropolitan regions.
Switzerland
Payers pilot reimbursement differentials that reward bacterially inactivated platelet units, creating premium tiering opportunities for pathogen-reduced inventories. Swissmedic standards align with EMA frameworks while permitting faster adoption of novel inactivation technologies. Hospital networks in Zurich and Geneva consolidate supplier relationships to capture volume-based contracting leverage.
Netherlands
Sanquin Blood Supply operates centralized processing facilities that capture margin pools from pathogen-reduction service fees amid EMA regulatory expansion. Dutch reimbursement pilots for premium-tier platelet units reshape procurement economics for hospital blood banks. The Randstad urban corridor concentrates demand from academic medical centers and trauma-designated facilities.
Blood Platelet Market Vendor Landscape
Player mix skews toward non-profit blood center networks and specialized equipment suppliers with divergent margin structures. Three national alliances control the majority of collection capacity while equipment vendors anchor the technology supply tier. Strategic archetypes include integrated collection-testing-distribution networks, automated apheresis system manufacturers, and regional operators lacking scale for pathogen reduction conversion. Competitive moves concentrate on sole-source contracting leverage and cold-chain logistics innovation.
Within the integrated network tier, America's Blood Centers and American National Red Cross exemplify divergent geographic strategies. America's Blood Centers leverages a distributed center model across multiple states to sustain coverage breadth. American National Red Cross occupies a position anchored by integrated testing and distribution infrastructure controlling last-mile delivery to hospitals. Terumo BCT sits within the equipment supply tier as a representative of automated collection system manufacturers. These three entities collectively illustrate the market's structural bifurcation between collection networks and technology suppliers.
| Leading Market Players |
|---|
| America's Blood Centers |
| American National Red Cross |
| Japanese Red Cross Society |
| European Blood Alliance |
| OneBlood |
| Canadian Blood Services |
| French Red Cross |
| Australian Red Cross |
| Terumo BCT |
| Others |
Supply Flow & Price Mechanics
Apheresis center utilization rates above eighty percent create fixed-cost leverage that compresses per-unit collection economics while simultaneously raising barriers for regional operators lacking volume scale to absorb pathogen reduction technology upgrades. This scale dynamic concentrates pricing power among three national blood center alliances that negotiate hospital contracts across multi-state networks.
Pricing Analysis
Cost-plus contracts with plasma-derived additive solution indexation dominate hospital procurement agreements, tying unit prices to albumin feedstock volatility. Price differentiation rests on pathogen reduction certification tier and geographic delivery density, with AABB-accredited centers commanding premiums over regional operators. Cost compression in conventional irradiation services is intensifying because academic medical centers are completing fleet conversions to amotosalen-based inactivation. Community hospitals exhibit highest price sensitivity due to constrained transfusion budgets, while trauma-designated academic centers prioritize supply security over unit cost.
Supply Chain Analysis
Five-day inventory turnover constraints and temperature excursion risks prevent buffer stock accumulation, forcing just-in-time coordination between collection centers and hospital blood banks. Supply concentrates in the United States, Germany, and Japan where aging populations sustain chronic transfusion demand. Raw material dependencies include apheresis kits, additive solutions, and nucleic acid testing reagents. Single-source vulnerability in automated collection equipment creates procurement risk for blood centers locked into Terumo BCT platform ecosystems. Distribution runs through integrated collection-testing-distribution networks controlling last-mile delivery to hospital transfusion services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Blood platelet demand follows surgical volume cycles, with elective procedure backlogs from pandemic disruptions now clearing through hospital systems and restoring baseline consumption patterns.
For Market Incumbents: Shield market position by accelerating pathogen reduction fleet conversions before FDA finalizes large-volume delayed sampling guidance, which would strand conventional irradiation capacity. Secure backward integration into additive solution manufacturing to capture margin pools from plasma fractionation feedstock volatility. Consolidate regional operator acquisition targets in states where sole-source contracting mandates are expanding. For New Entrants and Emerging Players: FDA 510(k) fast-track pathways for novel inactivation technologies offer regulatory arbitrage against established amotosalen platforms. Target outpatient orthopedic clinics in Germany's ambulatory surgical center expansion corridor where platelet-rich plasma preparation equipment demand outpaces hospital-based supply. Lead with point-of-care centrifugation systems that bypass blood bank infrastructure entirely. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among blood center networks with multi-year sole-source hospital contracts and embedded pathogen-reduction service fees. Long-term viability over the coming decade hinges on regulatory compliance infrastructure rather than collection volume alone. Monitor EMA Blood Directive amendment implementation timelines as inflection indicators for inactivation technology replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Pathogen Reduction Fleet Conversion | Academic medical centers in Boston and Philadelphia have completed conversions, displacing conventional irradiation suppliers. |
| Apheresis Automation Scale-Up | Closed-system collection platforms reduce contamination risk and extend shelf life for cardiac surgery suites. |
| Outpatient Orthopedic Expansion | German ambulatory surgical centers are migrating platelet-rich plasma protocols from hospital settings. |
| Cold-Chain Drone Delivery Pilot | Last-mile innovation enables same-day delivery to rural trauma centers previously served by overnight courier. |
| AABB Accreditation Investment | Certification bifurcates competitive landscape between certified networks and regional operators lacking scale. |
Methodological Framework
Cross-validation between blood center operations executives and hospital transfusion service directors anchors the qualitative findings, with secondary validation against FDA guidance documents, EMA Blood Directive amendments, AABB standards publications, and hospital procurement database records. Bottom-up triangulation incorporates apheresis technician interviews, biomedical engineer surveys, and GPO contracts manager input. Top-down validation draws from blood center alliance financial disclosures and equipment manufacturer regulatory filings.
Sensitivity analysis across product type, end user, therapy area, and delivery mode segmentation dimensions shapes the analytical framework over the projection horizon. CAGRs derive from surgical volume elasticity modeling, demographic aging trajectories, and regulatory compliance cost absorption curves. Forecast inputs incorporate pathogen reduction technology adoption rates and reimbursement pilot expansion timelines.
Underlying assumptions cover elective surgical procedure recovery trajectories and EMA regulatory implementation schedules, with deviation risk concentrated in regional disaster scenarios that disrupt collection network capacity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Diagnostics
Global HLA Typing Market
Medical Diagnostics
Global Complete Blood Count Device Market
Medical Diagnostics
Global HLA Typing for Transplant Market
Medical Diagnostics
Global ECG Stress Test Market
Medical Diagnostics
Global Hydrophobic Interaction Chromatography Market
Medical Diagnostics
Artificial Intelligence (AI) in Medical Diagnostics Market
Medical Diagnostics
Carrier Screening Market
Medical Diagnostics
Rapid Medical Diagnostic Kits Market
Medical Diagnostics
Flow Cytometry Market
Medical Diagnostics
US Molecular Diagnostics Market
Medical Diagnostics
AI in Medical Diagnostics Market
Medical Diagnostics
Protein Sequencing Market
Medical Diagnostics
Global Histology and Cytology Market
Medical Diagnostics
Cellular Pathology Market
Medical Diagnostics
Stem Cell Characterization Kits Market
Medical Diagnostics
Fluid Biopsy Market