
 In-Situ Hybridization (ISH) Market | 2026-2036
In-Situ Hybridization (ISH) Market Size, Share, and Industry Trends Forecast 2026-2036
In-Situ Hybridization (ISH) Market Insights
Buyer concentration across hospital networks and diagnostic laboratories is rebalancing as decentralized pathology services fragment procurement authority toward regional reference labs. Thermo Fisher Scientific leverages its consumables-recurring revenue model to sustain placement growth in academic medical centers. Danaher anchors its position through Leica Biosystems' integrated workflow automation. Abbott competes on clinical-lab throughput with automated staining platforms that reduce manual probe-handling steps.
In-situ hybridization denotes a molecular cytogenetic technique wherein labeled nucleic acid probes bind complementary target sequences within preserved tissue sections or cellular preparations, enabling spatial mapping of gene expression at single-cell resolution with detection thresholds reaching one to five target copies per cell. The method serves primarily to localize specific DNA or RNA sequences within morphological context for diagnostic and research applications. Fluorescent probes dominate clinical revenue owing to multiplexing capacity and digital-pathology compatibility, while chromogenic probes retain installed-base loyalty in anatomic pathology labs with legacy brightfield microscopes. FISH technology leads oncology diagnostics where HER2 and ALK biomarker testing commands premium reimbursement, whereas traditional ISH occupies stable demand in basic research settings with lower per-test budget constraints.
FDA oversees probe-based companion diagnostics through its in vitro diagnostic premarket pathway, requiring analytical and clinical validation for claims tied to specific therapeutic agents. The EU MDR and IVDR frameworks impose stricter post-market surveillance and notified-body involvement, elevating compliance costs for probe manufacturers seeking CE-marked access. ISO 15189 accreditation standards shape quality-management expectations for hospital laboratories running ISH assays. Stakeholders must monitor evolving payer evidence requirements for spatial biomarker tests as health technology assessment bodies weigh diagnostic utility against sequencing alternatives.
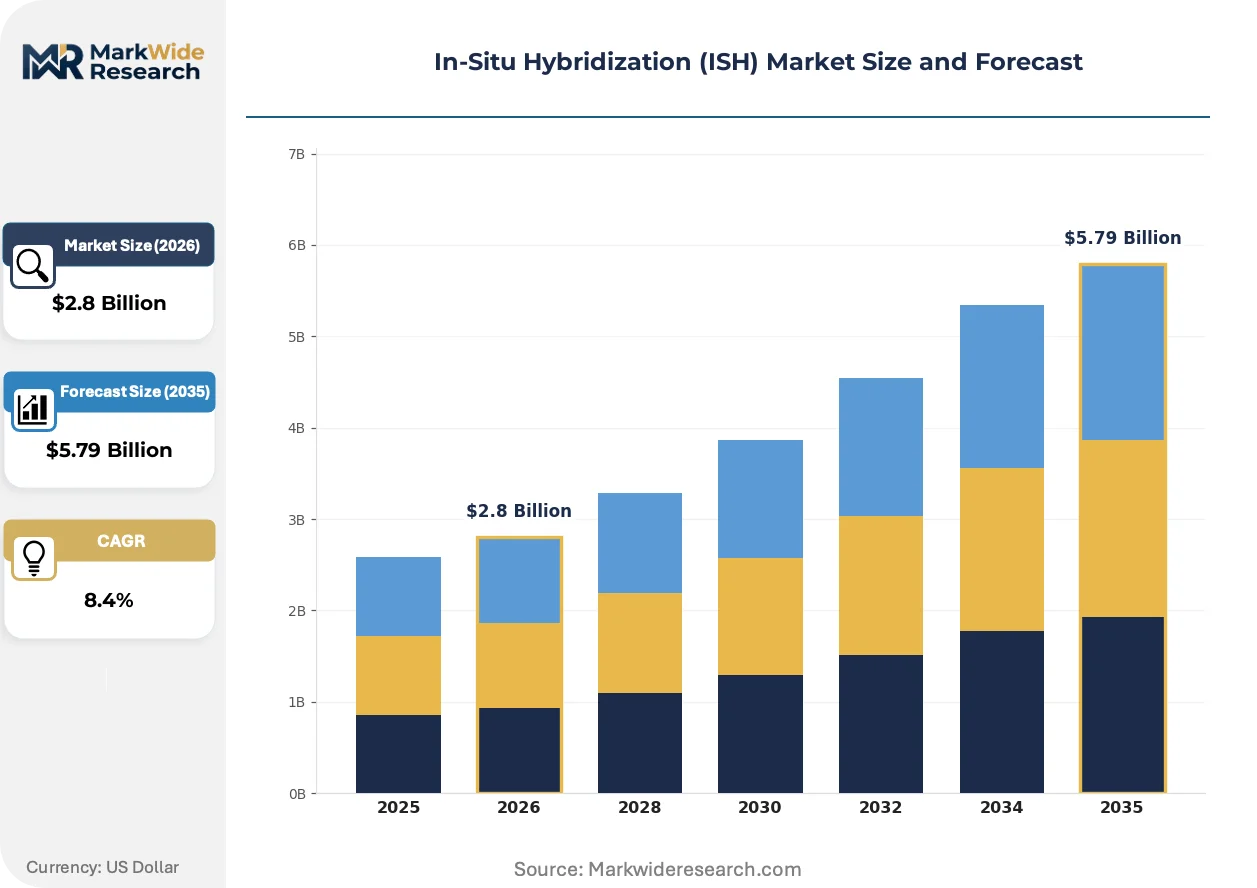
Market Dynamics
Spatial transcriptomics workflows are consolidating probe procurement around integrated platform vendors as academic medical centers seek to reduce vendor fragmentation in multi-omics pipelines.
Growth Catalysts
- IVDR compliance mandates:The EU In Vitro Diagnostic Regulation is accelerating hospital laboratory consolidation onto validated ISH platforms that satisfy notified-body documentation requirements for companion diagnostic workflows.
- NIH precision oncology funding:Sustained capital flows into advanced tissue-analysis technologies at US academic medical centers are expanding installed bases of automated staining systems.
- FISH multiplexing advances:Fluorescent probe technologies enabling simultaneous detection of multiple biomarkers are compressing diagnostic timelines in solid tumor pathology.
Market Restraints
- Probe manufacturing concentration:Specialized oligonucleotide synthesis capacity clusters among a limited set of contract manufacturers, creating supply vulnerability for customized research-grade probes.
- Capital intensity of automated platforms:High upfront equipment costs for integrated staining-and-imaging systems constrain adoption at mid-sized community hospital laboratories.
- Sequencing substitution:Next-generation sequencing platforms with spatial transcriptomics add-ons are capturing budget share in exploratory research settings where morphological context is secondary.
Strategic Opportunities
- Decentralized pathology networks:Regional reference laboratories in the United States are fragmenting procurement authority away from centralized hospital networks, creating new channel access points for mid-tier platform vendors.
- Digital pathology convergence:Integration of fluorescent ISH imaging with whole-slide scanning workflows is enabling remote diagnostic interpretation and second-opinion networks.
- ISO 15189 accreditation expansion:Rising quality-management certification requirements for hospital laboratories in Europe are creating service and consumables lock-in opportunities for compliant platform providers.
Industry Challenges
- Probe design expertise scarcity:Shortages of molecular cytogeneticists capable of optimizing probe specificity for novel biomarker targets are extending assay development timelines at diagnostic manufacturers.
- Legacy brightfield infrastructure:Chromogenic ISH workflows dependent on existing microscope installations create path dependency that slows fluorescent platform conversions in established anatomic pathology labs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | In-Situ Hybridization (ISH) Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.79 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fluorescent Probes, Chromogenic Probes, RNA Probes, DNA Probes Technology: Traditional ISH, FISH, CISH, SISH Application: Genetic Research, Cancer Diagnostics, Tissue Localization, Microbial Detection End User: Academic Research Institutions, Hospitals, Diagnostic Laboratories, Pharmaceutical Companies |
| Companies Covered | F. Hoffmann-La Roche Ltd, Danaher, Abbott, Thermo Fisher Scientific Inc., Agilent Technologies Inc., Merck KGaA, PerkinElmer Inc., Bio-Rad Laboratories Inc., QIAGEN N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
In-Situ Hybridization (ISH) Market Trends and Innovations
Multi-omics integration is compressing the boundary between research and diagnostic workflows, forcing probe manufacturers to design for dual-use compatibility from inception rather than retrofitting research tools for clinical validation.
RNAscope chromogenic and fluorescent detection chemistry is rewriting the accessibility of single-molecule RNA visualization in formalin-fixed tissue. Academic pathology departments are adopting these assays at accelerating pace for infectious disease and neuroscience applications. The technology is compressing the gap between discovery transcriptomics and clinical diagnostic implementation by standardizing probe design algorithms.
The EU Medical Device Regulation and In Vitro Diagnostic Regulation frameworks are tightening post-market surveillance obligations for probe-based companion diagnostics. Manufacturers must now maintain clinical evidence packages across product lifecycles rather than at launch only. Oncology assay providers are responding by embedding real-world data collection into laboratory information management systems.
Buyer concentration is fragmenting as integrated delivery networks spin out pathology services to standalone regional reference laboratories. Equipment vendors are adapting by unbundling service contracts from capital sales and offering consumables-only supply agreements. This pattern is most visible in the United States where Medicare reimbursement pressures are driving operational restructuring.
In-Situ Hybridization (ISH) Market Segmentation
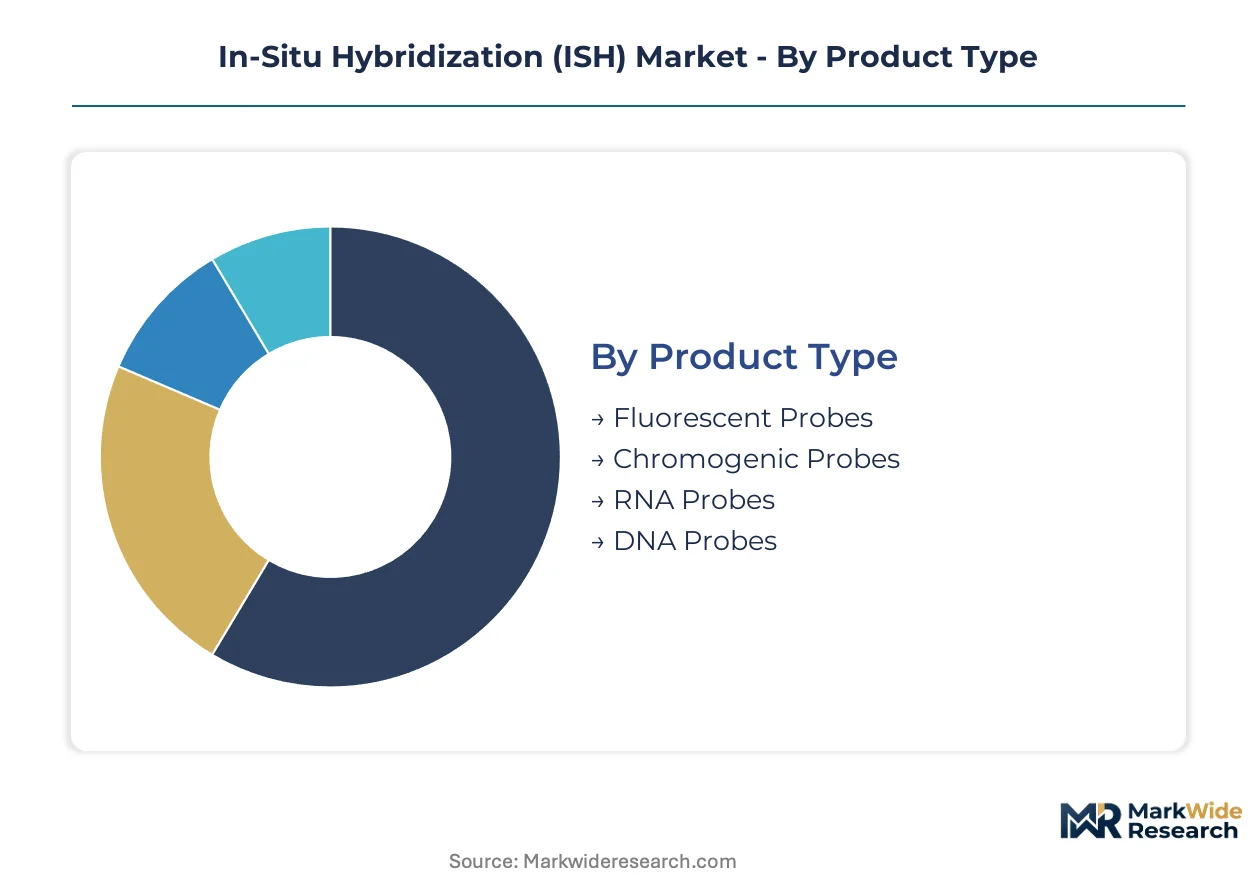
Probe architecture and detection chemistry define reimbursement pathways and regulatory burden across the ISH market. Segmentation reveals how FDA companion diagnostic requirements concentrate revenue in fluorescent multiplexing platforms while chromogenic formats retain installed-base loyalty in budget-constrained settings.
Product Type:
FDA premarket approval requirements and IVDR technical documentation obligations fall most heavily on fluorescent and DNA probe categories, while research-grade RNA probes navigate lighter regulatory scrutiny.
- Fluorescent Probes:Synthetic oligonucleotides conjugated to fluorophores enable simultaneous detection of multiple biomarkers through spectral separation. Demand concentrates in United States academic medical centers where HER2 and ALK companion diagnostic testing commands premium reimbursement from Medicare and private payers. Multiplexing capacity aligns with precision oncology workflows.
- Chromogenic Probes:Enzyme-labeled probes generate visible precipitates compatible with standard brightfield microscopy infrastructure. Anatomic pathology laboratories in Germany and France retain substantial installed bases of these assays owing to legacy microscope investments and lower per-test consumables costs. The format suits resource-limited diagnostic settings.
- RNA Probes:Riboprobe chemistry targets messenger RNA sequences with single-molecule sensitivity in formalin-fixed tissue.
- DNA Probes:Double-stranded DNA constructs target chromosomal loci for cytogenetic aberration detection.
Leading the category by volume: Chromogenic Probes. Growing fastest: Fluorescent Probes.
Technology:
Capital intensity and automation compatibility stratify adoption across hospital laboratory tiers, with integrated platforms commanding higher equipment expenditure but reducing manual handling labor.
- FISH:Fluorescence in situ hybridization dominates oncology diagnostics through FDA-cleared assays for breast and lung cancer biomarkers. United States reference laboratories deploy automated FISH platforms to process high companion diagnostic volumes under CAP proficiency testing requirements. The technology anchors revenue in the product category.
- Traditional ISH:Non-fluorescent radioactive or chromogenic methods persist in basic research settings with limited capital budgets. Academic institutions in Japan and Australia maintain substantial usage for gene expression mapping where morphological context outweighs throughput requirements. Lower regulatory burden suits exploratory applications.
- CISH:Chromogenic in situ hybridization bridges brightfield compatibility with DNA target detection.
- SISH:Silver in situ hybridization offers chromogenic detection without fluorescence microscopy requirements.
Deploying most widely: FISH. Expanding most quickly in automated formats: CISH.
Application:
Reimbursement coding and health technology assessment criteria vary sharply between clinically validated diagnostic indications and research exploratory use.
- Cancer Diagnostics:Solid tumor biomarker testing drives commercial revenue through FDA-cleared companion diagnostic claims. United States hospital laboratories process HER2, ALK, ROS1, and NTRK assays under established CPT coding. Payer evidence requirements concentrate procurement on validated platforms.
- Genetic Research:Discovery-phase transcriptomics and developmental biology applications operate outside clinical regulatory pathways. Academic medical centers in the United Kingdom and Netherlands allocate grant funding to spatial gene expression mapping without diagnostic reimbursement constraints. Budget flexibility enables protocol customization.
- Tissue Localization:Anatomical mapping of gene expression patterns supports pathology education and research.
- Microbial Detection:Ribosomal RNA targeting identifies infectious agents in tissue sections.
Generating highest revenue per test: Cancer Diagnostics. Gaining share fastest: Tissue Localization.
End User:
Procurement authority fragmentation and accreditation requirements reshape vendor relationships across institutional categories.
- Diagnostic Laboratories:Independent and hospital-affiliated labs in the United States face Medicare reimbursement compression and ISO 15189 quality management mandates. Regional reference laboratories are consolidating pathology services from integrated delivery networks, creating new channel access for platform vendors. Volume concentration enables consumables contract negotiation.
- Academic Research Institutions:NIH-funded medical centers deploy spatial transcriptomics platforms for multi-omics integration. Grant funding cycles drive capital equipment replacement timelines. Procurement favors vendors offering dual-use probe compatibility between research and potential clinical translation.
- Hospitals:In-house pathology departments manage regulatory compliance for patient care.
- Pharmaceutical Companies:Companion diagnostic development partnerships require probe manufacturing scale-up.
Highest volume concentration: Diagnostic Laboratories. Steepest expansion trajectory: Academic Research Institutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for in-situ hybridization platforms concentrates in the United States, where NIH precision oncology funding sustains the largest installed base of automated staining systems worldwide. Academic medical centers in Boston and San Francisco anchor procurement volumes for spatial transcriptomics workflows.
United States
Hospital laboratories in the United States process HER2 and ALK companion diagnostic assays under established CPT reimbursement codes. FDA premarket approval requirements for probe-based diagnostics elevate compliance costs for platform vendors seeking clinical claims. The Boston-Cambridge biotech corridor hosts the highest density of spatial transcriptomics research installations, with Danaher and Thermo Fisher Scientific maintaining field service presences.
Germany
Anatomic pathology laboratories in Germany retain substantial installed bases of chromogenic ISH assays compatible with legacy brightfield microscopy. The EU In Vitro Diagnostic Regulation imposes stricter post-market surveillance obligations on probe manufacturers seeking CE-marked access. Heidelberg and Munich anchor the country's diagnostic pathology cluster, where Leica Biosystems maintains workflow automation partnerships.
United Kingdom
Academic research institutions in the United Kingdom allocate grant funding to spatial gene expression mapping without diagnostic reimbursement constraints. ISO 15189 accreditation standards shape quality-management expectations for hospital laboratories running ISH assays. The Cambridge-Oxford-London triangle concentrates RNAscope adoption for infectious disease and neuroscience applications.
Japan
Academic institutions in Japan maintain substantial traditional ISH usage for gene expression mapping where morphological context outweighs throughput requirements. PMDA regulatory pathways for companion diagnostics require analytical and clinical validation for claims tied to specific therapeutic agents. The Kansai region around Osaka hosts specialized oligonucleotide synthesis capacity serving customized research-grade probe demand.
China
Hospital laboratories in China are expanding procurement of automated FISH platforms for solid tumor biomarker testing. NMPA oversight of in vitro diagnostics is tightening performance-documentation requirements for probe-based assays. Shanghai and Beijing anchor the country's precision oncology diagnostic infrastructure, with domestic platform vendors gaining share in mid-tier installations.
In-Situ Hybridization (ISH) Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue spatial transcriptomics specialization and digital pathology convergence. The market exhibits tiered concentration around integrated platform vendors with consumables-recurring revenue models and standalone probe manufacturers serving research segments. Three archetypes dominate: diversified life science conglomerates with workflow automation capabilities, specialized diagnostic platform vendors, and contract manufacturers of customized oligonucleotide probes. Competitive dynamics center on M&A activity consolidating spatial biology capabilities and strategic partnerships embedding real-world data collection into laboratory information systems.
Among diversified life science conglomerates, F. Hoffmann-La Roche Ltd and Danaher exemplify the integrated workflow automation archetype, anchoring positions through consumables lock-in and service contract bundling. Thermo Fisher Scientific occupies a comparable tier, representing the recurring-revenue platform model in academic medical center placements. Abbott sits within the clinical-lab throughput specialization, with its corporate structure signaling diagnostic equipment manufacturing scale. These three entities collectively illustrate how vendor consolidation around multi-omics pipelines is compressing procurement fragmentation in hospital networks.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| Danaher |
| Abbott |
| Thermo Fisher Scientific Inc. |
| Agilent Technologies Inc. |
| Merck KGaA |
| PerkinElmer Inc. |
| Bio-Rad Laboratories Inc. |
| QIAGEN N.V. |
| Others |
Pricing and Supply Chain Analysis
Captive probe manufacturing by Thermo Fisher Scientific and Danaher anchors both supply security and premium pricing power in the United States market. This backward integration into synthetic oligonucleotide production shields integrated platform vendors from contract manufacturer volatility while supporting consumables-recurring revenue models that lock in academic medical center procurement.
Pricing Analysis
High-volume FISH companion diagnostic testing in United States hospital laboratories commands premium per-test margins under established CPT reimbursement codes, while chromogenic probe formats compete on lower consumables costs for budget-constrained anatomic pathology labs in Germany and France. Price differentiation stems from FDA premarket approval tier and automation compatibility, with IVDR technical documentation obligations adding compliance cost premiums to CE-marked probes. Cost compression in research-grade RNA probe segments is intensifying because next-generation sequencing platforms are capturing exploratory transcriptomics budgets. Academic research institutions exhibit highest price sensitivity owing to grant funding cycles, whereas diagnostic laboratories running HER2 and ALK assays show lowest sensitivity due to pass-through reimbursement structures.
Supply Chain Analysis
Synthetic oligonucleotide feedstock rests on specialized chemical synthesis capacity concentrated in the United States, Germany, and Japan. Critical inputs include fluorophore conjugates, enzyme labels for chromogenic detection, and high-purity ribonucleotides for RNA probe construction. Single-source vulnerability clusters around contract manufacturers of customized research-grade probes in the Kansai region, where specialized synthesis expertise has not replicated geographically. Distribution runs through direct field service teams for automated platform placements and laboratory distributors for consumables replenishment in hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU IVDR and FDA premarket pathways have erected cost-of-compliance barriers that favor incumbent platform vendors with dedicated regulatory affairs infrastructure and penalize undercapitalized probe manufacturers lacking notified-body relationships.
For Market Incumbents: Deepen consumables lock-in at regional reference laboratories fragmenting from integrated delivery networks by unbundling service contracts and offering flexible consumables-only supply agreements. Accelerate ISO 15189 accreditation support services for European hospital laboratories facing quality management mandates, converting compliance assistance into multi-year consumables commitments that resist sequencing substitution threats. For New Entrants and Emerging Players: Digital pathology convergence channels offer lower-friction entry points for fluorescent imaging platform vendors seeking to bypass entrenched brightfield infrastructure at established anatomic pathology labs. Target mid-sized community hospital laboratories in the United States constrained by capital intensity of automated staining systems, penetrating through affordable instrument leasing models and pay-per-test consumables arrangements that reduce upfront equipment expenditure barriers. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified life science conglomerates seeking spatial transcriptomics capabilities to complete multi-omics integration strategies. Long-term viability favors platform vendors with demonstrated IVDR technical documentation competence and installed bases in NIH-funded academic medical centers. Monitor FDA companion diagnostic approval velocity for novel oncology biomarkers as the inflection indicator signaling expanded addressable market for validated probe manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| IVDR Technical Documentation Investment | CE marking pathway unlocks European hospital laboratory procurement for companion diagnostic workflows. |
| Spatial Transcriptomics Platform Integration | Multi-omics pipeline consolidation reduces vendor fragmentation in academic medical center procurement. |
| Regional Reference Laboratory Partnership | Decentralized pathology networks fragment procurement authority toward standalone diagnostic service providers. |
| Digital Pathology Imaging Convergence | Whole-slide scanning compatibility enables remote diagnostic interpretation and second-opinion network expansion. |
| Real-World Data Collection Embedding | Laboratory information management system integration satisfies EU MDR post-market surveillance obligations. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with molecular cytogeneticists, hospital laboratory directors, diagnostic platform procurement managers, and GPO contracts specialists. FDA 510(k) and PMA filings, EMA IVDR technical documentation databases, NIH RePORTER grant award records, and hospital procurement databases provided quantitative foundations. Bottom-up probe shipment estimates triangulated against top-down platform installed base calculations to validate market sizing.
Data-stream reconciliation across product type, technology format, application indication, and end-user institution dimensions shaped the analytical framework throughout the projection horizon. CAGRs derived from segment-level growth trajectories weighted by reimbursement pathway maturity and regulatory approval status. Forecast inputs incorporated NIH precision oncology funding allocations, EU IVDR implementation timelines, and spatial transcriptomics platform adoption curves in academic medical centers.
The model holds under stable regulatory enforcement intensity and sustained Medicare reimbursement for companion diagnostic testing; deviation in sequencing technology cost curves or IVDR notified body capacity constraints would shift probe demand trajectories. Forecasts reflect documented assumptions regarding platform replacement cycles and grant funding continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Diagnostics
Real-Time PCR, Digital PCR, and End-Point PCR Market
Medical Diagnostics
Flow Cytometry Market
Medical Diagnostics
Medical Isotope Market
Medical Diagnostics
Blood Platelet Market
Medical Diagnostics
Stem Cell Panel Market
Medical Diagnostics
Cellular Pathology Market
Medical Diagnostics
Global Complete Blood Count Device Market
Medical Diagnostics
Protein Sequencing Market
Medical Diagnostics
Carrier Screening Market
Medical Diagnostics
Asia Pacific Immunohistochemistry Market
Medical Diagnostics
X Ray Crystallography Market
Medical Diagnostics
Global ECG Stress Test Market
Medical Diagnostics
Magnetic Resonance Analyzer Market
Medical Diagnostics
MUC1 Antibody Market
Medical Diagnostics
Electroretinogram Market
Medical Diagnostics
Telepathology Market