
 Rapid Medical Diagnostic Kits Market | 2026-2036
Rapid Medical Diagnostic Kits Market Size, Share, and Industry Trends Forecast 2026-2036
Rapid Medical Diagnostic Kits Market Intelligence
CLIA waiver certification is redrawing competitive boundaries in the rapid diagnostic space. Abbott Laboratories leverages its broad immunoassay portfolio to sustain dominance in high-complexity laboratory channels. Danaher Corporation anchors its position through integrated molecular workflow systems that span sample prep to result reporting. bioMérieux SA differentiates via specialized infectious disease panels that command premium placement in European hospital networks.
Rapid medical diagnostic kits are portable analytical devices that detect target analytes in biological specimens through immunochromatographic, enzymatic, or nucleic acid amplification reactions, typically delivering results within fifteen minutes to two hours for clinical or home-based decision-making. Lateral flow assay technology occupies the largest installed base due to its minimal equipment requirements and suitability for resource-limited settings, while microfluidics represents the fastest-expanding segment as manufacturers miniaturize multiplexed testing onto disposable cartridges. Infectious disease applications generate the deepest revenue pools, though toxicology testing exhibits accelerating growth from workplace screening mandates and pain management clinic protocols.
FDA premarket notification requirements and CLIA complexity categorization govern U.S. market access, with the EPA occasionally intersecting where diagnostic waste streams trigger environmental disposal rules. The EU Medical Device Regulation imposes stricter clinical evidence standards on Class C and D in vitro devices, compelling manufacturers to rebuild technical documentation for CE marking continuity. Stakeholders must monitor evolving WHO prequalification criteria, as these standards increasingly determine eligibility for procurement by national health ministries in low- and middle-income countries.
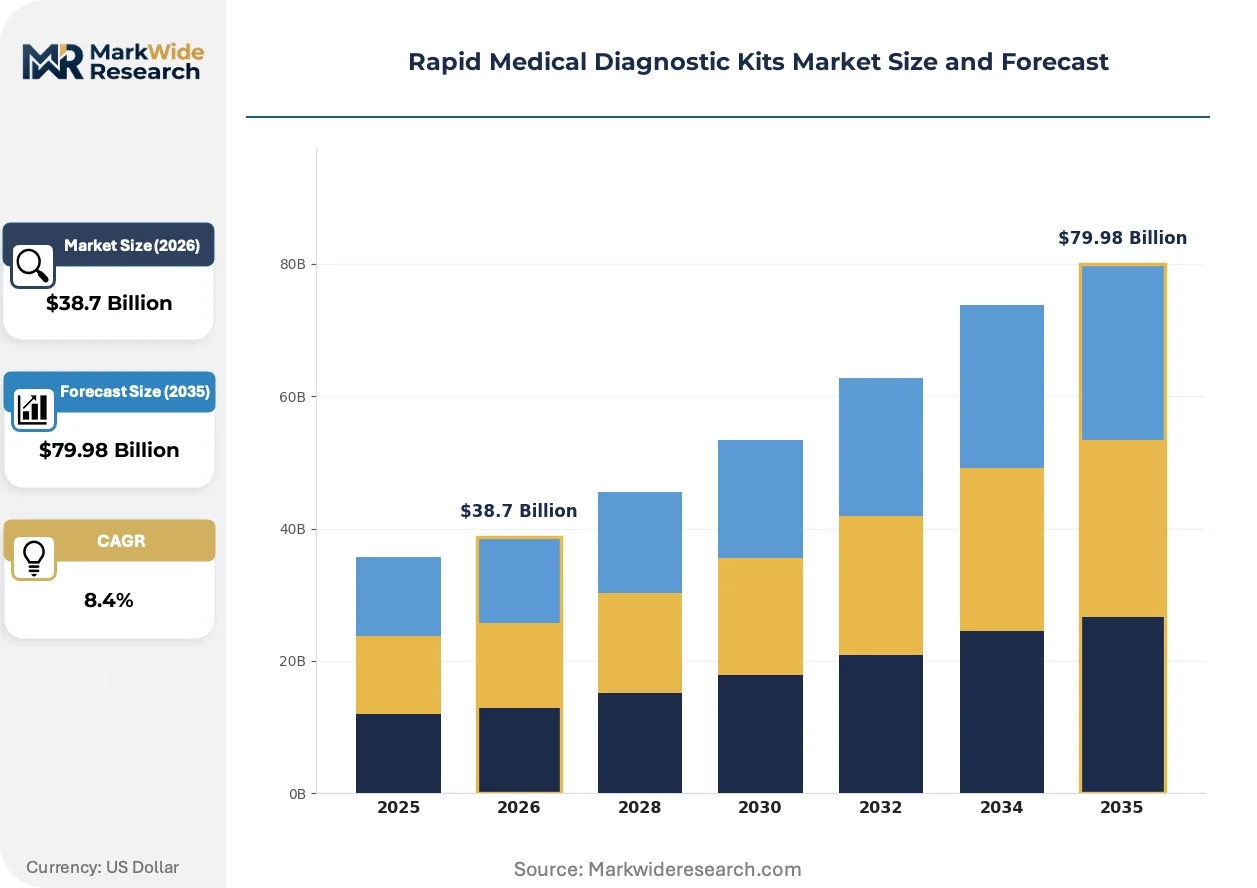
Market Dynamics
CLIA waiver pathways and decentralized testing mandates are compressing the traditional laboratory channel, forcing manufacturers to reconfigure distribution toward pharmacy and direct-to-consumer channels while maintaining diagnostic accuracy standards.
Growth Catalysts
- Home Care Decentralization:Patients in the United States bypass centralized laboratories as FDA-cleared over-the-counter tests expand shelf presence in retail pharmacy chains.
- India's National Screening Programs:Government procurement under the National Health Mission drives volume orders for affordable infectious disease panels at district hospital level.
- Microfluidics Miniaturization:Disposable cartridge architectures enable multiplexed testing on battery-powered readers, opening resource-limited clinic deployment.
Market Restraints
- Raw Material Concentration:Nitrocellulose membrane supply concentrates among three specialized chemical manufacturers, creating input vulnerability.
- EU MDR Compliance Burden:Stricter clinical evidence requirements for Class C in vitro devices extend recertification timelines and documentation costs.
- Lateral Flow Saturation:Commoditized immunoassay formats face price compression as manufacturing know-how diffuses to contract producers.
Strategic Opportunities
- Sub-Saharan Africa Distribution Gaps:WHO prequalification eligibility unlocks procurement by ministries of health in Nigeria, Kenya, and Ghana for malaria and HIV rapid tests.
- Workplace Toxicology Mandates:Occupational safety protocols in transportation and construction sectors expand saliva and urine screening panels.
- Telehealth Integration:Remote consultation platforms bundle diagnostic kit shipments with synchronous result interpretation, creating new channel economics.
Industry Challenges
- Multiplex Assay Development Expertise:Shortage of bioengineers skilled in microfluidic cartridge design and reagent stabilization constrains product pipeline velocity.
- Legacy LIS Interoperability:Hospital information system integration requires HL7 FHIR mapping that delays point-of-care device deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rapid Medical Diagnostic Kits Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antigen Tests, Antibody Tests, Nucleic Acid Tests, Molecular Diagnostics Technology: Enzyme-Linked Immunosorbent Assay, Lateral Flow Assay, Polymerase Chain Reaction, Microfluidics End User: Hospitals, Clinics, Home Care, Laboratories Application: Infectious Diseases, Chronic Diseases, Toxicology Testing, Genetic Testing |
| Companies Covered | Abbott Laboratories, ACON Laboratories, Inc., Artron Laboratories Inc., Alfa Scientific Designs, Inc., Becton, Dickinson and Company, bioMérieux SA, F. Hoffmann-La Roche AG, Cardinal Health, Danaher Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rapid Medical Diagnostic Kits Market Strategic Shifts & Innovations
Diagnostic manufacturers are racing to compress assay time-to-result while expanding analyte multiplexing, with regulatory pathways and distribution economics determining which technical architectures achieve commercial scale.
Isothermal nucleic acid amplification is supplanting traditional thermal cycler PCR in near-patient settings. Community health centers and urgent care clinics adopt battery-powered instruments that eliminate cold-chain logistics for reagent storage. This shift is compressing the addressable market for central laboratory molecular testing while expanding test menu breadth at decentralized sites.
The EU Medical Device Regulation imposes post-market surveillance obligations that demand continuous clinical performance monitoring. Manufacturers must maintain periodic safety update reports and vigilance databases that track device failures across member states. Class C infectious disease panels face the steepest documentation burden, prompting some firms to narrow product portfolios to core assays.
Pharmacy chains now curate diagnostic assortments based on CLIA waiver status and consumer self-test literacy. Retail buyers prioritize single-use devices with visual result interpretation over instrument-dependent systems requiring training. This pattern concentrates procurement power among three national pharmacy banners in the United States, compressing margins for suppliers without direct store-level relationships.
Rapid Medical Diagnostic Kits Market Segmentation
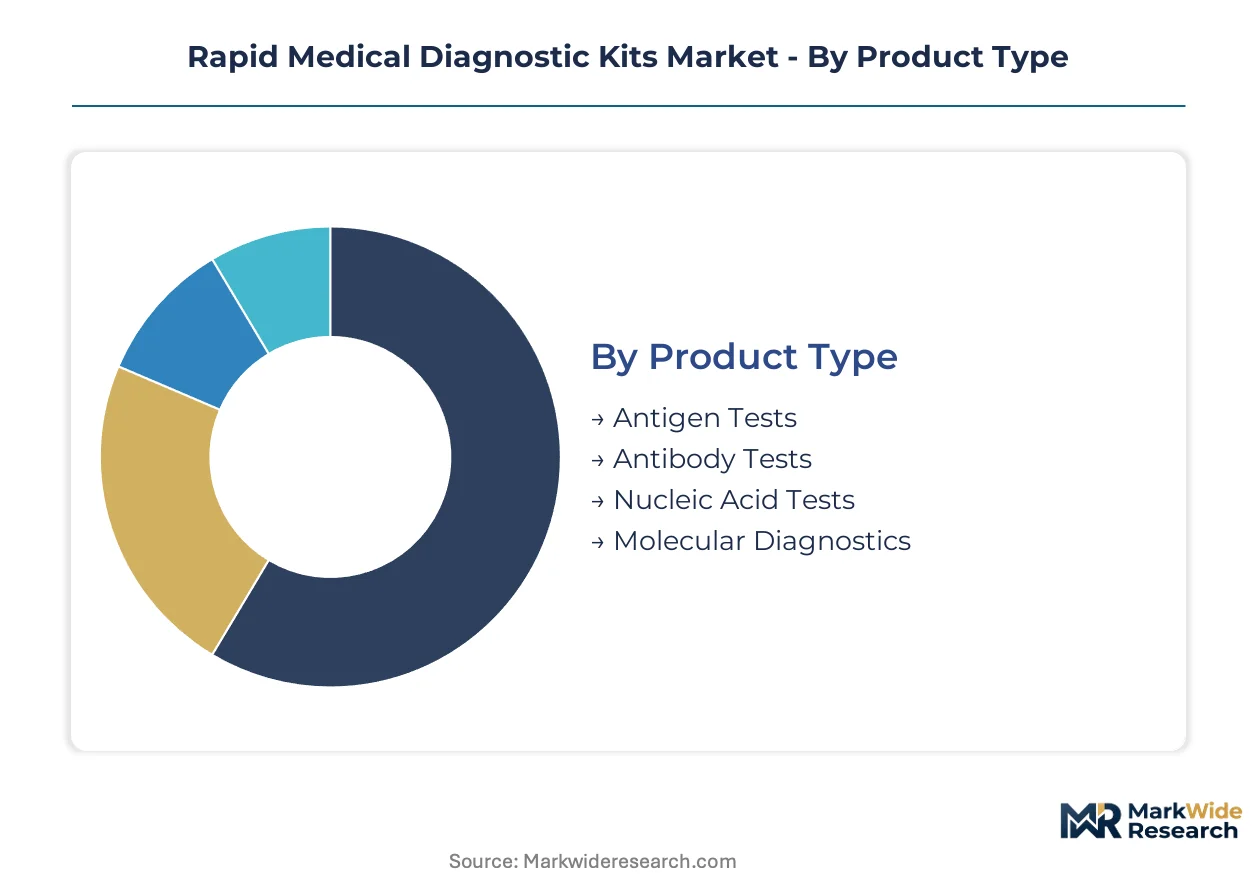
Segmentation in rapid diagnostics determines which technical architectures achieve commercial scale through specific channel economics. Each dimension—product chemistry, detection platform, care setting, and clinical indication—carries distinct regulatory pathways and margin structures that reshape competitive positioning.
Product Type:
Antigen and antibody formats flow through pharmacy retail and government procurement channels, while nucleic acid and molecular platforms concentrate in hospital laboratory networks requiring CLIA certification.
- Antigen Tests:These immunoassays detect pathogen surface proteins through lateral flow or membrane-based reactions, delivering results in 10-15 minutes without instrumentation. Demand concentrates in India's National Health Mission procurement for tuberculosis and malaria screening at district hospitals, where price sensitivity and cold-chain independence dominate specifications.
- Antibody Tests:Serological assays identify host immune response through IgM/IgG detection, typically requiring whole blood or serum specimens. Home care settings in the United States drive volume for over-the-counter HIV and hepatitis C self-tests, supported by FDA premarket notification pathways and pharmacy chain shelf placement.
- Nucleic Acid Tests:RNA/DNA amplification methods achieve highest analytical sensitivity for early infection detection.
- Molecular Diagnostics:Integrated cartridge systems automate sample prep through result reporting for centralized laboratory workflows.
Antigen Tests dominate installed base in resource-limited settings. Nucleic Acid Tests are where expansion concentrates for pandemic preparedness and antimicrobial stewardship programs.
Technology:
Cost tiers separate instrument-dependent platforms from disposable-only formats, with capital equipment requirements determining addressable clinic density in emerging markets.
- Lateral Flow Assay:Nitrocellulose membrane immunochromatography enables visual result interpretation without readers or power requirements. India's private pharmacy chains and sub-Saharan Africa ministry procurement programs favor this format for malaria, HIV, and dengue screening where infrastructure constraints preclude laboratory instrumentation.
- Microfluidics:Miniaturized fluidic networks integrate reagent storage, mixing, and detection onto disposable cartridges compatible with battery-powered readers. Urgent care clinics and community health centers in the United States adopt these systems for multiplexed respiratory panels, eliminating cold-chain logistics while expanding test menu breadth.
- Enzyme-Linked Immunosorbent Assay:Plate-based colorimetric detection remains standard for high-throughput laboratory screening.
- Polymerase Chain Reaction:Thermal cycler-dependent amplification retains dominance for reference laboratory confirmation testing.
Lateral Flow Assay commands the broadest geographic penetration. Microfluidics is climbing the fastest as manufacturers compress assay time-to-result for near-patient deployment.
End User:
Customer type determines regulatory complexity, with CLIA waiver status enabling pharmacy and direct-to-consumer channels that bypass traditional laboratory distribution.
- Home Care:Self-testing environments require FDA-cleared over-the-counter labeling, visual result interpretation, and minimal specimen collection complexity. United States retail pharmacy chains curate assortments based on consumer literacy and shelf space economics, concentrating procurement power among three national banners.
- Hospitals:Acute care settings integrate point-of-care devices with laboratory information systems through HL7 FHIR connectivity. EU Medical Device Regulation post-market surveillance obligations impose continuous clinical performance monitoring for Class C infectious disease panels deployed in European hospital networks.
- Clinics:Outpatient facilities balance test menu breadth with capital equipment constraints.
- Laboratories:Centralized reference sites prioritize throughput and analytical sensitivity over turnaround time.
Hospitals anchor revenue concentration for instrument-dependent platforms. Home Care is gaining share fastest as decentralized testing mandates compress traditional laboratory channel volume.
Application:
Clinical indication shapes reimbursement pathways and procurement frequency, with infectious disease screening generating recurring demand through outbreak response and routine surveillance.
- Infectious Diseases:Pathogen detection panels span respiratory, sexually transmitted, vector-borne, and gastrointestinal targets through antigen, antibody, or nucleic acid methods. WHO prequalification eligibility determines procurement access for national health ministries in Nigeria, Kenya, and Ghana, where malaria and HIV rapid tests constitute essential commodity categories.
- Toxicology Testing:Drug and metabolite detection serves workplace safety mandates, pain management protocols, and forensic applications. United States Department of Transportation regulations and construction sector occupational safety programs expand saliva and urine screening panel demand through certified laboratory and point-of-care channels.
- Chronic Diseases:Glycemic control and cardiovascular monitoring applications leverage rapid testing for patient self-management.
- Genetic Testing:Pharmacogenomic and carrier screening applications remain concentrated in specialized laboratory settings.
Infectious Diseases maintains the deepest revenue pools across all geographies. Toxicology Testing shows steepest expansion trajectory from regulatory compliance mandates and substance abuse monitoring protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government screening programs and regulatory clearance pathways are concentrating procurement volumes in specific national markets. Each geography presents distinct channel economics shaped by reimbursement rules, infrastructure constraints, and public health priorities.
United States
Retail pharmacy chains curate diagnostic assortments based on FDA premarket notification status and CLIA waiver eligibility. Home care decentralization accelerates as over-the-counter HIV and hepatitis C self-tests expand shelf presence in three national pharmacy banners. The Boston-Cambridge corridor anchors molecular diagnostic innovation clusters.
India
National Health Mission procurement drives volume orders for affordable tuberculosis and malaria screening panels at district hospitals. CDSCO regulatory pathways and government tenders favor cold-chain-independent lateral flow formats. Mumbai and Hyderabad host contract manufacturing clusters serving ministry of health contracts.
Germany
EU Medical Device Regulation post-market surveillance obligations reshape competitive positioning for Class C infectious disease panels. EMA clinical evidence standards extend recertification timelines for manufacturers seeking CE marking continuity. The Rhine-Ruhr industrial corridor concentrates diagnostic distribution logistics.
Brazil
ANVISA regulatory harmonization with WHO prequalification criteria unlocks procurement eligibility for national health ministry tenders. Workplace toxicology mandates from occupational safety protocols expand saliva and urine screening demand. São Paulo anchors Latin American distribution networks for rapid test imports.
China
NMPA streamlined approval pathways for innovative diagnostic devices accelerate domestic manufacturer market access. Government health screening programs in provincial hospital networks drive procurement of multiplexed respiratory panels. The Yangtze River Delta clusters microfluidic cartridge manufacturing capabilities.
Rapid Medical Diagnostic Kits Market Key Industry Players
Player mix skews toward diversified healthcare conglomerates with broad immunoassay portfolios and specialized infectious disease panel developers. Market structure exhibits tiered concentration, with integrated molecular workflow providers occupying distinct competitive positions from disposable-only lateral flow specialists. Strategic archetypes span CLIA waiver-focused retail channel players, laboratory-anchored high-complexity systems vendors, and WHO prequalification-eligible emerging market suppliers. Dominant competitive moves include portfolio diversification into multiplexed cartridge architectures and geographic expansion through ministry of health procurement relationships.
Within the diversified healthcare conglomerate tier, Abbott Laboratories and Danaher Corporation exemplify scale-driven positions spanning laboratory and point-of-care channels. Among specialized infectious disease developers, bioMérieux SA occupies a position emphasizing European hospital network placement and premium panel differentiation. These three entities represent contrasting strategic archetypes: broad-channel diversification, integrated workflow systems, and specialized disease-state focus.
| Leading Market Players |
|---|
| Abbott Laboratories |
| ACON Laboratories, Inc. |
| Artron Laboratories Inc. |
| Alfa Scientific Designs, Inc. |
| Becton, Dickinson and Company |
| bioMérieux SA |
| F. Hoffmann-La Roche AG |
| Cardinal Health |
| Danaher Corporation |
| Others |
Cost & Logistics Intelligence
Long-term offtake agreements between nitrocellulose membrane suppliers and lateral flow manufacturers lock in raw material access while anchoring price visibility across volatile chemical feedstock cycles. These contracts buffer Indian government tender participants and U.S. retail pharmacy suppliers against spot market swings in membrane pricing.
Pricing Analysis
Certification level (FDA-grade/CE-marked/WHO-prequalified) creates the primary spread between premium cartridge systems and economy lateral strips. Per-unit transactional pricing dominates government procurement channels, while subscription-tiered service models emerge for microfluidic reader placements in U.S. urgent care networks. Cost compression in economy antigen formats intensifies as contract manufacturers in China and India expand nitrocellulose conversion capacity. National health ministries in sub-Saharan Africa exhibit highest price sensitivity, whereas European hospital networks prioritize analytical performance over unit cost.
Supply Chain Analysis
Inventory lead times for specialized reagents stretch 12-18 weeks, forcing manufacturers to pre-position finished goods ahead of monsoon season distribution windows in South Asia. Nitrocellulose membrane supply concentrates in the United States, Germany, and China, with antibody raw material production anchored in the United States and Ireland. The supply chain rests on single-source vulnerability for high-affinity monoclonal antibodies used in HIV and malaria panels. Distribution runs through ministry of health central warehouses in emerging markets and direct-store-delivery networks for U.S. pharmacy chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Home care decentralization places the rapid diagnostic kits market in early-cycle expansion, with CLIA waiver pathways unlocking pharmacy channel penetration that laboratory-centric competitors cannot replicate.
For Market Incumbents: Consolidate control over nitrocellulose membrane supply through backward integration or captive offtake agreements to defend margin position against emerging contract manufacturers. Anchor capacity expansion in India to secure National Health Mission tender eligibility while maintaining FDA-grade production lines for U.S. retail pharmacy exclusivity. For New Entrants and Emerging Players: Lead with microfluidic cartridge development for multiplexed respiratory panels targeting U.S. urgent care clinics, where instrument placement creates recurring revenue streams. Sub-Saharan Africa ministry procurement channels offer the most penetrable white space for WHO-prequalified lateral flow entrants willing to navigate prequalification timelines. For Investors and Strategic Acquirers: Capital is best deployed toward specialized infectious disease panel developers with established European hospital network placement and premium CE-marked assay portfolios. The long-term viability window favors manufacturers bridging laboratory-grade sensitivity with point-of-care convenience. Watch FDA CLIA waiver grant velocity as the inflection signal for home care channel economics.| Strategic Initiative | Industry Significance |
|---|---|
| CLIA Waiver Pathway Investment | FDA clearance unlocks pharmacy shelf placement and direct-to-consumer channel economics. |
| WHO Prequalification Pursuit | Eligibility determines access to national health ministry tenders in Nigeria, Kenya, and Ghana. |
| Microfluidic Cartridge Development | Miniaturized multiplexing expands test menu breadth for urgent care clinic deployment. |
| Hospital System Partnership | HL7 FHIR integration agreements accelerate point-of-care device adoption in acute care settings. |
| Reimbursement Strategy | CPT code alignment with Medicare and private payer policies shapes home test accessibility. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital laboratory directors, pharmacy chain procurement managers, biomedical engineers at point-of-care device manufacturers, and regulatory affairs leads at IVD firms. Secondary validation drew from FDA 510(k) clearance databases, EMA medical device registration records, WHO prequalification listings, and CMS reimbursement code updates. Bottom-up modeling of cartridge and strip volumes triangulated against top-down market sizing from national health ministry tender disclosures.
Across the projection horizon, the analytical framework segmented value and volume by product chemistry, detection platform, care setting, and clinical indication, with regional regulatory clusters layered as an additional dimension. CAGRs were derived from weighted growth assumptions across these segments, incorporating pandemic preparedness funding cycles, antimicrobial stewardship program expansion, and decentralized testing mandate adoption curves as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained FDA clearance velocity, stable nitrocellulose feedstock pricing, or uninterrupted WHO prequalification processing would require recalibration. Forecasts reflect documented assumptions about channel migration patterns and reimbursement stability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Diagnostics
X Ray Crystallography Market
Medical Diagnostics
Cellular Pathology Market
Medical Diagnostics
Protein Sequencing Market
Medical Diagnostics
Fluid Biopsy Market
Medical Diagnostics
Artificial Intelligence (AI) in Medical Diagnostics Market
Medical Diagnostics
Global Complete Blood Count Device Market
Medical Diagnostics
Carrier Screening Market
Medical Diagnostics
MUC1 Antibody Market
Medical Diagnostics
Asia-Pacific Flow Cytometry Market
Medical Diagnostics
Global ELISA Analyzer Market
Medical Diagnostics
Medical Marker Bands Market
Medical Diagnostics
Karyotype Analysis Service Market
Medical Diagnostics
Fluorescence Cell Market
Medical Diagnostics
In-Situ Hybridization (ISH) Market
Medical Diagnostics
Asia-Pacific Single Cell Analysis Market
Medical Diagnostics
Liver Biopsy Market