
 Protein Sequencing Market | 2026-2036
Protein Sequencing Market Size, Share, and Industry Trends Forecast 2026-2036
Protein Sequencing Market Intelligence
Specialized bioinformatician talent is rotating toward proteomics divisions as pharmaceutical companies expand in-house sequencing capabilities. Thermo Fisher Scientific leverages its mass spectrometry installed base to dominate instrument supply chains. Creative Proteomics sustains competitive density through service-level specialization in de novo sequencing. Agilent Technologies anchors analytical workflow integration across chromatography and detection modules.
Protein sequencing determines the amino acid order within polypeptide chains using mass spectrometry resolution exceeding 10,000 Da or Edman degradation chemistry with iterative phenylisothiocyanate coupling. The technique enables biomarker validation, therapeutic target identification, and quality control of biologic drugs. Mass spectrometry commands the technology tier due to throughput scalability and compatibility with post-translational modification mapping. Drug development applications attract the largest service contract values, while biomarker discovery segments show the fastest adoption velocity among biotech firms with immuno-oncology pipelines.
FDA's In Vitro Diagnostic regulations and EMA's MDR framework both elevate analytical validation requirements for clinical proteomics assays, tightening market access for unvalidated platforms. ISO 17025 accreditation now functions as a procurement filter for pharmaceutical sponsors selecting contract sequencing providers. Stakeholders must monitor how computational methods segment reshapes pricing power as cloud-based analysis displaces instrument ownership models.
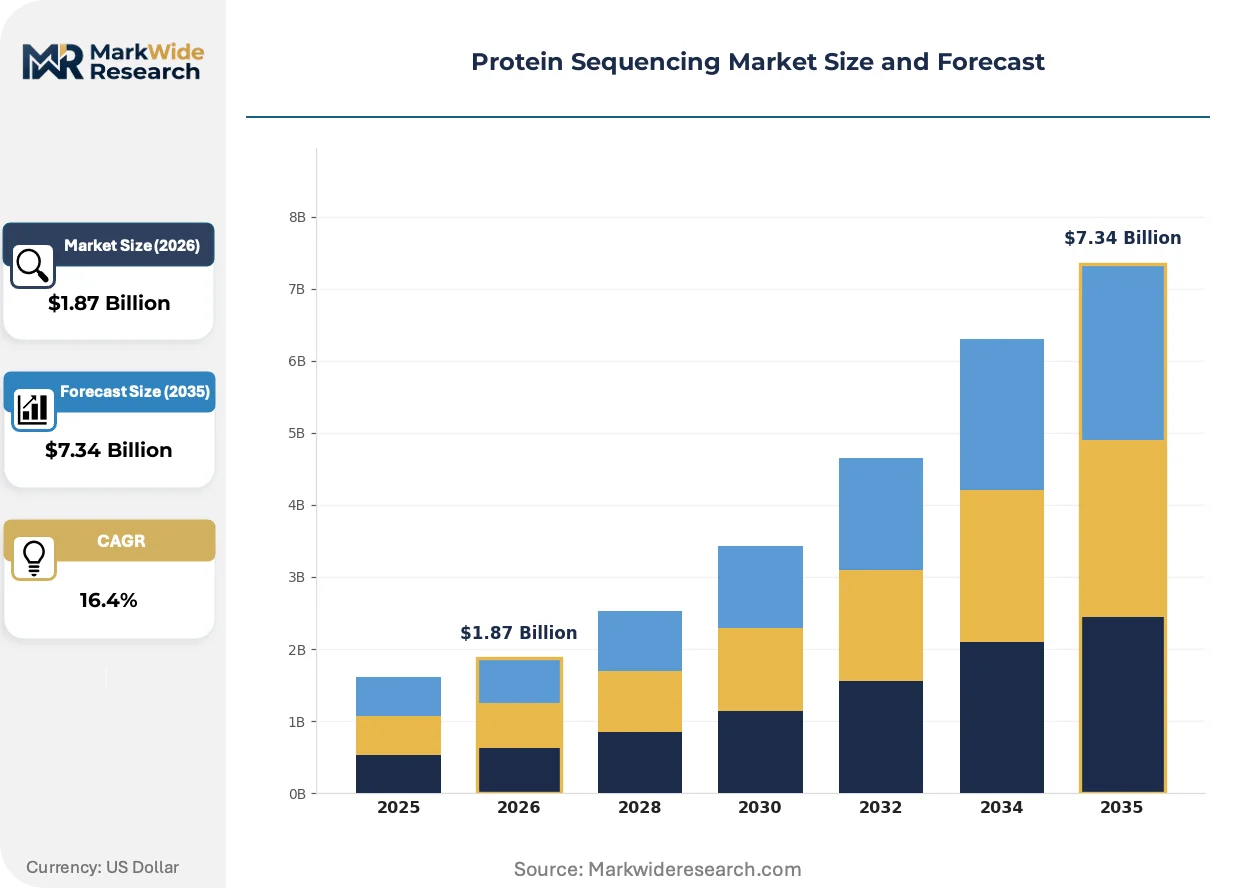
Market Dynamics
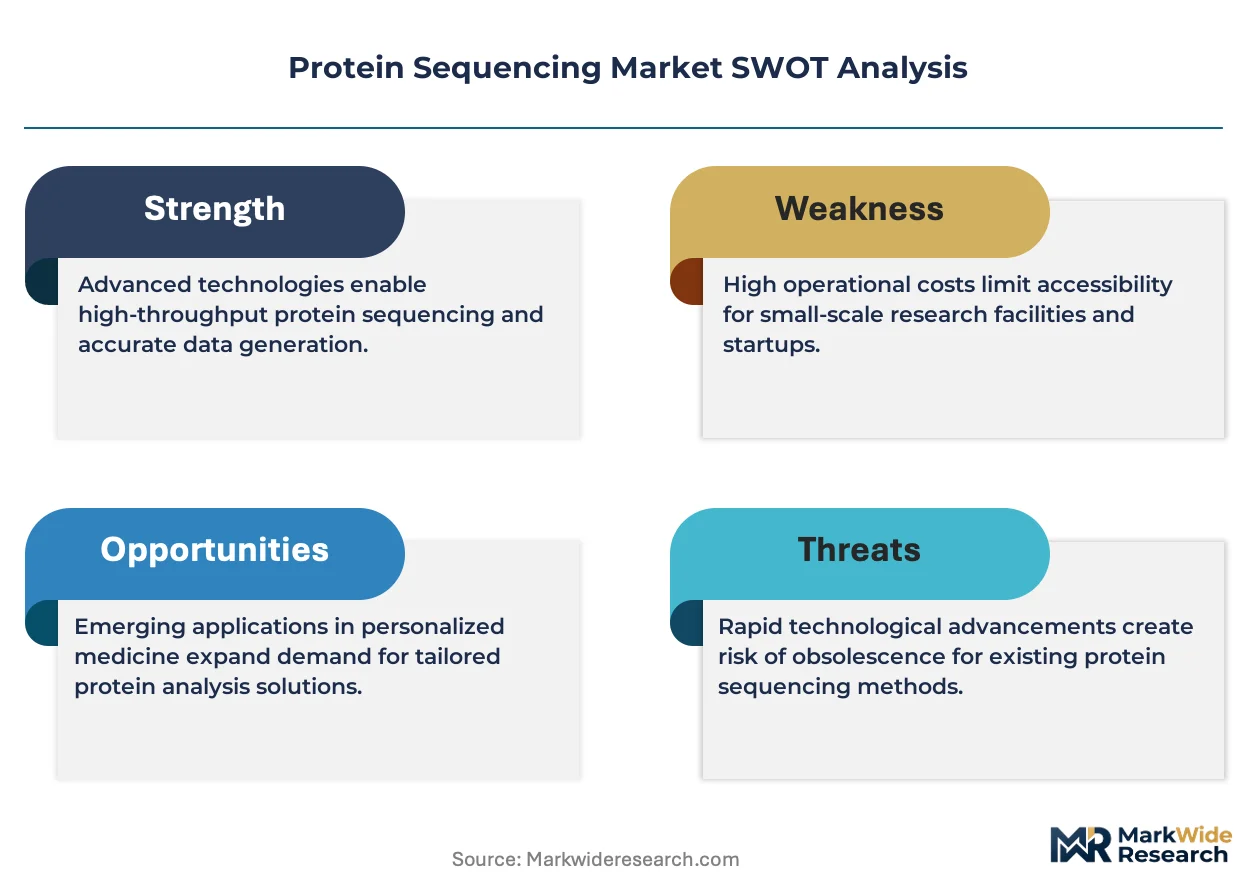
Mass spectrometry platform consolidation is compressing service provider margins while pharmaceutical sponsors internalize sequencing capabilities, creating a bifurcation between instrument vendors and specialized contract laboratories.
Growth Catalysts
- EMA's MDR framework:Elevated analytical validation requirements for clinical proteomics assays are filtering out unaccredited competitors and concentrating contract awards with ISO 17025-certified providers.
- Precision medicine pipelines:Pharmaceutical companies are embedding proteomic data into therapeutic target identification workflows, expanding sequencing volumes for biomarker validation studies.
- Boston biotech cluster:Concentrated contract research spending in this hub is anchoring demand for high-throughput de novo sequencing services.
Market Restraints
- Mass spectrometer supply concentration:Critical instrument components face sourcing bottlenecks from specialized German and Japanese optics manufacturers, extending procurement timelines.
- FDA In Vitro Diagnostic regulations:Stringent premarket notification requirements for sequencing-based clinical assays create multi-year validation cycles that deter platform commercialization.
- Edman degradation chemistry:This legacy technique retains niche applications for N-terminal analysis but faces throughput limitations that constrain scalability below mass spectrometry thresholds.
Strategic Opportunities
- Cloud-based bioinformatics:Computational methods segment is enabling subscription revenue models that displace instrument ownership for mid-size biotech firms.
- Post-translational modification mapping:Emerging demand for glycoprotein and phosphoprotein characterization is opening service specialization beyond standard amino acid sequencing.
- NMPA accelerated review pathway:China's streamlined approval for innovative diagnostics is compressing time-to-market for sequencing-based assays targeting the domestic hospital network.
Industry Challenges
- Bioinformatician talent scarcity:Specialized computational biologists with proteomics domain expertise command premium compensation, constraining service provider expansion.
- Mass spectrometer capex intensity:Orbitrap and time-of-flight platforms require seven-figure capital commitments that limit market entry for regional laboratories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Protein Sequencing Market |
| Market Size in 2026 | $1.87 Billion |
| Market Size in 2035 | $7.34 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Mass Spectrometry, Edman Degradation, Chromatography, Computational Methods Application: Drug Development, Biomarker Discovery, Disease Diagnosis, Proteomics Research End User: Pharmaceutical Companies, Academic Institutions, Research Laboratories, Biotech Firms Delivery Mode: Lab-Based Services, Online Platforms, Mobile Solutions, In-House Services |
| Companies Covered | Rapid Novor, Selvita, Thermo Fisher Scientific, Bioinformatics Solutions, Proteome Factory, Agilent Technologies, Charles River Laboratories, Creative Proteomics, Shimadzu Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Protein Sequencing Market Strategic Shifts & Innovations
Protein sequencing workflows are fragmenting across three vectors: instrument miniaturization, regulatory data harmonization, and procurement model restructuring toward analytical outcomes rather than per-sample pricing.
Single-cell proteomics instrumentation is decomposing the traditional bulk-analysis paradigm by enabling amino acid resolution at individual-cell thresholds. Immuno-oncology biotech firms in San Diego and Cambridge are adopting these platforms for rare-cell biomarker discovery. This capability is decomposing the market segmentation between research-grade and clinical-grade sequencing services, as sensitivity specifications converge.
ISO 17025 accreditation requirements are propagating from pharmaceutical sponsor procurement guidelines into de facto market access standards. Contract sequencing providers without this certification face exclusion from validated drug development workflows. European CROs are responding by consolidating analytical method transfers across multiple national accreditation bodies to maintain cross-border service eligibility.
Pharmaceutical sponsors are unbundling instrument ownership from analytical expertise, preferring fee-for-service contracts with guaranteed turnaround times over capital deployment. This restructuring favors mid-scale service providers with dedicated proteomics divisions over generalist CROs. The United States exhibits the fastest adoption velocity, where Boston-area biotech clusters prioritize speed-to-data over platform control.
Protein Sequencing Market Segmentation
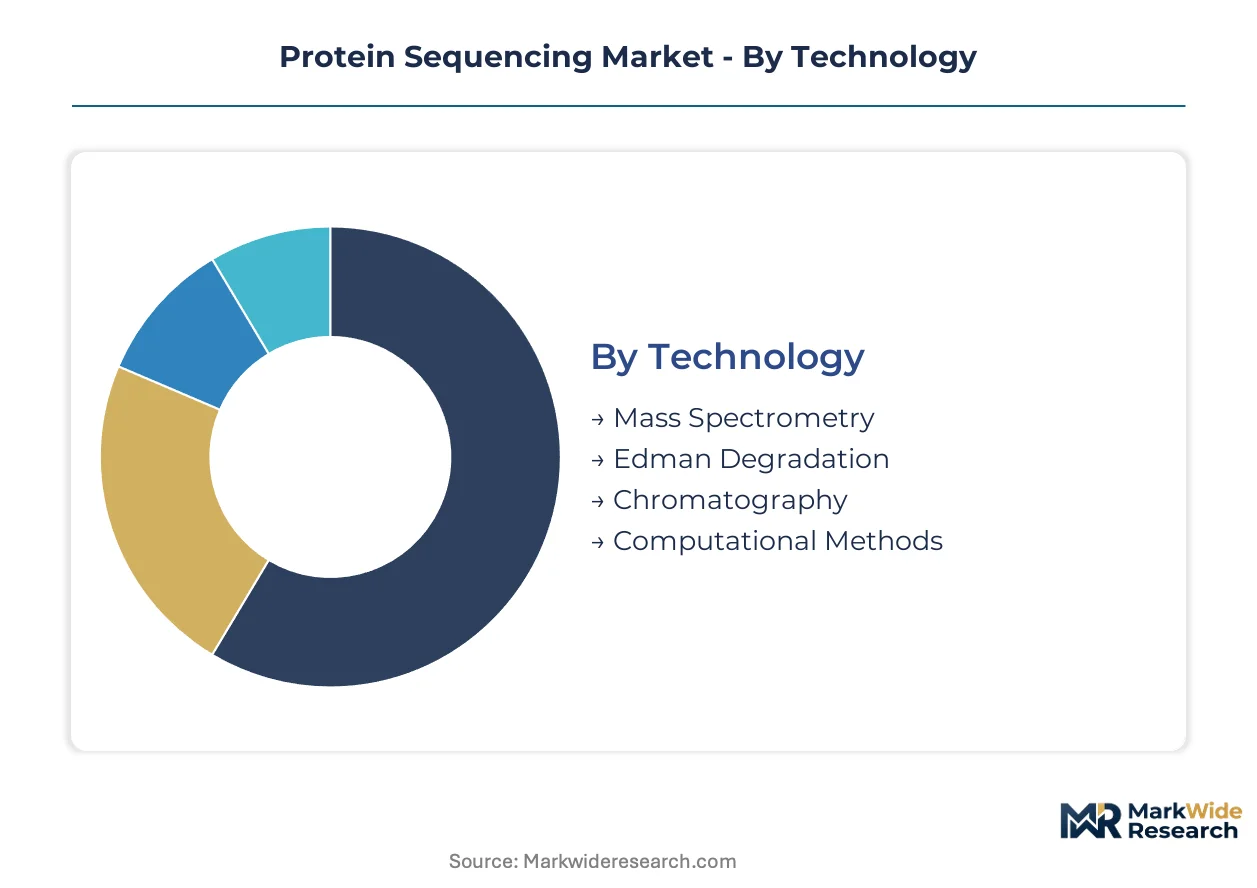
Protein sequencing demand fragments across technology platforms, application workflows, and procurement models. Each segment exhibits distinct margin profiles and customer concentration patterns that reshape competitive positioning.
Technology:
Instrument vendors route high-throughput platforms through pharmaceutical direct sales channels, while specialized service providers distribute niche techniques via contract research networks.
- Mass Spectrometry:Orbitrap and time-of-flight systems achieve resolution exceeding 10,000 Da with post-translational modification mapping capability. Pharmaceutical sponsors in Boston and San Diego anchor procurement volumes for biomarker validation pipelines, though seven-figure capital requirements limit regional laboratory entry.
- Edman Degradation:Iterative phenylisothiocyanate chemistry delivers precise N-terminal sequencing for synthetic peptide verification. Academic institutions retain demand for this legacy technique where throughput constraints matter less than absolute sequence certainty at the N-terminus.
- Chromatography:Separation modules integrate upstream of detection systems in analytical workflows.
- Computational Methods:Cloud-based analysis platforms are displacing instrument ownership for mid-size biotech firms.
Mass spectrometry dominates installed base. Computational methods are where expansion concentrates.
Application:
Contract values scale with regulatory validation burden, creating tiered pricing across discovery-phase and clinical-grade workflows.
- Drug Development:Therapeutic target identification and biologic quality control command the largest service contract values. FDA premarket notification requirements for sequencing-based clinical assays extend validation cycles, concentrating awards with ISO 17025-certified providers.
- Biomarker Discovery:Immuno-oncology pipelines in Cambridge and San Diego drive fastest adoption velocity for de novo sequencing services. Single-cell proteomics sensitivity specifications are converging research-grade and clinical-grade segmentation.
- Disease Diagnosis:Hospital network procurement prioritizes turnaround time over platform flexibility.
- Proteomics Research:Academic funding cycles sustain demand for grant-supported sequencing access.
Drug development captures premium pricing. Biomarker discovery is climbing the fastest.
End User:
Procurement authority concentrates with sponsors who internalize sequencing capabilities versus those who outsource to contract laboratories.
- Pharmaceutical Companies:In-house proteomics divisions embed sequencing into precision medicine pipelines. Thermo Fisher Scientific leverages mass spectrometry installed base to dominate instrument supply chains for this segment.
- Biotech Firms:Immuno-oncology specialists in Boston biotech clusters prioritize speed-to-data over platform control, favoring fee-for-service contracts with guaranteed turnaround times.
- Academic Institutions:Grant-funded researchers access shared core facilities for exploratory sequencing.
- Research Laboratories:Government and private labs sustain demand for standardized analytical protocols.
Pharmaceutical companies anchor contract research spending. Biotech firms are gaining share fastest.
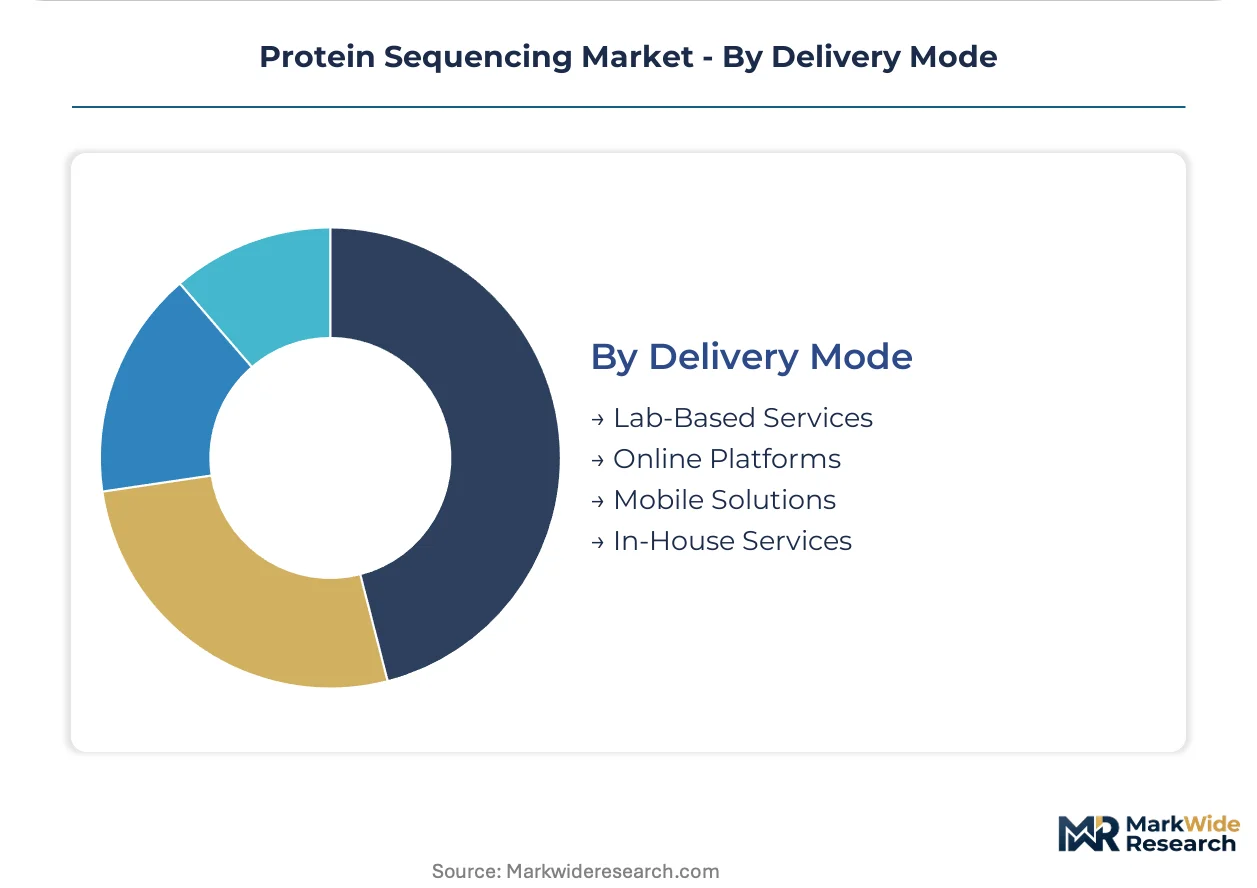
Delivery Mode:
Channel mix is restructuring toward analytical outcomes rather than per-sample pricing, unbundling instrument ownership from expertise.
- Lab-Based Services:ISO 17025-accredited contract sequencing providers execute validated workflows for pharmaceutical sponsors. European CROs consolidate analytical method transfers across multiple national accreditation bodies to maintain cross-border eligibility.
- In-House Services:Pharmaceutical sponsors internalize sequencing capabilities to protect proprietary target data, creating bifurcation between instrument vendors and specialized contract laboratories.
- Online Platforms:Cloud-based bioinformatics portals enable subscription revenue models.
- Mobile Solutions:Point-of-care proteomics remains nascent due to sensitivity requirements.
Lab-based services dominate current procurement. In-house services are where strategic investment concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical sponsors in the United States deploy protein sequencing primarily for biomarker validation in precision medicine pipelines, while Chinese hospital networks prioritize diagnostic assay commercialization under accelerated regulatory pathways.
United States
FDA premarket notification requirements for sequencing-based clinical assays compress validation timelines for instrument vendors. Boston and San Diego biotech clusters anchor contract research spending for de novo sequencing services. Pharmaceutical sponsors in these hubs internalize proteomics capabilities to protect proprietary target data.
China
NMPA's accelerated review pathway for innovative diagnostics compresses time-to-market for sequencing-based assays targeting domestic hospital networks. Shanghai and Beijing anchor demand for mass spectrometry platforms in biologic quality control workflows. Domestic CROs consolidate analytical method transfers to maintain cross-border service eligibility.
Germany
EMA's MDR framework elevates analytical validation requirements for clinical proteomics assays, filtering contract awards toward ISO 17025-certified providers. Munich and Heidelberg sustain demand for Edman degradation chemistry in synthetic peptide verification. Regional laboratories face extended procurement timelines for specialized optics components.
Japan
PMDA consultation procedures for proteomics-based companion diagnostics shape sponsor sequencing strategies. Osaka and Tokyo pharmaceutical clusters prioritize turnaround time guarantees in fee-for-service contracts. Domestic instrument vendors leverage mass spectrometry installed bases for analytical workflow integration.
United Kingdom
MHRA post-Brexit recognition agreements with FDA and EMA create dual-validation pathways for clinical proteomics assays. Cambridge and Oxford immuno-oncology pipelines drive fastest adoption velocity for single-cell proteomics sensitivity specifications. Academic core facilities sustain grant-funded demand for exploratory sequencing access.
Protein Sequencing Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier that dominates contract research execution. Instrument vendors with mass spectrometry installed bases capture pharmaceutical direct sales channels, while service providers with ISO 17025 accreditation concentrate validated workflow awards. Two strategic archetypes define positioning: platform-integrated conglomerates and sequencing-specialized CROs. Competitive moves center on consolidating analytical method transfers across accreditation bodies and unbundling instrument ownership from bioinformatics expertise.
Among North American platform-integrated conglomerates, Thermo Fisher Scientific exemplifies the instrument supply chain archetype through its mass spectrometry dominance. Agilent Technologies occupies a position spanning chromatography and detection module integration. Creative Proteomics represents the specialized CRO tier with service-level concentration in de novo sequencing workflows. These three anchors illustrate how competitive density fragments between captive instrument ecosystems and independent analytical service networks.
| Leading Market Players |
|---|
| Rapid Novor |
| Selvita |
| Thermo Fisher Scientific |
| Bioinformatics Solutions |
| Proteome Factory |
| Agilent Technologies |
| Charles River Laboratories |
| Creative Proteomics |
| Shimadzu Corporation |
| Others |
Cost & Logistics Intelligence
ISO 17025 accreditation gates both supplier qualification and price differentiation simultaneously, filtering contract awards toward certified providers who command premium positioning for validated drug development workflows while unaccredited competitors face margin compression in research-grade segments.
Pricing Analysis
Long-term offtake agreements dominate pharmaceutical sponsor procurement, though spot purchasing persists for exploratory biomarker discovery studies. Three-tier pricing structure across ISO-certified premium, standard service, and economy research-grade levels reflects validation burden and turnaround guarantees. Pricing pressure stems from mass spectrometer capex intensity as sponsors internalize capabilities. Biotech firms in Boston clusters exhibit highest price sensitivity, prioritizing speed-to-data over platform control.
Supply Chain Analysis
Inventory lead times for Orbitrap and time-of-flight platforms extend twelve to eighteen months due to specialized optics sourcing. Critical components concentrate in Germany and Japan, with final assembly anchored in the United States and China. Supply chain risk centers on single-source vulnerability for high-resolution detectors from Japanese optics manufacturers. Distribution runs through direct pharmaceutical sales channels and specialized CRO contract networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-based bioinformatics represents the fastest-expanding recurring-revenue layer, outpacing hardware growth as mid-size biotech firms abandon instrument ownership for subscription analysis portals.
For Market Incumbents: Fortify ISO 17025 accreditation across multiple national bodies to maintain cross-border eligibility as EMA's MDR framework tightens validation requirements. Deepen analytical method transfer capabilities to defend against sponsor internalization of sequencing capabilities. Prioritize service-level specialization in post-translational modification mapping where technical differentiation sustains pricing power.
For New Entrants and Emerging Players: Lead with cloud-based bioinformatics platforms targeting mid-size immuno-oncology biotech firms in San Diego and Cambridge clusters. The most penetrable white space sits in glycoprotein and phosphoprotein characterization services beyond standard amino acid sequencing. A fee-for-service model with guaranteed turnaround times bypasses capital barriers that constrain regional laboratory entry.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified life science conglomerates seeking to monetize non-core proteomics divisions as precision medicine pipelines concentrate investment. Long-term viability hinges on recurring bioinformatics revenue rather than instrument placement cycles. Monitor NMPA accelerated review pathway approvals as inflection indicators for Chinese diagnostic assay commercialization velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 17025 Multi-Body Accreditation | EMA's MDR framework elevates cross-border service eligibility for European CROs. |
| Cloud Bioinformatics Platform Launch | Subscription models displace instrument ownership among mid-size Boston biotech firms. |
| Post-Translational Modification Specialization | Glycoprotein mapping opens service differentiation beyond commodity sequencing. |
| Pharmaceutical Sponsor Partnership | Guaranteed turnaround contracts anchor revenue as sponsors internalize capabilities. |
| NMPA Pathway Navigation | Accelerated diagnostic approvals compress time-to-market for Chinese hospital networks. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across pharmaceutical proteomics divisions, CRO laboratory directors, bioinformatics platform engineers, and regulatory affairs specialists managing FDA premarket notifications. Secondary validation drew from FDA 510(k) filings, EMA MDR technical documentation, ClinicalTrials.gov protocol registries, and ISO 17025 accreditation databases. Bottom-up service provider revenue estimates triangulated against top-down pharmaceutical R&D spending allocations across the analysis window.
Across the projection horizon, the analytical framework modeled technology platform adoption curves, application workflow segmentation between discovery and clinical-grade services, and end-user procurement authority concentration. CAGRs derived from instrument placement trajectories, service contract value expansion, and computational methods subscription growth. Forecast inputs incorporated mass spectrometry resolution advancement timelines and regulatory validation cycle durations.
Forecasts assume regulatory continuity in FDA In Vitro Diagnostic and EMA MDR regimes; material policy shifts would require re-modeling validation burden impacts on commercialization timelines. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Diagnostics
Europe Circulating Tumor Cells (CTC) Liquid Biopsy Market
Medical Diagnostics
Circulating Tumor Cells (Ctcs) Prognostic Technologies Market
Medical Diagnostics
Carrier Screening Market
Medical Diagnostics
MUC1 Antibody Market
Medical Diagnostics
Asia Pacific Immunohistochemistry Market
Medical Diagnostics
Flow Cytometry Market
Medical Diagnostics
Global HLA Typing Market
Medical Diagnostics
US Molecular Diagnostics Market
Medical Diagnostics
Middle East and Africa Circulating Tumor Cells (CTC) Liquid Biopsy Market
Medical Diagnostics
Asia-Pacific Single Cell Analysis Market
Medical Diagnostics
Real-Time PCR, Digital PCR, and End-Point PCR Market
Medical Diagnostics
Fluorescence Cell Market
Medical Diagnostics
Telepathology Market
Medical Diagnostics
Global ELISA Analyzer Market
Medical Diagnostics
Medical Marker Bands Market
Medical Diagnostics
Global HLA Typing for Transplant Market